
 Railway Maintenance Machinery Market | 2026-2036
Railway Maintenance Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Maintenance Machinery Market Intelligence
The performance gap between premium precision systems and commodity-grade maintenance equipment is broadening across rail networks. Plasser & Theurer leverages its Austrian engineering heritage to dominate high-specification tamping and track geometry correction systems. Harsco Corporation anchors its position through extensive rail grinding service contracts across North American freight corridors. China Railway Construction Corporation Limited competes on manufacturing scale and domestic supply chain integration for the expanding Chinese high-speed rail maintenance base.
Railway maintenance machinery encompasses specialized track-bound and road-rail vehicles engineered to restore rail profiles, stabilize track beds, and manage ballast geometry within tolerances of 0.1 millimeters over 200-meter chord lengths. These systems sustain commercial rail operations by preventing fatigue cracks, correcting gauge deviations, and extending rail service life before replacement. Track Maintenance applications lead current procurement volumes as aging infrastructure in Western Europe and North America requires systematic rehabilitation, while Automated Systems technology captures expanding margin pools through reduced labor exposure and precision repeatability. Diesel-Powered Equipment retains dominance in remote and electrification-sparse territories, though Electric Machinery segments accelerate where catenary infrastructure permits zero-emission operation.
EU F-Gas Regulation and the EU Green Deal framework compel European operators to phase diesel-dependent fleets, directly redirecting procurement budgets toward electrified and battery-hybrid platforms. The US Federal Railroad Administration enforces Track Safety Standards that mandate geometric compliance thresholds, sustaining baseline demand for measurement-integrated maintenance machinery. China's Ministry of Ecology and Environment enforces dual carbon goals that filter into state rail procurement specifications. Stakeholders must monitor how divergent electrification timelines across regulatory jurisdictions reshape equipment compatibility requirements and residual value calculations for cross-border fleet deployments.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale equipment transition across European rail maintenance fleets, compressing diesel machinery residual values while redirecting capital toward electrified platforms and battery-hybrid architectures.
Growth Catalysts
- High-Speed Rail Fleet Renewal:China's expanding high-speed network maintenance schedules are generating concentrated demand for precision tamping and track geometry systems. State rail procurement specifications now embed dual carbon targets from the Ministry of Ecology and Environment.
- EU Green Deal Framework:The European regulatory push is accelerating zero-emission machinery adoption where catenary infrastructure permits full electrification. Procurement budgets are systematically redirecting from diesel-dependent platforms.
- Dedicated Freight Corridors:India's freight corridor expansion and metro rail extensions are creating sustained demand for heavy-duty ballast regulators and rail grinding vehicles. The Dedicated Freight Corridor Corporation is driving volume procurement.
Market Restraints
- Electrification Infrastructure Gaps:Remote territories and electrification-sparse networks lock operators into diesel-powered equipment, fragmenting fleet standardization and elevating total cost of ownership.
- Specialized Component Concentration:Precision measurement systems and hydraulic control modules concentrate supply among a limited base of German and Austrian component specialists, exposing procurement timelines to single-source risk.
- Steel and Rare Earth Volatility:Ballast regulator chassis fabrication and permanent magnet motor production face input cost pressure from commodity price swings in structural steel and neodymium.
Strategic Opportunities
- Battery-Hybrid Architectures:The technology convergence of lithium-ion traction batteries with regenerative braking systems creates a bridge solution for partially electrified networks. Operators in Spain and Italy are piloting dual-mode platforms.
- Predictive Maintenance Integration:Sensor-embedded tamping units and AI-driven rail profile analytics represent an emerging application layer. Deutsche Bahn infrastructure units are unbundling traditional maintenance contracts to incorporate data services.
- Urban Metro Extensions:Southeast Asian capital cities including Jakarta and Bangkok are accelerating underground rail construction, generating demand for compact road-rail maintenance vehicles with zero-emission operation mandates.
Industry Challenges
- Mechatronics Skill Scarcity:The intersection of hydraulic systems, precision measurement, and battery-electric drivetrains demands technicians with cross-functional competencies. German and Swiss rail maintenance depots report extended recruitment cycles for mechatronics specialists.
- Legacy Fleet Integration:New electrified platforms must interface with decades-old maintenance scheduling software and depot infrastructure. Operators face reconfiguration friction in mixed-fleet environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Maintenance Machinery Market |
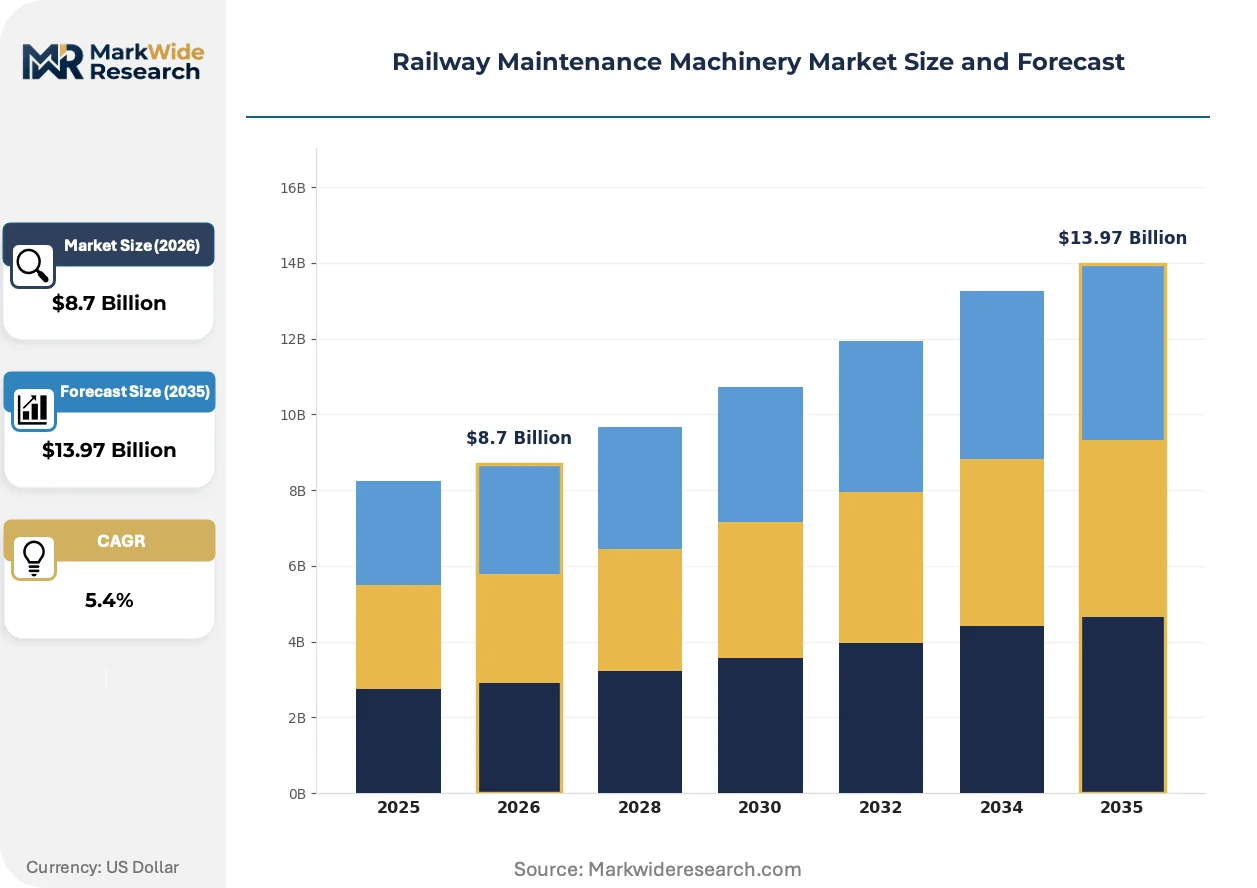
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rail Grinders, Track Stabilizers, Ballast Regulators, Rail Drilling Machines Application: Track Maintenance, Rail Construction, Infrastructure Upgrades, Emergency Repairs End User: Government Agencies, Private Operators, Contractors, Railway Authorities Technology: Automated Systems, Remote-Controlled Units, Diesel-Powered Equipment, Electric Machinery |
| Companies Covered | ROBEL Bahnbaumaschinen GmbH, Nordco, Inc., Plasser & Theurer, Strukton Rail, China Railway Construction Corporation Limited, Loram Maintenance of Way Inc., Harsco Corporation, Pandrol SAS, Speno International SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Maintenance Machinery Market Strategic Shifts & Innovations
Autonomous track measurement and correction systems are compressing labor exposure while tightening geometric tolerances. Regulatory pressure on emissions is accelerating powertrain diversification beyond conventional diesel architectures.
Machine vision-guided tamping systems are automating ballast compaction and track geometry correction within sub-millimeter tolerances. European infrastructure managers including ÖBB and SBB are deploying these platforms on high-traffic corridors. The technology is automating tasks previously requiring manual survey crews and reducing track possession windows.
The EU F-Gas Regulation and complementary national diesel phase-out timelines are mandating zero-emission machinery in electrified territories. German KBA type-approval processes now prioritize battery-electric and hydrogen fuel cell maintenance vehicles. Fleet operators in the Netherlands and Denmark are responding by front-loading electrified procurement to lock in residual value.
Asset-as-a-service contracting is displacing traditional capital purchase models for precision maintenance fleets. Infrastructure managers in France and the UK are unbundling equipment ownership from operational service delivery. This reconfiguration concentrates most visibly in high-frequency corridor maintenance where uptime guarantees dominate procurement evaluation.
Railway Maintenance Machinery Market Segmentation
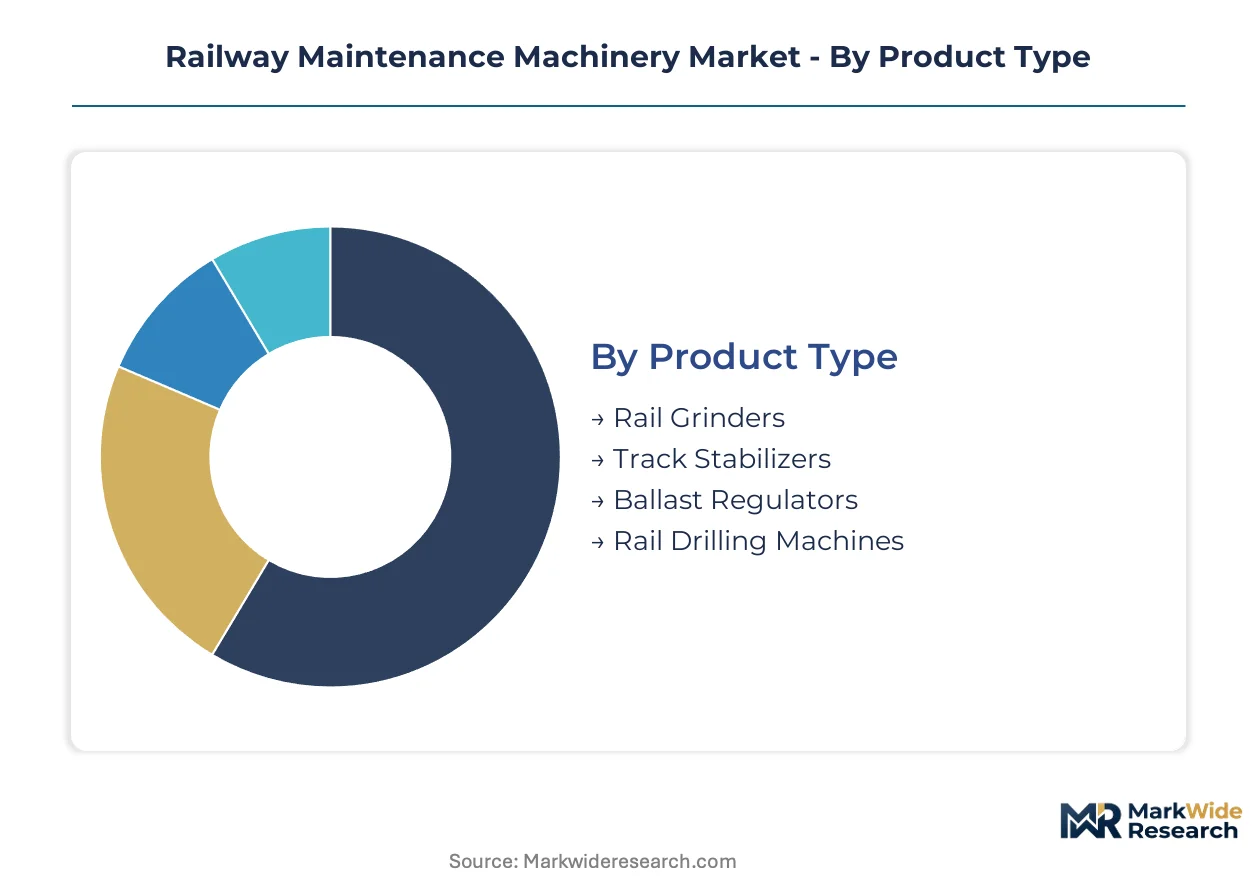
Railway maintenance machinery segments diverge sharply in margin structure and procurement cycles. Equipment specification tiers and technology readiness levels create distinct competitive arenas across product categories.
Product Type:
Component supply concentrates among Austrian and German precision engineering clusters, locking procurement timelines to specialized manufacturing capacity.
- Rail Grinders:Rotating grinding stones restore rail profiles to remove corrugations and rolling contact fatigue. Deutsche Bahn and SNCF deploy these units continuously on high-traffic corridors where surface defects propagate rapidly. Harsco Corporation anchors its service model on long-term grinding contracts across North American freight networks.
- Track Stabilizers:Dynamic compaction systems densify ballast beds through controlled vibration and vertical load application. China's high-speed rail maintenance depots are expanding stabilizer fleets as network density increases and possession windows compress.
- Ballast Regulators:Profile correction vehicles redistribute ballast to maintain drainage geometry and lateral stability.
- Rail Drilling Machines:Portable track-bound units execute precision hole patterns for rail jointing and fastening installation.
Rail Grinders absorb the bulk of installed capacity; Automated Systems technology is expanding most quickly.
Application:
Procurement volume clusters around rehabilitation-heavy geographies where aging infrastructure mandates systematic intervention.
- Track Maintenance:Systematic rehabilitation of ballast geometry, rail alignment, and fastening integrity sustains operational safety margins. Western European infrastructure managers including ÖBB and Network Rail are front-loading maintenance budgets to address decades of deferred renewal.
- Infrastructure Upgrades:Capacity expansion projects demand temporary machinery deployment for track realignment and gauge conversion. India's Dedicated Freight Corridor Corporation is driving concentrated demand for upgrade-capable equipment as freight corridors reach completion.
- Rail Construction:Greenfield track laying requires ballast distribution and initial geometry establishment.
- Emergency Repairs:Rapid-response units address derailment damage, washouts, and extreme weather disruption.
Track Maintenance commands the dominant share of fleet utilization; Infrastructure Upgrades are climbing the fastest as network expansion accelerates.
End User:
Contracting models are fragmenting traditional ownership structures across customer categories.
- Government Agencies:State rail infrastructure managers specify equipment through centralized procurement frameworks with embedded carbon compliance requirements. China's Ministry of Ecology and Environment filters dual carbon targets into state rail procurement specifications.
- Private Operators:Freight railroads including Class I carriers in the United States favor service-based contracts over capital ownership. Asset-as-a-service models are displacing traditional purchase arrangements where uptime guarantees dominate evaluation criteria.
- Contractors:Specialized maintenance firms lease or operate machinery on project-specific deployment schedules.
- Railway Authorities:Urban metro operators mandate zero-emission equipment specifications for tunnel and underground maintenance.
Government Agencies retain the largest installed base; Private Operators are gaining share fastest through service contracting conversion.
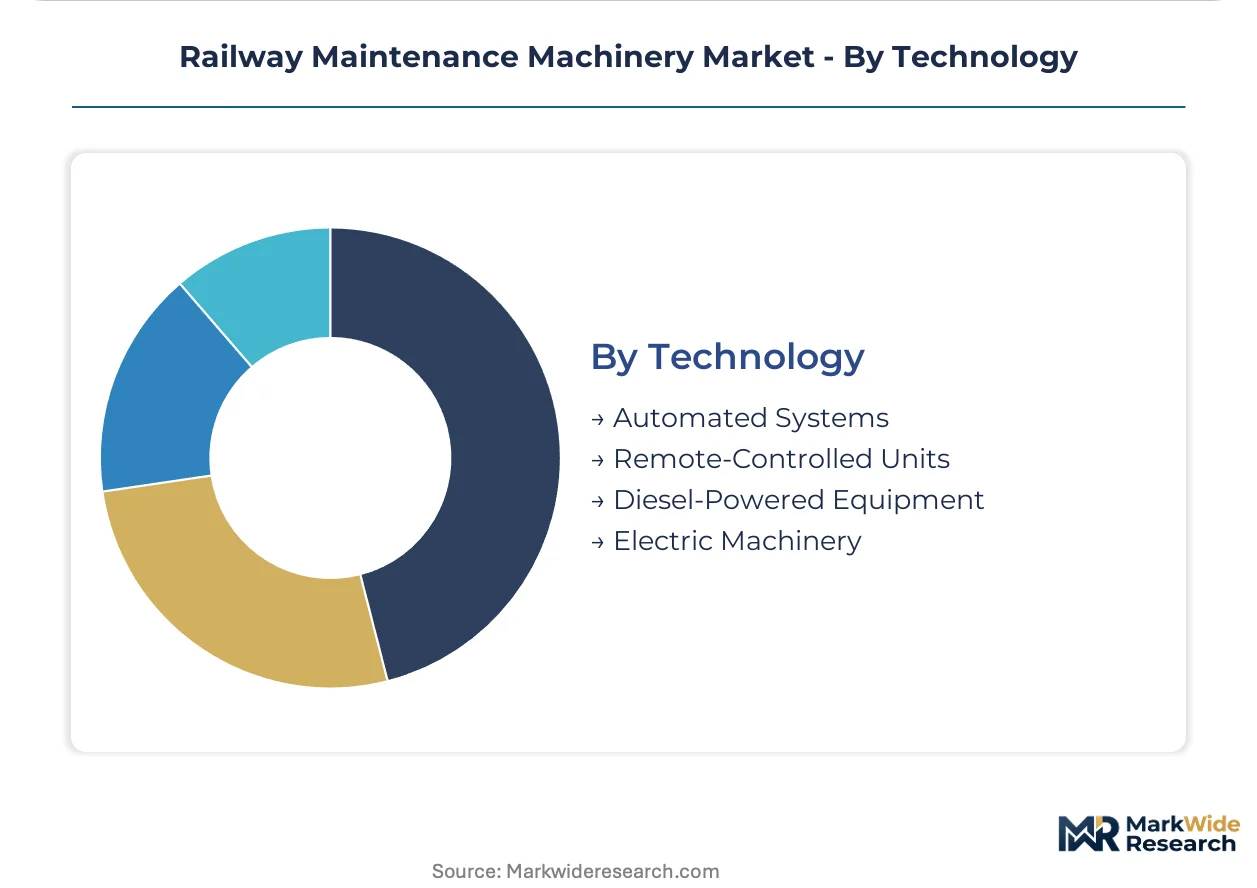
Technology:
Powertrain diversification is compressing residual values for conventional diesel platforms while elevating electrification premiums.
- Automated Systems:Machine vision-guided tamping and autonomous track measurement reduce labor exposure while tightening geometric tolerances to sub-millimeter precision. ÖBB and SBB are deploying these platforms on high-traffic corridors to compress possession windows.
- Electric Machinery:Catenary-dependent platforms eliminate direct emissions where electrification infrastructure permits full operation. The EU F-Gas Regulation and national diesel phase-out timelines are mandating zero-emission procurement in electrified territories.
- Remote-Controlled Units:Operator-separated machinery improves safety in hazardous track environments.
- Diesel-Powered Equipment:Conventional drivetrains retain necessity in remote and electrification-sparse networks.
Diesel-Powered Equipment retains the dominant installed base; Electric Machinery is expanding most quickly where regulatory pressure intersects infrastructure availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wuhan's high-speed rail maintenance complex anchors procurement intensity for precision tamping systems serving China's expanding network. State rail infrastructure managers across multiple continents are front-loading capital budgets to address deferred renewal cycles.
China
High-speed rail fleet renewal schedules concentrate demand for track geometry correction systems. The Ministry of Ecology and Environment embeds dual carbon targets into state rail procurement specifications. Wuhan and Beijing maintenance depots are expanding stabilizer fleets as network density compresses possession windows.
Germany
Deutsche Bahn infrastructure units are unbundling traditional maintenance contracts to incorporate predictive data services. The KBA type-approval process prioritizes battery-electric and hydrogen fuel cell maintenance vehicles. Bavarian engineering clusters supply precision measurement systems and hydraulic control modules to European fleet operators.
United States
Class I freight railroads favor service-based contracts over capital ownership for rail grinding fleets. The Federal Railroad Administration enforces Track Safety Standards mandating geometric compliance thresholds. Chicago and Omaha corridor maintenance bases sustain baseline demand for measurement-integrated machinery.
India
Dedicated freight corridor expansion generates concentrated demand for heavy-duty ballast regulators. The Dedicated Freight Corridor Corporation drives volume procurement through centralized frameworks. Gujarat and Maharashtra rail construction zones require temporary machinery deployment for track realignment.
France
Infrastructure managers are unbundling equipment ownership from operational service delivery through asset-as-a-service models. The EU F-Gas Regulation compels zero-emission machinery adoption in electrified territories. Paris corridor maintenance contracts concentrate on uptime guarantees dominating procurement evaluation.
Railway Maintenance Machinery Market Key Industry Players
Premium-margin players sit above commodity-margin players across precision specification tiers. The vendor base organizes around Austrian-German engineering heritage, North American service contracting scale, and Chinese domestic supply chain integration. Three archetypes dominate: precision system specialists, integrated service providers, and state-backed manufacturing conglomerates. Competitive moves center on asset-as-a-service contracting conversion and battery-hybrid platform development bridging electrification gaps.
Within the precision engineering tier, Plasser & Theurer and Speno International SA exemplify Austrian and Swiss heritage positioning. ROBEL Bahnbaumaschinen GmbH anchors German fabrication capabilities. China Railway Construction Corporation Limited occupies the state-backed scale-driven position serving domestic high-speed rail maintenance bases. Harsco Corporation and Loram Maintenance of Way Inc. represent North American service-contracting archetypes.
| Leading Market Players |
|---|
| ROBEL Bahnbaumaschinen GmbH |
| Nordco, Inc. |
| Plasser & Theurer |
| Strukton Rail |
| China Railway Construction Corporation Limited |
| Loram Maintenance of Way Inc. |
| Harsco Corporation |
| Pandrol SAS |
| Speno International SA |
| Others |
Cost & Logistics Intelligence
Neodymium permanent magnet costs cascade from Chinese rare earth refineries through Austrian-German hydraulic module fabricators into three-tier pricing structures across premium, standard, and economy equipment tiers. Buyers in electrified European corridors absorb elevated capital outlays for battery-electric platforms while freight operators in electrification-sparse territories lock in diesel equipment residual values before regulatory obsolescence compresses secondary markets.
Pricing Analysis
Uptime-guarantee contracting anchors value-based pricing for precision maintenance fleets. Asset-as-a-service models separate equipment ownership from operational delivery, compressing price transparency for government agency buyers while elevating total cost of ownership visibility for private operators. Price differentiation hinges on geometric precision certification and embedded predictive analytics capability. Cost compression in standard-tier diesel equipment is intensifying because European F-Gas Regulation deadlines accelerate residual value depreciation. Private freight railroads exhibit highest price sensitivity; state rail infrastructure managers in China and India demonstrate lowest sensitivity due to centralized procurement frameworks with embedded carbon compliance mandates.
Supply Chain Analysis
Direct-to-OEM channels handle fleet-scale procurement from state rail infrastructure managers, while specialized distributors serve contractor segments with project-specific deployment schedules. Precision measurement systems and hydraulic control modules concentrate in Austrian and German engineering clusters. Ballast regulator chassis fabrication draws from Chinese and Indian structural steel mills; permanent magnet motor production rests on Chinese rare earth processing. Single-source vulnerability in precision component supply exposes procurement timelines to extended manufacturing queues. Distribution runs through OEM-direct contracts for government agencies and tiered distributor networks for private operators and maintenance contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into precision component manufacturing and captive service delivery networks. Players securing upstream control over hydraulic control modules and downstream ownership of grinding service contracts capture margin pools unavailable to equipment-only vendors.
For Market Incumbents: Deploy battery-hybrid platform development to bridge electrification infrastructure gaps in partially cabled networks. Plasser & Theurer and Harsco Corporation should deepen Austrian-German engineering cluster relationships to defend precision specification tiers against Chinese state-backed manufacturing scale. EU F-Gas Regulation compliance investment represents the critical defensive lever; failure to front-load electrified R&D exposes residual value calculations to regulatory obsolescence. Channel control through asset-as-a-service contracting conversion locks out emerging competitors in French and British corridor maintenance markets. For New Entrants and Emerging Players: The premium-economy price-point gap in Southeast Asian metro rail extensions offers white-space entry without direct confrontation with Austrian-German precision specialists. Jakarta and Bangkok underground construction mandates zero-emission compact road-rail vehicles where established European players lack localized service infrastructure. Target India's Dedicated Freight Corridor Corporation procurement frameworks through joint venture structures with domestic fabrication partners. License battery-hybrid architectures from European technology holders rather than developing proprietary powertrains. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision component specialists in German engineering clusters facing temporary order compression from steel and rare earth input volatility. Mid-cap Austrian hydraulic control module fabricators offer acquisition targets with irreplaceable technical heritage and limited replication risk. Long-term viability over a five-to-ten year window hinges on electrification infrastructure buildout velocity across Asian freight corridors. Monitor Deutsche Bahn predictive maintenance contract unbundling as the inflection signal for data-service revenue pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Hybrid Platform Development | Bridges electrification gaps for ÖBB and SBB corridor operators awaiting full catenary coverage. |
| Predictive Maintenance Data Services | Captures unbundled revenue pools as Deutsche Bahn separates equipment ownership from analytics delivery. |
| Precision Component Backward Integration | Secures hydraulic module supply from Bavarian engineering clusters against single-source vulnerability. |
| Asset-as-a-Service Contracting Conversion | Locks residual value guarantees for infrastructure managers in France and UK corridor maintenance markets. |
| Southeast Asian Metro Localization | Positions compact zero-emission vehicles for Jakarta and Bangkok underground extension mandates. |
Research Approach
Document review covered EU F-Gas regulatory filings, Chinese Ministry of Ecology and Environment procurement specifications, and Indian Dedicated Freight Corridor Corporation tender documents, complemented by interviews with rail infrastructure maintenance directors, OEM procurement teams, aftermarket service heads, and precision component engineering leads. Secondary validation drew from Deutsche Bahn infrastructure unit disclosures, Harsco Corporation service contract filings, and Austrian-German trade association capacity reports. Bottom-up equipment deployment estimates triangulated against top-down rail network maintenance expenditure projections.
Segment-level value and volume trajectories across the analysis window reflect equipment specification tiering, powertrain technology readiness, and contracting model conversion velocity. The analytical framework modeled product type, application intensity, end-user ownership structure, and regional regulatory compliance clusters. CAGRs were derived from fleet renewal schedule alignment with electrification infrastructure buildout timelines. Key inputs included Chinese high-speed rail possession window compression rates and European diesel phase-out deadline stringency.
Inputs from infrastructure manager procurement disclosures and OEM order backlogs were available through the study window; gaps in contractor segment informal leasing activity introduce uncertainty bands in fleet utilization estimates. Forecasts reflect documented assumptions regarding electrification infrastructure completion schedules and rare earth supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market