
 Automotive Emission Test Equipment Market | 2026-2036
Automotive Emission Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Emission Test Equipment Market Intelligence
German component suppliers is recalibrating their production footprints to meet stepped-up European type-approval requirements. HORIBA, Ltd. leverages its spectroscopy heritage to dominate gas analyzer supply for OEM validation centers. AVL LIST GmbH anchors its position through captive engine testing know-how that extends into full vehicle certification workflows. SGS SA competes by operating accredited networks across multiple national approval systems.
Automotive emission test equipment comprises instruments that quantify exhaust constituents including nitrogen oxides, particulate matter, hydrocarbons, and carbon monoxide through calibrated sampling and detection methods. Chassis dynamometers simulate road-load conditions while gas analyzers measure tailpipe concentrations against regulatory thresholds, serving manufacturers seeking type-approval and in-service compliance verification. Portable Emission Measurement Systems command premium positioning as real-driving emissions protocols expand beyond laboratory conditions. Electrochemical sensors occupy mature cost-optimized tiers for workshop screening, while Fourier Transform Infrared Spectroscopy leads in multi-species precision for research and homologation labs.
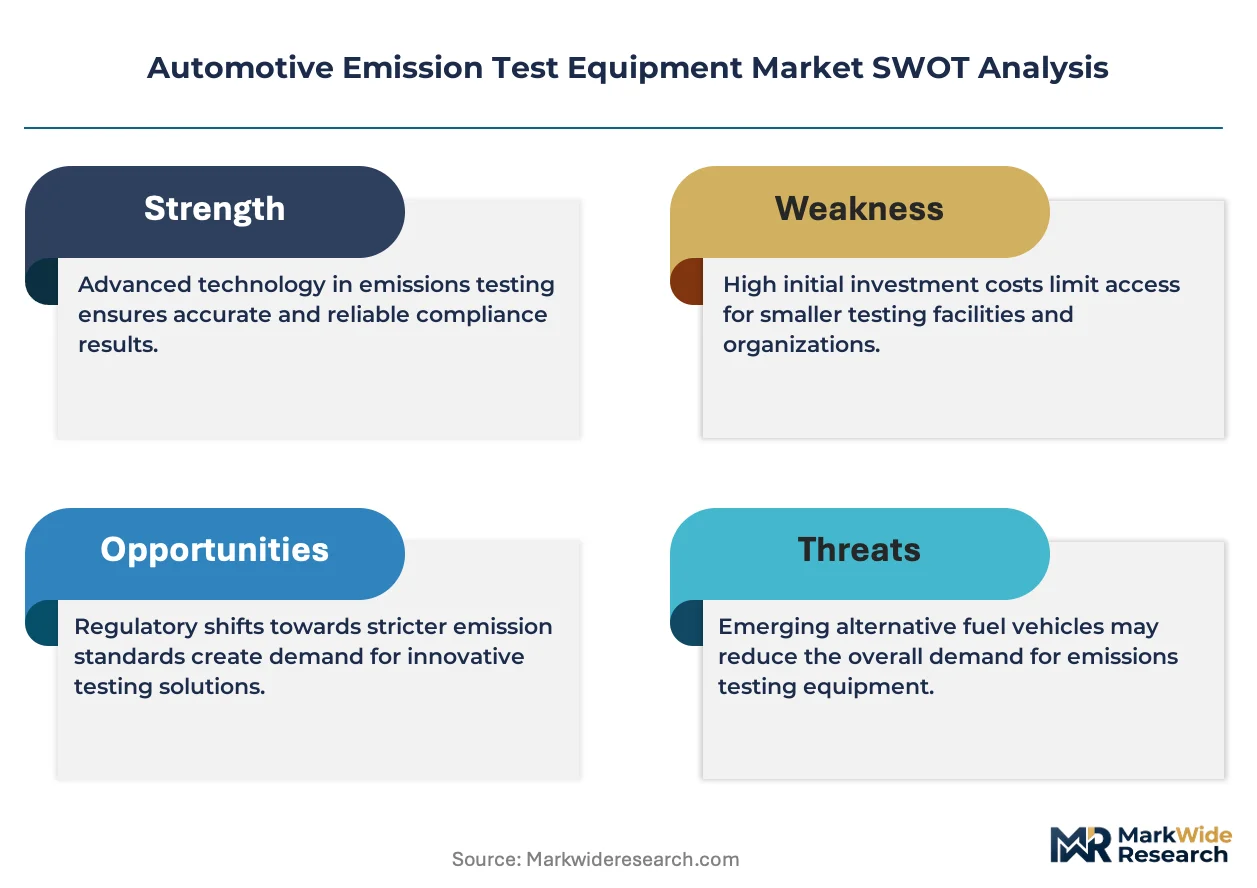
EPA tailpipe standards and Euro 7 frameworks from the European Commission are tightening allowable NOx and particulate limits, forcing equipment upgrades at testing labs and manufacturer facilities. California Air Resources Board mandates drive additional demand cycles distinct from federal baselines, creating specialized compliance segments. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate capital deployment timing for next-generation measurement protocols.
Market Dynamics
Real-driving emissions protocols are forcing equipment manufacturers to bridge laboratory precision with on-road validation, compressing development cycles while expanding hardware complexity.
Growth Catalysts
- Euro 7 Framework:The European Commission's tightened NOx and particulate thresholds mandate equipment upgrades across OEM validation centers and independent testing labs.
- California Air Resources Board:CARB mandates create specialized compliance demand cycles distinct from federal EPA baselines, requiring dual-capability equipment portfolios.
- Portable Emission Measurement Systems:PEMS technology adoption accelerates as regulatory scope expands beyond controlled laboratory conditions into actual traffic environments.
Market Restraints
- Fourier Transform Infrared Spectroscopy Costs:FTIR analyzer procurement represents significant capital outlay for mid-tier testing facilities, constraining fleet modernization.
- Electrochemical Sensor Supply:Component concentration among Asian semiconductor fabricators creates vulnerability in cost-optimized workshop screening equipment tiers.
- Regulatory Divergence:Misalignment between EPA tailpipe standards and European type-approval protocols fragments R&D investment across incompatible measurement methodologies.
Strategic Opportunities
- India BIS Type-Approval Expansion:India's automotive testing infrastructure remains underpenetrated relative to vehicle production volume, creating equipment deployment whitespace.
- Electrification Testing Convergence:Battery electric vehicle validation requirements merge thermal management assessment with traditional emission protocols, opening new application domains.
- Workshop Channel Digitization:Connected diagnostic platforms enable remote calibration and predictive maintenance, transforming aftermarket service delivery models.
Industry Challenges
- Spectroscopy Specialist Shortage:FTIR and laser absorption instrument operation demands rare cross-disciplinary expertise in optics, automotive engineering, and regulatory science.
- Homologation Timeline Compression:Accelerated Euro 7 preparation deadlines strain manufacturer capacity to validate equipment performance across multiple national approval systems simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Emission Test Equipment Market |
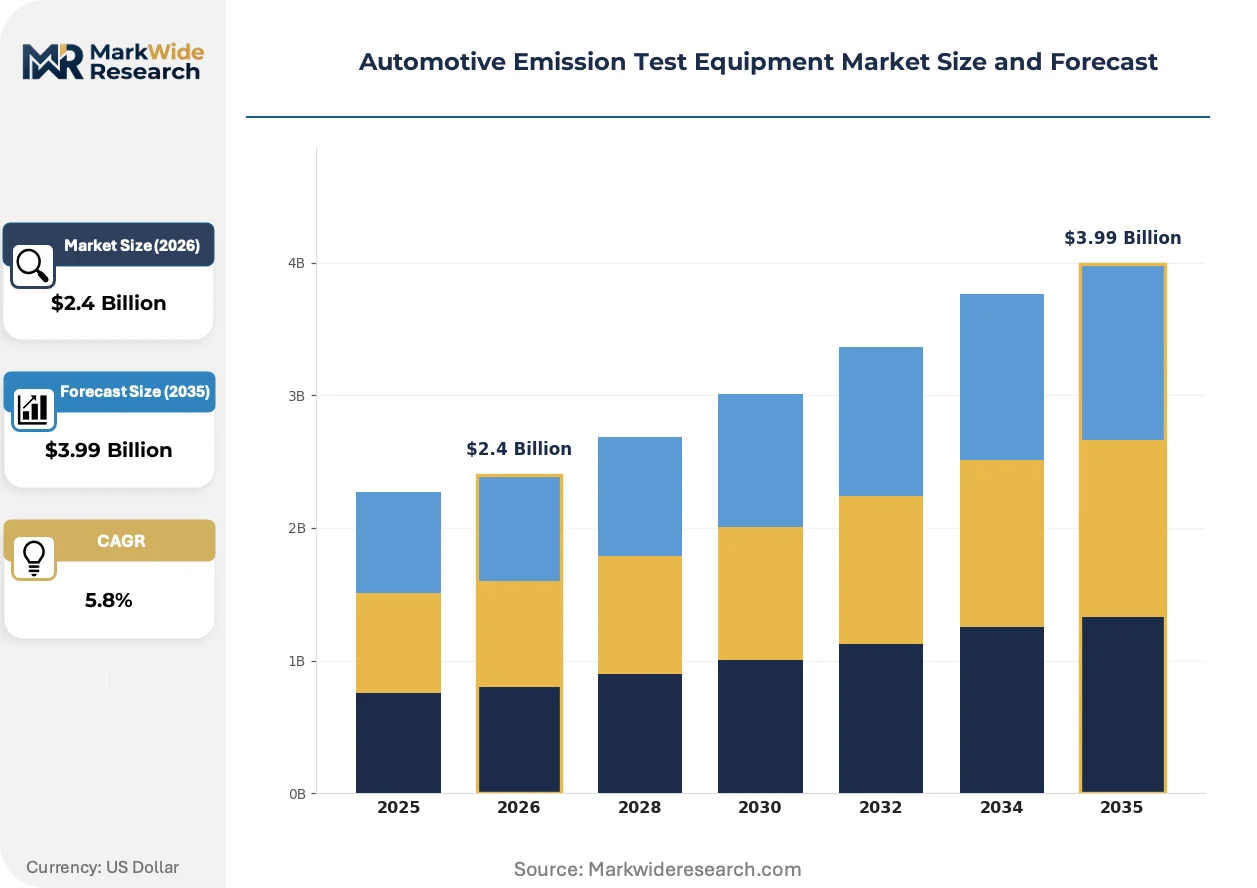
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Smoke Meters, Portable Emission Measurement Systems, Chassis Dynamometers, Particle Counters Technology: Non-Dispersive Infrared Sensors, Gas Chromatography, Flame Ionization Detectors, Fourier Transform Infrared Spectroscopy, Electrochemical Sensors Application: On-Road Vehicles, Off-Road Equipment, Two-Wheelers, Heavy-Duty Trucks, Light-Duty Commercial Vehicles End User: Emission Testing Labs, Vehicle Manufacturers, Regulatory Agencies, Independent Service Centers, Certification Bodies |
| Companies Covered | TÜV Nord Group, SGS SA, HORIBA, Ltd., TEXA S.p.A., CAPELEC, AVL LIST GmbH, Applus+, 3DATX Corporation, Opus Inspection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Emission Test Equipment Market Strategic Shifts & Innovations
Measurement modality convergence and regulatory scope expansion are redefining equipment specifications, with hardware platforms now required to span laboratory, production-line, and real-world operating conditions.
Laser absorption spectroscopy is absorbing market share from traditional chemiluminescence analyzers for NOx quantification. Tier 1 suppliers in Germany are retrofitting existing engine test cells with multi-species optical benches. The technology is absorbing capital previously allocated to discrete single-gas analyzers, consolidating instrument footprints while improving cross-species correlation.
EPA's evolving heavy-duty in-use testing program is extending PEMS mandates to vocational vehicle categories previously exempt from real-driving measurement. Equipment manufacturers are scaling portable system production to match fleet operator compliance deadlines. California's regulatory corridor remains the primary demand concentration for these expanded validation protocols.
Service unbundling now separates hardware procurement from calibration and certification support. Independent testing laboratories in Michigan and Stuttgart are negotiating outcome-based maintenance contracts that shift uptime risk to equipment vendors. This restructuring is most pronounced among multi-site operators seeking operational predictability across distributed validation networks.
Automotive Emission Test Equipment Market Segmentation
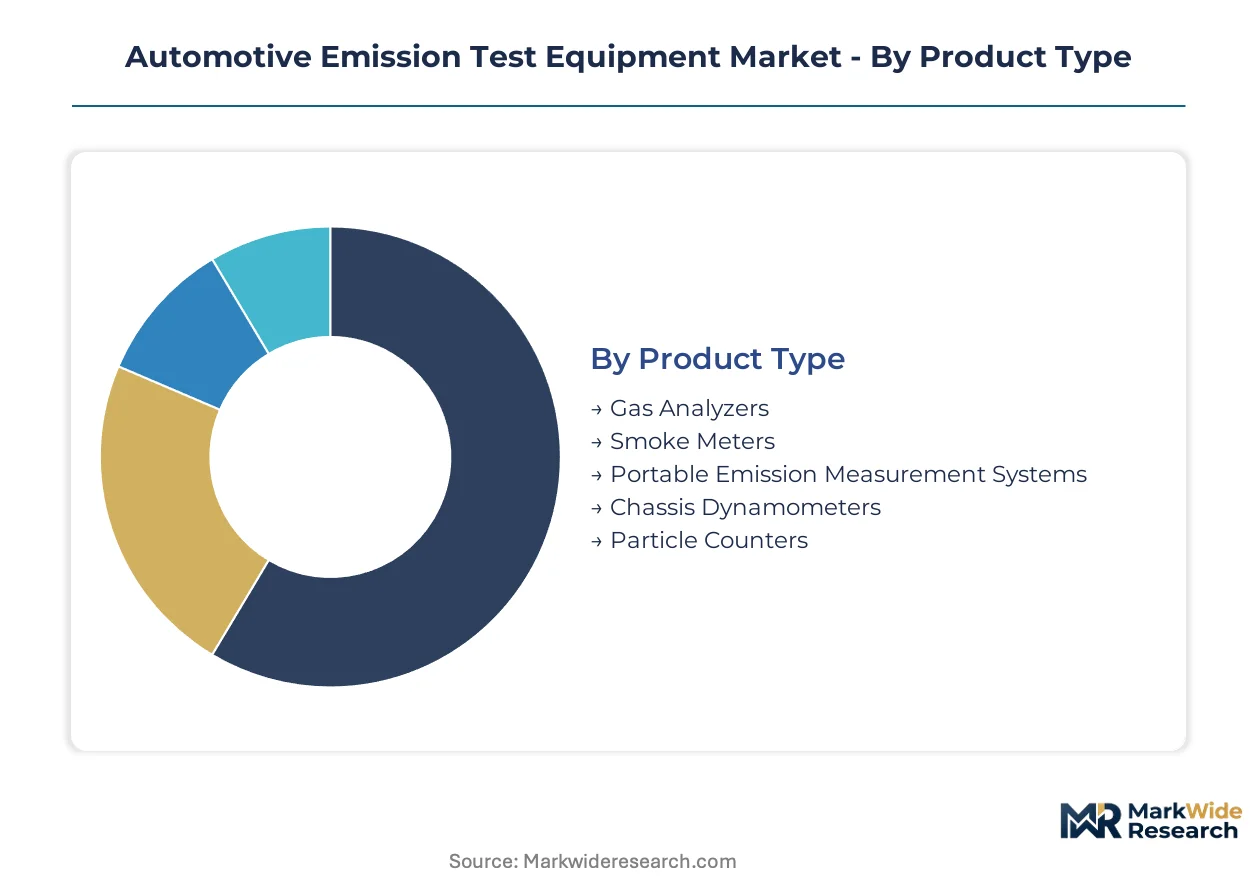
Equipment specifications diverge sharply across testing environments, from precision laboratory benches to ruggedized roadside units. Understanding these segment boundaries clarifies where capital concentrates and which technologies command pricing power.
Product Type:
Volume deployment clusters in cost-optimized workshop tiers, while premium positioning concentrates in regulatory validation and research applications.
- Gas Analyzers:Multi-species exhaust quantification instruments employing infrared absorption and electrochemical detection cells. Demand concentrates in German OEM validation centers preparing for Euro 7 type-approval deadlines, where simultaneous NOx, CO, and hydrocarbon measurement compresses testing cycles.
- Portable Emission Measurement Systems:Vehicle-mounted hardware capturing real-driving emissions data under actual traffic conditions. California's regulatory compliance corridor dominates procurement, driven by CARB mandates extending beyond laboratory protocols into on-road validation.
- Smoke Meters:Opacity-based particulate assessment for diesel engine screening.
- Chassis Dynamometers:Road-load simulation platforms for controlled tailpipe measurement.
- Particle Counters:Solid particle number quantification for particulate matter regulations.
Mature deployment sits with Gas Analyzers. Newer deployment is concentrated in Portable Emission Measurement Systems.
Technology:
Cost tier separates commodity sensor platforms from precision spectroscopy systems requiring specialized operation expertise.
- Fourier Transform Infrared Spectroscopy:Multi-species optical detection achieving simultaneous quantification of exhaust constituents through interferometric measurement. Homologation laboratories in Stuttgart and Michigan anchor demand, where cross-species correlation requirements justify capital intensity despite procurement constraints.
- Non-Dispersive Infrared Sensors:Single-beam absorption analyzers for CO and CO2 measurement in cost-sensitive applications. Workshop screening networks across India and Southeast Asia drive volume procurement, constrained by calibration drift limitations in high-humidity environments.
- Electrochemical Sensors:Amperometric detection cells for NOx and oxygen measurement.
- Flame Ionization Detectors:Hydrocarbon-specific quantification through combustion ionization.
- Gas Chromatography:Separation-based speciation for research-grade exhaust analysis.
Established deployment centers on Non-Dispersive Infrared Sensors. Steepest expansion trajectory belongs to Fourier Transform Infrared Spectroscopy.
Application:
Regulatory scope varies by vehicle category, with distinct equipment specifications for highway, non-road, and vocational duty cycles.
- On-Road Vehicles:Passenger car and light truck emission validation spanning laboratory and real-driving protocols. German and California regulatory frameworks drive dual-capability equipment procurement, requiring simultaneous chassis dynamometer and PEMS compatibility.
- Heavy-Duty Trucks:Commercial vehicle emission assessment under loaded operating conditions. EPA's evolving in-use testing program extends measurement mandates to vocational categories, scaling portable system production to match fleet operator compliance deadlines.
- Light-Duty Commercial Vehicles:Van and small truck emission screening.
- Two-Wheelers:Motorcycle and scooter exhaust measurement for urban air quality programs.
- Off-Road Equipment:Construction and agricultural machinery emission validation.
Concentrated deployment resides in On-Road Vehicles. Emerging deployment is accelerating in Heavy-Duty Trucks.
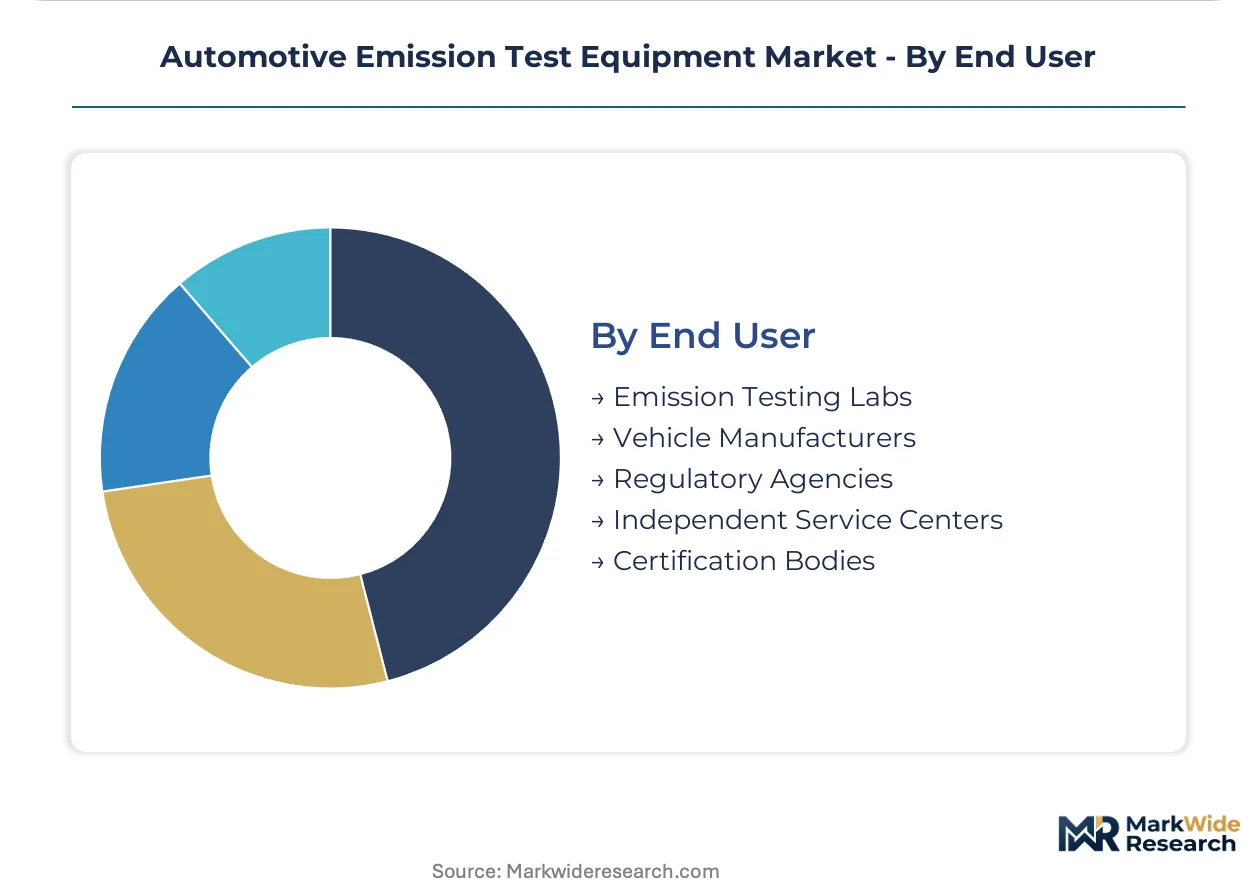
End User:
Customer type determines procurement scale, calibration requirements, and service contract structures.
- Vehicle Manufacturers:Captive validation centers conducting type-approval and production consistency testing. German automotive producers are expanding in-house testing capabilities under Euro 7 preparation timelines, consolidating instrument procurement across engine and full-vehicle certification workflows.
- Emission Testing Labs:Independent facilities serving multiple OEMs and regulatory submissions. Accredited networks spanning national approval systems compete on turnaround speed, driving outcome-based maintenance contracts that shift uptime risk to equipment vendors.
- Regulatory Agencies:Government enforcement and surveillance testing operations.
- Certification Bodies:Third-party type-approval and conformity assessment services.
- Independent Service Centers:Aftermarket workshop screening and periodic inspection.
Traditional deployment concentrates in Vehicle Manufacturers. Expanding deployment is shifting toward Emission Testing Labs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optical components from Stuttgart and Karlsruhe anchor European equipment manufacturing. German spectroscopy heritage supplies validation centers worldwide. Asian semiconductor fabrication clusters feed sensor demand for cost-optimized workshop tiers.
United States
EPA tailpipe standards and CARB mandates create dual compliance demand cycles. California's regulatory corridor concentrates Portable Emission Measurement Systems procurement. Michigan's automotive testing cluster in Ann Arbor and Detroit hosts independent laboratories negotiating outcome-based maintenance contracts.
Germany
Vehicle manufacturers in Munich and Stuttgart are expanding in-house testing capabilities under Euro 7 preparation timelines. KBA type-approval requirements drive simultaneous engine and full-vehicle certification workflows. Baden-Württemberg's precision engineering base supplies Fourier Transform Infrared Spectroscopy benches to homologation laboratories.
China
MIIT emission standards and GB compliance protocols scale domestic equipment demand. Yangtze River Delta automotive clusters in Shanghai and Jiangsu province drive chassis dynamometer deployment. Shenzhen's electronics manufacturing corridor feeds electrochemical sensor supply for workshop screening networks.
India
BIS type-approval expansion lags vehicle production volume, creating equipment deployment whitespace. Central Pollution Control Board mandates accelerate testing infrastructure investment. Tamil Nadu's Chennai automotive belt attracts emission lab accreditation networks seeking production-proximity validation.
Japan
METI regulatory frameworks and JIS standards maintain precision equipment demand. Nagoya's Chubu manufacturing corridor anchors gas analyzer development for hybrid powertrain validation. Tokyo-Yokohama metro hosts research-grade laser absorption spectroscopy deployment for next-generation measurement protocols.
Automotive Emission Test Equipment Market Key Industry Players
Global majors compete with regional champions across certification network coverage and spectroscopy specialization. The vendor base separates into three tiers: integrated validation service providers, precision instrument specialists, and cost-optimized workshop equipment fabricators. Consolidation pressure concentrates among captive engine testing know-how holders and multi-site accreditation network operators. Dominant competitive moves include backward integration into optical component supply and geographic expansion of accredited testing footprints.
Within the integrated validation tier, SGS SA and Applus+ exemplify network-scale competition through multi-jurisdiction accreditation coverage. HORIBA, Ltd. occupies a position representing spectroscopy heritage anchoring gas analyzer supply for OEM validation centers. AVL LIST GmbH sits within the captive testing tier, embodying engine-to-vehicle certification workflow consolidation. TEXA S.p.A. and CAPELEC represent European specialist positioning in diagnostic and measurement equipment. TÜV Nord Group anchors the certification-body archetype with regulatory agency proximity.
| Leading Market Players |
|---|
| TÜV Nord Group |
| SGS SA |
| HORIBA, Ltd. |
| TEXA S.p.A. |
| CAPELEC |
| AVL LIST GmbH |
| Applus+ |
| 3DATX Corporation |
| Opus Inspection |
| Others |
Cost & Logistics Intelligence
Spectroscopy specialist scarcity in Baden-Württemberg and Stuttgart anchors labor-cost differentials that widen pricing-tier spreads between FTIR-equipped homologation laboratories and electrochemical-sensor workshop networks. Calibration technician wages in German precision engineering clusters exceed Southeast Asian semiconductor fabrication hubs by multiples, compressing margins in cost-optimized tiers while sustaining premium positioning in regulatory validation segments.
Pricing Analysis
Service unbundling separates hardware procurement from calibration and certification support, with outcome-based maintenance contracts shifting uptime risk to equipment vendors. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in workshop screening tiers intensifies because electrochemical sensor oversupply from Asian fabricators erodes hardware margins. Independent service centers exhibit highest price sensitivity, while German OEM validation centers prioritize measurement precision over procurement cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Ann Arbor, and Shanghai coordinate hub-and-spoke patterns for precision optical benches and portable system assemblies. Manufacturing concentration rests on Germany for Fourier Transform Infrared Spectroscopy components, China for electrochemical sensor supply, and Japan for laser absorption spectroscopy subsystems. Critical dependencies include interferometric mirrors, infrared detector arrays, and amperometric sensor cells. Single-source vulnerability concentrates in Asian semiconductor fabricators serving cost-optimized workshop tiers. Distribution runs through accredited equipment vendor networks with captive service engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into optical component supply to defend margin position against spectroscopy specialist wage inflation.
For Market Incumbents: Lock in captive calibration technician pipelines through apprenticeship partnerships with Karlsruhe and Stuttgart technical institutes. Consolidate multi-site accreditation network coverage to compress homologation timeline risk from Euro 7 preparation deadlines. Laser absorption spectroscopy displacement of chemiluminescence analyzers threatens discrete single-gas instrument revenue streams. For New Entrants and Emerging Players: Euro 7 in Germany opens a window for PEMS retrofit services at mid-tier independent testing labs lacking in-house optical bench expertise. India's BIS type-approval expansion offers the most penetrable geography given equipment deployment whitespace relative to vehicle production volume. Workshop channel digitization provides a software-first go-to-market angle with lower capital barriers than hardware manufacturing. For Investors and Strategic Acquirers: Re-rating potential sits with captive engine testing know-how holders given electrification testing convergence opening battery thermal management validation domains. Long-term viability favors vertically integrated specialists spanning spectroscopy heritage through certification network accreditation. Watch EPA heavy-duty in-use testing program expansion as the inflection signal for portable system demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Component Supply | HORIBA's spectroscopy heritage in Kyoto secures interferometric mirror sourcing for FTIR benches. |
| Multi-Jurisdiction Accreditation Network Expansion | SGS SA operates across KBA, EPA, and CARB systems to compress OEM validation timelines. |
| PEMS Production Scale-Up | California's regulatory corridor mandates drive fleet operator compliance equipment procurement. |
| Workshop Channel Digitization Platform Launch | TEXA S.p.A. connects diagnostic platforms to enable remote calibration across European aftermarket networks. |
| Electrification Testing Capability Convergence | AVL LIST GmbH merges battery thermal assessment with traditional emission protocols for hybrid validation. |
Research Approach
Document review covered EPA regulatory filings, Euro 7 framework documentation, MIIT emission standard releases, and SGS SA accreditation disclosures, complemented by interviews with OEM validation center directors, independent testing lab operations managers, FTIR equipment calibration technicians, and CARB compliance officers. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs trade records for optical component imports, and KBA type-approval statistics. Bottom-up equipment procurement tracking and top-down regulatory mandate scaling were triangulated against manufacturer facility expansion announcements.
Historical equipment deployment patterns were cross-referenced against regulatory panel input from Stuttgart, Ann Arbor, and Shanghai industry clusters. The analytical framework modeled segmentation across product type, technology tier, vehicle application, and end-user category throughout the forecast period. CAGRs were derived from regulatory mandate timing, equipment replacement cycles, and production volume scaling. Forecast inputs included Euro 7 preparation timeline acceleration, EPA heavy-duty in-use testing program expansion, and India BIS laboratory accreditation growth.
Caveats apply where regulatory divergence between EPA and European type-approval protocols, semiconductor supply chain disruptions, or spectroscopy specialist labor shortages could materially shift the outlook. Forecasts reflect documented assumptions regarding mandate implementation schedules and equipment upgrade compliance deadlines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market