
 Automotive Prognostics Market | 2026-2036
Automotive Prognostics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Prognostics Market Intelligence
The EU Green Deal and its associated 'right to repair' initiatives are pivoting original equipment manufacturers toward designing vehicles with longer operational lifespans. This shift requires sophisticated component health monitoring. Robert Bosch GmbH leverages its system expertise in powertrain and electronics to offer integrated prognostic solutions. Denso Corporation specializes in advanced sensor technologies that feed crucial data to predictive algorithms, while NXP Semiconductor N.V. provides the processing hardware essential for on-board analysis.
Automotive prognostics involves systems that predict component failure by analyzing real-time vehicle data, often using algorithms with less than a 5% error margin on remaining useful life (RUL) estimates. Its primary purpose is to enable predictive maintenance, reducing unplanned downtime and ownership costs. Machine learning technology is displacing traditional signal processing due to its superior accuracy in fault prediction. Within applications, condition monitoring represents a mature segment, while maintenance scheduling represents the fastest-growing area as service providers adopt data-driven models.
Regulatory frameworks like the US EPA's On-Board Diagnostics (OBD) standards and the EU's type-approval system under Regulation (EU) 2018/858 mandate data accessibility for emissions and safety systems. These rules create a foundational data layer that prognostic systems build upon. The central decision for vehicle assemblers now involves whether to develop proprietary prognostic algorithms in-house or partner with specialized software providers for faster market entry.
Market Dynamics
The automotive prognostics market's central dynamic is the transition from reactive, failure-based maintenance to predictive, data-driven service models. This shift is enabled by the proliferation of onboard sensors and vehicle connectivity, creating a rich data stream for analysis.
Growth Catalysts
- Regulatory Mandates:The European Union's General Safety Regulation (GSR) compels the inclusion of advanced, data-generating systems like driver monitoring, creating a foundational layer for prognostic services to build upon.
- Commercial Fleet Economics:Demand from commercial fleet operators for solutions that minimize unplanned vehicle downtime and reduce total cost of ownership is a primary economic driver for prognostic system adoption.
- NEV Architecture:The inherently digital and sensor-rich nature of New Energy Vehicles (NEVs), particularly in production centers like China, provides a native platform for sophisticated battery and powertrain prognostics.
Market Restraints
- Data Governance and Privacy:Ambiguity and regional variation in data ownership laws, such as those influenced by GDPR in Europe, create friction between vehicle owners, OEMs, and service providers, limiting data sharing.
- Legacy System Integration:The high cost and technical complexity of retrofitting older vehicle models with the necessary sensors and telematics hardware present a significant barrier to market expansion beyond new vehicles.
- Lack of Standardization:The absence of universal data communication protocols and diagnostic standards across different automotive manufacturers complicates the development of interoperable, third-party prognostic solutions.
Strategic Opportunities
- Expansion to Non-Powertrain Systems:Extending prognostic capabilities beyond the engine and transmission to chassis components, ADAS sensors, and thermal management systems offers significant white space for growth and differentiation.
- Insurance Telematics Integration:Converging prognostic data with usage-based insurance (UBI) models allows insurers to offer dynamic premiums based on real-time vehicle health and driver behavior, creating new revenue streams.
- Aftermarket Service in Emerging Economies:Providing prognostic solutions for the aging vehicle parc in markets across Southeast Asia and Latin America represents a significant opportunity as connectivity infrastructure improves.
Industry Challenges
- Specialized Talent Scarcity:A shortage of data scientists and machine learning engineers who possess both advanced analytical skills and deep automotive domain expertise constrains algorithm development and validation.
- Algorithm Validation and Liability:Establishing the accuracy and reliability of Remaining Useful Life (RUL) predictions to satisfy legal and insurance requirements remains a complex technical and operational hurdle for all providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Prognostics Market |
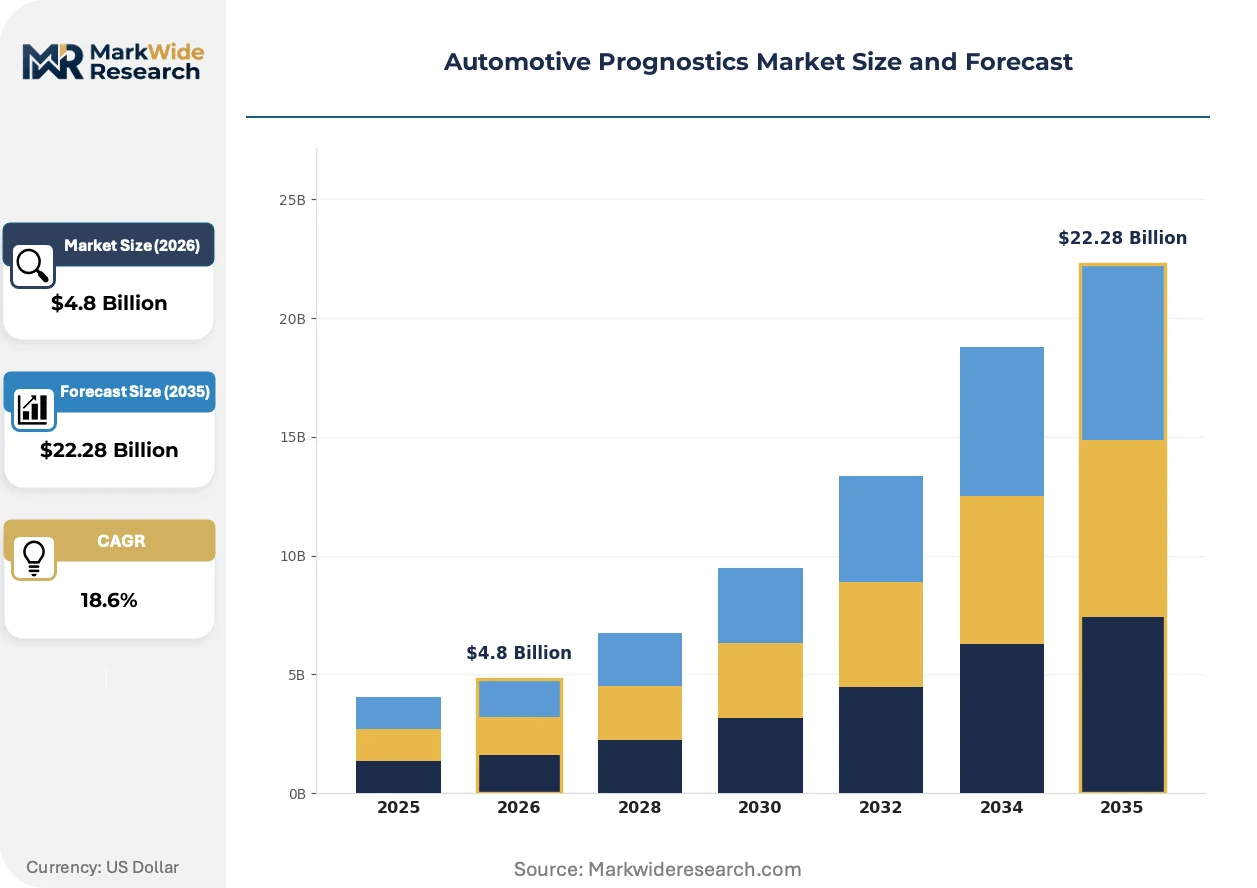
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Controllers, Diagnostic Tools, Communication Modules Technology: Machine Learning, Vibration Analysis, Thermal Imaging, Signal Processing Application: Condition Monitoring, Fault Prediction, Wear Analysis, Maintenance Scheduling End User: Vehicle Assemblers, Tier-1 Suppliers, Aftermarket Providers, Dealerships |
| Companies Covered | Siemens Mobility, Denso Corporation, Robert Bosch GmbH, NXP Semiconductor N.V., Magna International Inc., Continental AG, Garrett Motion Inc., Infineon Technologies AG, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Prognostics Market Strategic Shifts & Innovations
Software and data analytics are redefining vehicle value, shifting focus from mechanical durability to guaranteed operational uptime. This evolution transforms vehicles into service delivery platforms, with prognostics as the core enabling technology for ensuring reliability and efficiency.
Digital twin technology creates a dynamic, virtual replica of a physical vehicle system using real-time sensor data. While pioneered in aerospace, it is now being adopted by commercial and heavy-duty vehicle manufacturers for complex systems. The ability to simulate component stress and degradation under diverse operational scenarios is rewriting traditional approaches to lifecycle management and predictive maintenance.
The European Union's Regulation (EU) 2018/858 ensures that independent repairers have access to vehicle diagnostic and maintenance information. This policy directly counteracts OEM tendencies to create closed data ecosystems, fostering a more competitive market for advanced diagnostic tools. The independent aftermarket segment is most affected, gaining a legal foundation to offer services that compete with franchised dealerships.
Fleet operators are increasingly procuring vehicle uptime through comprehensive service-level agreements rather than just purchasing physical trucks. This model disrupts the conventional separation of vehicle sales and after-sales service parts and labor. This trend is most visible in the North American and European logistics sectors, where the financial cost of vehicle downtime is exceptionally high.
Automotive Prognostics Market Segmentation
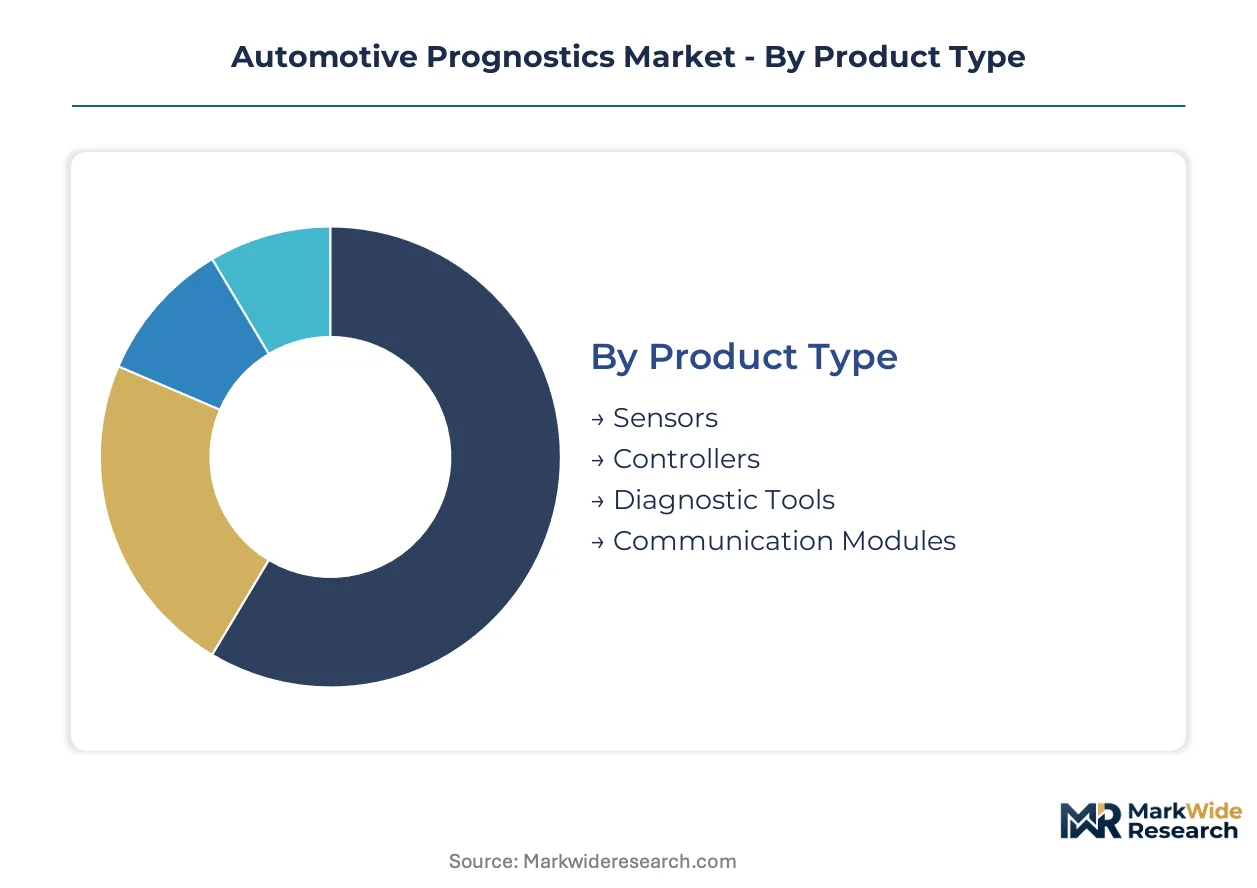
The automotive prognostics market segmentation highlights the diverse technological approaches and end-user requirements driving its expansion. Understanding these segments is crucial for stakeholders to tailor solutions that address specific operational challenges and capitalize on emerging demand for predictive maintenance.
Product Type:
The supply concentration for automotive prognostics product types reflects the foundational hardware required for data collection and processing.
- Sensors:These components generate real-time operational data from various vehicle systems, crucial for feeding predictive algorithms. Demand concentrates in New Energy Vehicles (NEVs) and commercial fleets, driven by the need for comprehensive component health monitoring.
- Diagnostic Tools:These systems interpret vehicle data streams to identify potential faults and recommend maintenance actions. Aftermarket providers and franchised dealerships represent significant demand, compelled by regulatory mandates like the US EPA's On-Board Diagnostics (OBD) standards.
- Controllers:These units integrate sensor inputs and execute prognostic algorithms for on-board data processing and analysis.
- Communication Modules:These devices facilitate secure and efficient data transmission from vehicles to cloud-based analysis platforms.
'Diagnostic Tools' absorbs the bulk of installed capacity; 'Sensors' is expanding most quickly.
Technology:
The application scope of various technologies within automotive prognostics defines their utility and accuracy in predicting component failures.
- Machine Learning:This technology employs advanced algorithms to analyze complex, multi-dimensional data patterns, offering superior accuracy in Remaining Useful Life (RUL) predictions. Advanced fault prediction across critical powertrain components drives demand, particularly in high-value commercial assets.
- Signal Processing:This discipline utilizes mathematical techniques to analyze raw sensor data for anomaly detection and feature extraction. It underpins many traditional diagnostic systems, with established demand in baseline condition monitoring applications.
- Vibration Analysis:This technique detects component wear and impending failures through characteristic frequency changes in mechanical vehicle components.
- Thermal Imaging:This method identifies abnormal heat signatures indicative of component stress or failure, particularly relevant for battery packs and power electronics.
Machine Learning technology holds the most significant promise for future accuracy improvements, while Signal Processing remains foundational for real-time data interpretation.
Application:
The customer type driving specific applications within automotive prognostics emphasizes the shift towards proactive vehicle management.
- Maintenance Scheduling:This application optimizes service intervals based on predicted component health, minimizing unplanned downtime and operational costs. Commercial fleet operators represent a key customer segment, seeking to maximize vehicle uptime and asset utilization.
- Condition Monitoring:This application continuously assesses the operational state of vehicle components to detect deviations from normal behavior. Vehicle assemblers integrate this for warranty management, particularly for high-value powertrain systems.
- Fault Prediction:This application anticipates specific component failures before they occur, enabling proactive intervention and efficient parts ordering.
- Wear Analysis:This application quantifies component degradation over time, informing lifecycle management and replacement strategies for vehicle components.
Maintenance Scheduling is witnessing the steepest expansion trajectory, driven by fleet operational efficiencies, whereas Condition Monitoring provides the foundational data layer.
End User:
The margin structure for automotive prognostics end users illustrates where value is captured across the vehicle lifecycle.
- Aftermarket Providers:These entities offer diagnostic and maintenance services for a wide range of vehicle models, leveraging prognostics for competitive advantage. Regulatory frameworks like the EU's Regulation (EU) 2018/858 support their access to critical vehicle data.
- Vehicle Assemblers:These manufacturers integrate prognostic capabilities directly into new vehicle designs, enhancing reliability and reducing warranty claims. Their focus lies on proprietary system development for critical components like NEV powertrains.
- Tier-1 Suppliers:These companies develop and supply prognostic-enabled components and sub-systems directly to vehicle manufacturers.
- Dealerships:These service providers utilize prognostic data to offer targeted service campaigns and improve customer retention through proactive maintenance recommendations.
Vehicle Assemblers command the highest value capture through integrated solutions, while Aftermarket Providers are gaining share fastest through data accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Automotive Prognostics Market exhibits a distinct production-consumption divide, with key manufacturing hubs in Asia and Europe driving technological advancements. Demand for predictive maintenance solutions concentrates heavily in regions with large commercial fleets and robust New Energy Vehicle production. This global market landscape shapes the adoption and development of prognostic systems across diverse geographies.
China
China's massive New Energy Vehicle (NEV) production and strong policy support drive significant demand for advanced prognostics. The country's dual carbon goals promote NEV adoption and associated digital technologies for battery and powertrain health monitoring. Shanghai and Shenzhen represent key innovation hubs for NEV manufacturing and advanced automotive software development.
Germany
Germany's established automotive industry and stringent environmental regulations fuel the demand for sophisticated prognostic solutions. The EU Green Deal and General Safety Regulation (GSR) compel advanced vehicle safety and diagnostic systems integration. Stuttgart and Munich host major automotive OEMs and Tier-1 suppliers developing integrated prognostic solutions.
United States
United States commercial fleet operations and strict emissions standards contribute to the demand for predictive maintenance technologies. The US EPA's On-Board Diagnostics (OBD) standards create a foundational data layer for prognostic systems. Detroit remains a central hub for automotive innovation, with increasing investment in predictive maintenance technologies for heavy-duty vehicles.
Japan
Japan's focus on advanced sensor technologies and high-reliability automotive components underpins the expansion of prognostic applications. METI initiatives support research and development in smart mobility and vehicle health monitoring systems. The Tokyo and Nagoya regions are centers for sophisticated electronics manufacturing and automotive engineering, fostering prognostic algorithm development.
India
India's rapidly expanding vehicle parc and a growing emphasis on operational efficiency for commercial transport create opportunities for aftermarket prognostics. Government policies under the PLI scheme encourage local manufacturing of advanced automotive components, including sensors and diagnostic tools. Pune and Chennai are emerging as significant automotive manufacturing and R&D centers, attracting investment in aftermarket prognostic solutions.
Automotive Prognostics Market Key Industry Players
The competitive structure tilts toward established automotive suppliers and specialized technology providers. The market exhibits a tiered structure, with large Tier-1 suppliers dominating the integrated solutions segment and smaller software firms focusing on niche algorithm development. Strategic partnerships between hardware manufacturers and analytics specialists represent a dominant competitive move. Portfolio diversification into advanced sensor technologies and machine learning capabilities also shapes market dynamics.
Within the established automotive technology providers, Robert Bosch GmbH, a leading German engineering and electronics company, exemplifies comprehensive system expertise spanning powertrain and electronics. Denso Corporation, a Japanese multinational automotive components manufacturer, represents a key player specializing in advanced sensor technologies crucial for feeding predictive algorithms. NXP Semiconductor N.V., a Dutch-American semiconductor manufacturer, anchors the processing hardware segment essential for on-board data analysis. These entities collectively demonstrate the diverse capabilities required to deliver end-to-end prognostic solutions, from data acquisition to complex algorithmic processing.
| Leading Market Players |
|---|
| Siemens Mobility |
| Denso Corporation |
| Robert Bosch GmbH |
| NXP Semiconductor N.V. |
| Magna International Inc. |
| Continental AG |
| Garrett Motion Inc. |
| Infineon Technologies AG |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
Software-defined vehicles and connected ecosystems redefine cost economics for automotive prognostics, centralizing supply chain power in specialized software and hardware providers. This transition impacts both pricing models and component availability.
Pricing Analysis
Margin tightening in the aftermarket segment reflects intensified competition from independent service providers leveraging data access. Prognostic solutions often employ a value-based pricing model, with tiered subscription services for commercial fleet operators seeking guaranteed uptime. Customization level and the accuracy of Remaining Useful Life (RUL) estimates act as key price differentiation drivers. Vehicle assemblers exhibit lower price sensitivity for integrated systems, valuing brand reputation and warranty management, while aftermarket providers prioritize cost-effectiveness.
Supply Chain Analysis
Direct-to-OEM channels dominate the distribution of integrated prognostic hardware and software solutions, particularly for new vehicle platforms. Geographic supply for critical semiconductor components primarily originates from Taiwan, South Korea, and the United States, impacting global availability. Prognostic systems rely on advanced sensor technologies, microcontrollers, and communication modules, creating single-source vulnerability for specialized processing hardware. Aftermarket distribution leverages existing diagnostic tool networks and third-party software providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive prognostics market is fundamentally a vertical-integration race, with players aggressively pursuing proprietary software development as a core differentiating lever. This strategic focus aims to control the entire data value chain.
For Market Incumbents: Cement existing relationships with vehicle assemblers by offering integrated, end-to-end prognostic solutions from hardware to algorithms. Consolidate market share through strategic acquisitions of niche software providers specializing in machine learning for RUL predictions. The threat of independent aftermarket players gaining data access necessitates continuous innovation in proprietary system development. Vertical integration into advanced sensor manufacturing can secure critical component supply. For New Entrants and Emerging Players: The EU's Regulation (EU) 2018/858 in Europe opens a window for specialized software firms to offer advanced diagnostic tools to the independent aftermarket. Target non-powertrain systems like ADAS sensors and thermal management, which represent significant white space. Focus on providing cost-effective, interoperable solutions for aging vehicle fleets in emerging economies like India. A partnership-driven go-to-market angle with existing repair networks can accelerate adoption. For Investors and Strategic Acquirers: Exit pathways primarily involve specialized software analytics firms with proven machine learning capabilities for predictive maintenance. Long-term viability over the next decade hinges on the ability to integrate diverse data streams and provide accurate RUL estimates. Target acquisition profiles include companies with robust intellectual property in digital twin technology or advanced sensor fusion algorithms. A key inflection indicator is the widespread adoption of service-level agreements by commercial fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Develop proprietary AI/ML algorithms | This enhances fault prediction accuracy for critical powertrain components, differentiating OEM offerings. |
| Expand prognostic capabilities to non-powertrain systems | Capturing white space in ADAS sensors and thermal management systems creates new revenue streams. |
| Form strategic partnerships with telematics providers | Integrating vehicle connectivity data enables comprehensive real-time condition monitoring for fleets. |
| Invest in digital twin technology for complex systems | Simulating component degradation under diverse operational scenarios redefines lifecycle management for heavy-duty vehicles. |
| Offer outcome-based service-level agreements | This aligns with fleet operator demand for guaranteed uptime, shifting focus from parts sales. |
Research Approach
Trade association data, regulatory filings, and vehicle production databases anchored secondary inputs for this analysis. Primary interviews were conducted with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and fleet operations managers. This fieldwork provided qualitative insights that were cross-referenced with quantitative data. Bottom-up market sizing and top-down validation ensured robust triangulation across all data points.
Market volume and value were modeled across product type, technology, application, and end-user segments, alongside vehicle class. An iterative, regression-based approach derived compound annual growth rates over the projection horizon. Key forecast inputs included New Energy Vehicle (NEV) production forecasts and commercial fleet expansion rates. This framework integrated macroeconomic factors influencing automotive sector growth.
The model assumes a particular technology adoption path; alternative pathways for machine learning integration could alter the outlook. Forecasts reflect assumptions regarding regulatory stability and data governance frameworks, where geopolitical events or unforeseen supply chain disruptions represent key risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Automotive Simulation Software Market