
 Automated Guided Cart Market | 2026-2036
Automated Guided Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Guided Cart Market Outlook
Buyer concentration among automotive and e-commerce fulfillment operators is hardening as large-scale manufacturing facilities and warehouse operators consolidate material handling procurement under single-vendor frameworks. Daifuku Co., Ltd. leverages its integrated conveyor and AGV portfolio to anchor high-volume automotive assembly contracts. Seegrid Corporation specializes in vision-based navigation systems that compete on deployment speed in brownfield warehouse environments.
An automated guided cart is a self-propelled, battery-powered vehicle that follows predefined paths or dynamic routes to transport materials, typically operating at speeds up to 2 meters per second with payload capacities ranging from 500 kilograms to several tons depending on configuration. These systems eliminate manual forklift dependency in repetitive horizontal transport loops within industrial and commercial facilities. Unit load carriers dominate installed base volumes in heavy manufacturing, while vision-based systems represent the fastest-expanding technology segment as camera and AI processing costs decline. Tow cart configurations sustain durable demand in automotive sequencing operations where multiple trailers consolidate parts delivery to assembly stations.
FDA facility design guidelines for pharmaceutical manufacturing, OSHA powered industrial truck standards, and ISO 3691-4 safety requirements for driverless trucks collectively shape product certification burdens and deployment protocols across end-use sectors. The EU Machinery Directive and CE marking obligations add compliance layers for suppliers serving European manufacturing and warehouse operators. Stakeholders must weigh navigation technology bets against evolving safety standard harmonization as regional regulators tighten autonomous vehicle workplace integration rules.
Market Dynamics
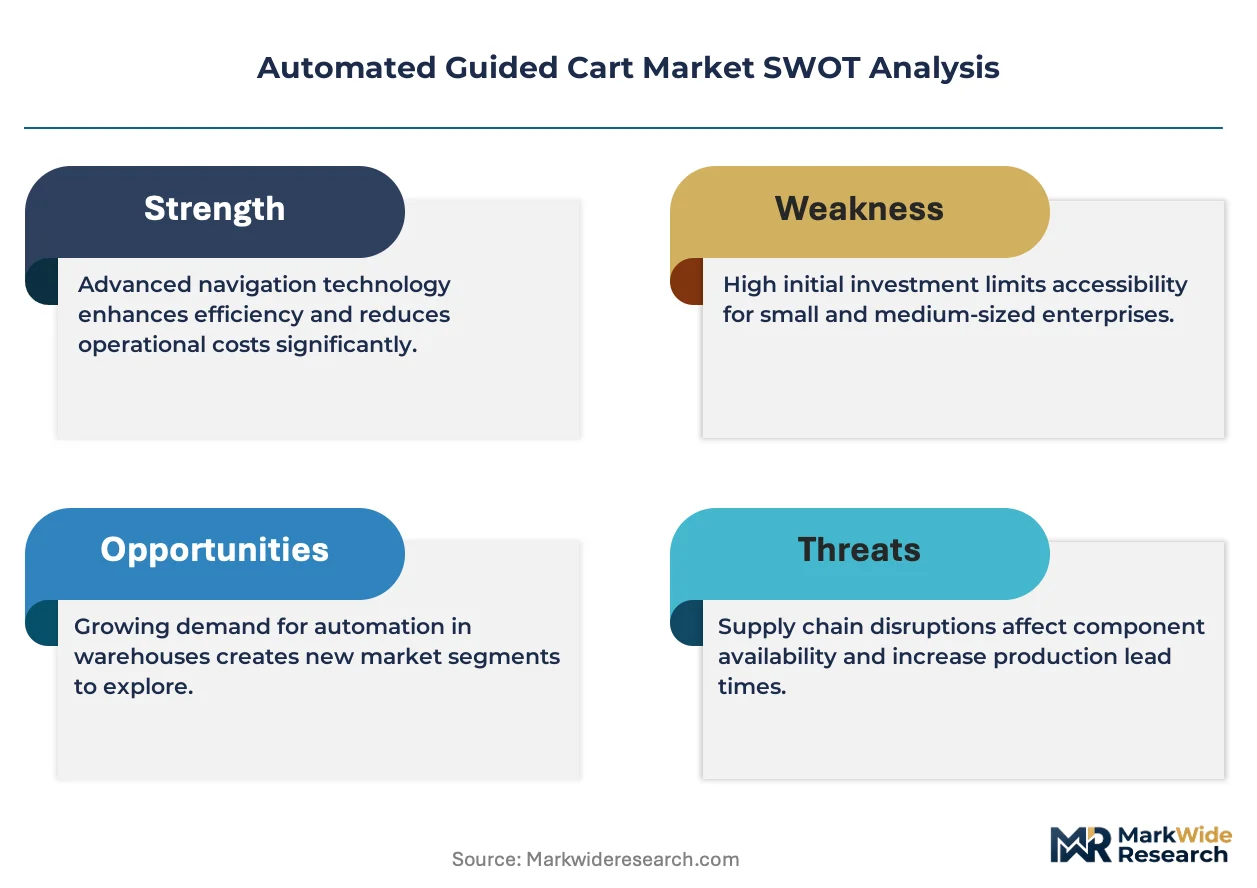
ISO 3691-4 safety mandates and OSHA workplace directives are compressing deployment timelines for autonomous mobile equipment while simultaneously elevating vendor qualification barriers across automotive and pharmaceutical manufacturing.
Growth Catalysts
- Just-in-time assembly feeding:Automotive OEMs in Germany are scaling vision-guided cart fleets to eliminate forklift traffic from production zones. Tier suppliers follow with synchronized sequencing deployments.
- ISO 3691-4 harmonization:The standardization of safety requirements for driverless industrial trucks reduces cross-border certification friction for European suppliers.
- Camera-lidar fusion:Declining sensor costs enable brownfield warehouse operators to retrofit existing facilities without infrastructure modifications.
Market Restraints
- Lithium battery supply concentration:Cell production capacity clusters in China creates input vulnerability for cart manufacturers dependent on regional battery sourcing.
- CE marking complexity:EU Machinery Directive compliance layers add six-to-twelve-month certification cycles that delay European revenue recognition.
- Manual forklift residual economics:Existing equipment fleets in mature manufacturing bases sustain substitution resistance where labor arbitrage remains viable.
Strategic Opportunities
- Cold-chain pharmaceutical logistics:FDA facility design guidelines for temperature-controlled manufacturing create validated AGV demand in aseptic fill-finish operations.
- 5G-private network convergence:Ultra-reliable low-latency connectivity enables real-time fleet coordination in high-density warehouse configurations previously unreachable.
- India PLI scheme:Production-linked incentives for advanced manufacturing equipment reduce effective capital costs for domestic automotive and electronics assemblers.
Industry Challenges
- Functional safety engineering scarcity:ISO 13849 and IEC 62061 competency gaps constrain vendor capacity to execute simultaneous multi-site deployments.
- Brownfield integration complexity:Legacy warehouse management systems require custom middleware development that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Guided Cart Market |
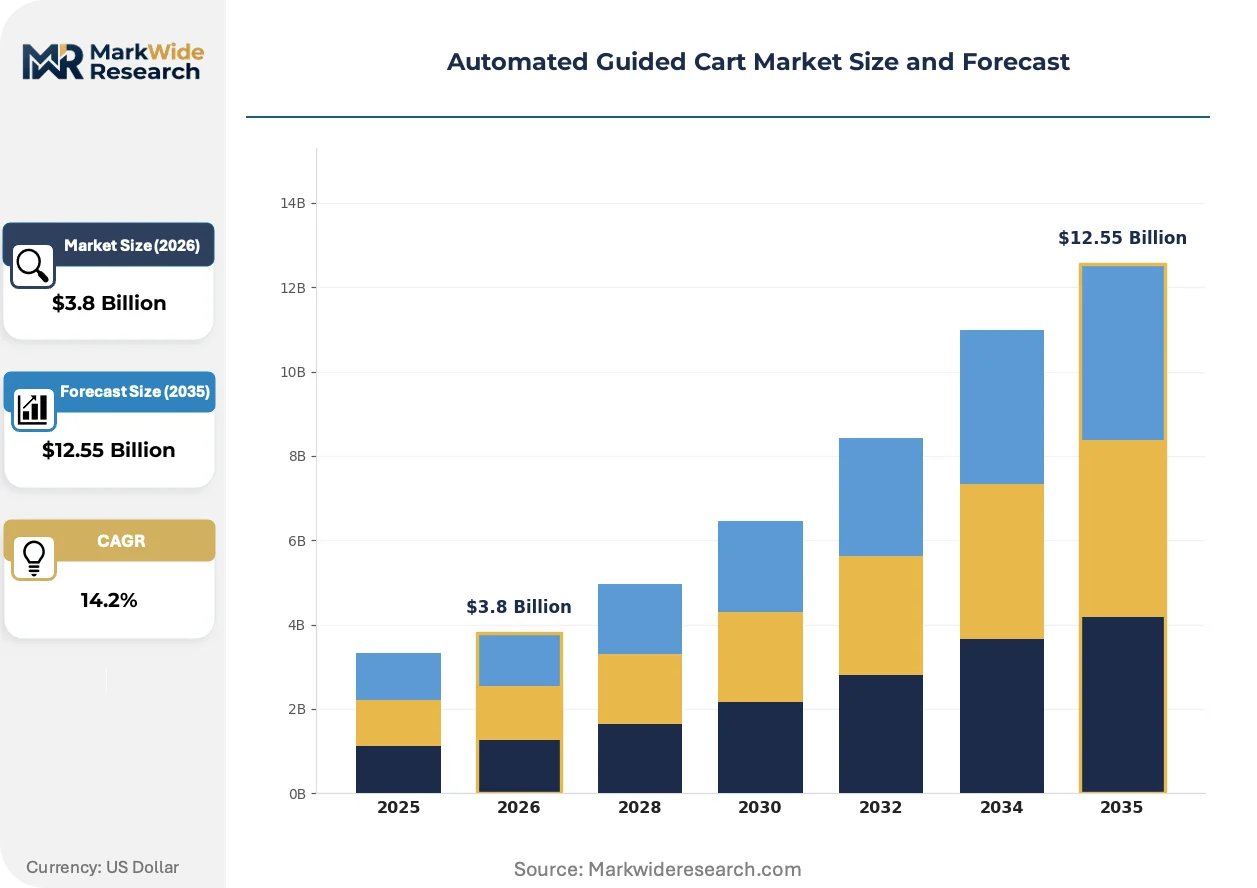
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit Load Carrier, Tow Cart, Delivery Cart, Sorting Cart End User: Manufacturing Facilities, Warehouses, Hospitals, Retail Stores Technology: Laser Guidance, Magnetic Navigation, Optical Navigation, Vision-Based Systems Application: Material Handling, Inventory Management, Distribution, Automated Transportation |
| Companies Covered | Daifuku Co., Ltd., JBT Corporation, Toyota Industries Corporation, KUKA AG, SSI Schaefer, Hyster-Yale Materials Handling, Dematic, Seegrid Corporation, EK Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Guided Cart Market Strategic Shifts
Navigation architecture is pivoting from magnetic tape and laser reflector dependence toward camera-based simultaneous localization and mapping, compressing infrastructure requirements and deployment economics.
Vision-based navigation is consolidating market preference as automotive assembly plants in Germany and the United States eliminate floor-mounted guidance infrastructure. Tier suppliers in sequencing operations adopt camera-guided tow carts to reconfigure routes without facility downtime. The technology is consolidating vendor competitive advantage around software differentiation rather than mechanical engineering scale.
OSHA powered industrial truck standards and ISO 3691-4 safety requirements are tightening collision avoidance and emergency stop specifications for autonomous equipment. Manufacturers must redesign sensor arrays and control systems to satisfy divergent regional certification timelines. Pharmaceutical and food processing facilities face the steepest compliance burden due to cleanroom validation requirements layered atop safety mandates.
Buyer consolidation under single-vendor material handling frameworks is displacing point-solution procurement. Large automotive OEMs and e-commerce fulfillment operators negotiate enterprise-wide AGV contracts covering multiple facilities. Germany hosts the most concentrated procurement activity, with automotive clusters around Stuttgart and Wolfsburg driving standardization across supplier tiers.
Automated Guided Cart Market Segmentation
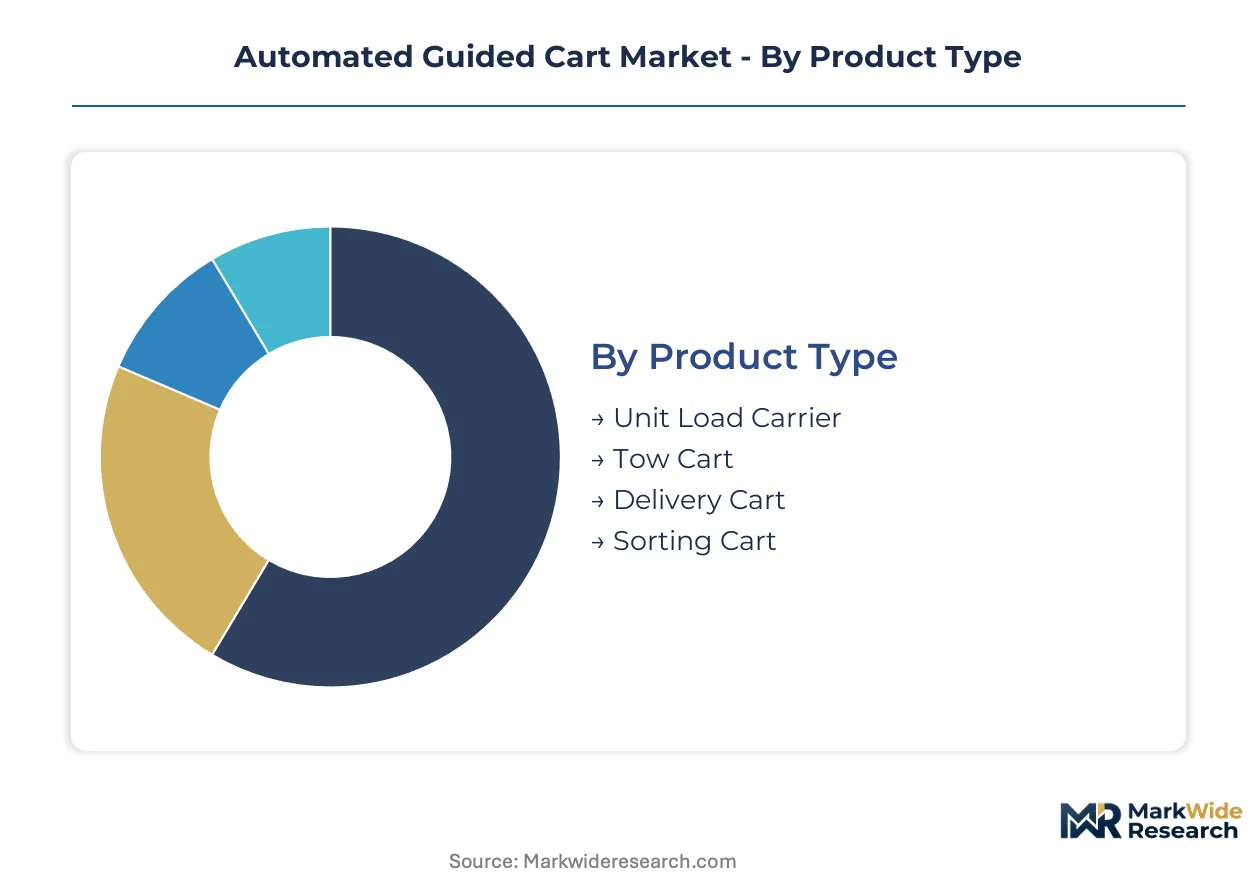
Automated guided cart procurement decisions hinge on payload geometry, navigation infrastructure costs, and facility retrofit complexity. Buyers weigh mechanical configuration against software flexibility when specifying fleet deployments across manufacturing and logistics operations.
Product Type:
Payload volume and trailer coupling requirements dominate capital allocation across product configurations.
- Unit Load Carrier:Self-contained platforms transport palletized or containerized loads up to several tons without external trailers. Heavy manufacturing facilities in Germany deploy these for direct-to-line feeding of stamped body panels and powertrain components.
- Tow Cart:Tractor units pull multiple trailers in train configurations, consolidating parts delivery to assembly stations. Automotive sequencing operations around Stuttgart sustain durable demand for reconfigurable tow cart fleets that adapt to model-mix changes without infrastructure modification.
- Delivery Cart:Compact chassis designed for point-to-point transport of smaller payloads in confined facility layouts.
- Sorting Cart:Integrated lift mechanisms and conveyor interfaces enable automated load transfer at pick-and-drop stations.
Unit load carriers lead on scale; vision-guided tow carts lead on momentum.
End User:
Operational tempo and labor cost arbitrage determine adoption timing across facility types.
- Manufacturing Facilities:Just-in-time assembly lines require synchronized material flow with cycle-time precision measured in seconds. Automotive OEMs in Germany and tier suppliers consolidate procurement under multi-site enterprise contracts.
- Warehouses:E-commerce fulfillment operators prioritize deployment speed in brownfield buildings where magnetic tape installation is impractical. Camera-lidar fusion systems eliminate floor infrastructure while satisfying OSHA powered industrial truck standards.
- Hospitals:Sterile supply transport and linen distribution demand quiet operation and bioburden-resistant surface finishes.
- Retail Stores:Back-of-house restocking applications favor compact footprints and pedestrian-aware navigation.
Manufacturing facilities anchor current installed base; warehouse operators are expanding most quickly.
Technology:
Navigation architecture selection determines upfront infrastructure investment and long-term route flexibility.
- Vision-Based Systems:Camera arrays and onboard AI processors construct facility maps without floor-mounted guidance infrastructure. Brownfield warehouse operators in the United States and Germany favor these for retrofit deployments where downtime is constrained.
- Laser Guidance:Reflector-based triangulation delivers centimeter-level positioning accuracy in high-bay storage environments. Cold-chain pharmaceutical facilities specify laser guidance for validated repeatability in temperature-controlled zones.
- Magnetic Navigation:Floor-embedded tape or wire guidance provides interference-resistant operation in metal-intensive manufacturing zones.
- Optical Navigation:Color-coded floor markings or barcodes enable low-cost guidance for simple loop configurations.
Magnetic navigation retains legacy installed base; vision-based systems gain share fastest.
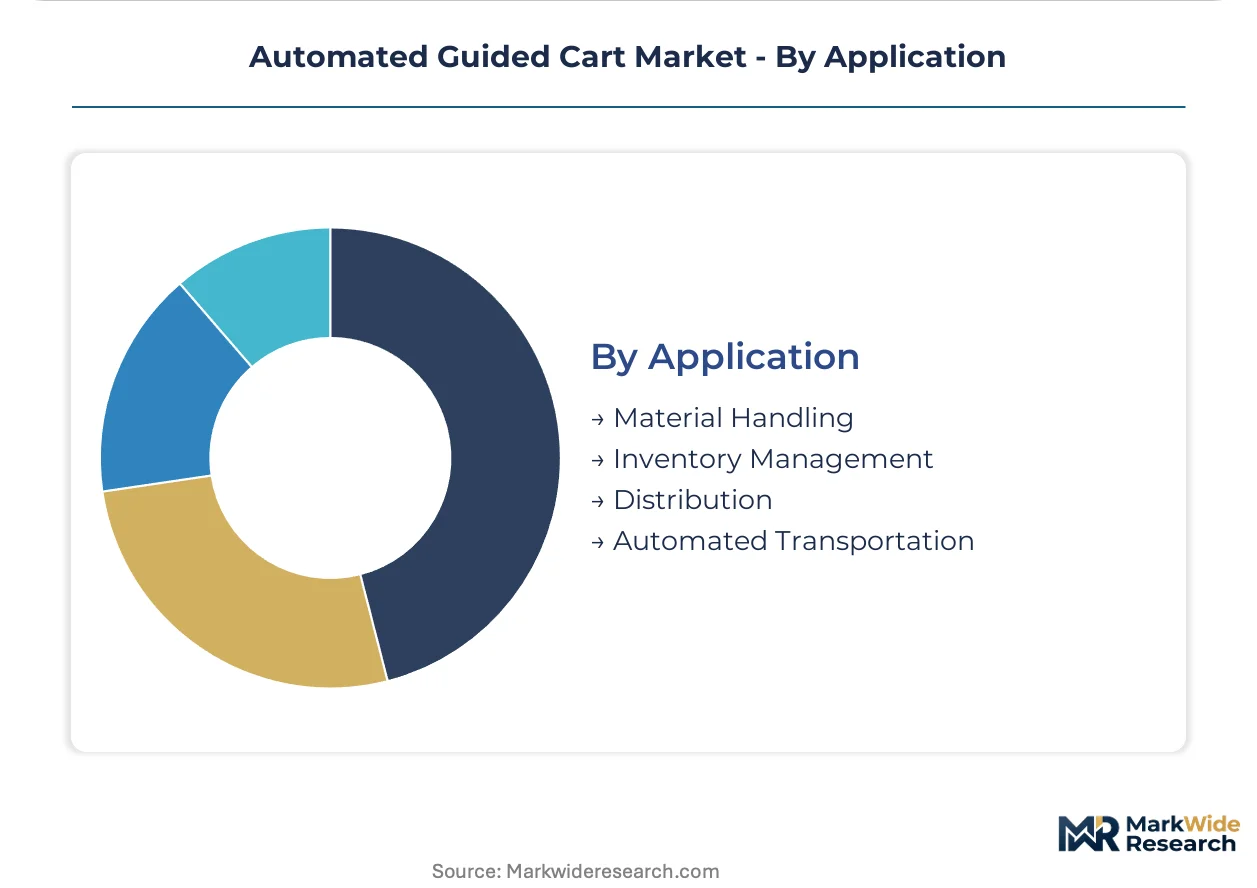
Application:
Workflow integration depth shapes software requirements and fleet management complexity.
- Material Handling:Repetitive horizontal transport between fixed origin-destination pairs constitutes the core value proposition. Automotive assembly plants eliminate forklift traffic from production zones using sequenced cart delivery.
- Inventory Management:Real-time location tracking and cycle-counting integration extend cart utility beyond pure transport. Warehouse management system middleware development extends commissioning timelines for these deployments.
- Distribution:Cross-dock operations and shipping consolidation demand high-speed traversal of large-footprint facilities.
- Automated Transportation:Inter-facility or outdoor routing requires enhanced sensor suites and regulatory compliance beyond indoor industrial truck standards.
Material handling commands volume concentration; inventory management shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys vision-guided cart fleets at scale for automotive sequencing, while the United States prioritizes brownfield warehouse retrofits where infrastructure-free navigation eliminates floor-mounted guidance systems. China concentrates cell production for lithium battery supply, creating input vulnerability for cart manufacturers elsewhere. India leverages production-linked incentives to reduce capital costs for domestic assemblers.
Germany
Automotive OEMs and tier suppliers around Stuttgart and Wolfsburg drive standardized procurement across supplier networks. ISO 3691-4 harmonization reduces cross-border certification friction for European suppliers serving these clusters. The Baden-Württemberg automotive corridor hosts the most concentrated vision-guided tow cart deployments for just-in-time assembly feeding.
United States
E-commerce fulfillment operators demand deployment speed in legacy warehouse buildings where magnetic tape installation is impractical. OSHA powered industrial truck standards tighten collision avoidance specifications for autonomous equipment. The Midwest manufacturing belt around Michigan and Ohio sustains demand for unit load carriers in heavy industrial applications.
China
Lithium battery cell production capacity clusters domestically, creating supply concentration for cart manufacturers dependent on regional sourcing. The national dual carbon goals accelerate electrification mandates across manufacturing logistics. The Yangtze River Delta industrial corridor integrates automated guided carts into electronics and automotive assembly at scale.
Japan
Precision manufacturing facilities require validated repeatability in cleanroom and semiconductor production environments. METI industrial automation initiatives support integration of mobile robotics into existing production lines. The Chubu region around Nagoya anchors automotive supplier adoption of sequenced material delivery systems.
India
The PLI scheme for advanced manufacturing equipment reduces effective capital costs for domestic automotive and electronics assemblers. BIS standards development lags European harmonization, creating certification complexity for imported systems. The Maharashtra-Gujarat industrial corridor hosts emerging demand from contract electronics manufacturers.
Automated Guided Cart Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology and mechanical engineering dimensions. The vendor base organizes into three tiers: integrated material handling conglomerates with conveyor and AGV portfolios, vision-based navigation specialists competing on software differentiation, and regional fabricators serving price-sensitive brownfield retrofits. Dominant competitive moves include enterprise-wide contract consolidation under single-vendor frameworks and navigation technology licensing partnerships that accelerate certification across regulatory jurisdictions.
Within the integrated systems tier, Daifuku Co., Ltd. and Toyota Industries Corporation represent conglomerate-scale positioning anchored by conveyor and industrial vehicle portfolios. Seegrid Corporation occupies the pure-play specialist position exemplifying vision-based navigation competition. Among European engineering groups, KUKA AG and SSI Schaefer sit within the automation-integrated tier bridging robotics and material handling domains.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| JBT Corporation |
| Toyota Industries Corporation |
| KUKA AG |
| SSI Schaefer |
| Hyster-Yale Materials Handling |
| Dematic |
| Seegrid Corporation |
| EK Robotics |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement consolidation under enterprise-wide AGV contracts compresses vendor margins while concentrating pricing power among tier-one material handling conglomerates. This buyer concentration forces suppliers to absorb ISO 3691-4 certification costs and lithium battery volatility within fixed project pricing.
Pricing Analysis
Capacity additions in China are reshaping price floors for lithium battery cells, the dominant cost component in automated guided cart manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates vision-guided systems with AI navigation from magnetic-tape legacy configurations. Cost compression in standard-tier hardware is intensifying because Chinese cell suppliers are expanding output faster than European demand absorption. Tier suppliers and brownfield warehouse operators exhibit the sharpest price sensitivity, while pharmaceutical manufacturers with FDA validation requirements accept premium positioning for certified systems.
Supply Chain Analysis
Freight cost escalation from Asia-to-Europe battery shipments is forcing geographic sourcing recalibration among cart manufacturers. Lithium cell production draws from China, South Korea, and Japan, with camera sensors and servo motors anchored in Taiwan and Germany. Single-source vulnerability concentrates in Chinese cathode material processing, exposing European assemblers to export restriction risk. Distribution runs through direct OEM contracts for large automotive fleets, with regional system integrators serving mid-size warehouse retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automated guided carts rests on camera-lidar sensor cost curves and premium-tier software differentiation displacing mechanical engineering value capture.
For Market Incumbents: To counter vision-navigation specialists eroding hardware margins, Daifuku and Toyota Industries should deepen backward integration into lithium battery pack assembly and anchor enterprise contracts with ISO 3691-4 certification bundling. Capacity addition in Germany's Baden-Württemberg corridor secures proximity to Stuttgart automotive clusters. For New Entrants and Emerging Players: Capture cold-chain pharmaceutical logistics where FDA facility design guidelines create validation barriers for undifferentiated hardware vendors. India's PLI scheme for advanced manufacturing equipment offers the most penetrable geography, with contract electronics manufacturers in the Maharashtra-Gujarat corridor seeking subsidized automation. Lead with 5G-private network integration as a deployment-speed differentiator. For Investors and Strategic Acquirers: Material handling conglomerates with conveyor-AGV integration capabilities are the most active acquirer in this space, targeting pure-play vision navigation software firms. The five-to-ten-year viability window favors vendors with functional safety engineering depth certified to IEC 62061. Watch for ISO 3691-4 harmonization completion as the signal for cross-border M&A acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vision Navigation Software Acquisition | Consolidates competitive advantage around AI differentiation rather than mechanical scale. |
| ISO 3691-4 Certification Investment | Reduces cross-border friction for European suppliers serving German automotive clusters. |
| Lithium Battery Pack Integration | Mitigates supply concentration risk from Chinese cell production capacity. |
| 5G-Private Network Partnership | Enables real-time fleet coordination in high-density warehouse configurations. |
| India PLI Scheme Localization | Captures production-linked incentives for domestic automotive and electronics assemblers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and warehouse operations directors with secondary validation against SEC filings, customs trade data, and vehicle production databases. Bottom-up unit economics and top-down sector sizing triangulated market estimates.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-2023 ISO 3691-4 implementation trajectories. The analytical framework modeled segmentation across navigation technology, payload configuration, end-use facility type, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and greenfield automation penetration curves, with lithium battery cost curves and 5G infrastructure rollout pace as key inputs.
Underlying measurement precision varies by segment; vision-based systems and automotive manufacturing applications carry tighter precision than magnetic navigation and hospital deployments. Forecasts reflect assumptions about regulatory harmonization timelines and sensor cost deflation that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Automotive Simulation Market