
 Vehicle Radar Test System Market | 2026-2036
Vehicle Radar Test System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Radar Test System Market Analysis
A shortage of millimeter-wave RF engineers is unwinding production timelines for radar test equipment across the supply chain. Robert Bosch GmbH leverages its captive semiconductor foundry to sustain vertical integration in test system components. NOFFZ Technologies specializes in automated radar-in-the-loop benches that anchor its position with Tier-1 validation programs.
Vehicle radar test systems comprise anechoic chambers, target simulators, and signal analysis hardware designed to validate 76-81 GHz automotive radar modules under reproducible electromagnetic conditions. Functional testing dominates current procurement volumes as OEMs verify object detection algorithms before homologation, while performance evaluation is gaining traction for autonomous vehicle programs requiring extended range validation. Millimeter wave technology leads equipment sales, though hybrid systems combining FMCW and pulse-Doppler architectures are capturing interest for next-generation 4D imaging radar.
FCC Part 95 rules govern radar emissions in the United States, while ETSI EN 302 858 shapes European spectrum allocation for automotive short-range radar. Japan's MIC ordinance and China's MIIT radio regulations add compliance layers for suppliers serving multi-regional OEMs. Stakeholders must track evolving UN R79 and R157 harmonization timelines, as regulatory divergence between major automotive markets directly determines test protocol complexity and capital deployment priorities for validation infrastructure.
Market Dynamics
The transition from Level 2 to Level 4 autonomy is compressing radar validation cycles as automotive OEMs demand test systems capable of verifying 4D imaging algorithms under reproducible electromagnetic conditions before homologation.
Growth Catalysts
- ECE R79 Mandate:Europe's updated steering regulation requires radar-based lane-keeping systems, forcing Tier-1 suppliers to expand validation bench capacity across Germany's automotive corridor.
- Millimeter-Wave Spectrum Harmonization:UN R79 and R157 convergence timelines are accelerating multi-regional test protocol standardization, reducing equipment reconfiguration costs for suppliers serving US, EU, and Chinese OEMs simultaneously.
- 4D Imaging Radar Deployment:FMCW-pulse-Doppler hybrid architectures require anechoic chambers with enhanced angular resolution capabilities, pulling demand from next-generation ADAS programs in Stuttgart and Ingolstadt.
Market Restraints
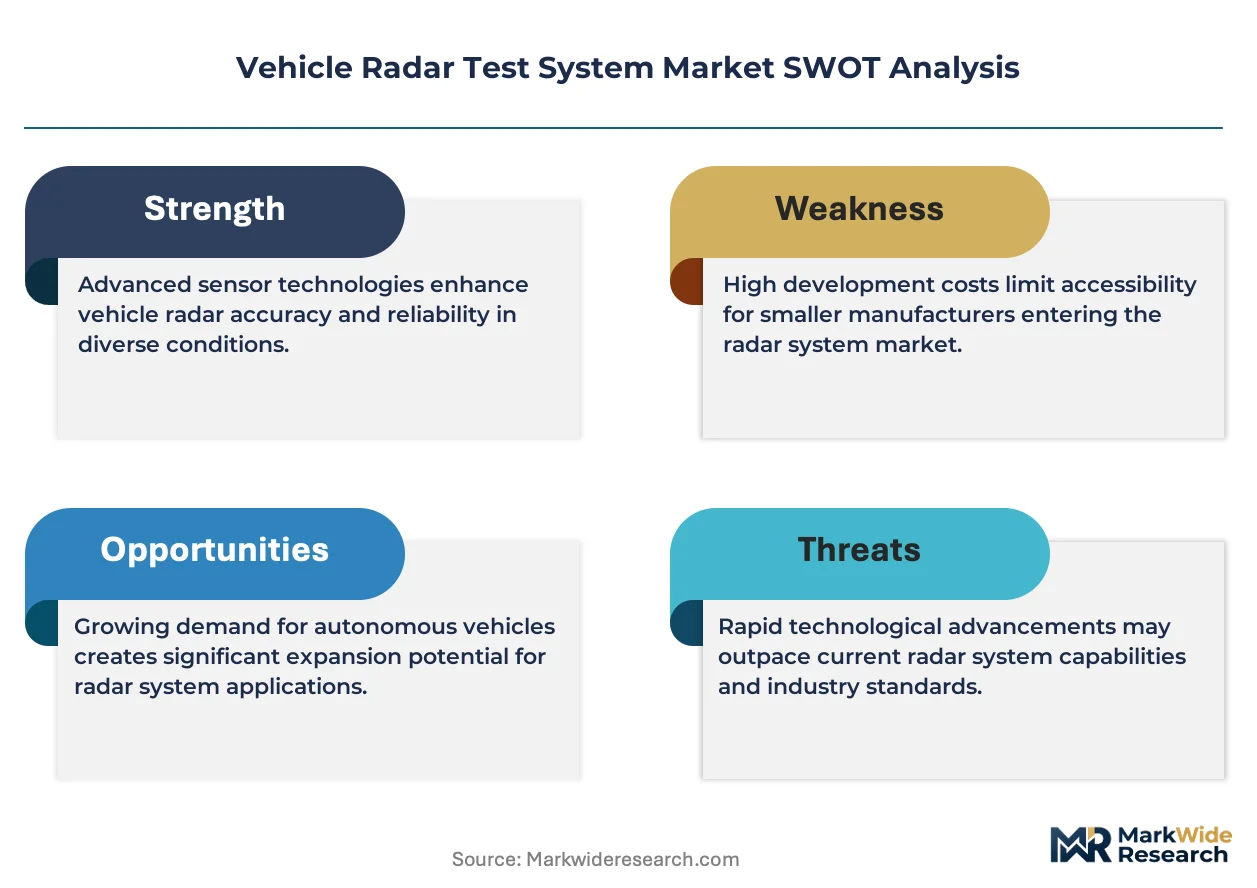
- Gallium Arsenide Substrate Volatility:RF frontend component costs fluctuate with compound semiconductor wafer pricing, squeezing margins for test equipment manufacturers dependent on external foundry supply.
- RF Engineering Talent Scarcity:Millimeter-wave circuit design expertise concentrates in Munich, Dresden, and limited US defense clusters, extending recruitment timelines for test system developers.
- Regulatory Divergence Friction:FCC Part 95, ETSI EN 302 858, and China's MIIT radio regulations maintain incompatible emission masks, forcing redundant test sequences and capital duplication for multi-market suppliers.
Strategic Opportunities
- Software-Defined Target Simulation:Digital twin integration with radar-in-the-loop benches enables scenario replication without physical anechoic chamber occupancy, opening subscription revenue streams for validation service providers.
- India PLI Scheme Alignment:Component localization incentives under India's automotive manufacturing policy create entry points for test system assembly operations serving emerging domestic EV radar suppliers.
- V2X Convergence Validation:Combined radar-DSRC test protocols for cooperative perception applications represent unaddressed white space as 5G-V2X deployment accelerates in South Korean and Japanese smart highway corridors.
Industry Challenges
- Millimeter-Wave Calibration Drift:Thermal cycling in compact anechoic chambers degrades measurement repeatability, requiring continuous recertification cycles that consume engineering bandwidth.
- Legacy CAN-FD Integration Complexity:Test systems must bridge 76-81 GHz RF validation with existing vehicle network architectures, extending commissioning timelines for OEMs with heterogeneous platform portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Radar Test System Market |
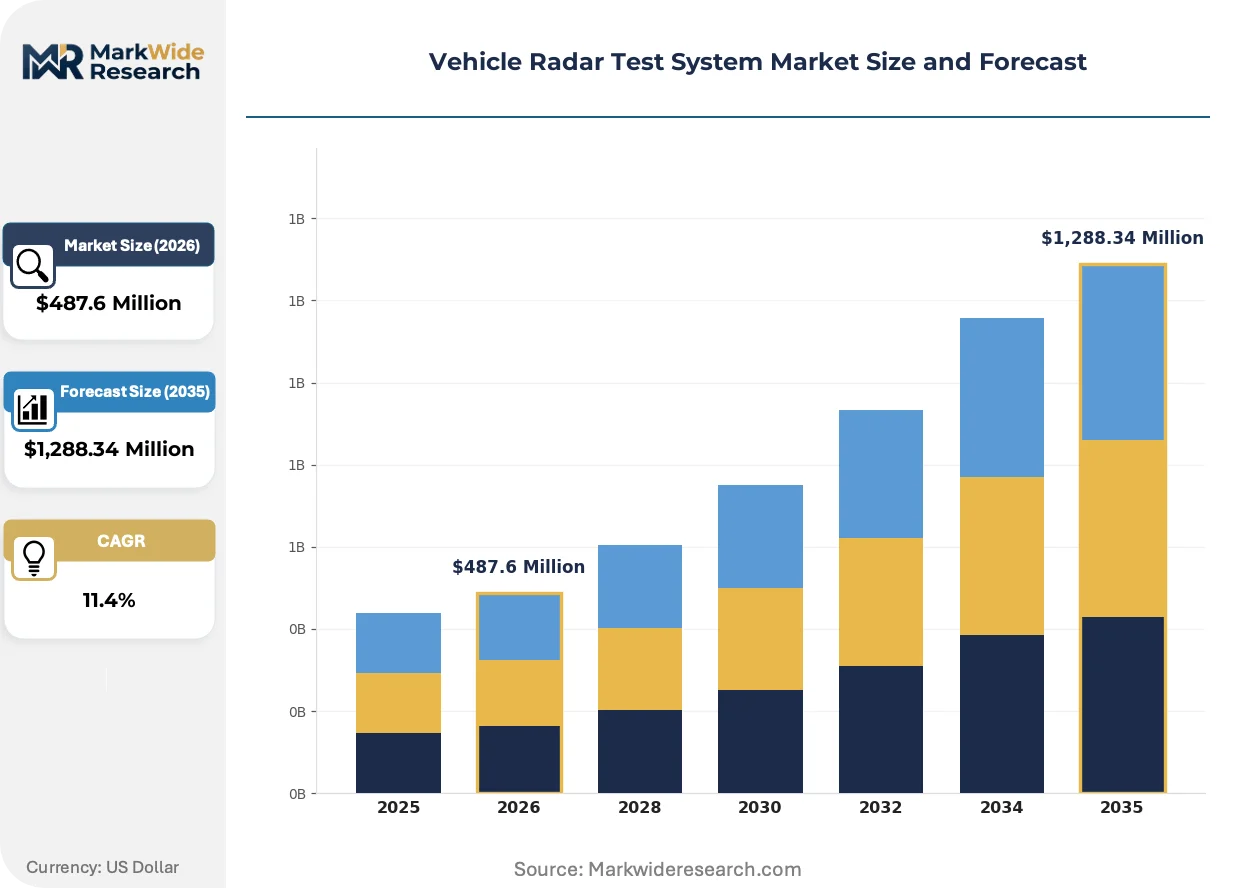
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Functional Testing, Performance Evaluation, Compliance Testing, Calibration Application: Autonomous Vehicles, Advanced Driver Assistance Systems, Safety Features, Radar Sensors End User: OEMs, Tier-1 Suppliers, Test Laboratories, Research Institutions Technology: Millimeter Wave, Frequency Modulated Continuous Wave, Pulse-Doppler, Hybrid Systems |
| Companies Covered | Denso Corporation, Aptiv, Robert Bosch GmbH, Valeo SA, NXP Semiconductors, Continental AG, Autoliv Inc., NOFFZ Technologies, Anritsu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Radar Test System Market Emerging Trajectories
Real-time target simulation is replacing static phantom testing as the dominant validation paradigm, compressing development timelines while demanding computational architectures capable of sub-millisecond latency in electromagnetic scenario rendering.
Hybrid FMCW-pulse-Doppler test architectures are displacing pure frequency-modulated systems in anechoic chamber deployments. Tier-1 suppliers in Germany's testing corridor adopt these configurations to validate elevation-angle resolution for pedestrian classification algorithms. The structural consequence is compressing equipment replacement cycles from seven years to four as 4D imaging specifications harden.
ETSI EN 302 858 spectrum allocation revisions are tightening emission mask tolerances for automotive short-range radar. European test houses must recalibrate existing benches or face accreditation suspension. German KBA homologation procedures now mandate documented margin verification against the revised limits, accelerating capital deployment toward next-generation signal analyzers.
Validation-as-a-service contracts are fragmenting traditional equipment procurement patterns. Automotive OEMs in Stuttgart and Ingolstadt now lease radar-in-the-loop capacity from specialized test houses rather than owning fixed infrastructure. South Korean battery-electric vehicle programs exhibit the most aggressive outsourcing ratios, with validation timelines contracted to eighteen-month sprint structures.
Vehicle Radar Test System Market Segmentation
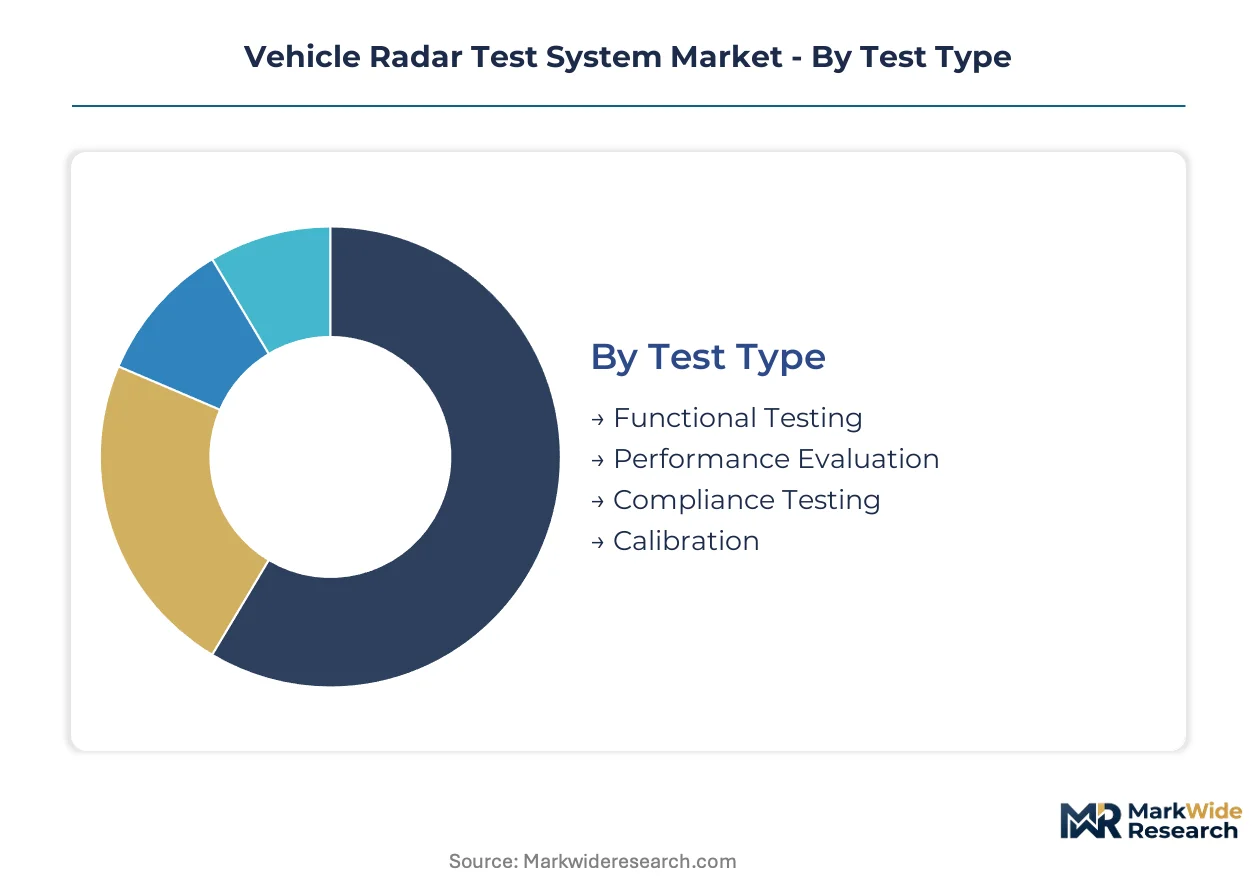
Radar validation requirements diverge sharply across test protocols, end-user capabilities, and regional regulatory frameworks. Equipment procurement patterns cluster around specific compliance mandates rather than uniform technology adoption curves.
Test Type:
FCC Part 95, ETSI EN 302 858, and Japan's MIC ordinance each impose distinct emission mask tolerances that shape test equipment specifications across procurement categories.
- Functional Testing:Object detection algorithm verification under controlled electromagnetic conditions dominates current procurement volumes. Stuttgart-based OEMs deploy these systems for pre-homologation validation of lane-keeping and adaptive cruise control modules.
- Performance Evaluation:Extended range validation for 4D imaging radar requires anechoic chambers with enhanced angular resolution. Ingolstadt testing corridors prioritize this category for autonomous vehicle programs demanding sub-degree elevation accuracy.
- Compliance Testing:Documented margin verification against ETSI EN 302 858 revised limits accelerates replacement of legacy signal analyzers.
- Calibration:Thermal cycling compensation for millimeter-wave measurement drift consumes continuous engineering bandwidth.
Functional Testing handles the majority of throughput; Performance Evaluation is the fastest mover on share.
Application:
Validation complexity escalates with autonomy levels, compressing equipment replacement cycles from seven years to four as specifications harden.
- Advanced Driver Assistance Systems:Level 2+ platforms require reproducible electromagnetic conditions for lane-keeping and collision avoidance verification. German KBA homologation procedures mandate these test sequences.
- Autonomous Vehicles:Level 4 programs demand hybrid FMCW-pulse-Doppler architectures capable of pedestrian classification algorithm validation.
- Safety Features:ECE R79 steering regulation compliance drives radar-based system mandates across European OEM portfolios.
- Radar Sensors:76-81 GHz module production lines integrate inline functional testing for manufacturing quality assurance.
Advanced Driver Assistance Systems anchors procurement volume; Autonomous Vehicles shows the steepest expansion trajectory.
End User:
Capital deployment patterns split between captive validation infrastructure and outsourced service contracts.
- Tier-1 Suppliers:NOFFZ Technologies and Robert Bosch GmbH anchor automated radar-in-the-loop bench deployments across Germany's automotive testing corridor. These stakeholders face compressed validation timelines from OEM customers.
- OEMs:Stuttgart and Ingolstadt manufacturers increasingly lease capacity rather than own fixed infrastructure.
- Test Laboratories:Validation-as-a-service providers capture South Korean battery-electric vehicle program demand through eighteen-month sprint structures.
- Research Institutions:Academic partnerships with foundry operations advance millimeter-wave RF frontend component development.
Tier-1 Suppliers concentrate capital expenditure; Test Laboratories are gaining share fastest through service model disruption.
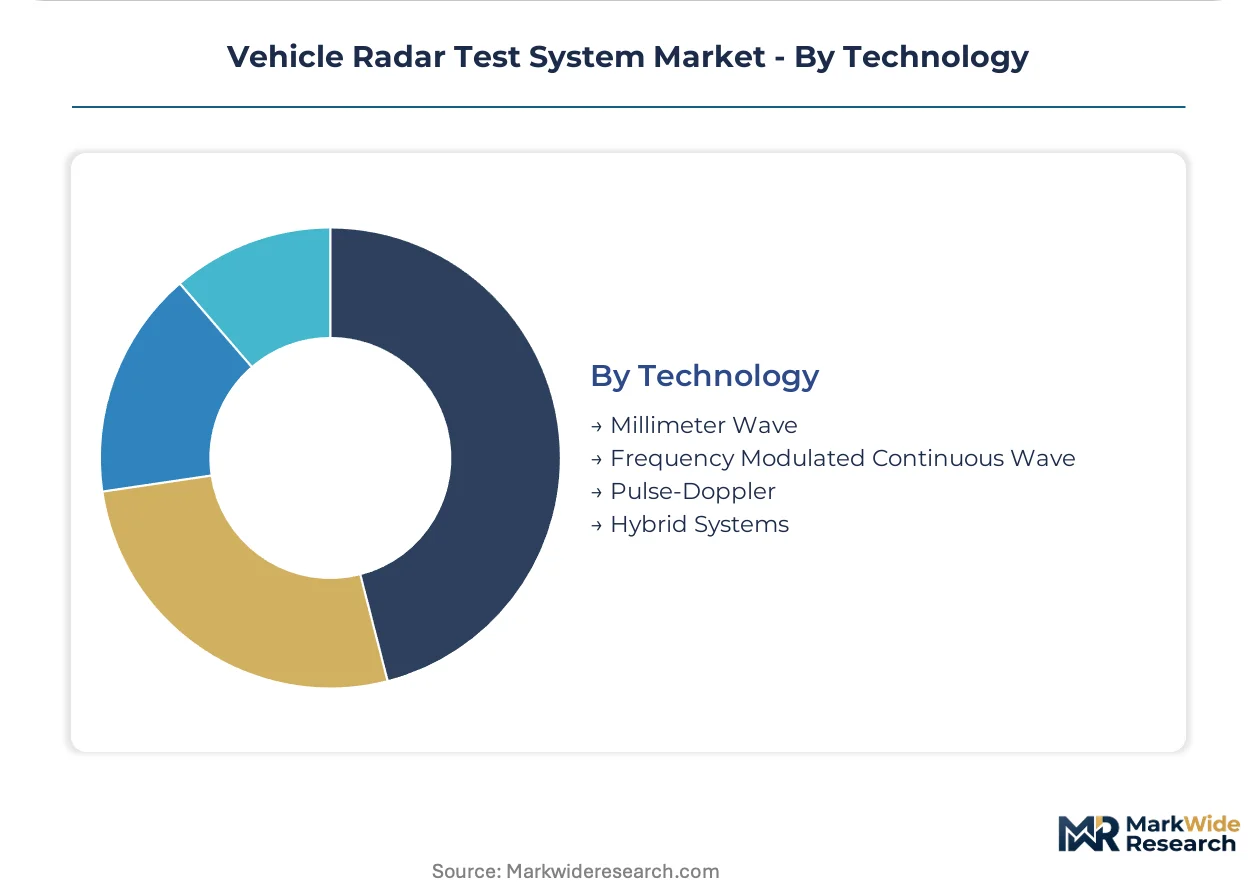
Technology:
Equipment architecture selection determines anechoic chamber configuration and signal analysis hardware requirements.
- Millimeter Wave:76-81 GHz systems lead equipment sales for current-generation automotive radar validation. RF frontend component costs fluctuate with compound semiconductor wafer pricing.
- Hybrid Systems:FMCW-pulse-Doppler combinations displace pure frequency-modulated configurations for 4D imaging radar deployment. These architectures demand enhanced angular resolution capabilities.
- Frequency Modulated Continuous Wave:Legacy installations face replacement pressure from hybrid architecture specifications.
- Pulse-Doppler:Specialized applications in elevation-angle resolution testing retain niche deployment.
Millimeter Wave dominates installed base; Hybrid Systems shows the strongest momentum in new procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs consume radar test systems primarily for pre-homologation validation, while Chinese manufacturers emphasize inline production testing for cost-sensitive 77 GHz modules. South Korean battery-electric vehicle programs outsource validation capacity through compressed sprint contracts, diverging from European captive infrastructure models.
Germany
ECE R79 steering regulation mandates and KBA homologation procedures drive procurement of automated radar-in-the-loop benches. The EU's updated General Safety Regulation accelerates Tier-1 supplier validation capacity expansion. Stuttgart and Ingolstadt anchor Germany's automotive testing corridor, where OEMs deploy hybrid FMCW-pulse-Doppler architectures for 4D imaging radar verification.
United States
FCC Part 95 emission rules govern 76-81 GHz radar module certification for domestic ADAS programs. NHTSA safety standards and pending autonomous vehicle federal frameworks shape capital deployment timelines. Michigan's automotive engineering clusters and California's Silicon Valley autonomous vehicle developers concentrate demand for performance evaluation systems with enhanced angular resolution.
China
MIIT radio regulations for automotive short-range radar create compliance complexity for multi-regional suppliers serving domestic EV manufacturers. The country's national automotive safety regulator mandates documented margin verification against localized emission masks. Yangtze River Delta manufacturing hubs prioritize inline functional testing for high-volume 77 GHz sensor production lines.
South Korea
MFDS-equivalent automotive safety protocols and 5G-V2X smart highway deployment accelerate combined radar-DSRC validation requirements. Government-backed battery-electric vehicle programs favor eighteen-month validation sprint structures over traditional equipment ownership. Seoul Capital Area test laboratories capture outsourced demand through subscription-based radar-in-the-loop capacity leasing.
Japan
MIC ordinance spectrum allocation shapes short-range radar test specifications for domestic OEM export programs. METI industrial policy supports millimeter-wave RF engineering talent development in defense-adjacent clusters. Nagoya's automotive engineering corridor and Tokyo metropolitan test houses specialize in elevation-angle resolution validation for pedestrian classification algorithms.
Vehicle Radar Test System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor foundry operations distinguishing the upper group from equipment-dependent competitors. The middle layer fragments across automated test bench developers and signal analysis hardware suppliers serving regional validation markets. Two strategic archetypes dominate: vertically integrated automotive Tier-1s with in-house test system production, and pure-play test equipment specialists focused on radar-in-the-loop automation. Competitive positioning hardens through foundry access for RF frontend components and software-defined target simulation capabilities that reduce anechoic chamber dependency.
Among German-anchored diversified industrials, Robert Bosch GmbH exemplifies the integrated archetype through captive supply of test system components, while NOFFZ Technologies occupies a specialist position with automated radar-in-the-loop bench deployments. Japanese test equipment manufacturers including Anritsu Corporation represent the precision instrumentation tier serving multi-regional compliance verification. These three entities anchor distinct competitive vectors: backward integration into semiconductor foundry operations, pure-play automation specialization, and cross-market signal analysis hardware leadership.
| Leading Market Players |
|---|
| Denso Corporation |
| Aptiv |
| Robert Bosch GmbH |
| Valeo SA |
| NXP Semiconductors |
| Continental AG |
| Autoliv Inc. |
| NOFFZ Technologies |
| Anritsu Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Germany's anechoic chamber facilities shapes price floors across validation equipment tiers, concentrating supply-side leverage among captive foundry operators while compressing margins for equipment-dependent competitors serving multi-regional OEMs.
Pricing Analysis
Long-term offtake contracts dominate procurement between Tier-1 suppliers and test equipment manufacturers, though validation-as-a-service subscriptions are fragmenting traditional ownership models. Three-tier pricing structure across premium, standard, and economy levels separates fully automated radar-in-the-loop benches from semi-automated configurations and basic functional test systems. Pricing pressure stems from gallium arsenide substrate volatility squeezing RF frontend margins, with South Korean battery-electric vehicle programs exhibiting highest price sensitivity through compressed eighteen-month sprint contracts.
Supply Chain Analysis
Just-in-time inventory strategies prevail for millimeter-wave RF components, though strategic stockpiling of compound semiconductor wafers has intensified following gallium arsenide pricing volatility. Supply concentrates in Germany's automotive testing corridor, Taiwan's semiconductor foundry ecosystem, and Japan's precision instrumentation clusters. Raw material dependencies include gallium arsenide substrates, high-frequency PCB laminates, and precision machined anechoic chamber absorbers. Single-source vulnerability around specialized RF engineering talent in Munich and Dresden clusters feeds distribution through direct OEM-Tier-1 relationships and specialized test house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by Level 2+ ADAS platform homologation waves, with OEM validation capex cycles now reaccelerating across Stuttgart and Ingolstadt corridors.
For Market Incumbents: Compound defensive positioning through captive semiconductor foundry access and software-defined target simulation capabilities that reduce anechoic chamber dependency. RF engineering talent scarcity in millimeter-wave circuit design threatens margin sustainability, making backward integration into GaAs substrate sourcing the priority lever for margin defense. For New Entrants and Emerging Players: Anchor in India's PLI scheme-aligned component localization incentives, where domestic EV radar suppliers lack validation infrastructure. The most penetrable white space sits in combined radar-DSRC test protocols for 5G-V2X cooperative perception applications. A service-led go-to-market model leasing radar-in-the-loop capacity bypasses capital-intensive equipment manufacturing barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among validation-as-a-service providers with subscription-based radar-in-the-loop capacity leasing. Long-term viability favors test laboratories with software-defined target simulation IP and multi-regional accreditation portfolios. The signal to watch is ETSI EN 302 858 spectrum allocation revision timelines, which trigger mandatory equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Target Simulation | Digital twin integration reduces physical chamber occupancy for Stuttgart OEM validation programs. |
| Captive Semiconductor Foundry Investment | GaAs substrate supply control insulates margins from compound semiconductor wafer pricing volatility. |
| Validation-as-a-Service Platform Launch | Subscription revenue streams capture South Korean battery-electric vehicle program outsourcing demand. |
| Multi-Regional Accreditation Expansion | Simultaneous FCC Part 95, ETSI EN 302 858, and MIIT compliance reduces OEM equipment reconfiguration costs. |
| RF Engineering Talent Pipeline Development | Munich and Dresden cluster partnerships address millimeter-wave circuit design expertise scarcity. |
Methodological Framework
A spread of perspectives from Tier-1 supplier procurement officers, OEM platform validation engineers, test house operations directors, and RF frontend component sourcing managers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings of listed automotive electronics suppliers, KBA homologation procedure documentation, ETSI spectrum allocation regulatory filings, and IHS Markit vehicle production databases. Bottom-up equipment procurement tracking and top-down OEM validation capex analysis provided triangulation across the analysis window.
Segmentation dimensions modeled span test type, application, end user, and technology architecture across the projection horizon. CAGRs were derived from equipment replacement cycle compression analysis and ADAS platform deployment trajectories. Industry-specific forecast inputs include ECE R79 mandate implementation timelines and 4D imaging radar specification hardening rates.
Material uncertainties — regulatory divergence between FCC, ETSI, and MIIT emission mask standards, gallium arsenide substrate pricing volatility, and millimeter-wave RF engineering talent availability — sit outside the modeled envelope. Forecasts reflect documented assumptions about homologation procedure stability and OEM captive versus outsourced validation preference evolution. Revision becomes warranted when UN R79 and R157 harmonization timelines accelerate or decelerate beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market