
 Vegan Ice Cream Market | 2026-2036
Vegan Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Ice Cream Market Intelligence
Food service buyer concentration is rebalancing as specialty coffee chains and fast-casual restaurants expand vegan dessert menus, fragmenting demand across thousands of independent outlets while concentrating volume with national distributors. Nestlé S.A. leverages its frozen dairy logistics network to secure retail freezer placement. Danone S.A. anchors its position through R&D partnerships with European ingredient suppliers. Cado Inc. differentiates with avocado-based formulations that bypass commodity nut milk supply constraints.
Vegan ice cream is a frozen dessert formulated without animal-derived ingredients, typically employing plant-based fats from coconut, almond, or cashew sources combined with emulsifiers and stabilizers to achieve overrun and mouthfeel comparable to dairy ice cream. Its primary commercial purpose is to serve lactose-intolerant consumers, ethical vegans, and flexitarian households seeking indulgence without animal agriculture inputs. Coconut-based formulations currently lead value contribution due to superior fat structure and creaminess, though cashew bases represent the fastest-growing product type as manufacturers resolve allergen labeling complexities. The bar packaging format captures outsized margin pools in convenience retail, while pint and tub formats dominate supermarket velocity.
The FDA's plant-based labeling standards in the United States and the EU Green Deal's sustainability disclosure requirements collectively pressure manufacturers toward cleaner ingredient decks and carbon footprint transparency. EFSA guidelines on novel food approvals shape which emerging protein sources gain European market access. Stakeholders must monitor evolving allergen thresholds and front-of-pack labeling mandates as these regulations increasingly determine which formulations qualify for mainstream retail distribution.
Market Dynamics
Plant-based fat sourcing and clean-label formulation standards are restructuring competitive advantage, as coconut supply volatility and FDA labeling scrutiny force manufacturers toward diversified ingredient portfolios and transparent supply chain documentation.
Growth Catalysts
- FDA Plant-Based Labeling Guidance:The FDA's updated standards for plant-based dairy alternatives in the United States clarify permissible claims, reducing regulatory uncertainty for manufacturers entering mainstream retail freezer placement.
- Food Service Channel Expansion:Specialty coffee chains and quick-service restaurants now carry multiple vegan dessert SKUs, fragmenting demand across thousands of independent outlets while concentrating volume with national food service distributors.
- EU Green Deal Farm-to-Fork Targets:The European Union's sustainability disclosure requirements pressure manufacturers toward carbon footprint transparency and cleaner ingredient decks, qualifying products for premium retail positioning.
Market Restraints
- Coconut Oil Price Volatility:Coconut-based formulations depend on Philippine and Indonesian harvest cycles, exposing margins to weather-driven supply shocks and currency fluctuation.
- Cashew Allergen Labeling Complexity:EFSA thresholds for tree nut cross-contamination create formulation barriers that slow European market entry for cashew-based product lines.
- Dairy Substitution Economics:Commodity dairy prices in Germany and the Netherlands periodically compress the vegan premium, eroding price-positioning power during milk oversupply cycles.
Strategic Opportunities
- Avocado Fat Platform Diversification:Avocado-based formulations bypass commodity nut milk supply constraints and allergen labeling burdens, opening shelf-stable distribution channels.
- Bar Format Convenience Retail:Single-serve bar packaging captures outsized margin pools in petrol station and transit-hub retail, where impulse purchase behavior dominates.
- CSRD-Aligned Carbon Accounting:The EU's Corporate Sustainability Reporting Directive creates first-mover advantage for manufacturers with verified lifecycle emissions data on plant-based versus dairy inputs.
Industry Challenges
- Emulsifier Stabilizer Expertise Gap:Formulation chemistry talent capable of replicating dairy overrun and mouthfeel without animal-derived inputs commands scarcity premiums that strain R&D budgets.
- Cold Chain Capex Requirements:Frozen distribution infrastructure for pint and tub formats demands capital-intensive freezer placement fees and temperature-controlled logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Ice Cream Market |
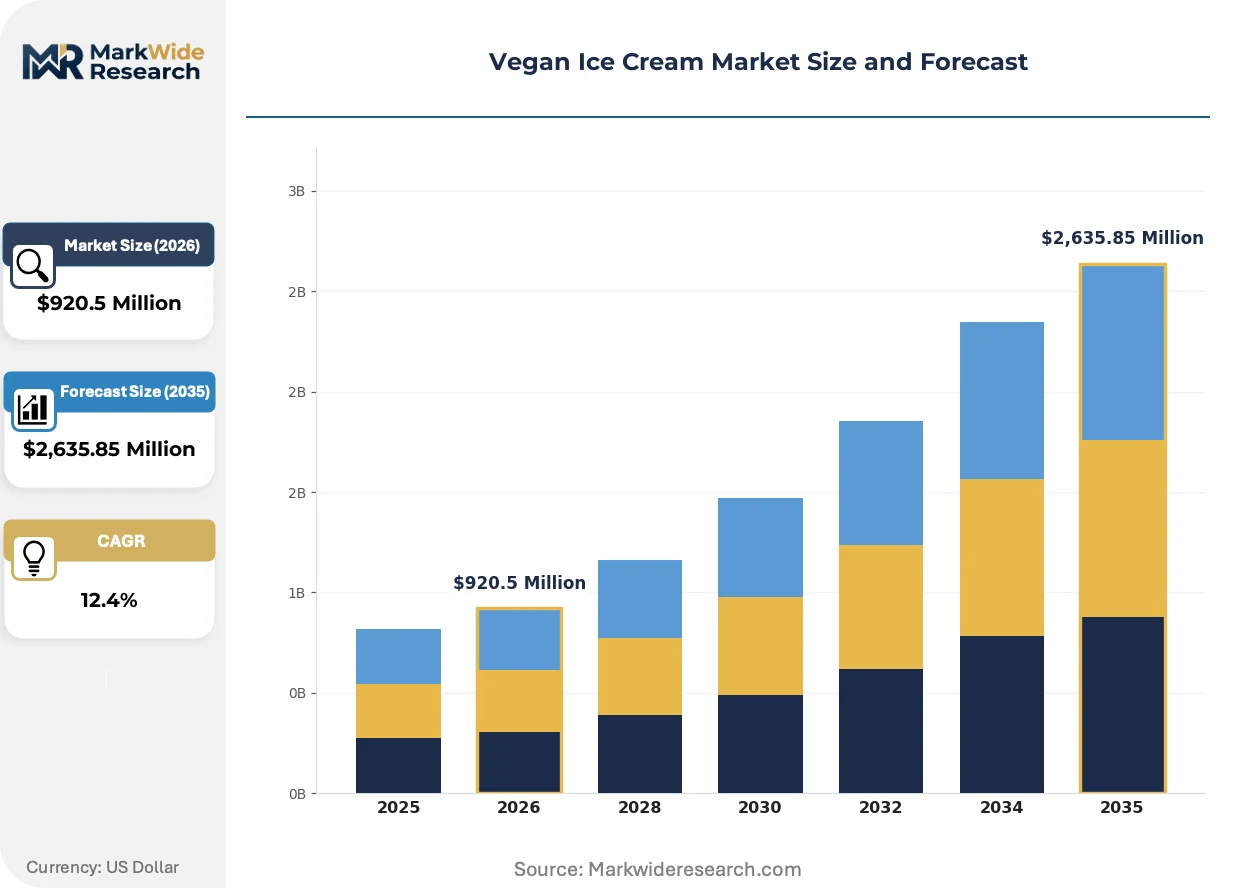
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,635.85 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut, Almond, Soy, Cashew Flavor Profile: Vanilla, Chocolate, Strawberry, Mint Packaging Type: Pint, Tub, Cup, Bar Distribution Channel: Retail, Online, Food Service, Supermarkets |
| Companies Covered | Pressed Juicery Inc, Vegetarian Express Ltd., Nestlé S.A., The Brooklyn Creamery, Booja-Booja Ltd., Danone S.A., GoodPop LLC, Cado Inc., Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Ice Cream Market Strategic Shifts & Innovations
Precision fermentation for dairy-identical proteins and advanced emulsifier systems are rewriting formulation possibilities, while regulatory pressure on carbon disclosure accelerates supply chain digitization.
Oat protein isolation technology is decentralizing fat-source dependence in vegan ice cream formulation. Mid-size manufacturers in Sweden and Finland are adopting enzymatic oat fractionation at commercial scale, reducing reliance on Southeast Asian coconut supply chains. This shift is decentralizing ingredient sourcing geography and compressing lead times for European production facilities.
The EU Green Deal's farm-to-fork sustainability targets now mandate ingredient provenance disclosure for plant-based foods sold in member states. Manufacturers must document agricultural input origins and processing energy consumption, raising compliance costs but creating differentiation for verified low-carbon supply chains. German retail buyers are responding by prioritizing suppliers with blockchain-tracked ingredient documentation.
Flexitarian households are displacing pure vegan consumers as the primary volume driver, altering flavor and texture expectations toward dairy-comparable indulgence rather than compromise positioning. Supermarket velocity data from the United Kingdom and United States shows premium price acceptance correlates with sensory parity claims, not ethical messaging. This behavioral pivot is most visible in German retail, where shelf space for dairy alternatives has expanded specifically for flexitarian-positioned SKUs.
Vegan Ice Cream Market Segmentation
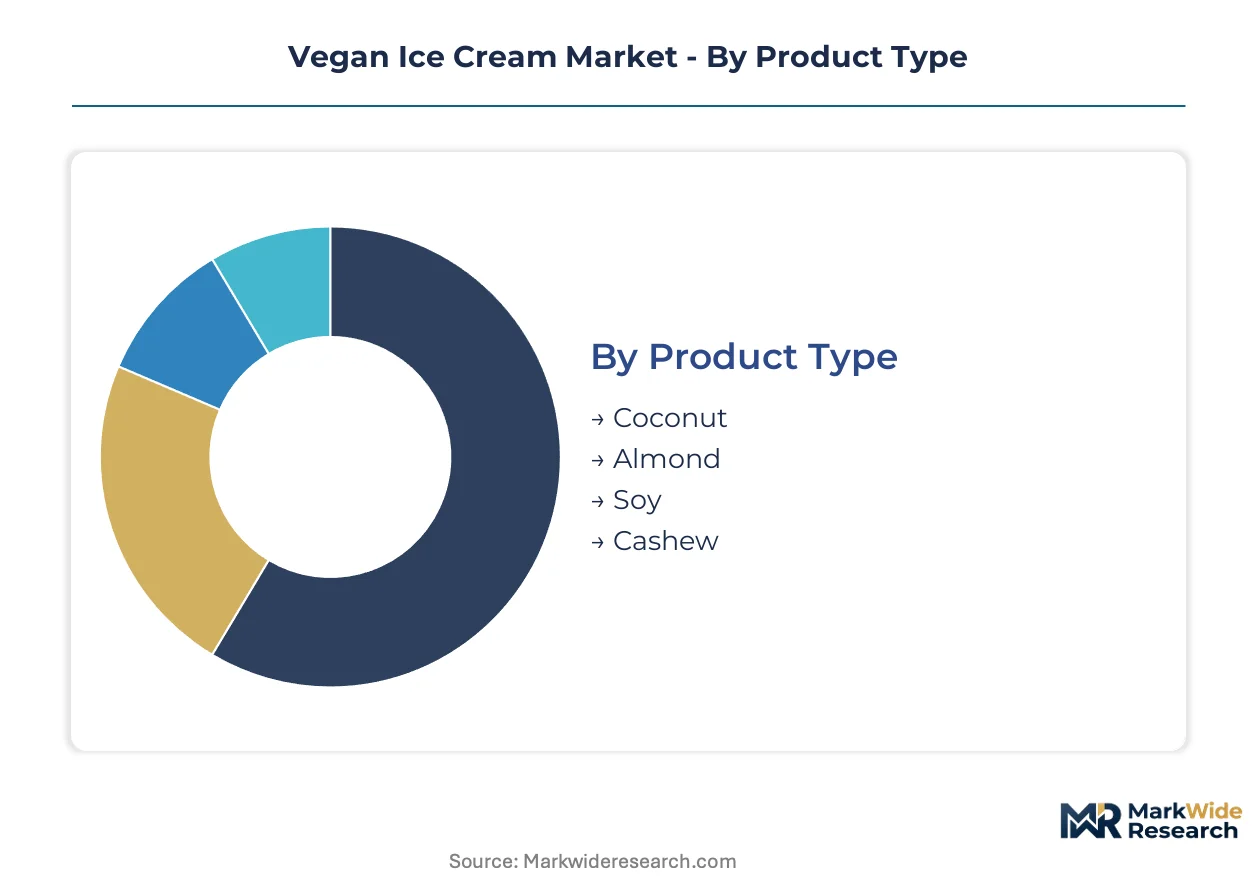
Vegan ice cream segmentation reveals how formulation chemistry, packaging economics, and channel access requirements fragment commercial opportunity. Manufacturers must align R&D investment with the certification burdens and margin structures specific to each segment cluster.
Product Type:
EFSA novel food approvals and FDA labeling standards impose distinct compliance burdens on each base ingredient, with coconut and cashew facing the most stringent documentation requirements for European market entry.
- Coconut:Dominant fat structure delivers superior creaminess through high saturated fat content that mimics dairy mouthfeel. German and Dutch retail buyers prioritize coconut-based SKUs for mainstream freezer placement due to established consumer acceptance and clean-label positioning.
- Cashew:Neutral flavor profile enables cleaner taste translation of premium inclusions, though EFSA tree nut thresholds create cross-contamination documentation hurdles that slow European rollout. Swedish and Finnish manufacturers are resolving these barriers through dedicated facility investments.
- Almond:Mature supply infrastructure in California and Spain supports cost-competitive sourcing, though water intensity disclosures under EU Green Deal pressure transparency investments.
- Soy:Legacy protein base with established processing technology but declining preference among flexitarian consumers seeking differentiated positioning beyond commodity alternatives.
Leading the category by volume: Coconut. Growing fastest: Cashew.
Flavor Profile:
Flavor selection directly determines ingredient sourcing complexity, with chocolate and mint requiring named supplier verification for cocoa and peppermint oil traceability under EU farm-to-fork mandates.
- Vanilla:Benchmark flavor for sensory parity testing against dairy benchmarks. Bourbon and Tahitian varietals command premium positioning in UK and US specialty retail channels where flexitarian consumers evaluate vegan alternatives against conventional indulgence standards.
- Chocolate:Cocoa butter and cocoa powder sourcing from Côte d'Ivoire and Ghana demands blockchain-tracked documentation for German retail compliance. Dark chocolate formulations with higher cocoa percentages capture outsized margins in convenience retail.
- Strawberry:Fruit inclusion requires frozen supply chain integration and seasonal procurement planning that strains working capital for mid-size manufacturers.
- Mint:Peppermint oil concentration affects emulsifier stability, creating formulation expertise barriers that concentrate production among established players with advanced stabilizer capabilities.
Chocolate holds the volume lead. Mint shows the steepest expansion trajectory in food service channels.
Packaging Type:
Cold chain capex requirements vary dramatically by format, with pint and tub formats demanding freezer placement fees that favor manufacturers with Nestlé-scale logistics networks.
- Pint:Standard supermarket velocity driver requiring temperature-controlled distribution infrastructure and slotting fee negotiations with national retail chains. German and UK supermarket data shows pint formats dominate household penetration metrics.
- Bar:Single-serve convenience format captures impulse purchase behavior at petrol stations and transit hubs. Margin pools exceed tub formats due to portion-controlled pricing architecture and lower cold chain intensity.
- Tub:Family-size positioning competes directly with conventional dairy ice cream on price-per-volume, compressing premium positioning power during milk oversupply cycles in the Netherlands.
- Cup:Individual portion format concentrated in food service and institutional channels where portion control and waste reduction drive procurement decisions.
Pint formats lead retail volume. Bar formats gain share fastest in convenience and travel retail.
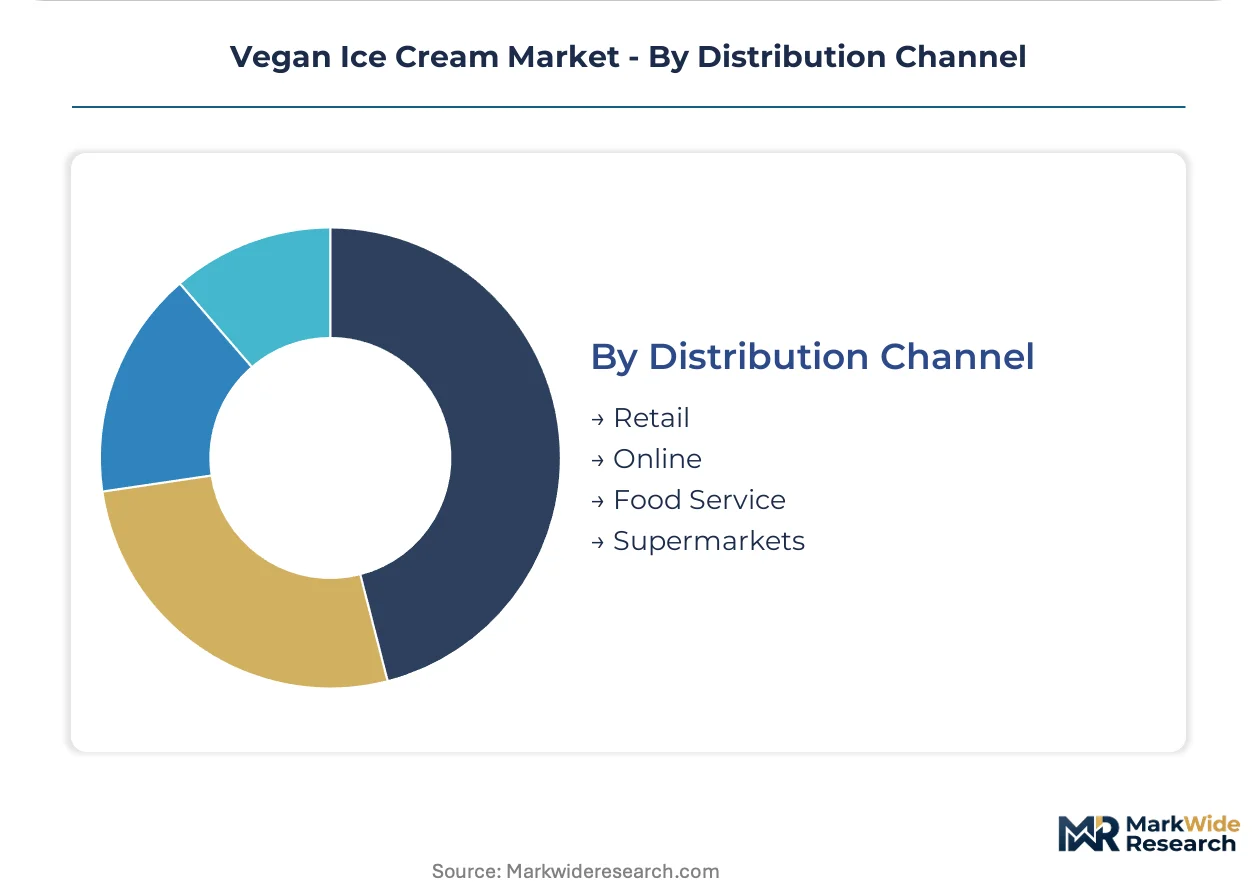
Distribution Channel:
Channel selection determines regulatory exposure, with food service bypassing front-of-pack labeling requirements that apply to retail and supermarket placements.
- Retail:Independent specialty stores and natural food chains require SKU breadth and rotating flavor innovation to maintain freezer space. FDA plant-based labeling compliance is mandatory for US placement.
- Supermarkets:National chains in Germany and the UK demand carbon footprint documentation and blockchain-tracked ingredient provenance under EU Green Deal procurement policies. Slotting fees and promotional spending concentrate volume with diversified manufacturers.
- Food Service:Specialty coffee chains and quick-service restaurants fragment demand across thousands of outlets while concentrating volume with national distributors. Menu integration requires technical support for texture stability in soft-serve applications.
- Online:Direct-to-consumer and third-party platforms enable subscription models and flavor experimentation with lower cold chain infrastructure requirements, though last-mile frozen delivery costs erode margins.
Supermarkets dominate value contribution. Food service channels are expanding most quickly as QSR menu integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where retail shelf space for dairy alternatives has expanded significantly. The United States and United Kingdom follow as volume centers, with food service channel penetration accelerating across specialty coffee chains and quick-service restaurants.
Germany
Flexitarian households drive volume growth through mainstream supermarket penetration. The EU Green Deal's farm-to-fork sustainability targets mandate carbon footprint disclosure for plant-based foods. Berlin and Hamburg anchor retail innovation, with national chains prioritizing suppliers with blockchain-tracked ingredient documentation.
United States
Specialty coffee chains and QSR menu integration fragment demand across thousands of independent outlets. The FDA's updated plant-based labeling guidance clarifies permissible claims for dairy alternatives. California and New York metro areas concentrate R&D activity, with precision fermentation startups clustering near Bay Area biotech infrastructure.
United Kingdom
Supermarket velocity data shows premium price acceptance correlates with sensory parity claims. EFSA guidelines on novel food approvals shape which emerging protein sources gain market access. London and the Southeast lead convenience retail expansion for single-serve bar formats at transit hubs.
Sweden
Enzymatic oat fractionation technology reduces reliance on Southeast Asian coconut supply chains. The EU Corporate Sustainability Reporting Directive creates first-mover advantage for manufacturers with verified lifecycle emissions data. Stockholm and Malmö host mid-size manufacturers adopting commercial-scale oat protein isolation.
Netherlands
Commodity dairy prices periodically compress the vegan premium during milk oversupply cycles. REACH compliance and ECHA chemical safety standards affect emulsifier and stabilizer sourcing. Amsterdam and Rotterdam concentrate cold chain logistics infrastructure for frozen distribution across Benelux markets.
Vegan Ice Cream Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue differentiated fat platforms and clean-label positioning. The market structure tiers between multinational frozen dessert networks and specialized plant-based innovators. Three archetypes dominate: diversified food conglomerates leveraging existing cold chain infrastructure, mid-size specialists resolving allergen and supply constraints through novel ingredients, and venture-backed challengers targeting convenience retail formats. Competitive moves concentrate on securing freezer placement through slotting fee negotiations and forming R&D partnerships with European ingredient suppliers.
Among diversified conglomerates, Nestlé S.A. and Unilever occupy positions anchored by frozen logistics networks that secure retail freezer placement at scale. Danone S.A. sits within the European specialist tier, exemplifying manufacturers that anchor market presence through partnerships with regional ingredient suppliers. Cado Inc. represents the novel-platform archetype, with avocado-based formulations that bypass commodity nut milk supply constraints and allergen labeling burdens.
| Leading Market Players |
|---|
| Pressed Juicery Inc |
| Vegetarian Express Ltd. |
| Nestlé S.A. |
| The Brooklyn Creamery |
| Booja-Booja Ltd. |
| Danone S.A. |
| GoodPop LLC |
| Cado Inc. |
| Unilever |
| Others |
Cost & Logistics Intelligence
Enzymatic oat fractionation technology is decentralizing fat-source dependence in vegan ice cream formulation, simultaneously compressing European production lead times and eroding the premium pricing power historically anchored to Southeast Asian coconut supply chains. This production-method transition forces manufacturers to recalibrate cost structures around regional ingredient sourcing while reshaping competitive dynamics between commodity-dependent and technology-enabled players.
Pricing Analysis
Volume concentrates in pint and tub formats where family-size positioning competes directly with conventional dairy on price-per-volume, while margin pools concentrate in single-serve bar formats at petrol stations and transit hubs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and sensory parity claims, with German and UK supermarket buyers demanding blockchain-tracked provenance for premium placement. Pricing pressure stems from commodity dairy price cycles in the Netherlands and Germany that periodically compress the vegan premium. Price-sensitive buyers cluster in family-size tub purchasers, while least-sensitive buyers concentrate in convenience retail bar purchasers seeking impulse indulgence.
Supply Chain Analysis
Single-source vulnerability sits with Philippine and Indonesian coconut harvest cycles, exposing margins to weather-driven supply shocks and currency fluctuation. Geographic supply concentration centers on Southeast Asia for coconut oil, California and Spain for almond protein, and Sweden and Finland for enzymatic oat fractionation. Raw material dependencies rest on plant-based fats, emulsifier stabilizers, and frozen fruit inclusions. Supply chain risk hinges on tariff exposure for Southeast Asian coconut derivatives entering European processing facilities. Distribution runs through temperature-controlled logistics networks with capital-intensive freezer placement fees favoring manufacturers with established frozen dessert infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation for dairy-identical proteins is displacing legacy plant-fat formulation as the dominant technology pathway, creating asymmetric opportunity for manufacturers capable of integrating biotech-derived ingredients at commercial scale.
For Market Incumbents: Deploy cold chain infrastructure leverage to secure exclusive freezer placement agreements with German and UK national retail chains, insulating against precision fermentation entrants. Accelerate R&D partnerships with European ingredient suppliers to resolve EFSA novel food approval barriers before cashew-based competitors achieve market access. Threat concentration sits with venture-backed challengers targeting convenience retail bar formats with avocado-based formulations that bypass commodity nut milk constraints. For New Entrants and Emerging Players: FDA plant-based labeling guidance in the United States opens a window for clean-label positioning in specialty coffee chain and QSR menu integration. Target food service channel technical support contracts for soft-serve texture stability, the most penetrable segment given incumbent concentration in retail freezer placement. Go-to-market angle: subscription-based direct-to-consumer flavor experimentation with lower cold chain infrastructure requirements than national retail distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified frozen dessert conglomerates seeking novel fat platform diversification. Long-term viability frames around manufacturers with verified lifecycle emissions data aligned to EU Corporate Sustainability Reporting Directive requirements. Acquisition target archetype: mid-size specialists with commercial-scale oat protein isolation or avocado-based formulation capabilities. Signal to watch: EFSA novel food approval velocity for precision fermentation-derived proteins as inflection indicator for technology-transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Access to dairy-identical proteins from Bay Area biotech clusters rewrites formulation possibilities for sensory parity claims. |
| Blockchain Ingredient Documentation | German retail buyers prioritize suppliers with verified provenance under EU Green Deal farm-to-fork mandates. |
| Food Service Channel Expansion | QSR menu integration fragments demand across thousands of outlets while concentrating volume with national distributors. |
| Avocado Fat Platform Scale-Up | Cado Inc.'s approach bypasses commodity nut milk supply constraints and allergen labeling burdens in European markets. |
| CSRD-Aligned Carbon Accounting | Verified lifecycle emissions data creates first-mover advantage for premium retail positioning under EU disclosure requirements. |
Research Approach
Document review covered FDA plant-based labeling guidance, EU Green Deal farm-to-fork sustainability targets, EFSA novel food approval databases, and supermarket velocity data from Germany and the United Kingdom, complemented by interviews with R&D directors at enzymatic oat fractionation facilities, procurement leads at national food service distributors, category buyers at German retail chains, and formulation chemistry specialists. Secondary validation drew from customs records of coconut oil imports, SEC filings of diversified frozen dessert manufacturers, and cold chain logistics infrastructure disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from trade association data.
Cross-referencing historical capacity expansion patterns with expert panel input on precision fermentation commercialization timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis and constraint-bound scenario testing. Industry-specific forecast inputs incorporated EFSA approval velocity assumptions and food service menu integration penetration curves.
Caveats apply where EFSA novel food approval delays, Philippine coconut harvest disruptions, or commodity dairy price cycle inversions could materially shift the outlook. Forecasts reflect documented assumptions about technology adoption rates and regulatory implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Middle East Dairy Alternatives Market