
 Plant-Based Flour Market | 2026-2036
Plant-Based Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Flour Market Intelligence
Milling technologist availability is collapsing across North American and European facilities, constraining capacity expansion for pulse and nut flour processing. Bob's Red Mill Natural Foods leverages its employee-owned structure to retain specialized talent in Oregon. Ingredion anchors its advantage through integrated pea protein and starch extraction networks in the Midwest. Cargill competes by controlling origination contracts for yellow peas across the Canadian prairies.
Plant-based flour denotes mechanically processed, de-oiled, or milled powders derived from legumes, oilseeds, tree nuts, or tubers, typically achieving particle sizes below 250 microns and protein contents ranging from 8% to 28% depending on source material. These flours function as gluten-free structure builders, fat replacers, and protein fortifiers in formulated foods. Almond flour occupies the premium tier in bakery applications due to its lipid stability and neutral flavor profile, while chickpea flour sustains the fastest growth trajectory in pasta and extruded snacks driven by its emulsifying properties and complete amino acid score. Coconut flour differentiates through high dietary fiber content, though its hygroscopic nature limits inclusion rates in commercial formulations.
FDA enforcement of Food Safety Modernization Act preventive controls governs allergen cross-contact protocols in multi-purpose milling facilities, while EU REACH and EFSA novel food assessments shape ingredient approval timelines for emerging sources like fava bean or lupin flour. India's FSSAI fortification mandates and BIS quality specifications for pulse products create compliance thresholds for import-dependent processors. Stakeholders must monitor evolving protein content labeling thresholds and carbon intensity disclosure requirements as procurement criteria tighten across institutional buyers.
Market Dynamics
Milling technologist availability is collapsing across North American and European facilities, constraining capacity expansion for pulse and nut flour processing. Specialized talent retention now determines which processors can scale commercial gluten-free production.
Growth Catalysts
- EU Green Deal agricultural targets:Carbon intensity disclosure requirements are tightening procurement criteria for institutional buyers across German and French food manufacturing, accelerating demand for traceable pulse flour supply chains.
- Clean-label bakery reformulation:Bakeries are replacing wheat flour with chickpea and almond formulations to meet consumer protein fortification expectations without synthetic additives.
- FDA Food Safety Modernization Act enforcement:Preventive control mandates for allergen cross-contact protocols are consolidating multi-purpose milling toward dedicated pulse and nut facilities.
Market Restraints
- Yellow pea origination concentration:Canadian prairie contract control by major traders creates input cost volatility for independent processors lacking captive supply.
- Coconut flour hygroscopic limitation:High moisture absorption restricts inclusion rates below 15% in commercial formulations, capping addressable volume in fiber-enriched applications.
- EFSA novel food assessment timelines:Fava bean and lupin flour approvals face 18-24 month evaluation windows, delaying European commercialization for emerging protein sources.
Strategic Opportunities
- India FSSAI fortification mandates:Government-backed pulse flour integration into staple foods creates institutional procurement channels for import-dependent processors.
- Extruded snack protein convergence:Chickpea flour emulsifying properties combined with air-puffing technology enable clean-label savory snack expansion beyond traditional bakery.
- Direct-to-manufacturer sourcing platforms:Digital procurement channels are bypassing commodity brokers, allowing mid-scale mills to capture margin from specialty flour buyers.
Industry Challenges
- Milling technologist skill scarcity:Specialized operators capable of maintaining sub-250 micron particle consistency in pulse processing command premium wages that erode facility margins.
- Integrated pea protein-starch extraction capex:Fractionation equipment requirements for high-value ingredient recovery demand capital deployment beyond standalone flour milling economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Flour Market |
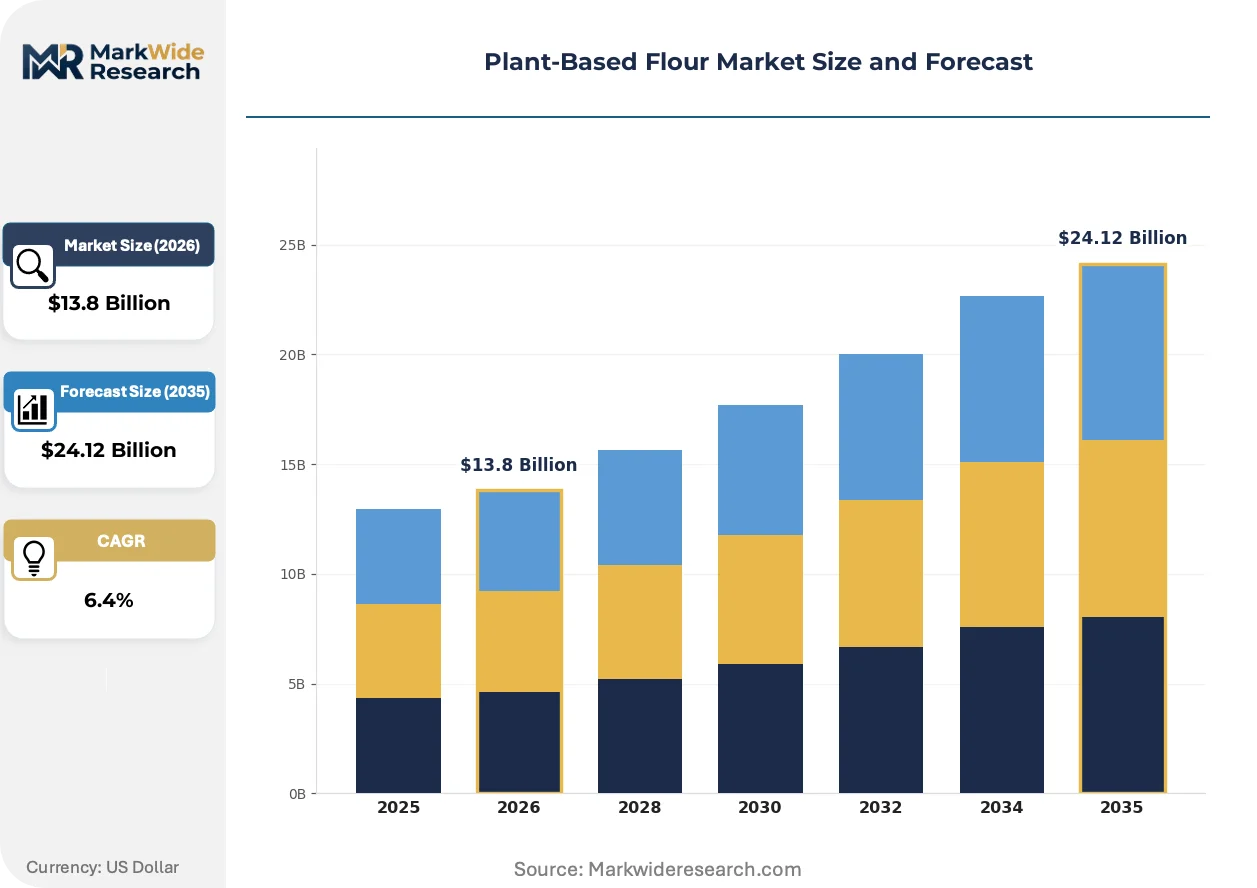
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Flour, Soy Flour, Coconut Flour, Chickpea Flour Application: Baked Goods, Snacks, Pasta, Cereals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Households, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | Bob's Red Mill Natural Foods, GoodMills Group, Ingredion, Vestkorn Milling AS, Rolling Hills Nut Company, Cargill, Wilmar International, Richardson Milling, The Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Flour Market Strategic Shifts & Innovations
Processing technology and regulatory disclosure requirements are compressing traditional supply chain structures while opening new application categories for pulse and nut-derived ingredients.
Air-classification milling systems are achieving sub-150 micron particle distributions for chickpea flour without cryogenic grinding energy costs. Pasta manufacturers in Italy and extruded snack producers in the United States are adopting these systems at pilot scale. This particle size reduction is miniaturizing the functional gap between pulse flours and refined wheat in gluten-free structure building.
REACH chemical safety registrations and EFSA novel food assessments are converging into unified compliance timelines for emerging ingredients like fava bean flour. European processors now face dual-track documentation requirements that extend market entry by 12-18 months. Small and mid-scale mills without dedicated regulatory affairs functions are outsourcing compliance to specialized consultancies.
Clean-label certification is displacing conventional quality assurance as the primary supplier selection criterion among German and United States bakery chains. Third-party non-GMO and allergen-free audits are replacing historical price-first procurement protocols. This preference shift is most visible in private-label gluten-free bread programs where ingredient traceability commands 8-12% price premiums.
Plant-Based Flour Market Segmentation
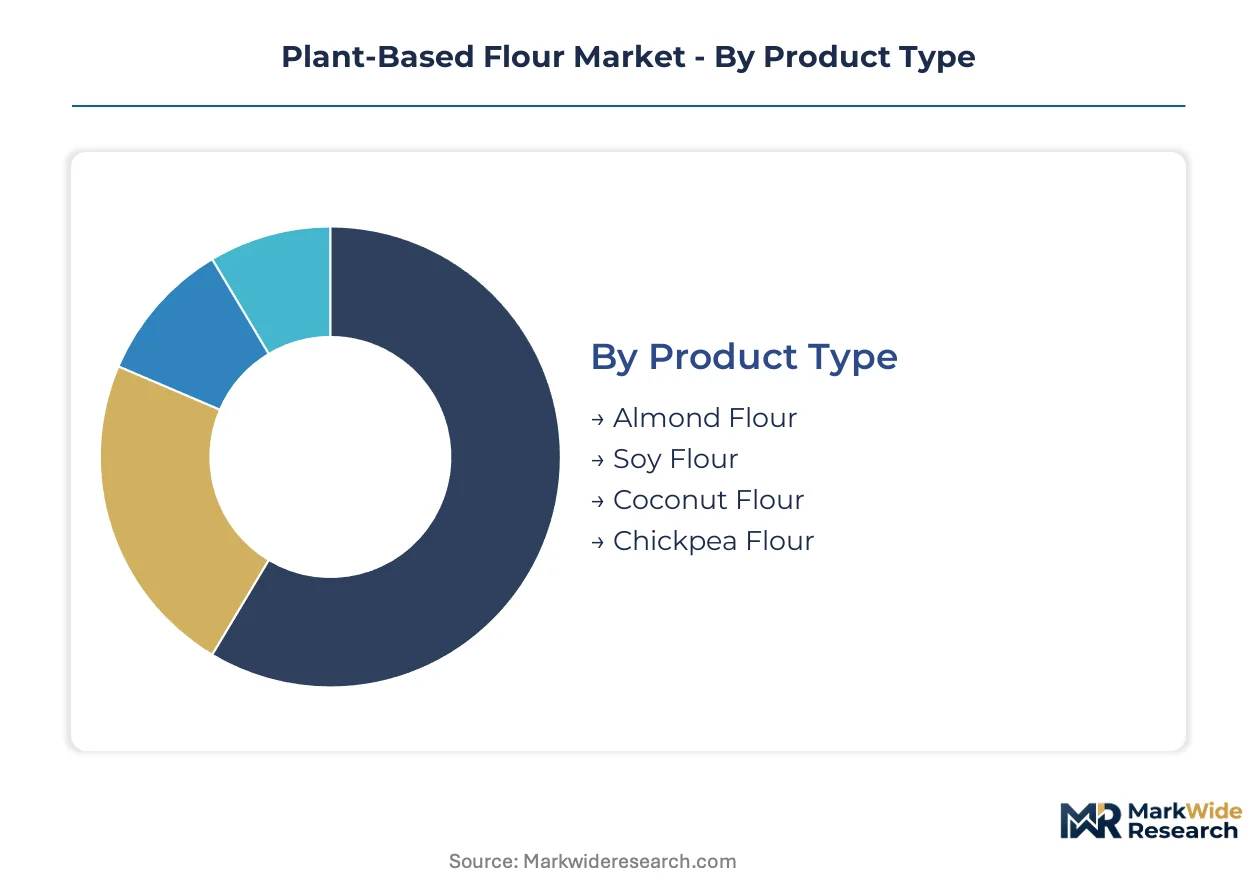
Plant-based flour procurement patterns diverge sharply across product specifications, end-use processing requirements, and channel access protocols. Regulatory thresholds for allergen labeling and protein content certification reshape how each segment commands price premiums and volume allocation.
Product Type:
FDA preventive controls and EU novel food assessments create divergent compliance burdens across protein sources, concentrating investment toward ingredients with established regulatory pathways.
- Almond Flour:Mechanically milled from blanched almonds with lipid stability above 12 months and neutral flavor profile. Premium bakery applications in Germany and California sustain pricing power as clean-label certification displaces conventional quality assurance among institutional buyers.
- Chickpea Flour:Dehulled and milled Cicer arietinum achieving 20-25% protein content with emulsifying properties from residual starches. Pasta manufacturers in Italy and extruded snack producers in the United States are adopting air-classification systems to exploit its complete amino acid score.
- Soy Flour:Heat-treated defatted soybean meal with protein content ranging 40-50%, constrained by allergen declaration requirements in multi-purpose milling facilities.
- Coconut Flour:Dried coconut meat powder with dietary fiber exceeding 35%, limited by hygroscopic absorption rates below 15% inclusion in commercial formulations.
Established volume favors almond flour; emerging adoption favors chickpea flour.
Application:
Processing equipment compatibility and finished product shelf stability determine which flour types penetrate each end-use category.
- Baked Goods:Structure-building applications requiring gluten-free reformulation in commercial bread and pastry production, with private-label programs commanding traceability premiums.
- Snacks:Extruded and air-puffed savory products leveraging chickpea flour emulsification combined with high-temperature expansion technology.
- Pasta:Durum wheat replacement in Italian manufacturing facilities, where sub-150 micron particle distributions from pulse sources are miniaturizing functional gaps.
- Cereals:Breakfast and granola applications with protein fortification mandates under India's FSSAI integration requirements for institutional procurement channels.
Volume concentration sits with baked goods; steepest expansion trajectory belongs to snacks.
Distribution Channel:
Customer procurement sophistication and lot-size requirements segment channel economics.
- Online Retail:Direct-to-consumer platforms capturing specialty and allergen-free demand with subscription models for household replenishment.
- Supermarkets:Mass-market penetration dependent on third-party non-GMO and allergen-free audit certifications replacing historical price-first protocols.
- Health Food Stores:Regional chains in Germany and the United States prioritizing ingredient traceability with 8-12% price premiums over conventional retail.
- Specialty Shops:Artisan bakery supply and foodservice distribution with technical consultation requirements for gluten-free formulation support.
Supermarkets anchor current throughput; online retail is gaining share fastest.
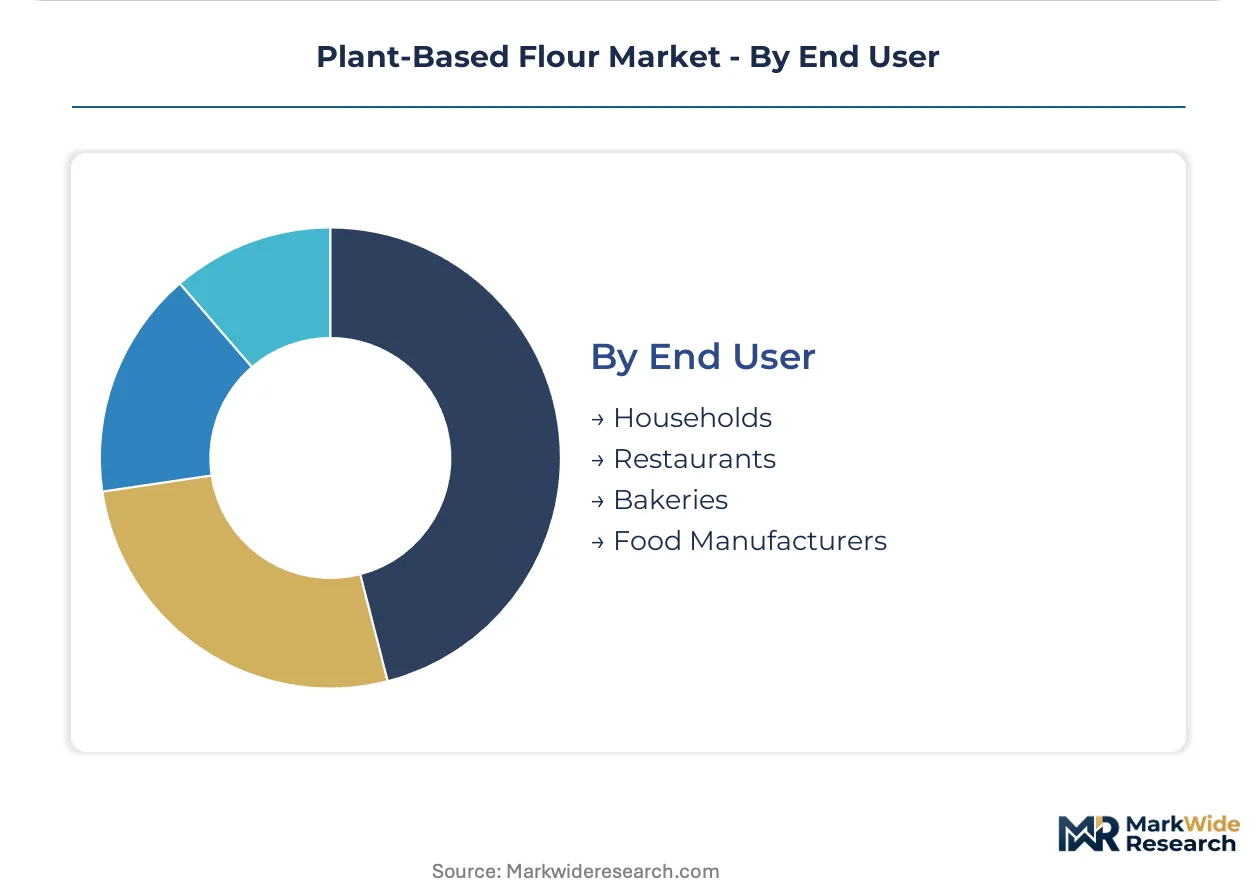
End User:
Scale of operation and technical capability separate procurement behavior across buyer categories.
- Households:Small-package retail consumption driven by home baking trends and dietary restriction management.
- Restaurants:Foodservice procurement with menu-specific gluten-free and clean-label positioning requirements.
- Bakeries:Commercial production facilities scaling dedicated pulse and nut processing lines to meet preventive control mandates for allergen cross-contact protocols.
- Food Manufacturers:Industrial-scale buyers with carbon intensity disclosure requirements tightening procurement criteria across German and French manufacturing.
Food manufacturers dominate volume capture; restaurants show the fastest adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German food manufacturers command 8-12% traceability premiums over United States buyers, while Indian institutional procurement channels operate under government-mandated price ceilings that compress processor margins.
United States
Clean-label bakery reformulation and extruded snack expansion drive chickpea flour procurement from Midwest processing clusters. FDA Food Safety Modernization Act preventive controls mandate dedicated allergen-free milling lines. Oregon-based employee-owned facilities retain specialized milling technologists through equity participation structures.
Germany
Carbon intensity disclosure requirements from EU Green Deal agricultural targets tighten procurement criteria for institutional buyers. EFSA novel food assessments for emerging pulse sources extend compliance timelines. North Rhine-Westphalia food manufacturing corridors concentrate gluten-free private-label bread production with third-party non-GMO audit protocols.
India
FSSAI fortification mandates create institutional procurement channels for pulse flour integration into staple cereals and government feeding programs. BIS quality specifications for processed pulse products establish import thresholds. Maharashtra and Gujarat processing zones scale commercial chickpea milling for domestic bakery and export snack applications.
Canada
Yellow pea origination concentration across prairie provinces supplies North American protein fractionation networks. Contract control by major traders generates input cost volatility for independent processors. Saskatchewan and Alberta milling clusters anchor captive supply arrangements for integrated pea protein-starch extraction facilities.
Italy
Durum wheat replacement demand in pasta manufacturing accelerates air-classification milling adoption for sub-150 micron pulse flour distributions. REACH chemical safety registrations converge with EFSA novel food timelines for emerging ingredients. Emilia-Romagna processing corridors pilot chickpea flour formulations in traditional extrusion equipment.
Plant-Based Flour Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the plant-based flour market. The vendor base organizes around three strategic tiers: integrated agribusiness conglomerates controlling origination and fractionation, specialized pulse and nut milling operations with dedicated allergen-free facilities, and employee-owned regional processors retaining technical talent through equity structures. Competitive moves concentrate on captive supply contract negotiation and air-classification milling capacity deployment.
Within the integrated agribusiness tier, Cargill and Ingredion exemplify scale-driven positioning through upstream control over yellow pea origination and Midwest extraction networks. Bob's Red Mill Natural Foods occupies a distinct archetype as an Oregon-based employee-owned processor leveraging equity participation to retain specialized milling technologists. These three entities represent divergent strategic paths: commodity flow control, integrated ingredient fractionation, and technical talent retention through ownership structure.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods |
| GoodMills Group |
| Ingredion |
| Vestkorn Milling AS |
| Rolling Hills Nut Company |
| Cargill |
| Wilmar International |
| Richardson Milling |
| The Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day inventory cycles for yellow pea and almond feedstocks concentrate pricing power with origination controllers across Canadian prairies and California Central Valley operations, while spot-market processors absorb margin compression from input volatility. This lead-time band shapes how contract structures allocate risk between captive supply arrangements and open-market procurement.
Pricing Analysis
Configured-to-order pricing for sub-150 micron air-classified chickpea flour commands 15-20% premiums over standard-milled product in Italian pasta and U.S. extruded snack applications. Three-tier pricing structure across premium, standard, and economy levels segments by protein certification grade and allergen-test documentation depth. Pricing pressure stems from yellow pea origination concentration among major traders, eroding independent processor margins. Food manufacturers with carbon disclosure mandates show least price sensitivity; commodity bakers in price-controlled Indian procurement channels exhibit highest sensitivity.
Supply Chain Analysis
Canada, the United States, and India anchor plant-based flour supply through distinct specializations: Canadian prairies for yellow pea origination, Oregon and Midwest clusters for integrated protein-starch extraction, and Maharashtra-Gujarat zones for chickpea milling. Raw material dependencies center on blanched almond supply from California, dehulled chickpea from India, and prairie yellow peas. Single-source vulnerability concentrates in Canadian pea protein fractionation where three traders control origination contracts. Distribution runs through direct-to-manufacturer digital platforms bypassing commodity brokers, with institutional procurement channels in Germany and India commanding dedicated supply allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based flour incumbents face substitution defense against refined wheat gluten-free formulations and emerging microbial protein ingredients, requiring structural positioning to retain formulation share in clean-label bakery and extruded snack applications.
For Market Incumbents: Fortify captive supply positions through origination contract renegotiation in Saskatchewan and Alberta, and accelerate air-classification milling deployment to exploit particle-size premium capture before commodity competitors scale. Regulatory compliance investment in FDA preventive controls and EFSA novel food pathways creates switching costs against emerging fava bean and lupin entrants. For New Entrants and Emerging Players: FSSAI fortification fast-track certification for pulse flour integration into Indian government feeding programs opens institutional procurement channels shielded from price competition. Target extruded snack applications in U.S. Midwest manufacturing corridors where emulsifying chickpea flour properties enable clean-label savory product expansion beyond established bakery saturation. Digital direct-to-manufacturer sourcing platforms provide go-to-market bypass of entrenched commodity broker networks. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated agribusiness conglomerates seeking to divest non-core milling assets, particularly Midwest facilities with stranded pea protein-starch extraction capacity. Long-term viability hinges on regulatory pathway acceleration and milling technologist retention structures. The signal to watch is EFSA novel food approval velocity for fava bean and lupin sources, indicating competitive pressure on established pulse flour pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Air-Classification Milling Deployment | Sub-150 micron particle consistency captures premium pricing in Italian pasta manufacturing. |
| Captive Yellow Pea Origination Contracts | Saskatchewan-Alberta contract control insulates margin from spot-market volatility. |
| FDA Preventive Controls Certification | Dedicated allergen-free facility status consolidates multi-purpose milling toward compliant processors. |
| EFSA Novel Food Pathway Investment | Fava bean and lupin approval acceleration opens European commercialization for emerging protein sources. |
| Employee-Owned Equity Structures | Oregon-based retention models preserve specialized milling technologist capability against wage inflation. |
Research Approach
A standing panel of milling operations directors, bakery procurement managers, pulse processing plant engineers, and regulatory affairs specialists provided ongoing calibration against secondary validation from FDA enforcement records, EU REACH registration databases, FSSAI fortification mandate filings, and customs trade flow data. Bottom-up facility capacity surveys triangulated with top-down ingredient demand modeling across the value chain.
Consistency checks against external benchmarks validated volume and value outputs across product type, application, distribution channel, and end-user segmentation dimensions, with regional regulatory clusters as an additional modeling layer. CAGRs were derived from trend-line extrapolation of procurement volume shifts and price realization patterns, incorporating air-classification technology adoption curves and carbon intensity disclosure implementation timelines as industry-specific inputs.
Underlying assumptions cover EFSA novel food approval velocity, milling technologist wage trajectory, and yellow pea origination contract renewal patterns, with deviation risk concentrated in regulatory timeline extensions and input cost volatility from prairie weather events. Recalibration cycles align with material shifts in EU Green Deal procurement criteria and FSSAI mandate expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Bacon Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
North America Tofu Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Fermented Plant-Based Food Market