
 South America Food Stabilizers Market | 2026-2036
South America Food Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Stabilizers Market Analytics
A capital-intensity divergence between multinational ingredient suppliers and regional compounders is unwinding competitive dynamics across the stabilizer value chain. Cargill Incorporated leverages its captive corn wet-milling infrastructure to anchor modified starch supply in Brazil's dairy corridor. Tate & Lyle Plc sustains formulation partnerships with Argentine bakery groups, while Meridional TCS competes through localized gum Arabic blending operations in Montevideo.
Food stabilizers comprise hydrocolloid, starch-derived, and protein-based compounds that manage water mobility, control syneresis, and maintain rheological consistency across thermal processing and freeze-thaw cycles; pectin requires a degree of methoxylation above fifty percent to form calcium-crosslinked gels suitable for acidified dairy matrices. Modified starches dominate volume flows into Brazil's UHT milk and yogurt segments, where cost-positioned waxy maize derivatives hold margin pools against native alternatives. Gums represent the fastest-expanding stabilizer type, driven by clean-label positioning in Argentine plant-based beverages where locust bean and guar systems displace synthetic emulsifiers.
ANVISA governs food additive maximum limits and positive-list inclusion for hydrocolloids entering Brazilian formulations, while Argentina's national food code enforces modified starch labeling thresholds that reshape supplier qualification protocols. MERCOSUR's harmonized technical regulations on food additives create cross-border compliance leverage for manufacturers holding multi-country registrations. Stakeholders must monitor pending updates to MERCOSUR's Common Market Group resolutions on novel hydrocolloid sources, as these will determine which suppliers retain formulation access across the customs union.
Market Dynamics
ANVISA's tightened hydrocolloid purity benchmarks are forcing Brazilian dairy manufacturers to requalify entire supplier bases, triggering a cascade of specification upgrades across MERCOSUR's cross-border supply chains.
Growth Catalysts
- Clean-label reformulation:Argentine beverage producers are accelerating locust bean and guar gum adoption in plant-based drink matrices to displace synthetic emulsifiers and capture premium positioning.
- MERCOSUR harmonization:The customs union's Common Market Group resolutions on novel hydrocolloid sources are creating unified compliance pathways that reduce multi-country registration burdens for qualified suppliers.
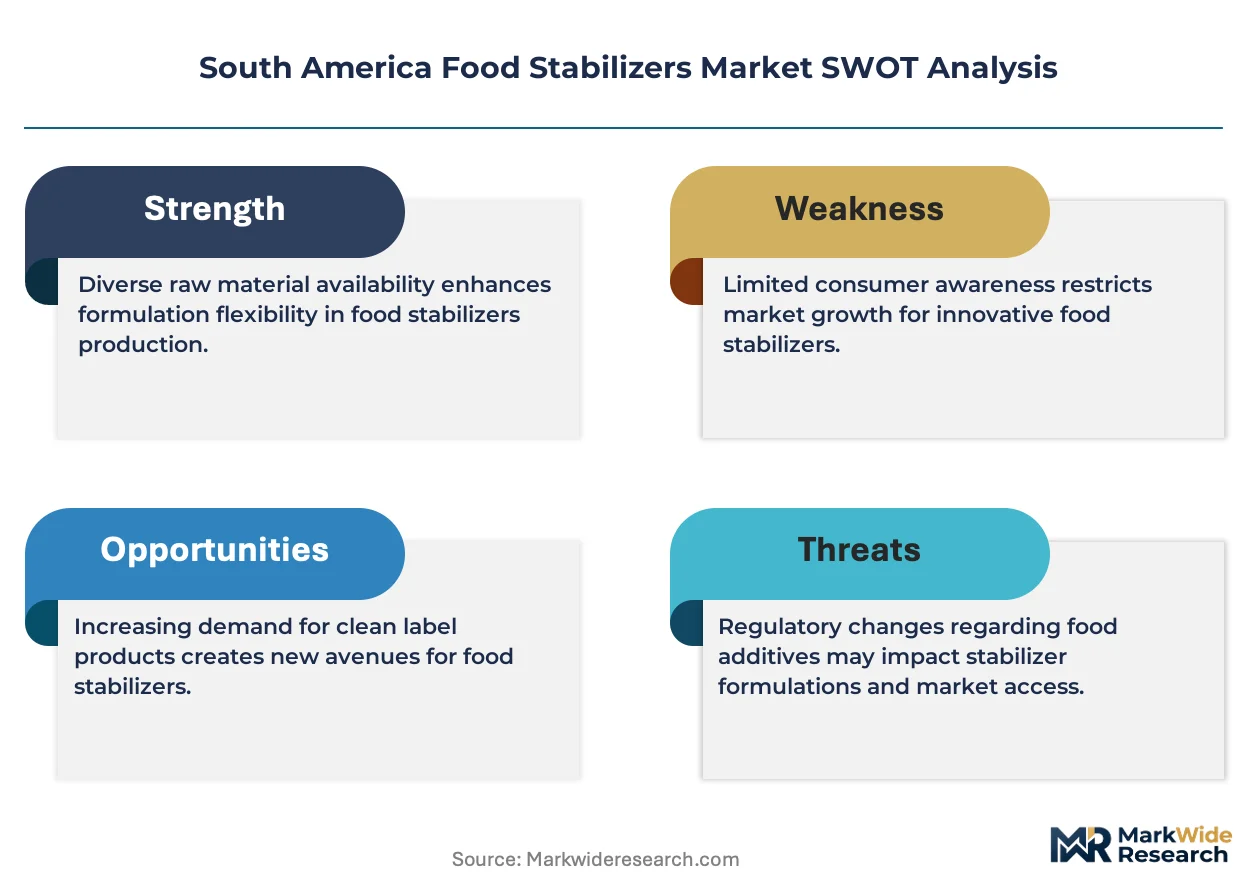
- Pectin substitution:Argentina's confectionery sector is displacing traditional gelatin with high-methoxyl pectin systems in gummy formulations to meet vegetarian and kosher dietary requirements.
Market Restraints
- Import dependency:Brazil's modified starch sector relies on captive corn wet-milling infrastructure concentrated among multinational suppliers, limiting regional compounder access to cost-competitive waxy maize derivatives.
- Purity standard escalation:ANVISA's updated food additive regulations impose analytical testing burdens that extend qualification timelines for hydrocolloid imports from non-preferred origins.
- Native starch displacement:Cost-positioned modified starches from integrated processors are compressing margin pools for native starch alternatives in UHT milk and yogurt segments.
Strategic Opportunities
- Uruguay gum Arabic blending:Montevideo-based localized processing operations offer tariff-advantaged hub status for distributing hydrocolloid compounds across MERCOSUR's southern cone.
- Extended shelf-life dairy:Brazilian manufacturers are reformulating processed dairy applications with advanced stabilizer systems to reduce cold-chain dependency and expand interior distribution reach.
- Freeze-thaw stability innovation:Convergence of modified starch and protein-based stabilizer technologies is enabling new dessert and frozen confection applications previously limited by texture degradation.
Industry Challenges
- Formulation expertise scarcity:Regional compounders lack sufficient rheology specialists to optimize multi-hydrocolloid synergies for acidified dairy matrices requiring precise calcium-crosslinked gel structures.
- Certification timeline compression:Argentina's national food code labeling thresholds for modified starches demand accelerated supplier requalification, straining technical documentation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Stabilizers Market |
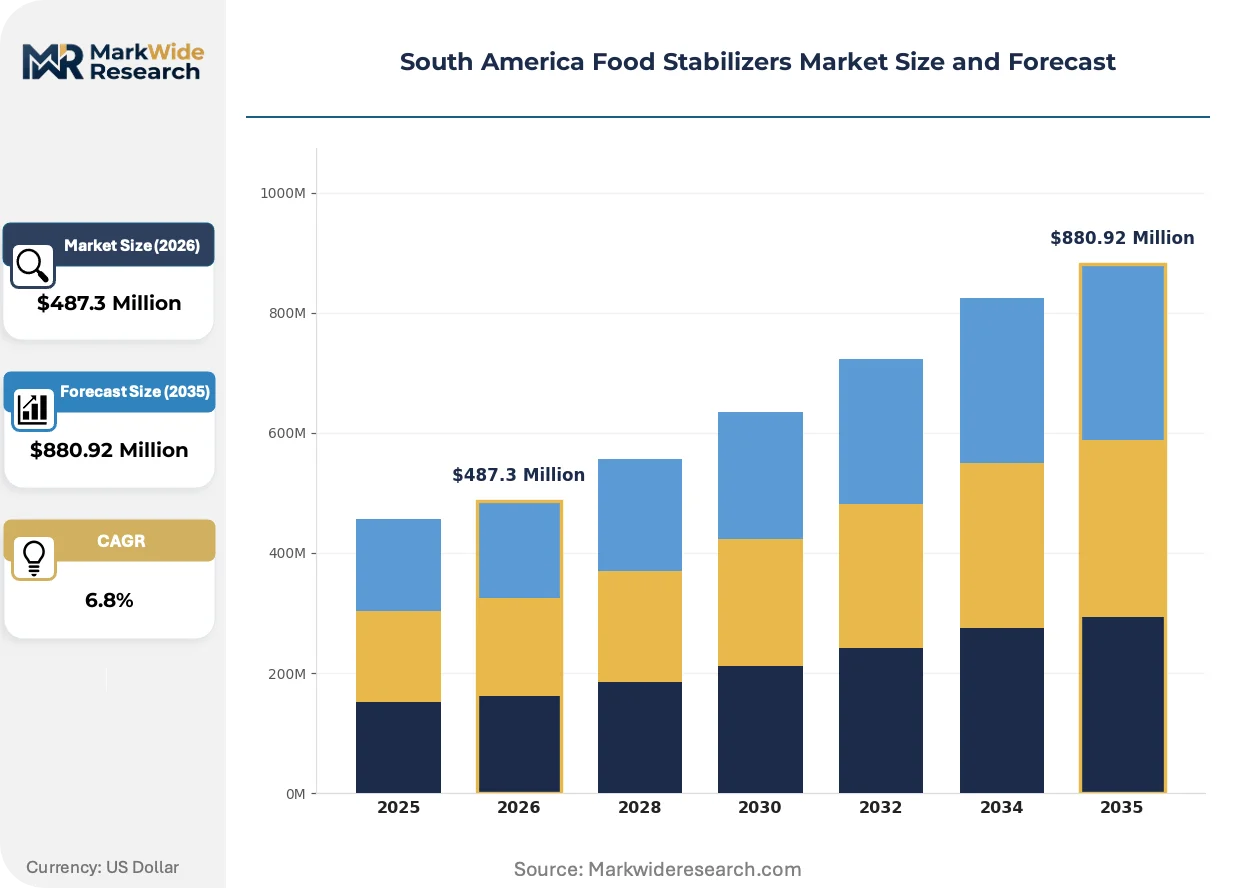
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Stabilizer Type: Modified Starches, Pectin, Gels, Gums Application: Dairy Products, Bakery Goods, Sauces, Dressings Form: Liquid, Powder, Granulated, Paste End User: Food Manufacturers, Restaurants, Catering Services, Home Consumers |
| Companies Covered | Ingredion Incorporated, Tate & Lyle Plc, Cargill Incorporated, AOM SA, Kerry Group plc, DuPont de Nemours Inc, BASF SE, Meridional TCS, Archer Daniels Midland Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Stabilizers Market Evolving Landscape
Reformulation priorities across South American food manufacturing are pivoting from cost minimization toward functional performance and regulatory pre-emption, reshaping how stabilizer suppliers structure technical service relationships.
Enzymatically decomposed starches with tailored rheological profiles are penetrating Brazil's dairy corridor at accelerating rates. UHT milk and yogurt producers are adopting these precision-modified derivatives to achieve viscosity stability across thermal processing cycles. The technology is decomposing traditional volume-based procurement into specification-driven partnerships where functional performance metrics override unit cost comparisons.
ANVISA's positive-list inclusion protocols for novel hydrocolloid sources are tightening entry barriers for non-established suppliers. The regulatory friction is compressing formulation flexibility for mid-tier compounders lacking dedicated regulatory affairs capacity. Brazilian dairy and Argentine confectionery segments are responding by consolidating supplier relationships with entities holding pre-validated multi-country registrations.
Ingredient procurement patterns are fragmenting as Argentine bakery groups and Brazilian dairy processors establish direct formulation partnerships with starch and hydrocolloid specialists. Traditional distribution intermediaries are losing specification influence as end-users internalize rheological testing capabilities. This disintermediation is most visible in São Paulo and Buenos Aires metropolitan clusters where technical service proximity determines supplier selection.
South America Food Stabilizers Market Segmentation
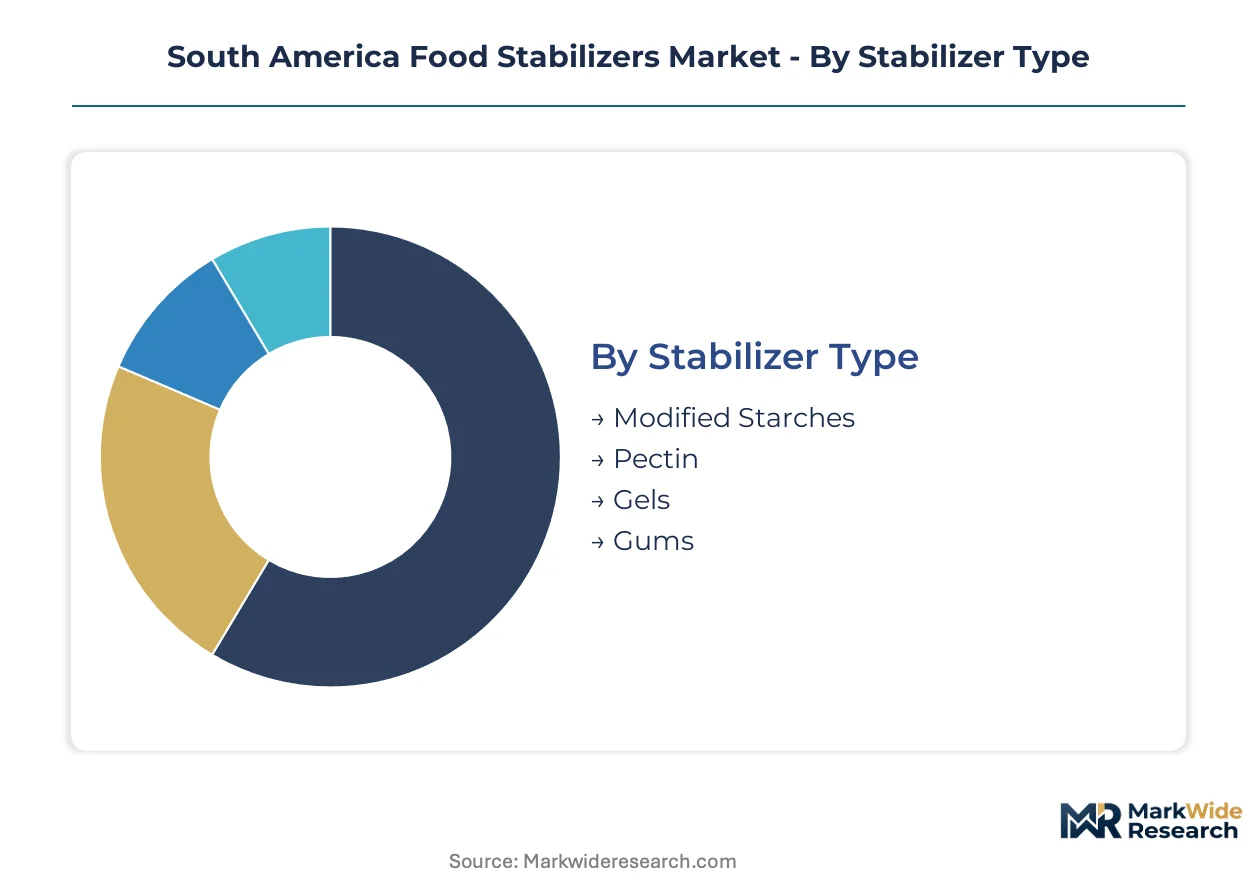
Stabilizer procurement patterns across South America fragment sharply by technical specification and supply chain proximity. Manufacturers in Brazil's dairy corridor and Argentina's confectionery belt prioritize different performance matrices, creating distinct segment trajectories.
Stabilizer Type:
Domestic production concentrates in modified starches through captive corn wet-milling infrastructure, while gums and specialized hydrocolloids remain import-dependent with purity verification burdens.
- Modified Starches:Waxy maize derivatives dominate Brazilian UHT milk and yogurt formulations. São Paulo-based dairy processors specify these for viscosity stability across thermal processing cycles.
- Pectin:High-methoxyl varieties requiring above-fifty-percent methoxylation enable calcium-crosslinked gels in acidified dairy matrices. Argentine confectioners specify these for vegetarian gummy formulations displacing traditional gelatin.
- Gels:Protein-based systems from regional collagen sources serve cost-sensitive dessert applications.
- Gums:Locust bean and guar systems gain share fastest in Argentine plant-based beverages as clean-label alternatives to synthetic emulsifiers.
Modified starches command the established base. The steepest expansion runs through gums.
Application:
Volume concentration tracks per capita dairy consumption in Brazil against Argentina's processed food export orientation toward MERCOSUR partners.
- Dairy Products:UHT milk and yogurt segments in Brazil's interior distribution networks drive specification-grade modified starch demand. Extended shelf-life reformulations reduce cold-chain dependency.
- Bakery Goods:Argentine bakery groups in Buenos Aires metropolitan clusters source tailored hydrocolloid synergies for texture retention in frozen dough systems.
- Sauces:Emulsion stability requirements in mayonnaise and ketchup production favor gum Arabic and xanthan blends.
- Dressings:Vinaigrette and creamy dressing manufacturers specify cold-swelling starches for process efficiency.
Dairy applications anchor volume procurement. Dressings climb the fastest as convenience formats penetrate smaller urban centers.
Form:
Dispersion characteristics determine logistics economics across Brazil's extended interior supply lines versus Argentina's concentrated Pampas manufacturing belt.
- Liquid:Pre-hydrated gum solutions serve high-throughput dairy processors seeking batch-to-batch consistency. Tanker delivery reduces handling labor.
- Powder:Free-flowing modified starches dominate Brazilian UHT milk powder fortification and Argentine dry-mix confectionery bases.
- Granulated:Low-dust handling properties suit automated dosing systems in mid-scale sauce production.
- Paste:Concentrated pectin preparations enable precise gel strength control in artisanal Argentine jam producers.
Powder forms retain the broadest installed base. Liquid concentrates gain share fastest among integrated dairy processors.
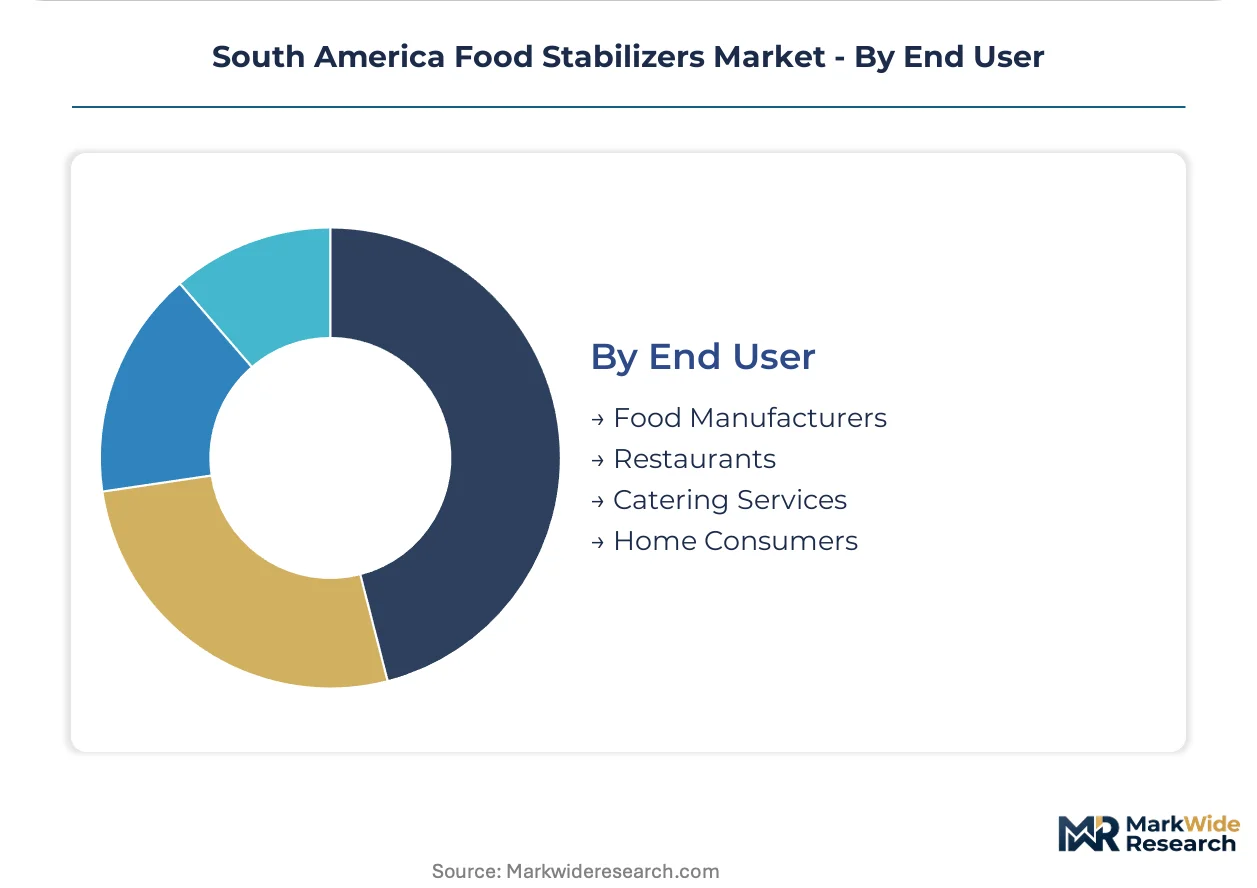
End User:
Specification authority concentrates differently across Brazil's fragmented food manufacturing landscape versus Argentina's more consolidated processor tiers.
- Food Manufacturers:Brazilian dairy and Argentine confectionery groups internalize rheological testing capabilities. Direct partnerships with starch and hydrocolloid specialists displace traditional distribution intermediaries.
- Restaurants:Chain operators in São Paulo and Buenos Aires metropolitan clusters specify stabilizer systems for menu consistency across franchise networks.
- Catering Services:Institutional foodservice procurement favors cost-optimized native starch blends for volume feeding applications.
- Home Consumers:Retail-format pectin and gelatin alternatives serve small-batch jam and dessert preparation in urban households.
Food manufacturers control specification authority. Restaurants expand procurement fastest as chain formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian buyers demonstrate the highest price elasticity in modified starch procurement, while Argentine confectioners absorb premium pricing for high-methoxyl pectin systems without volume reduction.
Brazil
UHT milk and yogurt processors in São Paulo's dairy corridor drive specification-grade modified starch demand for extended shelf-life reformulations. ANVISA's tightened hydrocolloid purity benchmarks are forcing manufacturers to requalify entire supplier bases with extended analytical testing timelines. Campinas-based compounders are consolidating direct partnerships with starch specialists to bypass traditional distribution intermediaries.
Argentina
Buenos Aires metropolitan confectionery groups are displacing traditional gelatin with high-methoxyl pectin systems in vegetarian gummy formulations. Argentina's national food code enforces modified starch labeling thresholds that reshape supplier qualification protocols and accelerate documentation burdens. Rosario-based bakery clusters source tailored hydrocolloid synergies for frozen dough texture retention systems.
Uruguay
Montevideo-based gum Arabic blending operations serve tariff-advantaged hub status for distributing hydrocolloid compounds across MERCOSUR's southern cone. The country's national food regulator maintains alignment with MERCOSUR harmonized technical regulations on food additives. Punta del Este corridor processors are expanding clean-label plant-based beverage production using locust bean and guar systems.
Chile
Santiago metropolitan food manufacturers are internalizing rheological testing capabilities to establish direct formulation partnerships with hydrocolloid specialists. Chile's national food safety authority enforces maximum additive limits consistent with MERCOSUR's Common Market Group resolutions. Valparaíso port logistics clusters are handling increased hydrocolloid import volumes for cross-border distribution into Argentine and Bolivian markets.
Colombia
Bogotá-based sauce and dressing producers specify cold-swelling starches for emulsion stability in mayonnaise and ketchup manufacturing. The country's national food and drug surveillance institute regulates additive inclusion through positive-list protocols. Medellín industrial corridors are adopting pre-hydrated gum solutions for high-throughput processing efficiency in emerging dairy applications.
South America Food Stabilizers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in South America's food stabilizer supply base. Multinational ingredient suppliers with captive corn wet-milling infrastructure command volume positions in Brazil's dairy corridor, while regional compounders compete through localized blending operations and tariff-optimized logistics. Three archetypes dominate: integrated starch processors with backward supply control, hydrocolloid specialists with multi-country regulatory registrations, and regional compounders with MERCOSUR cross-border distribution networks. Competitive moves concentrate on supplier requalification acceleration and direct technical service partnerships that displace traditional distribution channels.
Among the integrated processor tier, Cargill Incorporated and Ingredion Incorporated represent scale-driven positions anchored by captive infrastructure in key supply corridors. Tate & Lyle Plc exemplifies the formulation partnership archetype through sustained technical relationships with Argentine bakery groups. Meridional TCS occupies a regional compounder position with Montevideo-based operations leveraging tariff-advantaged hub status across the southern cone. These three entities illustrate how competitive positioning fragments between infrastructure-heavy, partnership-driven, and logistics-optimized strategies.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Tate & Lyle Plc |
| Cargill Incorporated |
| AOM SA |
| Kerry Group plc |
| DuPont de Nemours Inc |
| BASF SE |
| Meridional TCS |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day hydrocolloid import lead times from Asian origins concentrate pricing power among Brazilian compounders holding strategic safety stock, while Argentine pectin buyers absorb premium positioning without volume elasticity. ANVISA's purity verification extensions amplify inventory carrying costs, feeding back into supplier qualification premiums that reshape procurement hierarchies across MERCOSUR.
Pricing Analysis
Technical service contracts and formulation partnership fees generate disproportionate lifetime value against commodity ingredient sales. Contract-based long-term offtake structures dominate Brazilian dairy procurement, with price differentiation hinging on ANVISA pre-validation status and volume scale tiers. Cost compression in standard-grade modified starches is intensifying because captive corn wet-milling infrastructure limits regional compounder access. Brazilian UHT milk processors demonstrate highest price sensitivity, while Argentine confectioners absorb premium pectin pricing without volume reduction.
Supply Chain Analysis
Strategic stockpiling of high-methoxyl pectin and gum Arabic prevails among Argentine confectioners facing Argentine national food code documentation timelines, while Brazilian dairy processors favor just-in-time modified starch flows from Campinas-based compounders. Supply concentrates in Brazil's corn wet-milling corridor, India's guar cultivation belts, and European pectin extraction facilities. Raw material dependencies include waxy maize feedstock, locust bean gum from Mediterranean sources, and guar splits from Rajasthan processing clusters. Single-source vulnerability around ANVISA-preferred hydrocolloid origins creates qualification bottlenecks. Distribution runs through São Paulo and Buenos Aires metropolitan technical service hubs that displace traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in rheological testing and formulation partnership contracts expand faster than commodity stabilizer volumes, as Brazilian dairy processors internalize technical capabilities and disintermediate traditional distributors.
For Market Incumbents: Consolidate supplier requalification acceleration capabilities to capture ANVISA-driven specification upgrades before regional compounders build regulatory affairs capacity. Deepen backward integration into captive corn wet-milling infrastructure to defend margin position against emerging Argentine starch processors. Threat substitution from enzymatically decomposed starches demands R&D investment in precision-modified derivatives. For New Entrants and Emerging Players: Formulation expertise scarcity in multi-hydrocolloid synergy optimization opens white-space in acidified dairy matrices requiring calcium-crosslinked gel structures. Uruguay's tariff-advantaged hub status offers the most penetrable geography for MERCOSUR cross-border distribution buildout. Go-to-market through direct technical service partnerships with São Paulo metropolitan dairy clusters bypasses entrenched distribution channels. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational ingredient parents seeking to divest non-core South American stabilizer assets amid portfolio rationalization pressures. Long-term viability across the analysis window favors hydrocolloid specialists with pre-validated multi-country registrations over commodity starch processors facing margin compression. Watch MERCOSUR Common Market Group resolution updates on novel hydrocolloid sources as inflection signal for formulation access rights.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet-Milling | Cargill's captive waxy maize infrastructure anchors Brazilian dairy corridor supply security. |
| Multi-Country Regulatory Registration | ANVISA and Argentine national food code alignment reduces cross-border compliance burdens. |
| Technical Service Partnership Expansion | Tate & Lyle's Buenos Aires bakery relationships displace traditional distribution intermediaries. |
| Localized Gum Arabic Blending Hub | Meridional TCS leverages Montevideo tariff advantages for southern cone distribution reach. |
| Enzymatic Starch Modification R&D | Precision rheology profiles penetrate Brazil's UHT milk specification-driven procurement. |
Research Methodology
Cross-validation between ANVISA regulatory filing databases and Argentine national food code amendment records anchors the qualitative findings on purity benchmark evolution. Primary interviews with Brazilian dairy formulation managers, Argentine confectionery technical directors, Uruguayan gum Arabic compounders, and MERCOSUR regulatory affairs specialists combined with secondary validation from customs trade data, SEC 10-K filings of listed ingredient suppliers, and FAO agricultural commodity statistics. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Sensitivity analysis around ANVISA timeline compression scenarios and MERCOSUR harmonization pace variations stress-tests projection robustness. The analytical framework models stabilizer type, application segment, form factor, and end-user specification authority across the projection horizon. CAGRs derive from segment-level volume trajectory analysis calibrated to per capita dairy consumption patterns and clean-label reformulation adoption curves. Industry-specific inputs include hydrocolloid import dependency ratios and corn wet-milling capacity utilization assumptions.
Forecasts assume regulatory continuity in Brazilian ANVISA and Argentine national food code regimes; material policy shifts would require re-modeling. Commodity price volatility in guar and locust bean gum feedstocks, alongside ANVISA positive-list expansion timing, constitute primary revision triggers. Practitioners should keep alternative scenarios live as MERCOSUR Common Market Group resolution trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Antistaling Agent Market