
 Dairy-Free Smoothies Market | 2026-2036
Dairy-Free Smoothies Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy-Free Smoothies Market Outlook
Capital-intensity divergence between cold-press infrastructure and private-label co-manufacturing is rotating competitive advantage toward brands with captive bottling networks. Innocent Drinks leverages its European chilled distribution backbone to sustain shelf-space premiums in UK and German retail. Daily Harvest anchors its direct-to-consumer model with frozen supply-chain control, while Califia Farms competes through almond-milk processing integration that extends from California orchards to retail placement.
Dairy-free smoothies are shelf-stable or refrigerated beverages formulated without lactose, casein, or whey, typically blending plant milks, fruit purees, and functional additives at pH levels between 3.8 and 4.6 for microbial stability and sensory acceptance. Fruit-based formulations occupy the largest volume share, though protein-infused variants capture disproportionate margin pools as vegan athletes and fitness enthusiasts shift post-workout recovery spending from dairy isolates to pea and soy protein blends. Plant-based ingredient sourcing dominates formulation decisions, with almond milk and coconut water bases leading clean-label positioning among health-conscious consumers.
FDA nutrition labeling requirements and USDA organic certification standards govern product claims and market access in the United States, while EFSA health-claim regulations and EU organic labeling rules constrain promotional language across European retail channels. The EU Green Deal's packaging-waste directives are forcing reformulation of single-use plastic bottles toward recycled PET or fiber-based alternatives. Stakeholders must monitor evolving allergen disclosure mandates and carbon-footprint reporting obligations as procurement criteria for retail listing agreements tighten.
Market Dynamics
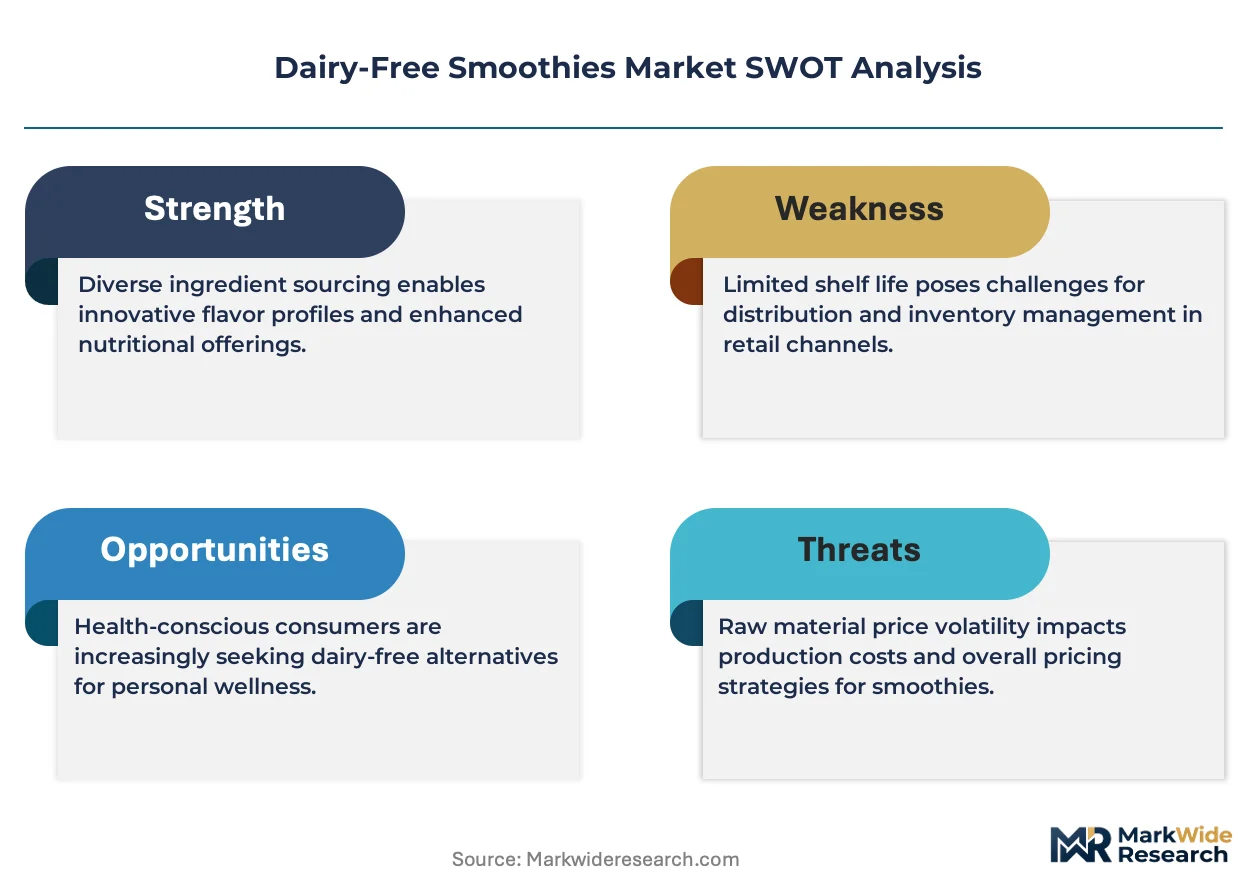
Clean-label formulation mandates across multiple jurisdictions are compressing ingredient flexibility while amplifying sourcing costs, forcing brands to restructure supplier relationships and reformulate around restricted additive palettes.
Growth Catalysts
- EU Green Deal packaging directives:Recycled PET and fiber-based bottle mandates are accelerating capital deployment into sustainable packaging infrastructure, creating first-mover advantages for compliant brands.
- Pea protein isolation advances:Improved extraction yields and neutral flavor profiles are displacing soy as the preferred vegan protein base in functional smoothie formulations.
- Brazilian functional beverage adoption:Post-workout recovery culture expansion in São Paulo and Rio de Janeiro is driving demand for protein-infused plant-based smoothies.
Market Restraints
- Almond milk input volatility:California water restrictions and orchard disease pressure create recurring margin compression for brands dependent on almond-base supply chains.
- Single-source coconut water concentration:Philippine and Indonesian supplier dominance exposes formulations to climate-driven harvest disruptions and price spikes.
- pH stability technical ceiling:Current natural preservation methods limit shelf-life extension beyond 45 days for clean-label refrigerated products, constraining distribution radius.
Strategic Opportunities
- USDA Organic certification tailwind:Premium pricing power attached to organic claims remains underexploited in conventional retail channels outside natural grocery.
- Frozen direct-to-consumer channel:Subscription-based frozen smoothie delivery bypasses refrigerated retail slotting fees while capturing higher lifetime value per subscriber.
- Oat milk and hemp protein convergence:Blending these ingredients addresses allergen concerns while delivering complete amino acid profiles for athletic recovery segments.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning plant-protein functionality, natural preservation, and sensory optimization commands premium compensation and lengthens R&D timelines.
- Co-packer certification backlog:USDA organic and SQF facility qualifications face 12-18 month approval queues, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy-Free Smoothies Market |
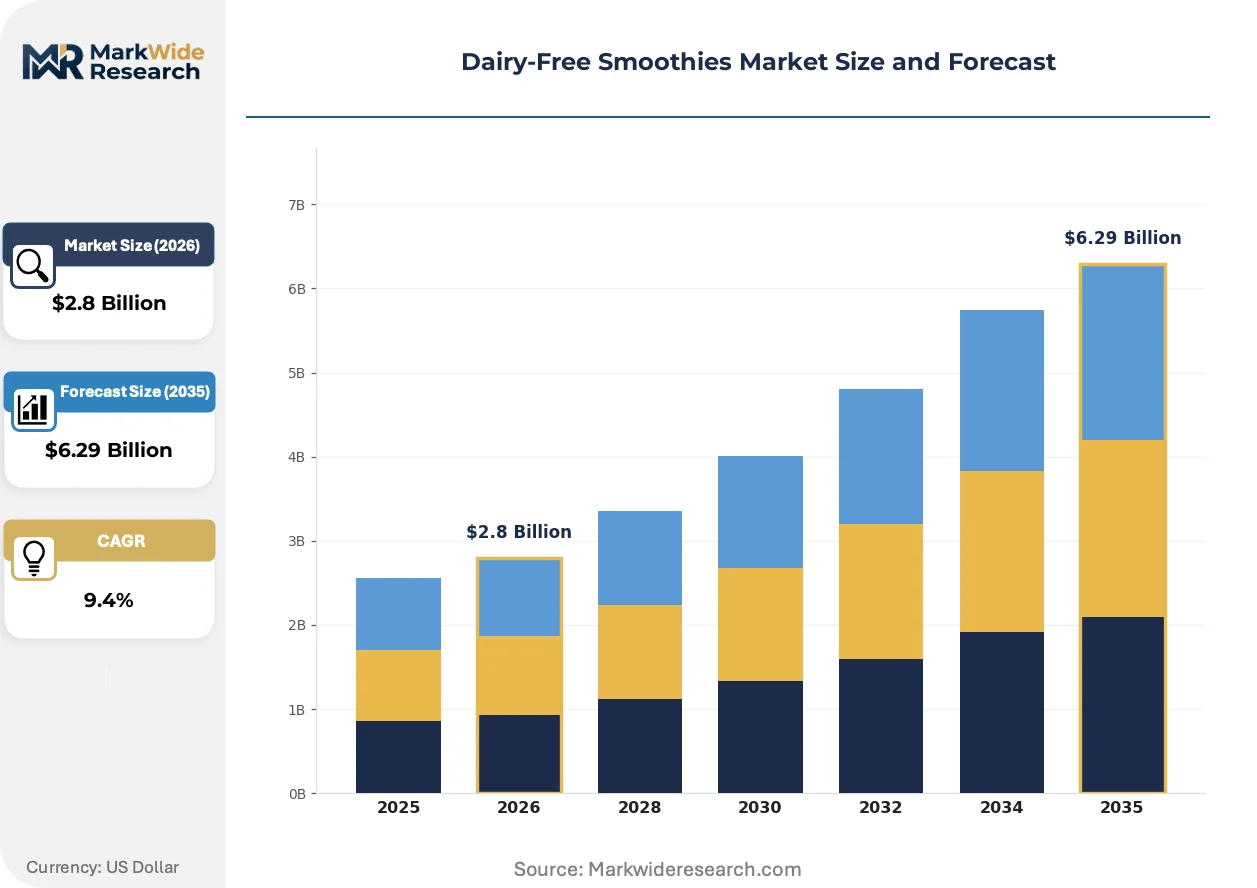
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit-Based, Protein-Infused, Vegetable-Enhanced, Nut-Smoothies Ingredient Source: Plant-Based, Almond Milk, Coconut Water, Soy Protein Flavor Profile: Berry Blend, Tropical Mix, Green Detox, Chocolate Target Consumer: Health-Conscious, Vegan Athletes, Busy Professionals, Fitness Enthusiasts |
| Companies Covered | Innocent Drinks, Daily Harvest, Bolthouse Farms, Suja Juice, Koia, Naked Juice, Califia Farms, Happy Planet, Smoothie King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy-Free Smoothies Market Strategic Shifts
High-pressure processing and aseptic filling technologies are redrawing the boundary between refrigerated and shelf-stable segments, while regulatory pressure on packaging materials accelerates format experimentation.
Pulsed electric field pasteurization is fragmenting the traditional thermal processing landscape. Cold-press juice operators and plant-based beverage startups are adopting this non-thermal method to preserve enzyme activity and vitamin retention. The technology is fragmenting incumbent equipment supplier relationships as engineering firms specializing in PEF systems capture retrofit contracts from established thermal vendors.
EFSA health-claim substantiation requirements are tightening promotional language across European retail channels. Brands must now provide clinical trial documentation for immunity, digestive health, and energy claims, elevating R&D spend for market access. Protein-infused variants targeting German fitness consumers face the steepest compliance burden as claim scrutiny intensifies.
Direct-to-consumer frozen smoothie subscriptions are displacing single-serve refrigerated purchases among urban millennials. Daily Harvest and similar platforms bypass retail slotting fees while capturing recurring revenue and consumption data. This channel shift concentrates in US coastal metros where cold-chain logistics density supports reliable frozen delivery.
Dairy-Free Smoothies Market Segmentation
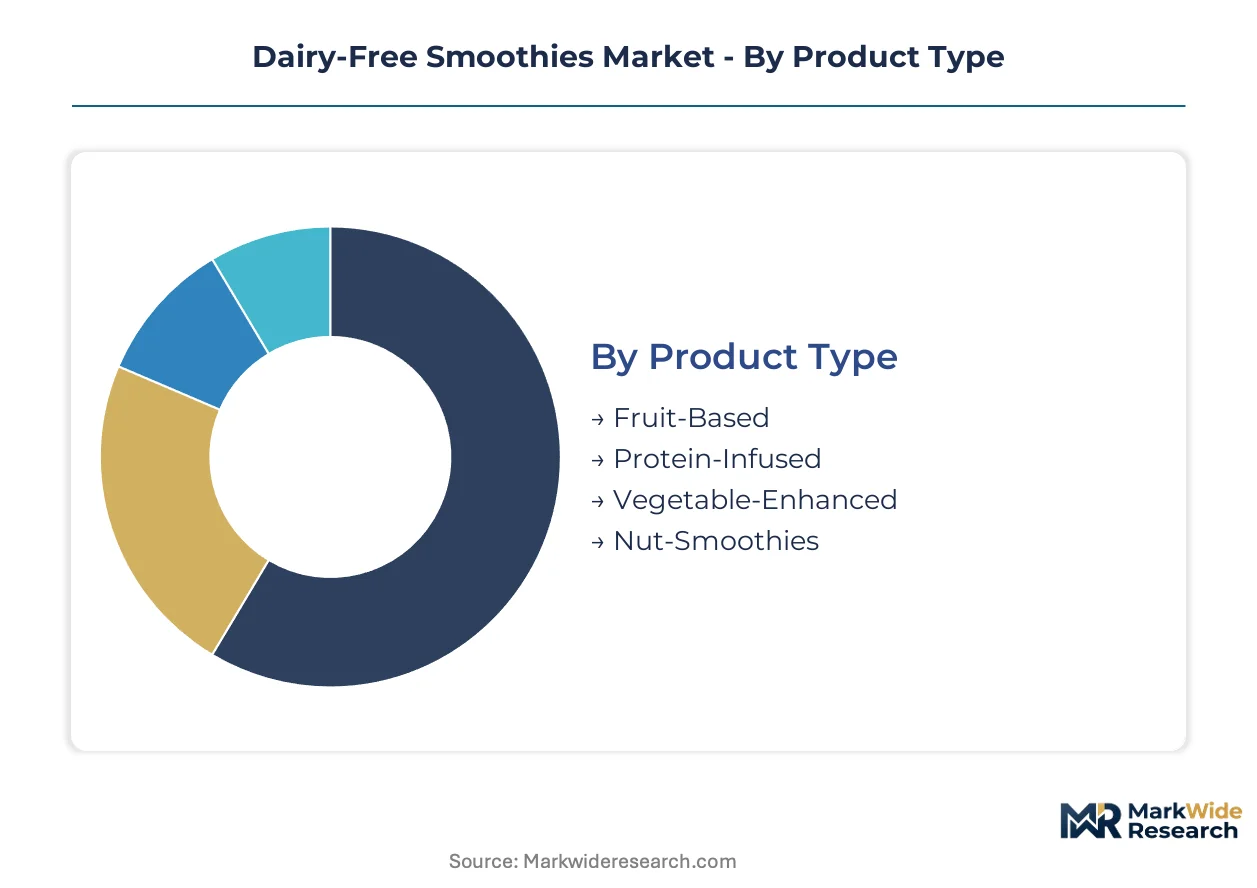
Product differentiation in dairy-free smoothies hinges on functional positioning and ingredient provenance rather than flavor alone. Segmentation reveals where substitution pressure from adjacent beverage categories—cold-press juices, sports nutrition drinks, ready-to-drink coffee—threatens incumbent formats most acutely.
Product Type:
Fruit-based formulations face the most intense substitute threat from cold-press juice operators and private-label refrigerated beverages, while protein-infused variants build defensive moats through functional claims and athletic recovery positioning.
- Fruit-Based:Blends rely on fruit purees and natural sweeteners at pH levels between 3.8 and 4.6 for microbial stability. Demand concentrates in conventional grocery refrigerated cases across Germany and the United States, where clean-label positioning competes directly with private-label juice alternatives and squeezes margin pools.
- Protein-Infused:Pea and soy protein isolates deliver 15-25g protein per serving for post-workout recovery applications. Vegan athletes in São Paulo and Los Angeles drive disproportionate volume as spending shifts from dairy isolates to plant-based alternatives, supported by gym channel distribution partnerships.
- Vegetable-Enhanced:Spinach, kale, and beet formulations target nutrient-density positioning with lower sugar profiles than fruit-dominant alternatives.
- Nut-Smoothies:Cashew and macadamia bases deliver creamier mouthfeel for premium positioning in natural grocery channels.
Fruit-based retains volume leadership; protein-infused holds the steepest expansion curve.
Ingredient Source:
Cost tier stratification separates commodity plant milk bases from specialty protein isolates, with almond milk occupying the contested middle ground where input volatility disrupts pricing predictability most severely.
- Plant-Based:Oat milk and hemp protein blends address allergen concerns while delivering complete amino acid profiles for athletic recovery segments. Formulation flexibility allows brands to bypass California almond supply constraints and EFSA allergen disclosure mandates.
- Almond Milk:California orchard sourcing dominates clean-label positioning despite water restriction pressures and hull rot disease cycles that create recurring margin compression. Brands with captive orchard relationships or long-term supply contracts defend position most effectively.
- Coconut Water:Philippine and Indonesian supplier concentration exposes formulations to climate-driven harvest disruptions and price spikes.
- Soy Protein:Neutral flavor profile improvements and cost advantages sustain presence in economy-tier formulations despite pea protein displacement in premium segments.
Almond milk dominates current volume; oat and hemp blends are climbing the fastest as allergen-free alternatives gain shelf space.
Flavor Profile:
Application context determines flavor selection more than demographic targeting, with consumption occasion—breakfast replacement, post-workout, afternoon snack—driving preference patterns across retail and direct-to-consumer channels.
- Berry Blend:Strawberry, blueberry, and raspberry combinations dominate breakfast replacement occasions and conventional grocery velocity. German and UK retailers prioritize berry SKUs for chilled distribution backbone efficiency and turnover predictability.
- Tropical Mix:Mango, pineapple, and coconut formulations align with summer seasonal programming and Brazilian market preferences. São Paulo and Rio de Janeiro consumers drive tropical flavor adoption as functional beverage culture expands beyond traditional fruit juice consumption.
- Green Detox:Kale, spirulina, and matcha combinations target wellness-oriented consumers seeking perceived cleansing benefits.
- Chocolate:Cacao-based formulations compete with ready-to-drink protein shakes for dessert replacement and post-workout occasions.
Berry blend commands the broadest retail distribution; tropical mix shows the strongest geographic expansion momentum into European and North American markets.
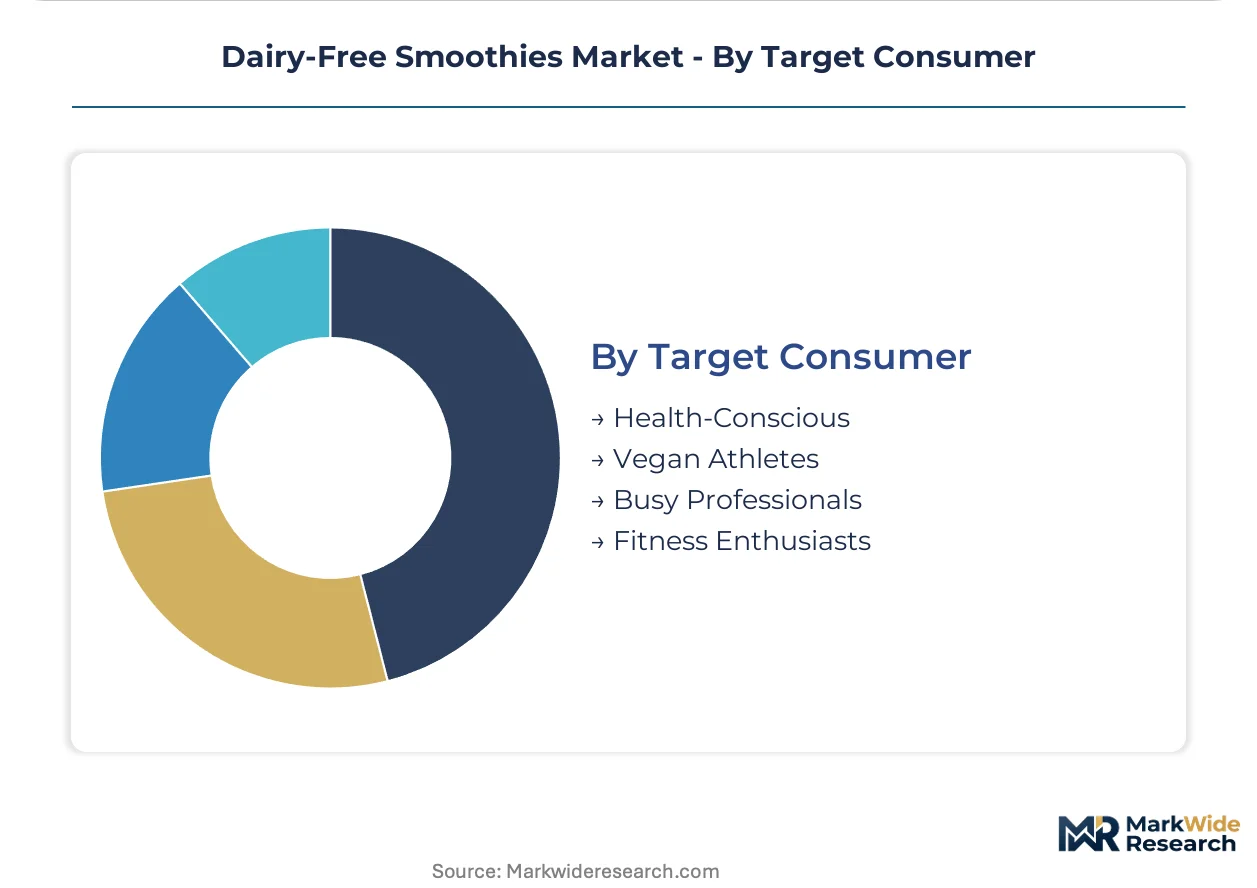
Target Consumer:
Customer type segmentation reveals divergent channel preferences and price elasticity profiles, with subscription-based frozen delivery capturing highest lifetime value from urban professionals while fitness enthusiasts drive protein-infused velocity through gym and specialty retail.
- Health-Conscious:Clean-label seekers prioritize USDA Organic and EU organic certification claims, accepting price premiums for verified ingredient sourcing. This segment concentrates in US coastal metros and German urban centers where natural grocery penetration supports premium positioning.
- Vegan Athletes:Post-workout recovery demands drive protein-infused purchasing with specific amino acid profile requirements. Brazilian fitness culture expansion and German gym channel development accelerate this segment's commercial significance.
- Busy Professionals:Breakfast replacement and meal substitution occasions favor single-serve refrigerated formats and frozen subscription deliveries.
- Fitness Enthusiasts:Broader than vegan athletes, this group includes flexitarians seeking plant-based alternatives to dairy protein for digestive comfort and perceived health benefits.
Health-conscious consumers provide the volume foundation; vegan athletes deliver the steepest margin expansion as protein positioning commands price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German consumers absorb organic premiums with minimal volume sacrifice. Brazilian buyers trade down aggressively when coconut water or almond milk input costs spike. US coastal metros split between subscription-insensitive professionals and discount-seeking conventional grocery shoppers.
United States
FDA nutrition labeling and USDA organic certification govern market access, with clean-label claims facing heightened FTC scrutiny. Frozen direct-to-consumer subscriptions concentrate in New York, Los Angeles, and San Francisco metros where cold-chain density supports reliable delivery. Califia Farms anchors West Coast almond-milk processing integration from orchard to retail placement.
Germany
EFSA health-claim substantiation requirements constrain immunity and digestive wellness promotional language, elevating R&D compliance spend. EFSA and EU organic labeling rules reshape ingredient sourcing for conventional retail placement. Berlin and Munich urban clusters drive protein-infused variant adoption among vegan athlete segments seeking post-workout recovery alternatives.
Brazil
ANVISA governs functional beverage claims and allergen disclosure mandates for imported formulations. São Paulo and Rio de Janeiro fitness culture expansion accelerates protein-infused plant-based smoothie demand as gym channel partnerships proliferate. Tropical flavor profiles dominate local formulation preferences, with mango and coconut bases capturing shelf-space premiums.
United Kingdom
Post-Brexit regulatory divergence from EU labeling standards creates compliance complexity for cross-channel suppliers. Innocent Drinks leverages its chilled distribution backbone to sustain retail shelf-space premiums across Tesco, Sainsbury's, and Waitrose networks. London metro health-conscious millennials drive clean-label velocity in premium refrigerated cases.
Canada
Health Canada and PMRA regulate organic claims and natural health product classifications for functional additive positioning. Toronto and Vancouver urban centers concentrate demand for oat milk and hemp protein blends addressing allergen-sensitive consumers. Frozen subscription services penetrate less deeply than US coastal markets due to sparser cold-chain infrastructure.
Dairy-Free Smoothies Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive bottling networks and orchard relationships conferring sourcing stability. The competitive terrain splits between refrigerated retail slotting-fee warriors and frozen direct-to-consumer subscription operators. Three archetypes dominate: vertically integrated processors controlling upstream ingredient supply, platform-native brands bypassing retail entirely, and legacy juice houses retooling around plant-based positioning. Consolidation pressure operates through co-packer certification backlogs and organic facility qualification queues rather than headline M&A.
Within the integrated processing tier, Innocent Drinks and Califia Farms exemplify divergent geographic and channel strategies. Daily Harvest occupies the platform-native archetype with frozen supply-chain control. Bolthouse Farms and Naked Juice represent legacy juice house repositioning toward plant-based formulations. Koia anchors the protein-infused functional specialist segment. Suja Juice and Happy Planet exemplify cold-press heritage brands adapting to clean-label dairy-free demand. Smoothie King operates the service-layer model with blended-to-order retail presence rather than pre-packaged manufacturing.
| Leading Market Players |
|---|
| Innocent Drinks |
| Daily Harvest |
| Bolthouse Farms |
| Suja Juice |
| Koia |
| Naked Juice |
| Califia Farms |
| Happy Planet |
| Smoothie King |
| Others |
Value Chain & Pricing Dynamics
Capital utilization at cold-press bottling facilities and frozen co-packing plants shapes both supply concentration and price floors across the dairy-free smoothie category. Scale advantages at Innocent Drinks' European chilled distribution network and Daily Harvest's frozen fulfillment centers create defensive moats that smaller brands cannot replicate without equivalent infrastructure investment.
Pricing Analysis
Subscription renewal revenue and frozen bundle commitments drive lifetime value more than single-unit retail transactions. Three-tier pricing structure across premium organic, standard clean-label, and economy private-label levels stratifies the market, with USDA Organic certification and EFSA-compliant health claims commanding shelf-space premiums. Pricing pressure stems from California almond milk input volatility and Philippine coconut water harvest disruptions that compress margins for non-integrated brands. Health-conscious millennials in urban clusters show lowest price sensitivity, while Brazilian conventional grocery shoppers trade down aggressively when base ingredient costs spike.
Supply Chain Analysis
Inventory cycles for frozen fruit concentrates and protein isolates extend lead times beyond refrigerated fresh formats, compressing working capital flexibility for direct-to-consumer operators. Raw material sourcing concentrates in California for almond milk, the Philippines and Indonesia for coconut water, and the Midwest for pea protein isolation. Formulation rests on single-source coconut water concentration and California orchard dependency that exposes brands to climate-driven supply disruptions. Distribution runs through refrigerated retail slotting-fee networks for conventional brands and frozen last-mile delivery partnerships for subscription-native operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail buyers and platform-native subscription operators, as fragmentation among small-format juice bars and independent natural grocers accelerates category consolidation.
For Market Incumbents: Compound captive bottling advantages by securing long-term organic certification queues and exclusive co-packer relationships that lock out emerging competitors. Cold-press infrastructure investments at Innocent Drinks and Daily Harvest demonstrate how fixed-asset control defends against private-label encroachment. Prioritize backward integration into almond orchard partnerships or oat protein processing to bypass input volatility that erodes margin pools. For New Entrants and Emerging Players: Gym channel distribution partnerships represent an under-served service layer where incumbent beverage giants lack dedicated fitness-focused sales infrastructure. Brazilian protein-infused smoothie demand and German vegan athlete segments offer the most penetrable white-space targets with localized formulation requirements. Pursue direct-to-consumer frozen subscription models that bypass refrigerated retail slotting barriers entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors brands with pulsed electric field pasteurization capabilities and aseptic filling infrastructure that bridge refrigerated and shelf-stable segments. Long-term viability hinges on sustainable packaging compliance and clean-label R&D pipelines rather than flavor innovation alone. Watch for co-packer certification backlog resolution as the inflection signal for accelerated new product commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Unlocks premium shelf placement at Whole Foods and Sprouts while commanding price premiums. |
| Pulsed Electric Field Pasteurization Adoption | Preserves enzyme activity for clean-label positioning against thermal-processed competitors. |
| Frozen Direct-to-Consumer Launch | Bypasses refrigerated retail slotting fees while capturing recurring subscription revenue streams. |
| Backward Integration into Oat Processing | Reduces allergen disclosure burden and insulates margins from almond supply volatility. |
| Sustainable Packaging Transition | EU Green Deal compliance secures European retail listing agreements and first-mover positioning. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at dairy-free smoothie manufacturers, category buyers at natural grocery retailers, supply chain directors at cold-press bottling facilities, and formulation scientists at plant-protein ingredient suppliers and refined through secondary validation. FDA nutrition labeling databases, EFSA health-claim substantiation filings, USDA organic certification records, and Nielsen retail velocity data anchored quantitative triangulation. Bottom-up volume modeling across ingredient source and product type segments converged with top-down category sizing from trade association publications.
Variance decomposition across price tier, distribution channel, and geographic demand cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, ingredient source, flavor profile, and target consumer archetype alongside regulatory compliance tier as an industry-specific dimension. CAGRs were derived from trend extrapolation of historical velocity patterns adjusted for channel-shift assumptions. Forecast inputs incorporated EFSA health-claim approval timelines and EU Green Deal packaging mandate implementation schedules.
Underlying assumptions cover clean-label formulation standard persistence, cold-chain logistics density expansion, and protein isolate supply scaling, with deviation risk concentrated in California water restriction severity and Philippine climate disruption frequency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Non-Dairy Creamer Powder Market