
 Legumes Plant-Based Milk Market | 2026-2036
Legumes Plant-Based Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Legumes Plant-Based Milk Market Insights
Subscription-based replenishment services for pea and soy milk is broadening recurring revenue streams beyond one-time retail purchases. Danone leverages its refrigerated distribution network to sustain shelf-stable and fresh-format product lines across multiple continents. Ripple Foods specializes in pea protein extraction technology that anchors its position in the premium plant-based beverage segment. Califia Farms competes through diversified carton and bottle packaging formats that extend its presence in café and household channels.
Legumes plant-based milk denotes aqueous extracts from protein-rich legume seeds, typically containing 2-8% plant protein by weight, homogenized and fortified with calcium, vitamin D, and stabilizers to emulate dairy milk functionality in beverages, cooking, and food manufacturing. Soy milk retains the largest volume position due to decades of processing infrastructure maturity, while pea milk captures faster growth trajectories driven by allergen-friendly positioning and neutral flavor profiles. Tetra pack formats dominate ambient retail distribution, though bottle formats command margin premiums in chilled dairy-alternative aisles where visual differentiation and premium positioning matter.
The FDA oversees allergen labeling requirements that shape pea and soy milk disclosure protocols in the United States, while EFSA establishes novel food safety assessments for emerging lentil and faba bean milk entries into European commerce. REACH compliance for food-contact materials influences packaging substrate selection across Tetra pack and bottle categories. Stakeholders must monitor evolving protein content standardization debates between regulators and dairy industry lobbies that could redefine permissible product nomenclature and nutritional claims.
Market Dynamics
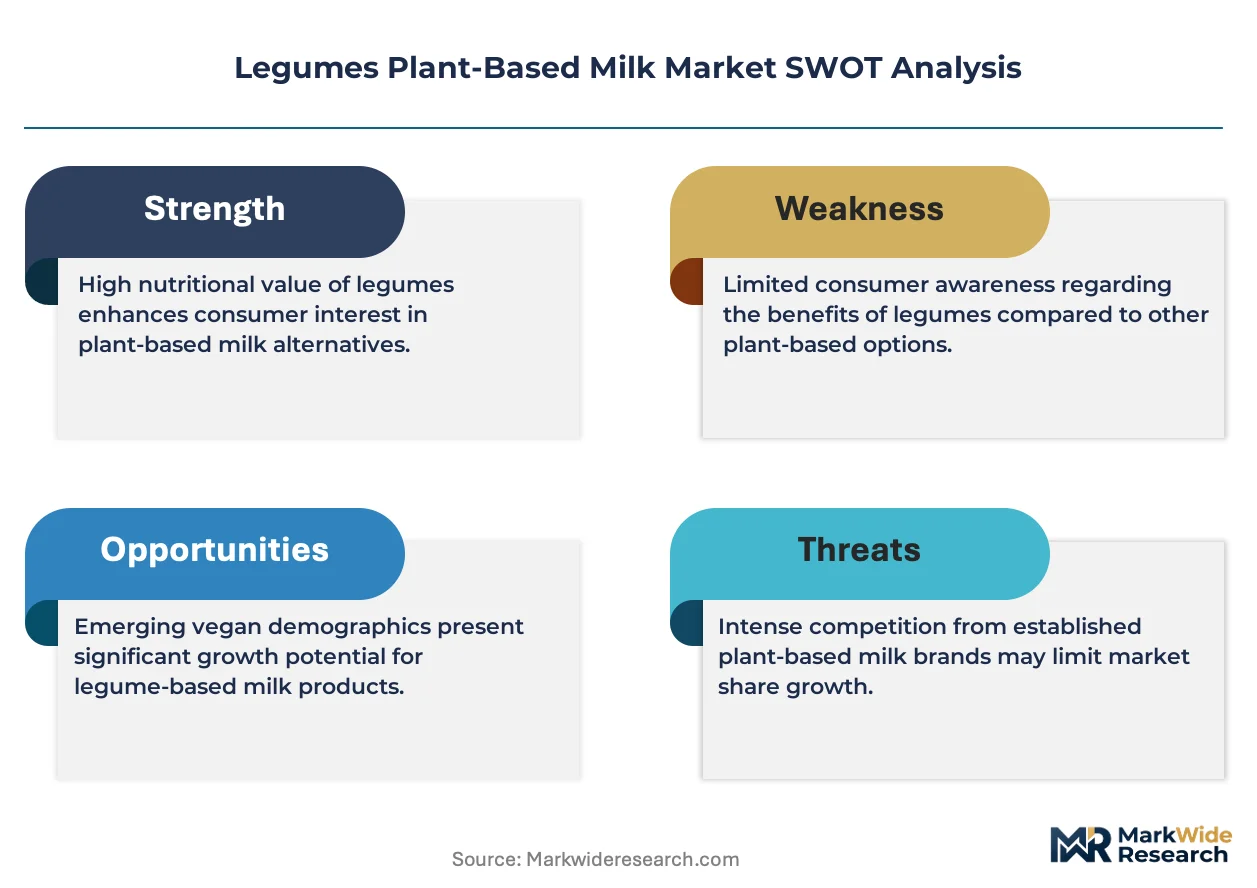
The EU Green Deal and F-Gas Regulation are compressing formulation timelines for legume-derived beverages, forcing processors to decarbonize extraction infrastructure while maintaining protein yield targets. Food manufacturers now face binding sustainability disclosures that extend from seed sourcing through retail shelf placement.
Growth Catalysts
- Protein fortification mandates:EFSA novel food assessments for lentil and faba bean milk entries are accelerating commercialization timelines for allergen-friendly alternatives. European retailers are expanding dedicated plant-based aisles.
- Chilled distribution infrastructure:Refrigerated logistics networks in Germany, France, and the United Kingdom now accommodate ambient and fresh-format legume milk simultaneously. This dual-channel capability unlocks foodservice penetration.
- Pea protein extraction yields:Mechanical separation technologies have improved protein recovery rates from yellow split peas. Processing efficiency gains are lowering unit costs for premium-positioned beverages.
Market Restraints
- Organic pea supply concentration:Contract farming agreements cluster in specific Canadian prairie provinces and Ukrainian black-soil regions. Geopolitical disruption or weather events constrain input security.
- Beany off-flavor persistence:Lipoxygenase activity in raw legume materials creates sensory barriers for mainstream dairy consumers. Enzymatic treatment adds processing steps and capital intensity.
- REACH food-contact compliance:Packaging substrate selection for Tetra pack and bottle formats faces restricted chemical migration thresholds. Alternative barrier materials carry cost premiums.
Strategic Opportunities
- Faba bean milk white space:Faba bean protein extraction remains underdeveloped relative to soy and pea. European novel food approvals position this legume for 2025-2026 retail launches.
- Subscription replenishment models:Direct-to-consumer platforms for pea and soy milk are building recurring revenue streams beyond conventional retail. Data capture enables personalized formulation recommendations.
- Carbon labeling differentiation:EU Green Deal corporate sustainability reporting requirements reward transparent lifecycle emissions data. Early adopters gain shelf placement advantages in German and French supermarkets.
Industry Challenges
- Protein standardization disputes:Dairy industry lobbies are contesting permissible nutritional claims and product nomenclature for legume-derived beverages. Regulatory uncertainty delays marketing investments.
- Cross-contamination protocols:Shared processing lines between allergenic soy and allergen-friendly pea require rigorous cleaning validation. FDA allergen labeling scrutiny elevates compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legumes Plant-Based Milk Market |
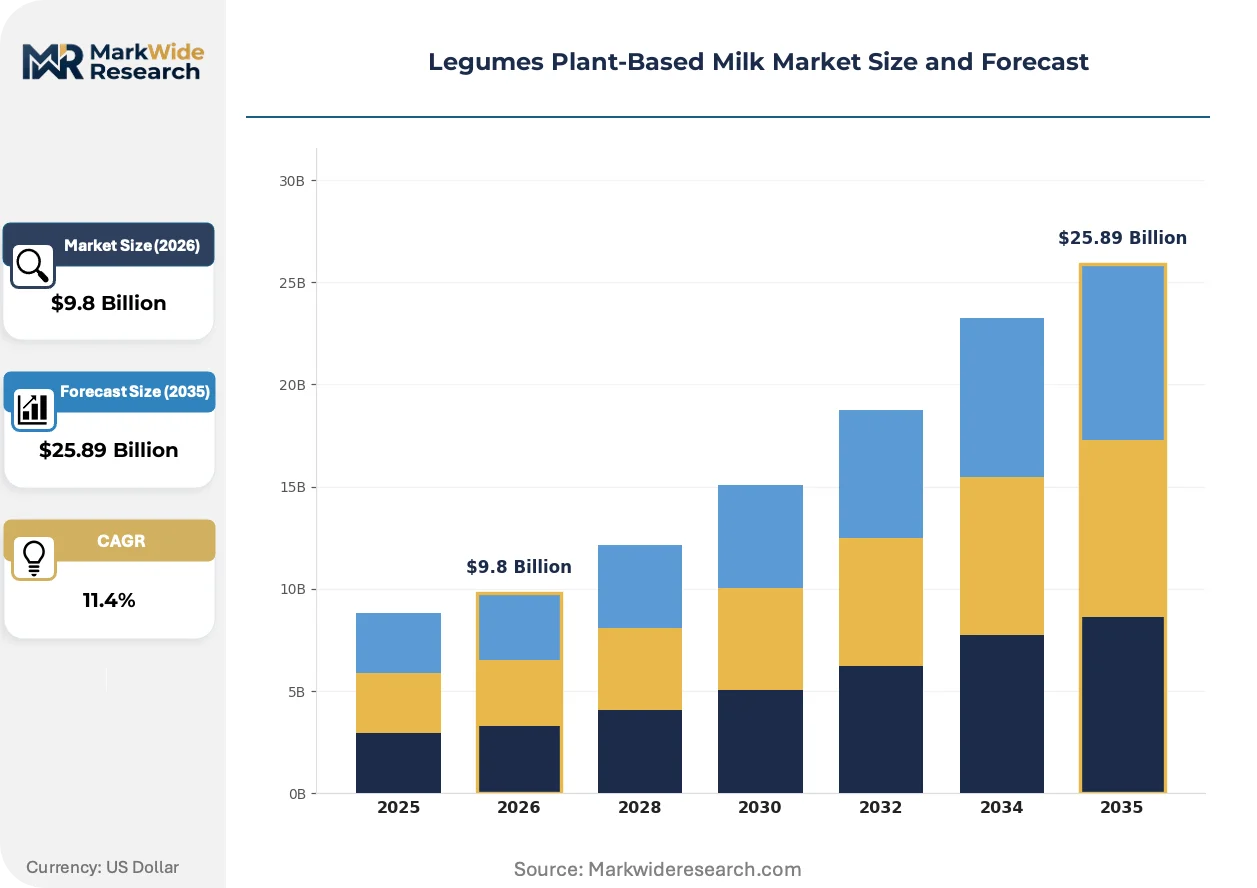
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Pea Milk, Lentil Milk, Faba Bean Milk Packaging Type: Bottles, Tetra Packs, Cartons, Pouches End User: Households, Restaurants, Cafés, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Shops |
| Companies Covered | Danone, Ripple Foods, Silk, Alpro, Eden Foods, Califia Farms, Elmhurst Milked Direct, SunOpta, Döhler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legumes Plant-Based Milk Market Trends and Innovations
Enzymatic debittering and membrane filtration technologies are reshaping sensory profiles and shelf stability for legume-derived beverages. These advances are compressing the quality gap with conventional dairy while enabling cleaner label positioning.
High-pressure processing is expanding into ambient-stable legume milk categories, replacing thermal sterilization for premium chilled products. Café chains and specialty retailers in the United Kingdom are adopting these formats for oat-pea blended beverages. The technology is expanding into previously unreachable foodservice channels that demanded extended refrigerated holding periods.
REACH compliance for food-contact materials is tightening migration limits for multilayer cartons and plastic bottles used in legume milk distribution. European converters are accelerating paper-based barrier development to meet 2025 circular economy targets. Tetra pack suppliers in Germany and France are responding with fiber-dominant packaging that maintains six-month ambient shelf life.
Foodservice procurement teams are consolidating supplier relationships around dual-capability vendors offering both shelf-stable and refrigerated legume milk formats. Institutional buyers in French and German contract catering are replacing multiple single-source contracts with integrated beverage programs. This concentration is most visible in hospital and university feeding operations where menu standardization reduces operational complexity.
Legumes Plant-Based Milk Market Segmentation
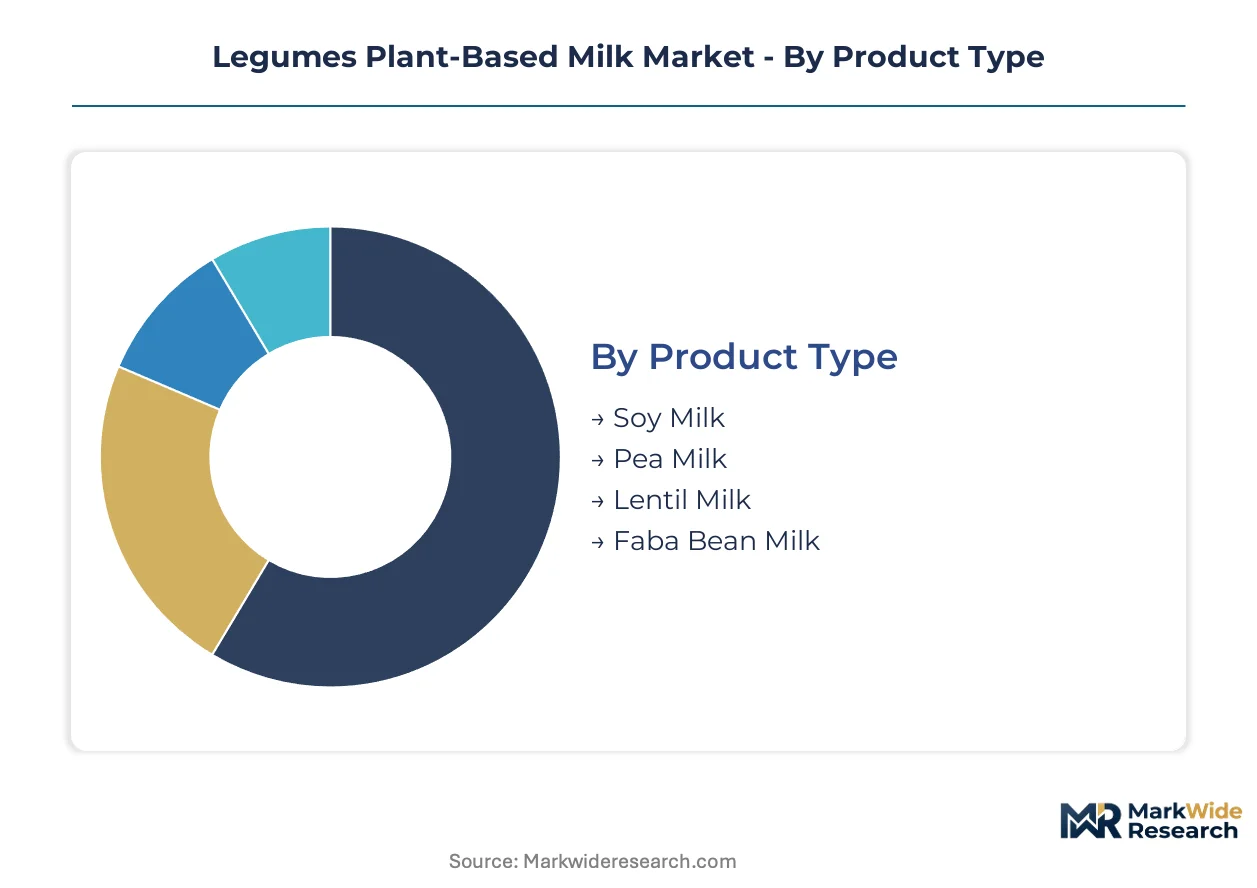
Legumes plant-based milk purchasing decisions pivot on protein functionality, shelf stability requirements, and channel accessibility. Manufacturers configure production lines around these segment intersections to capture volume in retail while building margin in foodservice and direct-to-consumer channels.
Product Type:
Protein content and allergen profile dominate buyer selection, with formulation flexibility determining end-use penetration.
- Soy Milk:Contains 3-4% protein by weight with established isoflavone research supporting cardiovascular claims. Demand concentrates in East Asian food manufacturing and German retail private-label programs where decades of processing infrastructure ensure cost parity with dairy.
- Pea Milk:Delivers 8g protein per serving with neutral flavor enabling barista-quality foam formation. French and British chilled dairy-alternative aisles are expanding facings for this segment as allergen-friendly positioning captures households avoiding both dairy and soy.
- Lentil Milk:Emerging extraction protocols yield earthy, high-fiber formulations suited to savory cooking applications.
- Faba Bean Milk:Novel food approval pathways in Europe are unlocking commercialization for this nitrogen-fixing crop with superior sustainability credentials.
Volume sits with soy milk; growth tilts toward pea milk.
Packaging Type:
Distribution economics and shelf-life requirements segment buyers between ambient-stable and refrigerated supply chains.
- Tetra Packs:Multilayer aseptic cartons deliver six-month ambient stability through ultra-high temperature processing. German and French supermarkets stock these formats in dedicated plant-based aisles where space constraints favor rectangular stacking efficiency.
- Bottles:PET and HDPE containers command refrigerated placement premiums in UK café channels where visual transparency signals freshness and enables latte art performance.
- Cartons:Gable-top refrigerated formats bridge fresh and ambient positioning for household weekly purchasing.
- Pouches:Flexible packaging reduces shipping cube for online retail fulfillment, though limited penetration in mainstream grocery.
Tetra packs anchor volume; bottles capture the steepest margin expansion trajectory.
End User:
Application specificity separates commodity protein sourcing from value-added formulation partnerships.
- Food Manufacturers:Industrial buyers specify protein content, emulsion stability, and neutral flavor for bakery, confectionery, and processed meat analog applications. German contract manufacturers are consolidating supplier relationships around dual-format vendors.
- Cafés:Barista-grade formulations with microfoam stability command formulation premiums in UK and French specialty coffee chains.
- Restaurants:Menu versatility requirements favor unsweetened, neutral bases for both sweet and savory applications.
- Households:Direct consumption drives the largest absolute volume through retail channels with flavor variety and fortification claims influencing repeat purchase.
Food manufacturers dominate procurement tonnage; cafés are expanding most quickly.
Distribution Channel:
Channel selection determines margin structure and consumer data capture capabilities for brand owners.
- Supermarkets:Multinational retailers in Germany, France, and the United Kingdom are expanding dedicated plant-based refrigerated sets. Category management negotiations favor suppliers offering both ambient and chilled formats.
- Online Retail:Subscription replenishment models for pea and soy milk build recurring revenue streams with direct consumer relationship data.
- Health Stores:Specialist retailers emphasize organic certification and clean-label positioning for premium-priced segments.
- Specialty Shops:Independent grocers and zero-waste refill stations cater to sustainability-motivated urban consumers.
Supermarkets retain volume concentration; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of legume protein concentrates clusters in Canadian prairie provinces and Ukrainian black-soil regions, while consumption tilts toward Western European retail and North American foodservice channels. This geographic split shapes trade flows and cold-chain infrastructure investment priorities.
Germany
Retailers in Berlin and Hamburg operate dedicated plant-based refrigerated sets spanning ambient Tetra packs and fresh-format bottles. The EU Green Deal mandates corporate sustainability disclosures that favor suppliers with transparent carbon labeling. Processing infrastructure in North Rhine-Westphalia handles bulk soy and pea protein imports for redistribution across Central Europe.
France
Parisian café chains and contract caterers are consolidating supplier relationships around dual-format vendors offering both shelf-stable and refrigerated legume milk. EFSA novel food assessments for faba bean entries are accelerating commercialization timelines for allergen-friendly alternatives. The Brittany region hosts pilot extraction facilities testing enzymatic debittering for reduced off-flavor profiles.
United Kingdom
Specialty coffee retailers in London and Manchester specify barista-grade pea milk formulations with microfoam stability for latte art performance. The F-Gas Regulation compresses refrigeration infrastructure upgrade cycles for chilled distribution networks. High-pressure processing adoption is expanding into ambient-stable categories previously limited to thermal sterilization.
United States
Subscription replenishment platforms for pea and soy milk are building recurring revenue streams with direct consumer data capture capabilities. FDA allergen labeling requirements shape disclosure protocols for cross-contamination risks between soy and pea processing lines. California-based beverage innovators compete through diversified packaging formats targeting café and household channels simultaneously.
Canada
Organic pea supply contracts concentrate in Saskatchewan and Manitoba prairie provinces, creating input security vulnerabilities to weather and geopolitical disruption. The country's national food regulator maintains alignment with FDA allergen disclosure standards for cross-border trade efficiency. Winnipeg and Regina host mechanical separation technology pilots improving protein recovery rates from yellow split peas.
Legumes Plant-Based Milk Market Competitive Landscape
Top-tier vendors anchor refrigerated distribution networks across multiple continents, while mid-tier specialists compete on extraction technology and packaging differentiation. The vendor base spans dairy conglomerates diversifying into plant-based portfolios, protein technology startups, and private-label manufacturers serving retail chains. Three archetypes dominate: infrastructure-heavy multinationals with cold-chain control, technology-focused innovators with proprietary extraction methods, and agile co-manufacturers capturing private-label volume. Competitive moves concentrate on portfolio diversification into blended legume-oat formulations and geographic expansion through dual-format distribution partnerships.
Among North American beverage innovators, Ripple Foods and Califia Farms exemplify technology-driven and format-differentiated positioning respectively, while Danone represents the multinational infrastructure archetype with integrated refrigerated logistics. These three occupy distinct competitive vectors without direct overlap in core capabilities.
| Leading Market Players |
|---|
| Danone |
| Ripple Foods |
| Silk |
| Alpro |
| Eden Foods |
| Califia Farms |
| Elmhurst Milked Direct |
| SunOpta |
| Döhler GmbH |
| Others |
Pricing and Supply Chain Analysis
Mechanical separation specialists in Winnipeg and Regina anchor protein recovery operations, with labor-cost differentials between Canadian prairie extraction facilities and European packaging plants driving spreads between economy Tetra pack formats and premium chilled bottle positioning.
Pricing Analysis
Margin tightening in economy-tier Tetra pack formats reflects organic pea input volatility from Saskatchewan and Manitoba contract farming regions. Three-tier pricing structure across premium barista-grade bottles, standard chilled cartons, and economy ambient cartons separates buyers by channel access and protein content certification. Cost-down pressure on standard-tier products accelerates as German and French retailers consolidate supplier relationships around dual-format vendors. Food manufacturers exhibit highest price sensitivity due to bulk procurement tonnage, while UK specialty café chains absorb premiums for microfoam-stable formulations.
Supply Chain Analysis
Single-source vulnerability sits with Canadian prairie organic pea supply and Ukrainian black-soil regions for conventional protein inputs. Extraction infrastructure draws from Saskatchewan, Manitoba, and North Rhine-Westphalia processing clusters. Raw material dependencies include yellow split peas, faba beans, and enzymatic treatment chemicals. Tariff exposure on multilayer packaging substrates threatens margin stability under REACH compliance tightening. Distribution runs through refrigerated logistics networks in Germany, France, and the United Kingdom accommodating ambient and fresh-format simultaneously.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU Green Deal sustainability disclosure mandates force subscale processors into exit or acquisition.
For Market Incumbents: To counter margin compression from dual-format vendor consolidation by German and French retailers, anchor shelf position through backward integration into Saskatchewan organic pea supply contracts and accelerate carbon labeling certification ahead of corporate sustainability reporting deadlines. Channel control through refrigerated distribution network density remains the critical defensive lever against private-label encroachment. For New Entrants and Emerging Players: Faba bean milk procurement teams in French contract catering represent the most penetrable buyer archetype given EFSA novel food approval tailwinds and nitrogen-fixing crop sustainability positioning. Target unsweetened neutral-base formulations for institutional feeding operations where menu standardization reduces supplier complexity. Direct-to-consumer subscription platforms with personalized fortification recommendations offer the clearest go-to-market angle bypassing retail slotting fee barriers. For Investors and Strategic Acquirers: Re-rating potential sits with technology-focused extraction specialists given mechanical separation yield improvements compressing unit costs for premium-positioned beverages. Five-to-ten year viability hinges on protein standardization regulatory clarity resolving dairy industry nomenclature disputes. Signal to watch: EFSA novel food assessment completion timelines for lentil and faba bean entries unlocking European retail distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Pea Supply | Saskatchewan contract farming agreements secure input volume against weather and geopolitical disruption. |
| Carbon Labeling Certification Program | Transparent lifecycle emissions data rewards shelf placement in German supermarkets under EU Green Deal. |
| Dual-Format Distribution Partnership | Simultaneous ambient Tetra pack and chilled bottle capability unlocks French hospital and university feeding contracts. |
| Enzymatic Debittering Technology Licensing | Brittany pilot facilities reduce beany off-flavor barriers for mainstream dairy consumers. |
| Subscription Replenishment Platform Launch | Direct-to-consumer data capture enables personalized formulation recommendations beyond retail intermediation. |
Research Methodology
Trade databases, EFSA novel food submission records, and EU customs filings formed the secondary backbone, supplemented by primary interviews with extraction technology directors, refrigerated logistics operators, French contract catering procurement heads, and German supermarket category managers. Bottom-up and top-down triangulation validated volume estimates against protein concentrate production capacity and retail scanner data.
Bottom-up modeling anchored forecasts to individual country consumption patterns, while top-down cross-checks applied macro protein displacement assumptions across the analysis window. Segmentation dimensions included product type, packaging format, end-user application, and distribution channel complexity. CAGRs derived from protein fortification mandate acceleration, chilled infrastructure expansion rates, and extraction yield improvement curves.
Revisions become necessary when EFSA regulatory timelines shift, organic pea supply contracts face geopolitical disruption, or dairy industry nomenclature disputes resolve unfavorably. Forecasts reflect documented assumptions about protein content standardization and sustainability disclosure enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Coconut Yogurt Market