
 Oat Milk Market | 2026-2036
Oat Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Milk Market Analysis
Specialty coffee shop supply chains are reconfiguring around oat milk as a standard offering rather than a premium upsell. Oatly Group AB leverages its barista-certified formulations to anchor premium positioning in café channels across Stockholm, London, and New York. Califia Farms competes through diversified plant-based portfolios that extend beyond oat into almond and macadamia, reducing single-crop risk. Danone SA sustains scale advantages in European retail through existing dairy distribution networks that now carry oat-based lines alongside traditional products.
Oat milk is an aqueous suspension of hydrolyzed oat starches and fibers, typically processed through enzymatic liquefaction and homogenization to achieve colloidal stability at protein levels below two percent. Its primary commercial purpose is to replicate the mouthfeel and foaming properties of dairy milk in hot beverages while eliminating lactose and reducing allergen exposure. Barista Blend formulations command the highest margin pools due to specialized fat-protein ratios engineered for steam wand performance, while Original and Unsweetened variants dominate household retail volumes through broader distribution in supermarkets and health food shops. Flavored segments remain niche but show structural growth in grab-and-go convenience formats.
The EU Green Deal and F-Gas Regulation shape European oat milk production by pressuring manufacturers to reduce refrigeration emissions across cold-chain distribution, while the FDA oversees allergen labeling and GRAS status for enzymatic processing aids in the United States. BIS and FSSAI in India are developing parallel standards for plant-based dairy alternatives as import volumes rise. Stakeholders must monitor whether emerging carbon-border adjustments reclassify oat sourcing from Nordic growers versus North American suppliers as a compliance variable rather than merely a cost decision.
Market Dynamics
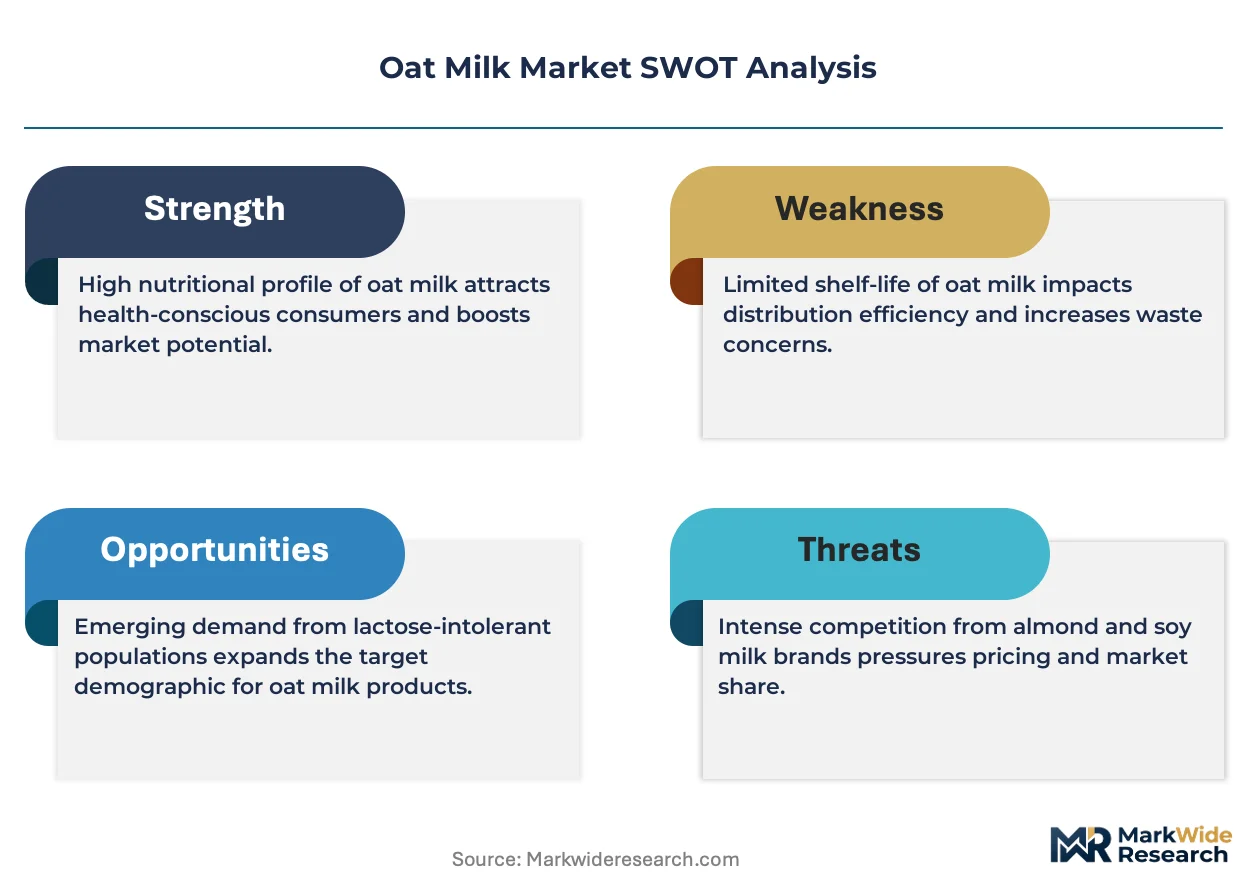
Enzymatic processing advances are compressing production cycles while EU carbon-border mechanisms are reclassifying Nordic oat sourcing from a preference to a compliance necessity, forcing supply chain reconfiguration across cold-chain distribution networks.
Growth Catalysts
- EU Green Deal incentives:Lower-carbon crop sourcing provisions reward oat cultivation over dairy equivalents, redirecting agricultural subsidies toward sustainable protein alternatives.
- Specialty café channel expansion:Stockholm, London, and New York cafés now default to oat milk, normalizing premium positioning and locking in recurring B2B volume commitments.
- Enzymatic liquefaction maturation:Improved hydrolysis protocols reduce starch retrogradation, extending shelf stability without synthetic stabilizers and opening ambient distribution channels.
Market Restraints
- Raw oat supply concentration:Premium milling-grade oat cultivation clusters in southern Sweden and Finland, exposing processors to regional weather volatility and single-source dependency.
- F-Gas Regulation compliance costs:Cold-chain refrigeration retrofits to meet EU fluorinated gas phase-down targets add capital intensity to perishable distribution networks.
- Protein content ceiling:Two percent protein maximum in finished oat milk limits nutritional parity with dairy and soy alternatives, constraining sports nutrition positioning.
Strategic Opportunities
- India import channel development:BIS and FSSAI standards finalization will unlock formal retail distribution for imported oat milk, bypassing current gray-market limitations.
- Grab-and-go convenience formats:Flavored single-serve cartons align with commuter consumption patterns in urban transit corridors across Germany and the Netherlands.
- Carbon-border arbitrage:Early certification of Nordic sourcing under emerging EU CBAM rules creates preferential access versus North American supply.
Industry Challenges
- Barista formulation talent scarcity:Steam wand performance optimization requires specialized food science expertise that outpaces current vocational training pipeline output.
- GRAS petition timelines:FDA enzymatic processing aid approvals for novel protease blends extend R&D-to-market cycles by eighteen to thirty-six months.
- Allergen cross-contamination protocols:Shared equipment with gluten-containing grains demands validated cleaning procedures that slow line changeovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Milk Market |
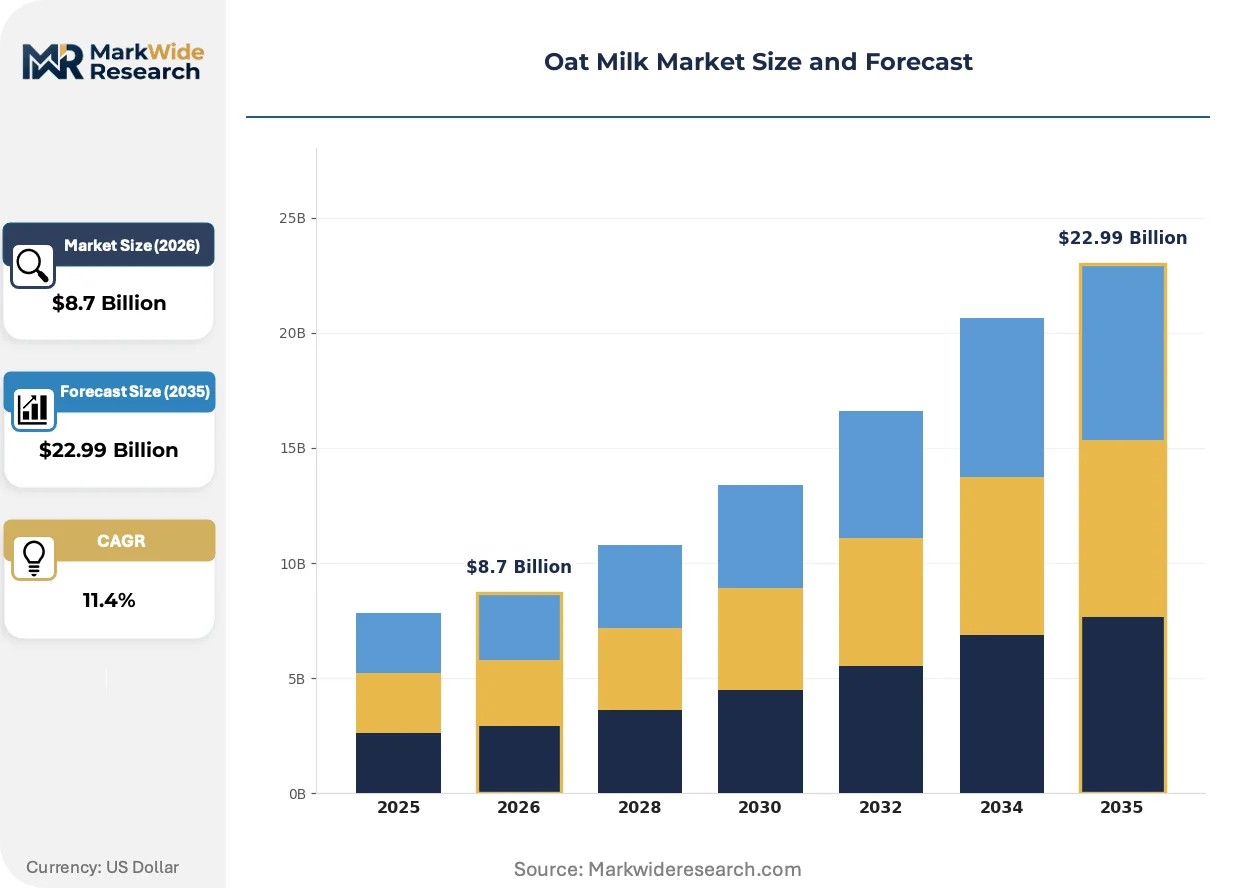
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barista Blend, Original, Flavored, Unsweetened End User: Households, Cafés, Restaurants, Food Service Packaging Type: Carton, Bottle, Tetra Pak, Can Distribution Channel: Online, Supermarkets, Specialty Stores, Health Food Shops |
| Companies Covered | Oatly Group AB, Califia Farms, Danone SA, HP Hood LLC, Chobani LLC, Campbell Soup Company, Planet Oat, Pacific Foods, Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Milk Market Emerging Trajectories
Formulation science is converging with carbon accounting to redefine competitive advantage, as mouthfeel engineering and supply chain transparency become inseparable purchase criteria for institutional buyers.
High-pressure homogenization is hybridizing with ultrasonic emulsification to achieve sub-micron fat globule distribution without chemical stabilizers. Barista Blend manufacturers in Sweden and Germany are adopting these twin-unit configurations to replicate dairy foam structure. The resulting capital intensity is consolidating equipment procurement among multi-line processors.
EU F-Gas Regulation phase-down schedules are accelerating industrial refrigeration retrofits across Dutch and Danish processing facilities. Cold-chain operators face stranded asset risk in aging ammonia systems while magnetic cooling and CO2 transcritical cycles attract green bond financing. Ambient-stable UHT formulations are gaining share specifically to circumvent refrigeration dependency in southern European markets.
Café procurement committees now require documented carbon intensity per liter alongside organoleptic scoring. This dual-criteria evaluation compresses supplier shortlists to vertically integrated processors with captive Nordic oat supply. German and Austrian coffeehouse chains are piloting blockchain-tracked sourcing to satisfy corporate sustainability mandates.
Oat Milk Market Segmentation
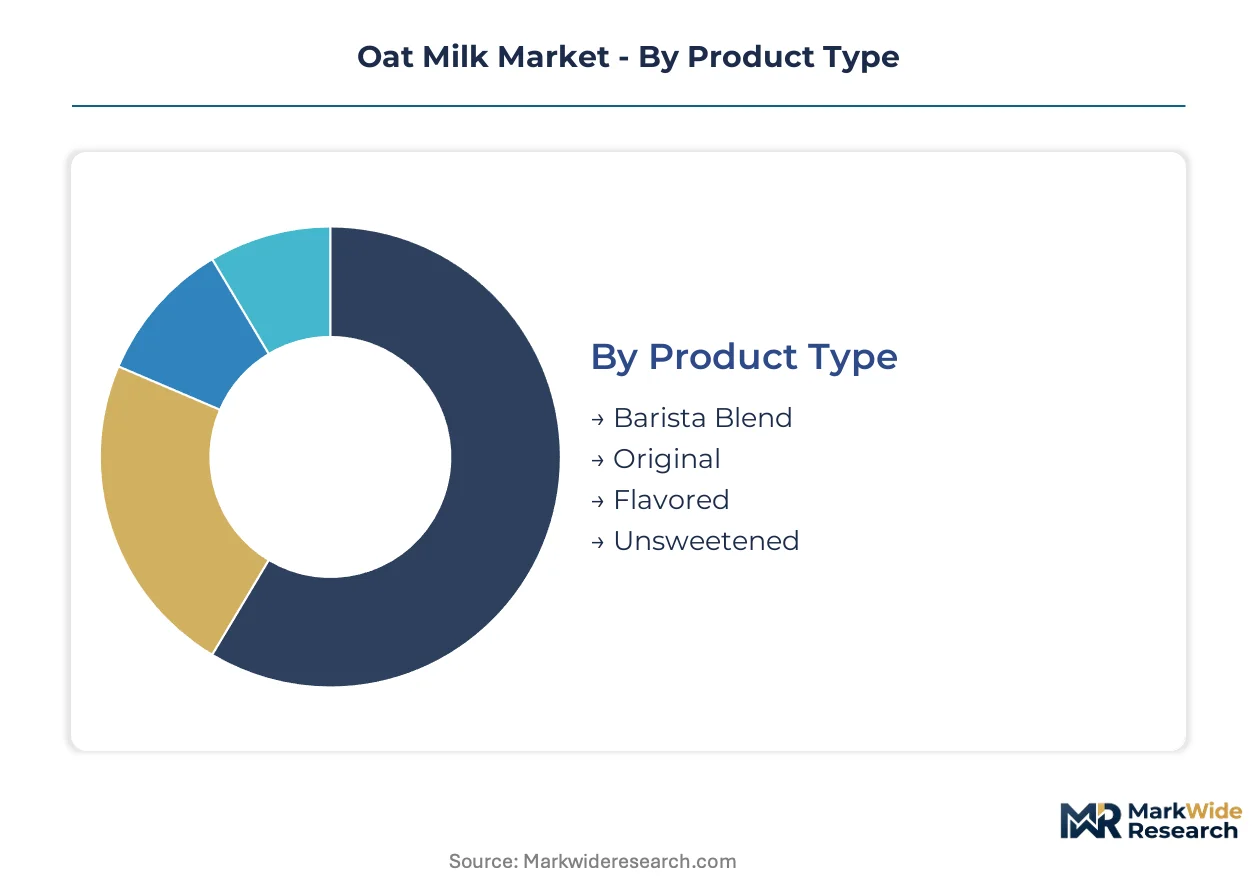
Oat milk segmentation reveals how formulation chemistry, channel economics, and consumption occasions create distinct margin pools. Each dimension carries different inventory velocities and capital requirements that reshape competitive positioning.
Product Type:
Barista Blend rotates fastest through café supply chains due to daily restocking rhythms, while Unsweetened moves slowest in retail with extended shelf life. Original and Flavored occupy intermediate velocity tiers tied to promotional calendars.
- Barista Blend:Engineered with elevated fat-protein ratios and specific viscosity profiles to withstand steam wand temperatures above 60°C without denaturing. Stockholm and London specialty cafés now specify this grade as default milk alternative, locking processors into dedicated production runs with compressed lead times.
- Original:Standard formulation balancing taste accessibility with cost efficiency, typically containing 2-3% fat and moderate sweetness from enzymatic hydrolysis. German and Dutch supermarkets move the highest volumes here, though price compression limits processor margins compared to specialized grades.
- Flavored:Vanilla, chocolate, and barista-specific variants targeting grab-and-go convenience channels in urban transit corridors.
- Unsweetened:Zero-added-sugar positioning for health-conscious households and diabetic-friendly applications, with longer production cycles due to stability challenges.
Original dominates installed base across European retail. Barista Blend is where expansion concentrates as café procurement committees harden specification requirements.
End User:
Cost tier stratification separates institutional buyers with volume contracts from fragmented household purchasing. Food Service operates on intermediate economics with menu-integrated sourcing.
- Cafés:Premium channel demanding consistent foam microstructure and supply reliability, with procurement committees now requiring carbon intensity documentation alongside organoleptic scoring. Oatly Group AB anchors this tier through barista certification programs.
- Food Service:Intermediate volume tier spanning corporate catering, university dining, and airline meal programs, where UHT stability and ambient distribution reduce refrigeration capital requirements.
- Households:Price-sensitive retail purchasers driving volume through German and Dutch supermarket chains, with Califia Farms and Danone SA competing on shelf placement and promotional depth.
- Restaurants:Menu-integrated demand concentrated in Nordic farm-to-table establishments and quick-service chains testing oat milk as default alternative.
Households anchor volume base through retail distribution density. Cafés are climbing the fastest as default-oat policies spread from Stockholm to London and New York.
Packaging Type:
Supply concentration in Nordic milling regions shapes packaging selection, with ambient-stable formats gaining share specifically to circumvent cold-chain dependency in southern European markets.
- Tetra Pak:Aseptic brick format enabling 12-month ambient shelf life without refrigeration, critical for export logistics from Swedish processors to Mediterranean markets and emerging Indian import channels.
- Carton:Gable-top refrigerated format dominating North American retail with shorter shelf life but lower per-unit packaging cost.
- Bottle:Transparent PET or glass positioning for premium refrigerated placement and visual differentiation in specialty stores.
- Can:Emerging format for single-serve convenience and on-premise dispensing systems in German commuter rail stations.
Tetra Pak dominates installed production capacity. Carton is where expansion concentrates as refrigerated retail networks deepen penetration.
Distribution Channel:
Customer type separation distinguishes procurement sophistication, with institutional buyers consolidating suppliers while health food shops fragment across regional preferences.
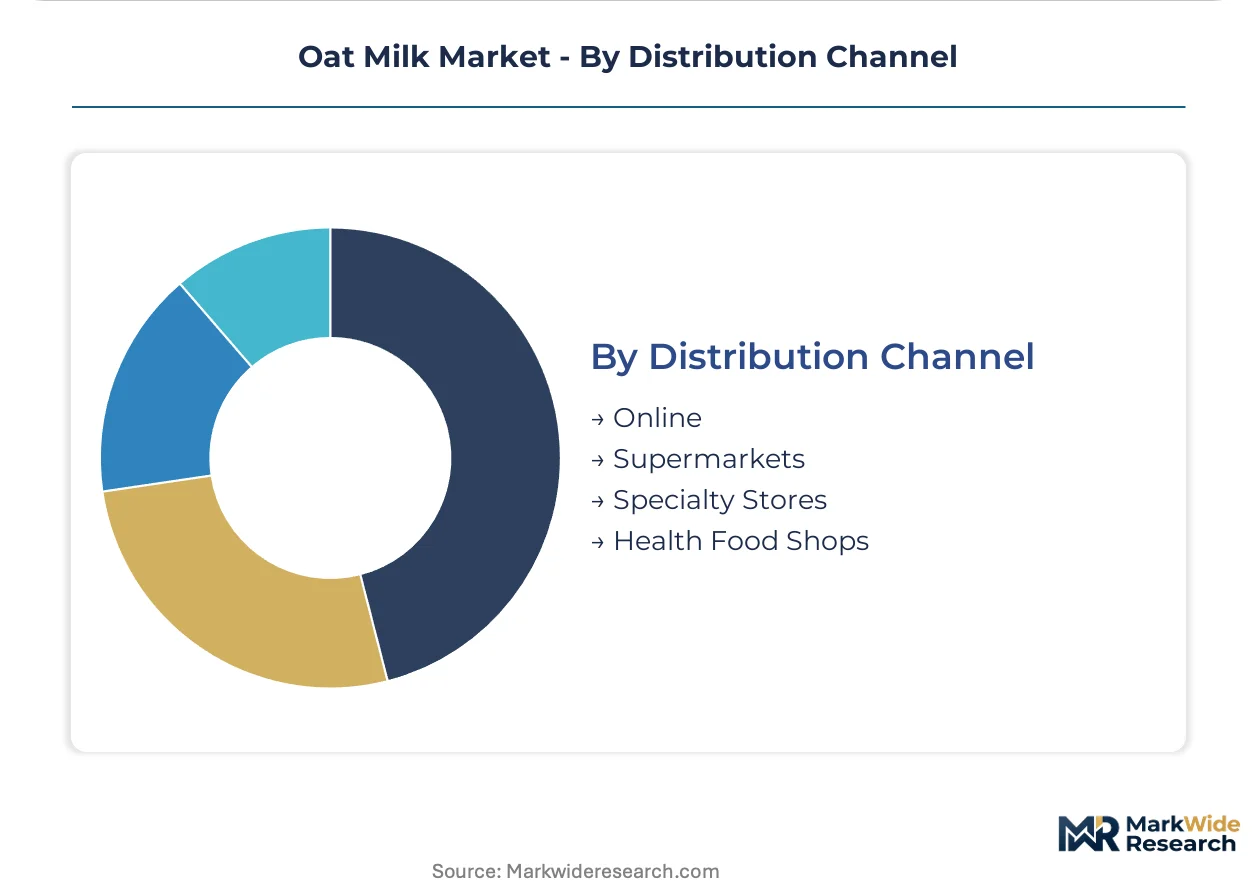
- Supermarkets:Mass retail channel where Danone SA leverages existing dairy distribution networks for shelf placement alongside traditional milk, with promotional calendars driving volume spikes in German and Dutch markets.
- Specialty Stores:Curated assortment channel emphasizing organic certification and local sourcing narratives, particularly strong in Swedish and Finnish markets with domestic oat cultivation proximity.
- Online:Direct-to-consumer and platform-based sales enabling subscription models and bulk purchasing for households with consistent consumption patterns.
- Health Food Shops:Fragmented independent retail channel prioritizing clean-label positioning and allergen-free claims, with slower inventory turns than mainstream retail.
Supermarkets anchor volume throughput. Specialty Stores are gaining share fastest as organic and carbon-certified positioning commands price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish processors command price premiums of 15-20% over North American suppliers due to carbon-certified sourcing and established barista-channel relationships. German retail chains absorb volume at compressed margins. Indian import channels remain informal pending regulatory clarity.
Sweden
Per-capita oat milk consumption exceeds all developed markets, with Stockholm cafés defaulting to oat-based alternatives and locking processors into dedicated production runs. The EU Green Deal's sustainable agriculture provisions direct subsidy flows toward domestic oat cultivation. Southern Sweden's milling-grade oat belt anchors premium supply for Oatly Group AB and competing processors.
Germany
Supermarket chains move the highest retail volumes in Europe, though promotional calendars compress processor margins compared to specialized grades. The F-Gas Regulation accelerates industrial refrigeration retrofits across Dutch and Danish processing facilities serving German distribution. Berlin and Hamburg coffeehouse chains pilot blockchain-tracked sourcing to satisfy corporate sustainability mandates.
United States
Specialty cafés in New York now specify barista-grade formulations as default, normalizing premium positioning and recurring B2B volume commitments. The FDA oversees allergen labeling and GRAS status for enzymatic processing aids, extending R&D-to-market cycles. California-based processors compete through diversified plant-based portfolios extending beyond oat into almond and macadamia.
United Kingdom
London cafés replicate Stockholm's default-oat policies, driving fastest channel expansion outside Nordic markets. REACH compliance shapes enzymatic processing aid selection for processors serving British retail. Scottish oat cultivation is expanding to reduce import dependency from Swedish suppliers.
India
Gray-market import volumes are rising ahead of formal regulatory frameworks, with urban consumers in Mumbai and Delhi driving initial demand. BIS and FSSAI are developing parallel standards for plant-based dairy alternatives that will unlock formal retail distribution. Tetra Pak aseptic formats are critical for export logistics from Swedish processors to emerging Indian channels.
Oat Milk Market Vendor Landscape
Specialist oat milk pure-players and diversified dairy conglomerates split the market along channel-specific lines, with the former anchoring café procurement and the latter dominating retail shelf placement. Three archetypes dominate: Nordic-origin specialists with barista certification programs, North American plant-based portfolio diversifiers, and European dairy incumbents leveraging existing cold-chain distribution. Consolidation is accelerating through strategic partnerships between equipment manufacturers and processors, alongside backward integration into captive Nordic oat supply.
Among Nordic-origin specialists, Oatly Group AB exemplifies the barista-channel archetype through its Stockholm roots and café certification infrastructure. Califia Farms represents the diversified portfolio approach, with geographic signaling in its name anchoring North American market development. Danone SA occupies the incumbent dairy position, leveraging European distribution networks built for traditional milk to carry oat-based lines alongside core products.
| Leading Market Players |
|---|
| Oatly Group AB |
| Califia Farms |
| Danone SA |
| HP Hood LLC |
| Chobani LLC |
| Campbell Soup Company |
| Planet Oat |
| Pacific Foods |
| Hain Celestial Group |
| Others |
Supply Flow & Price Mechanics
Baltic Sea container routes from southern Swedish milling hubs to Rotterdam and Hamburg transmit freight cost volatility directly into processor margins, compressing the customization-premium spread between barista-certified formulations and standard retail grades while amplifying price differentiation between Nordic carbon-certified supply and North American alternatives.
Pricing Analysis
The customization-premium spread between barista-grade formulations and standard retail variants spans three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from promotional depth in German supermarket chains, where Danone SA and Califia Farms compete on shelf placement. Household retail purchasers show highest price sensitivity, while café procurement committees prioritize foam performance and carbon intensity documentation over per-liter cost.
Supply Chain Analysis
Tetra Pak and SIG Combibloc hold dominant contract-manufacturing capacity for aseptic filling lines serving oat milk processors. Geographic supply concentration centers on Sweden, Finland, and Denmark for premium milling-grade oats, with enzymatic processing aids and barrier packaging films as critical input dependencies. Single-source vulnerability in Nordic oat cultivation exposes processors to regional weather volatility. Distribution runs through dedicated cold-chain networks for refrigerated cartons and ambient logistics for Tetra Pak formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists in this market as café procurement committees splinter supplier shortlists between carbon-certified Nordic specialists and diversified portfolio players, creating niche entry points for regional formulators with barista-channel relationships.
For Market Incumbents: Insulate barista-channel positioning through backward integration into captive Nordic oat supply and accelerated certification under emerging EU CBAM rules. Threat substitution from almond and macadamia alternatives demands formulation R&D investment in foam stability. Channel control via exclusive equipment partnerships with café chains represents the priority defensive lever. For New Entrants and Emerging Players: Indian import channel development pending BIS and FSSAI standards finalization offers the most penetrable white-space target, with Tetra Pak aseptic formats enabling export logistics from established processors. Grab-and-go convenience formats in German commuter rail stations provide secondary entry angle. Go-to-market execution should prioritize direct relationships with urban café chains over supermarket slotting fees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated processors with captive Nordic oat supply and established barista certification infrastructure. Long-term viability over a five-to-ten year window rests on carbon-border compliance advantages and enzymatic processing IP portfolios. Watch for FDA GRAS petition approvals for novel protease blends as inflection indicator for R&D-to-market cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Oat Supply | Captive sourcing secures carbon-certified raw material access under EU CBAM rules. |
| Barista Certification Program Expansion | Oatly Group AB's channel relationships lock processors into recurring B2B volume commitments. |
| Ambient-Stable UHT Formulation Development | Circumvents F-Gas Regulation compliance costs in southern European cold-chain distribution. |
| Blockchain-Tracked Sourcing Pilot | German coffeehouse chains satisfy corporate sustainability mandates through documented carbon intensity. |
| India Import Channel Preparation | Tetra Pak logistics readiness positions Swedish processors for BIS and FSSAI standards unlock. |
Methodological Framework
A spread of perspectives from café procurement managers, enzymatic processing engineers, Nordic oat mill operators, and EU regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, EFSA guidance documents, F-Gas Regulation implementation reports, and SEC filings from publicly traded processors. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation dimensions spanning product type, end-user channel, packaging format, and distribution route. CAGRs were derived from fitted growth curves applied to base-year estimates, with enzymatic liquefaction maturation timelines and EU carbon-border mechanism phase-in schedules as industry-specific forecast inputs over the projection horizon.
Practitioners should monitor FDA GRAS petition timelines, Nordic oat harvest yields, and EU CBAM certification rollout for early signals requiring forecast revision. Cross-checking against EIA agricultural commodity price benchmarks and European cold-chain logistics indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
Germany Dairy Alternatives Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Soy Milk Market