
 Saudi Arabia Dairy Alternatives Market | 2026-2036
Saudi Arabia Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Dairy Alternatives Market Insights
Precision fermentation and enzymatic processing is reshaping how Saudi manufacturers replicate dairy mouthfeel and protein profiles in oat and almond bases. Koita Milk leverages its Italian supply partnerships to sustain premium positioning in Gulf retail channels. Blue Diamond Growers anchors its regional presence through bulk ingredient supply to Saudi foodservice operators. Oatly Group AB differentiates via barista-grade formulations that dominate specialty coffee partnerships in Riyadh and Jeddah.
Dairy alternatives comprise plant-derived beverages and ingredients formulated to replicate the functional and sensory properties of cow milk through mechanical milling, enzymatic hydrolysis, and homogenization, typically achieving protein contents between one and eight grams per serving depending on source material. These products serve lactose-intolerant consumers, vegan populations, and flexitarian households seeking cholesterol-free options for direct consumption and recipe integration. Almond milk occupies the mature volume position among product types, while oat milk captures the fastest growth trajectory driven by frothability advantages in café applications. Distribution through supermarkets generates the largest revenue pool, though online retail channels exhibit the steepest expansion curve as subscription models penetrate health-conscious segments.
SFDA nutritional labeling mandates and SASO food product standards govern ingredient disclosure and health claim verification for all plant-based beverages sold in the Kingdom. The Saudi Food and Drug Authority's tightening scrutiny on protein content declarations and allergen warnings is forcing reformulation investments and third-party certification adoption. Halal certification requirements from SFDA-aligned bodies further filter which international suppliers qualify for import authorization. Stakeholders must monitor evolving enforcement patterns around front-of-pack labeling and anticipate how forthcoming sustainability disclosure rules from the Saudi Standards, Metrology and Quality Organization will reshape supplier qualification criteria.
Market Dynamics
SFDA nutritional labeling mandates and SASO food product standards are compressing formulation timelines as manufacturers race to comply with protein content verification and allergen disclosure rules before enforcement windows tighten.
Growth Catalysts
- Oat milk frothability:Barista-grade formulations from European suppliers are displacing almond milk in Riyadh and Jeddah specialty coffee chains, creating pull-through demand for home consumption.
- SFDA Halal certification alignment:Streamlined import authorization for SFDA-aligned certifying bodies is accelerating product registration timelines for international suppliers.
- Enzymatic hydrolysis:Local manufacturers are deploying precision fermentation to replicate dairy mouthfeel in oat bases, narrowing sensory gaps with conventional milk.
Market Restraints
- Almond input cost volatility:California drought cycles and water pricing spikes transmit directly into Saudi retail pricing, compressing margins for almond-dominant portfolios.
- European supply concentration:Premium oat milk formulations depend on Italian and Swedish processing capacity, exposing distributors to freight cost surges and currency fluctuation.
- Protein content technical ceilings:Plant bases without enzymatic fortification stall at sub-optimal protein levels, limiting appeal to fitness-oriented consumers seeking post-workout recovery beverages.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar retail channels carry limited SKUs versus Riyadh and Jeddah, presenting first-mover shelf space for barista-grade entrants.
- Subscription channel innovation:Direct-to-consumer models with automated replenishment are capturing health-conscious households in gated compounds, bypassing supermarket margin stacking.
- SASO sustainability disclosure rules:Forthcoming carbon footprint labeling requirements will favor suppliers with verified supply chain data, creating certification-based differentiation.
Industry Challenges
- Clean-label formulation skill scarcity:Food technologists capable of balancing shelf stability with minimal ingredient decks are concentrated in Jeddah, constraining Riyadh-based production scaling.
- Third-party certification capex intensity:SFDA-aligned laboratory testing and ISO 22000 implementation require six-figure investments that strain mid-cap manufacturer cash flows.
- Legacy dairy distribution integration:Plant-based SKUs must slot into existing chilled dairy logistics networks, creating temperature protocol conflicts and cross-contamination risk management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Dairy Alternatives Market |
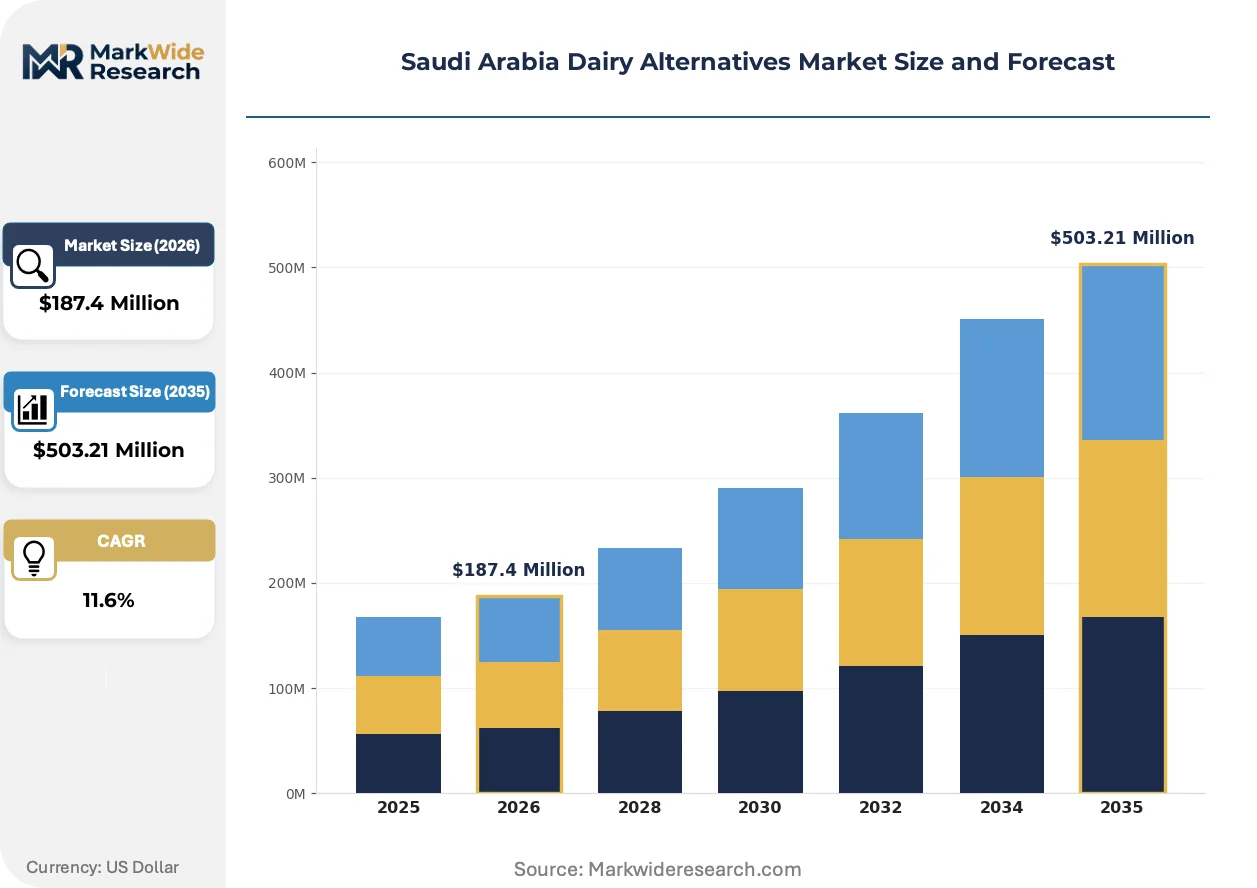
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Coconut Milk, Oat Milk End User: Retail Consumers, Foodservice Providers, Manufacturers, Health-Conscious Individuals Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops Application: Baking, Cooking, Beverages, Smoothies |
| Companies Covered | Koita Milk, Sanitarium Health and Wellbeing Company, Blue Diamond Growers, The Bridge Srl, Saudia Dairy and Foodstuff Company (SADAFCO), Britvic Plc, Oatly Group AB, Upfield Holdings BV, Danone SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Dairy Alternatives Market Trends and Innovations
Precision fermentation and enzymatic processing are compressing the sensory gap between plant bases and conventional dairy, while regulatory disclosure requirements and channel fragmentation are rewriting supplier qualification protocols.
Enzymatic hydrolysis technology is hybridizing oat protein structures to achieve dairy-equivalent mouthfeel without additive-heavy stabilizer systems. Saudi foodservice operators in Riyadh's specialty coffee segment are adopting these formulations at accelerating pace to reduce customer complaints about thin texture. The technology is hybridizing competitive positioning by enabling local manufacturers to bypass European import dependency for premium barista-grade products.
SFDA front-of-pack labeling mandates are forcing reformulation investments across all plant-based beverage categories sold in the Kingdom. The regulation's protein content declaration requirements are compressing product development cycles as manufacturers await third-party laboratory verification. Almond milk portfolios face the steepest compliance burden due to naturally lower protein levels versus oat and soy alternatives.
Subscription-based replenishment models are displacing conventional supermarket stocking patterns among health-conscious consumers in Jeddah's affluent districts. Direct-to-consumer platforms with automated delivery scheduling are capturing household pantry share from hypermarket beverage aisles. This behavioral shift is most visible in compounds with high expatriate density, where English-language app interfaces and flexible payment terms accelerate adoption curves.
Saudi Arabia Dairy Alternatives Market Segmentation
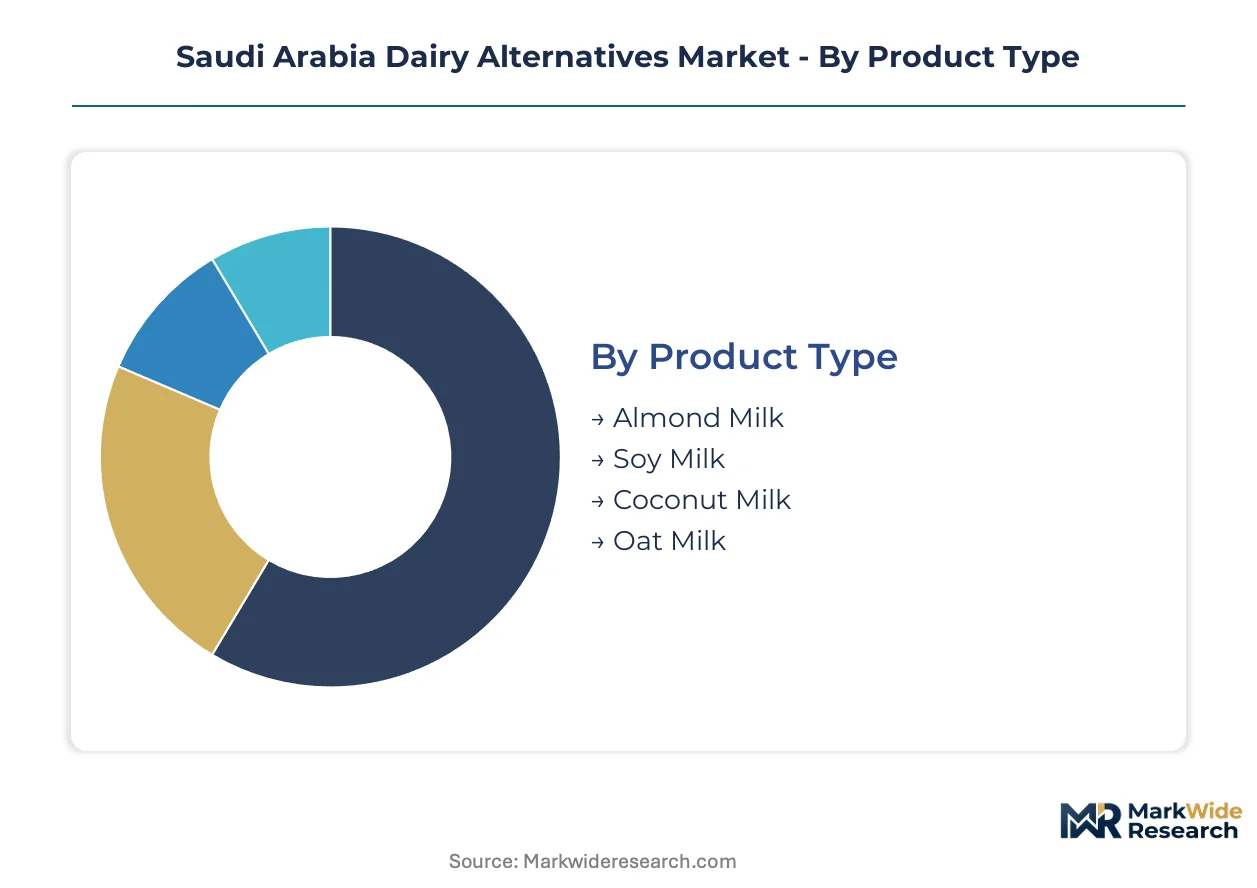
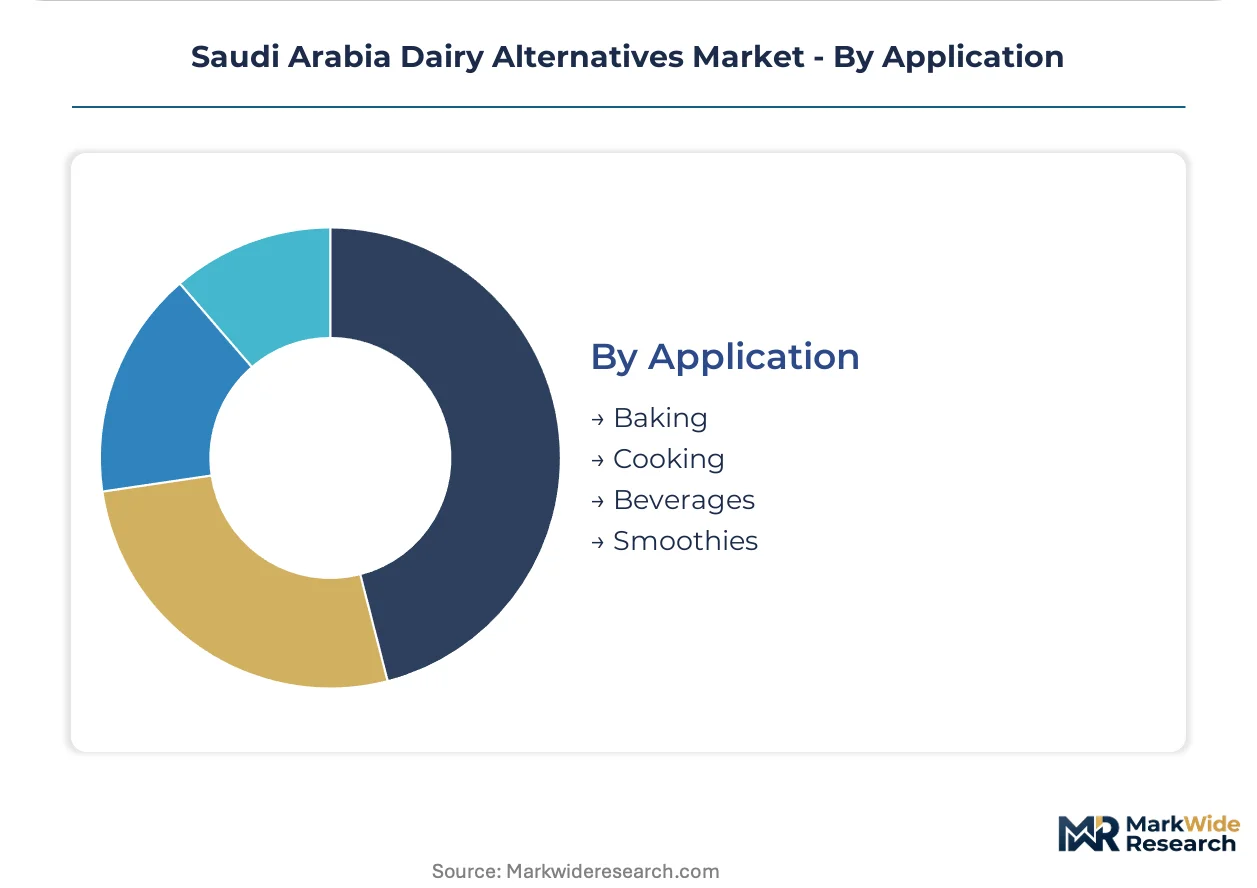
Saudi Arabia's dairy alternatives market fragments across four distinct dimensions, each mapping to different consumption occasions and procurement behaviors. Understanding these splits reveals where formulation investments concentrate versus where channel expansion delivers disproportionate returns.
Product Type:
Formulation chemistry and sensory performance divide the competitive landscape, with frothability and protein content acting as the primary technical battlegrounds.
- Oat Milk:Barista-grade enzymatic hydrolysis delivers dairy-equivalent mouthfeel and superior foam stability for Riyadh and Jeddah specialty coffee chains. Demand concentrates among café operators seeking to reduce customer texture complaints while avoiding European import dependency.
- Almond Milk:Mature volume position sustained by household familiarity and lower price points in supermarket chilled aisles. California drought cycles transmit directly into Saudi retail pricing, compressing margins for almond-dominant portfolios.
- Soy Milk:Higher native protein content appeals to fitness-oriented consumers in Eastern Province compounds, though allergen labeling requirements complicate formulation compliance.
- Coconut Milk:Tropical flavor profile finds niche adoption in dessert applications and South Asian expatriate households, limited by saturated fat content concerns.
Established volume favors almond milk; emerging adoption favors oat milk.
End User:
Procurement authority and consumption context reshape product specifications from ingredient-grade bulk to single-serve retail formats.
- Foodservice Providers:Riyadh and Jeddah specialty coffee chains drive barista-grade formulation demand, with frothability specifications dicting supplier selection. Procurement concentrates through consolidated distributor relationships serving multi-outlet operators.
- Retail Consumers:Home consumption in Jeddah's affluent districts and Riyadh's gated compounds generates the largest revenue pool. Subscription replenishment models are displacing supermarket stocking patterns among health-conscious households.
- Health-Conscious Individuals:Cholesterol-free and lactose-intolerant positioning drives premium pricing tolerance. Fitness-oriented consumers seek post-workout recovery beverages with elevated protein content.
- Manufacturers:Ingredient-grade oat and almond bases supply Saudi food manufacturers developing plant-based yogurt and ice cream lines. Bulk procurement runs through specialized ingredient distributors with cold-chain capabilities.
Revenue concentration sits with retail consumers; steepest expansion trajectory belongs to foodservice providers.
Distribution Channel:
Physical versus digital fulfillment paths segment customers by urgency tolerance and pantry planning horizons.
- Supermarkets:Hypermarket beverage aisles in Riyadh and Jeddah generate the largest revenue pool, with chilled dairy adjacency driving impulse purchases. Temperature protocol conflicts complicate plant-based SKU integration into legacy dairy logistics networks.
- Online Retail:Direct-to-consumer platforms with automated replenishment capture health-conscious households in compounds with high expatriate density. English-language interfaces and flexible payment terms accelerate adoption curves.
- Health Food Stores:Curated SKU selection and staff consultation support premium positioning. Concentrated in Jeddah's affluent districts with limited Eastern Province presence.
- Specialty Shops:Gourmet retailers and organic-focused independents serve niche demand for imported European formulations. Higher margin tolerance offsets lower throughput velocity.
Supermarkets anchor current volume; online retail climbs the fastest.
Application:
Functional requirements from heat stability to flavor neutrality determine base selection and formulation investment priorities.
- Beverages:Direct consumption as milk replacement drives the majority of volume, with café applications demanding superior frothability. Barista-grade oat formulations are displacing almond milk in specialty coffee partnerships.
- Cooking:Sauce and soup applications require heat-stable emulsions without separation. Coconut and oat bases demonstrate superior performance versus almond under thermal stress.
- Smoothies:Protein fortification and texture blending compatibility attract fitness-oriented consumers. Enzymatic hydrolysis enables smoother mouthfeel without gritty particulate residue.
- Baking:Maillard reaction compatibility and moisture retention properties favor soy and oat bases. Almond milk's lower protein content limits structural performance in yeast-raised applications.
Beverage applications command volume share; smoothie applications gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious households in Riyadh and Jeddah drive premium oat milk adoption through specialty coffee chains and direct-to-consumer subscription models. Expatriate-heavy compounds accelerate English-language platform penetration. SFDA labeling mandates reshape formulation investments nationwide.
Riyadh
Specialty coffee chains dominate barista-grade oat milk procurement, with frothability specifications dictating supplier selection. SFDA Halal certification alignment streamlines import authorization for European formulations. The King Abdullah Financial District concentrates high-income households subscribing to automated replenishment services.
Jeddah
Affluent districts generate the strongest subscription channel penetration among health-conscious retail consumers. SASO food product standards enforce protein content verification and allergen disclosure compliance. The Red Sea coastal cluster anchors gourmet retailer presence for imported European formulations.
Eastern Province
Dammam and Khobar retail channels carry limited SKUs versus central and western regions, presenting first-mover shelf space opportunities. The country's national food regulator tightens scrutiny on front-of-pack labeling across all plant-based beverages. Industrial compounds with South Asian expatriate populations sustain niche coconut milk demand for dessert applications.
Western Region
Makkah and Madinah pilgrimage traffic creates seasonal demand spikes for shelf-stable plant-based beverages in hospitality channels. Halal certification requirements from SFDA-aligned bodies filter international supplier qualification. The Taif agricultural cluster supports emerging local oat processing investments.
NEOM Northwest
Sustainability disclosure rules from the Saudi Standards, Metrology and Quality Organization favor suppliers with verified supply chain data for future mega-project procurement. The giga-project's planned food tech hub attracts precision fermentation technology partnerships. Zero-carbon construction timelines accelerate demand for low-carbon-footprint beverage sourcing.
Saudi Arabia Dairy Alternatives Market Competitive Landscape
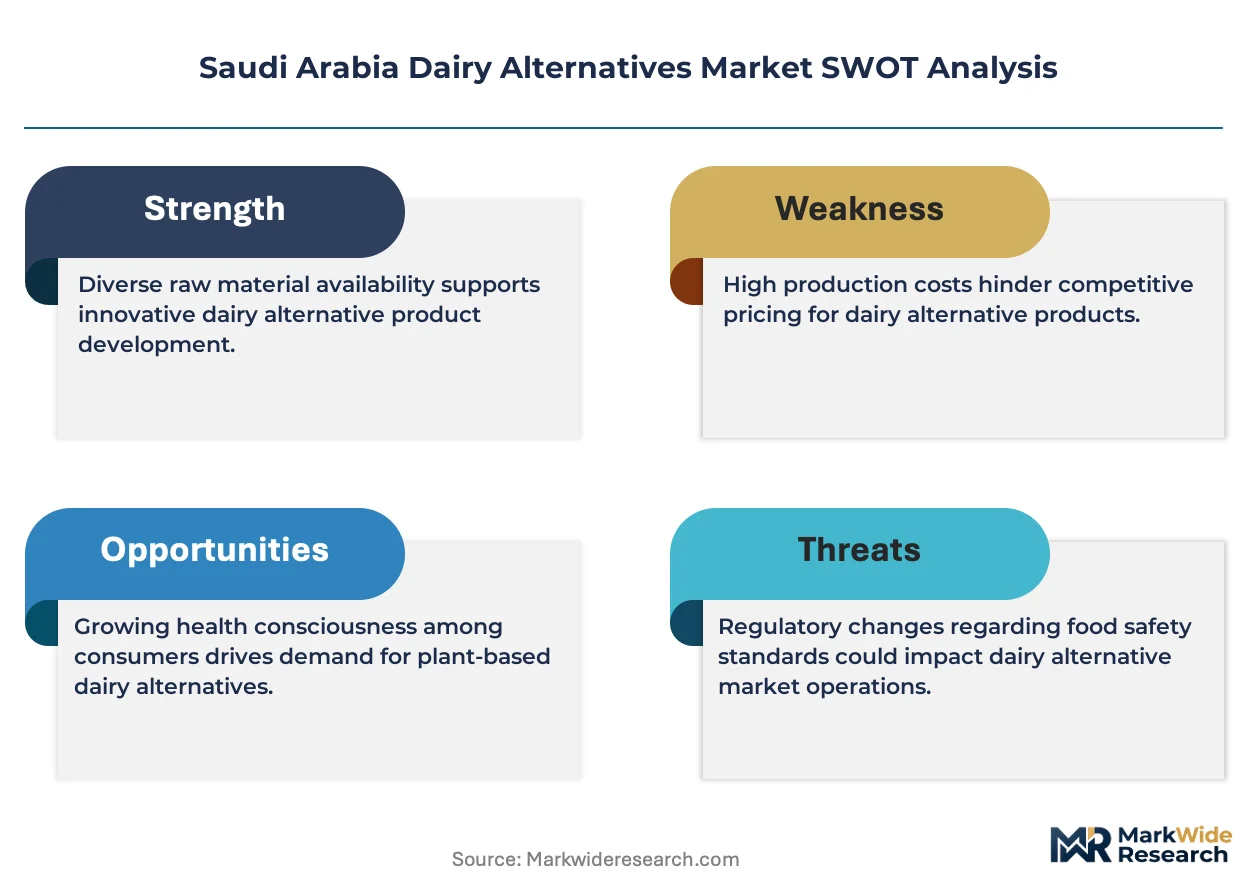
Channel-controlling players compete with product-specialist players across fragmented tiering. Supermarket beverage aisle dominance and foodservice distributor consolidation create divergent scale requirements. Strategic archetypes split between European-import-dependent premium formulators, Gulf-aligned Halal certification specialists, and local production scaling entrants. Competitive moves concentrate on strategic partnerships with coffee chain operators and portfolio diversification into enzymatically processed barista-grade lines.
Among European-origin premium formulators, Oatly Group AB and Koita Milk occupy positions exemplifying barista-grade specialization and Italian supply partnership leverage respectively. Blue Diamond Growers anchors the bulk ingredient supply archetype for foodservice operators. These three represent distinct competitive vectors: frothability-focused café partnerships, premium retail channel positioning, and commodity-scale almond base provision.
| Leading Market Players |
|---|
| Koita Milk |
| Sanitarium Health and Wellbeing Company |
| Blue Diamond Growers |
| The Bridge Srl |
| Saudia Dairy and Foodstuff Company (SADAFCO) |
| Britvic Plc |
| Oatly Group AB |
| Upfield Holdings BV |
| Danone SA |
| Others |
Pricing and Supply Chain Analysis
Italian and Swedish oat processing capacity concentration anchors premium barista-grade pricing power in Saudi Arabia's dairy alternatives market, with margin pools accumulating at the distributor tier serving Riyadh and Jeddah specialty coffee chains. California almond supply volatility transmits directly into retail shelf price instability, compressing profitability for almond-dominant portfolios while enzymatic hydrolysis investments by local manufacturers erode European import dependency.
Pricing Analysis
Cost-plus contracts with California almond indexation dominate procurement for almond milk portfolios, while oat milk pricing rests on fixed-term agreements with European processors. Three-tier pricing structure across premium barista-grade, standard retail, and economy private-label levels separates formulations by enzymatic processing intensity and SFDA certification tier. Pricing pressure stems from California drought-driven almond input cost spikes and freight rate volatility on European oat concentrate shipments. Foodservice operators in specialty coffee chains exhibit lowest price sensitivity due to frothability specifications, while supermarket retail consumers demonstrate highest elasticity to shelf price movements.
Supply Chain Analysis
Supply-chain finance facilities from Saudi distributor networks extend payment terms to 90-120 days for mid-cap manufacturers, easing working capital strain during SFDA registration periods. Raw material sourcing draws from Italian and Swedish oat processing hubs, California almond orchards, and emerging local oat cultivation trials in Taif. Single-source vulnerability concentrates in European barista-grade oat concentrate supply, with limited qualified alternative processors. Distribution runs through chilled dairy logistics networks controlled by legacy dairy distributors, creating temperature protocol conflicts and cross-contamination risk management complexity for plant-based SKU integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's dairy alternatives market fragments across formulation technology tiers and regional channel penetration gaps, with subscription channel innovation and Eastern Province underpenetration creating distinct niche opportunities for specialized entrants.
For Market Incumbents: Insulate barista-grade positioning through captive enzymatic hydrolysis capability investments in Riyadh production facilities, reducing European oat concentrate import dependency. Secure exclusive distributor relationships with expanding specialty coffee chains before local manufacturers achieve sensory parity. SFDA protein content verification tightening threatens almond-dominant portfolios; accelerate oat base portfolio diversification to preempt compliance-driven share erosion. For New Entrants and Emerging Players: Establish a beachhead in Dammam and Khobar retail channels where limited SKU availability creates first-mover shelf space advantages before incumbent portfolio expansion. Target subscription replenishment models in Jeddah's affluent gated compounds, leveraging English-language app interfaces and flexible payment terms to bypass supermarket margin stacking. Lead with barista-grade oat formulations featuring local enzymatic processing partnerships to differentiate from European-import-dependent competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Gulf distributor networks holding exclusive foodservice relationships but lacking formulation technology capabilities. Five-to-ten year viability hinges on enzymatic processing localization and SFDA certification infrastructure ownership. Monitor Saudi Standards, Metrology and Quality Organization sustainability disclosure rule implementation timing as inflection indicator for supply chain data verification premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Localization | Reduces European oat concentrate import dependency for Riyadh manufacturers seeking barista-grade sensory parity. |
| SFDA Halal Certification Infrastructure | Accelerates import authorization timelines for international suppliers aligned with Saudi Food and Drug Authority protocols. |
| Subscription Channel Platform Buildout | Captures health-conscious households in Jeddah compounds through automated replenishment bypassing supermarket margins. |
| Eastern Province Distribution Expansion | Secures first-mover shelf space in Dammam and Khobar retail channels with limited incumbent SKU presence. |
| Precision Fermentation Partnership | Attracts NEOM food tech hub investment for zero-carbon beverage sourcing aligned with giga-project sustainability mandates. |
Research Methodology
Initial hypotheses were tested against primary input from foodservice procurement managers, retail category buyers, food technology R&D directors, and SFDA regulatory affairs specialists and refined through secondary validation. Primary interviews combined with SFDA regulatory filings, SASO food product standards documentation, Saudi customs trade data, and European processor capacity disclosures. Bottom-up volume modeling across product type, end user, distribution channel, and application segments triangulated against top-down market sizing from trade flow analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type chemistry, end user procurement authority, physical versus digital fulfillment paths, and heat stability requirements. CAGRs derived from weighted average of historical trajectory and forward-looking capacity expansion announcements, incorporating oat milk frothability adoption curves and almond input cost volatility assumptions.
Sensitivities concentrate around California drought cycle intensity, European freight rate volatility, and SFDA enforcement timing on front-of-pack protein content declarations. Forecasts reflect documented assumptions on enzymatic hydrolysis localization pace and subscription channel penetration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
On-The-Go Yoghurt Market