
 Non-Dairy Creamer Powder Market | 2026-2036
Non-Dairy Creamer Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Dairy Creamer Powder Market Analytics
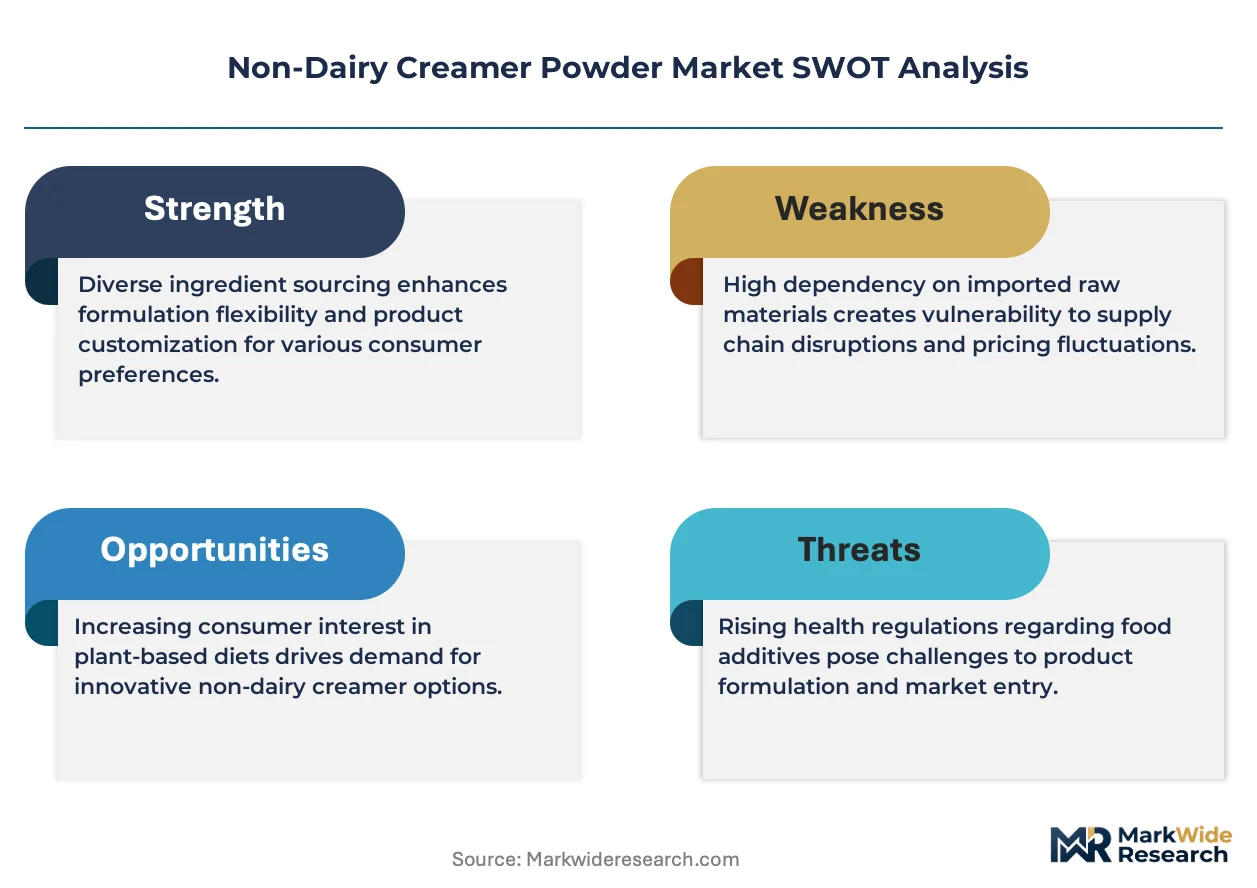
Clean-label specification tiers is redrawing competitive boundaries in non-dairy creamer powders. Nestlé S.A. leverages its global dairy-alternative R&D infrastructure to anchor premium positioning. Kerry Group plc specializes in customized fat-protein emulsion systems for food service clients. Cargill Incorporated controls upstream plant-oil supply chains that sustain cost advantages across standard-grade segments.
Non-dairy creamer powder comprises a spray-dried or agglomerated blend of hydrogenated or interesterified vegetable oils, corn syrup solids, sodium caseinate, and emulsifying salts designed to mimic dairy cream functionality in hot beverages and processed foods. The powder typically contains 35-50% fat content by weight and achieves dispersibility through lecithin or mono-diglyceride stabilization. Application segmentation shows food service commanding the largest volume share as restaurant chains standardize across outlets, while bakery products represent the fastest-expanding category as manufacturers reformulate frostings and fillings to reduce dairy dependency. Distribution through wholesale channels captures the dominant margin pool by securing multi-year supply contracts with institutional buyers.
The FDA governs ingredient disclosure and fat characterization standards for non-dairy creamers sold in the United States, while the USDA oversees school nutrition programs that influence institutional procurement specifications. EFSA and national regulators across Europe enforce allergen labeling for sodium caseinate content despite the "non-dairy" designation, creating formulation complexity for exporters. Stakeholders must monitor evolving plant-based fat health claims litigation and prepare for potential FDA guidance on "dairy-free" terminology that could force label revisions across existing product lines.
Market Dynamics
The FDA's updated labeling requirements for plant-based fat sources are forcing reformulation across existing product lines while coffee shop chains accelerate powdered creamer adoption in specialty beverage programs.
Growth Catalysts
- Food Service Standardization:Restaurant chains in the United States are mandating powdered creamer specifications across outlet networks to ensure beverage consistency. Bulk procurement volumes from institutional buyers are compressing per-unit costs.
- REACH Compliance Export Window:European manufacturers reformulating to eliminate hydrogenated oils ahead of EFSA scrutiny are creating demand for alternative emulsion systems. Kerry Group and similar suppliers are capturing this specification upgrade cycle.
- Spray-Drying Efficiency Gains:Agglomeration technology improvements are reducing energy input per kilogram of finished powder. Processing plants in Malaysia and Indonesia are achieving throughput rates that undercut legacy equipment economics.
Market Restraints
- Palm Oil Price Volatility:Hydrogenated palm kernel and coconut oil inputs comprise 35-50% of finished powder weight. Malaysian and Indonesian supply disruptions transmit directly to margin compression for standard-grade producers.
- Sodium Caseinate Allergen Friction:EFSA and national European regulators enforce milk allergen labeling despite "non-dairy" positioning. Export formulations must either absorb caseinate substitution costs or forfeit shelf space.
- Oat Milk Concentrate Substitution:Liquid oat creamers in refrigerated distribution are capturing home and office consumption occasions. Powdered formats lack equivalent mouthfeel without fat content increases that trigger nutritional objections.
Strategic Opportunities
- Bakery Application Expansion:Frosting and filling manufacturers are reformulating to reduce dairy dependency. Powdered creamer fat-protein emulsions achieve stability in high-sugar matrices where liquid alternatives fail.
- USDA School Nutrition Channel:The USDA oversees institutional procurement specifications that influence K-12 food service buying. Clean-label powder formulations that meet sodium and saturated fat thresholds unlock multi-year district contracts.
- Direct-to-Consumer Subscription Models:Specialty coffee enthusiasts are purchasing barista-format powders for home espresso systems. E-commerce channels bypass food service distributor markups while capturing premium pricing.
Industry Challenges
- Emulsion Chemistry Talent Scarcity:Formulation expertise in fat-protein stabilization and spray-drying parameter optimization is concentrating among retiring cohorts. Food science programs are producing fewer specialists in dried dairy analogs.
- Clean-Label Certification Timelines:Non-GMO Project and organic certifications require 12-18 month validation cycles. Product development pipelines must front-load regulatory documentation to hit seasonal launch windows.
- Legacy Equipment Retrofit Costs:Existing spray-drying towers require agglomeration capability additions to produce instant-dispersing powders. Capital allocation decisions are complicated by uncertain payback periods against alternative ingredient investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Dairy Creamer Powder Market |
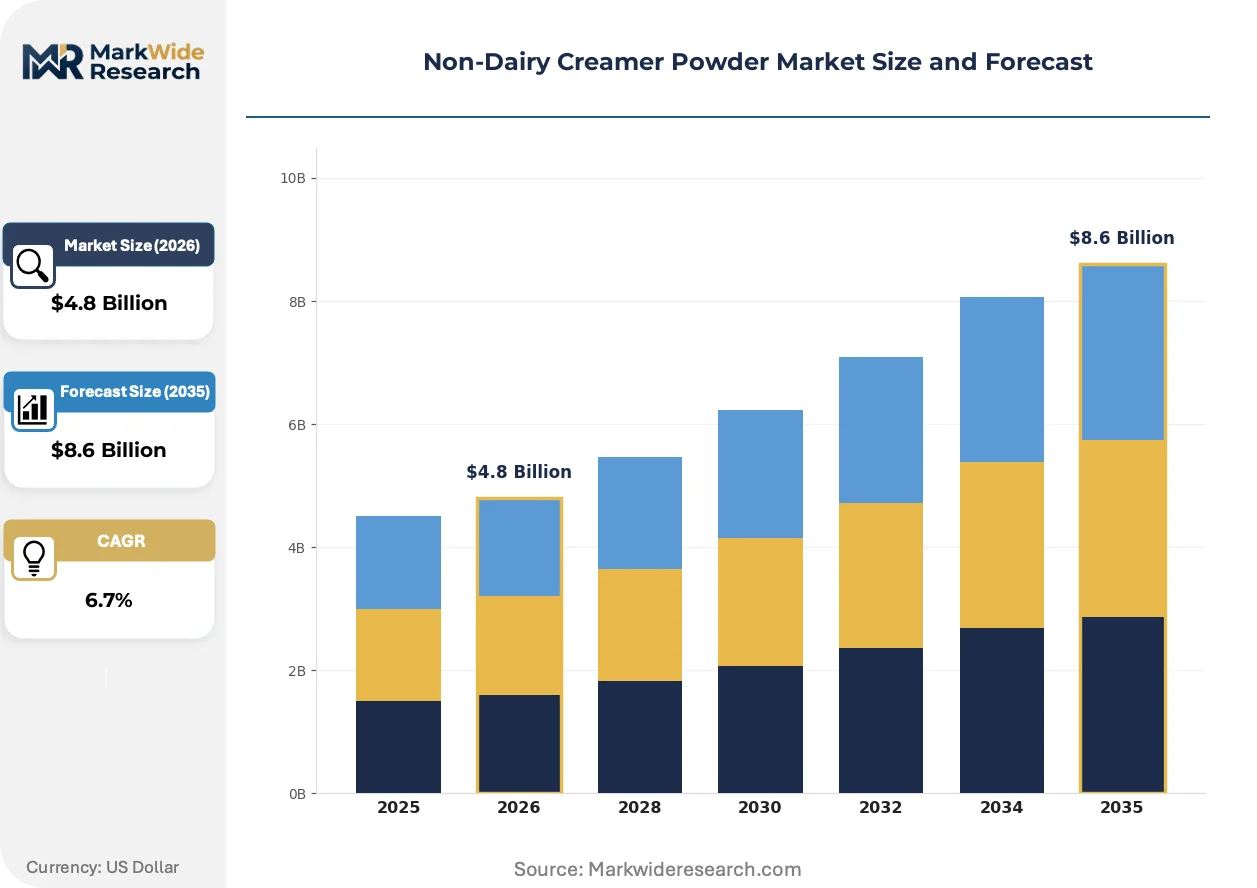
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Concentrate, Instant Application: Food Service, Bakery Products, Beverages, Confectionery End User: Restaurants, Coffee Shops, Households, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Wholesale, Convenience Stores |
| Companies Covered | Royal FrieslandCampina N.V., Land O'Lakes Inc., Nestlé S.A., Tree House Foods Inc., Rich Products Corporation, Cargill Incorporated, Kerry Group plc, Balchem Corporation, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Dairy Creamer Powder Market Evolving Landscape
Formulation science and procurement models are diverging simultaneously. Manufacturers are pursuing divergent paths on fat source transparency while buyers restructure how they source and specify powdered creamer inputs.
Microencapsulation technology for volatile flavor compounds is miniaturizing protection architectures around fat droplets. Coffee roasters and private-label brands are adopting these systems to extend shelf stability without synthetic antioxidants. The structural consequence is compressing the gap between clean-label and conventional product performance, enabling premium positioning without functional sacrifice.
EFSA's evolving stance on processed plant fat health claims is reshaping permissible marketing language across European markets. Manufacturers are preemptively reformulating to interesterified rather than hydrogenated fat bases to retain "zero trans fat" positioning. Bakery and beverage premix segments are most affected, with exporters to Germany and France accelerating documentation of fat modification processes.
Specification consolidation among US food service buying cooperatives is compressing supplier rosters. Multi-unit restaurant chains are delegating ingredient selection to procurement consortiums that mandate third-party audit compliance. This concentration is most visible in the Southeast and Midwest, where district-level school nutrition programs and regional chain headquarters cluster.
Non-Dairy Creamer Powder Market Segmentation
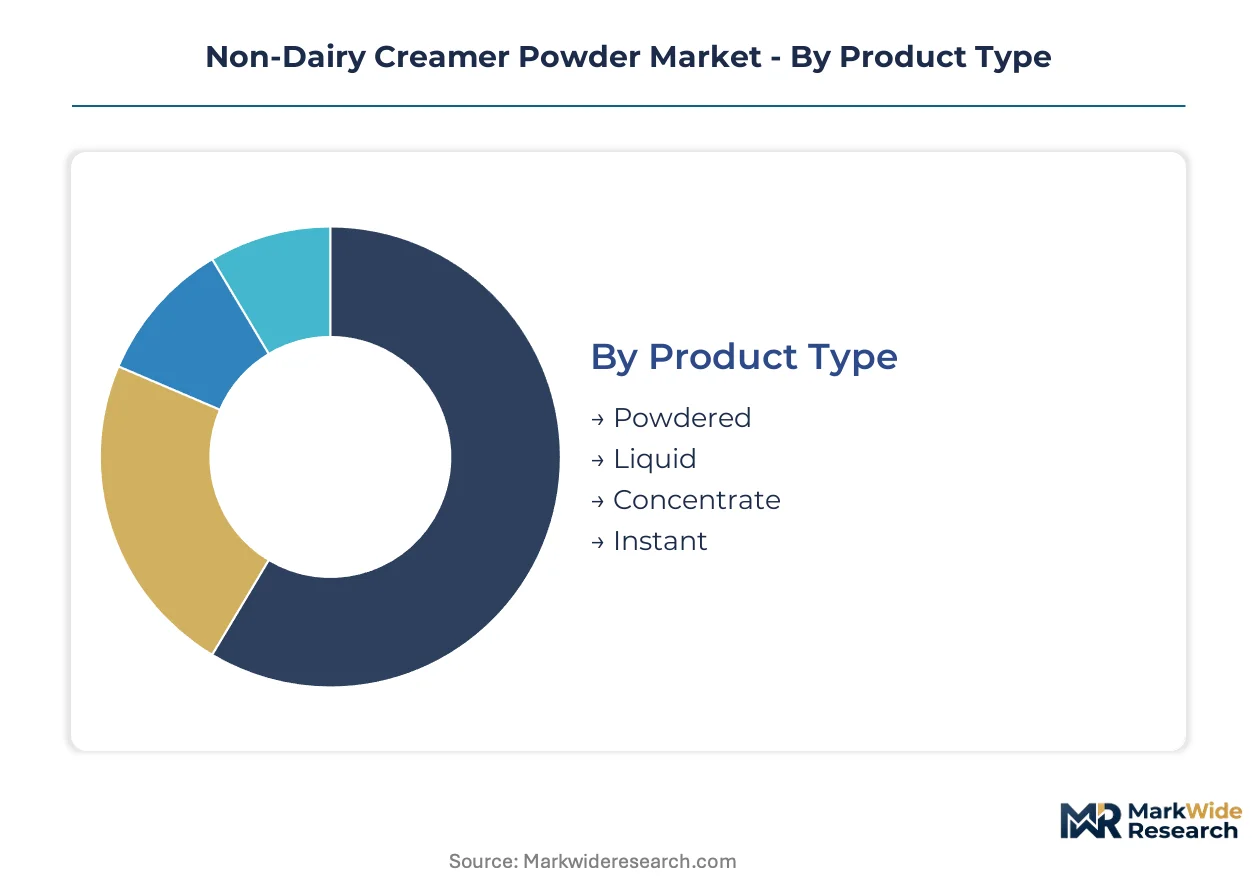
Segmentation in non-dairy creamer powders reveals how substitute threats concentrate differently across physical formats, use occasions, and procurement channels. Manufacturers must align R&D investment with the specific vulnerability profile of each segment rather than pursuing uniform reformulation strategies.
Product Type:
Liquid concentrates and refrigerated alternatives are pressuring powdered formats most aggressively in household and premium coffee shop channels, forcing powder producers to differentiate on stability and cost rather than mouthfeel parity.
- Powdered:Spray-dried or agglomerated formulations containing 35-50% vegetable oil content by weight achieve shelf stability without refrigeration. Food service operators in the United States specify these formats for back-of-house consistency across outlet networks, though sodium caseinate allergen labeling creates friction in European export markets.
- Liquid:Ready-to-pour emulsions in aseptic packaging capture convenience-oriented household consumption and specialty coffee shop front-of-house service. The format sacrifices shelf stability and shipping efficiency for immediate dispersibility without stirring.
- Concentrate:High-solids formulations requiring dilution target industrial beverage manufacturing and large-scale food service operations seeking transport cost reduction. Users must invest in blending equipment and quality control protocols.
- Instant:Agglomerated particles engineered for cold-water dispersibility serve single-serve hospitality applications and on-the-go consumption occasions. Processing requires modified spray-drying towers with fluidized bed agglomeration capability.
Powdered formats retain volume leadership across institutional procurement; instant formulations hold the steepest expansion curve as cold beverage applications multiply.
Application:
Cost tier differentiation separates commodity beverage service from value-added bakery and confectionery applications where fat-protein emulsion functionality commands specification premiums.
- Food Service:Restaurant chains and institutional feeders standardize powdered creamer specifications across outlet networks to ensure beverage consistency. Bulk procurement through distributor cooperatives compresses per-unit costs while mandating third-party audit compliance.
- Bakery Products:Frosting, filling, and dough manufacturers reformulate to reduce dairy dependency while maintaining structural stability in high-sugar matrices. Powdered creamer fat-protein emulsions achieve functionality where liquid alternatives fail, driving the fastest volume expansion among application segments.
- Beverages:Coffee, tea, and cocoa premix manufacturers specify powder formats for dry blending compatibility and extended shelf life. The segment faces direct substitution pressure from liquid oat and almond creamers in retail channels.
- Confectionery:Chocolate compound coatings and caramel applications utilize specialized high-fat powder fractions for texture modification and cost reduction against dairy butter equivalents.
Food service commands procurement volume; bakery applications are climbing the fastest as manufacturers accelerate dairy reduction targets.
End User:
Customer type determines whether procurement prioritizes unit economics, brand differentiation, or regulatory compliance in formulation specifications.
- Restaurants:Multi-unit chains delegate ingredient selection to procurement consortiums that mandate consistency across hundreds of outlets. Specifications emphasize dispersibility reliability and supply security over clean-label positioning.
- Coffee Shops:Specialty beverage programs differentiate through custom fat-protein emulsion systems and flavor microencapsulation. Chains are expanding powdered creamer adoption for back-of-house efficiency while front-of-house service experiments with liquid alternatives.
- Households:Retail purchasers in supermarkets and online channels demonstrate bifurcated behavior: price-sensitive bulk buying of standard powders versus premium positioning of organic and non-GMO certified formats.
- Food Manufacturers:Industrial buyers integrate powdered creamers into bakery premixes, beverage bases, and confectionery compounds where emulsion stability in processing conditions determines supplier selection.
Restaurants generate the largest procurement volumes; coffee shops are gaining share fastest as specialty beverage programs proliferate.
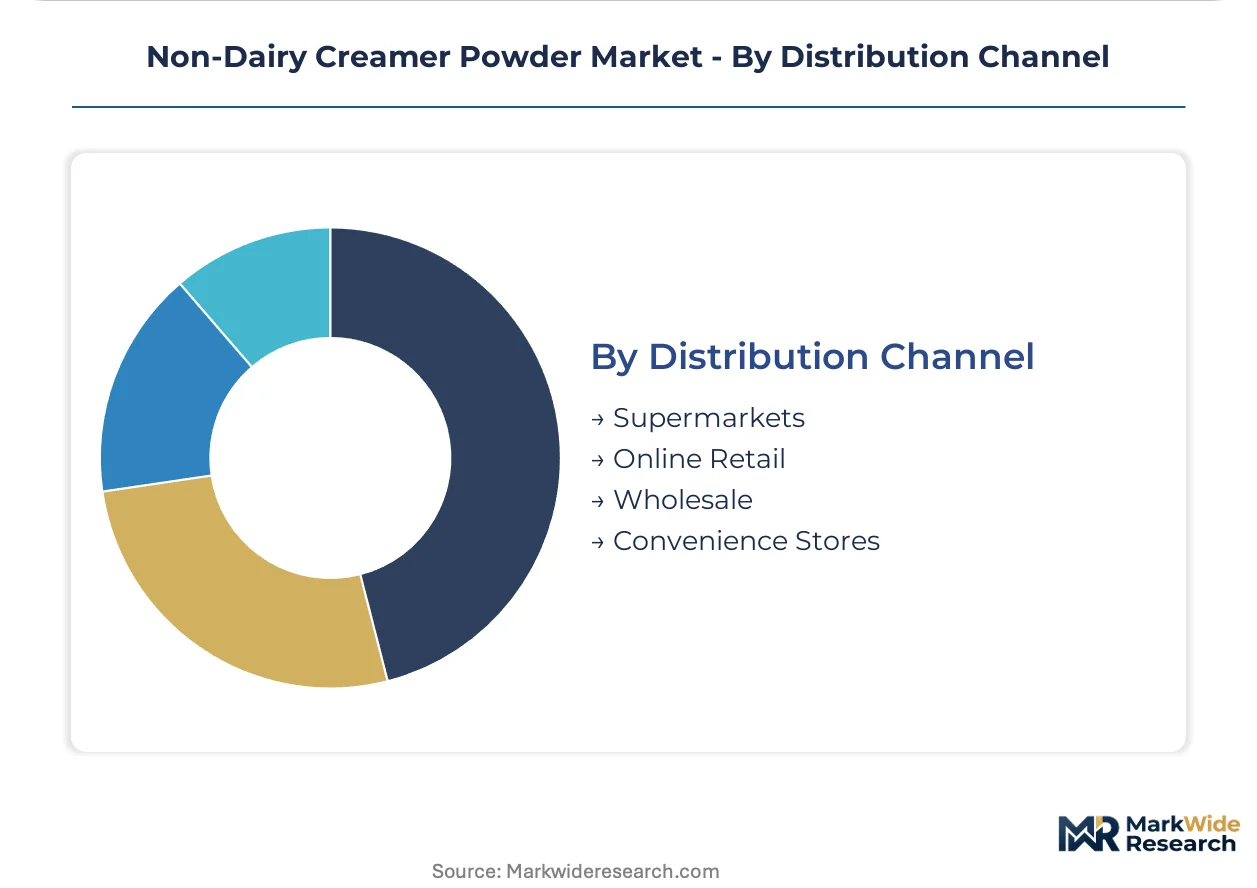
Distribution Channel:
Channel selection locks in margin structure and customer access, with wholesale institutional contracts offering volume security against retail channel volatility.
- Supermarkets:Retail shelf placement requires slotting fee investment and competes with liquid creamer refrigerator space allocation. Clean-label and organic certifications differentiate premium positioning.
- Online Retail:Direct-to-consumer subscription models bypass distributor markups and capture specialty coffee enthusiast demand for barista-format powders. E-commerce enables micro-brand entry without physical retail infrastructure.
- Wholesale:Food service distributors and buying cooperatives secure multi-year supply contracts with institutional buyers, capturing the dominant margin pool through volume concentration and logistics integration.
- Convenience Stores:Single-serve sachet formats target immediate consumption occasions with portability and portion control. The channel sacrifices margin for impulse purchase accessibility.
Wholesale channels retain procurement volume leadership; online retail holds the steepest expansion curve as subscription models penetrate specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major consuming regions. The United States maintains substantial domestic production capacity while sourcing specialized emulsion systems from European suppliers. Asian manufacturing clusters in Malaysia and Indonesia supply standard-grade powders to deficit markets in the Middle East and Africa.
United States
Food service operators drive bulk procurement volumes through distributor cooperatives. The FDA governs ingredient disclosure and fat characterization standards for plant-based creamers. Chicago and the Midwest corridor concentrate spray-drying infrastructure serving institutional buyers.
Germany
Bakery manufacturers accelerate dairy-free reformulation in frosting and filling applications. EFSA scrutiny of hydrogenated oils forces interesterified fat adoption ahead of regulatory deadlines. The North Rhine-Westphalia industrial belt hosts reformulation service providers supporting confectionery exporters.
China
Domestic coffee shop chains expand powdered creamer adoption in tier-two and tier-three cities. SAMR enforces labeling standards for plant-based fat sources in imported formulations. The Yangtze River Delta agglomerates spray-drying capacity targeting beverage premix manufacturers.
Indonesia
Palm kernel oil supply disruptions transmit directly to regional powder pricing volatility. The country's national food safety regulator monitors hydrogenation processes in export-oriented facilities. Java-based processing plants achieve throughput rates that undercut legacy equipment economics in competing origins.
Brazil
Coffee sector consolidation creates specification standardization opportunities for creamer suppliers. ANVISA regulates sodium caseinate allergen disclosure in cross-border trade. São Paulo state concentrates food service distribution infrastructure serving South American markets.
Non-Dairy Creamer Powder Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The vendor base stratifies into three capability tiers: multinational ingredient conglomerates with integrated supply chains, mid-scale emulsion technology specialists, and regional private-label converters. Strategic archetypes include upstream oil controllers, customized formulation engineers, and scale-driven commodity producers. Competitive moves concentrate on agglomeration technology licensing and backward integration into palm oil refining.
Within the multinational conglomerate tier, Nestlé S.A. and Cargill Incorporated occupy positions anchored by global procurement networks and captive vegetable oil supply. Kerry Group plc exemplifies the formulation specialist archetype, leveraging customized fat-protein emulsion capabilities to serve food service and industrial accounts. These three entities represent divergent strategic postures on clean-label positioning versus cost-engineered standard grades.
| Leading Market Players |
|---|
| Royal FrieslandCampina N.V. |
| Land O'Lakes Inc. |
| Nestlé S.A. |
| Tree House Foods Inc. |
| Rich Products Corporation |
| Cargill Incorporated |
| Kerry Group plc |
| Balchem Corporation |
| Danone S.A. |
| Others |
Value Network & Pricing Analysis
Non-GMO Project certification gates both supplier qualification and price tiering simultaneously, forcing manufacturers to front-load validation costs while enabling premium positioning against uncertified alternatives. Clean-label procurement specifications from institutional buyers concentrate purchasing power among qualified suppliers, compressing margins for standard-grade producers while rewarding certified tier premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the non-dairy creamer powder market. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified formulations from conventional powders and commodity-grade alternatives. Cost compression in standard-grade segments is intensifying because palm oil price volatility transmits directly to input costs. Food service distributors demonstrate highest price sensitivity due to volume concentration and multi-year contract pressures, while specialty coffee roasters show lowest sensitivity for microencapsulated and barista-format powders.
Supply Chain Analysis
Inventory cycles for hydrogenated vegetable oils extend lead times during Malaysian and Indonesian harvest disruptions, forcing manufacturers to carry buffer stocks that tie up working capital. Spray-drying capacity concentrates in Malaysia, Indonesia, and the United States, with Java-based plants achieving throughput advantages through agglomeration technology retrofits. Raw material dependencies rest on palm kernel oil, coconut oil, and sodium caseinate supplies, with corn syrup solids rounding out formulation bases. Single-source vulnerability in Southeast Asian palm oil refining creates exposure to export restriction shocks. Distribution runs through food service buying cooperatives and wholesale distributor networks serving institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise in fat-protein emulsion chemistry is concentrating among retiring cohorts faster than university programs replenish supply, creating capability scarcity that advantages incumbents with captive technical talent and disadvantages new entrants lacking apprenticeship pipelines.
For Market Incumbents: Shield market position by deepening backward integration into palm oil refining in Malaysia and Indonesia to neutralize input cost volatility, while accelerating interesterified fat reformulation ahead of EFSA hydrogenation scrutiny. Prioritize certification investment in Non-GMO Project and organic tiers to defend margin structure against commodity-grade competitors facing clean-label procurement mandates from US school nutrition programs. For New Entrants and Emerging Players: Organic certification fast-track programs unlock white-space penetration in direct-to-consumer subscription channels where established brands lack agility, particularly among specialty coffee enthusiasts seeking barista-format powders for home espresso systems. Target bakery application segments where fat-protein emulsion functionality commands specification premiums unavailable to liquid oat creamer substitutes, leveraging e-commerce infrastructure to bypass food service distributor gatekeepers. For Investors and Strategic Acquirers: FDA guidance on "dairy-free" terminology reshapes the acquisition landscape by forcing label revision costs across existing product lines that could strain target balance sheets. Long-term viability favors mid-scale emulsion technology specialists with demonstrated spray-drying parameter optimization capabilities and existing clean-label certification portfolios. Watch EFSA enforcement patterns on processed plant fat health claims as the signal for accelerated reformulation spending cycles that would favor acquisition targets with preemptive interesterified fat capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Refining | Captive supply of hydrogenated and interesterified fats neutralizes Malaysian export volatility. |
| Agglomeration Technology Licensing | Fluidized bed spray-drying capability unlocks instant-dispersing powder premiums in cold beverage applications. |
| Clean-Label Certification Program | Non-GMO Project and organic validation enables access to USDA school nutrition procurement channels. |
| Direct-to-Consumer Launch | Subscription models bypass food service distributor markups while capturing specialty coffee enthusiast demand. |
| Bakery Application Expansion | Fat-protein emulsion stability in high-sugar matrices defends against liquid oat creamer substitution threats. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EFSA scientific opinions, USDA school nutrition program specifications, and trade customs data for vegetable oil derivatives. Interviews with spray-drying plant managers, food service procurement consortium directors, bakery R&D formulators, and emulsion chemistry specialists inform operational and technical parameters. Secondary validation draws from SEC 10-K filings of listed ingredient suppliers, Non-GMO Project certification databases, and SAMR labeling standards for plant-based fat sources. Bottom-up volume estimates from application segments triangulate against top-down market sizing from wholesale channel revenue concentration.
Segmentation dimensions modeled include product type differentiation across powdered, liquid, concentrate, and instant formats; application segmentation spanning food service, bakery products, beverages, and confectionery; end-user archetypes from restaurant chains to household consumers; and distribution channel structures from wholesale institutional contracts to direct-to-consumer e-commerce. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points and substitution elasticity parameters across the projection horizon. Industry-specific inputs incorporate spray-drying capacity utilization rates, palm oil futures curve dynamics, and certification timeline lags.
The analysis sits within stated boundaries; outcomes outside sustained palm oil supply stability, unchanged FDA labeling frameworks, and continued food service standardization trends would require recalibration. Forecasts reflect documented assumptions regarding emulsion chemistry talent availability, clean-label certification pipeline durations, and REACH compliance export window persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Rice Milk Market