
 North America Non-Dairy Yogurt Market | 2026-2036
North America Non-Dairy Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Dairy Yogurt Market Insights
Canadian oat milk suppliers is rebalancing capacity toward cultured products as fermentation infrastructure expands. Danone S.A. anchors its North American position through specialized almond and coconut yogurt lines. Chobani LLC leverages its Idaho dairy heritage to build credibility in oat-based alternatives. Forager Project LLC differentiates through cashew-forward formulations and organic certification.
North America non-dairy yogurt comprises plant-based milk substrates inoculated with live bacterial cultures, fermented under controlled temperature and pH conditions to achieve target acidity, viscosity, and probiotic counts. The product serves consumers seeking lactose-free, vegan, or lower-saturated-fat alternatives to conventional yogurt with comparable protein and calcium fortification. Coconut and oat substrates command the widest retail shelf presence, though almond maintains entrenched distribution in conventional supermarkets. Online retail and health stores capture the fastest velocity among distribution channels as subscription models and direct-to-consumer shipping reduce friction for repeat purchases.
The U.S. FDA governs allergen labeling and nutrient content claims, while Health Canada sets bilingual packaging and fortification standards for plant-based dairy alternatives. USDA organic certification and Non-GMO Project verification function as de facto market access filters for premium placement. Stakeholders must monitor how evolving federal definitions of "yogurt" affect plant-based labeling permissions and retail positioning.
Market Dynamics
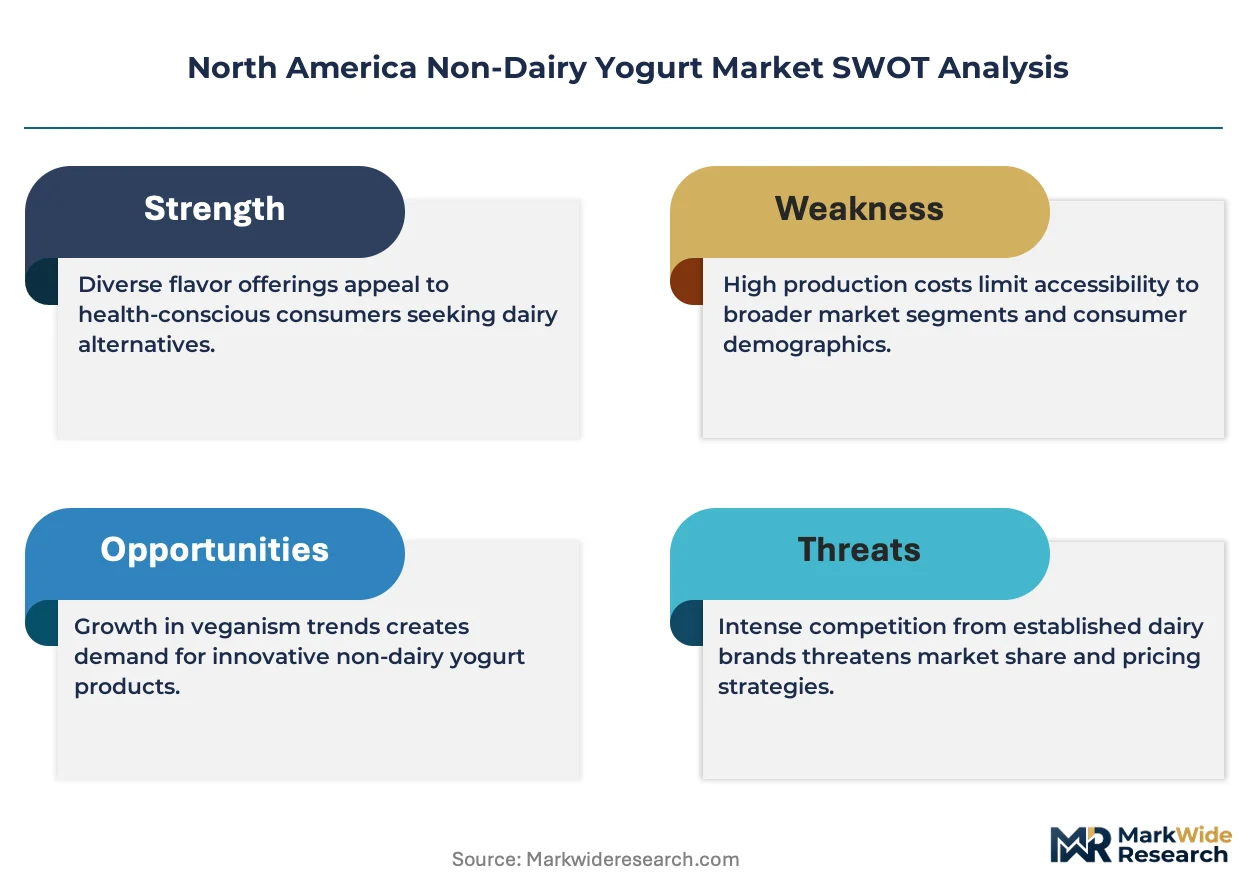
The U.S. FDA's evolving labeling standards for plant-based dairy alternatives are forcing reformulation investments and packaging redesigns across the supply chain, compressing margins while reshaping competitive positioning.
Growth Catalysts
- Flexitarian Density:California and the Pacific Northwest sustain concentrated demand clusters where vegan and flexitarian consumer density runs highest, creating natural test markets for innovation.
- Fermentation Infrastructure:Canadian oat milk suppliers are rebalancing capacity toward cultured products as fermentation capacity expands, unlocking substrate diversification.
- USDA Organic Certification:Organic and Non-GMO Project verification function as de facto market access filters for premium retail placement, accelerating quality-tier stratification.
Market Restraints
- Oat Substrate Volatility:Raw oat supply concentrates in Prairie provinces and upper Midwest growing regions, exposing processors to climate-driven yield variability.
- Protein Fortification Limits:Technical constraints on achieving comparable protein density to dairy yogurt without off-flavor development restrict formulation latitude.
- Allergen Labeling Friction:FDA allergen disclosure requirements for coconut and almond substrates create compliance complexity that slows new product velocity.
Strategic Opportunities
- Subscription Commerce:Direct-to-consumer shipping and subscription models through online retail and health food stores reduce friction for repeat purchases, capturing the fastest channel velocity.
- Cashew Substrate Expansion:Underexploited cashew-forward formulations offer texture and fat-profile differentiation in conventional supermarket channels where coconut and oat dominate.
- University Foodservice:Campus cafeterias and institutional dining represent underpenetrated volume contracts as Gen Z plant-based preference intensifies.
Industry Challenges
- Live Culture Stability:Maintaining viable probiotic counts through cold-chain distribution and shelf-life windows demands specialized fermentation expertise that outstrips current talent pools.
- Calcium Fortification Compliance:Meeting Health Canada's bilingual fortification standards while harmonizing with FDA nutrient content claims creates dual-compliance engineering burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Dairy Yogurt Market |
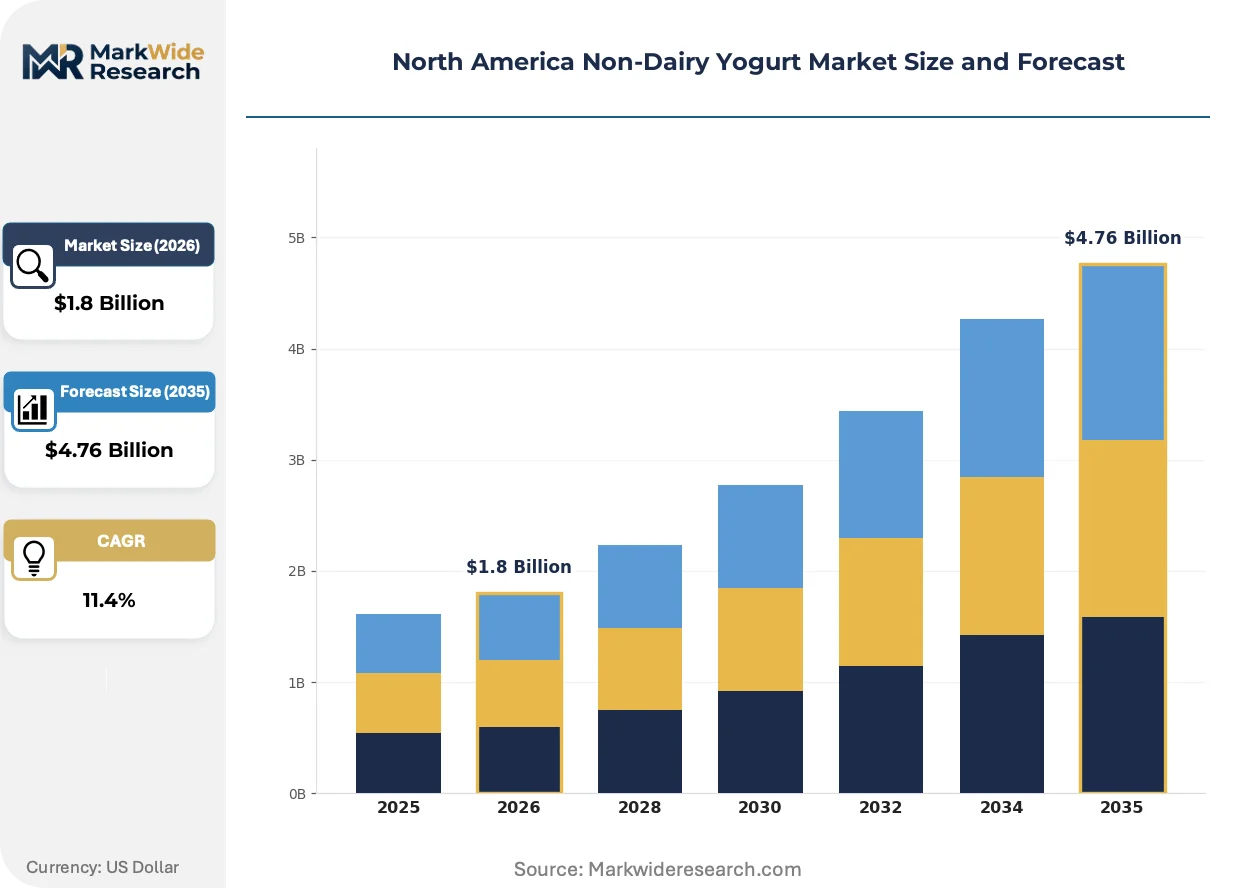
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut, Almond, Soy, Oat Distribution Channel: Supermarkets, Health Stores, Online Retail, Food Service End User: Vegan Consumers, Health Enthusiasts, Lactose Intolerant Individuals, General Public Flavor Profile: Plain, Strawberry, Blueberry, Vanilla |
| Companies Covered | General Mills Inc., Yoso Brands, Danone S.A., Kite Hill, Good Karma Foods Inc., The Hain Celestial Group Inc., Forager Project LLC, Otsuka Holdings Co. Ltd., Chobani LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Dairy Yogurt Market Trends and Innovations
Automation and precision fermentation are compressing production timelines while regulatory clarity around plant-based identity standards is reshaping how brands communicate differentiation to increasingly sophisticated buyers.
Precision fermentation technology is automating the cultivation of dairy-identical proteins without animal inputs, enabling hybrid formulations that bridge sensory gaps between plant-based and conventional yogurt. Specialty ingredient suppliers are scaling capacity to serve mid-tier brands previously locked out of advanced biotechnology. This automation is compressing the R&D-to-shelf cycle from 18 months toward 8-10 months.
The U.S. FDA's ongoing deliberation on standardized "yogurt" definitions for plant-based alternatives is forcing preemptive reformulation investments ahead of final rulemaking. Manufacturers are stripping "dairy-free" claims from front-of-pack to reduce litigation exposure while lobbying for permissive standards. Almond-based incumbents face the steepest repositioning costs given entrenched conventional supermarket distribution.
Health food store buyers are consolidating purchasing around subscription-enabled direct relationships, bypassing traditional distributor markups. Independent natural retailers in Colorado and Oregon are piloting exclusive SKUs with cashew-forward specialists, locking in margin share previously captured by distributors. This channel compression is most visible in Pacific Northwest metropolitan corridors where consumer willingness-to-pay for organic certification remains elevated.
North America Non-Dairy Yogurt Market Segmentation
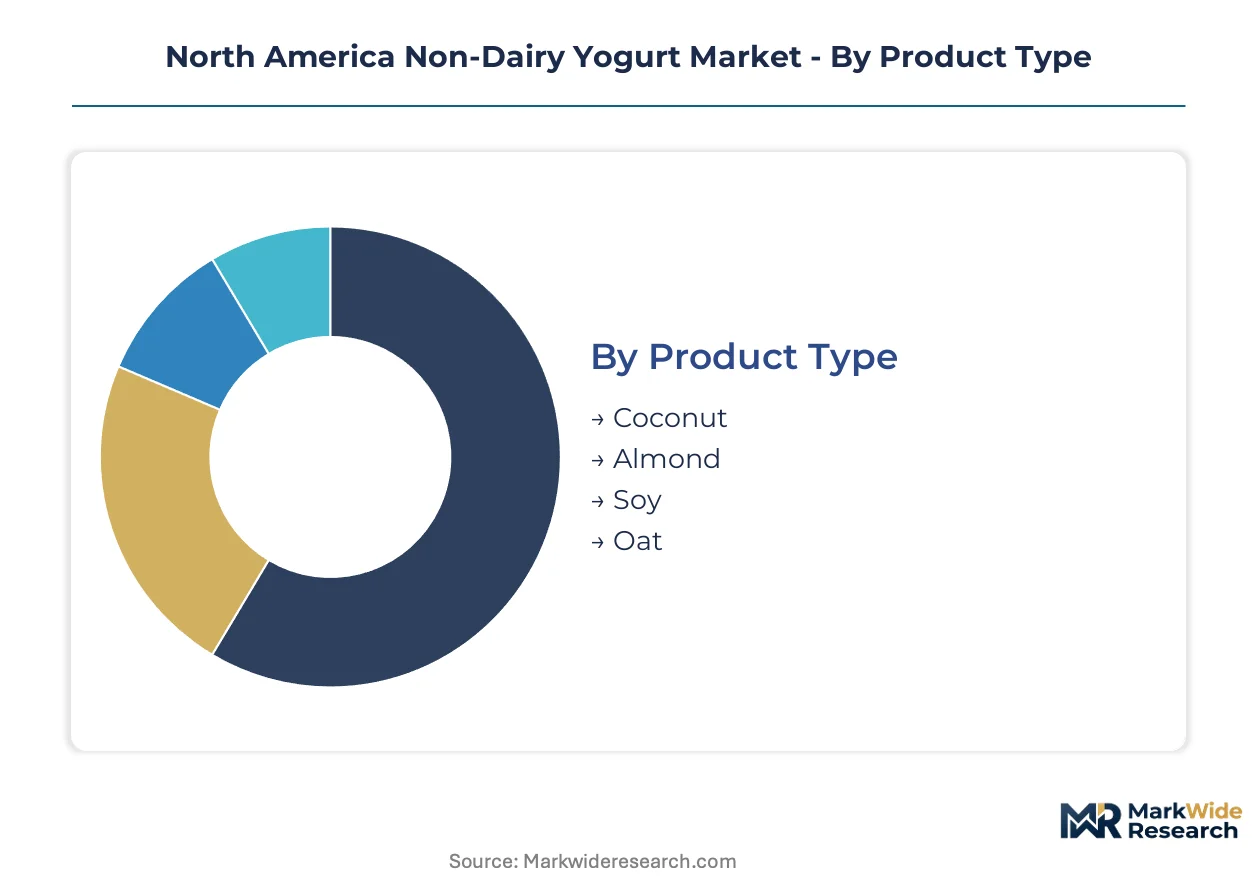
Non-dairy yogurt manufacturers configure production lines and ingredient sourcing around substrate-specific fermentation parameters. Segmentation reveals where formulation investments concentrate and which distribution pathways unlock repeat purchase economics.
Product Type:
Fermentation kinetics and fat-protein matrices differentiate substrate technologies and determine equipment compatibility.
- Oat:Beta-glucan content delivers viscosity without added stabilizers, though amylase activity requires precise temperature control during culture inoculation. Pacific Northwest flexitarian clusters drive disproportionate velocity here as Chobani and Canadian suppliers expand cultured oat capacity.
- Coconut:High saturated fat content creates creamy mouthfeel that bridges sensory gaps to dairy yogurt, but lipid oxidation limits shelf-life windows. Conventional supermarket distribution concentrates in California and Florida where tropical flavor familiarity runs highest.
- Almond:Established supply chains from California Central Valley growing regions support cost-competitive positioning despite protein deficit versus dairy benchmarks.
- Soy:Complete amino acid profile matches dairy protein density most closely, though beany off-notes restrict flavor masking flexibility.
Oat leads on scale; coconut leads on momentum.
Distribution Channel:
Channel economics separate high-frequency replenishment models from bulk contract structures.
- Online Retail:Subscription algorithms and direct-to-consumer shipping compress customer acquisition costs for repeat buyers. Cold-chain logistics investments by specialty carriers enable probiotic viability guarantees that conventional e-commerce cannot match.
- Health Stores:Exclusive SKU arrangements with cashew-forward specialists lock in margin share previously captured by distributors in Colorado and Oregon metropolitan corridors.
- Supermarkets:Almond-based incumbents hold entrenched shelf placement despite reformulation pressures from FDA labeling deliberations.
- Food Service:University cafeteria contracts represent underpenetrated volume as Gen Z plant-based preference intensifies across campus dining programs.
Supermarkets dominate absolute volume; online retail gains share fastest.
End User:
Consumer motivation segments determine fortification priorities and claims communication strategies.
- Vegan Consumers:Ethical positioning demands extend to packaging sustainability and supply chain transparency certifications.
- Health Enthusiasts:Probiotic count specifications and live culture guarantees command price premiums in Pacific Northwest and California clusters.
- Lactose Intolerant Individuals:Functional need-state prioritizes digestive comfort claims over environmental or ethical positioning.
- General Public:Flexitarian experimentation drives trial purchases where taste parity with conventional yogurt determines repeat conversion.
Health enthusiasts anchor premium tier pricing; the general public offers the steepest expansion trajectory.
Flavor Profile:
Flavor development pipelines balance clean-label constraints against masking requirements for plant substrate off-notes.
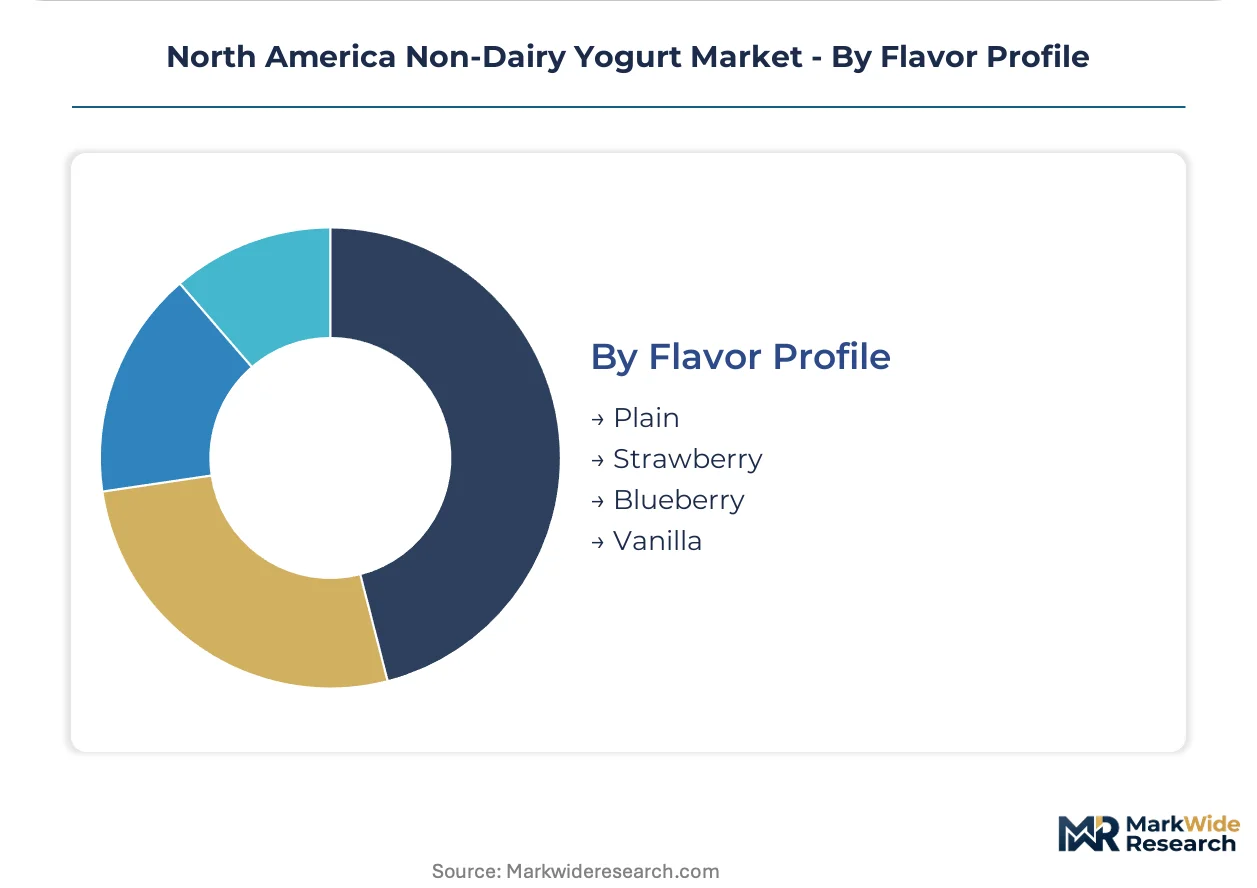
- Plain:Unflavored formulations serve as ingredient inputs for smoothie preparation and cooking applications, demanding neutral taste profiles.
- Vanilla:Vanilla bean and natural flavor systems mask oat and almond substrate characteristics most effectively across age demographics.
- Strawberry:Fruit preparation inclusions require pH stability coordination with live culture viability through shelf-life windows.
- Blueberry:Anthocyanin color stability challenges create formulation complexity for clean-label positioning without synthetic stabilizers.
Plain commands food service volume; vanilla drives retail velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with streamlined plant-based labeling pathways. The U.S. FDA's deliberative approach on standardized definitions creates compliance cost differentials against Health Canada's more prescriptive bilingual fortification mandates. Substrate sourcing clusters and flexitarian population density determine where fermentation capacity expands fastest.
United States
California and Pacific Northwest metropolitan corridors concentrate vegan and flexitarian consumer density, creating natural test markets for oat and coconut substrate innovations. The FDA's evolving standards for plant-based dairy alternatives force preemptive reformulation investments, particularly for almond-based incumbents with entrenched conventional supermarket distribution. Idaho's dairy heritage region now anchors oat-based fermentation capacity as Chobani LLC leverages existing infrastructure.
Canada
Prairie provinces supply raw oat substrates to cross-border processors, though climate-driven yield variability exposes supply chains to production shocks. Health Canada mandates bilingual packaging and fortification standards that create dual-compliance engineering burdens for exporters. Ontario and Quebec fermentation infrastructure is expanding as domestic oat milk suppliers rebalance capacity toward cultured products.
Mexico
Central Mexico's growing middle-class population generates trial demand for imported plant-based alternatives through supermarket channels. The country's national food safety regulator applies labeling standards that generally align with U.S. frameworks, reducing friction for cross-border product flows. Mexico City Metro serves as the primary distribution hub where health-conscious consumer segments cluster in upscale retail formats.
North America Non-Dairy Yogurt Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cashew-forward and precision-fermentation differentiation. The market structure stratifies across three tiers: multinational food conglomerates with diversified plant-based portfolios, mid-sized specialists with substrate-specific expertise, and venture-backed innovators leveraging biotechnology. Two dominant competitive moves define current dynamics: capacity expansion into oat fermentation infrastructure and strategic partnerships with precision fermentation ingredient suppliers.
Within the multinational tier, Danone S.A. and General Mills Inc. represent archetypal incumbents with diversified substrate coverage spanning almond, coconut, and oat lines. Chobani LLC occupies a distinctive position bridging dairy heritage credibility with oat-based alternative expansion. Forager Project LLC exemplifies the specialist archetype through organic certification and cashew-forward formulation focus.
| Leading Market Players |
|---|
| General Mills Inc. |
| Yoso Brands |
| Danone S.A. |
| Kite Hill |
| Good Karma Foods Inc. |
| The Hain Celestial Group Inc. |
| Forager Project LLC |
| Otsuka Holdings Co. Ltd. |
| Chobani LLC |
| Others |
Pricing and Supply Chain Analysis
Raw oat substrate costs from Prairie provinces and upper Midwest growing regions cascade through three-tier pricing structures across premium, standard, and economy levels, with organic certification and live culture density separating price tiers as they reach California flexitarian clusters through cold-chain logistics networks.
Pricing Analysis
Distributor markups compress as direct-to-consumer subscription channels capture fastest velocity in Pacific Northwest metropolitan corridors. Price differentiation separates USDA organic certified lines from conventional formulations, with probiotic count guarantees commanding premiums in health food stores. Cost compression in almond-based SKUs is intensifying because FDA labeling deliberations force packaging redesign investments. University cafeteria contracts exhibit highest price sensitivity, while health enthusiasts in Colorado and Oregon show lowest elasticity for organic certified cashew-forward products.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale supermarket demand through conventional distribution networks, while health food stores and online retail bypass traditional markups via exclusive SKU arrangements. Raw oat supply concentrates in Canadian Prairie provinces and the U.S. upper Midwest, with coconut substrate sourcing anchored in Southeast Asian processing hubs. Fermentation infrastructure expansion in Ontario and Quebec draws from cross-border substrate flows, creating tariff exposure on cultured product re-exports. Cold-chain logistics investments by specialty carriers enable probiotic viability guarantees that conventional e-commerce cannot match.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The U.S. FDA's evolving plant-based dairy labeling standards function as a regulatory compounder, with preemptive reformulation investments ahead of final rulemaking accelerating quality-tier stratification and consolidation incentives across substrate technologies.
For Market Incumbents: Cement shelf position in conventional supermarkets by locking in almond-based distribution ahead of FDA labeling clarity, while building captive oat fermentation capacity in Idaho to offset Prairie province supply volatility. Precision fermentation ingredient partnerships represent the critical lever against emerging biotechnology entrants threatening sensory parity claims.
For New Entrants and Emerging Players: Health Canada's bilingual fortification standards in Canada open a window for domestic formulation specialists to capture margin share previously captured by cross-border exporters. University foodservice contracts represent the most penetrable volume channel, with Gen Z plant-based preference intensifying across campus dining programs. A direct-to-institutional sales model bypasses distributor markups and builds recurring revenue foundations.
For Investors and Strategic Acquirers: Roll-up economics work for regional oat fermentation specialists because Health Canada's prescriptive standards create dual-compliance engineering burdens that favor scaled operators with dedicated regulatory affairs capabilities. Acquisition targets should demonstrate live culture stability expertise and established cold-chain partnerships. The signal to watch is FDA final rulemaking on plant-based identity standards, which will determine repositioning cost burdens for almond-based incumbents and validate precision fermentation hybrid formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Enables dairy-identical protein integration without animal inputs, bridging sensory gaps for hybrid formulations. |
| Subscription Commerce Platform | Direct-to-consumer algorithms reduce customer acquisition costs for repeat buyers in Pacific Northwest clusters. |
| Organic Certification Investment | USDA organic and Non-GMO Project verification function as de facto market access filters for premium retail placement. |
| University Foodservice Contracting | Campus cafeteria volume locks in underpenetrated institutional demand as Gen Z plant-based preference intensifies. |
| Fermentation Infrastructure Expansion | Ontario and Quebec capacity additions rebalance Canadian oat milk suppliers toward cultured product output. |
Research Methodology
Multiple input streams — primary interviews with fermentation specialists and retail category buyers, regulatory filing analysis, and trade flow databases — were reconciled through bottom-up and top-down triangulation. Industry stakeholders interviewed included plant-based R&D directors, health food store purchasing managers, cold-chain logistics coordinators, and university foodservice procurement officers. Secondary validation drew from FDA docket submissions, Health Canada fortification guidance documents, USDA organic certification records, and Nielsen retail audit data.
Data-stream reconciliation across substrate-specific production volumes, channel shipment records, and end-user consumption patterns informed the analytical framework over the projection horizon. Segmentation dimensions modeled include substrate technology, distribution channel structure, end-user motivation, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts, with oat substrate yield variability and live culture stability constraints serving as key forecast inputs.
Revisions become necessary when FDA final rulemaking on plant-based identity standards materializes, or when climate-driven oat yield shocks disrupt Prairie province supply bases. Forecasts reflect assumptions regarding regulatory timeline adherence and fermentation talent pool expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Dairy Free Yogurt Market