
 Spirulina Chocolate Market | 2026-2036
Spirulina Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Spirulina Chocolate Market Analysis
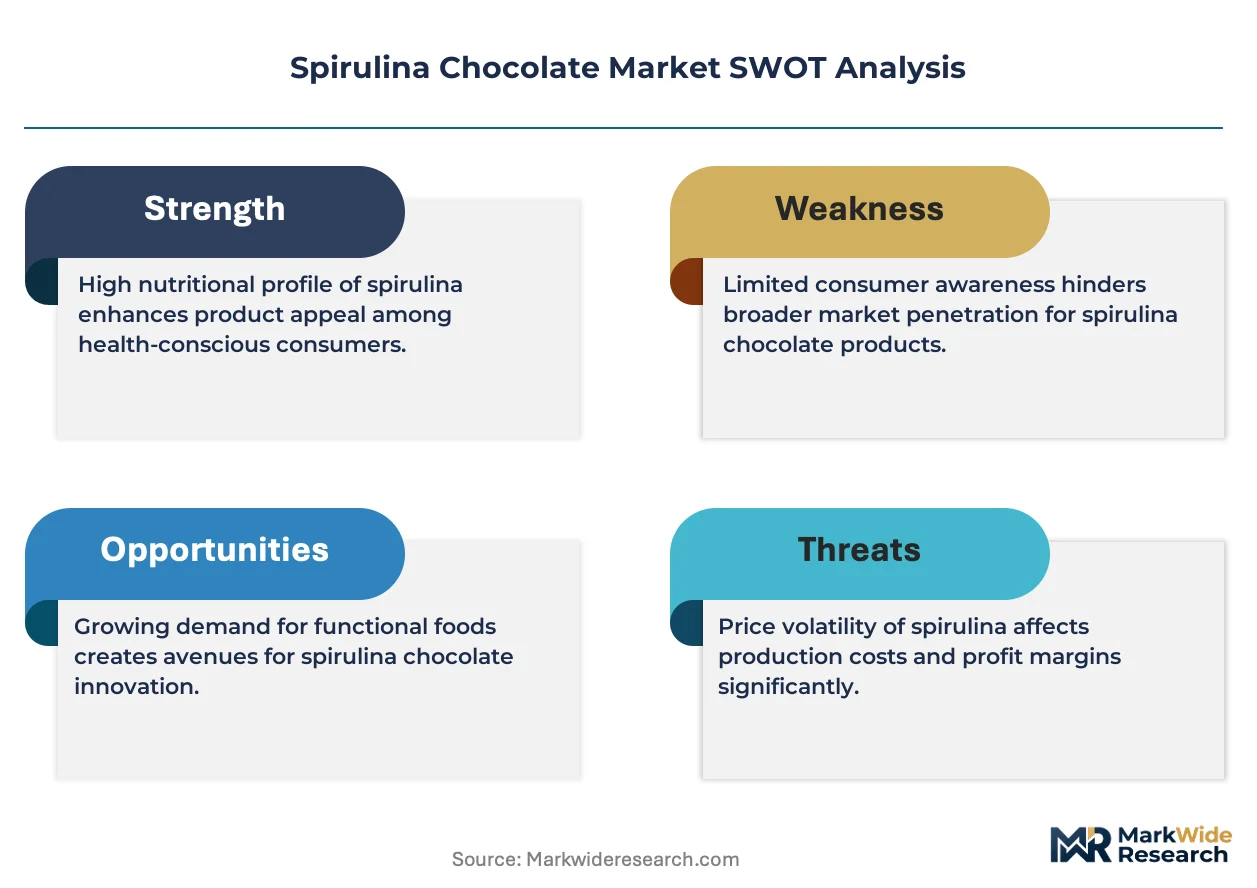
Artisanal confectionery craftsmanship is bifurcating the competitive landscape between heritage chocolate makers and algae biotechnology specialists. Vosges Haut Chocolat Ltd. leverages its gourmet positioning to command premium shelf placement in specialty retail channels. Zeoes Biotech anchors its operations on spirulina cultivation expertise that extends into finished chocolate applications. Doisy & Dam competes through ethical sourcing narratives that dominate the clean-label segment.
Spirulina chocolate denotes confectionery products incorporating Arthrospira platensis biomass as a functional ingredient, typically at concentrations of one to three percent by weight to preserve palatability while delivering phycocyanin-derived antioxidant properties and complete protein profiles. The manufacturing process requires controlled temperature tempering below forty-two degrees Celsius to prevent degradation of heat-sensitive phytonutrients. Dark chocolate formulations lead the product type category due to compatible bitter flavor profiles that mask spirulina's marine notes, while organic chocolate commands the strongest margin pool through certification premiums. Health-conscious consumers represent the most penetrated consumer group, though vegan consumers are expanding fastest as plant-based dietary frameworks normalize algae-derived nutrition.
FDA food additive regulations and USDA organic certification standards govern product claims and market access in North American channels, while EFSA novel food assessments shape European formulation pathways. Organic certification requirements under USDA National Organic Program create compliance barriers that filter smaller entrants from premium distribution tiers. Stakeholders must monitor evolving algae biomass sourcing standards and adapt procurement strategies as regulatory clarity around spirulina fortification thresholds solidifies across major consuming jurisdictions.
Market Dynamics
Clean-label formulation mandates under EFSA novel food guidelines are compressing product development timelines while forcing manufacturers to revalidate spirulina sourcing protocols across European distribution channels.
Growth Catalysts
- EFSA Novel Food Framework:Regulatory clarity on Arthrospira platensis biomass approval accelerates premium chocolate line extensions in Germany and France.
- Protein-Integrated Snacking:Fitness enthusiasts in urban centers drive functional confectionery adoption through gym-adjacent retail placement.
- Algae Biotechnology Maturation:Cultivation efficiency gains in photobioreactor systems reduce spirulina input costs for finished chocolate applications.
Market Restraints
- Heat-Sensitive Phytonutrient Degradation:Temperature-controlled tempering below forty-two degrees Celsius constrains throughput in conventional chocolate manufacturing infrastructure.
- USDA Organic Certification Barriers:National Organic Program compliance costs filter smaller entrants from premium retail tiers.
- Marine Flavor Masking Requirements:Dark chocolate formulations dominate because milk chocolate's sweetness profile inadequately covers spirulina's oceanic notes.
Strategic Opportunities
- Vegan Consumer Expansion:Plant-based dietary normalization in the United Kingdom creates white space for algae-derived protein positioning.
- Specialty Retail Channel Penetration:Gourmet food halls and wellness-focused e-commerce platforms offer margin-rich alternatives to mass grocery.
- Dual Carbon Goals Convergence:China's national climate targets incentivize low-carbon algae cultivation methods that resonate with sustainability-marketed confectionery.
Industry Challenges
- Phycocyanin Stability Expertise Gap:Food technologists with specialized knowledge of blue pigment preservation in lipid matrices command scarcity premiums.
- Multi-Jurisdiction Label Harmonization:Divergent FDA and EFSA fortification thresholds force SKU proliferation for cross-Atlantic distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spirulina Chocolate Market |
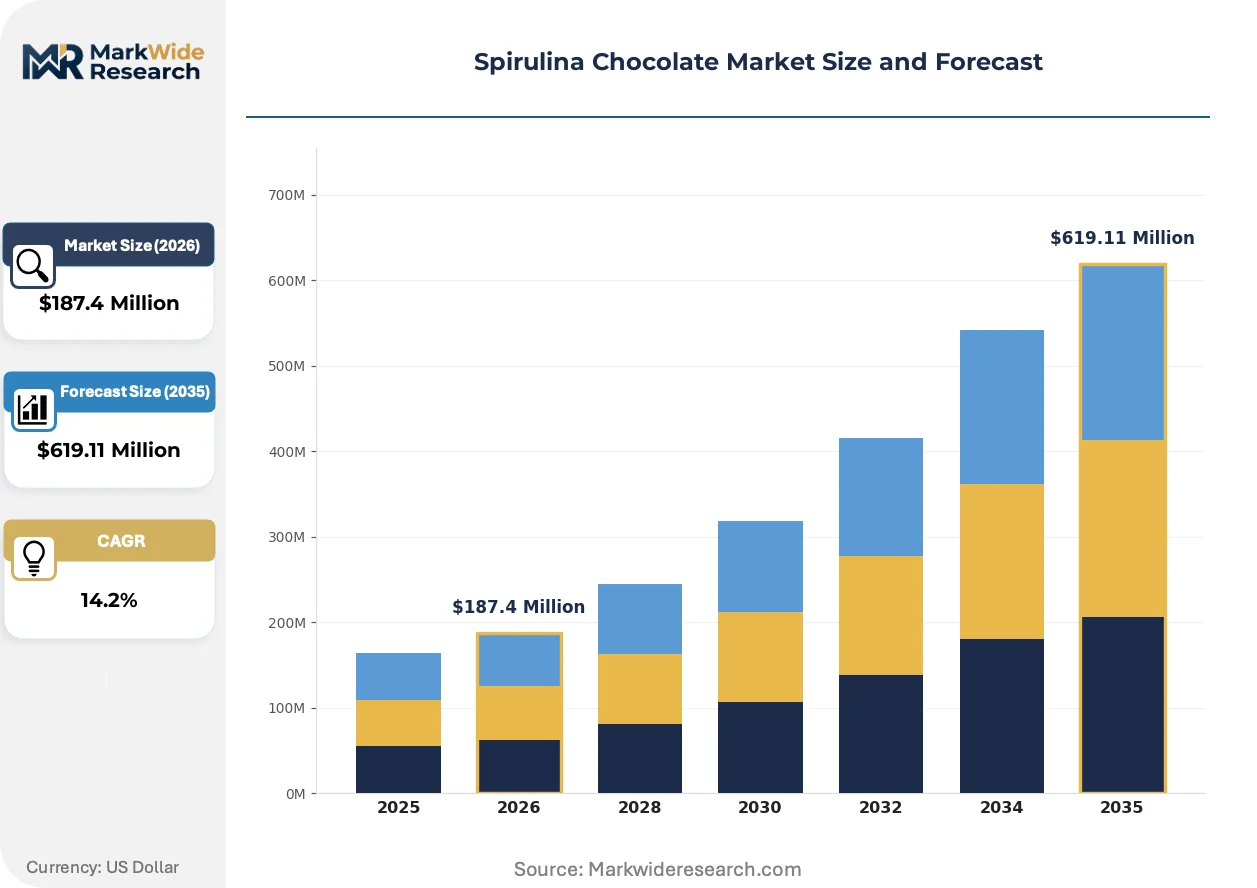
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, Organic Chocolate, Sugar-Free Chocolate Consumer Group: Health-Conscious Consumers, Fitness Enthusiasts, Vegan Consumers, Gourmet Food Lovers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Package Type: Bar, Box, Pouch, Bulk |
| Companies Covered | Doisy & Dam, Vosges Haut Chocolat Ltd., The Date Place Cafe, HeartofShasta, Zeoes Biotech, Biotein Naturals Spirulina, Orange Chocolat, Tricous, Reviver Particles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spirulina Chocolate Market Emerging Trajectories
Microencapsulation technologies are rewriting the palatability-performance tradeoff in functional confectionery, enabling higher spirulina loadings without sensory compromise.
Cold-press microencapsulation of Arthrospira platensis extract is supplanting conventional spray-dried powder incorporation in premium formulations. Artisanal chocolate manufacturers in Belgium and Switzerland adopt this method to achieve three-percent-plus biomass concentrations. The technology is compressing the historical barrier between functional efficacy and consumer acceptance.
EFSA's evolving guidance on novel food tolerance studies is tightening clinical evidence requirements for antioxidant claims. Manufacturers must now commission dedicated bioavailability trials rather than extrapolating from generic spirulina literature. Dark chocolate segments with established phytochemical positioning face the steepest compliance cost escalation.
Subscription-based wellness box curation is displacing impulse confectionery purchases in direct-to-consumer channels. Health-conscious buyers in metropolitan Germany and the Netherlands now discover spirulina chocolate through quarterly delivery programs rather than supermarket aisles. This shift concentrates brand discovery power with algorithm-driven platform operators.
Spirulina Chocolate Market Segmentation
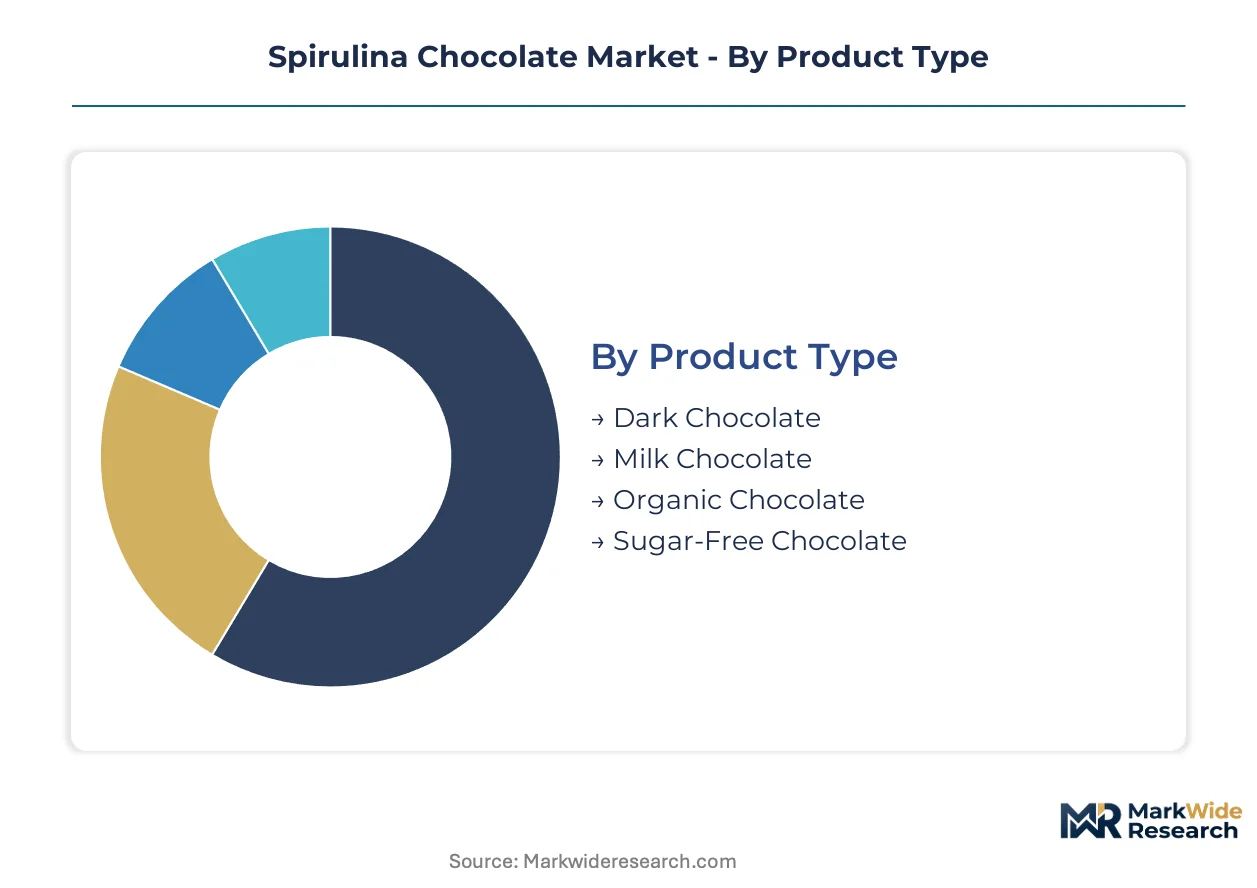
Segmentation in spirulina chocolate reveals how functional positioning, ethical sourcing narratives, and temperature-sensitive manufacturing constraints create distinct margin architectures across product tiers and channel strategies.
Product Type:
Premium margin pools concentrate in formulations that mask spirulina's marine notes while preserving heat-sensitive phytonutrients through controlled processing.
- Dark Chocolate:Cocoa solids at 70 percent or higher provide bitter flavor profiles that naturally obscure Arthrospira platensis biomass taste. German and Belgian manufacturers dominate this segment through heritage tempering expertise adapted for sub-forty-two-degree Celsius thresholds.
- Organic Chocolate:USDA National Organic Program and EU organic certification create compliance barriers that filter commodity competitors and sustain price premiums. Demand concentrates in metropolitan France and the Netherlands where clean-label verification commands shelf space allocation.
- Milk Chocolate:Sweeter taste profiles struggle to mask spirulina's oceanic character, limiting biomass loading to sub-two-percent concentrations.
- Sugar-Free Chocolate:Alternative sweetener systems from stevia or erythritol expand addressable base for diabetic and ketogenic diet adherents.
The dominant share belongs to Dark Chocolate, while Organic Chocolate is closing the gap fastest.
Consumer Group:
Volume concentration tracks dietary framework adoption curves, with plant-based normalization expanding addressable base beyond traditional wellness demographics.
- Vegan Consumers:Complete protein profiles from Arthrospira platensis biomass satisfy amino acid requirements absent dairy or whey alternatives. United Kingdom metropolitan centers show steepest adoption trajectory as plant-based dietary frameworks mainstream.
- Health-Conscious Consumers:Phycocyanin-derived antioxidant properties drive repeat purchase behavior among urban professionals seeking functional snacking alternatives. Penetration concentrates in German fitness culture and Dutch wellness retail channels.
- Fitness Enthusiasts:Gym-adjacent retail placement and protein-integrated positioning align with post-workout recovery consumption occasions.
- Gourmet Food Lovers:Artisanal craftsmanship narratives and limited-batch releases sustain specialty channel premiums.
Vegan Consumers capture the steepest expansion trajectory, though Health-Conscious Consumers retain the deepest penetration base.
Distribution Channel:
Channel economics diverge sharply between algorithm-driven discovery platforms and conventional grocery infrastructure.
- Specialty Shops:Gourmet food halls and wellness-focused independent retailers offer margin-rich environments where storytelling around algae biotechnology justifies price positioning. Belgian and Swiss chocolatiers leverage this channel for brand authority construction.
- Online Retail:Subscription-based wellness box curation displaces impulse purchasing in direct-to-consumer channels. Netherlands-based platform operators concentrate discovery power through algorithmic personalization.
- Health Food Stores:Staff expertise and category-dedicated shelf space support education-intensive product launches.
- Supermarkets:Mass grocery placement requires price compression and simplified messaging that conflicts with spirulina's technical value proposition.
Specialty Shops command the highest margin realization, while Online Retail is gaining share fastest through subscription model lock-in.
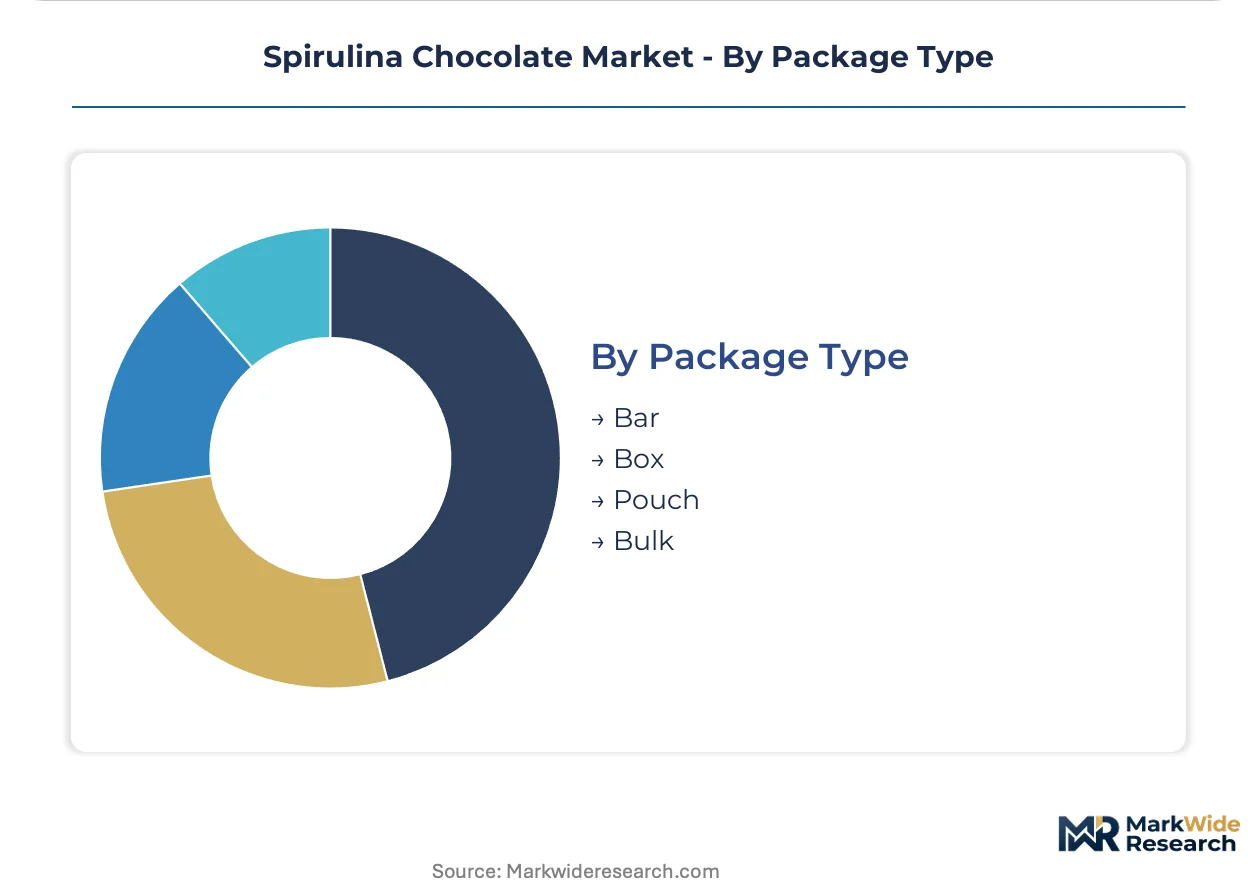
Package Type:
Packaging economics reflect consumption occasion fragmentation between personal indulgence and gifting rituals.
- Bar:Single-serve formats dominate personal consumption and on-the-go functional snacking. Standard weights of 50-100 grams optimize price accessibility for trial conversion.
- Box:Premium gifting occasions sustain higher per-gram pricing through presentation value and seasonal assortment strategies.
- Pouch:Flexible formats reduce material costs and support portion-controlled consumption patterns.
- Bulk:Foodservice and ingredient supply applications serve bakery and confectionery manufacturers seeking Arthrospira platensis biomass for in-house formulation.
Bar formats hold the dominant volume position, while Box formats realize the strongest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments anchor European market access protocols, with Germany commanding the deepest penetration of algae-based superfoods within premium chocolate categories. Regulatory clarity on Arthrospira platensis biomass approval accelerates formulation investments across metropolitan centers.
Germany
Fitness culture and functional snacking adoption drive demand among urban professionals seeking protein-integrated confectionery. EFSA novel food guidelines under EU Regulation 2015/2283 govern spirulina fortification thresholds and tolerance study requirements. Berlin and Munich host the densest concentration of specialty retailers and wellness-focused e-commerce platforms.
United States
Clean-label verification and plant-based dietary normalization expand the addressable consumer base beyond traditional wellness demographics. FDA food additive regulations and USDA National Organic Program standards create compliance barriers that filter smaller entrants. California and New York metro areas concentrate subscription-based wellness box curation and algorithm-driven brand discovery.
United Kingdom
Vegan consumer expansion accelerates as algae-derived protein positioning mainstreams within plant-based dietary frameworks. Trading Standards and Food Standards Agency enforcement align with evolving EFSA guidance on novel food claims. London metropolitan centers show steepest adoption trajectory for gym-adjacent retail placement.
France
Heritage chocolate craftsmanship and artisanal production expertise sustain premium positioning for functional confectionery. ANSM and DGCCRF oversight intersect with EU novel food frameworks for antioxidant claim substantiation. Paris and Lyon anchor gourmet food hall distribution networks where storytelling justifies price premiums.
China
Sustainability-marketed confectionery gains traction as national dual carbon goals incentivize low-carbon algae cultivation methods. SAMR food safety standards and GB labeling requirements shape product development pathways for imported functional foods. Shanghai and Beijing concentrate wellness-focused e-commerce platform operators and specialty retail channel penetration.
Spirulina Chocolate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with algae biotechnology specialists commanding cultivation expertise while heritage chocolatiers dominate brand equity and distribution relationships. The vendor base spans vertically integrated spirulina producers, artisanal confectionery houses, and ethical sourcing specialists. Three archetypes define competitive positioning: biotechnology-forward cultivators extending into finished goods, gourmet heritage brands leveraging craft narratives, and clean-label challengers built on transparency platforms. Capacity expansion in photobioreactor systems and strategic partnerships for cold-chain distribution constitute the dominant competitive moves.
Within the biotechnology-cultivator archetype, Zeoes Biotech anchors operations on spirulina cultivation expertise that extends into chocolate applications. Vosges Haut Chocolat Ltd. occupies a position exemplifying gourmet heritage positioning with premium shelf placement in specialty retail channels. Doisy & Dam represents the clean-label challenger segment, competing through ethical sourcing narratives that dominate transparency-focused consumer segments.
| Leading Market Players |
|---|
| Doisy & Dam |
| Vosges Haut Chocolat Ltd. |
| The Date Place Cafe |
| HeartofShasta |
| Zeoes Biotech |
| Biotein Naturals Spirulina |
| Orange Chocolat |
| Tricous |
| Reviver Particles |
| Others |
Supply Flow & Price Mechanics
Photobioreactor cultivation systems replacing open-pond spirulina harvesting in premium chocolate applications simultaneously relocate supply gravity toward Germany and Belgium while compressing unit economics for biomass inputs. This substitution dynamic concentrates pricing power with vertically integrated cultivators capable of cold-chain tempering infrastructure.
Pricing Analysis
German shelf prices for spirulina chocolate command 40-60 percent premiums over comparable functional confectionery in mass-market channels. Three-tier pricing structure across artisanal, specialty retail, and mass grocery levels tracks certification density and tempering protocol sophistication. Pricing pressure stems from EFSA novel food compliance cost escalation forcing smaller heritage chocolatiers toward private-label contract manufacturing. Health-conscious consumers in metropolitan fitness cultures show lowest price sensitivity, while supermarket shoppers in peripheral regions resist premium positioning.
Supply Chain Analysis
Just-in-time spirulina biomass procurement dominates artisanal chocolate manufacturing, though strategic stockpiling of phycocyanin extract concentrates is emerging among scale producers. Supply concentrates in Germany, France, and Belgium for finished chocolate tempering, with Arthrospira platensis biomass drawing from Israeli, Indian, and Chinese cultivation operations. Raw material dependencies center on photobioreactor-grade spirulina, organic cocoa butter, and cold-chain logistics infrastructure. Single-source vulnerability in phycocyanin extraction expertise creates bottleneck risk. Distribution runs through specialty retail networks and algorithm-driven subscription platforms rather than conventional grocery wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spirulina chocolate sits in early-cycle expansion as gym-adjacent retail placement normalizes protein-integrated confectionery among fitness enthusiasts previously unreachable by functional foods.
For Market Incumbents: Shield premium positioning by deepening backward integration into photobioreactor cultivation and securing exclusive cold-tempering capacity in Belgium and Switzerland. Algae biotechnology specialists extending into finished goods represent the primary competitive threat. Certification investment in EU organic and EFSA novel food frameworks anchors shelf access against clean-label challengers. For New Entrants and Emerging Players: USDA National Organic Program fast-track certification unlocks premium retail placement in California and New York metropolitan wellness channels. Vegan consumer segments in United Kingdom urban centers offer the most penetrable white space. Direct-to-consumer subscription positioning bypasses incumbent-controlled specialty retail gatekeeping. For Investors and Strategic Acquirers: EFSA's anticipated phycocyanin bioavailability study requirements reshape the acquisition landscape toward targets with in-house clinical trial capabilities. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Vertically integrated cultivators with chocolate applications expertise represent the priority acquisition archetype. Watch for EFSA tolerance study publication timelines as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Israeli and German cultivation scale-up reduces biomass input costs for finished chocolate applications. |
| EFSA Novel Food Compliance Investment | Dedicated bioavailability trials satisfy tightening antioxidant claim requirements in EU distribution channels. |
| Cold-Chain Distribution Partnership | Belgian logistics specialists preserve phycocyanin stability through sub-forty-two-degree Celsius tempering protocols. |
| Subscription Platform Integration | Netherlands-based algorithmic curation concentrates brand discovery power away from impulse retail. |
| Organic Certification Fast-Track | USDA National Organic Program compliance filters commodity competitors from premium shelf tiers. |
Methodological Framework
A spread of perspectives from artisanal chocolatiers, algae biotechnology R&D directors, specialty retail buyers, and EFSA regulatory consultants converged on the working assumptions. Primary fieldwork combined structured interviews with supply chain stakeholders and secondary validation through customs records, organic certification databases, and EFSA novel food submission filings. Bottom-up volume modeling triangulated against top-down category spend analysis.
Segmentation dimensions modeled include product type hierarchy, consumer group adoption curves, distribution channel economics, and regional regulatory cluster variations. CAGRs derived from trend-line extrapolation of biomass input cost trajectories and premium chocolate price elasticity across metropolitan wellness markets. Forecast inputs incorporated photobioreactor yield improvement curves and EFSA compliance timeline scenarios.
Decision-makers should treat outputs as directional under sustained EFSA regulatory clarity and stable algae cultivation technology diffusion; material deviation would warrant model refresh. Revision becomes warranted when phycocyanin stability breakthroughs or novel food approval delays cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Tahini Market
Specialty Foods
Miso Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Dong Quai Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Halal Foods Market