
 Reduced Fat Coconut Milk Market | 2026-2036
Reduced Fat Coconut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Fat Coconut Milk Market Analytics
Food manufacturers seeking lower-fat dairy alternatives is collapsing the traditional household-centric demand model for coconut milk. Thai Agri Foods Public Company Limited leverages integrated plantation-to-can operations across Southeast Asia. Goya Foods competes through specialized Hispanic and Caribbean channel control in North American grocery. Vita Coco anchors premium positioning in beverage applications with brand strength built on coconut water recognition.
Reduced fat coconut milk is an emulsion of coconut cream and water with fat content reduced to approximately 10-15% through centrifugal separation or dilution, serving as a lighter cooking base and dairy substitute in commercial kitchens. Shelf-stable cartons lead volume due to extended ambient distribution reach, while powdered formats represent the fastest-growing structural segment as food manufacturers prioritize freight efficiency and inventory flexibility. Dairy alternatives applications concentrate margin pools where beverage brands command premium positioning against oat and almond competitors.
FDA nutrition labeling rules and EFSA health claims frameworks shape permissible fat-content descriptors and front-of-package communication across major markets. USDA organic certification and EU organic regulation create tiered market access thresholds that filter supplier participation. Stakeholders must monitor evolving plant-based milk standard-of-identity debates in Washington and Brussels that could redefine compositional thresholds and competitive positioning.
Market Dynamics
Centrifugal separation technology is collapsing the traditional fat-content gradient in coconut milk manufacturing, enabling precision fat reduction that reconfigures supplier relationships between Southeast Asian processors and North American beverage formulators.
Growth Catalysts
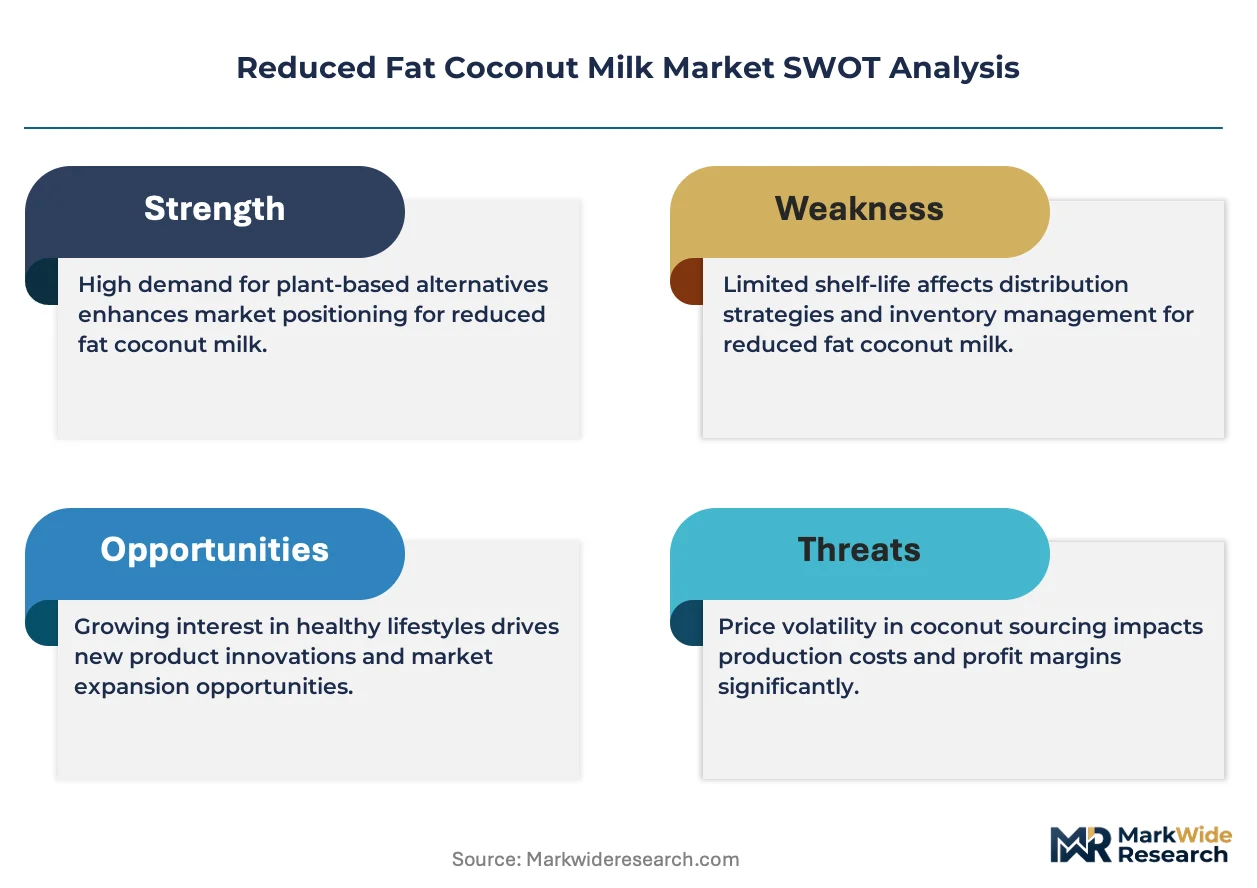
- USDA Organic Certification:Tiered market access thresholds in the United States filter supplier participation and reward integrated plantation operations with premium channel placement.
- Thailand:Integrated plantation-to-can infrastructure across Southeast Asia reduces input cost volatility for processors serving export markets.
- Clean-label mandates:EFSA health claims frameworks in the European Union tighten additive disclosure requirements and accelerate formulation partnerships between plant-based beverage brands and food manufacturers.
Market Restraints
- Copra price volatility:Input cost swings in dried coconut kernel markets compress margin buffers for processors lacking backward integration into plantation assets.
- Indonesia-Philippines supply concentration:Sourcing gravity across two archipelago nations exposes buyers to climate disruption and port congestion risks.
- Oat milk substitution:Barista-grade oat formulations displace reduced fat coconut milk in specialty coffee applications through superior foam stability.
Strategic Opportunities
- Philippines processing expansion:Underpenetrated copra refining capacity in Mindanao and Visayas regions offers first-mover advantages for integrated facility investment.
- Powdered format innovation:Freight efficiency priorities among food manufacturers accelerate demand for spray-dried and freeze-dried structural variants.
- EU Green Deal procurement standards:Carbon footprint disclosure mandates create competitive differentiation for processors with verified sustainable sourcing protocols.
Industry Challenges
- Plant-based milk standard-of-identity debates:Pending definitional rulings in Washington and Brussels threaten reformulation costs and label compliance timelines.
- Emulsion stability expertise:Scarce technical talent in lipid chemistry and colloidal systems constrains R&D velocity for mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Fat Coconut Milk Market |
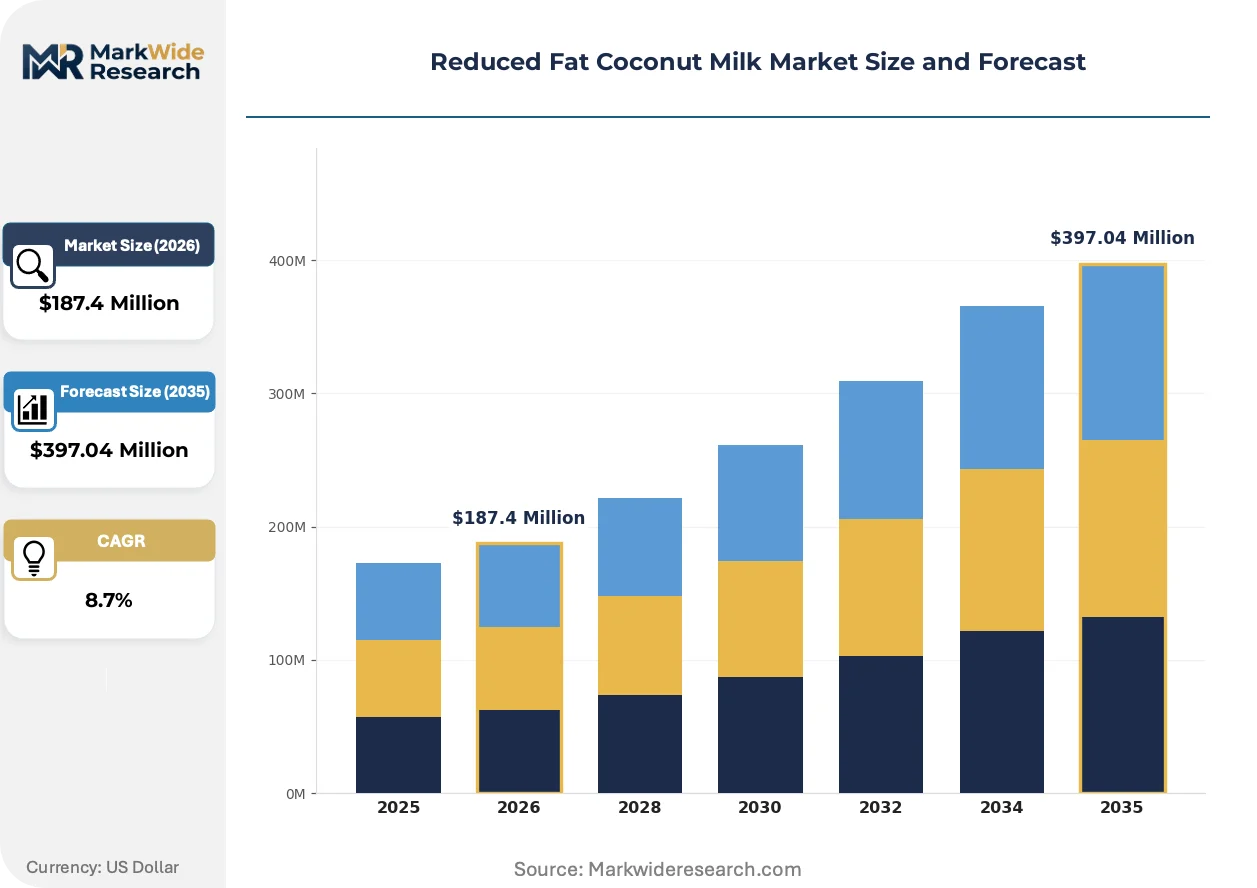
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Shelf-Stable, Frozen, Powdered Application: Dairy Alternatives, Baking, Cooking, Beverages Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Health Food Shops End User: Households, Restaurants, Cafes, Food Manufacturers |
| Companies Covered | Thai Coconut Public Company Limited, So Delicious Dairy Free, Silk, GraceKennedy Limited, AroyD, Thai Agri Foods Public Company Limited, Goya Foods, Pacific Foods, Vita Coco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Fat Coconut Milk Market Evolving Landscape
Formulation partnerships between coconut processors and beverage brands are rewriting procurement specifications and quality assurance protocols across the plant-based dairy alternative sector.
Membrane filtration technology is fragmenting the traditional centrifugal separation monopoly in fat reduction processing. Mid-scale Thai and Indonesian processors are adopting ceramic microfiltration systems to achieve 10-15% fat targets without dilution-based volume loss. This capability compression enables regional suppliers to bypass established toll-processing relationships and contract directly with North American private-label brands.
EFSA health claims frameworks are tightening permissible fat-content descriptors and front-of-package communication across European Union member states. Manufacturers must now substantiate "light" and "reduced fat" nomenclature through compositional testing protocols. German and Dutch retail chains have responded by consolidating supplier audits around accredited laboratory verification.
Food service distributors are unbundling traditional broadline contracts to source reduced fat coconut milk through direct plantation relationships. Restaurant chains and commercial kitchen operators in the United States now specify origin documentation and harvest-date traceability. This channel disintermediation concentrates volume with processors maintaining captive supply agreements rather than spot-market traders.
Reduced Fat Coconut Milk Market Segmentation
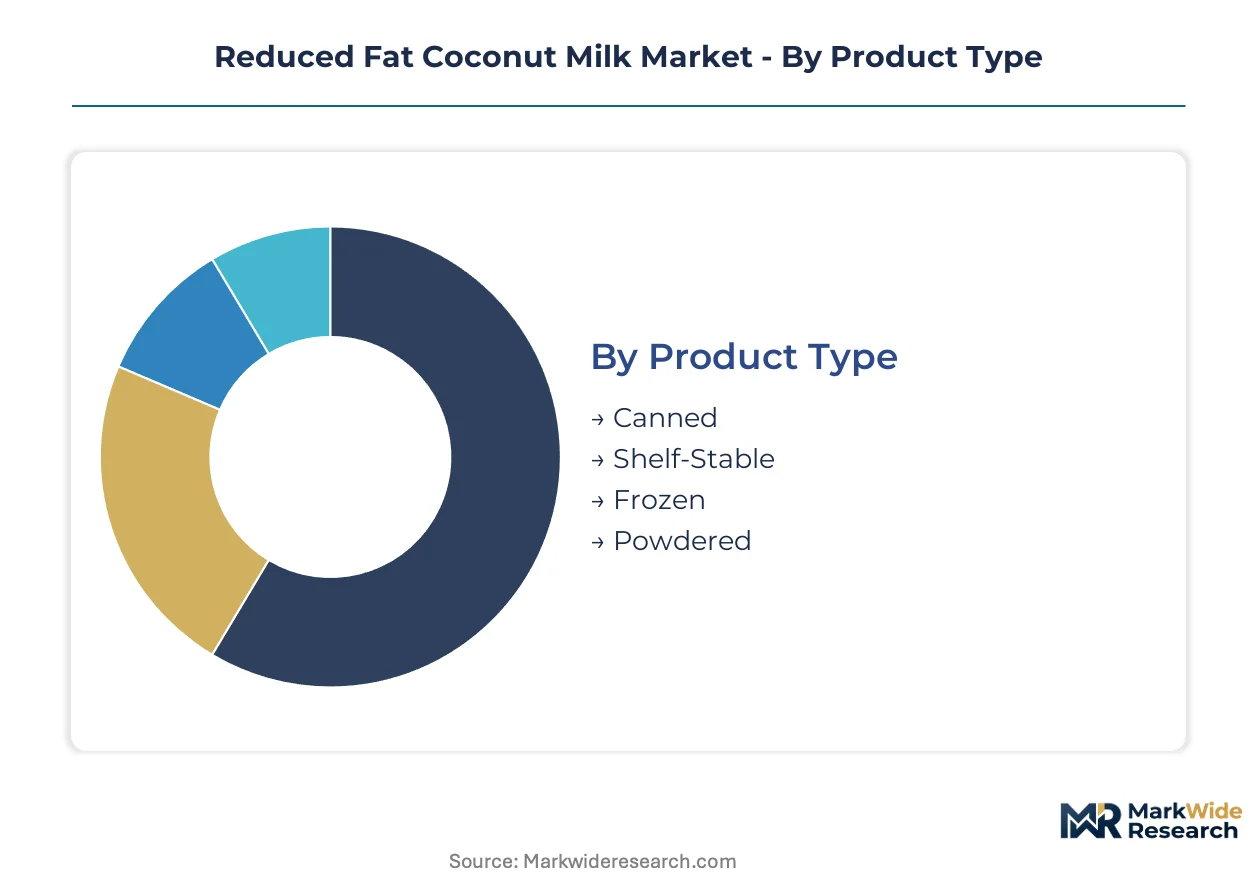
Reduced fat coconut milk serves divergent user requirements across format stability, culinary application, and procurement scale. Segmentation reveals where oat and almond substitutes exert maximum pressure and where coconut fat emulsions retain irreplaceable functional properties.
Product Type:
Shelf-stable cartons face the most aggressive substitution threat from barista-grade oat milk in beverage applications, while powdered formats resist displacement through freight economics and inventory flexibility advantages.
- Shelf-Stable:Aseptic cartons with extended ambient distribution reach dominate volume through retail grocery penetration. Food service distributors in the United States consolidate procurement around this format for back-of-house consistency.
- Powdered:Spray-dried and freeze-dried variants reduce shipping weight by 85% versus liquid equivalents, enabling direct contracting between Southeast Asian processors and North American private-label brands seeking freight efficiency.
- Canned:Traditional tin-plate packaging retains penetration in Hispanic and Caribbean pantry channels through heritage recipe alignment.
- Frozen:Limited distribution infrastructure constrains expansion outside food service hubs with dedicated cold-chain capabilities.
Shelf-stable retains volume leadership; powdered holds the steepest expansion curve.
Application:
Margin concentration varies sharply across use cases, with beverage applications commanding premium positioning against oat and almond competitors while cooking applications compete on unit cost efficiency.
- Dairy Alternatives:Refrigerated beverage positioning requires clean-label certification and front-of-package communication compliance under FDA and EFSA frameworks. German and Dutch retail chains now mandate accredited laboratory verification for "light" nomenclature claims.
- Cooking:Commercial kitchen demand concentrates on 10-15% fat emulsions as lighter bases for Southeast Asian and Caribbean cuisine. Restaurant chains specify origin documentation and harvest-date traceability, disintermediating broadline distributors.
- Baking:Fat-reduced formulations substitute for evaporated milk in pastry applications where coconut flavor compatibility determines adoption.
- Beverages:Specialty coffee applications face erosion from oat milk foam stability advantages, though coconut fat emulsions retain share in tropical flavor-profile drinks.
Dairy alternatives command margin concentration; cooking applications drive procurement volume.
Distribution Channel:
Channel control patterns reflect certification tier requirements, with organic and clean-label products concentrating in specialty retail while conventional formats flow through mass grocery.
- Supermarkets:Mass retail placement demands case-rate efficiency and promotional slotting fees that favor processors with integrated plantation-to-can operations.
- Specialty Stores:Ethnic grocery chains and independent retailers maintain Hispanic and Caribbean channel control through heritage brand relationships.
- Online Stores:Direct-to-consumer subscription models enable harvest-date traceability marketing and bypass retail margin stacking.
- Health Food Shops:USDA organic certification and EU organic regulation create tiered access thresholds that filter supplier participation in this channel.
Supermarkets anchor volume throughput; online stores are expanding most quickly.
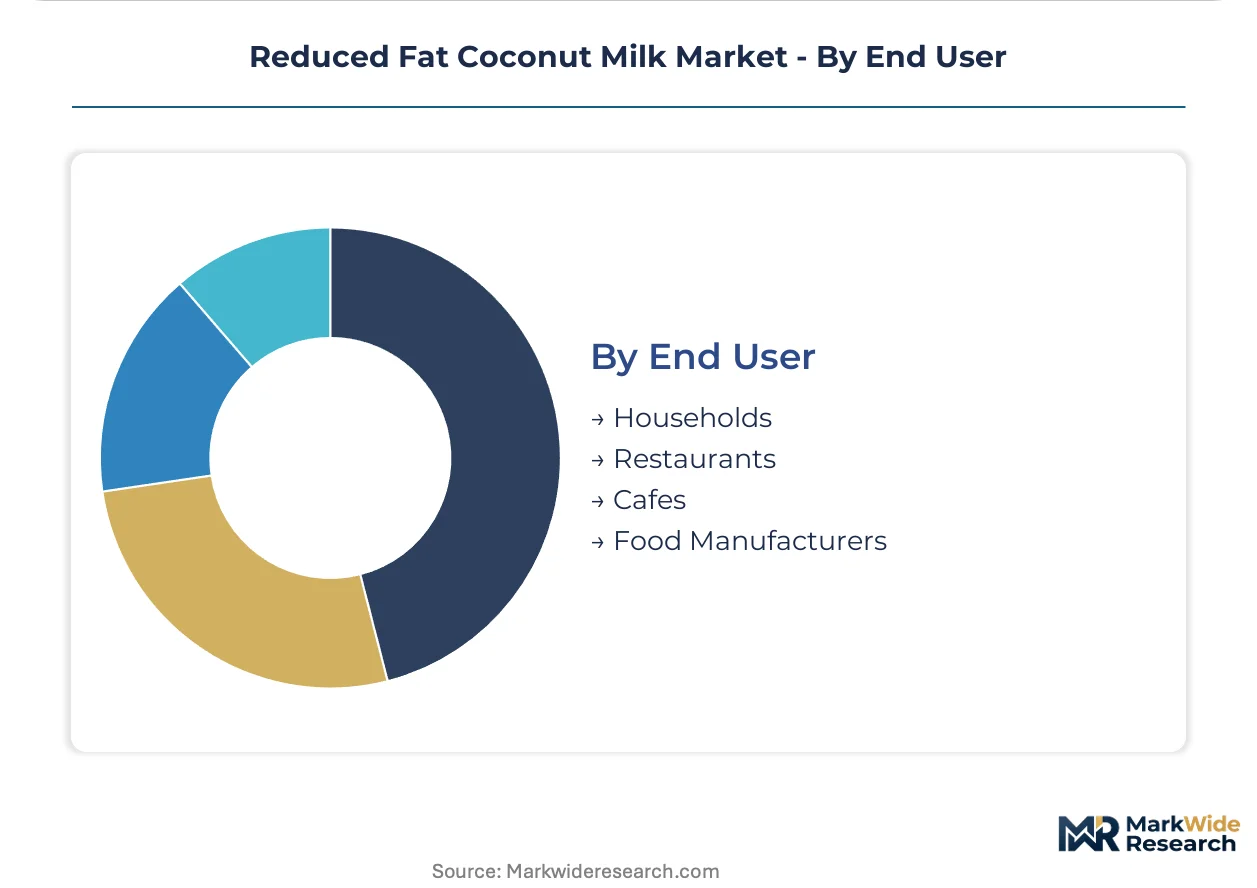
End User:
Procurement scale and specification complexity separate household purchasers from institutional buyers, with food manufacturers driving the most demanding quality assurance protocols.
- Food Manufacturers:Industrial buyers prioritize spray-dried formats for formulation flexibility and specify copra origin documentation for clean-label compliance. Membrane filtration adoption among Thai and Indonesian processors enables direct contracting without toll-processing intermediaries.
- Restaurants:Chain operators unbundle broadline contracts to source through direct plantation relationships, concentrating volume with processors maintaining captive supply agreements.
- Households:Pantry stock-up behavior favors shelf-stable cartons and canned formats through retail grocery channels.
- Cafes:Specialty coffee operators face oat milk displacement in foam-dependent applications, though coconut emulsions retain share in flavor-forward menu items.
Food manufacturers dictate specification evolution; restaurants are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers and beverage brands in the United States drive import demand, while integrated plantation processors in Thailand and Indonesia anchor supply-side capacity. Procurement sophistication varies sharply across consumption clusters.
United States
Specialty coffee chains and plant-based beverage brands concentrate demand in California and New York metro markets. FDA nutrition labeling rules govern fat-content descriptor claims on front-of-package communication. Restaurant operators in Los Angeles and Miami now specify harvest-date traceability, bypassing broadline distributors for direct plantation contracts.
Thailand
Integrated plantation-to-can operations across the central plains and southern provinces reduce input cost volatility for export-oriented processors. USDA organic certification requirements from American buyers filter supplier participation and reward backward integration. Samut Sakhon and Surat Thani provinces host the densest copra refining clusters serving North American private-label brands.
Indonesia
Copra processing capacity concentrates in North Sulawesi and Riau Islands, though port congestion and climate exposure create supply reliability concerns. The national food safety agency enforces additive disclosure standards that align with EU clean-label mandates. Processors in Medan and Makassar are adopting membrane filtration to bypass traditional toll-processing relationships.
Germany
EFSA health claims frameworks tighten permissible "light" and "reduced fat" nomenclature, mandating accredited laboratory verification. Retail chains in Berlin and Hamburg have consolidated supplier audits around compositional testing protocols. German beverage formulators increasingly contract directly with Southeast Asian processors for spray-dried formats.
Philippines
Mindanao and Visayas regions offer underpenetrated copra refining capacity with first-mover advantages for integrated facility investment. The Department of Agriculture promotes export-oriented processing through value-chain development programs. Davao and Cebu industrial zones attract foreign direct investment targeting powdered format production for freight efficiency.
Reduced Fat Coconut Milk Market Competitive Landscape
Player mix skews toward integrated plantation processors and brand-marketing specialists, with limited mid-tier toll-processing presence. Structure concentrates around Southeast Asian supply-side integration and North American channel control. Three archetypes dominate: plantation-integrated exporters, brand-positioning beverage specialists, and ethnic-channel heritage players. Capacity expansion and direct procurement relationships represent the dominant competitive moves.
Within the plantation-integrated tier, Thai Agri Foods Public Company Limited and Thai Coconut Public Company Limited exemplify backward integration from copra sourcing through aseptic processing. Goya Foods occupies a position in ethnic-channel heritage control, leveraging Hispanic and Caribbean pantry relationships. Vita Coco anchors premium beverage positioning built on coconut water brand recognition. GraceKennedy Limited represents Caribbean-origin supply concentration with North American distribution reach.
| Leading Market Players |
|---|
| Thai Coconut Public Company Limited |
| So Delicious Dairy Free |
| Silk |
| GraceKennedy Limited |
| AroyD |
| Thai Agri Foods Public Company Limited |
| Goya Foods |
| Pacific Foods |
| Vita Coco |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for copra feedstock concentrate pricing power with Thai and Indonesian processors possessing backward integration into plantation assets, while spot-market buyers absorb volatility through compressed margin structures. This lead-time asymmetry rewards integrated operators with cost predictability and penalizes toll-dependent competitors.
Pricing Analysis
Centrifugal-generation processing commands premium positioning against dilution-based legacy methods, while membrane filtration systems are capturing mid-tier price points through capability compression. Three-tier pricing structure across USDA organic certified, conventional clean-label, and economy unbranded tiers separates premium channel placement from mass retail penetration. Pricing pressure stems from oat milk substitution in beverage applications, where barista-grade foam stability commands shelf space. Food manufacturers exhibit highest price sensitivity due to freight efficiency mandates, while specialty retailers absorb premiums for harvest-date traceability.
Supply Chain Analysis
Thailand and Indonesia anchor copra processing capacity through integrated plantation-to-can infrastructure across Samut Sakhon, Surat Thani, North Sulawesi, and Riau Islands. Philippine Mindanao and Visayas regions offer expansion frontiers with underpenetrated refining capacity. Raw material flows draw from Southeast Asian coconut palm harvests, with ceramic microfiltration equipment and aseptic carton packaging as critical processing dependencies. Single-source vulnerability concentrates in Indonesian archipelago exposure to climate disruption and port congestion. Distribution runs through food service broadline networks consolidating around shelf-stable formats, with direct plantation contracting fragmenting traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward food manufacturers and restaurant chains consolidating procurement through direct plantation relationships, fragmenting traditional distributor intermediation and compressing spot-market margins.
For Market Incumbents: Consolidate backward integration into Mindanao and Visayas processing capacity to capture first-mover freight efficiency advantages. Deepen captive supply agreements with North American private-label brands before membrane filtration capability diffuses to regional competitors. Oat milk substitution in specialty coffee represents the primary demand erosion threat; defend through tropical flavor-profile beverage formulation partnerships. For New Entrants and Emerging Players: Anchor in Philippine powdered format production targeting food manufacturer freight efficiency priorities. Spray-dried and freeze-dried variants offer the most penetrable white space, with direct contracting protocols bypassing established toll-processing relationships. Pursue EU Green Deal carbon footprint verification as differentiated positioning against Southeast Asian incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underutilized copra processing assets in secondary Indonesian provinces. Long-term viability hinges on clean-label certification infrastructure and membrane filtration technical talent acquisition. Watch for inflection in plant-based milk standard-of-identity rulings from FDA and EFSA as regulatory clarity catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Thai processors reduce copra price volatility exposure through captive supply control. |
| Membrane Filtration Capability Investment | Indonesian mid-scale processors bypass toll-processing relationships with ceramic microfiltration adoption. |
| Powdered Format Production Scale-Up | Philippine facilities capture food manufacturer freight efficiency priorities through spray-dried output. |
| Direct Plantation Contracting Protocols | Restaurant chains specify harvest-date traceability, disintermediating broadline distributors. |
| EU Green Deal Certification Program | Carbon footprint disclosure mandates create competitive differentiation for verified sustainable sourcing. |
Research Methodology
Operator-level perspectives from coconut processing plant managers, food manufacturer procurement directors, restaurant chain supply chain leads, and beverage brand formulation scientists anchored the qualitative base. Secondary validation drew from USDA organic certification databases, FDA nutrition labeling guidance documents, EFSA health claims registers, and Southeast Asian customs export records. Bottom-up volume modeling triangulated against top-down category spend analysis.
Sensitivity analysis tested forecast robustness across copra price volatility scenarios, oat milk substitution acceleration rates, and regulatory standard-of-identity ruling timelines. Segmentation dimensions spanned product format stability, application functional requirements, distribution channel certification tiers, and end-user procurement scale. CAGRs derived from trend extrapolation against structural shift inflection points, with membrane filtration adoption curves and direct contracting penetration rates as industry-specific forecast inputs.
Material uncertainties — FDA and EFSA definitional rulings, climate disruption frequency in Indonesian archipelago, oat milk foam stability improvements — sit outside the modeled envelope. Forecasts reflect assumptions around clean-label regulatory trajectory and freight cost normalization. Recalibration cycles align with material shifts in plant-based milk competitive dynamics and Southeast Asian processing capacity utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Dairy-Free Spreads Market