
 Activated Cake Emulsifier Market | 2026-2036
Activated Cake Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Cake Emulsifier Market Outlook
Consolidation among European industrial bakery groups is recalibrating procurement leverage across the activated cake emulsifier supply base. BASF SE leverages its integrated oleochemicals platform to secure backward integration into monoglyceride feedstocks. Palsgaard A/S anchors its position through specialized emulsifier blends tailored to high-ratio cake systems. Kerry Group plc competes by extending its technical service footprint directly into customer formulation labs.
An activated cake emulsifier is a surface-active agent, typically comprising distilled monoglycerides or polyglycerol esters, that stabilizes oil-water interfaces in batter systems to improve aeration, crumb structure, and shelf-life extension in chemically leavened goods. Powder formulations dominate industrial-scale baking operations due to handling efficiency and dosing precision, while liquid concentrates represent the fastest-growing category as artisan producers adopt pumpable batch systems. The application split shows baking commanding the primary margin pool, with confectionery emerging as a secondary growth vector where fat bloom control requirements intensify emulsifier specification.
The European Food Safety Authority (EFSA) and REACH govern additive safety assessments and chemical registration thresholds, respectively, compelling reformulation away from synthetic ester variants toward plant-derived alternatives. The FDA's GRAS self-determination framework in the United States creates asynchronous approval pathways that fragment product registration timelines across jurisdictions. Stakeholders must monitor divergence between EU precautionary standards and US notification-based systems when allocating R&D portfolios.
Market Dynamics
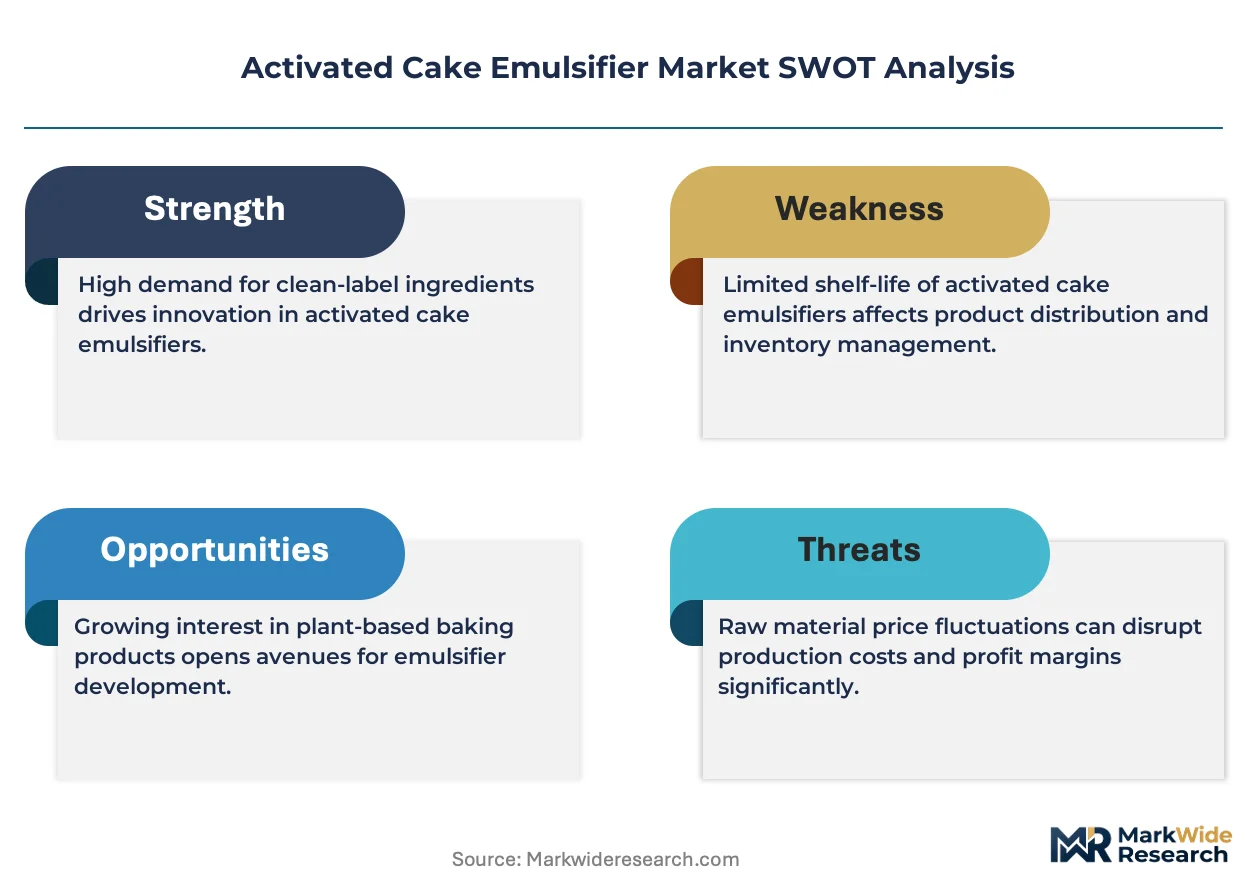
Clean-label reformulation mandates under EU REACH and the F-Gas Regulation are compressing formulation timelines while elevating plant-derived emulsifier specifications across European industrial baking clusters.
Growth Catalysts
- REACH chemical registration thresholds:Manufacturers accelerate substitution of synthetic esters with distilled monoglycerides to preempt compliance deadlines.
- Artisan bakery chain expansion:Pumpable liquid concentrate systems gain adoption in small-batch operations seeking dosing precision without powder handling infrastructure.
- Munich-Hamburg industrial baking corridor:Concentrated procurement demand from large-scale producers drives premium emulsifier volume commitments.
Market Restraints
- Palm oil feedstock volatility:Oleochemical input costs fluctuate with Malaysian and Indonesian supply disruptions, compressing margin stability for monoglyceride producers.
- EFSA additive safety reassessments:Pending evaluations of polyglycerol ester toxicology data create regulatory uncertainty that delays new product launches.
- Enzyme-based aeration systems:Transglutaminase and lipase formulations emerge as functional substitutes in high-ratio cake applications, threatening emulsifier incumbency.
Strategic Opportunities
- Confectionery fat bloom control:Premium chocolate and coating applications specify emulsifier systems for polymorph stabilization, opening adjacent revenue pools beyond baking.
- German artisan producer segment:Underpenetrated mid-tier bakeries in Bavaria and Baden-Württemberg lack technical service support for emulsifier optimization.
- EU Green Deal bio-based mandates:Incentives for renewable feedstock conversion accelerate R&D investment in microbially derived surfactant alternatives.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in batter rheology and aeration kinetics concentrates at established suppliers, constraining customer technical service expansion.
- GRAS self-determination asynchrony:Divergent FDA notification timelines versus EFSA pre-approval requirements fragment product registration portfolios and delay cross-border launches.
- Legacy dosing equipment incompatibility:Powder-to-liquid system conversions require capital expenditure at industrial bakeries with depreciated batch infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activated Cake Emulsifier Market |
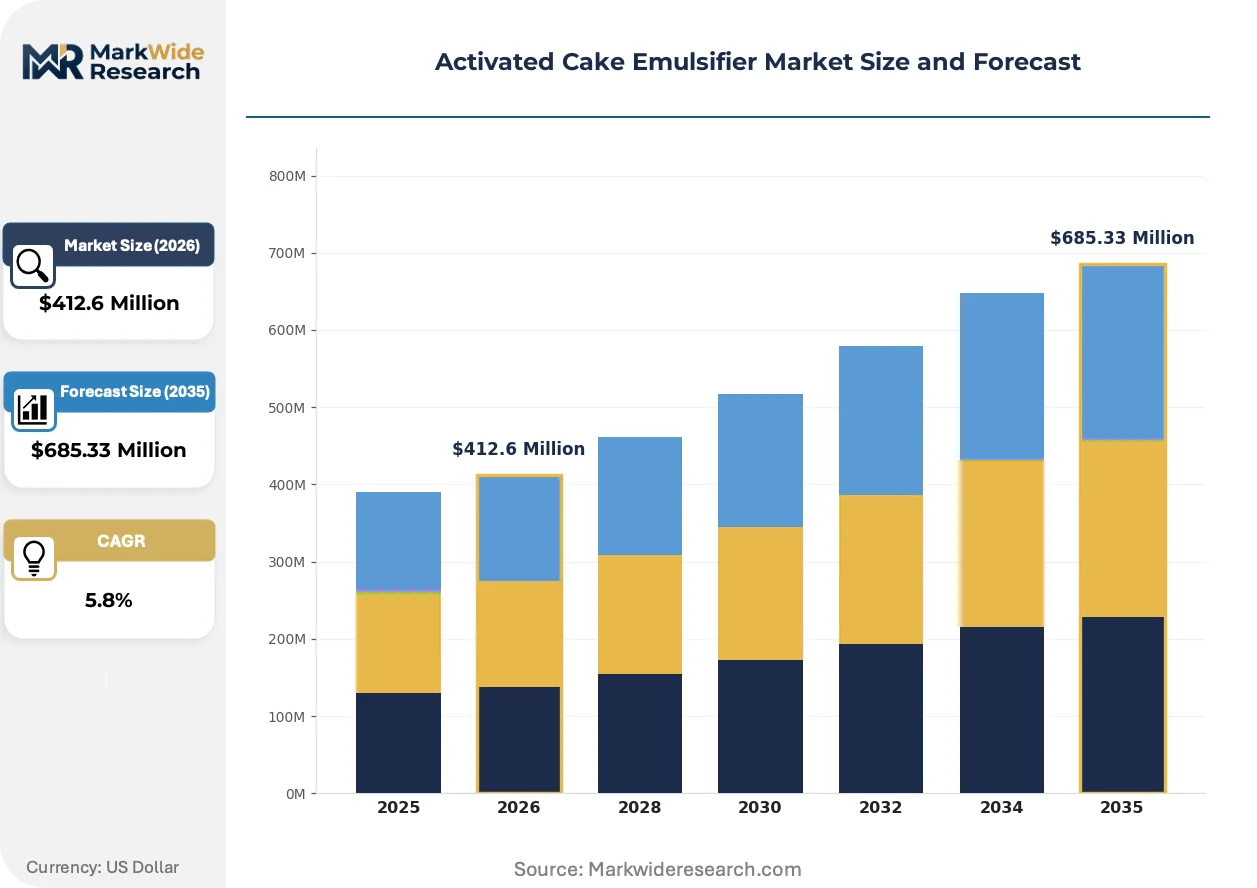
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granulated, Concentrate Application: Baking, Confectionery, Dairy, Sauces End User: Bakery, Restaurants, Food Services, Retailers Distribution Channel: Online, Wholesale, Retail, Direct Sales |
| Companies Covered | BASF SE, DuPont de Nemours Inc., Palsgaard A/S, Ingredion Incorporated, Wacker Chemie AG, Corbion N.V., Cargill Incorporated, FrieslandCampina Professional, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Cake Emulsifier Market Strategic Shifts
Electrification of process control and precision fermentation are converging to transform emulsifier manufacturing economics and specification capabilities.
Precision fermentation of microbial lipids is electrifying the supply base for plant-derived monoglycerides. Specialty chemical producers in the Netherlands and Denmark are scaling bioreactor capacity to displace oleochemical dependency. This biotechnology is compressing feedstock cost structures while enabling custom fatty acid profiles for high-ratio cake systems.
The EU F-Gas Regulation phase-down schedule tightens restrictions on hydrofluorocarbon use in food processing equipment, indirectly elevating emulsifier importance for ambient-stable batter storage. Industrial bakeries in Germany and France are retrofitting production lines to reduce refrigeration loads. Powder emulsifier formulations benefit as extended ambient processing windows reduce cold-chain infrastructure requirements.
Direct technical service embedding represents a behavioral pivot among ingredient buyers. Large industrial baking groups now require supplier chemists to operate inside customer formulation laboratories rather than remote consultation. This proximity model concentrates contract value with integrated solution providers and marginalizes transactional distributors in the Rhine-Ruhr and northern Italian baking corridors.
Activated Cake Emulsifier Market Segmentation
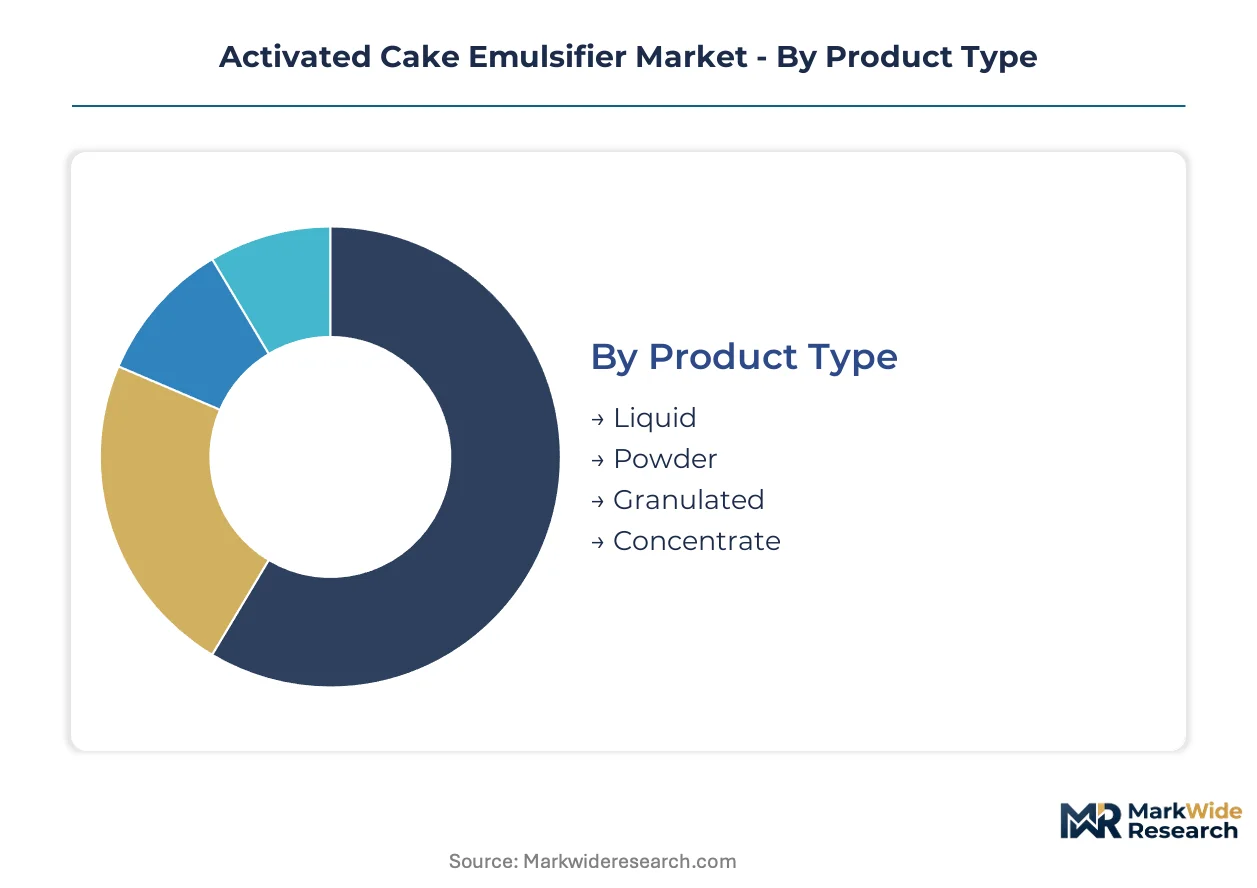
Segmentation in the activated cake emulsifier market reveals how formulation format, application intensity, and procurement channel determine margin capture. Suppliers calibrate R&D investment and technical service deployment against these divides.
Product Type:
Standardization dominates powder and liquid formats, while concentrates and granulated variants command customization premiums for specific batter rheology requirements.
- Liquid:Pumpable concentrates enable precise dosing in artisan bakery batch systems without powder handling infrastructure. Demand clusters in Bavaria and Baden-Württemberg mid-tier bakeries lacking capital for legacy equipment conversion.
- Powder:Free-flowing distilled monoglyceride blends dominate industrial-scale operations across the Munich-Hamburg corridor for handling efficiency and extended ambient storage stability under F-Gas Regulation phase-down pressures.
- Granulated:Agglomerated formats reduce dust exposure and improve dispersion kinetics in high-shear mixing environments.
- Concentrate:High-active systems minimize transport costs and cold-chain requirements for export-oriented producers.
Leading the category by volume: Powder. Expanding most quickly: Liquid.
Application:
Margin pools concentrate where fat stabilization requirements intersect with aeration performance demands.
- Baking:High-ratio cake systems specify emulsifier blends for crumb structure and shelf-life extension across German industrial clusters. REACH compliance deadlines accelerate substitution toward plant-derived monoglycerides in chemically leavened goods.
- Confectionery:Chocolate and coating applications require polymorph stabilization for fat bloom control, opening premium specification tiers beyond traditional baking margins.
- Dairy:Whipped topping and frozen dessert systems leverage emulsifier functionality for overrun control and freeze-thaw stability.
- Sauces:Oil-in-water emulsion stability drives specification in mayonnaise and dressing applications with clean-label formulation constraints.
Dominant revenue share: Baking. Steepest expansion trajectory: Confectionery.
End User:
Procurement sophistication varies sharply between formulation-capable industrial groups and ingredient-dependent smaller operators.
- Bakery:Industrial baking groups in the Rhine-Ruhr corridor consolidate procurement leverage and demand embedded technical service from suppliers. EFSA additive reassessments create reformulation urgency across this segment.
- Restaurants:Central kitchen operations in chain formats specify emulsifier systems for consistency in outsourced dessert production.
- Food Services:Institutional catering procurement prioritizes cost stability and supply assurance over performance optimization.
- Retailers:Private-label bakery programs drive specification for clean-label emulsifier claims on consumer-facing packaging.
Highest volume concentration: Bakery. Gaining share fastest: Retailers.
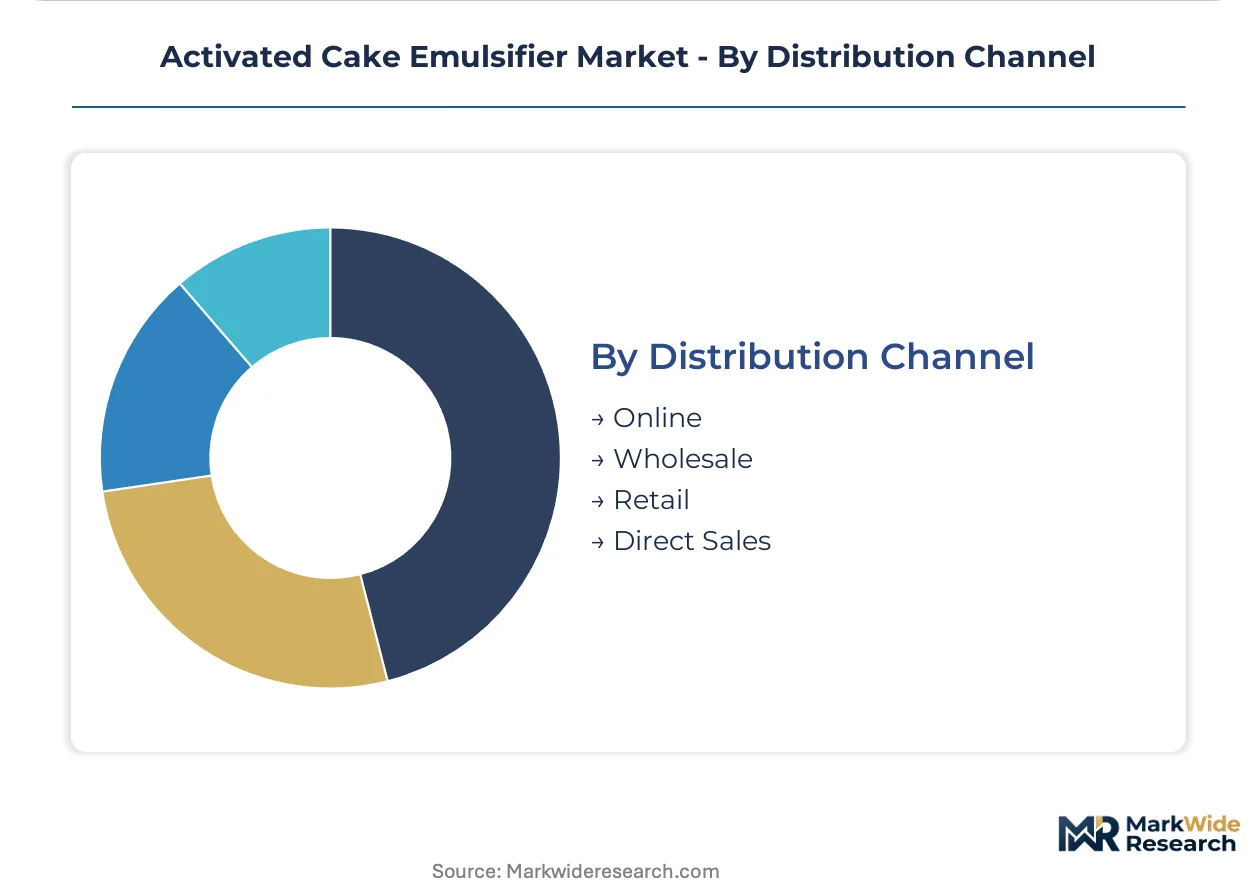
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and inventory velocity priorities.
- Direct Sales:Integrated solution providers embed chemists in customer formulation laboratories for large industrial baking groups. Proximity contracting concentrates contract value and marginalizes transactional alternatives.
- Wholesale:Ingredient distributors serve mid-tier producers with standard powder and liquid formats where technical optimization is secondary to supply assurance.
- Online:Digital procurement platforms gain traction among artisan producers for small-batch concentrate orders with transparent specification documentation.
- Retail:Packaged emulsifier blends for foodservice and small commercial bakeries move through specialty ingredient stores with formulation guidance.
Primary volume channel: Wholesale. Climbing the fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration in Germany anchors European demand for activated cake emulsifiers, with industrial baking clusters around Munich and Hamburg driving premium volume commitments. REACH compliance deadlines and F-Gas Regulation phase-downs are accelerating reformulation timelines across continental markets.
Germany
Industrial baking groups in the Munich-Hamburg corridor consolidate procurement leverage for high-ratio cake systems. EFSA additive safety reassessments create urgency for plant-derived monoglyceride substitution. Bavaria and Baden-Württemberg host underpenetrated mid-tier artisan bakeries lacking technical service support for emulsifier optimization.
United States
GRAS self-determination frameworks enable faster product launches for clean-label emulsifier variants compared to European pre-approval requirements. FDA notification timelines fragment registration portfolios against asynchronous EU standards. Industrial bakeries in the Midwest and Southeast retrofit legacy batch infrastructure for liquid concentrate adoption.
France
Premium chocolate and confectionery applications in the Île-de-France and Rhône-Alpes regions specify emulsifier systems for fat bloom control and polymorph stabilization. EU Green Deal bio-based mandates accelerate R&D investment in microbially derived surfactant alternatives. Paris-based industrial baking groups demand embedded supplier chemists in formulation laboratories.
Netherlands
Specialty chemical producers in the Randstad region scale precision fermentation capacity for microbial lipid-derived monoglycerides. ECHA registration thresholds under REACH compole substitution away from synthetic ester variants. Rotterdam-Antwerp logistics corridors enable efficient distribution of high-active concentrate formats to export-oriented producers.
United Kingdom
Post-Brexit regulatory divergence from EU REACH creates parallel compliance pathways for emulsifier registration. London-Southeast baking clusters prioritize clean-label claims for private-label retail programs. Midlands industrial bakeries face capital expenditure pressures for powder-to-liquid system conversions.
Activated Cake Emulsifier Market Competitive Environment
German producers anchor one tier through integrated oleochemicals platforms; Danish and Dutch specialists hold differentiated positions in precision fermentation and tailored emulsifier blends. The vendor structure concentrates around three strategic archetypes: integrated chemical conglomerates with backward feedstock control, specialty emulsifier houses with formulation expertise, and diversified ingredient groups extending technical service footprints. Competitive moves center on bioreactor capacity expansion for microbial lipid production and direct embedding of chemists in customer laboratories.
Within the integrated chemical tier, BASF SE exemplifies backward integration into monoglyceride feedstocks through captive oleochemicals production. Palsgaard A/S occupies a specialist position representing tailored emulsifier blend capabilities for high-ratio cake systems. Kerry Group plc anchors the technical service expansion archetype, with proximity contracting models concentrating contract value away from transactional distributors.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours Inc. |
| Palsgaard A/S |
| Ingredion Incorporated |
| Wacker Chemie AG |
| Corbion N.V. |
| Cargill Incorporated |
| FrieslandCampina Professional |
| Kerry Group plc |
| Others |
Value Chain & Pricing Dynamics
Precision fermentation scale-up in the Netherlands and Denmark is compressing feedstock cost structures while redrawing supplier concentration maps for plant-derived monoglycerides. This biotechnology transition simultaneously elevates capital barriers for traditional oleochemical producers and creates dual-track sourcing economics across European industrial baking clusters.
Pricing Analysis
Volume concentrates in standard powder formats while margins concentrate in liquid concentrates and high-active systems for artisan applications. Price differentiation rests on formulation complexity and embedded technical service depth, with premium tiers commanding substantial markups for customer-laboratory chemist deployment. Cost compression in standard powder grades is intensifying because Malaysian and Indonesian palm oil supply disruptions feed directly into monoglyceride input costs. Mid-tier artisan bakeries in Bavaria exhibit the highest price sensitivity due to capital constraints for dosing equipment conversion, while large industrial groups in the Munich-Hamburg corridor prioritize performance optimization over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from REACH-registered suppliers now dominate procurement protocols for European industrial baking groups seeking compliance assurance. Geographic supply concentration centers on Germany, the Netherlands, and Denmark, where integrated oleochemicals platforms and precision fermentation bioreactors anchor production. Raw material dependencies draw from Malaysian and Indonesian palm oil estates, European rapeseed processing, and emerging microbial lipid fermentation feedstocks. Single-source vulnerability concentrates in palm-based oleochemical inputs subject to Southeast Asian climate and trade policy disruptions. Distribution runs through Rotterdam-Antwerp logistics corridors for high-active concentrate formats serving export-oriented producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The activated cake emulsifier market functions as a vertical-integration race where control over monoglyceride feedstocks and embedded technical service capabilities determine contract capture. Players are pursuing backward integration into fermentation-derived lipids to escape oleochemical commodity cycles.
For Market Incumbents: Cement formulation expertise advantages by expanding precision fermentation capacity in the Randstad region to displace palm-dependent oleochemicals. Deepen customer captivity through direct chemist embedding in Rhine-Ruhr and northern Italian industrial baking laboratories. Enzyme-based aeration systems from transglutaminase suppliers threaten emulsifier incumbency in high-ratio cake applications; preempt substitution through performance guarantees tied to crumb structure specifications. For New Entrants and Emerging Players: EU Green Deal bio-based mandates in Germany and France open a window for microbial surfactant specialists to capture premium specification tiers. Target underpenetrated mid-tier artisan bakeries in Bavaria and Baden-Württemberg lacking technical service support for emulsifier optimization. Build market entry through digital procurement platforms offering transparent concentrate documentation and small-batch dosing guidance without capital equipment requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified ingredient groups seeking technical service footprint expansion. Long-term viability favors precision fermentation platforms with demonstrated cost parity against oleochemicals and regulatory pre-qualification under REACH. Acquisition targets should demonstrate captive bioreactor capacity and embedded customer relationships in at least two industrial baking corridors. Watch for EFSA additive safety reassessments on polyglycerol esters as a signal for reformulation-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor capacity in the Netherlands displaces Malaysian palm oil dependency for monoglyceride supply. |
| Backward Integration into Oleochemicals | Captive feedstock production insulates BASF from palm price volatility and REACH registration disruptions. |
| Direct Technical Service Embedding | Supplier chemists in customer laboratories concentrate contract value away from Rhine-Ruhr distributors. |
| Clean-Label Reformulation Partnerships | Plant-derived emulsifier development with German industrial bakers accelerates REACH compliance substitution. |
| Confectionery Application Expansion | Fat bloom control specifications in French chocolate production open premium margin pools beyond baking. |
Study Parameters
Independent corroboration across primary interviews with plant managers, procurement leads at industrial baking groups, distribution channel partners, and technical R&D directors, combined with secondary validation through EFSA additive safety databases, REACH registration filings, Cefic chemical industry reports, and customs trade data, underwrites the qualitative findings. Bottom-up demand modeling from end-use application intensity triangulates against top-down supply-side capacity assessments across German, Dutch, and Danish production facilities.
Rate-of-change decomposition across the projection horizon separates volume growth from value expansion by modeling segmentation across product format, application intensity, end-user procurement sophistication, and distribution channel structure. CAGRs derive from iterative convergence between demand-side adoption curves and supply-side capacity commissioning timelines. Forecast inputs incorporate F-Gas Regulation phase-down schedules, EFSA additive reassessment timelines, and precision fermentation cost reduction trajectories.
The model assumes a particular technology adoption path; alternative pathways for microbial lipid-derived emulsifiers would alter the outlook if bioreactor scale-up delays or feedstock cost structures diverge from projected curves. Deviation in EU regulatory enforcement intensity on synthetic ester variants would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market
Food Additives and Ingredients
Fish Tank Water Additives Market