
 Non-Dairy Frozen Dessert Market | 2026-2036
Non-Dairy Frozen Dessert Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Dairy Frozen Dessert Market Intelligence
Demand from health-conscious and allergen-avoidant consumers is rotating away from traditional dairy enthusiasts who are only occasional buyers. Oatly leverages its strong brand identity in oat-based products to capture this consumer shift. Unilever (Breyers) competes by extending its established distribution network into non-dairy lines, while So Delicious Dairy Free specializes in coconut and cashew-based formulations to serve specific taste profiles.
Non-dairy frozen dessert refers to a frozen confection formulated with plant-based milks such as coconut, almond, or soy instead of animal milk. These products require specific hydrocolloids and emulsifiers to achieve a creamy texture and prevent ice crystal formation, mimicking traditional ice cream. Coconut and almond-based products dominate the market by product type, though cashew-based desserts represent a rapidly expanding segment. Supermarkets remain the primary distribution channel, but online sales are accelerating.
Labeling regulations from the US FDA and the European Food Safety Authority (EFSA) mandate clear allergen declarations for nuts and soy. These frameworks govern the use of terms like 'plant-based' and 'dairy-free,' directly impacting product marketing and consumer perception. Stakeholders must continuously monitor evolving international food standards to ensure compliance and maintain consumer trust across different jurisdictions.
Market Dynamics
The market's central dynamic is the tension between advancing food science and evolving consumer health consciousness. Innovations in texturizing plant-based proteins are directly responding to flexitarian consumer demand for desserts that offer sensory parity with traditional dairy without compromising on clean-label ideals.
Growth Catalysts
- Plant-Protein Texturization:Advancements in hydrocolloid and emulsifier systems are enabling manufacturers to replicate the creamy mouthfeel of dairy, overcoming a primary adoption barrier for new consumers.
- Flexitarian Dietary Shift:The rising adoption of flexitarian diets, particularly in European markets like Germany and the United Kingdom, expands the addressable consumer base beyond vegans to a larger health-motivated demographic.
- Regulatory Clarity on Labeling:Clear allergen declaration mandates from the US FDA and EFSA regarding nuts and soy build consumer confidence and streamline marketing for 'dairy-free' and 'plant-based' products.
Market Restraints
- Input Cost Volatility:The market is exposed to price fluctuations in key agricultural inputs, particularly almonds and cashews, which can compress manufacturer margins or necessitate price increases for consumers.
- Sensory Parity Challenges:Achieving the exact taste, texture, and melting properties of traditional dairy ice cream remains a significant technical hurdle, especially with certain plant bases that have strong inherent flavors.
- Supply Chain Bottlenecks:A concentration of supply for specialized hydrocolloids and emulsifiers among a few key producers creates potential sourcing vulnerabilities and pricing power for those suppliers.
Strategic Opportunities
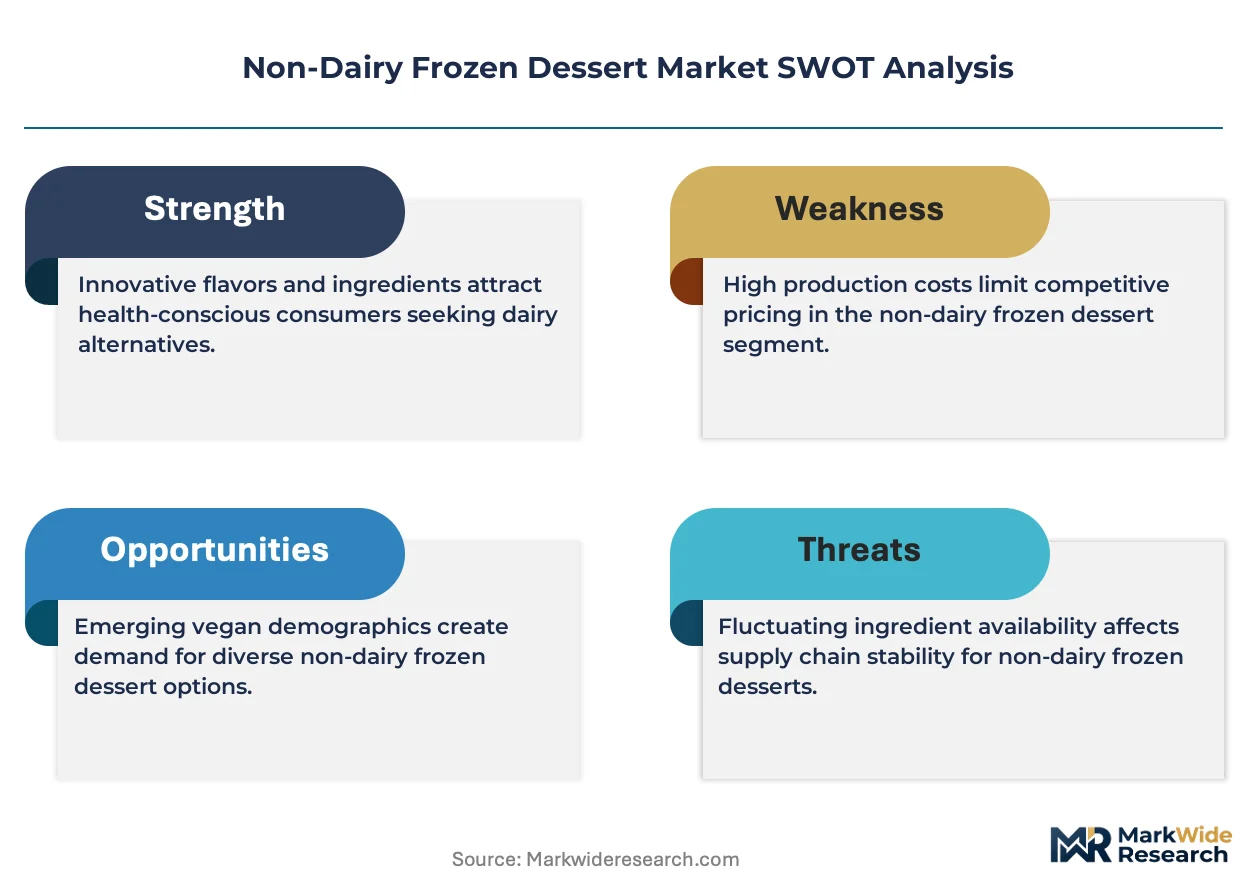
- Geographic Expansion:Untapped demand exists in Asia-Pacific countries with high rates of lactose intolerance, presenting a significant opportunity for market entry and product line introduction.
- Novel Protein Sources:Developing products from alternative bases like fava beans, chickpeas, or sunflower seeds can attract consumers with nut allergies and differentiate brands in a crowded market. *Food Service Channel Growth: Supplying bulk non-dairy dessert formats to restaurants, hotels, and cafes allows for brand exposure and integration into professional culinary applications, creating a new revenue stream.
Industry Challenges
- Allergen Cross-Contamination Risk:Maintaining completely segregated production facilities to prevent cross-contamination and comply with stringent food safety regulations from bodies like the EFSA is capital-intensive and operationally complex.
- Overcoming Consumer Skepticism:A persistent challenge involves convincing traditional dairy consumers that non-dairy alternatives can deliver an equally satisfying dessert experience in terms of taste and texture.
- Ingredient List Complexity:Balancing the need for stabilizers and emulsifiers to achieve desired textures with consumer demand for simple, 'clean-label' ingredient lists creates a formulation and marketing challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Dairy Frozen Dessert Market |
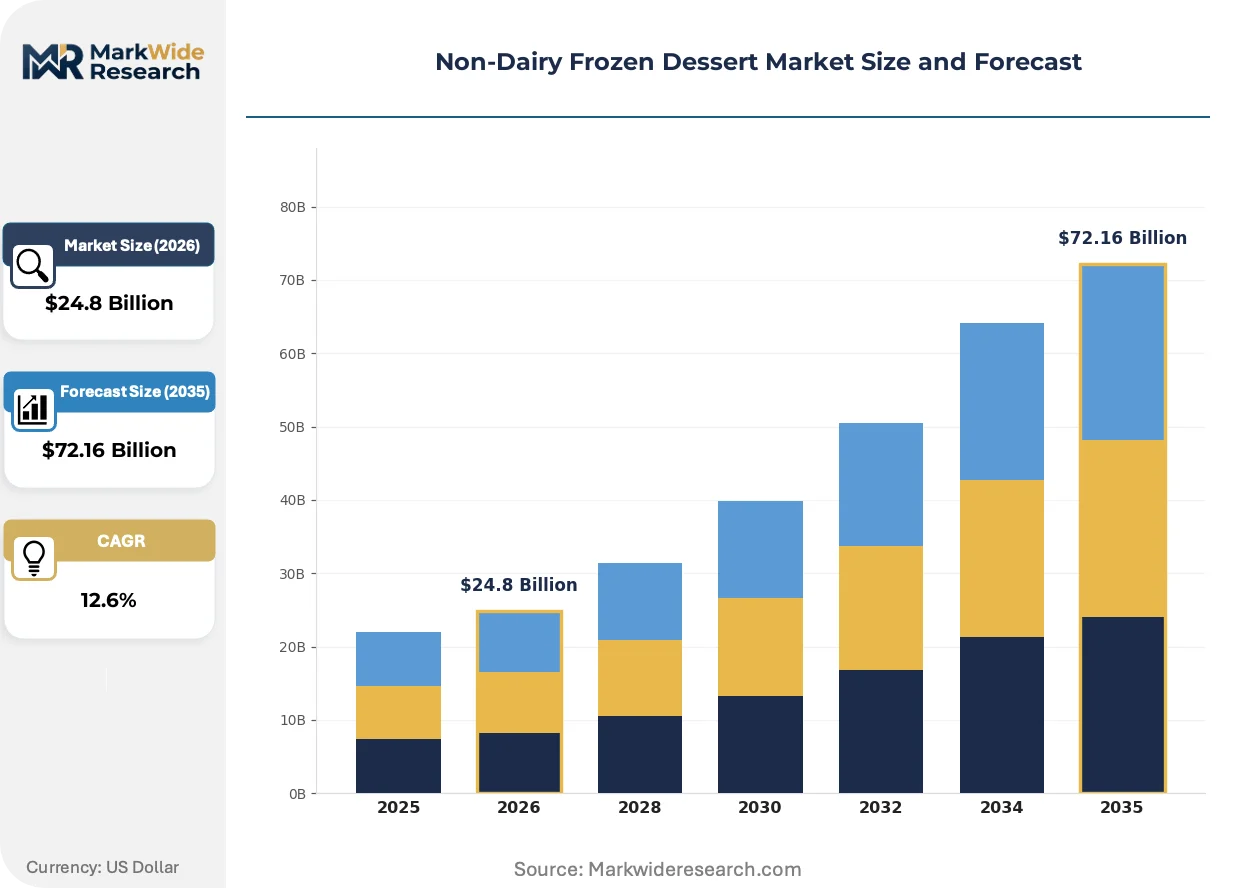
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $72.16 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut, Almond, Soy, Cashew Flavor: Vanilla, Chocolate, Strawberry, Mint Packaging Type: Cup, Tub, Bar, Cone Distribution Channel: Supermarket, Health Food Store, Online, Specialty Retailer |
| Companies Covered | Oatly, Ben & Jerry's, So Delicious Dairy Free, Jeni's Splendid Ice Creams, Coconut Bliss, NadaMoo, Unilever (Breyers), Tofutti Brands, Ripple Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Dairy Frozen Dessert Market Strategic Shifts & Innovations
The industry's trajectory is defined by a scientific pursuit of sensory equivalence with dairy, driven by ingredient innovation. This effort runs parallel to a market-wide adaptation to evolving consumer demands for transparency, sustainability, and simplified product formulations.
Precision fermentation technology allows for the creation of dairy-identical proteins, such as whey and casein, without animal inputs. Food technology firms and innovative startups are leading the adoption of these novel ingredients. This technology is decomposing the fundamental dependency on animal agriculture for key dairy components, paving the way for a new category of animal-free products.
European Food Safety Authority (EFSA) regulations are tightening the criteria for 'free-from' and health-related claims on packaging. This development compels manufacturers to provide robust scientific evidence to substantiate any nutritional advantages advertised for their plant-based desserts. Coconut and almond-based products are particularly impacted, requiring a reassessment of marketing strategies to ensure full compliance.
Consumer purchasing behavior is rotating towards products with shorter, more recognizable ingredient lists. This clean-label movement disrupts the reliance on complex chemical-sounding stabilizers, favoring simpler texturizing agents like starches or fruit purees. The shift is most pronounced in North American and Western European markets, where ingredient scrutiny is a key part of the buying process.
Non-Dairy Frozen Dessert Market Segmentation
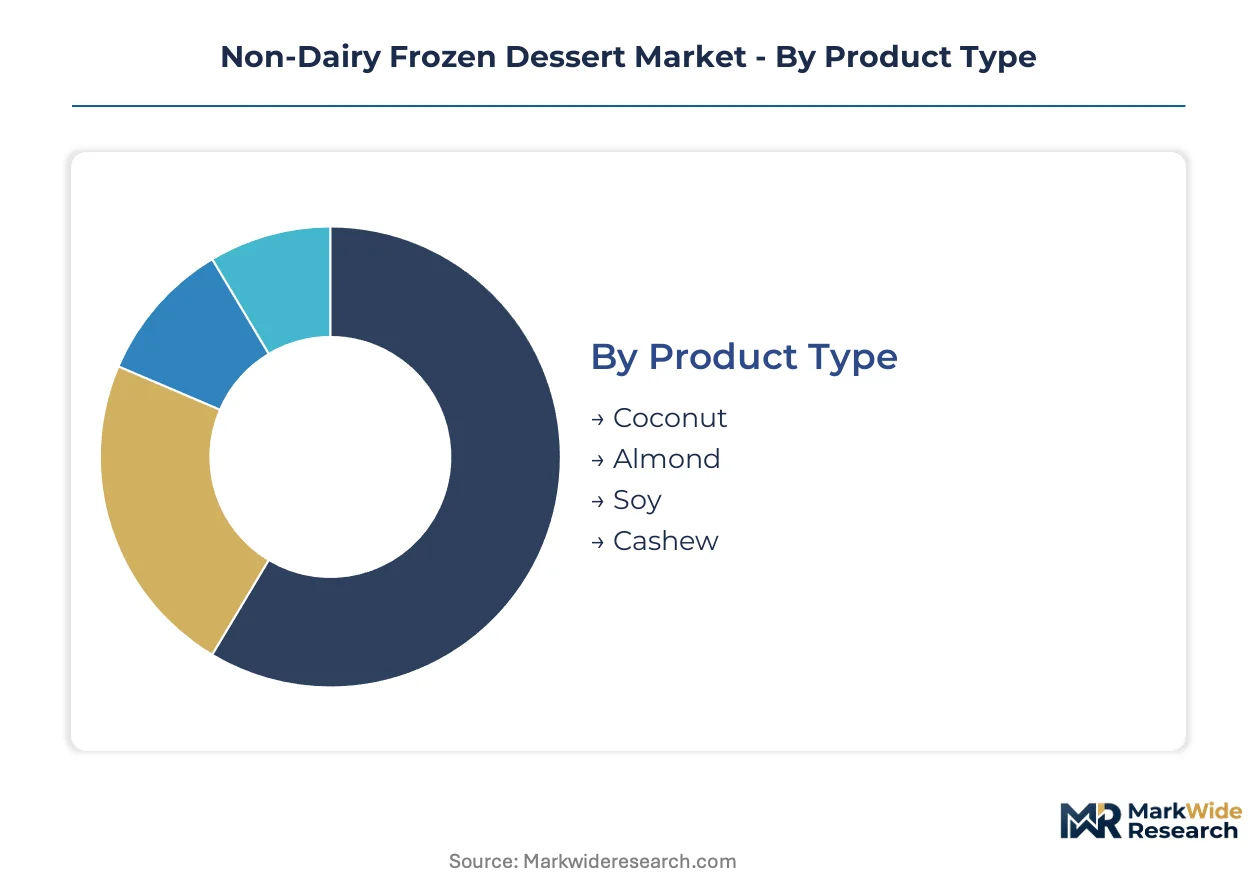
Understanding the non-dairy frozen dessert market's composition reveals distinct consumer preferences and operational realities. Strategic segmentation allows manufacturers to tailor product development and market entry strategies effectively. This analysis dissects the market across product type, flavor, packaging, and distribution to identify commercial opportunities.
Product Type:
Product type segmentation highlights the varying regional popularity and ingredient sourcing dynamics across the global market.
- Coconut:Coconut-based desserts offer a naturally rich and creamy texture due to their high fat content, making them a popular dairy alternative. Demand concentrates in Southeast Asian markets and the United Kingdom, driven by traditional flavor profiles and widespread ingredient availability.
- Almond:Almond milk serves as a versatile base for frozen desserts, providing a neutral flavor profile that blends well with various additions. Consumption is highest in North American markets and Germany, appealing to health-conscious consumers seeking lower-calorie options.
- Soy:Soy-based frozen desserts provide a protein-rich alternative, favored in parts of East Asia for its nutritional benefits and established market presence.
- Cashew:Cashew-based formulations deliver a notably creamy mouthfeel, gaining traction in Western Europe among consumers desiring premium textures.
Coconut commands the established base. The steepest expansion runs through Cashew.
Flavor:
Flavor preferences often reflect diverse consumer palates, ranging from traditional comfort to more adventurous tastes.
- Vanilla:Vanilla flavor, derived from vanilla beans or extracts, provides a classic and universally appealing base for frozen desserts. It commands consistent demand across all age groups in the United States and France, valued for its versatility and familiarity.
- Chocolate:Chocolate-flavored non-dairy desserts incorporate cocoa powder or chocolate liquor, delivering a rich, indulgent experience. This flavor maintains strong popularity in the United Kingdom and Canada, frequently chosen for its widespread appeal as a treat.
- Strawberry:Strawberry flavors offer a fruity and refreshing profile, particularly popular with younger demographics and in warmer climates.
- Mint:Mint flavors, often combined with chocolate, target consumers seeking a distinctive and refreshing dessert experience.
While Vanilla maintains broad appeal, Mint is rapidly carving out a niche.
Packaging Type:
Packaging type influences consumer convenience, portion control, and shelf presence, impacting purchase decisions and consumption patterns.
- Tub:Tubs represent multi-serving formats, designed for at-home consumption and often featuring resealable lids for convenience. This format dominates household purchases in Germany and Australia, driven by family consumption and value considerations.
- Bar:Bars are single-serving, handheld frozen desserts, typically coated and designed for immediate, on-the-go consumption. They are particularly favored in urban areas of the United States and Japan, catering to convenience-seeking individuals.
- Cup:Cups offer individual portions, popular in foodservice channels and for portion-controlled snacking across European markets.
- Cone:Cones provide a traditional ice cream experience, appealing to consumers seeking classic dessert formats, especially in warmer regions.
Household consumption gravitates towards Tub. Individualized portions are gaining significant momentum through Bar.
Distribution Channel:
Distribution channels reflect the market's maturity, consumer access points, and the strategic reach of non-dairy frozen dessert brands.
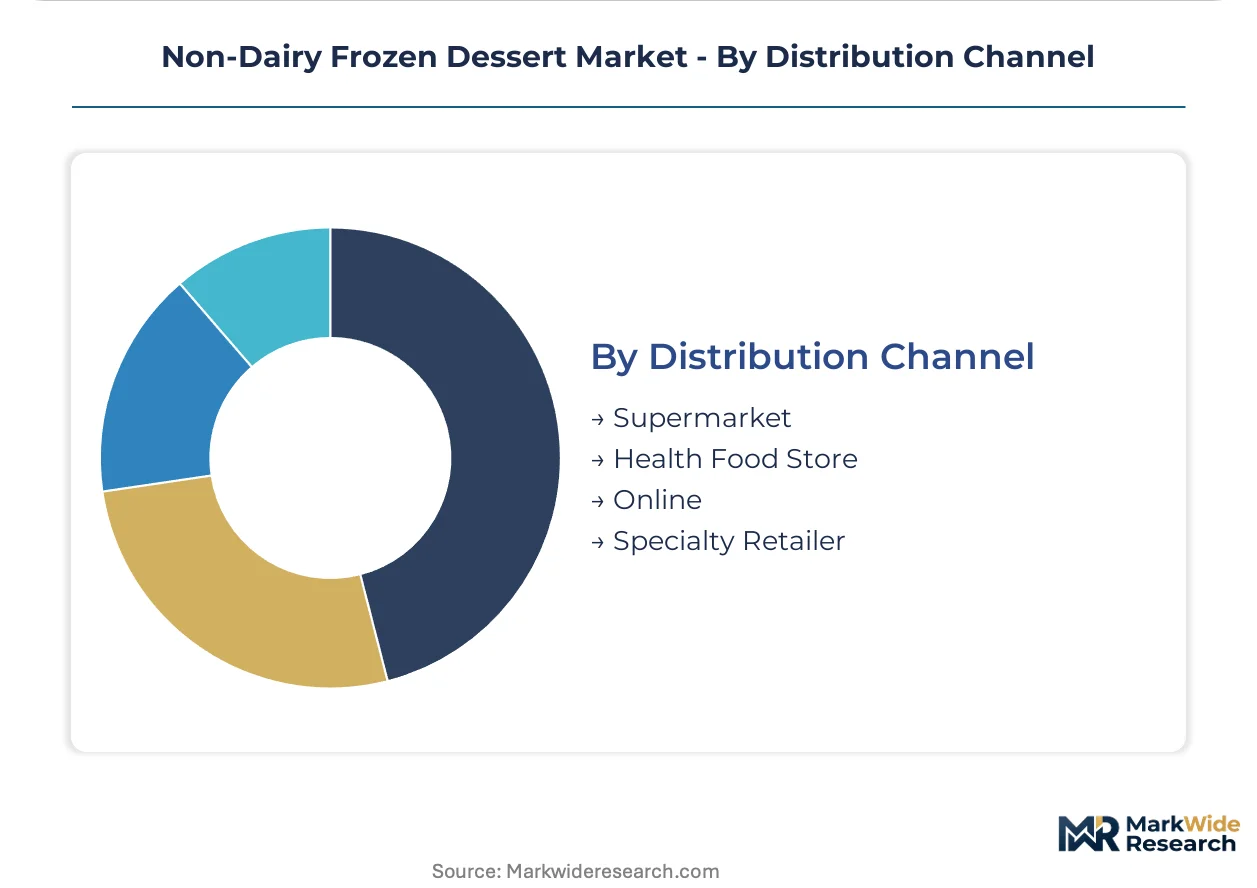
- Supermarket:Supermarkets serve as the primary retail channel, offering broad product selections and competitive pricing to mass consumer bases. This channel maintains dominance across Western Europe and the United States, driven by convenience and established shopping habits.
- Online:Online sales encompass direct-to-consumer and e-retailer platforms, providing convenience and access to a wider product range. This channel is accelerating rapidly in markets like the United Kingdom and Canada, fueled by digital adoption and home delivery services.
- Health Food Store:Health food stores cater to niche consumers seeking organic, allergen-friendly, or specific dietary products, particularly in urban centers.
- Specialty Retailer:Specialty retailers focus on premium or artisanal non-dairy desserts, attracting discerning consumers in high-income demographics.
While Supermarket remains foundational, Online is experiencing the most dynamic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of specialized plant-based ingredients from European producers often serves diverse consumer bases in North American markets. This trade supports manufacturers seeking specific hydrocolloids and emulsifiers for non-dairy formulations. Such ingredient exchanges facilitate the global expansion of innovative frozen dessert products.
Germany
German consumers increasingly adopt flexitarian diets, driving demand for innovative non-dairy frozen desserts. EFSA regulations mandate clear labeling for 'plant-based' products, building consumer trust. Berlin's vibrant food tech scene fosters startups focused on novel ingredient development for creamy textures.
United Kingdom
United Kingdom consumers show strong demand for chocolate-flavored non-dairy frozen desserts. The UK Food Standards Agency (FSA) enforces strict allergen declaration guidelines for nut and soy-based products. London's dynamic urban areas exhibit high purchasing of convenient single-serving bars.
United States
American consumers maintain consistent demand for classic vanilla-flavored non-dairy frozen desserts across all age groups. US FDA labeling regulations govern the use of 'dairy-free' and 'plant-based' terms, impacting product marketing. California's robust health culture fosters innovation in almond-based and lower-calorie formulations.
Japan
Japanese consumers increasingly favor convenient single-serving non-dairy frozen dessert bars for on-the-go consumption. Japan's Ministry of Health, Labour and Welfare (MHLW) sets stringent standards for food additives. Tokyo's dense urban environment drives demand for innovative packaging solutions and rapid online delivery services.
Australia
Australian households predominantly purchase multi-serving non-dairy frozen dessert tubs for at-home consumption. Food Standards Australia New Zealand (FSANZ) regulations provide clear guidelines for allergen declarations. Melbourne and Sydney's family-oriented markets exhibit strong demand for value-driven, larger format packaging.
Non-Dairy Frozen Dessert Market Key Industry Players
Listed leaders compete with private specialists across product innovation and distribution reach. The non-dairy frozen dessert market exhibits a tiered structure, with established food conglomerates alongside agile, plant-based focused brands. Strategic archetypes include large consumer packaged goods companies leveraging existing infrastructure and specialized startups focused on novel ingredients and specific allergen-free formulations. Competitive moves center on portfolio diversification into new plant bases and geographic expansion into untapped markets like Asia-Pacific.
At the scale-driven end, Unilever (Breyers) exemplifies a large conglomerate extending its established distribution network into non-dairy lines, leveraging its existing market presence. Oatly represents a brand with a strong identity in oat-based products, successfully capturing the consumer shift towards plant-based alternatives through focused messaging. So Delicious Dairy Free, occupying a position of specialization, focuses on coconut and cashew-based formulations to serve specific taste profiles and allergen-avoidant consumers. These companies anchor different competitive strategies, from mass-market penetration to niche segment leadership, within the evolving non-dairy frozen dessert market.
| Leading Market Players |
|---|
| Oatly |
| Ben & Jerry's |
| So Delicious Dairy Free |
| Jeni's Splendid Ice Creams |
| Coconut Bliss |
| NadaMoo |
| Unilever (Breyers) |
| Tofutti Brands |
| Ripple Foods |
| Others |
Cost & Logistics Intelligence
Plant-based protein texturization, as a named substitution dynamic, is simultaneously reshaping supply geography by demanding specialized agricultural inputs and driving pricing economics through innovation costs. This shift influences sourcing from diverse regions for plant bases and specialized chemical producers for hydrocolloids.
Pricing Analysis
Precision fermentation technology, representing a next-generation approach, commands a premium over established plant-based formulations. The market exhibits premium-mid-economy pricing differentiation, driven by brand premium and specialized ingredient formulations like cashew-based creaminess. Price erosion runs through economy-tier products due to input cost volatility and intense competition. Health-conscious flexitarians demonstrate lower price sensitivity for premium, innovative options, while budget-conscious mass-market buyers remain highly price-sensitive.
Supply Chain Analysis
The limited number of specialized hydrocolloid and emulsifier producers underwrites pricing power for these key suppliers. Geographic supply concentrations for raw materials include almonds from California, cashews from Vietnam, and coconuts from Southeast Asia. Key raw material dependencies include almonds, cashews, and specialized hydrocolloids. Single-source vulnerability for specialized ingredients presents a significant supply chain risk. Distribution runs through supermarkets as the primary retail channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-dairy frozen dessert market is experiencing a cyclical recovery, driven by sustained consumer health consciousness. This reflects a broader societal shift towards plant-based diets.
For Market Incumbents: Shield existing market share through continuous product innovation in texture and flavor. Invest in proprietary plant-protein texturization technologies to counter emerging startups leveraging novel protein sources. Expanding distribution networks into foodservice offers a critical lever for market penetration against margin pressure.
For New Entrants and Emerging Players: Allergen-free certification fast-tracks offer a compelling entry point for new brands. Develop products from novel protein sources like fava beans or sunflower seeds, targeting consumers with specific nut allergies. Asia-Pacific markets, with high lactose intolerance, present a penetrable geographic segment. Partnering with health food stores and online specialty retailers provides an effective go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward agile, technology-driven startups specializing in ingredient science. The market shows strong long-term viability, underpinned by evolving dietary preferences and food technology advancements. Companies with patented precision fermentation capabilities or unique plant-base formulations represent attractive acquisition targets. Watch for regulatory approvals of novel dairy-identical proteins as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Introduces new plant bases like fava beans, attracting consumers with diverse dietary needs. |
| Distribution Channel Expansion | Integrates products into foodservice, increasing brand exposure and revenue streams. |
| Precision Fermentation Investment | Develops animal-free dairy proteins, achieving sensory equivalence with traditional dairy. |
| Clean Label Formulation | Simplifies ingredient lists, responding to consumer demand for transparency and natural products. |
| Geographic Market Entry | Targets lactose-intolerant populations in Asia-Pacific, unlocking significant untapped demand. |
Research Approach
The analysis maps non-dairy frozen dessert product types, flavors, and distribution channels, each validated through primary interviews with R&D directors, marketing managers, and ingredient suppliers. Secondary data from company annual reports, food regulatory filings, and trade association publications informed initial hypotheses. Bottom-up data from company disclosures and top-down market sizing informed the overall market structure through triangulation.
Consistency checks against external industry benchmarks ensured forecast reliability across the analysis window. A multi-factor analytical framework integrated historical growth patterns with projected consumer trends. Market segmentation modeled by product type, flavor, packaging, distribution channel, and regional consumer preference. Compound annual growth rates derived through regression analysis of demand drivers and supply-side capacity, incorporating plant-based ingredient pricing and regulatory changes in food labeling.
Underlying assumptions cover stable regulatory environments and consistent consumer shifts, with deviation risk concentrated in agricultural commodity price volatility. Unexpected advancements in dairy alternatives or unforeseen global supply chain disruptions could revise forecasts. Practitioners should keep alternative scenarios live as food science innovations and consumer preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market