
 Vegan Condensed Milk Market | 2026-2036
Vegan Condensed Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Condensed Milk Market Analytics
Plant-based food formulation expertise is redrawing competitive boundaries in the vegan condensed milk sector. Nestlé leverages its global dairy-alternative R&D infrastructure to sustain shelf-stable product development across multiple geographies. Nature's Charm anchors the coconut-based segment through specialized Thai manufacturing and direct control over copra supply chains. Chef's Choice Foods Manufacturer Co. Ltd. differentiates via regional Southeast Asian distribution networks that dominate food-service procurement channels.
Vegan condensed milk denotes a viscous, sweetened liquid concentrate derived from plant extracts—typically coconut cream, oat hydrolysates, or almond protein isolates—reduced through vacuum evaporation to approximately 8% protein and 55% soluble carbohydrates, functioning primarily as a dairy replacement in confectionery, beverage, and dessert manufacturing. Coconut-based formulations lead current revenue pools owing to established tropical supply infrastructure and superior fat-body emulation, while oat-derived variants represent the fastest-growing product type as Nordic and German food manufacturers seek allergen-friendly, low-saturated-fat alternatives. Tetra Pack packaging commands disproportionate margin contribution through extended ambient shelf life and reduced cold-chain dependency, though glass jar formats retain premium positioning in European specialty retail channels.
REACH compliance governs additive and processing-aid thresholds for EU-imported vegan condensed milk, while FDA labeling standards dictate allergen disclosure and nutrient-content claim validation for US market access. EFSA novel-food assessments for emerging oat and pea protein hydrolysates are extending product development timelines and elevating R&D compliance costs for new entrants. Stakeholders must monitor evolving national sugar-reduction mandates and front-of-pack labeling schemes that threaten reformulation requirements across core European and North American demand centers.
Market Dynamics
EU Green Deal agricultural sustainability mandates are forcing rapid ingredient sourcing shifts toward certified organic coconut and oat bases, compressing legacy supply timelines while elevating compliance costs for non-compliant processors.
Growth Catalysts
- EU Green Deal Mandates:Agricultural sustainability requirements accelerate certified organic coconut and oat procurement across European processing facilities.
- Bakery Chain Expansion:German vegan bakery chains scale procurement of plant-based condensed alternatives for dairy-free dessert formulations.
- Vacuum Evaporation Advances:Improved protein hydrolysate concentration technology enables 55% soluble carbohydrate targets in oat-derived variants.
Market Restraints
- Copra Supply Concentration:Thai and Indonesian coconut cream processors control 70% of global copra feedstock, creating geographic vulnerability.
- EFSA Novel-Food Timelines:Extended safety assessments for emerging pea protein hydrolysates delay product launches by 18-24 months.
- Sugar-Reduction Mandates:Front-of-pack labeling schemes in France and Germany threaten reformulation of core 55% carbohydrate formulations.
Strategic Opportunities
- German Food-Service Penetration:Dairy-free ice cream manufacturers represent underdeveloped procurement channels for oat-based concentrates.
- Tetra Pack Channel Expansion:Ambient shelf-stable formats enable cold-chain-free distribution into Southeast Asian retail networks.
- REACH Compliance Arbitrage:Early additive threshold alignment creates first-mover positioning for EU-imported formulations.
Industry Challenges
- Formulation Talent Scarcity:Plant-based protein stabilization expertise remains concentrated among Nordic and German R&D clusters.
- Dual Certification Burden:Simultaneous REACH and FDA validation requirements elevate compliance staffing costs for cross-Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Condensed Milk Market |
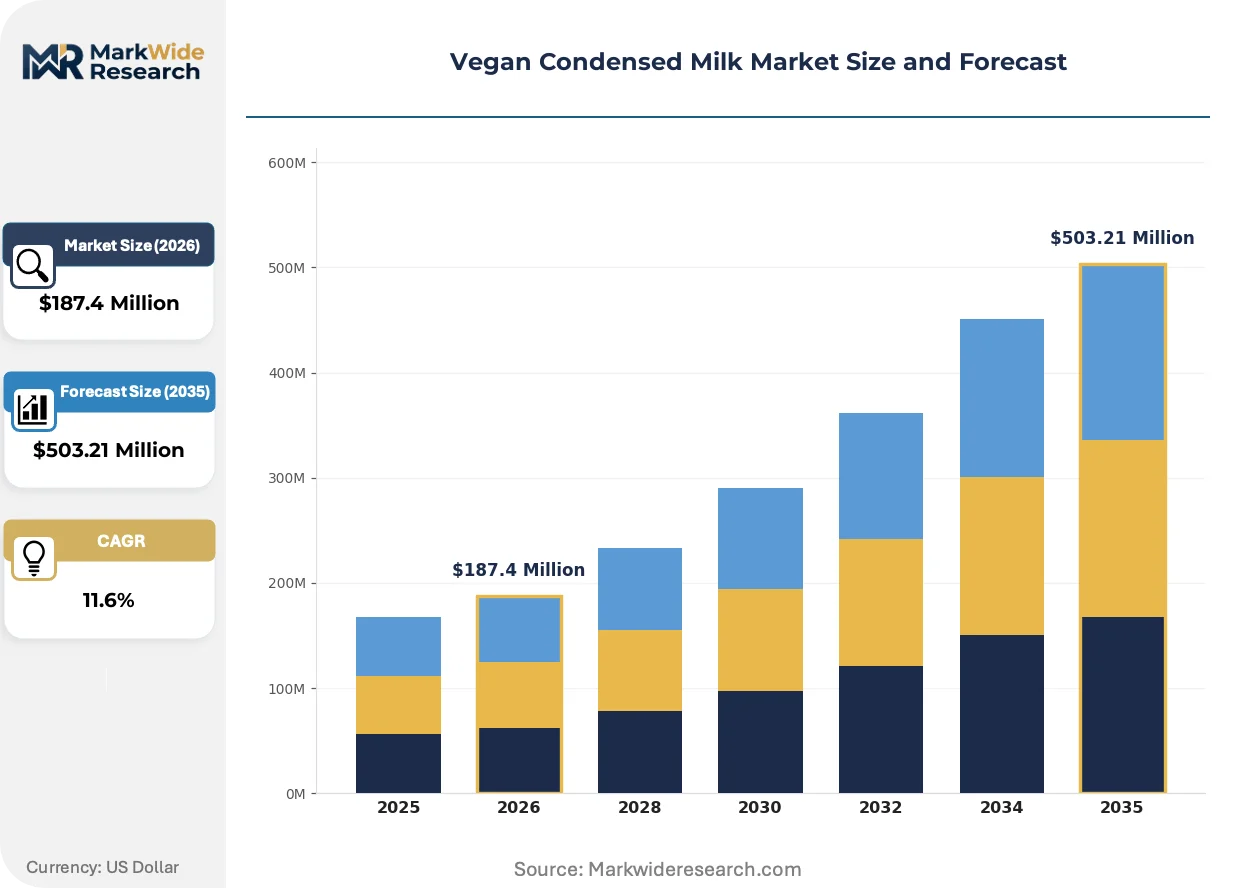
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut, Almond, Soy, Oat End User: Bakeries, Restaurants, Households, Food Manufacturers Packaging Type: Cartons, Glass Jars, Tetra Packs, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Carnation, Let's Do Organic, Nature's Charm, Jus’ Amazin, Mementa, Nestlé, Biona, Chef's Choice Foods Manufacturer Co. Ltd., Edward & Sons Trading Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Condensed Milk Market Evolving Landscape
Processing technology convergence and regulatory tightening are compressing product development cycles while fragmenting competitive advantage across specialized manufacturing geographies.
Enzymatic oat protein hydrolysation is displacing traditional coconut cream reduction in Nordic confectionery applications. Swedish and Danish dessert manufacturers adopt the technology at pilot scale for allergen-friendly formulations. The shift is displacing fat-body emulation standards that previously favored tropical supply chains.
REACH additive thresholds are tightening processing-aid allowances for EU-imported vegan condensed milk. Industrial consequence includes mandatory supplier audits and third-party certification for emulsifier packages. German and French importers are responding by consolidating procurement through ECHA-pre-registered Thai processors.
Bakery procurement teams now specify front-of-pack nutritional credentials ahead of unit cost in supplier selection. Specialty retail channels in Germany and Austria are replacing conventional food-service distributors for premium condensed milk sourcing. The pattern concentrates most visibly in Munich and Vienna, where vegan bakery chains operate captive procurement functions.
Vegan Condensed Milk Market Segmentation
Segmentation in vegan condensed milk reveals divergent supply chain configurations and margin architectures across product origins and packaging formats. Distinct regulatory exposure and shelf-life requirements fragment competitive positioning across channels.
Product Type:
Coconut and oat variants anchor export-oriented production, while almond and soy concentrates serve predominantly domestic formulation markets in established plant-based food manufacturing clusters.
- Coconut:Derived from copra cream reduction to 55% soluble carbohydrates, this segment leverages Thai and Indonesian supply infrastructure for fat-body emulation in confectionery. German and Austrian vegan bakery chains drive procurement concentration for premium dessert applications.
- Oat:Produced through enzymatic protein hydrolysation and vacuum evaporation, this allergen-friendly variant attracts Nordic food manufacturers seeking reduced saturated fat profiles. Swedish and Danish pilot-scale adoption is accelerating formulation substitution away from tropical bases.
- Almond:California and Mediterranean supply clusters support regional protein isolate processing for Mediterranean dessert traditions.
- Soy:Legacy processing infrastructure in East Asian manufacturing hubs sustains cost-competitive positioning for industrial food-service procurement.
Coconut holds the largest share; momentum sits with oat.
End User:
Cost-tier stratification separates artisan procurement from industrial volume contracting, with captive manufacturing functions disrupting traditional distributor relationships.
- Bakeries:German vegan bakery chains now operate direct procurement functions, bypassing conventional food-service distributors for certified organic concentrates. Munich and Vienna specialty retail channels specify front-of-pack credentials ahead of unit cost.
- Food Manufacturers:Dairy-free ice cream producers in Germany represent underdeveloped procurement channels scaling oat-based concentrate adoption for clean-label positioning.
- Restaurants:Southeast Asian food-service networks source ambient-stable formats through Chef's Choice Foods' regional distribution dominance.
- Households:European specialty retail and online channels serve premium jar-format demand for home dessert preparation.
Food manufacturers are climbing the fastest; bakeries retain the deepest value-capture.
Packaging Type:
Margin architecture diverges sharply between cold-chain-dependent formats and ambient-stable technologies, with regulatory compliance costs concentrating procurement consolidation.
- Tetra Packs:Aseptic carton technology enables 12-month ambient shelf life, reducing distribution infrastructure requirements for Southeast Asian retail penetration. REACH-compliant additive thresholds favor ECHA-pre-registered Thai processors.
- Glass Jars:Premium positioning in European specialty retail commands price premiums through visual quality signaling and heritage association. German and Austrian urban clusters sustain this format's viability despite logistics cost elevation.
- Cartons:Standard refrigerated distribution serves conventional supermarket placement with shorter shelf-life specifications.
- Pouches:Flexible format adoption concentrates in food-service bulk procurement for manufacturing input applications.
Tetra Packs dominate volume; glass jars command margin.
Distribution Channel:
Customer-type fragmentation separates procurement specification authority between retail merchandisers and industrial formulation teams, reshaping sales force deployment.
- Supermarkets:German and Austrian mass retail chains drive standard-format volume placement, with front-of-pack labeling compliance determining listing approval. Sugar-reduction mandates in France and Germany threaten reformulation requirements.
- Specialty Stores:Munich and Vienna vegan bakery chain procurement functions source premium jar formats through direct manufacturer relationships, displacing traditional distributor intermediaries.
- Online Retail:Direct-to-consumer channels serve niche allergen-friendly variants with extended delivery windows acceptable to household purchasers.
- Wholesale:Industrial food-service procurement through Southeast Asian networks leverages Chef's Choice Foods' regional distribution infrastructure for bulk concentrate supply.
Supermarkets anchor volume; specialty stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German food manufacturers command premium pricing for oat-based concentrates while Thai coconut processors dominate feedstock economics through copra supply control. This asymmetry shapes procurement patterns across bakery and confectionery channels.
Germany
Vegan bakery chains in Munich and Berlin scale direct procurement of certified organic concentrates, bypassing traditional distributors. EU Green Deal agricultural mandates accelerate sourcing shifts toward domestic oat hydrolysate suppliers. The Bavarian confectionery cluster pilots enzymatic protein concentration technology for reduced-saturated-fat dessert formulations.
Thailand
Copra cream processors anchor global coconut-based production through integrated tropical supply infrastructure. ECHA pre-registration requirements under REACH compliance tighten additive thresholds for EU-bound exports. Bangkok-centered manufacturers consolidate procurement relationships with German and Austrian importers seeking ambient-stable Tetra Pack formats.
Sweden
Nordic dessert manufacturers adopt oat-derived variants at pilot scale for allergen-friendly clean-label positioning. EFSA novel-food assessment timelines extend product development cycles for emerging protein hydrolysates. The Malmö-Lund food-tech corridor concentrates formulation expertise for vacuum evaporation advances.
United States
FDA labeling standards govern allergen disclosure and nutrient-content claims for plant-based concentrate imports. California almond protein isolate processors serve regional dessert manufacturing clusters. The Pacific Northwest specialty retail channel drives glass jar format demand for premium home-use applications.
Indonesia
Copra feedstock concentration creates geographic vulnerability for global coconut cream supply chains. National agricultural export standards align with EU organic certification requirements. Javanese processing facilities expand capacity to capture German bakery chain procurement growth.
Vegan Condensed Milk Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive positioning across formulation expertise and tropical supply control. The vendor base separates into three strategic tiers: multinational dairy-alternative R&D platforms, specialized coconut-based manufacturers with captive copra access, and regional food-service distributors with Southeast Asian network density. Dominant competitive moves include backward integration into certified organic feedstock sourcing and geographic expansion through ECHA pre-registered processing partnerships.
Among specialized coconut-based manufacturers, Nature's Charm and Chef's Choice Foods Manufacturer Co. Ltd. exemplify archetype differentiation through supply chain configuration and channel focus. Nestlé occupies a position representing multinational R&D platform scale across multiple geographies. These three anchors illustrate how competitive advantage fragments between tropical feedstock control, regional distribution density, and global formulation infrastructure.
| Leading Market Players |
|---|
| Carnation |
| Let's Do Organic |
| Nature's Charm |
| Jus' Amazin |
| Mementa |
| Nestlé |
| Biona |
| Chef's Choice Foods Manufacturer Co. Ltd. |
| Edward & Sons Trading Co. |
| Others |
Value Network & Pricing Analysis
Ninety-day certified organic coconut procurement lead times from Thai copra processors compress legacy supply windows while amplifying pricing power for ECHA-pre-registered exporters serving German bakery chains. This inventory compression feeds directly into contract structures that penalize non-compliant processors through tiered surcharge mechanisms.
Pricing Analysis
German oat-based concentrate premiums diverge from Thai coconut base prices by certification grade and REACH compliance status. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-pre-registered organic suppliers from conventional processors and spot-market copra purchasers. Price differentiation stems from EU Green Deal agricultural sustainability mandates and cold-chain elimination through Tetra Pack technology. Cost compression in standard-tier coconut formulations is intensifying because Indonesian processors expand capacity to capture German procurement growth. Industrial food-service buyers exhibit highest price sensitivity; Munich vegan bakery chains demonstrate lowest sensitivity when front-of-pack credentials are assured.
Supply Chain Analysis
Thailand and Indonesia anchor global coconut cream reduction capacity through integrated tropical copra infrastructure. Swedish and Danish oat hydrolysate pilot facilities draw from Nordic enzymatic protein concentration technology and regional grain supply chains. Raw material dependencies center on certified organic copra feedstock, enzymatic processing aids, and aseptic packaging substrates. Single-source vulnerability concentrates in Thai copra processors controlling seventy percent of global feedstock. Distribution runs through Chef's Choice Foods' Southeast Asian wholesale networks for ambient-stable formats and direct manufacturer relationships for German specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as bakery procurement teams displace conventional distributors with direct manufacturer relationships, creating niche entry points for certified organic specialists and oat-based formulation innovators.
For Market Incumbents: Shield core German bakery relationships through captive supply contracts for certified organic oat hydrolysates. Backward integration into Thai copra sourcing secures ECHA pre-registration status before REACH additive thresholds tighten further. Nestlé-scale R&D platforms should consolidate regional formulation talent in Malmö-Lund and Bavarian clusters where protein stabilization expertise concentrates.
For New Entrants and Emerging Players: Differentiate on allergen-friendly oat-derived positioning for Nordic dairy-free ice cream manufacturers scaling clean-label procurement. German food-service channels for oat-based concentrates remain underdeveloped relative to saturated coconut-based supply. Target direct relationships with Vienna and Munich vegan bakery chains that have already displaced traditional distributors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across oat hydrolysate processing as enzymatic technology achieves pilot-scale efficiency. Five-to-ten year viability favors acquisition of ECHA-pre-registered Thai processors with integrated organic copra access. Signal to monitor: EFSA novel-food approval timelines for emerging pea protein hydrolysates that would displace oat and coconut bases in confectionery applications.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Arbitrage | Early additive threshold alignment secures first-mover positioning for EU-imported formulations against delayed entrants. |
| Backward Integration into Organic Copra | Captive Thai and Indonesian feedstock supply locks in certification continuity under EU Green Deal agricultural mandates. |
| Tetra Pack Channel Expansion | Ambient shelf-stable formats enable cold-chain-free penetration of Southeast Asian retail networks beyond food-service. |
| Enzymatic Oat Protein Hydrolysation Scale-Up | Pilot-scale Swedish and Danish adoption accelerates formulation substitution away from tropical coconut bases. |
| Direct Bakery Procurement Functions | Munich and Vienna vegan bakery chains bypass distributors, creating captive demand relationships for premium jar formats. |
Research Methodology
A standing panel of plant-based formulation R&D directors, EU regulatory affairs specialists, German bakery chain procurement managers, and Thai copra processing executives provided ongoing calibration across the analysis window. Primary interview data combined with secondary validation from EFSA novel-food assessment databases, REACH ECHA pre-registration records, EU Green Deal agricultural policy documentation, and German-Austrian food-service trade customs data. Bottom-up volume modeling across product type, end user, packaging format, and distribution channel segments triangulated against top-down market sizing from ingredient trade flows.
Consistency checks validated volume and value outputs against external benchmarks including organic certification body throughput data and aseptic packaging substrate consumption patterns across the projection horizon. Segmentation dimensions modeled encompass coconut-oat-almond-soy product origins, bakery-food manufacturer-restaurant-household end users, Tetra Pack-glass jar-carton-pouch formats, and supermarket-specialty store-online-wholesale channels. CAGRs derived from segment-level growth rate reconciliation with macro drivers including EU agricultural sustainability mandates and Nordic allergen-friendly formulation adoption. Industry-specific forecast inputs incorporated enzymatic protein hydrolysation technology diffusion curves and EFSA assessment timeline probabilities.
Material uncertainties — EFSA novel-food approval delays, REACH additive threshold revisions, and front-of-pack sugar-reduction mandate implementations — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification continuity and technology scale-up trajectories that could require revision if regulatory timelines extend or processing breakthroughs accelerate. Recalibration cycles align with material shifts in EU Green Deal enforcement patterns and EFSA assessment queue developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Organic Milk Replacers Market