
 Middle East Dairy Alternatives Market | 2026-2036
Middle East Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Dairy Alternatives Market Insights
Halal certification alignment with plant-based processing standards is collapsing the supplier pool to facilities capable of dual-compliant production. Almarai Company leverages its chilled distribution network across Saudi Arabia to sustain refrigerated oat milk availability. Danone SA competes through fortified soy formulations that meet Gulf nutritional labeling thresholds. Oatly Group AB differentiates by controlling specialty coffee shop channels in Dubai and Riyadh.
Middle East dairy alternatives comprise plant-derived beverages formulated from aqueous extractions of oilseeds, cereals, or nuts, typically homogenized to particle sizes below five microns for colloidal stability and mouthfeel parity with bovine milk. These formulations serve lactose-intolerant consumers, vegan diet adherents, and foodservice operators seeking menu flexibility across the Gulf Cooperation Council. Almond milk and oat milk anchor retail shelf space in UAE supermarkets, where margin pools favor premium-positioned unsweetened and organic variants. Online retail channels for dairy alternatives are expanding fastest, though health food stores retain higher per-unit profitability due to curated assortment and educated consumer traffic.
Saudi Arabia's SFDA and the UAE's MOHAP enforce distinct labeling and nutritional claim standards for plant-based beverages, creating compliance fragmentation that favors multi-market operators with regulatory affairs capacity. Egypt's EOS and Jordan's JSMO standards add further certification layers for brands targeting North African and Levantine expansion. Stakeholders must monitor evolving fortification requirements and halal supply chain documentation as gatekeepers to foodservice procurement contracts across the region.
Market Dynamics
Halal certification alignment with plant-based processing standards is collapsing the supplier pool to facilities capable of dual-compliant production, forcing capital reallocation toward segregated production lines and dedicated supply chain documentation systems across Gulf markets.
Growth Catalysts
- SFDA Labeling Mandates:Saudi Arabia's tightened nutritional disclosure requirements for non-dairy beverages are accelerating reformulation investments that improve protein fortification and shelf stability, creating quality differentiation among compliant suppliers.
- Foodservice Procurement Expansion:Hotel chains and airline catering divisions across the Gulf are expanding plant-based beverage procurement as part of broader menu diversification strategies targeting lactose-intolerant travelers and vegan diet adherents.
- Enzymatic Hydrolysis Advances:Novel enzyme treatments for oat base processing are reducing viscosity without additive dependence, enabling cleaner label positioning that commands retail premium in UAE supermarkets.
Market Restraints
- Input Cost Volatility:Almond kernel prices fluctuate with California harvest yields and water allocation disputes, compressing margin pools for Middle East importers dependent on US supply.
- Supply Concentration Risk:Specialty oat milling capacity concentrates in Nordic and North American facilities, creating lead time vulnerability for Gulf-based brands lacking backward integration into grain sourcing.
- Technical Limitation:Colloidal stability below five microns remains difficult to achieve in ambient-stable formulations without stabilizer systems that conflict with clean label positioning sought by UAE health food retailers.
Strategic Opportunities
- Egyptian Market Entry:Underpenetrated retail infrastructure in Cairo and Alexandria offers first-mover positioning for ambient-stable soy and oat variants ahead of EOS regulatory harmonization with Gulf standards.
- E-Commerce Channel Development:Direct-to-consumer subscription models for refrigerated oat milk are bypassing traditional supermarket slotting fee structures, capturing margin pools previously allocated to retail intermediaries.
- Fortification Incentive Alignment:UAE MOHAP nutritional labeling thresholds for calcium and vitamin D create regulatory tailwinds for brands investing in micronutrient premix integration during base formulation.
Industry Challenges
- Halal Supply Chain Documentation:Dual-compliant facilities must maintain segregated ingredient receipt, processing, and packaging records that extend certification timelines and audit costs for multi-market operators.
- Chilled Distribution Infrastructure:Refrigerated oat milk availability depends on cold chain density that remains patchy outside Saudi Arabia's major urban corridors, limiting geographic expansion for perishable-positioned brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Dairy Alternatives Market |
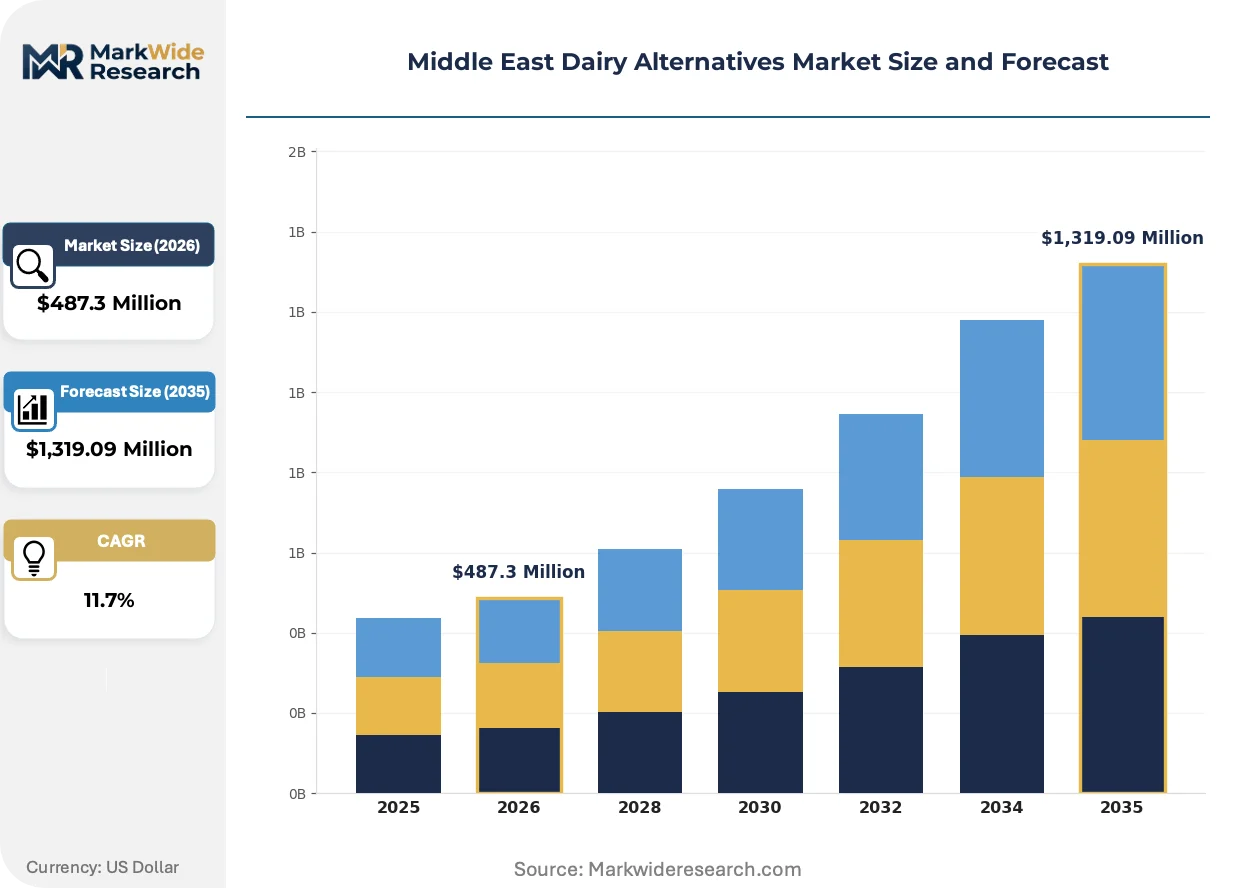
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Coconut Milk, Oat Milk Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Consumer Segment: Health-Conscious Consumers, Vegan Diet Followers, Lactose Intolerant Individuals, General Consumers Formulation Type: Flavored, Unsweetened, Organic, Fortified |
| Companies Covered | Almarai Company, SADAFCO, Juhayna Food Industries, Alpro Middle East, Danone SA, Oatly Group AB, Lactalis Group, Chobani LLC, Flora Food Group, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Dairy Alternatives Market Trends and Innovations
Enzymatic processing advances and regulatory fortification mandates are reconfiguring formulation priorities across the Middle East, while channel fragmentation creates new entry points beyond traditional retail dominance.
High-pressure homogenization systems operating above 200 MPa are achieving particle size distributions below two microns without stabilizer dependence. Specialty coffee chains in Dubai and Riyadh are specifying these textures for latte art performance. Enzyme-assisted oat processing is supplanting traditional milling approaches that required hydrocolloid addition for mouthfeel parity.
MOHAP's evolving nutritional claim thresholds for protein and micronutrient content are forcing reformulation cycles that favor integrated premix suppliers. Brands must resubmit label approvals biannually under tightened documentation requirements. Fortified soy formulations meeting these thresholds are capturing shelf space from unfortified competitors in Abu Dhabi retail clusters.
Foodservice operators are consolidating procurement through centralized purchasing cooperatives that bypass traditional distributor markups. Hotel chains now specify direct manufacturer relationships for plant-based beverages across property portfolios. This concentration is most visible in Dubai's hospitality sector, where procurement standardization across Emirates-based hotel groups is compressing supplier margins while securing volume commitments.
Middle East Dairy Alternatives Market Segmentation
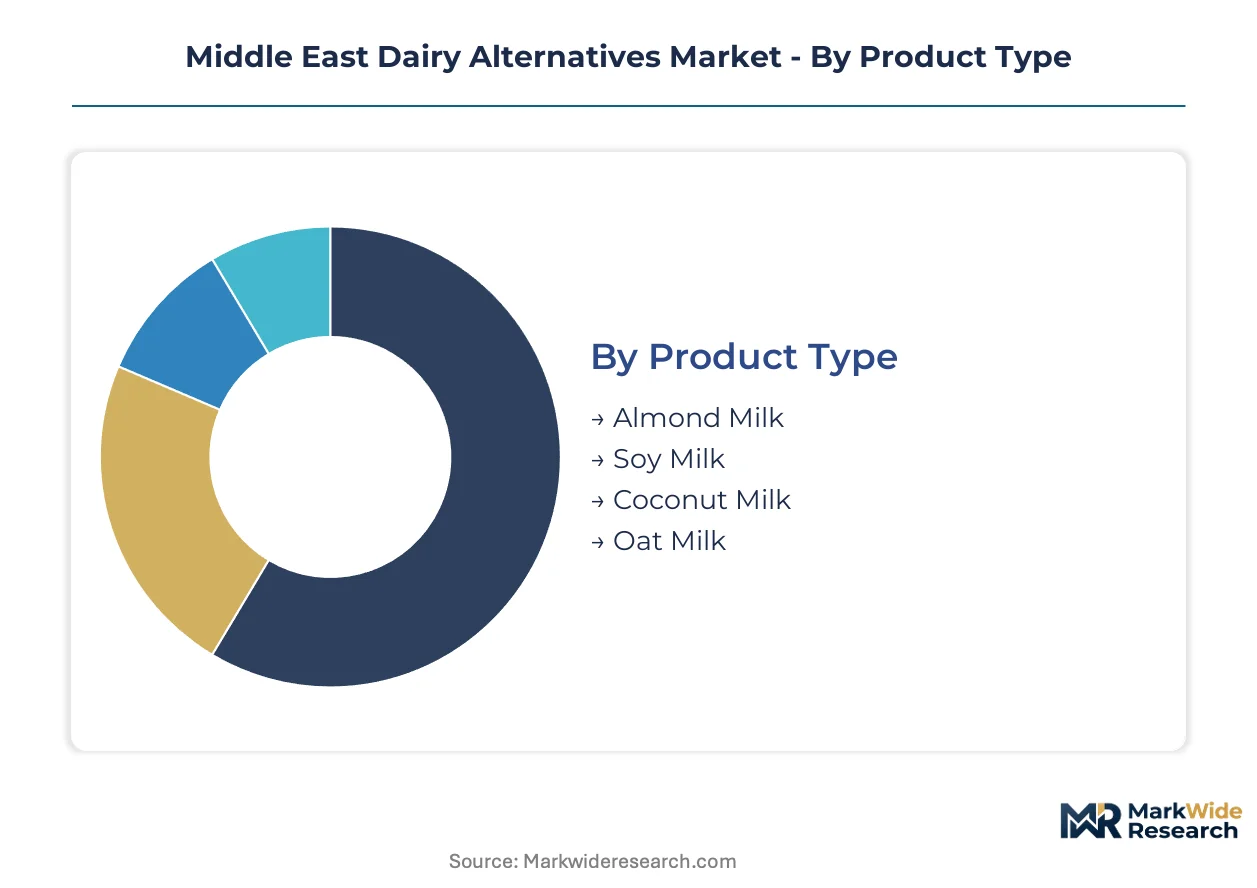
Segmentation in Middle East dairy alternatives reflects divergent compliance burdens and channel economics. Product formulations face distinct fortification mandates across Saudi Arabia and the UAE, while distribution channels carry varying documentation requirements for halal certification.
Product Type:
SFDA and MOHAP protein disclosure standards split this category by fortification feasibility and base material sourcing complexity.
- Oat Milk:Enzymatic hydrolysis reduces viscosity without hydrocolloid additives, achieving sub-two-micron particle distributions via high-pressure homogenization above 200 MPa. Dubai specialty coffee chains specify these textures for latte art performance, though Nordic and North American milling concentration creates lead time vulnerability for Gulf brands lacking backward integration into grain sourcing.
- Almond Milk:Aqueous extractions of California-sourced kernels dominate UAE retail shelf space, where premium-positioned unsweetened variants capture favorable margin pools. California harvest yields and water allocation disputes generate input cost volatility that compresses margins for Middle East importers dependent on US supply.
- Soy Milk:Fortified formulations meeting UAE MOHAP nutritional thresholds for calcium and vitamin D are displacing unfortified competitors in Abu Dhabi retail clusters.
- Coconut Milk:Ambient-stable variants serve foodservice procurement contracts across Egyptian and Levantine markets ahead of EOS regulatory harmonization.
Oat milk handles the majority of throughput; oat milk is the fastest mover on share.
Distribution Channel:
Channel selection determines cold chain investment requirements and halal documentation audit frequency.
- Supermarkets:Slotting fee structures in Dubai and Abu Dhabi retail infrastructure favor premium-positioned unsweetened and organic variants with established brand recognition. Chilled distribution density requirements limit oat milk availability to Saudi Arabia's major urban corridors.
- Online Retail:Direct-to-consumer subscription models bypass traditional supermarket slotting fees, capturing margin pools previously allocated to retail intermediaries. E-commerce channels for dairy alternatives are expanding most quickly, though fulfillment costs for refrigerated products constrain geographic reach.
- Health Food Stores:Curated assortment and educated consumer traffic sustain higher per-unit profitability than mass retail channels.
- Convenience Stores:Ambient-stable soy and fortified variants dominate procurement due to limited refrigeration capacity.
Supermarkets handle the majority of throughput; online retail is climbing the fastest on share.
Consumer Segment:
Dietary restriction severity and price sensitivity stratify procurement patterns across foodservice and retail.
- Lactose Intolerant Individuals:Medical necessity drives consistent repurchase and brand loyalty, with hotel chains and airline catering divisions expanding procurement to serve this demographic across Gulf hospitality portfolios.
- Vegan Diet Followers:Ethical positioning aligns with clean label preferences, concentrating demand in UAE health food stores where enzymatically processed oat variants command retail premiums.
- Health-Conscious Consumers:Fortified formulations with micronutrient premix integration attract buyers responding to MOHAP nutritional labeling thresholds.
- General Consumers:Price-driven selection favors ambient-stable soy milk in markets with patchy cold chain infrastructure outside Saudi Arabia's urban corridors.
Lactose intolerant individuals handle the majority of throughput; vegan diet followers are gaining share fastest.
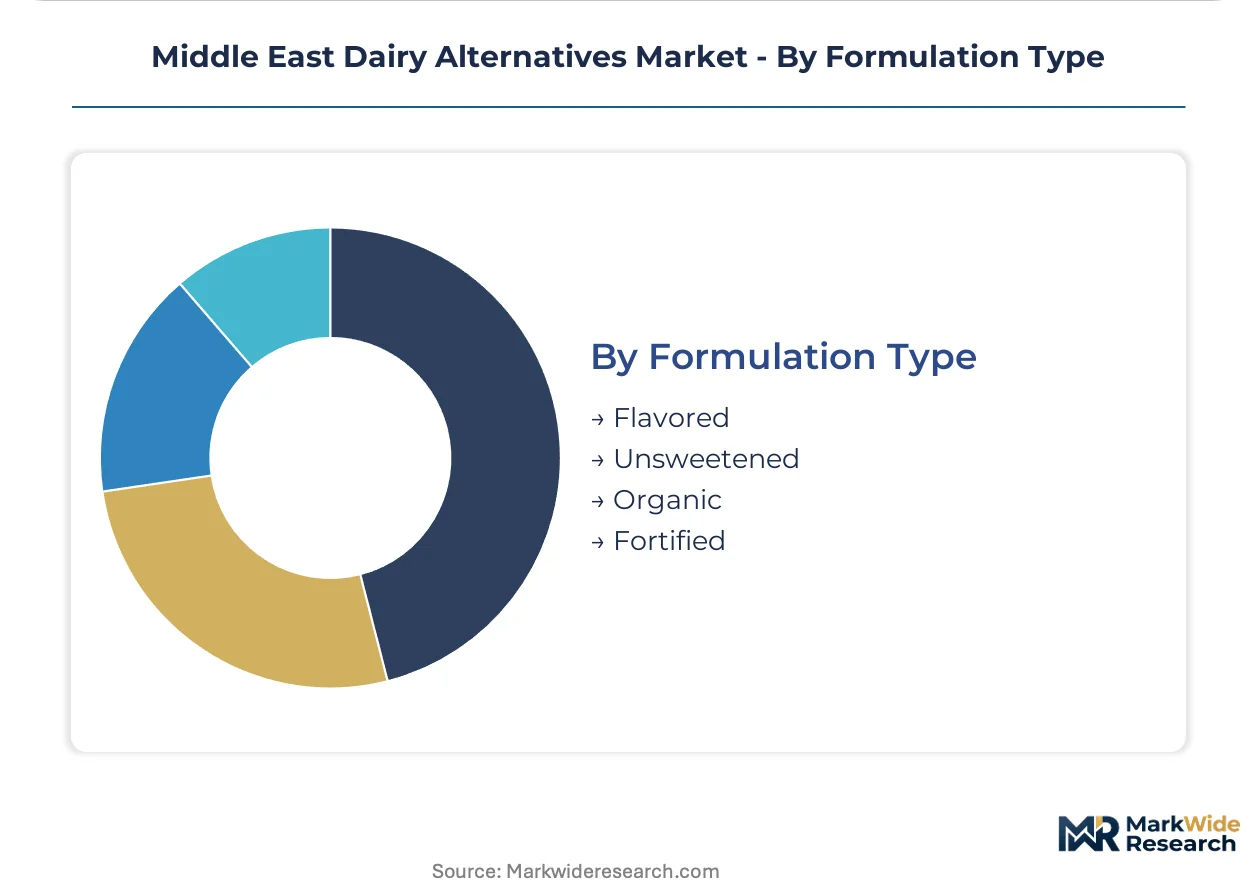
Formulation Type:
Label claim permissibility under SFDA and MOHAP standards determines reformulation investment returns.
- Fortified:Calcium and vitamin D premix integration during base formulation enables regulatory compliance with UAE MOHAP nutritional claim thresholds, securing shelf space from unfortified competitors.
- Unsweetened:Zero-added-sugar positioning captures premium margin pools in UAE supermarkets where health-conscious consumers prioritize glycemic control.
- Organic:Certification documentation extends halal supply chain audit timelines, favoring multi-market operators with dedicated regulatory affairs capacity.
- Flavored:Vanilla and chocolate variants serve foodservice procurement for hotel breakfast buffets, though stabilizer systems required for colloidal stability conflict with clean label positioning.
Fortified handles the majority of throughput; fortified is also the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA labeling mandates and MOHAP fortification thresholds are reshaping procurement patterns across Gulf markets, with chilled distribution infrastructure determining geographic rollout feasibility for perishable oat variants.
Saudi Arabia
Hotel chains and airline catering divisions in Riyadh and Jeddah are expanding plant-based procurement for lactose-intolerant travelers. SFDA tightened nutritional disclosure requirements for non-dairy beverages, compelling reformulation investments. Almarai Company leverages its chilled distribution network across the Kingdom to sustain refrigerated oat milk availability in major urban corridors.
United Arab Emirates
Dubai and Abu Dhabi retail infrastructure supports premium positioning for oat and almond milk variants in supermarket channels. MOHAP enforces distinct nutritional claim standards for protein and micronutrient content that favor fortified formulations. Specialty coffee chains across Emirates-based hospitality portfolios specify high-pressure homogenized textures for latte art performance.
Egypt
Underpenetrated retail infrastructure in Cairo and Alexandria offers first-mover positioning for ambient-stable soy and oat variants. EOS standards add certification layers for brands targeting North African expansion ahead of regulatory harmonization with Gulf requirements. Procurement concentrates in foodservice contracts for hotel breakfast buffets seeking menu flexibility.
Jordan
JSMO standards create additional compliance documentation for brands targeting Levantine market entry. Amman-based distribution networks serve as transit corridors for ambient-stable coconut milk variants entering Iraqi and Syrian adjacent markets. Health food stores in the capital sustain higher per-unit profitability through curated assortment of organic-positioned alternatives.
Qatar
Doha's hospitality procurement standardization across property portfolios is compressing supplier margins while securing volume commitments for plant-based beverages. The country's national food regulator maintains halal certification alignment with Gulf processing standards that collapse supplier pools to dual-compliant facilities. Chilled distribution density remains concentrated in the capital corridor.
Middle East Dairy Alternatives Market Competitive Landscape
Player mix skews toward diversified food conglomerates with existing chilled distribution assets and specialist oat milk pure-plays controlling premium foodservice channels. Market structure concentrates around vertically integrated dairy operators diversifying into plant-based lines and Nordic-origin oat specialists leveraging enzymatic processing differentiation. Two strategic archetypes dominate: legacy dairy giants repurposing cold chain infrastructure, and clean-label specialists commanding specialty coffee shop placement. Competitive moves center on direct procurement relationships with hotel chains bypassing distributor markups, and enzymatic hydrolysis licensing for viscosity reduction without additive dependence.
Within the legacy dairy diversification tier, Almarai Company and Danone SA represent archetypes of incumbent leverage, the former through captive chilled distribution networks across Saudi Arabia, the latter through fortified soy formulations meeting Gulf nutritional labeling thresholds. Among specialist oat pure-plays, Oatly Group AB occupies a position exemplifying channel control through specialty coffee shop penetration in Dubai and Riyadh. These three anchors illustrate the competitive tension between infrastructure scale and formulation differentiation across the region.
| Leading Market Players |
|---|
| Almarai Company |
| SADAFCO |
| Juhayna Food Industries |
| Alpro Middle East |
| Danone SA |
| Oatly Group AB |
| Lactalis Group |
| Chobani LLC |
| Flora Food Group |
| Others |
Pricing and Supply Chain Analysis
Nordic and North American oat milling capacity utilization above 85% is compressing margin pools for Gulf-based brands lacking backward integration into grain sourcing, while halal certification documentation costs create fixed cost floors that stratify pricing across compliant and non-compliant supplier tiers.
Pricing Analysis
Certification level (halal/SFDA-compliant) creates the primary spread between premium and standard tiers in Middle East dairy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects fortification investment, enzymatic processing sophistication, and cold chain density requirements. Cost compression in ambient-stable soy segments is intensifying because Egyptian and Jordanian procurement favors lower-price-point variants ahead of EOS regulatory harmonization. Foodservice operators consolidating through hotel chain procurement cooperatives exhibit lowest price sensitivity, while general retail consumers in patchy cold chain markets drive volume at economy tiers.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and Red Sea routing disruptions are extending lead times for California almond kernel shipments into UAE ports. Geographic supply concentration centers on Nordic countries for specialty oat milling, California for almond kernel extraction, and Southeast Asia for coconut milk base production. Raw material dependencies rest on enzymatic processing inputs, micronutrient premix formulations, and halal-certified packaging substrates. Single-source vulnerability concentrates in Nordic oat milling capacity, where limited alternative suppliers create procurement bottlenecks for Gulf brands. Distribution runs through chilled networks in Saudi Arabia's urban corridors and ambient-stable wholesale channels for Egyptian and Levantine expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis advances and MOHAP fortification thresholds are accelerating a technological inflection that rewards integrated formulation capabilities over pure distribution scale.
For Market Incumbents: Compound defensive positioning by deepening backward integration into Nordic oat milling partnerships and securing dedicated halal-certified production lines ahead of supplier pool collapse. Almarai-style chilled network density represents the critical lever against specialty coffee channel erosion from Oatly-type entrants. SFDA labeling mandate compliance costs will filter sub-scale competitors within 36 months. For New Entrants and Emerging Players: Anchor in Egyptian ambient-stable segments where EOS regulatory harmonization lags Gulf standards, creating first-mover positioning before Alpro and Danone fortification investments arrive. Direct-to-consumer subscription models bypass supermarket slotting fee structures that incumbent dairy conglomerates dominate. Target health food store curation in Amman and Cairo where educated consumer traffic sustains premium per-unit economics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic processing specialists with high-pressure homogenization capabilities above 200 MPa and established halal supply chain documentation systems. Long-term viability hinges on regulatory affairs capacity spanning SFDA, MOHAP, and EOS jurisdictions. The signal to watch is consolidation of specialty coffee procurement specifications toward sub-two-micron particle distributions that require capital-intensive equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Licensing | Enables viscosity reduction without hydrocolloid additives, securing clean label premiums in UAE health food channels. |
| Halal-Certified Production Line Segregation | SFDA and MOHAP dual compliance collapses supplier pools to documented facilities, creating scarcity rents for compliant operators. |
| Direct Hotel Chain Procurement Relationships | Bypasses distributor markups in Dubai hospitality procurement standardization, compressing margins while securing volume commitments. |
| Micronutrient Premix Integration | MOHAP calcium and vitamin D thresholds displace unfortified competitors in Abu Dhabi retail clusters. |
| E-Commerce Subscription Infrastructure | Captures margin pools previously allocated to supermarket intermediaries, though refrigerated fulfillment constrains geographic reach. |
Research Methodology
Operator-level perspectives from foodservice procurement directors, halal certification auditors, chilled distribution network managers, and enzymatic processing R&D leads anchored the qualitative base for this analysis. Primary interview data triangulated against secondary sources including SFDA regulatory filings, MOHAP nutritional claim databases, UAE customs import records, and GCC hospitality procurement contract disclosures. Bottom-up volume estimates from product-level retail audit data converged with top-down market sizing derived from foodservice channel expansion rates across the analysis window.
Sensitivity analysis tested forecast robustness across alternative scenarios for California almond harvest yield volatility, Red Sea logistics disruption duration, and EOS regulatory harmonization timing with Gulf standards. The analytical framework modeled segmentation dimensions spanning product type, distribution channel, consumer segment, and formulation type across the projection horizon. CAGRs derived from regression against protein fortification investment cycles, specialty coffee outlet expansion trajectories, and halal certification penetration rates in foodservice procurement.
Decision-makers should treat outputs as directional under assumptions of continued SFDA labeling enforcement, sustained MOHAP fortification thresholds, and stable enzymatic processing technology diffusion; material deviation in regulatory timing or input cost volatility would warrant model refresh. Forecasts embed assumptions regarding cold chain infrastructure rollout density in Saudi secondary cities and Egyptian retail modernization pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Canada Dairy Alternatives Market