
 South America Dairy Alternatives Market | 2026-2036
South America Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Dairy Alternatives Market Analytics
ANVISA's updated allergen labeling mandates for plant-based beverages is repositioning how manufacturers formulate and communicate ingredient integrity across Brazil and Argentina. Danone S.A. leverages its established dairy distribution infrastructure to accelerate oat and almond milk penetration in metropolitan São Paulo. Oatly Inc. competes through dedicated oat milk specialization and brand recognition among urban millennials. Nestle SA anchors its position with diversified plant-based portfolios spanning retail and food service channels.
South America dairy alternatives encompass plant-derived liquid and semi-liquid formulations manufactured through aqueous extraction, enzymatic treatment, or homogenization of oilseeds, cereals, or nuts, typically achieving protein concentrations between one and eight percent and serving as functional substitutes in beverages, cooking, and food processing applications. Almond milk occupies the premium shelf-position in Brazilian supermarkets and health food stores, commanding higher unit margins despite smaller volume throughput. Oat milk represents the fastest-growing product type as food service providers standardize it for barista applications across Buenos Aires and Santiago. Soy milk retains volume leadership through entrenched consumer familiarity and lower price points in traditional retail channels.
Brazil's ANVISA enforces compositional standards and allergen disclosure rules that determine which formulations qualify for retail placement, while Argentina's national food code sets parallel protein content thresholds that manufacturers must satisfy for market access. The EU-Mercosur trade negotiations continue to threaten tariff advantages for imported European brands, compelling local production investments. Stakeholders must monitor regulatory divergence between Brazilian and Argentine labeling regimes when scaling regional supply chains.
Market Dynamics
ANVISA's allergen disclosure mandates are compressing formulation timelines across Brazilian manufacturing facilities while simultaneously accelerating transparency investments from multinational suppliers. This regulatory pressure is reshaping competitive positioning by favoring producers with established compliance infrastructure over smaller domestic entrants.
Growth Catalysts
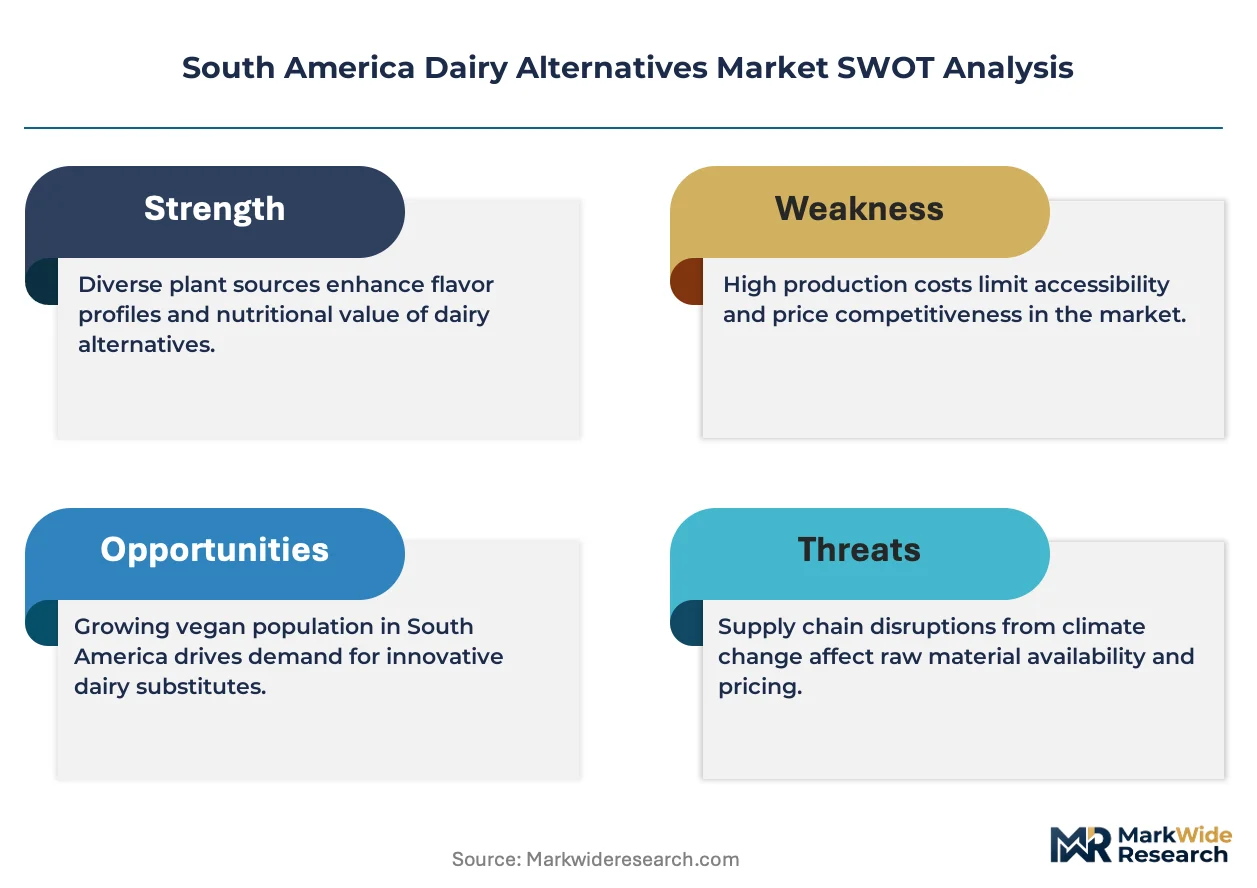
- ANVISA Labeling Mandates:Brazil's updated allergen disclosure rules for plant-based beverages are forcing manufacturers to reformulate with cleaner ingredient decks, creating first-mover advantages for compliant brands in São Paulo's retail channels.
- Food Service Standardization:Specialty coffee chains across Buenos Aires and Santiago are locking in oat milk as their default dairy alternative, generating volume commitments that stabilize procurement for regional distributors.
- Enzymatic Processing Advances:Novel enzymatic treatment methods are improving protein extraction rates from Brazilian-grown soy and oats, reducing input waste and narrowing cost gaps with conventional dairy in industrial applications.
Market Restraints
- Input Cost Volatility:Argentine almond harvest fluctuations are transmitting price instability through South American supply chains, compressing margins for premium-positioned nut milk producers.
- Single-Source Concentration Risk:Brazil's southeastern urban corridor generates disproportionate demand volume, creating geographic vulnerability if logistics disruptions affect São Paulo-Rio distribution networks.
- Protein Fortification Limits:Current enzymatic and homogenization technologies face technical ceilings in achieving protein parity with dairy, constraining appeal among performance-oriented consumers in sports nutrition segments.
Strategic Opportunities
- Colombian Market Entry:Bogotá and Medellín exhibit underpenetrated retail shelf space for plant-based beverages, offering expansion runway before competitive saturation mirrors Brazilian conditions.
- Regulatory Tailwind from EU-Mercosur Tensions:Threatened tariff advantages for European imports are compelling local production investments, creating partnership opportunities for domestic processors with multinational brands seeking manufacturing hedges.
- Direct-to-Institutional Channels:Brazilian hospital and school feeding programs represent emerging bulk procurement avenues, bypassing traditional retail markups while securing volume commitments through public tender processes.
Industry Challenges
- Formulation Talent Scarcity:Brazil lacks sufficient food technologists specializing in plant protein stabilization and emulsion science, extending product development cycles for novel oat and almond milk variants.
- Dual Certification Burden:Manufacturers serving both Brazilian and Argentine markets must simultaneously satisfy ANVISA compositional standards and Argentina's national food code protein thresholds, duplicating testing and documentation costs.
- Legacy Dairy Infrastructure Lock-In:Established dairy processors attempting plant-based pivots face capital intensity in retrofitting UHT lines and aseptic packaging equipment originally configured for animal milk parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Dairy Alternatives Market |
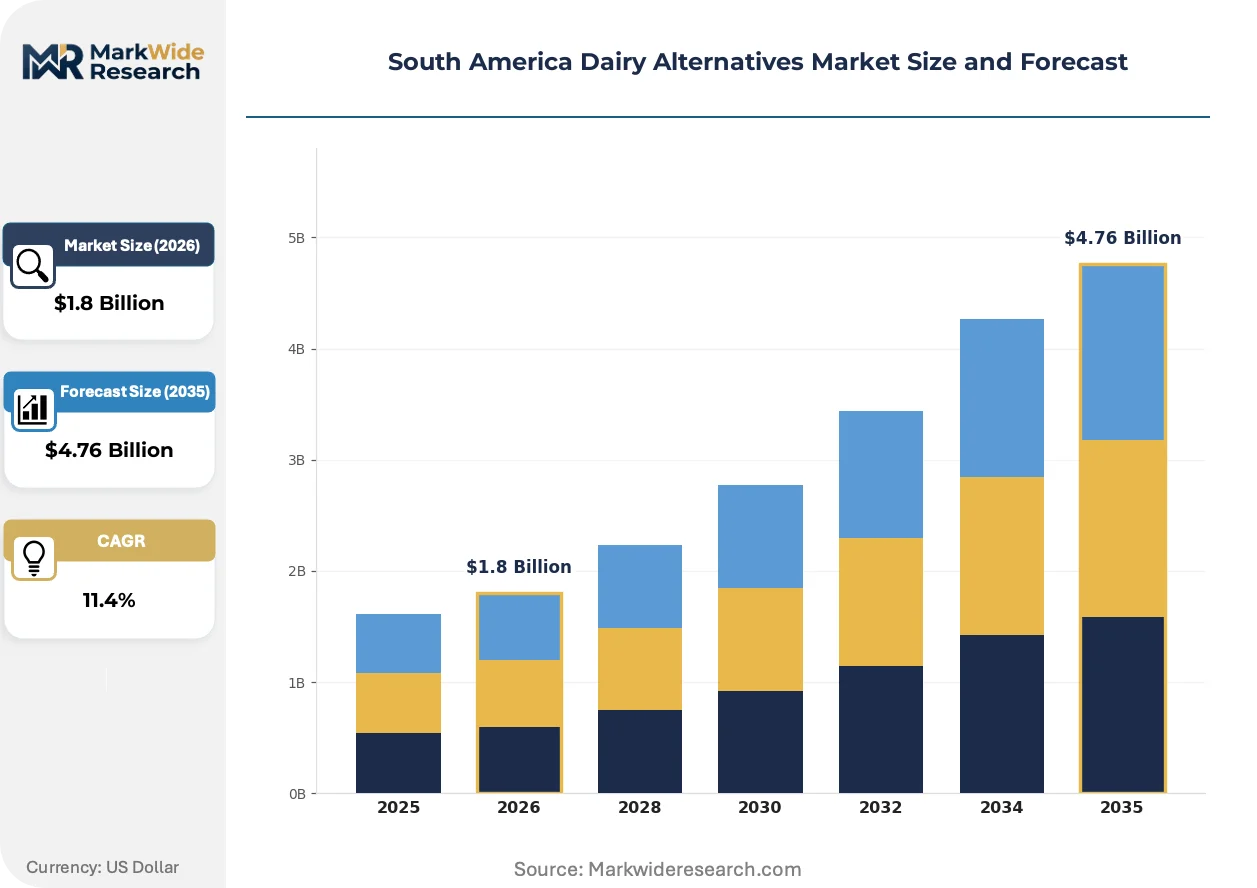
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk End User: Retail Consumers, Food Service Providers, Dairy Manufacturers, Health-conscious Customers Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops Packaging Type: Tetra Packs, Bottles, Cans, Pouches |
| Companies Covered | Nestle SA, Danone S.A., Blue Diamond Growers, General Mills Inc., SunOpta Inc., Califia Farms, LLC, Oatly Inc., McCormick & Company, Inc., Grupo Lala, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Dairy Alternatives Market Evolving Landscape
Electrification of processing infrastructure and precision fermentation research are converging to reshape how South American manufacturers approach protein extraction and product formulation. These developments are compressing traditional competitive advantages rooted in scale economies.
High-pressure processing technology is electrifying quality assurance protocols across Brazilian oat milk facilities. São Paulo-based industrial dairies adopting HPP systems are extending shelf life without thermal degradation of flavor compounds. This capability is enabling direct distribution to remote retail locations previously inaccessible due to cold chain limitations.
Argentina's national food code amendments regarding protein content claims are tightening enforcement thresholds for plant-based beverage labeling. Manufacturers must now verify minimum protein concentrations through third-party laboratory certification before retail placement authorization. The soy milk segment faces disproportionate compliance pressure as legacy formulations fall below revised minimums.
Urban millennial consumers in Santiago and Buenos Aires are consolidating purchases through subscription-based delivery platforms specializing in functional foods. These digital-native channels are displacing traditional supermarket discovery patterns for almond and oat milk trial. Brazilian southeastern cities exhibit the most pronounced channel migration, with direct-to-consumer volumes accelerating fastest in São Paulo's metropolitan periphery.
South America Dairy Alternatives Market Segmentation
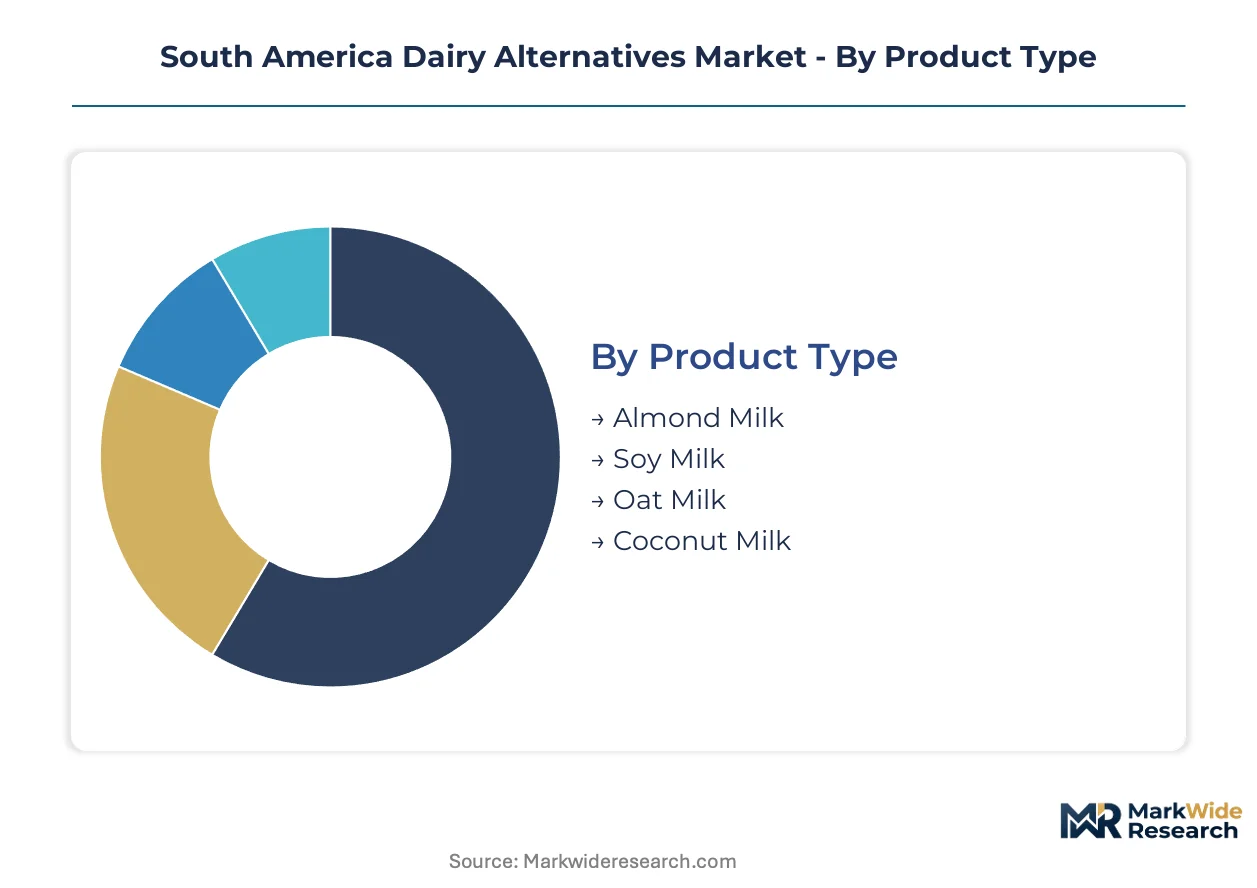
Segmentation across South American dairy alternatives reveals divergent growth trajectories between commodity soy formulations and premium oat and almond variants. Understanding where each segment sits on the standalone-to-embedded spectrum clarifies why food service procurement patterns diverge so sharply from retail shelf dynamics.
Product Type:
Product categories span from legacy formulations requiring minimal processing infrastructure to emerging variants demanding specialized enzymatic and homogenization capabilities.
- Soy Milk:Aqueous extraction of Brazilian-grown soybeans yields protein concentrations between one and four percent, with formulations stabilized through thermal treatment rather than enzymatic methods. Demand concentrates in traditional retail channels across São Paulo's peripheral municipalities where price sensitivity dominates purchase decisions and established distribution networks favor shelf-stable cartons over refrigerated alternatives.
- Oat Milk:Enzymatic treatment of Argentine and Brazilian oat cultivars achieves superior emulsion stability for barista applications, with beta-glucan content driving functional positioning. Buenos Aires specialty coffee chains are standardizing oat milk as their default dairy alternative, generating procurement commitments that stabilize regional distributor volumes and justify dedicated production lines.
- Almond Milk:Cold-pressed or blanched almond formulations from Argentine harvests command premium positioning in Brazilian health food stores.
- Coconut Milk:Traditional aqueous extraction methods serve both beverage and cooking applications with minimal processing investment.
Soy milk leads volumes today; oat milk is gaining share fastest.
End User:
End-user segmentation tracks how formulation requirements shift between direct consumption and industrial ingredient applications.
- Retail Consumers:Individual purchasers selecting shelf-stable or refrigerated formats for home consumption, with trial behavior increasingly migrating toward subscription platforms in São Paulo's metropolitan corridor.
- Food Service Providers:Specialty coffee chains and casual dining operators across Buenos Aires and Santiago require barista-grade foam stability and consistent supply commitments that favor oat milk standardization.
- Dairy Manufacturers:Industrial processors incorporating plant-based inputs into blended or co-manufactured product lines, facing reformulation pressure from ANVISA's updated allergen disclosure mandates.
- Health-conscious Customers:Niche purchasers prioritizing protein fortification and clean-label positioning, concentrated in Rio de Janeiro's upscale neighborhoods and Medellín's emerging wellness retail clusters.
Retail consumers anchor current volume; food service providers are expanding most quickly.
Distribution Channel:
Channel segmentation reflects the tension between consolidated retail gatekeepers and fragmented specialty access points.
- Supermarkets:Hypermarket and supermarket chains across Brazil's southeastern urban corridor control shelf placement economics, with oat and almond milk securing premium positioning adjacent to conventional dairy while soy milk occupies value-tier placement.
- Online Retail:Subscription-based delivery platforms are displacing traditional discovery patterns among urban millennials in São Paulo's metropolitan periphery, enabling direct-to-consumer trial of novel formulations without retail markup.
- Health Food Stores:Independent and chain specialty retailers in Buenos Aires and Santiago curate premium almond and coconut milk assortments targeting clean-label preferences.
- Specialty Shops:Boutique grocers and organic markets serve as gatekeepers for imported or small-batch formulations not yet scaled to supermarket distribution.
Supermarkets dominate transaction volumes today; online retail shows the steepest expansion trajectory.
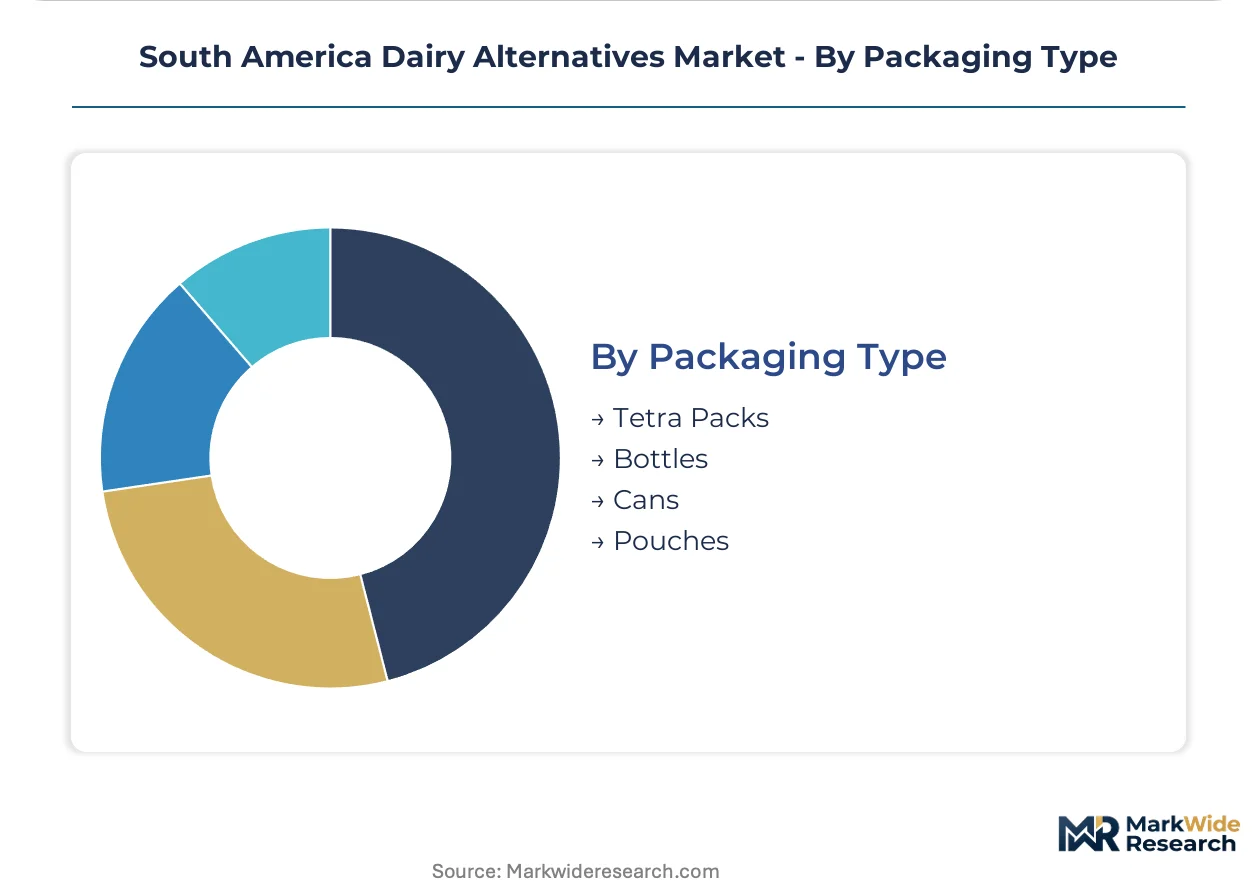
Packaging Type:
Packaging selection tracks shelf-life requirements against cold chain infrastructure constraints.
- Tetra Packs:Aseptic carton formats enable ambient distribution throughout Brazil's interior regions with limited refrigeration infrastructure, supporting soy milk's volume leadership through extended shelf stability.
- Bottles:Refrigerated PET and glass formats serve premium oat and almond milk positioning in urban supermarkets with established cold chain networks across São Paulo and Rio de Janeiro.
- Cans:Metal packaging supports coconut milk's cooking-application positioning with durability for export and institutional procurement.
- Pouches:Flexible formats target value-conscious segments with reduced material costs and logistical efficiency for bulk distribution.
Tetra packs lead volumes today; bottles are climbing the fastest among premium-positioned segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and formulation specialists concentrate in São Paulo's metropolitan corridor, anchoring South American dairy alternatives development. This talent density shapes regional production capabilities and accelerates product iteration cycles across the continent.
Brazil
ANVISA's allergen disclosure mandates and protein fortification standards are compressing formulation timelines for oat and soy milk producers. The regulator's updated compositional rules determine retail placement eligibility for plant-based beverages. São Paulo anchors demand volume, with food service providers in the southeastern urban corridor standardizing oat milk procurement for specialty coffee applications.
Argentina
Buenos Aires specialty coffee chains are locking in oat milk as their default dairy alternative, generating stabilized procurement commitments for regional distributors. The national food code amendments regarding protein content claims are tightening enforcement thresholds through mandatory third-party laboratory certification. Mendoza's almond harvest fluctuations transmit price instability through South American supply chains, compressing margins for premium-positioned nut milk producers.
Chile
Santiago's urban millennial consumers are consolidating purchases through subscription-based delivery platforms specializing in functional foods. These digital-native channels are displacing traditional supermarket discovery patterns for almond and oat milk trial. The capital's established cold chain networks support refrigerated PET and glass format distribution for premium-positioned products.
Colombia
Bogotá and Medellín exhibit underpenetrated retail shelf space for plant-based beverages, offering expansion runway before competitive saturation mirrors Brazilian conditions. The country's national food regulator maintains compositional standards for protein content claims that manufacturers must satisfy for market access. Antioquia's emerging wellness retail clusters are attracting clean-label positioning from multinational brands seeking first-mover advantages.
South America Dairy Alternatives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South American dairy alternatives, with multinational food conglomerates leveraging established distribution infrastructure against specialized plant-based entrants. The market structure tilts toward consolidation at the top tier, where scale economies in procurement and compliance create defensive moats. Three archetypes dominate: diversified dairy conglomerates pivoting into plant-based portfolios, oat milk specialists commanding brand recognition among urban millennials, and ingredient suppliers controlling upstream nut and grain sourcing. Dominant competitive moves include portfolio diversification into adjacent plant-based categories and backward integration into captive supply of Argentine almonds and Brazilian oats.
Within the diversified conglomerate tier, Nestle SA and Danone S.A. occupy positions representing scale-driven market presence, while Oatly Inc. exemplifies the specialist archetype focused on single-category depth. These three anchors illustrate how competitive positioning diverges between breadth-oriented portfolio players and narrow-focused brand builders in South American retail and food service channels.
| Leading Market Players |
|---|
| Nestle SA |
| Danone S.A. |
| Blue Diamond Growers |
| General Mills Inc. |
| SunOpta Inc. |
| Califia Farms, LLC |
| Oatly Inc. |
| McCormick & Company, Inc. |
| Grupo Lala |
| Others |
Value Network & Pricing Analysis
Buenos Aires specialty coffee chains standardizing oat milk as their default dairy alternative are forcing procurement commitments that reshape Argentine and Brazilian sourcing networks, compressing supplier margins while elevating volume-tier pricing power for compliant processors.
Pricing Analysis
Unbundled ingredient supply contracts dominate commodity soy milk transactions, while bundled service agreements covering technical support and barista training anchor premium oat milk positioning. Three-tier pricing structure across premium, standard, and economy levels separates Argentine almond milk from Brazilian oat formulations from legacy soy cartons. Price differentiation rests on ANVISA certification tier and volume scale commitments. Cost compression in premium nut milk segments is intensifying because Mendoza harvest volatility transmits through South American supply chains. Traditional retail channels exhibit highest price sensitivity; food service providers demonstrate lowest sensitivity due to standardization lock-in.
Supply Chain Analysis
ANVISA protein content certification and Argentina's national food code laboratory verification create dual qualification gating that filters supplier eligibility across Brazilian and Argentine markets. Raw material supply concentrates in Argentina for almonds, Brazil for soy and oats, with enzymatic processing inputs sourced from European specialty chemical suppliers. Argentine almond harvest fluctuations and Brazilian oat crop cycles generate commodity price volatility that propagates through formulation costs. Distribution runs through São Paulo-based regional distributors serving southeastern urban corridors, with cold chain-dependent refrigerated formats requiring parallel logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America dairy alternatives market functions as a stable compounder, with ANVISA regulatory tailwinds and food service standardization generating predictable procurement volume expansion across Brazilian and Argentine channels.
For Market Incumbents: Acquire captive oat processing capacity in São Paulo's metropolitan corridor to secure supply continuity against Argentine harvest volatility. Incumbent processors should deepen backward integration into Brazilian oat cultivation partnerships while simultaneously retrofitting legacy UHT lines for plant-based parameters. This dual move defends margin position against enzymatic processing specialists threatening technical differentiation. For New Entrants and Emerging Players: Precision fermentation research platforms offer technology-first wedge positioning for protein fortification solutions addressing current enzymatic ceilings. New entrants should target Colombian institutional feeding programs in Bogotá and Medellín, where underpenetrated shelf space and public tender processes enable volume anchoring without retail gatekeeper competition. Direct-to-institutional channels provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Brazilian processors possessing ANVISA compliance infrastructure and established food service relationships. Long-term viability over a multi-year horizon depends on regulatory adaptation capacity rather than brand recognition alone. Investors should monitor EU-Mercosur negotiation outcomes as the critical inflection signal for local production investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Cultivation | São Paulo processors securing Brazilian oat supply reduce exposure to Argentine harvest volatility. |
| ANVISA Certification Investment | Dual-market manufacturers satisfying Brazilian and Argentine protein thresholds unlock regional scale. |
| Food Service Partnership Lock-In | Buenos Aires coffee chain standardization generates multi-year procurement commitments stabilizing distributor volumes. |
| Enzymatic Processing Capability Buildout | Specialized protein extraction facilities narrow cost gaps with conventional dairy in industrial applications. |
| Colombian Market Entry | Bogotá and Medellín institutional channels offer first-mover positioning before competitive saturation. |
Research Methodology
Bottom-up food service procurement modeling reconciled against top-down raw material supply tracking forms the analytical core of this study. Primary interviews with plant-based beverage formulators, ANVISA regulatory affairs specialists, specialty coffee chain procurement directors, and Brazilian supermarket category buyers combined with secondary validation from customs trade records, ANVISA compositional standard filings, and Argentine national food code amendments. This approach triangulates volume estimates against input supply constraints.
Input-output matrices mapping oat and soy cultivation through enzymatic processing to finished beverage distribution generate segment-level volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user application, distribution channel, and packaging format, with CAGRs derived from trend extrapolation moderated by regulatory implementation timelines. Forecast inputs incorporate ANVISA compliance cost trajectories and food service standardization adoption curves.
The model holds under stable regulatory implementation schedules; deviation in EU-Mercosur trade negotiation outcomes or ANVISA enforcement intensity would shift production investment timing and regional competitive positioning. A model refresh is warranted upon material change in Mercosur tariff structure or protein fortification technology breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
North America Almond Milk Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Vegan Cheese Alternatives Market