
 A2 Milk Powder Market | 2026-2036
A2 Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
A2 Milk Powder Market Insights
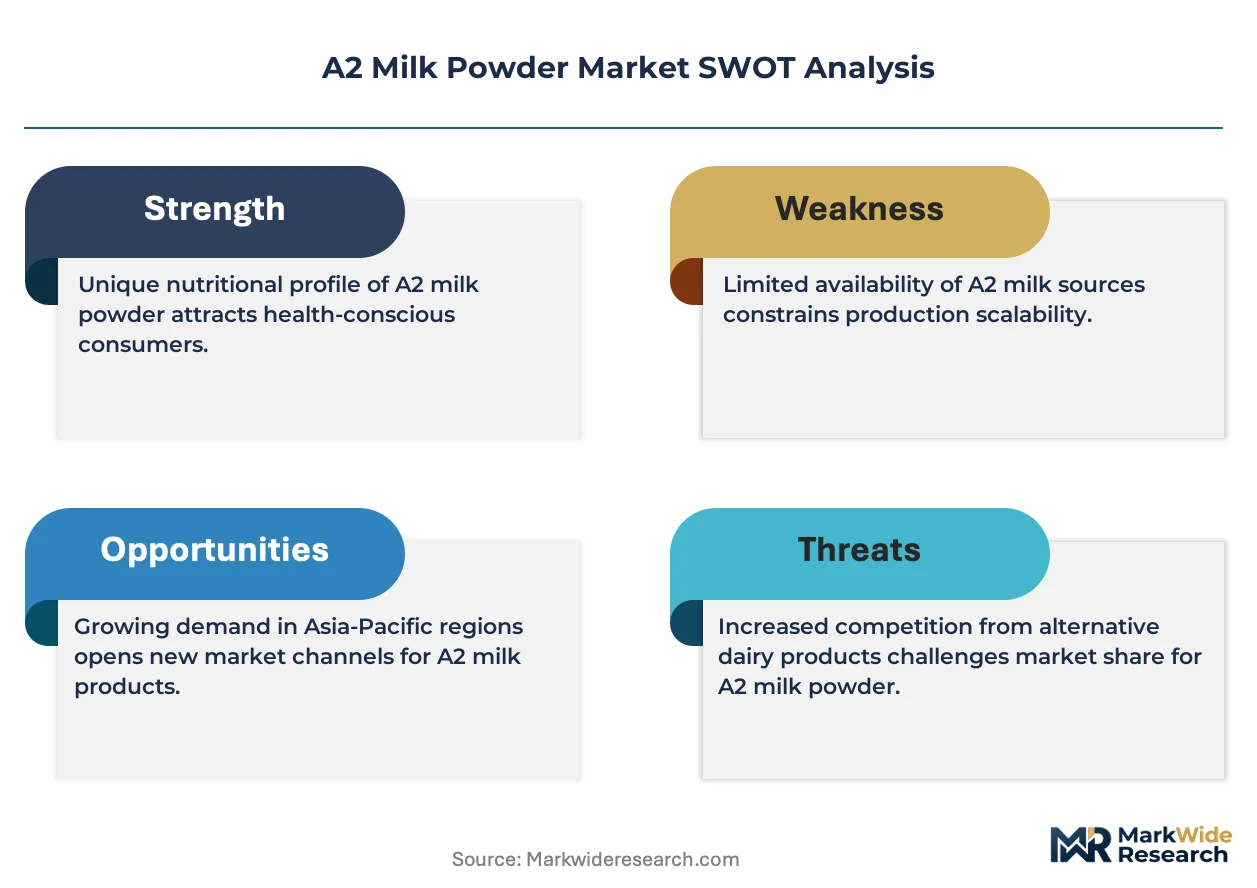
Parental buyers seeking digestive-friendly infant nutrition is collapsing the historical dominance of conventional milk powder in premium nursery aisles. The a2 Milk Company leverages its proprietary herd certification program to sustain supply scarcity and price premiums across Australasia. Fonterra Cooperative Group anchors its competitive position through backward integration into A2 beta-casein testing laboratories and controlled breeding cooperatives. Nestlé competes by extending its pediatric nutrition R&D infrastructure into A2 protein clinical validation studies.
A2 milk powder contains exclusively A2 beta-casein protein, omitting the A1 variant associated with gastrointestinal discomfort in sensitive individuals, and undergoes chromatographic or genetic herd screening before spray-drying to preserve protein integrity. The product serves primarily as a premium nutritional base for infant formula, adult dietary supplements, and sports recovery beverages where protein tolerance commands formulation priority. Powdered milk and full cream A2 milk occupy the dominant volume positions, while organic A2 milk captures disproportionate margin pools due to dual-certification requirements and limited herd availability. Online retail and specialty stores are growing fastest as direct-to-consumer subscription models and pharmacy-grade positioning reshape channel economics away from mass supermarket distribution.
FDA nutrition labeling requirements and China's SAMR infant formula registration standards shape product claim substantiation and cross-border market access for A2-positioned powders. New Zealand's MPI dairy export certification and Australia's FSANZ food standards code govern beta-casein testing protocols and country-of-origin labeling for international shipments. Stakeholders must monitor evolving protein-variant testing methodologies and regulatory recognition of A2-specific health claims to calibrate R&D allocation and geographic prioritization.
Market Dynamics
China's SAMR infant formula registration overhaul is forcing multinationals to rebuild product portfolios around A2-specific certifications, converting what was a niche protein claim into a mandatory competitive entry ticket for premium nursery shelf space.
Growth Catalysts
- Digestive-tolerance positioning:Pediatric nutrition buyers now prioritize A2 beta-casein claims over conventional milk powder, collapsing historical brand loyalty in premium infant formula aisles.
- Australia's FSANZ food standards code:Clear beta-casein testing protocols enable export-grade certification that unlocks pharmacy and specialty retail channels across Asia-Pacific markets.
- Genomic herd screening:Chromatographic protein verification and DNA-based cow selection are compressing conversion timelines for dairy cooperatives expanding A2 supply bases.
Market Restraints
- A2 beta-casein supply scarcity:Herd conversion programs require 18-24 month breeding cycles, constraining volume expansion regardless of demand pull from infant nutrition applications.
- Dual-certification cost burden:Organic A2 milk powder carries overlapping audit requirements from organic certifiers and A2 protein testing laboratories, inflating unit economics for mid-tier processors.
- Conventional milk powder substitution:Price-sensitive adult nutrition and sports recovery segments retain tolerance for standard beta-casein blends, capping A2 penetration in non-pediatric categories.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail channels enable recurring revenue capture and pharmacy-grade positioning that bypasses mass supermarket margin compression.
- Sports recovery beverage formulation:Protein tolerance claims are penetrating athletic nutrition segments previously dominated by whey isolates, opening volume pools beyond infant formula.
- New Zealand's MPI dairy export certification:Country-of-origin labeling protocols create premium positioning for A2 powder in Chinese cross-border e-commerce channels.
Industry Challenges
- A2 protein clinical validation capacity:Pediatric nutrition R&D infrastructure requires expansion to generate peer-reviewed substantiation for digestive-comfort claims under tightening regulatory scrutiny.
- Legacy spray-drying asset retrofit:Protein integrity preservation during powder conversion demands temperature-controlled processing lines that many conventional dairy plants lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A2 Milk Powder Market |
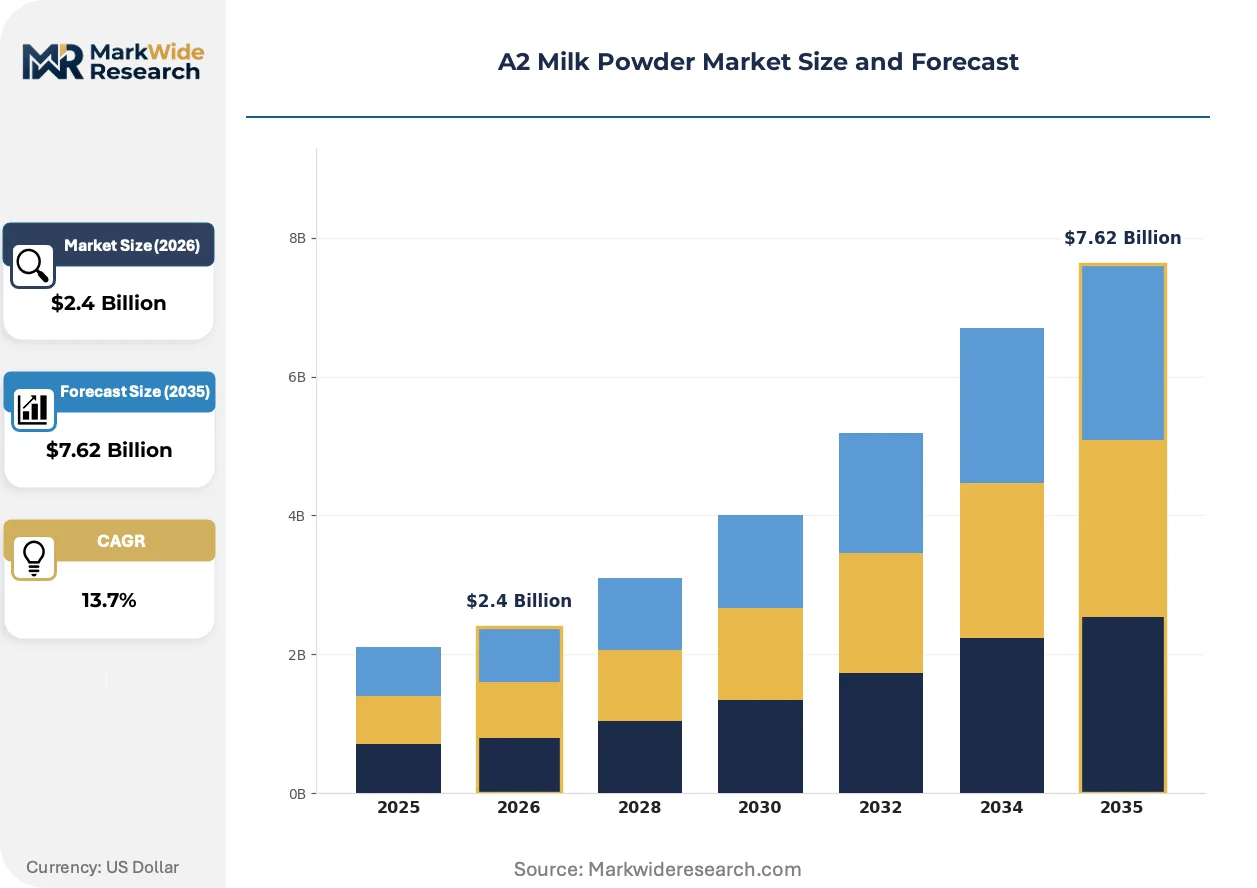
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Milk, Organic A2 Milk, Full Cream A2 Milk, Skimmed A2 Milk End User: Adults, Infants, Athletes, Seniors Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Carton, Tetra Pack, Pouch, Can |
| Companies Covered | The a2 Milk Company, GCMMF (Amul), Vinamilk, Fonterra Cooperative Group, Freedom Foods Group, Provilac Dairy Farms Pvt. Ltd., Erden Creamery Private Limited, Nestlé, Vedaaz Organics Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A2 Milk Powder Market Trends and Innovations
Genomic selection and chromatographic verification are converging to compress A2 beta-casein sourcing timelines, while regulatory recognition of protein-variant health claims is reshaping competitive positioning across pediatric nutrition channels.
Genomic herd screening is miniaturizing the A2 cow identification process from laboratory-scale chromatography to on-farm DNA testing kits. Dairy cooperatives in New Zealand and Australia are deploying these systems to accelerate selective breeding programs. The technology is miniaturizing capital requirements for A2 supply expansion, enabling mid-tier processors to enter premium powder segments without captive laboratory infrastructure.
China's SAMR tightened infant formula registration standards now mandate clinical substantiation for protein-variant claims, mirroring the FDA's nutrition labeling rigor for digestive health positioning. Multinational processors must rebuild dossiers around A2-specific clinical data to maintain cross-border market access. Infant formula SKUs face the steepest compliance burden, with reregistration timelines extending 12-18 months for legacy products lacking A2 protein validation.
Subscription-based replenishment is displacing supermarket bulk purchasing in premium pediatric nutrition. Direct-to-consumer platforms capture recurring revenue and enable pharmacy-grade positioning that mass retail channels cannot replicate. This channel migration concentrates in Australia and New Zealand's urban centers, where parental buyers prioritize convenience and digestive-tolerance assurance over price comparison.
A2 Milk Powder Market Segmentation
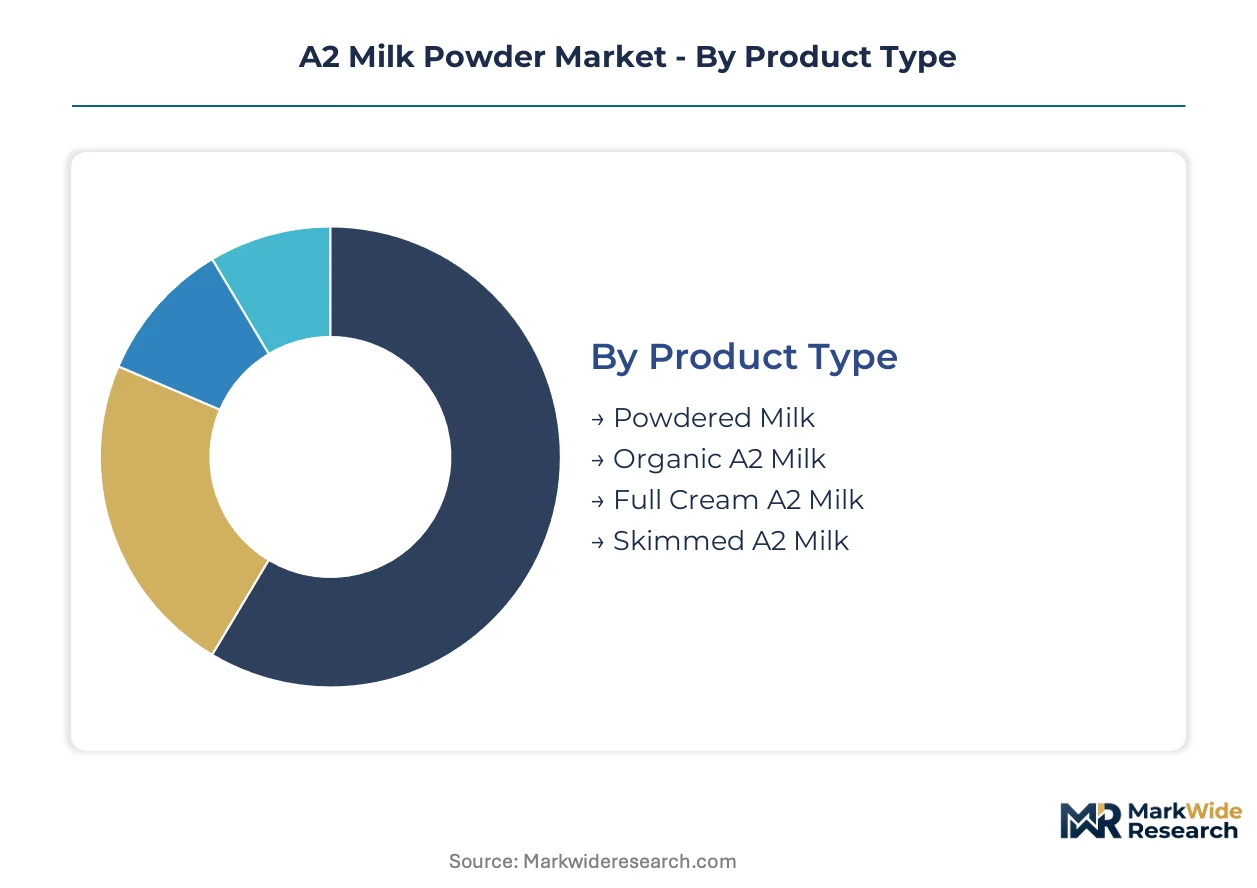
A2 milk powder segmentation reveals how protein-variant certification reshapes product positioning across pediatric nutrition, adult dietary supplements, and athletic recovery formulations. Category boundaries increasingly blur as digestive-tolerance claims migrate from infant formula into sports nutrition and senior wellness applications.
Product Type:
Substitution pressure from conventional dairy powder concentrates in commodity-adjacent segments where A2 beta-casein certification fails to command measurable price premiums.
- Powdered Milk:Standard spray-dried A2 beta-casein powder serves as the volume base for infant formula manufacturing and bulk ingredient supply to beverage processors. Demand clusters in Australia and New Zealand export channels where MPI and FSANZ certification unlocks Chinese cross-border e-commerce access.
- Organic A2 Milk:Dual-certified powder carries overlapping organic and A2 protein audit requirements, limiting herd availability and inflating unit economics for mid-tier processors. Parents in Australian urban centers and Chinese tier-one cities drive disproportionate demand for nursery-grade positioning.
- Full Cream A2 Milk:Retained milkfat content preserves lipid-soluble vitamins and delivers caloric density preferred in pediatric nutrition formulations.
- Skimmed A2 Milk:Reduced-fat variant targets adult weight-management and sports recovery segments where protein tolerance claims compete with whey isolate alternatives.
Powdered Milk retains volume leadership; Organic A2 Milk holds the steepest expansion curve.
End User:
Application-driven cost tiers separate premium pediatric nutrition from price-sensitive adult wellness and athletic recovery segments.
- Adults:Digestive-comfort positioning penetrates dietary supplement aisles as A2 beta-casein claims challenge conventional whey and plant-based alternatives. Chinese and Australian direct-to-consumer platforms capture recurring subscription revenue from urban professionals.
- Infants:SAMR registration requirements in China and FDA nutrition labeling standards in the US mandate clinical substantiation for protein-variant claims, elevating R&D barriers and consolidating share among multinational pediatric nutrition specialists. This segment commands the highest certification burden and price realization.
- Athletes:Protein tolerance marketing displaces whey isolate dominance in sports recovery formulations where gastrointestinal discomfort limits conventional dairy acceptance.
- Seniors:Age-related digestive sensitivity drives A2 positioning in bone health and protein supplementation products targeting pharmacy retail channels.
Infants anchor margin concentration; Athletes gain share fastest as sports nutrition certification expands.
Distribution Channel:
Channel maturity separates established supermarket infrastructure from rapidly scaling digital direct-to-consumer platforms.
- Online Retail:Subscription-based replenishment models bypass mass retail margin compression and enable pharmacy-grade positioning unavailable in conventional supermarkets. Australian and New Zealand urban centers concentrate adoption.
- Supermarkets:Legacy bulk purchasing channels face erosion as parental buyers prioritize convenience and digestive-assurance over price comparison in premium nursery categories.
- Specialty Stores:Pharmacy and health food retail captures premium positioning through trained staff consultation and clinical-grade product presentation.
- Direct Sales:Healthcare practitioner and lactation consultant networks drive recommendation-based purchasing in infant nutrition segments.
Supermarkets retain transaction volume; Online Retail climbs the fastest as subscription economics mature.
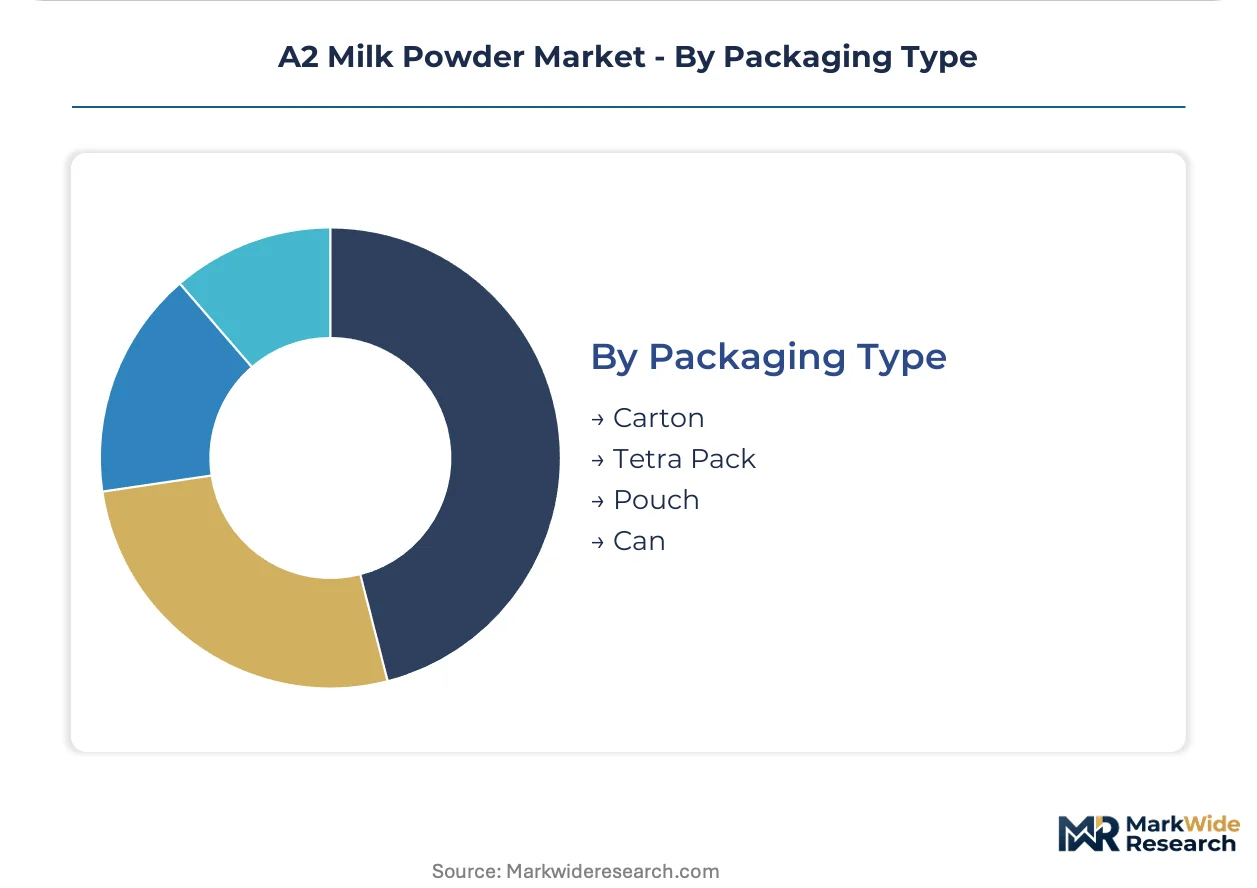
Packaging Type:
Supply concentration in dairy processing infrastructure favors formats compatible with existing spray-drying and filling lines.
- Carton:Paperboard packaging dominates adult nutritional powder segments where shelf-stable dry storage and environmental positioning drive format selection.
- Tetra Pack:Aseptic carton technology preserves protein integrity in liquid-concentrate intermediates for reconstitution markets.
- Pouch:Flexible film formats reduce shipping cube and enable single-serve portioning for travel and on-the-go athletic consumption.
- Can:Metal packaging retains dominance in infant formula segments where oxygen barrier properties and premium tactile perception justify higher unit cost.
Can retains value concentration in pediatric applications; Pouch expands most quickly in sports nutrition portability segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A2 beta-casein supply chains cluster in Australia and New Zealand, where genomic herd screening infrastructure and MPI export certification protocols enable premium positioning in Chinese cross-border channels. Demand pull concentrates in urban centers across China, Australia, and select Southeast Asian markets where pediatric nutrition buyers prioritize digestive-tolerance claims.
Australia
Parental buyers in Sydney and Melbourne drive subscription-based replenishment through direct-to-consumer platforms that bypass supermarket margin compression. FSANZ food standards code governs beta-casein testing protocols and country-of-origin labeling for export shipments. The a2 Milk Company anchors supply scarcity through proprietary herd certification programs spanning New South Wales and Victorian dairy cooperatives.
China
SAMR infant formula registration standards mandate clinical substantiation for A2 protein-variant claims, elevating compliance barriers for cross-border market access. Tier-one cities including Shanghai, Beijing, and Guangzhou concentrate demand for pharmacy-grade pediatric nutrition positioning. Domestic processors are rebuilding product portfolios around A2-specific certifications to secure premium nursery shelf space.
New Zealand
MPI dairy export certification unlocks Chinese e-commerce channels for Fonterra Cooperative Group and mid-tier processors with controlled breeding cooperatives. Canterbury and Waikato dairy regions deploy genomic screening to compress A2 cow identification timelines from laboratory-scale chromatography to on-farm DNA testing. Herd conversion programs require 18-24 month breeding cycles, constraining volume expansion despite demand acceleration.
United States
FDA nutrition labeling requirements shape digestive-health claim substantiation for A2-positioned powders entering pediatric and adult wellness segments. California and Northeast Corridor urban centers concentrate early adoption of protein-tolerance marketing in sports recovery formulations. Specialty retail and pharmacy channels capture premium positioning unavailable in conventional supermarket infrastructure.
Vietnam
Vinamilk and regional dairy cooperatives leverage proximity to Chinese demand while navigating SAMR registration complexity for formal cross-border access. Ho Chi Minh City and Hanoi concentrate urban professional demand for adult dietary supplement applications. Domestic processors face dual-certification cost burdens when pursuing organic A2 positioning alongside standard beta-casein verification.
A2 Milk Powder Market Competitive Landscape
Concentration sits with proprietary herd certification specialists and backward-integrated dairy cooperatives that control A2 beta-casein testing infrastructure. The vendor base spans three tiers: genomic screening technology licensors, spray-drying processors with temperature-controlled protein preservation lines, and direct-to-consumer subscription platforms with pharmacy-grade positioning. Strategic moves center on selective breeding program expansion and clinical validation study partnerships that satisfy tightening regulatory substantiation requirements.
Within the proprietary certification tier, The a2 Milk Company exemplifies supply scarcity management through captive herd programs, while Fonterra Cooperative Group anchors cooperative-scale A2 beta-casein sourcing across New Zealand. Nestlé occupies a position bridging pediatric nutrition R&D infrastructure with multinational regulatory dossier capacity. Among Asia-Pacific processors, Vinamilk and GCMMF represent emerging competitive presence in Southeast Asian and Indian market development respectively.
| Leading Market Players |
|---|
| The a2 Milk Company |
| GCMMF (Amul) |
| Vinamilk |
| Fonterra Cooperative Group |
| Freedom Foods Group |
| Provilac Dairy Farms Pvt. Ltd. |
| Erden Creamery Private Limited |
| Nestlé |
| Vedaaz Organics Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
New Zealand's MPI dairy export certification gates both supply qualification and price differentiation simultaneously, requiring A2 beta-casein verification for premium positioning in Chinese cross-border channels while segmenting processors by their captive laboratory infrastructure.
Pricing Analysis
China's SAMR infant formula registration dictates the pricing tier structure across the A2 milk powder market. Pricing stratifies across organic dual-certified premium, standard A2-verified, and conventional beta-casein economy tiers based on certification burden and herd scarcity. Cost compression in the standard tier is intensifying because genomic screening technology is democratizing A2 cow identification. Adult dietary supplement buyers exhibit highest price sensitivity while pediatric nutrition segments retain lowest elasticity due to clinical claim substantiation requirements.
Supply Chain Analysis
Container availability constraints on the Australia-China and New Zealand-Shanghai trade lanes are elevating inbound logistics costs for temperature-controlled powder shipments. Supply concentrates in Australia, New Zealand, and select Southeast Asian processing zones where MPI and FSANZ certification infrastructure exists. Raw material flows draw from A2 beta-casein verified herds, chromatographic testing reagents, and organic pasture feed stocks. Single-source vulnerability sits with proprietary herd certification programs controlled by dominant cooperatives. Distribution runs through pharmacy-grade direct-to-consumer platforms and specialty retail channels rather than mass supermarket infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A2 milk powder operates as a regulatory-entrenchment market where SAMR and FDA clinical validation requirements create switching costs that protect incumbent dossiers while raising barriers for new pediatric nutrition entrants.
For Market Incumbents: Shield market position by deepening backward integration into genomic screening laboratories and controlled breeding cooperatives to secure A2 beta-casein supply scarcity. Expand temperature-controlled spray-drying capacity in Victoria and Canterbury to preserve protein integrity during powder conversion. Counter emerging processor threats from Southeast Asia by accelerating clinical validation study partnerships that satisfy tightening SAMR substantiation timelines. For New Entrants and Emerging Players: FDA nutrition labeling fast-track pathways offer entry acceleration for adult sports recovery formulations where digestive-tolerance claims face lower clinical burden than infant nutrition segments. Target pharmacy-grade direct-to-consumer subscription models in Australian urban centers where parental buyers prioritize convenience over established brand loyalty. Deploy on-farm DNA testing kits to compress A2 cow identification timelines without captive laboratory infrastructure investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across genomic screening technology deployment as miniaturized testing kits displace laboratory-scale chromatography. Long-term viability favors processors with dual organic-A2 certification capabilities and established Chinese cross-border e-commerce relationships. Acquisition target archetypes include mid-tier New Zealand dairy cooperatives with MPI export certification and controlled A2 herd programs. Monitor SAMR infant formula reregistration timelines as inflection indicator for competitive consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Genomic Herd Screening Deployment | Miniaturized DNA testing kits compress A2 cow identification timelines from laboratory chromatography to on-farm verification. |
| Clinical Validation Study Partnership | Peer-reviewed digestive-comfort substantiation satisfies SAMR and FDA tightening requirements for protein-variant claims. |
| Temperature-Controlled Processing Line Retrofit | Protein integrity preservation during spray-drying enables premium pediatric nutrition positioning unavailable from conventional dairy plants. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture and pharmacy-grade positioning bypass mass supermarket margin compression in Australian urban centers. |
| Dual Organic-A2 Certification Investment | Overlapping audit requirements limit herd availability and inflate unit economics for mid-tier processors seeking premium margin pools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pediatric nutrition brand managers, dairy cooperative procurement leads, genomic screening technology providers, pharmacy retail category buyers, and regulatory affairs specialists at multinational processors. Secondary validation drew from SAMR infant formula registration databases, MPI dairy export certification records, FSANZ food standards filings, and Chinese cross-border e-commerce trade data. Bottom-up volume modeling triangulated against top-down value projections across product type, end user, and distribution channel dimensions.
Across the analysis window, the forecasting framework modeled segmentation dimensions including beta-casein certification grade, pediatric versus adult application, online versus offline channel structure, and organic dual-certification status. CAGRs were derived from trend extrapolation anchored in historical conversion rates for genomic herd screening adoption and regulatory registration timeline compression. Industry-specific inputs incorporated A2 cow breeding cycle durations and chromatographic testing capacity expansion curves.
Underlying assumptions cover sustained SAMR enforcement of clinical substantiation requirements and stable Australia-New Zealand pasture feed availability, with deviation risk concentrated in regulatory recognition shifts for A2-specific health claims and logistics disruption on Asia-Pacific dairy export lanes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Breast Milk Substitutes Market