
 Europe Almond Milk Market | 2026-2036
Europe Almond Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Almond Milk Market Insights
Multi-source almond procurement is decoupling from traditional California-dependent supply chains as European brands seek Mediterranean and Australian origins. Danone S.A. leverages its plant-based R&D infrastructure in France to develop stabilized barista formulations. Alpro S.A. anchors the Benelux retail channel through dedicated chilled-dairy-alternative shelf space. Blue Diamond Growers competes on raw nut processing scale, though its European presence remains import-reliant.
Europe almond milk denotes a non-dairy beverage produced by blending soaked almonds with water, typically containing two to twelve percent almond content, then homogenized and ultra-high-temperature treated for ambient or chilled distribution; its primary purpose is to serve lactose-intolerant consumers, vegan diets, and specialty coffee preparation requiring stable microfoam. Unsweetened variants lead volume in German and French supermarkets where sugar-reduction labeling influences basket choice. Tetra Pack formats dominate ambient retail, though chilled bottles command margin premiums in urban convenience channels. Food manufacturers represent the fastest-growing end-user segment as bakery and confectionery reformulators adopt almond milk for clean-label positioning.
EFSA allergen thresholds and EU organic regulation shape formulation transparency and sourcing documentation requirements across the value chain. The EU Green Deal's farm-to-fork targets pressure brands to shorten supply distances and verify water-stress metrics in almond cultivation regions. Stakeholders must monitor evolving EFSA guidance on nut-based beverage nutritional equivalence claims and decide whether to invest in regional European almond cultivation partnerships or maintain established import arrangements.
Market Dynamics
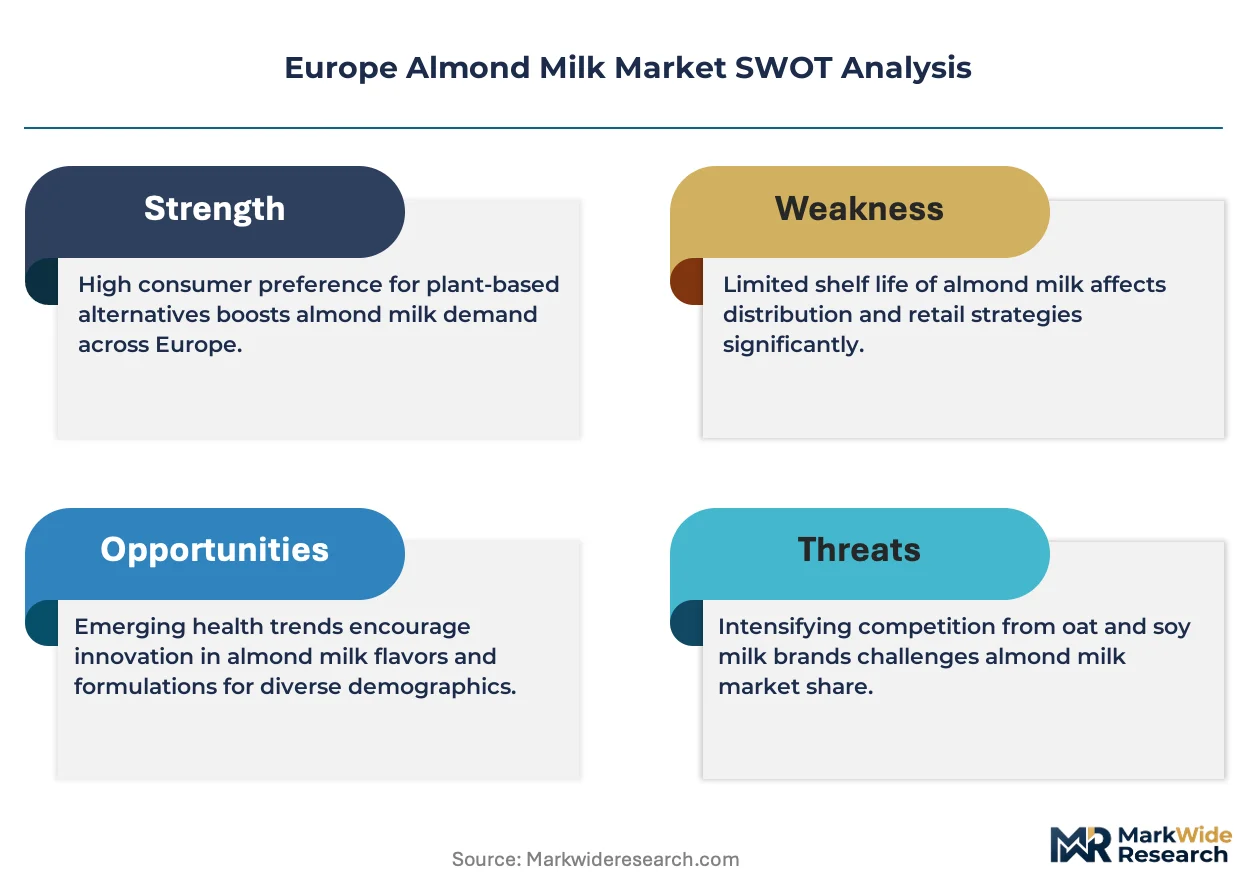
EFSA allergen labeling mandates and EU organic certification requirements are compressing formulation flexibility while Mediterranean and Australian sourcing routes displace California-dependent procurement patterns.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Water-stress verification requirements pressure brands toward shorter supply distances and documented sustainability metrics in almond cultivation.
- Specialty café channel expansion:German, French, and Italian coffee shops now standardize almond milk alongside oat and soy alternatives, creating pull-through for barista-grade formulations.
- Sugar-reduction labeling influence:Unsweetened variants lead German and French supermarket basket choices as health-conscious consumers prioritize clean-label positioning.
Market Restraints
- Input cost volatility:Almond kernel prices fluctuate with California drought cycles and Mediterranean harvest variability, compressing margin stability for ambient-format producers.
- Supply concentration risk:European brands remain import-dependent for raw nut processing scale, exposing formulations to transatlantic shipping cost spikes and currency hedging complexity.
- Technical limitation:Microfoam stability in barista applications requires hydrocolloid stabilization systems that complicate clean-label claims and organic certification pathways.
Strategic Opportunities
- Underpenetrated Italian retail:Chilled-dairy-alternative shelf space lags Northern European penetration, creating white space for dedicated almond milk cooler door placements in Rome and Milan convenience channels.
- Food manufacturer segment:Bakery and confectionery reformulators adopt almond milk for clean-label positioning, representing the fastest-growing end-user vertical beyond beverage retail.
- Regulatory tailwind:CSRD sustainability disclosure requirements favor brands with verified Mediterranean or Australian origin documentation, rewarding early supply chain reconfiguration investments.
Industry Challenges
- Certification timeline compression:EU organic regulation updates demand accelerated sourcing documentation that outpaces existing supplier audit cycles, delaying product launches.
- Capex intensity:In-house UHT processing infrastructure for ambient Tetra Pack formats requires capital deployment that mid-scale challengers struggle to finance against established chilled-bottle competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Almond Milk Market |
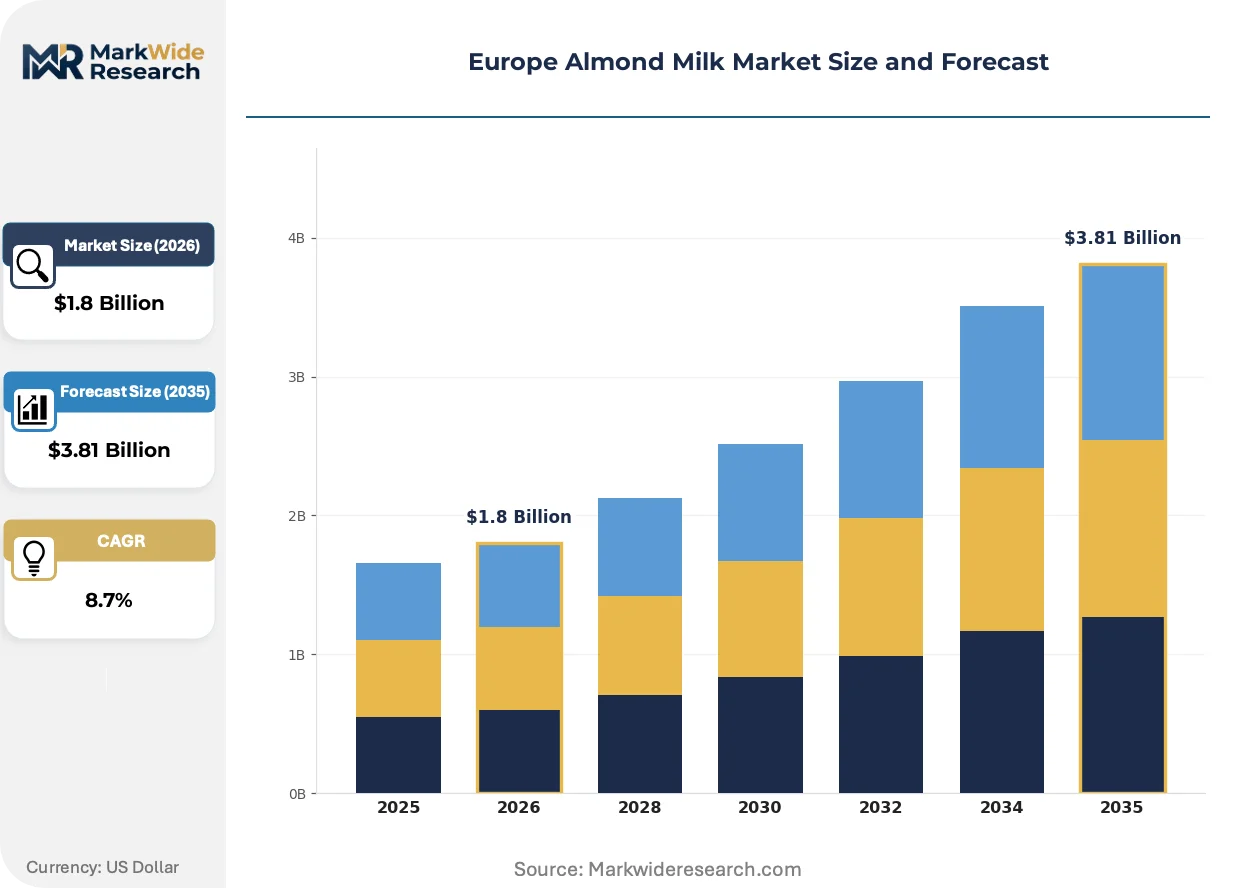
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Flavored, Organic End User: Households, Restaurants, Cafés, Food Manufacturers Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Supermarkets, Online, Health Stores, Convenience Stores |
| Companies Covered | Alpro S.A., Califia Farms, Danone S.A., SunOpta Inc., Pacific Foods of Oregon, Blue Diamond Growers, Oatly Group AB, Britvic PLC, Nestlé S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Almond Milk Market Trends and Innovations
Formulation science and packaging technology are converging to solve the microfoam stability problem that has historically limited almond milk penetration in specialty coffee channels.
High-pressure homogenization combined with enzymatic lipid modification is overtaking traditional stabilization approaches. German and French barista-grade producers adopt these systems to achieve oat-milk-comparable foam structure without hydrocolloid additives. The technology is overtaking conventional processing lines in new facility investments, compressing the performance gap between almond and dairy alternatives in café applications.
EFSA guidance evolution on nut-based beverage nutritional equivalence claims is tightening label transparency requirements. Manufacturers must reformulate fortification levels or restrict specific health positioning statements. German retail channels show the strongest compliance response, with several brands preemptively adjusting packaging claims ahead of formal enforcement timelines.
Café procurement managers now specify origin-verified almond milk with documented water-stress metrics. Specialty coffee chains in Berlin and Munich replace undifferentiated supply contracts with direct sourcing partnerships. This specification shift is most visible in urban German convenience channels, where chilled bottle premiums increasingly reflect traceability certification rather than brand equity alone.
Europe Almond Milk Market Segmentation
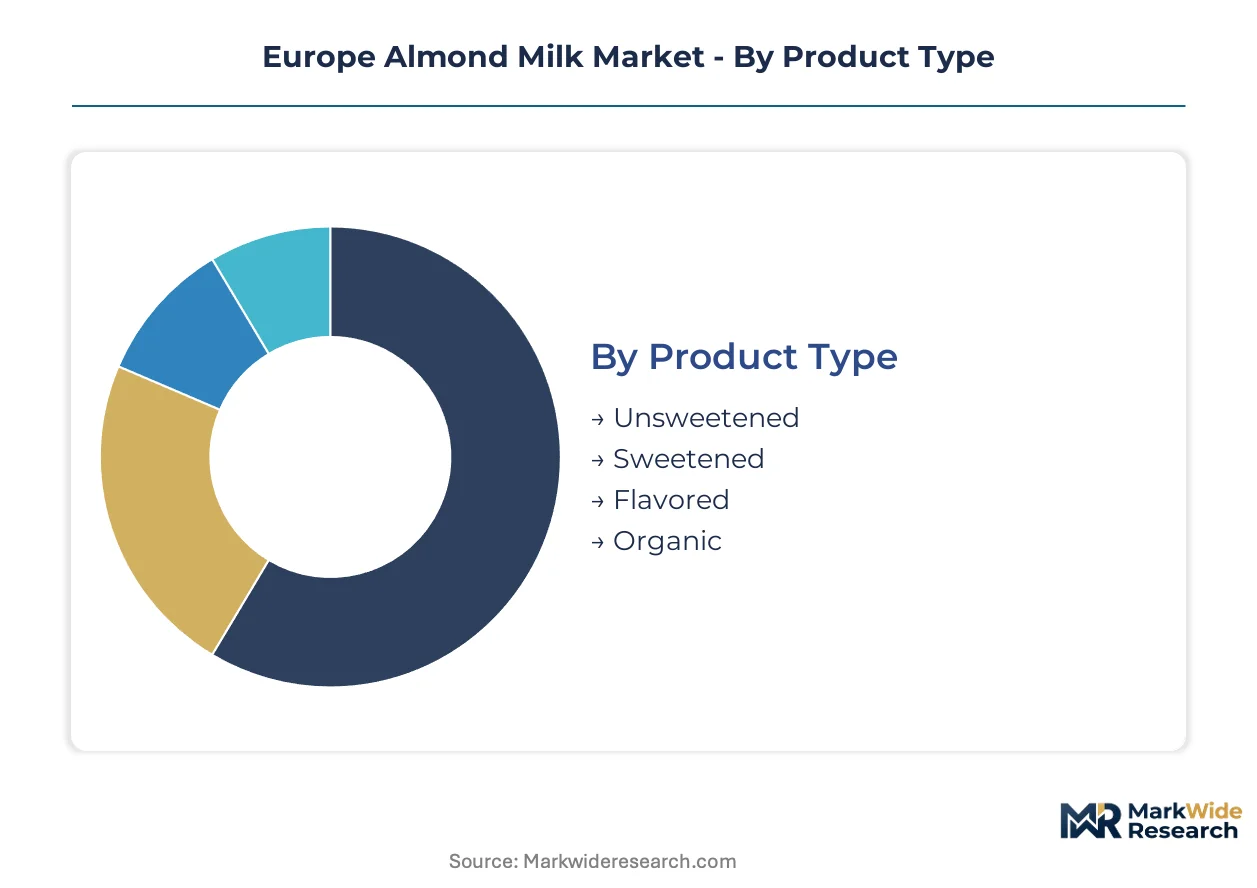
Almond milk purchasing decisions in Europe hinge on formulation transparency, café-grade performance, and shelf-stable logistics. Segmentation reveals where margin concentrates versus where volume scales.
Product Type:
Clean-label preferences and sugar-reduction mandates drive formulation selection across German and French retail channels.
- Unsweetened:Zero-added-sugar formulations with two to four percent almond content dominate German supermarket baskets. Health-conscious consumers in Berlin and Munich prioritize front-of-pack labeling that signals reduced caloric load.
- Organic:EU-certified organic variants command chilled-door placement premiums in urban French convenience channels. EFSA documentation requirements and water-stress verification protocols from Mediterranean sourcing regions shape procurement timelines.
- Sweetened:Vanilla and chocolate variants retain volume in Southern European family-format purchasing.
- Flavored:Seasonal limited editions and barista-specific profiles target café channel differentiation.
Volume sits with Unsweetened; growth tilts toward Organic.
End User:
Application requirements determine formulation investment intensity and stabilization technology choices.
- Cafés:Specialty coffee preparation demands hydrocolloid-free microfoam stability achieved through high-pressure homogenization. German and Italian barista-grade procurement now specifies origin-verified supply with documented water metrics.
- Food Manufacturers:Bakery and confectionery reformulators adopt almond milk for clean-label positioning in reformulated pastries and premium chocolate. This segment expands most quickly as ingredient-grade specifications diverge from beverage retail.
- Households:Ambient Tetra Pack formats dominate pantry-stock purchasing across Northern European retail.
- Restaurants:Foodservice bulk dispensing favors cost-optimized standard formulations without barista-grade stabilization.
Margin concentrates in Cafés; volume scales through Households.
Packaging Type:
Format selection balances shelf-life extension against cold-chain cost structures and urban convenience access.
- Tetra Packs:Aseptic carton formats with UHT treatment dominate ambient retail distribution across German and Benelux supermarkets. Extended shelf life without refrigeration enables pantry-stock purchasing and reduces retail shrink.
- Bottles:Chilled PET and glass containers command premium placement in French and Italian urban convenience channels. Perceived freshness and barista-grade positioning justify distribution cost structures.
- Cans:Single-serve aluminum formats target on-the-go consumption in transit retail.
- Pouches:Flexible packaging for bulk foodservice dispensing and manufacturing ingredient supply.
Volume sits with Tetra Packs; margin expansion favors Bottles.
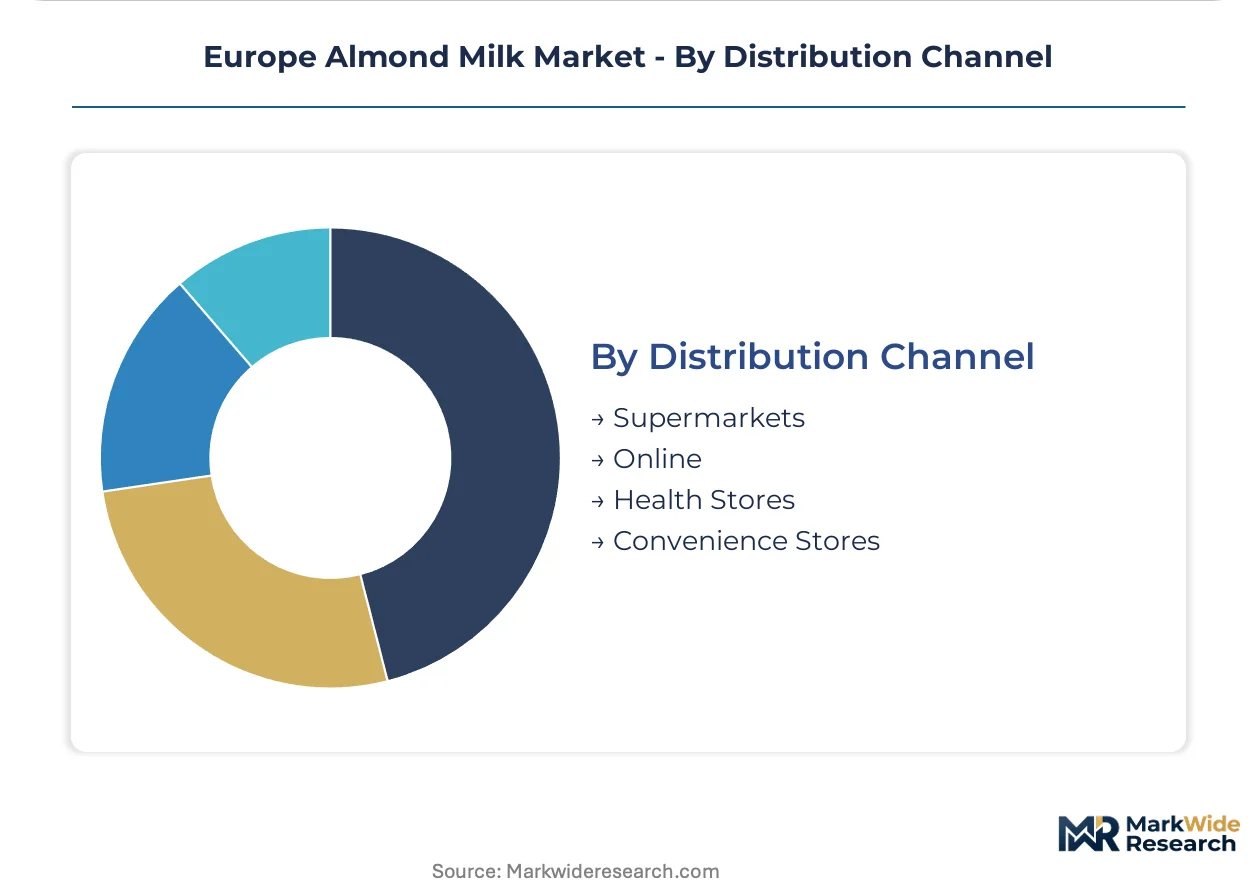
Distribution Channel:
Channel selection determines pricing architecture and consumer education requirements for specialty formulations.
- Supermarkets:Dedicated chilled-dairy-alternative shelf space in German and French hypermarkets anchors volume distribution. Retailer private-label expansion compresses branded margin while expanding category penetration.
- Online:Direct-to-subscription models and specialized health platforms build loyalty for organic and barista-grade variants. German consumers show strongest adoption of recurring delivery for ambient multi-pack formats.
- Health Stores:Independent organic retailers in France and Italy curate premium-positioned SKUs with full provenance documentation.
- Convenience Stores:Chilled single-serve bottles target impulse purchasing in urban Italian and Spanish transit locations.
Volume sits with Supermarkets; growth tilts toward Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean almond cultivation in Spain and Italy supplies European processors seeking shorter supply distances and documented water-stress metrics under EU Green Deal farm-to-fork targets.
Germany
Berlin and Munich retail channels drive volume for organic and barista-grade variants. EFSA allergen labeling rules tighten formulation transparency requirements. Bavaria's food-tech clusters host high-pressure homogenization equipment suppliers serving stabilized microfoam development.
France
Urban convenience channels in Paris command premium placement for chilled bottles with traceability certification. EU organic regulation updates accelerate sourcing documentation demands. The Île-de-France region anchors Danone S.A.'s plant-based R&D infrastructure for barista formulations.
Italy
Rome and Milan convenience channels show underpenetrated chilled-dairy-alternative shelf space relative to Northern Europe. CSRD sustainability disclosure requirements favor brands with verified Mediterranean origin documentation. Lombardy-based specialty cafés now standardize almond milk alongside traditional alternatives.
Spain
Andalusian almond orchards provide European brands with drought-cycle diversification from California-dependent procurement. The EU Green Deal pressures water-stress verification in cultivation regions. Valencia and Catalonia processing hubs shorten supply distances for Tetra Pack ambient distribution.
Netherlands
Benelux retail channels anchor volume through dedicated chilled-dairy-alternative shelf space. REACH compliance shapes packaging material specifications for aseptic carton formats. Rotterdam logistics clusters facilitate Mediterranean and Australian import routing.
Europe Almond Milk Market Competitive Landscape
Global majors compete with regional champions across formulation technology and sourcing documentation capabilities. The vendor base separates into three tiers: multinational dairy-alternative conglomerates with integrated R&D infrastructure, specialized nut-processing scale operators, and agile private-label challengers. Two dominant competitive moves are reshaping positioning: direct sourcing partnerships with origin-verified Mediterranean orchards, and high-pressure homogenization capacity investments for hydrocolloid-free barista formulations.
Among multinational conglomerates, Danone S.A. and Nestlé S.A. exemplify the integrated R&D archetype with captive plant-based development infrastructure. Alpro S.A. anchors the regional specialist tier with dedicated chilled-dairy-alternative shelf space dominance in Benelux channels. Blue Diamond Growers occupies a position representing raw nut processing scale, though its European presence remains import-reliant.
| Leading Market Players |
|---|
| Alpro S.A. |
| Califia Farms |
| Danone S.A. |
| SunOpta Inc. |
| Pacific Foods of Oregon |
| Blue Diamond Growers |
| Oatly Group AB |
| Britvic PLC |
| Nestlé S.A. |
| Others |
Pricing and Supply Chain Analysis
Barista-grade certification against commodity ambient formats splits the market into divergent value capture tiers, with the former commanding chilled-door premiums in Berlin and Munich while the latter competes on pantry-stock volume through Tetra Pack logistics. This bifurcation traces directly to supply chain configuration: origin-verified Mediterranean sourcing with EFSA documentation supports premium positioning, whereas California-dependent bulk procurement feeds cost-optimized standard formulations.
Pricing Analysis
Service-bundling separates traceability-certified supply contracts from undifferentiated bulk purchasing. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status and barista-grade microfoam performance. Price differentiation hinges on EFSA allergen documentation completeness and water-stress verification protocols. Cost compression in ambient Tetra Pack tiers is intensifying because retailer private-label expansion erodes branded margin. German supermarket buyers show highest price sensitivity; Italian café procurement managers demonstrate lowest sensitivity given specification requirements.
Supply Chain Analysis
Workforce availability in Valencia and Catalonia processing hubs underpins European Tetra Pack capacity expansion against chilled-bottle concentration in Bavarian food-tech clusters. Raw nut supply draws from Andalusian orchards, Australian drought-cycle diversification regions, and residual California import channels. Almond kernel, hydrocolloid stabilizers, and aseptic packaging materials constitute critical input dependencies. Single-source vulnerability concentrates in California drought-exposed procurement. Distribution runs through Rotterdam logistics clusters for Mediterranean and Australian import routing, then disperses to Benelux retail and German urban convenience channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure homogenization systems are displacing legacy hydrocolloid stabilization in barista-grade formulation, compressing the performance gap with oat milk and rewriting competitive requirements across European café channels.
For Market Incumbents: Anticipate margin compression in ambient Tetra Pack formats as retailer private-label expansion accelerates in German and French supermarkets. Defensive moves require backward integration into Mediterranean almond cultivation partnerships with EFSA-compliant documentation, plus captive high-pressure homogenization capacity in Bavaria or Île-de-France to lock in barista-grade supply contracts before equipment scarcity tightens. For New Entrants and Emerging Players: Direct-to-subscription digital routes offer lowest customer acquisition cost for organic and barista-grade variants in German urban markets. White space targets include underpenetrated chilled-door placement in Rome and Milan convenience channels, plus ingredient-grade supply to bakery and confectionery reformulators seeking clean-label positioning. Food manufacturer segment penetration offers fastest volume scaling with lowest brand equity requirements. For Investors and Strategic Acquirers: Re-rating potential sits with Mediterranean-origin-verified processors given CSRD sustainability disclosure tailwinds and EU Green Deal farm-to-fork compliance premiums. Long-term viability favors operators with documented water-stress metrics and shortened supply distances against California-dependent import models. Watch EFSA guidance evolution on nut-based beverage nutritional equivalence claims as inflection indicator for fortification investment requirements and label restriction risk.| Strategic Initiative | Industry Significance |
|---|---|
| Mediterranean Sourcing Partnership | EFSA documentation and water-stress verification unlock premium pricing in German café channels. |
| High-Pressure Homogenization Investment | Hydrocolloid-free microfoam capability captures barista-grade specifications from Berlin procurement managers. |
| Chilled-Door Expansion | Dedicated cooler placement in Rome and Milan addresses underpenetrated Italian retail against Northern European benchmarks. |
| Food Manufacturer Supply Agreement | Ingredient-grade positioning in bakery and confectionery reformulation accesses fastest-growing end-user vertical. |
| CSRD Compliance Certification | Verified origin documentation rewards early supply chain reconfiguration under EU sustainability disclosure mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant-based R&D directors, café procurement managers, almond orchard operators, and chilled-dairy-alternative category buyers at German and French retailers combined with EFSA guidance documents, EU organic certification databases, and CSRD disclosure filings. Bottom-up volume modeling and top-down value reconciliation triangulated across these sources.
Data-stream reconciliation aligned production capacity announcements, import flow patterns, and channel inventory turns across the projection horizon. Segmentation dimensions modeled include product type, end-user application, packaging format, and distribution channel, with additional granularity on certification tier and geographic origin. CAGRs derived from trend extrapolation against historical growth inflection points, incorporating almond kernel price volatility cycles and café channel expansion rates as industry-specific inputs.
The model holds under stable EFSA regulatory interpretation and continued EU Green Deal implementation; deviation in drought severity across Mediterranean cultivation regions or transatlantic shipping cost spikes would shift volume and value trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
North America Almond Milk Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Global Milk Replacers Market