
 Milk Protein Crisps Market | 2026-2036
Milk Protein Crisps Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Protein Crisps Market Analytics
Sports nutrition is recalibrating its ingredient matrix as endurance and strength-training consumers shift toward textured protein inclusions over conventional powders. Glanbia plc leverages its whey protein isolate capabilities to supply crisp formats that anchor the functional bar segment across North America. Saputo Inc. competes through dairy protein fractionation expertise that extends into value-added crisp applications for bakery customers.
Milk protein crisps are extruded or puffed protein matrices derived from whey or casein fractions, typically containing 50-80% protein by weight and manufactured through high-temperature short-time extrusion to create crunchy, low-moisture inclusions for food fortification. Whey Crisp dominates volume due to its superior solubility and neutral flavor profile, while Blended Crisp formats are gaining fastest in sports nutrition applications where texture and amino acid completeness matter. Functional Foods represents the deepest margin pool as pharmaceutical-grade protein positioning commands premium pricing over conventional snacking applications.
The FDA oversees protein content labeling and health claim substantiation for milk protein crisps sold in the United States, while the USDA administers dairy grading standards that affect raw material quality tiers. The EU's EFSA evaluates novel protein processing methods under the Novel Food Regulation, creating compliance thresholds that filter smaller suppliers from European market access. Stakeholders must monitor evolving protein digestibility-corrected amino acid score methodologies as these recalibrate formulation standards across jurisdictions.
Market Dynamics
The Milk Protein Crisps Market pivots on clean-label protein fortification mandates that are compressing formulation cycles across sports nutrition and functional snacking. Texture-driven consumer preferences are forcing manufacturers to abandon conventional powder inclusions for extruded protein matrices that deliver crunch without compromising amino acid density.
Growth Catalysts
- Novel Food Regulation:The EU's updated ingredient transparency requirements are filtering non-compliant suppliers from European distribution channels, creating shelf space for certified whey crisp producers.
- Performance Nutrition:Endurance and strength-training consumers are driving textured protein inclusion demand across North American functional bar formulations.
- Extrusion Technology:High-temperature short-time processing advances are enabling 50-80% protein density matrices with neutral flavor profiles previously unattainable at commercial scale.
Market Restraints
- Dairy Input Volatility:Whey protein isolate feedstock costs fluctuate with global milk powder commodity cycles, compressing margin predictability for crisp manufacturers.
- Regulatory Friction:EFSA novel protein processing evaluations under EU Novel Food Regulation create 18-24 month approval timelines that freeze smaller suppliers out of European market access.
- Substitution Threat:Pea and fava protein crisps are capturing price-sensitive bakery customers seeking plant-based fortification alternatives.
Strategic Opportunities
- Japan Functional Foods:METI-backed longevity nutrition initiatives are opening distribution channels for pharmaceutical-grade protein positioning in aging-population formulations.
- Direct-to-Consumer Channels:Subscription-based performance nutrition platforms are bypassing traditional retail gatekeepers for whey crisp ingredient bundles.
- Blended Crisp Convergence:Casein-whey hybrid matrices are unlocking texture-amino acid completeness combinations that monofraction crisps cannot achieve.
Industry Challenges
- Extrusion Engineering Talent:Food protein rheology specialization scarcity is constraining R&D throughput for novel crisp density formulations.
- PDCAAS Recalibration:Evolving protein digestibility-corrected amino acid score methodologies are forcing reformulation cycles across FDA and EFSA jurisdictions.
- Legacy Equipment Retrofit:Conventional snack extrusion lines require capital-intensive modification to achieve the precise moisture-temperature profiles milk protein matrices demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Protein Crisps Market |
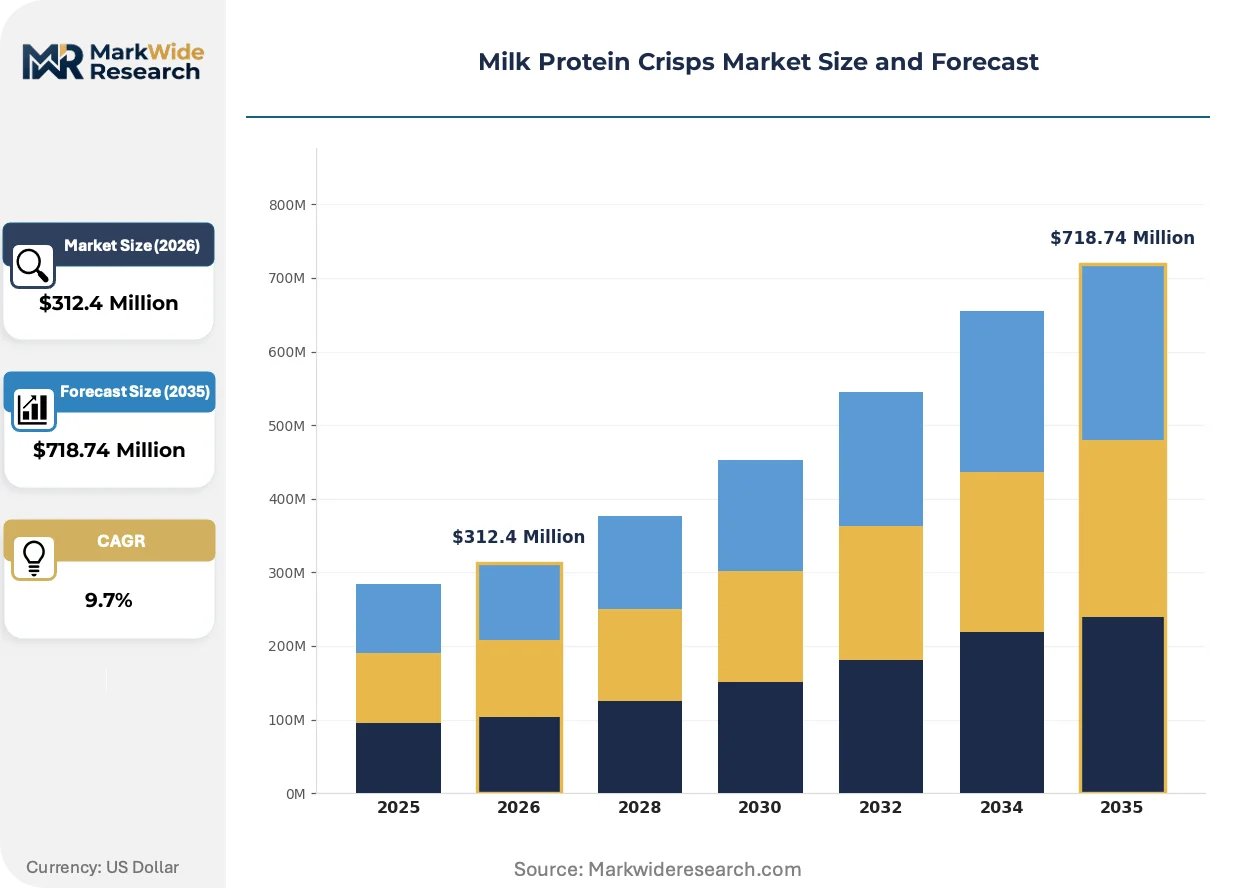
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Crisp, Casein Crisp, Blended Crisp, Plant-based Crisp Application: Snacking, Functional Foods, Sports Nutrition, Bakery Form: Powder, Bar, Coating, Ready-to-eat Distribution Channel: Online, Supermarkets, Health Stores, Specialty Retailers |
| Companies Covered | Glanbia plc, Saputo Inc., Leprino Foods Company, Hilmar Cheese Company, Inc., Lactalis American Group, Fonterra Co-operative Group Limited, Royal FrieslandCampina N.V., Agropur Dairy Cooperative, Arla Foods amba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Protein Crisps Market Evolving Landscape
Processing precision and regulatory transparency are converging to reshape competitive positioning in protein fortification. Manufacturers are racing to deploy sensor-driven extrusion control and blockchain-verified supply chains before certification mandates harden.
High-temperature short-time extrusion with inline near-infrared moisture sensing is automating density consistency in whey crisp production. Sports nutrition contract manufacturers in the United States are adopting these systems at pilot scale. The technology is automating quality variance reduction that previously required manual batch oversight.
EFSA's expanded novel protein processing evaluations under the EU Novel Food Regulation are compressing formulation disclosure requirements. Ingredient dossiers must now document extrusion temperature profiles and amino acid retention rates. European functional food brands are responding by consolidating supplier bases to pre-certified whey fractionation specialists.
Clean-label procurement is rotating buyer preference toward single-origin dairy protein traceability. North American performance nutrition brands are displacing anonymous commodity whey with farm-identified crisp inclusions. This shift is most visible in United States subscription-based direct-to-consumer channels where ingredient storytelling drives retention.
Milk Protein Crisps Market Segmentation
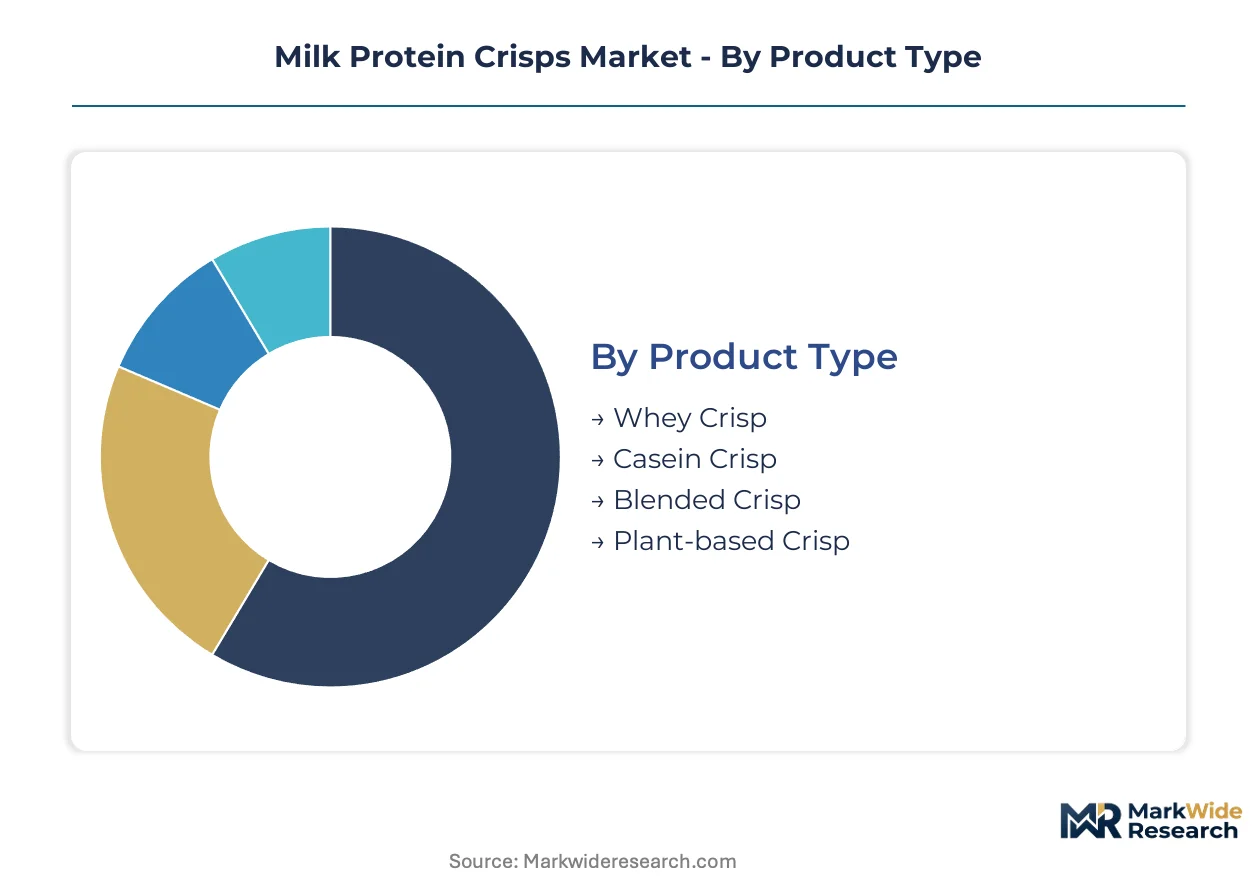
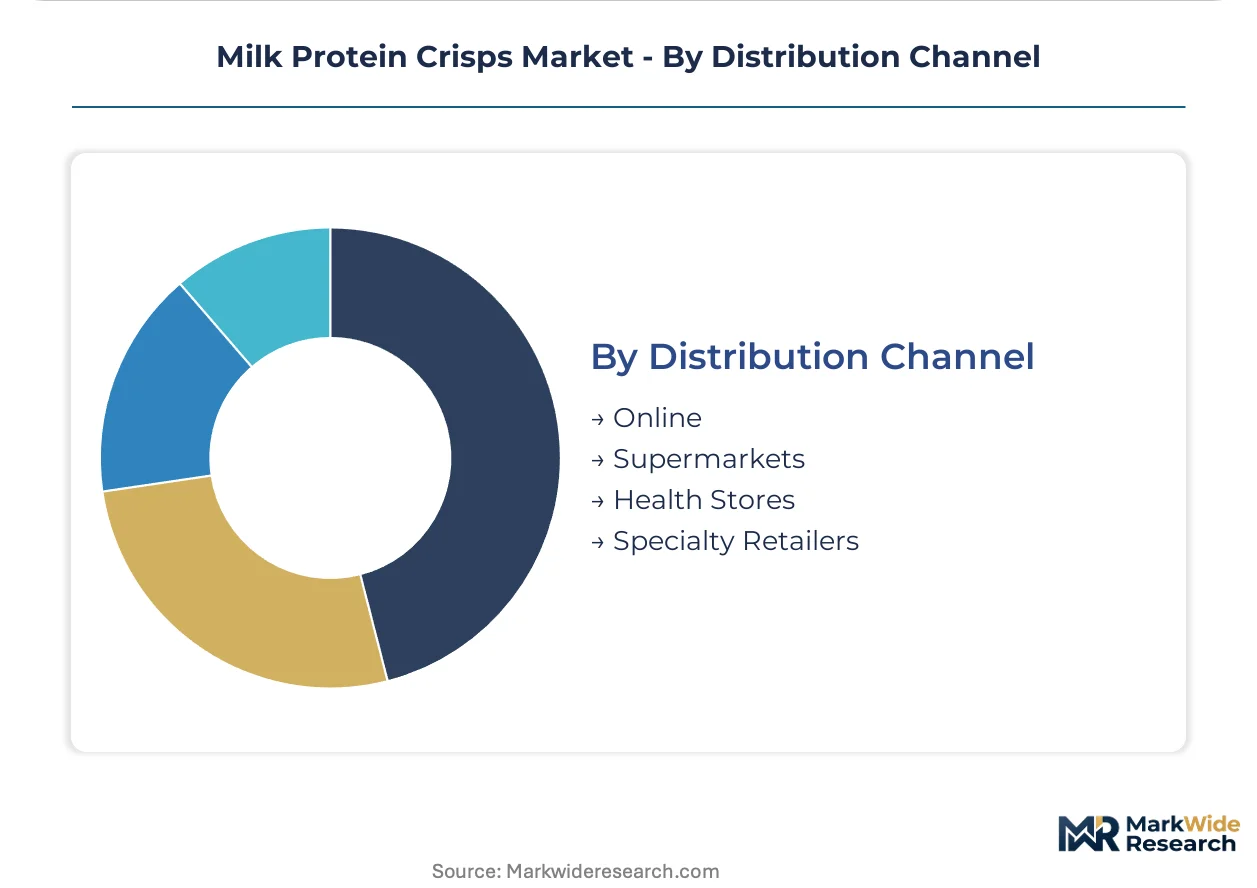
Milk protein crisps fragment across four distinct dimensions, each reflecting divergent buyer priorities from texture engineering to procurement channel preferences. Understanding where demand concentrates within each category enables suppliers to align extrusion capabilities with margin pools.
Product Type:
Buyers in this category differentiate by protein fraction solubility, amino acid completeness, and clean-label positioning requirements.
- Whey Crisp:Extruded whey protein isolate matrices containing 50-80% protein by weight with superior solubility and neutral flavor profiles. Demand concentrates in United States sports nutrition bars where rapid amino acid absorption drives formulation choices.
- Blended Crisp:Casein-whey hybrid matrices engineered for texture-amino acid completeness combinations. United States functional food manufacturers are adopting these for overnight recovery positioning and sustained-release protein claims.
- Casein Crisp:Micellar casein-based matrices with slower digestion kinetics and denser mouthfeel.
- Plant-based Crisp:Pea and fava protein alternatives capturing price-sensitive bakery customers seeking vegan fortification.
Volume sits with Whey Crisp; growth tilts toward Blended Crisp.
Application:
End-use buyers separate by margin tolerance, regulatory scrutiny intensity, and ingredient storytelling requirements.
- Functional Foods:Pharmaceutical-grade protein positioning in longevity and clinical nutrition applications commanding premium pricing tiers. Japan's METI-backed aging-population initiatives are opening distribution channels for certified whey crisp suppliers.
- Sports Nutrition:Performance bars and recovery formulations where texture-driven consumers reject conventional powders. United States endurance and strength-training segments are forcing brands toward extruded protein inclusions.
- Snacking:Better-for-you chip and puff applications where clean-label fortification competes on taste.
- Bakery:Protein-enriched bread and pastry inclusions where moisture stability determines adoption.
Functional Foods commands the deepest margins; Sports Nutrition is expanding most quickly.
Form:
Processing requirements and shelf-stability needs drive buyer selection in this dimension.
- Bar:Pre-formed protein crisp inclusions bonded with hydrocolloids for cohesive texture in finished products. United States contract manufacturers are standardizing on 2-4mm particle sizes for uniform distribution.
- Powder:Milled crisp fragments for beverage and smoothie fortification with rapid dispersibility.
- Coating:Surface-applied crisp layers adding crunch to confectionery and nutrition bar exteriors.
- Ready-to-eat:Standalone crisp snacks requiring minimal further processing by end consumers.
Bar format dominates current procurement; Powder is gaining share fastest in beverage applications.
Distribution Channel:
Buyer reach and margin retention trade-offs define channel strategy for crisp suppliers.
- Online:Direct-to-consumer and B2B ingredient platforms bypassing retail gatekeepers. United States subscription-based performance nutrition brands are consolidating procurement through verified supplier portals.
- Specialty Retailers:Dedicated sports nutrition and health food stores with educated staff and premium positioning.
- Supermarkets:Mass-market penetration requiring price competitiveness and broad consumer appeal.
- Health Stores:Independent retailers emphasizing local and traceable sourcing credentials.
Supermarkets move the highest tonnage; Online channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the United States and strategic dairy processing corridors in the Netherlands concentrate milk protein crisp production capacity. FDA and USDA oversight shapes formulation standards. EFSA novel food evaluations filter European market access.
United States
Sports nutrition bar manufacturers in the Midwest and California drive whey crisp procurement volumes. FDA protein content labeling rules and USDA dairy grading standards create compliance tiers that favor large-scale whey fractionators. Chicago-area extrusion facilities supply contract manufacturers serving endurance and strength-training brands.
Germany
Functional food brands in Bavaria and North Rhine-Westphalia import pharmaceutical-grade protein crisps for longevity positioning. EFSA novel food processing evaluations under EU regulations extend approval timelines for non-certified suppliers. Munich-based ingredient distributors consolidate procurement toward pre-certified whey specialists.
Japan
METI-backed longevity nutrition initiatives open distribution channels for high-purity protein crisps in aging-population formulations. PMDA oversight of functional food claims shapes positioning requirements. Osaka and Nagoya clusters host contract manufacturers blending milk protein crisps into clinical nutrition products.
Netherlands
Dairy protein fractionation expertise concentrates in Wageningen and Rotterdam port corridors serving EU and export markets. EFSA transparency mandates accelerate supplier consolidation. Dutch extrusion technology providers equip manufacturers achieving 50-80% protein density matrices.
Canada
Health Canada protein fortification guidelines influence cross-border formulation standards for US-exporting manufacturers. Agropur and Saputo processing networks in Quebec and Ontario supply whey fractions for crisp production. Toronto-area R&D facilities develop casein-whey hybrid matrices for texture optimization.
Milk Protein Crisps Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with dairy cooperatives and publicly traded ingredient companies commanding distinct tier positions. The vendor base organizes around three archetypes: integrated dairy processors with captive whey streams, independent protein fractionators serving multi-source buyers, and sports nutrition contract manufacturers backward-integrating into ingredient production. M&A activity concentrates on whey processing asset acquisition, while capacity expansion focuses on high-temperature short-time extrusion lines.
Among Irish and Canadian publicly traded ingredient specialists, Glanbia plc and Saputo Inc. exemplify the integrated processor archetype with dairy protein fractionation capabilities extending into value-added crisp applications. Leprino Foods Company represents the private, family-owned dairy processor model with significant North American whey production infrastructure. These three entities anchor competitive dynamics as buyers consolidate procurement toward suppliers with verified extrusion capabilities and regulatory pre-certification.
| Leading Market Players |
|---|
| Glanbia plc |
| Saputo Inc. |
| Leprino Foods Company |
| Hilmar Cheese Company, Inc. |
| Lactalis American Group |
| Fonterra Co-operative Group Limited |
| Royal FrieslandCampina N.V. |
| Agropur Dairy Cooperative |
| Arla Foods amba |
| Others |
Value Network & Pricing Analysis
Whey protein isolate commodity benchmarks cascade through milk protein crisp supply chains into three distinct procurement tiers. FDA certification tiers and EFSA novel food pre-approval status stratify supplier pricing power, with uncertified manufacturers absorbing margin compression while pre-certified fractionators command premium positioning.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate expedited whey crisp procurement from standard contract schedules. Three-tier pricing structure across pharmaceutical-grade, sports nutrition-grade, and commodity bakery-grade certification levels reflects extrusion precision and amino acid retention documentation. Cost compression in commodity bakery tiers intensifies because pea protein substitutes capture price-sensitive volume buyers. Functional food manufacturers exhibit least price sensitivity due to clinical positioning requirements, while mass-market snack brands drive hardest bargain negotiations.
Supply Chain Analysis
Refrigerated freight costs from Midwest dairy processing corridors to coastal extrusion facilities add meaningful landed cost variance across United States distribution networks. Raw material supply concentrates in Wisconsin and California whey fractionation plants, with Dutch port corridors serving European demand. Feedstock dependencies span whey protein isolate, micellar casein, and hydrocolloid binding agents. Single-source vulnerability around high-temperature short-time extrusion equipment manufacturers creates procurement bottleneck risk. Distribution runs through B2B ingredient platforms and direct contract manufacturing relationships rather than commodity spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Novel Food Regulation compliance costs erect formidable barrier-to-entry moats favoring incumbent whey fractionators with pre-certified dossiers. EFSA's eighteen-to-twenty-four-month evaluation timelines freeze capital-constrained entrants from European market access, consolidating pricing power among certified suppliers.
For Market Incumbents: Deploy extrusion capacity expansion in Rotterdam and Chicago corridors to anchor supply security for sports nutrition contract manufacturers. Consolidate supplier relationships with Midwest dairy cooperatives to lock whey protein isolate feedstock streams against commodity volatility. Counter pea protein substitution threats by accelerating casein-whey hybrid crisp development for texture-differentiated positioning.
For New Entrants and Emerging Players: Capture Japan METI-backed longevity nutrition channels where pharmaceutical-grade protein positioning commands premium procurement tolerance. Target direct-to-consumer subscription platforms in United States bypassing retail gatekeeper consolidation. Pursue co-manufacturing partnerships with established extrusion facilities rather than greenfield capacity investment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap whey fractionators with dormant extrusion assets in Netherlands and Canada. Long-term viability hinges on regulatory certification asset accumulation rather than commodity scale alone. Watch EFSA novel food approval velocity as inflection indicator for European market access premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Pre-Certification Investment | Novel Food dossier completion unlocks European distribution channels before competitors clear regulatory gates. |
| Casein-Wey Hybrid Matrix Development | Texture-amino acid completeness combinations differentiate sports nutrition formulations from commodity whey alternatives. |
| Direct-to-Consumer Channel Partnership | Subscription platform procurement bypasses retail margin compression and enables ingredient storytelling premium capture. |
| Inline Near-Infrared Sensor Deployment | Automated moisture sensing reduces batch variance and manual quality oversight labor costs. |
| Single-Origin Dairy Traceability Program | Farm-identified sourcing credentials satisfy clean-label procurement rotation among North American performance nutrition brands. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with sports nutrition brand formulators, dairy cooperative procurement directors, and extrusion equipment engineers. FDA GRAS notification databases, EFSA novel food registers, and USDA dairy grading reports supplied regulatory trajectory validation. Bottom-up whey crisp volume estimates triangulated against top-down sports nutrition bar production data.
Segment-level modeling captured whey crisp, blended crisp, and casein crisp product dynamics across functional foods, sports nutrition, snacking, and bakery applications. Protein density tiers, extrusion technology generations, and distribution channel mix were modeled at country-level granularity. CAGRs derived from regression analysis against whey protein commodity price cycles and clean-label procurement trend indices.
The model holds under stable dairy input cost regimes and continued EFSA evaluation timeline consistency; deviation in whey protein isolate commodity spikes or regulatory acceleration would shift margin pool distribution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Africa Dairy Protein Market
Dairy Products
Low Fat Cheese Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
North America Dairy Market
Dairy Products
Clotted Cream Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
China Dairy Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Organic Milk Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Cream Powder Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Emmental Cheese Market
Dairy Products
North America Organic Dairy Market