
 Coconut Cream Market | 2026-2036
Coconut Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Cream Market Outlook
Organic certification under USDA NOP and EU Regulation 2018/848 is rotating supplier eligibility, favoring processors with integrated farming operations. Celebes Coconut Corporation leverages its Philippine plantation network to secure certified organic feedstock. Axelum Resources Corp. dominates export channels from Mindanao with scale advantages in copra processing. Danone competes in European retail through specialized plant-based R&D pipelines.
Coconut cream is the emulsified lipid fraction extracted from mature coconut kernel, typically containing 17-25% fat by weight, obtained through mechanical pressing or wet-milling of fresh coconut meat for culinary and industrial food production. The organic product type commands premium shelf positioning as clean-label formulations displace conventional alternatives in North American and European supermarkets. Food manufacturers represent the fastest-expanding end user segment, driven by dairy-free frozen dessert and confectionery applications where coconut fat provides structural stability. Tetra pack packaging is gaining share in ambient distribution channels due to extended shelf life and reduced logistics costs versus glass jar equivalents.
FDA enforcement of Food Safety Modernization Act preventive controls and EFSA maximum residue limits for aflatoxins shape import gatekeeping and processing standards across major supply origins. BIS certification requirements in India and FSSAI quality specifications for packaged coconut products create additional compliance layers for exporters targeting South Asian retail channels. Stakeholders must monitor evolving organic equivalency agreements between the EU and Southeast Asian producer nations, as these determine which processors retain premium market access without dual certification costs.
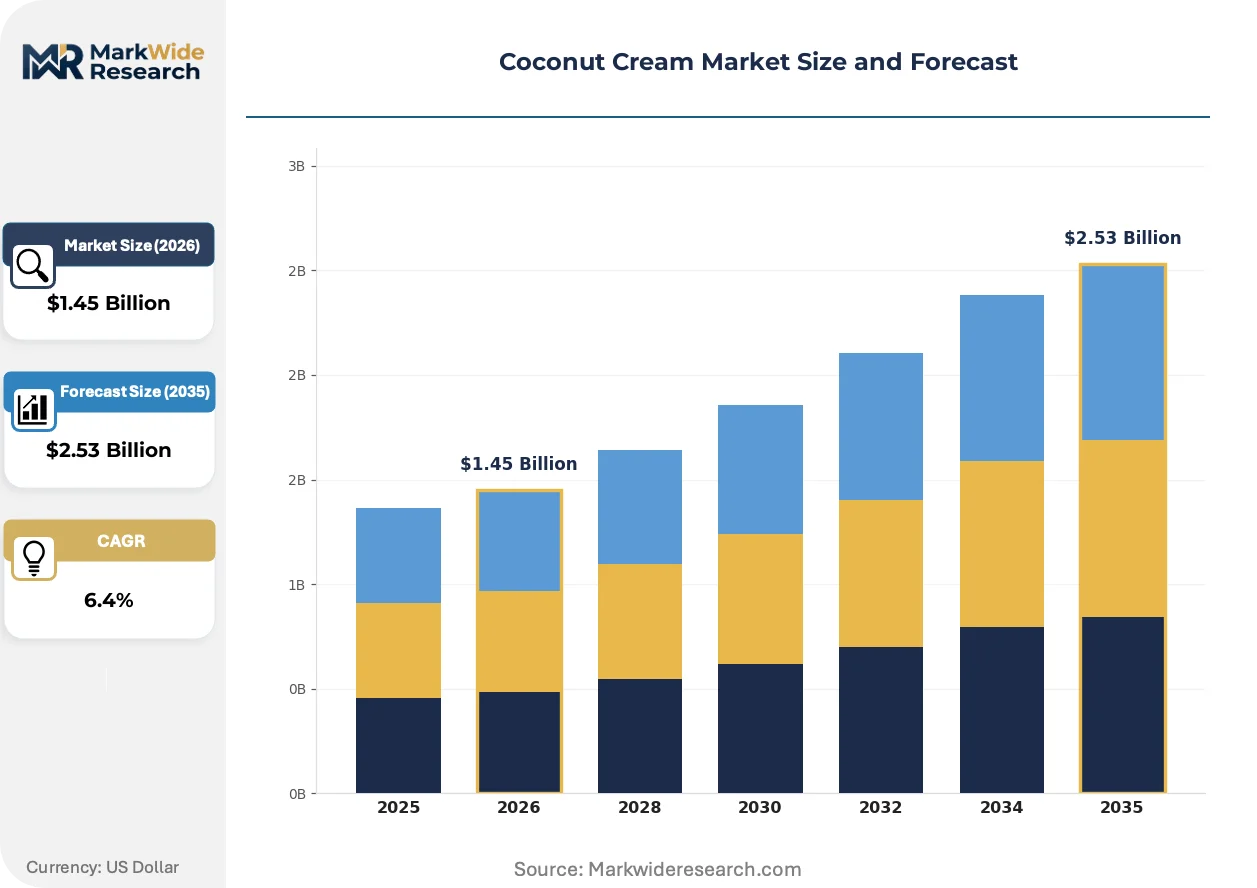
Market Dynamics
Clean-label displacement of dairy alternatives is compressing formulation cycles across food manufacturing, forcing coconut cream suppliers to accelerate organic certification timelines and fat standardization protocols.
Growth Catalysts
- FSMA Preventive Controls:FDA enforcement of hazard analysis requirements is filtering out informal processors, concentrating procurement among certified exporters with documented supply chain controls.
- Plant-based frozen desserts:Dairy-free ice cream manufacturers in the United States and Germany are specifying coconut fat for structural stability at sub-zero temperatures.
- Wet-milling automation:Philippine processors deploying continuous extraction systems are achieving batch consistency that satisfies European industrial buyer specifications.
Market Restraints
- Copra price volatility:Raw material costs fluctuate with Philippine and Indonesian weather patterns, compressing processor margins during El Niño drought cycles.
- Dual certification burden:Organic exporters face redundant audit costs where EU-Southeast Asian equivalency agreements remain unsigned.
- Oat and almond substitution:Neutral-flavored plant creams are displacing coconut in beverage applications where fat content requirements are less stringent.
Strategic Opportunities
- Clean-label confectionery:European chocolate manufacturers are reformulating enrobing compounds with coconut fat to eliminate hydrogenated palm oil from ingredient declarations.
- Tetra Pak ambient channels:Extended-shelf-life packaging is opening foodservice distribution in landlocked Central Asian markets previously unreachable with glass jar logistics.
- EU Organic Regulation 2018/848:Updated certification protocols favor integrated plantation-processors with in-house farming operations over third-party feedstock aggregators.
Industry Challenges
- Aflatoxin testing capacity:Laboratory bottlenecks at Indonesian export points are extending shipment release timelines beyond contractual delivery windows.
- Organic traceability systems:Smallholder aggregation networks lack digital documentation infrastructure required for EU mass balance certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Cream Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Light, Organic, Flavored End User: Households, Commercial Kitchens, Food Manufacturers, Restaurants Distribution Channel: Supermarkets, Online Retail, Health Stores, Direct Sales Packaging Type: Cans, Tetra Packs, Glass Jars, Pouches |
| Companies Covered | Danone, Nestlé, Celebes Coconut Corporation, Califia Farms, Pacific Foods of Oregon, The Vita Coco Company, Inc., Sambu Group, Axelum Resources Corp., McCormick & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Cream Market Strategic Shifts
Processing technology convergence with packaging format evolution is redrawing competitive boundaries between commodity copra processors and integrated fresh-cream specialists.
High-pressure processing equipment is miniaturizing at Philippine and Indonesian facilities, enabling on-farm sterilization that preserves volatile aromatic compounds lost in conventional heat treatment. Specialty food manufacturers in France and the United States are specifying HPP-treated cream for premium dessert applications. This capability gap is compressing price premiums between artisan and industrial-grade supply tiers.
EFSA maximum residue limits for aflatoxins are tightening import gatekeeping across Rotterdam and Hamburg entry points, forcing Southeast Asian processors to invest in controlled atmosphere storage. Rejected shipments are redirecting toward Middle Eastern markets with less stringent enforcement. Indonesian exporters with EU-recognized laboratory partnerships are capturing displaced volume from competitors lacking pre-shipment certification.
Food manufacturers are consolidating coconut cream procurement through direct-origin contracts rather than trading house intermediaries, compressing margin layers in traditional export channels. Danone and Unilever's specialized procurement teams are establishing annual volume commitments with Mindanao processors. This disintermediation is most visible in German and Dutch industrial buying offices, where sustainability audit requirements now exceed trading house capabilities.
Coconut Cream Market Segmentation
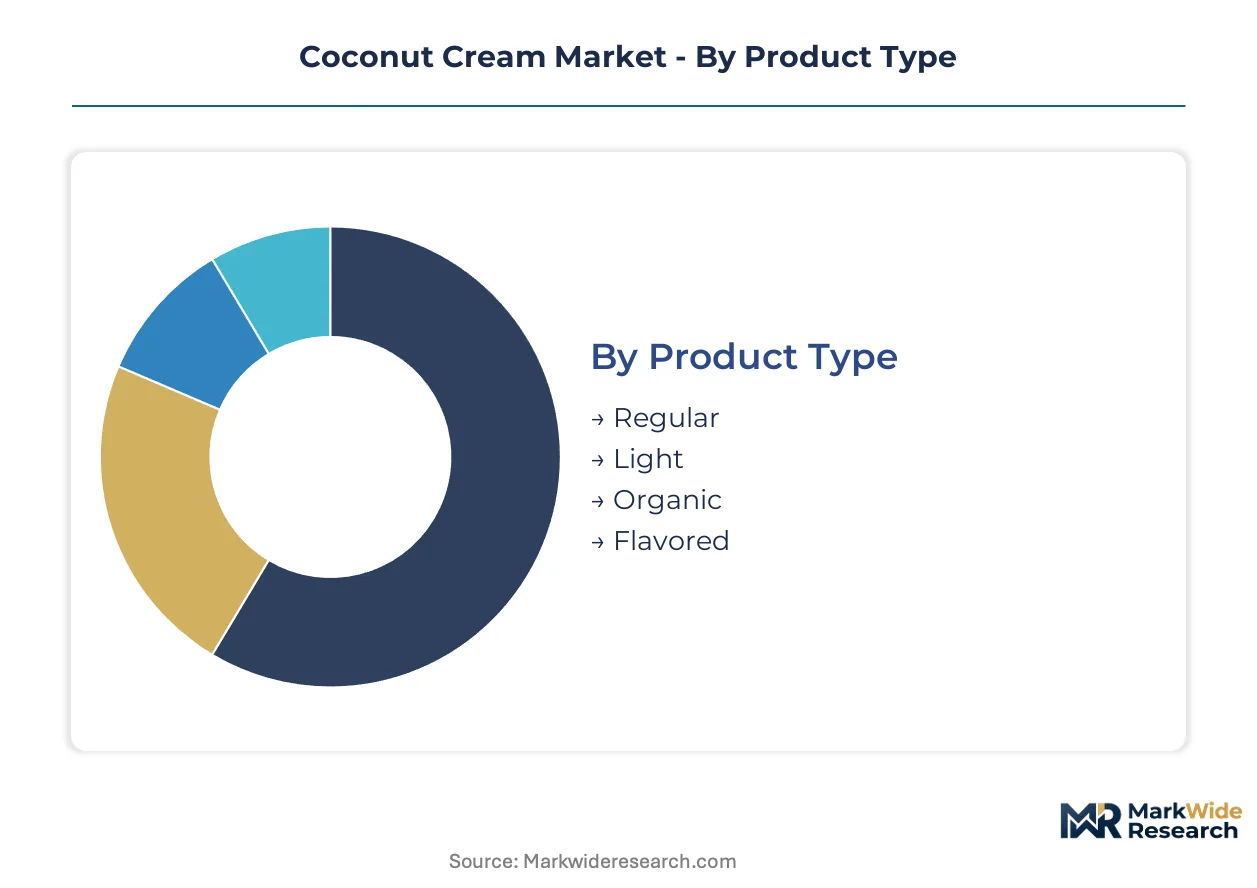
Coconut cream segmentation reveals distinct pressure points where oat and almond alternatives threaten volume, while organic and industrial-grade tiers defend margin through certification barriers and functional specifications that substitutes cannot replicate.
Product Type:
Regular and Light segments face the most acute substitution threat from neutral-flavored plant creams in beverage applications, while Organic and Flavored variants build defensive moats through clean-label positioning and proprietary taste profiles.
- Regular:Standard 17-25% fat emulsion extracted through mechanical pressing or wet-milling of mature coconut kernel. Commercial kitchens in Germany and the Netherlands specify this grade for cost-sensitive curry and soup bases where fat functionality outweighs label claims.
- Organic:Certified under USDA NOP or EU Regulation 2018/848 with integrated plantation traceability. North American supermarkets command shelf premiums as clean-label formulations displace conventional alternatives in dairy-free frozen dessert aisles.
- Light:Reduced-fat variant typically 10-15% lipid content achieved through partial skimming or dilution. Health-conscious households in France and the United Kingdom select this tier for lower-calorie cooking applications.
- Flavored:Value-added formulations incorporating vanilla, pandan, or spice extracts. Southeast Asian retail channels and specialty Asian grocery networks in the United States drive procurement.
Regular anchors the volume base while Organic gains share at the steepest rate.
End User:
Cost tier stratification separates commodity procurement in foodservice from premium specification buying in branded manufacturing, with certification requirements widening the gap between industrial and household segments.
- Food Manufacturers:Industrial-scale buyers specifying coconut fat for structural stability in dairy-free ice cream and confectionery enrobing compounds. German chocolate manufacturers reformulate with coconut fat to eliminate hydrogenated palm oil from ingredient declarations.
- Commercial Kitchens:Plant-based dairy alternatives in professional foodservice operations across the United States and Germany are expanding procurement volumes for sauce, soup, and dessert applications.
- Households:Retail consumers purchasing through supermarkets and online channels for home cooking and baking. Clean-label preferences in France and the Netherlands favor organic certification.
- Restaurants:Independent and chain foodservice operators sourcing through distributors for menu items targeting vegan and allergen-free diners.
Food Manufacturers anchor the volume base while Commercial Kitchens climb the fastest as plant-based menu penetration deepens.
Distribution Channel:
Supply concentration in Indonesian and Philippine export corridors shapes channel economics, with direct-origin contracts compressing traditional trading house margins and favoring scaled retail partnerships.
- Supermarkets:Mass-market retail placement in North American and European chains with ambient and refrigerated shelf sets. Clean-label positioning drives organic SKU expansion.
- Online Retail:E-commerce platforms enabling direct-to-consumer access for specialty and bulk formats. Subscription models for coconut cream concentrate in the United States.
- Health Stores:Natural products retailers emphasizing organic certification and non-GMO verification. Premium pricing accepted for traceable supply chains.
- Direct Sales:Processor-to-manufacturer contracts bypassing intermediaries. Danone and Unilever procurement teams establish annual volume commitments with Mindanao processors.
Supermarkets anchor the volume base while Direct Sales expands most quickly as food manufacturers consolidate procurement relationships.
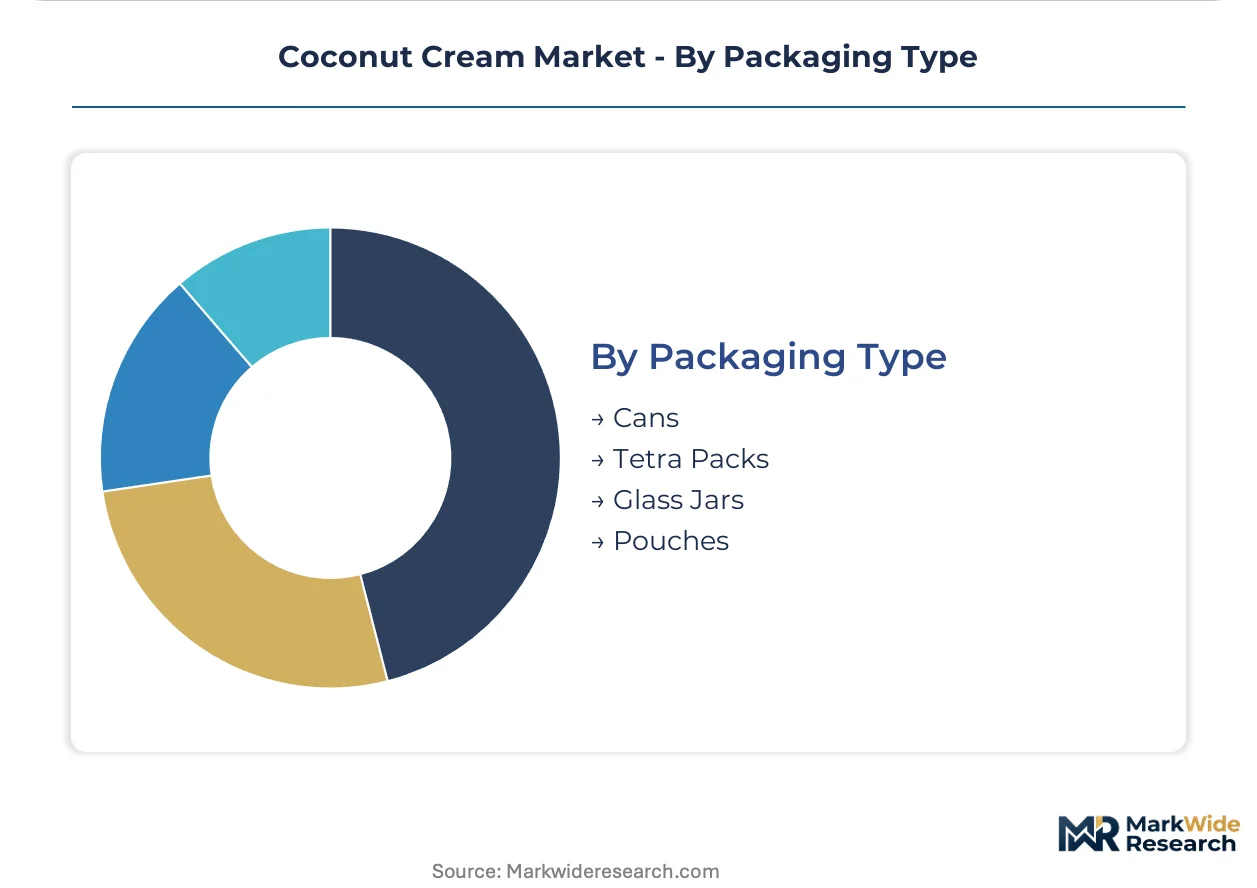
Packaging Type:
Logistics cost and shelf-life requirements create divergent optimal formats, with ambient-stable solutions opening previously unreachable landlocked markets and premium positioning sustaining glass jar demand in gift and specialty segments.
- Tetra Packs:Aseptic carton formats enabling 12-month ambient shelf life and reduced logistics costs versus glass. Extended-shelf-life packaging opens foodservice distribution in Central Asian markets previously unreachable with glass jar logistics.
- Cans:Metal packaging for industrial and foodservice bulk procurement. Philippine and Indonesian export processors favor this format for ocean freight efficiency.
- Glass Jars:Premium positioning for organic and specialty retail segments. Higher unit economics justified by gift market and clean-label perception in France and Germany.
- Pouches:Flexible format for single-serve and foodservice portion control. Emerging adoption in Asian convenience store channels.
Cans anchor the volume base while Tetra Packs gains share at the steepest rate as ambient distribution networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Manila anchors Philippine coconut cream exports through dedicated reefer terminals handling Mindanao-sourced copra. Rotterdam's Europoort distribution complex redistributes Southeast Asian shipments across German and Dutch food manufacturing clusters. Hamburg's cold-chain infrastructure processes Tetra Pak consignments for Central European retail channels.
United States
Plant-based frozen dessert manufacturers in California and Oregon specify coconut fat for structural stability at sub-zero temperatures. FDA enforcement of FSMA preventive controls filters procurement toward certified exporters with documented supply chain controls. Los Angeles and Portland host concentrated dairy-free ice cream production facilities sourcing direct from Philippine processors.
Germany
Chocolate manufacturers in Cologne and Hamburg reformulate enrobing compounds with coconut fat to eliminate hydrogenated palm oil from ingredient declarations. EFSA maximum residue limits for aflatoxins tighten import gatekeeping through Rotterdam and Hamburg entry points. The Hamburg metropolitan area anchors industrial procurement offices consolidating annual volume commitments with Southeast Asian suppliers.
Philippines
Mindanao plantation-processors leverage integrated farming operations to secure EU organic certification under updated 2018/848 protocols. Philippine export authorities coordinate with EFSA-recognized laboratories to pre-certify shipments and avoid Rotterdam rejection. Davao City concentration of wet-milling facilities achieves batch consistency satisfying German industrial buyer specifications.
Indonesia
North Sulawesi and Riau processors face laboratory bottlenecks extending shipment release timelines beyond contractual delivery windows. The country's national food safety regulator enforces aflatoxin testing protocols that redirect rejected EU-bound volume toward Middle Eastern markets. Surabaya port infrastructure handles bulk copra exports while Manado specialists target premium organic segments.
France
Specialty food manufacturers in Paris and Lyon specify high-pressure processed cream for premium dessert applications. ANSM labeling requirements for allergen declarations shape retail packaging specifications for coconut-derived ingredients. The Île-de-France region hosts clean-label confectionery R&D facilities reformulating with coconut fat to meet EU Green Deal sustainability targets.
Coconut Cream Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base fragments between plantation-integrated processors with organic credentials and commodity copra traders serving industrial bulk buyers. Three archetypes dominate: integrated plantation-processors controlling feedstock origin, branded consumer goods multinationals with specialized procurement teams, and regional export specialists leveraging scale advantages in copra processing. Capacity expansion and direct-origin contract consolidation represent the dominant competitive moves.
Within the integrated plantation-processor tier, Celebes Coconut Corporation and Axelum Resources Corp. exemplify the Philippine model of captive feedstock supply. Among branded consumer goods players, Danone occupies a position representing European retail channel dominance through plant-based R&D pipelines. These three names anchor the competitive structure without exhausting the field.
| Leading Market Players |
|---|
| Danone |
| Nestlé |
| Celebes Coconut Corporation |
| Califia Farms |
| Pacific Foods of Oregon |
| The Vita Coco Company, Inc. |
| Sambu Group |
| Axelum Resources Corp. |
| McCormick & Company |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles at Rotterdam entry points concentrate pricing power among Philippine and Indonesian processors with EU-recognized laboratory partnerships, while compressing margins for competitors facing aflatoxin-related shipment rejections. This lead-time asymmetry rewards integrated plantation-processors capable of pre-certification documentation.
Pricing Analysis
Volume-discount tiering separates annual contract purchasers from spot-market buyers, with food manufacturers locking in 12-month offtake agreements at standardized fat-content specifications. Price differentiation rests on organic certification under EU Regulation 2018/848 and USDA NOP, commanding shelf premiums in North American and European retail channels. Pricing pressure stems from oat and almond substitution in beverage applications where fat functionality requirements are less stringent. Commercial kitchens exhibit highest price sensitivity, while specialty food manufacturers in France and Germany demonstrate lowest sensitivity due to structural stability requirements in frozen dessert formulations.
Supply Chain Analysis
Indonesia and the Philippines anchor global coconut cream production through Mindanao and North Sulawesi plantation belts. Raw material supply draws from mature coconut kernel harvesting cycles and copra drying operations, with wet-milling capacity concentrated in Davao City and Surabaya processing clusters. Single-source vulnerability runs through Philippine export corridors during El Niño drought cycles that compress copra availability. Distribution runs through Rotterdam's Europoort redistribution complex for European food manufacturing clusters, with direct-origin contracts increasingly bypassing traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among food manufacturing multinationals with specialized procurement teams, fragmenting traditional export channel margins and forcing processor consolidation around direct-contract capabilities.
For Market Incumbents: Secure backward integration into plantation operations to maintain EU organic certification eligibility under updated 2018/848 protocols. Add wet-milling capacity in Mindanao to satisfy German industrial buyer specifications for batch consistency. Channel control through direct-origin contracts with Danone and Unilever procurement teams defends margin position against trading house disintermediation. For New Entrants and Emerging Players: Lead with high-pressure processing capabilities for premium dessert applications in French and United States specialty food channels. Target Central Asian landlocked markets through Tetra Pak ambient distribution partnerships where incumbent glass jar logistics face cost disadvantages. A sustainability audit-ready digital traceability platform unlocks foodservice procurement offices in Germany and the Netherlands. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because organic equivalency agreements between the EU and Southeast Asian producer nations remain unsigned, creating dual-certification cost barriers for non-integrated processors. Acquisition candidates center on Philippine plantation-processors with in-house farming operations and EFSA-recognized laboratory partnerships. The signal to watch is ratification timelines for EU-Indonesia organic equivalency protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Operations | EU Regulation 2018/848 favors integrated farming over third-party feedstock aggregators. |
| Wet-Milling Automation Investment | Continuous extraction systems achieve batch consistency for German chocolate manufacturer specifications. |
| Tetra Pak Format Expansion | Ambient shelf-life packaging opens Central Asian foodservice distribution previously unreachable with glass. |
| EFSA-Recognized Laboratory Partnership | Pre-certification capabilities avoid Rotterdam rejection and capture displaced competitor volume. |
| Direct-Origin Contract Consolidation | Annual volume commitments with Danone and Unilever procurement teams compress trading house margins. |
Study Parameters
Operator-level perspectives from plantation operations managers, Philippine export processors, European food manufacturing procurement leads, and Tetra Pak packaging specialists anchored the qualitative base. Secondary validation drew from FDA FSMA guidance documents, EFSA maximum residue limit specifications, EU organic regulation texts, and Indonesian national food safety regulator protocols. Bottom-up volume modeling triangulated against top-down value estimates across product type, end user, and packaging format segmentation dimensions.
Sensitivity analysis tested forecast outputs against copra price volatility scenarios and organic certification timeline variations across the projection horizon. The analytical framework modeled Regular, Organic, Light, and Flavored product tiers against Food Manufacturer, Commercial Kitchen, Household, and Restaurant end-user segments. CAGRs derived from historical trajectory analysis adjusted for substitution elasticity from oat and almond alternatives. Forecast inputs incorporated wet-milling capacity expansion announcements and EU-Southeast Asian organic equivalency negotiation statuses.
The analysis sits within stated boundaries; outcomes outside sustained plant-based frozen dessert demand growth or EFSA aflatoxin limit stability would require recalibration. Forecasts reflect documented assumptions regarding El Niño cycle frequency and EU organic regulation implementation timelines. Recalibration cycles align with material shifts in EU-Indonesia equivalency agreement ratification and Philippine wet-milling automation deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Camel Milk Products Market