
 Vegan Milk Alternatives Market | 2026-2036
Vegan Milk Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Milk Alternatives Market Insights
Foodservice buyer concentration is rebalancing as multinational coffee chains consolidate procurement around oat and almond bases while independent cafés fragment demand across niche variants. Danone S.A. leverages its European dairy-alternative infrastructure to dominate refrigerated distribution. Blue Diamond Growers anchors North American almond supply through grower cooperative scale. Oatly Group AB competes on barista-specific formulation strength in away-from-home channels.
Vegan milk alternatives are aqueous emulsions or extracts derived from oilseeds, cereals, or nuts, typically containing two to twelve percent solids by weight with added fortificants such as calcium carbonate and vitamins D2 or B12 to mimic nutritional profiles of bovine milk. The primary commercial purpose is to serve as a functional beverage and ingredient substitute in applications ranging from direct consumption to foam-stable espresso preparation. Oat milk leads product type momentum due to neutral flavor and lower environmental footprint, while almond milk occupies the mature volume position with established household penetration. Carton packaging dominates retail logistics for ambient distribution, though bottle formats gain traction in premium refrigerated sets where visual differentiation commands shelf attention.
FDA nutrition labeling requirements and USDA organic certification shape product positioning in the United States, while EU EFSA health claim regulations and REACH-compliant packaging mandates govern European market access. These frameworks elevate formulation transparency and restrict unsubstantiated nutritional comparisons to conventional dairy. Stakeholders must monitor evolving allergen disclosure thresholds and carbon accounting standards that will determine which base ingredients retain formulation priority.
Market Dynamics
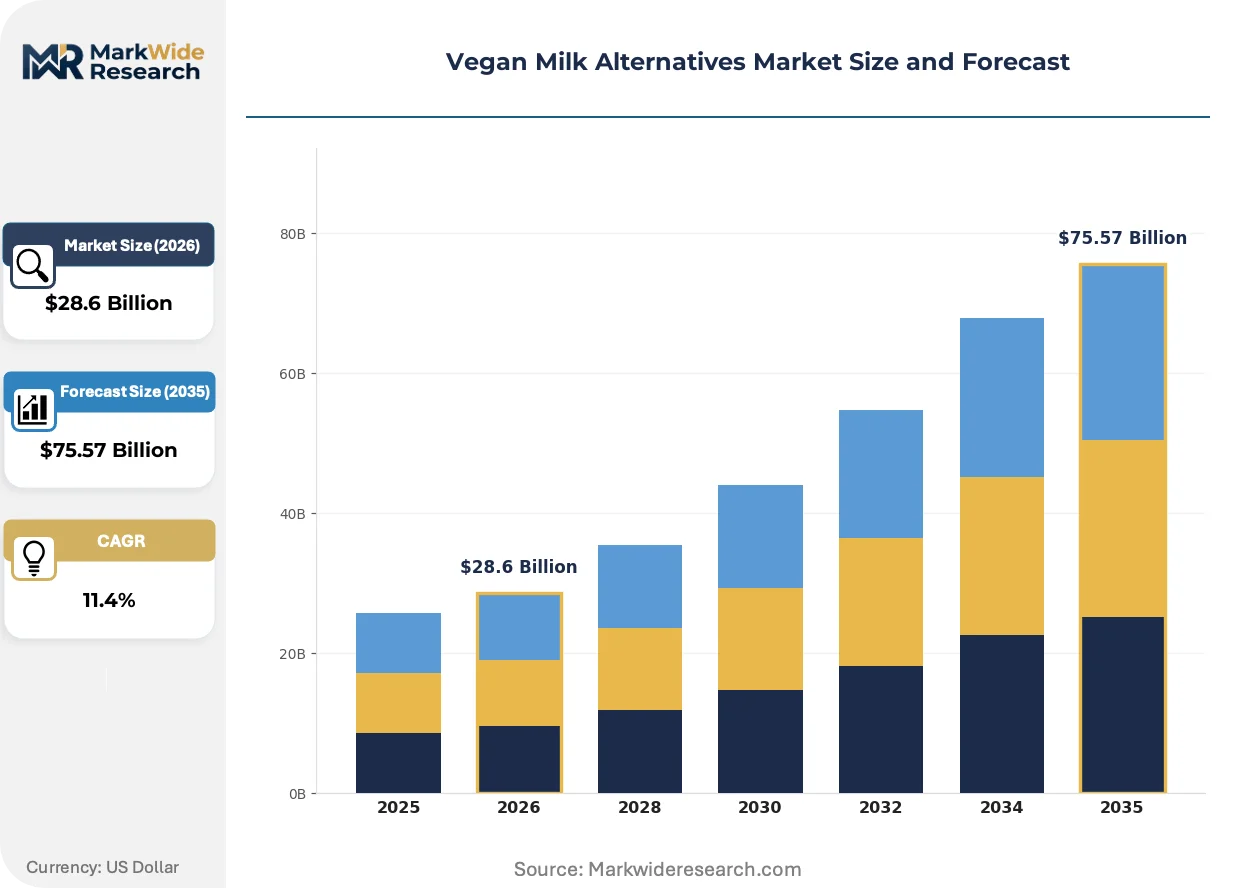
Foodservice procurement consolidation around oat and almond bases is compressing supplier margins while EU Green Deal carbon-labeling mandates force rapid reformulation toward lower-water crop inputs.
Growth Catalysts
- EU Green Deal carbon-labeling schemes:National frameworks in Germany and France mandate disclosure of water and carbon footprints, accelerating retailer shelf space allocation toward oat and pea-based formulations.
- Third-wave café channel expansion:Specialty coffee chains in Berlin, Stockholm, and Melbourne now specify barista-grade oat milk as default, creating pull-through demand for foam-stable emulsion technology.
- Enzymatic hydrolysis advances:Improved beta-glucan extraction processes reduce viscosity variability, enabling broader industrial bakery and confectionery applications beyond beverage use.
Market Restraints
- Almond water intensity:California drought cycles expose supply chains to input cost volatility, with single-origin dependency creating price transmission risk to European importers.
- EFSA health claim substantiation:Protein and calcium equivalence assertions require clinical validation timelines that delay product launches by 18-24 months in EU member states.
- Soy allergen substitution ceiling:Established household penetration faces hard limits where nut and legume allergies restrict addressable population segments in pediatric and school nutrition channels.
Strategic Opportunities
- Fermentation-derived dairy proteins:Precision fermentation converging with plant lipid bases enables hybrid products that bypass allergen labeling while accessing clean-label positioning.
- Direct-to-café subscription logistics:Cold-chain independent ultra-high temperature formats open bypass routes around conventional retail slotting fee structures.
- Indian foodservice penetration:Tier-one metropolitan tea stall and QSR channels remain underpenetrated by organized plant-milk supply, with FSSAI fortification guidelines creating compliant formulation pathways.
Industry Challenges
- Barista certification standardization:Absence of unified foam stability and sensory benchmarks across specialty coffee associations fragments R&D investment and quality assurance protocols.
- Cross-contamination audit complexity:Shared production lines with conventional dairy require segregation protocols that extend compliance timelines and inflate capex for dedicated facility construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Milk Alternatives Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Packaging Type: Carton, Bottle, Tetra Pack, Pouch Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Shops End User: Households, Cafés, Restaurants, Food Manufacturers |
| Companies Covered | Danone S.A., Blue Diamond Growers, Oatly Group AB, Califia Farms LLC, SunOpta, Inc., The Hain Celestial Group, Inc., Vitasoy International Holdings Ltd, Archer-Daniels-Midland Company, Ripple Foods, PBC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Milk Alternatives Market Trends and Innovations
Reformulation priorities are pivoting from nutritional mimicry toward functional performance in professional food preparation, with processing technology and packaging innovation converging to extend ambient shelf stability.
Enzymatic lipid structuring technology is expanding into commercial oat milk production, enabling precise control of fat droplet size distribution for espresso foam retention. Italian and Australian roasting chains are adopting these formulations at scale for consistency across multi-location operations. The technology is expanding into industrial ice cream and whipped topping applications, compressing demand for conventional emulsifier additives.
REACH-compliant packaging mandates from ECHA are eliminating certain multilayer carton laminates from EU distribution, forcing migration toward recyclable mono-material structures or aseptic bottle formats. Industrial consequence includes reformulation of oxygen barrier requirements to match new substrate permeability profiles. Refrigerated premium sets in Germany and France are responding with transparent PET and rPET bottle adoption that commands visual shelf differentiation.
Café procurement committees now specify origin-verified base crops with documented water stewardship credentials, displacing commodity sourcing for traceable supply agreements. Roasting cooperatives in Copenhagen and Portland are consolidating volumes through direct contracting with Scandinavian and North American oat millers. This pattern concentrates most visibly in urban clusters where municipal procurement guidelines prioritize environmental disclosure in foodservice vendor selection.
Vegan Milk Alternatives Market Segmentation
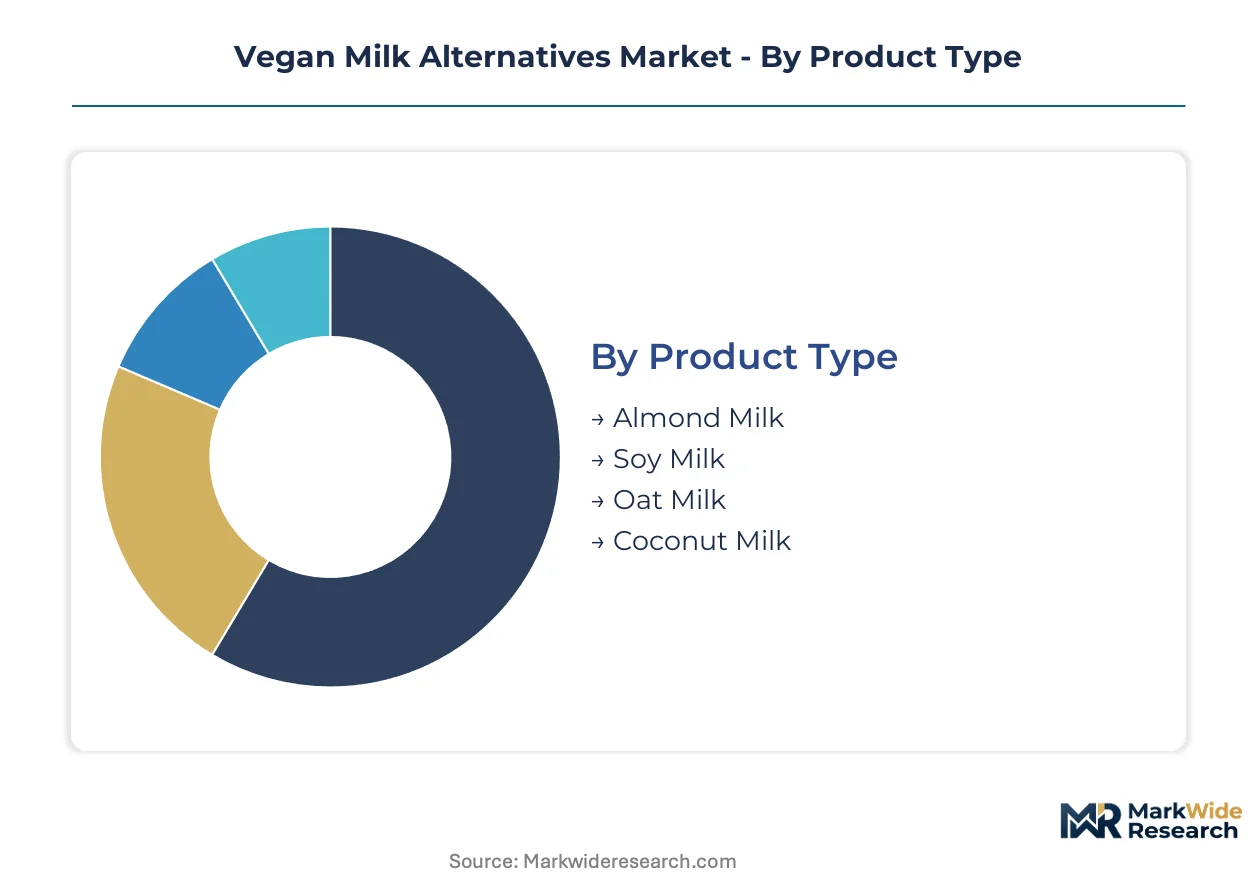
Segmentation in vegan milk alternatives determines procurement priorities, margin structures, and reformulation roadmaps. Product type concentration around oat and almond bases compresses supplier economics while packaging and channel choices govern shelf stability requirements and cold-chain investments.
Product Type:
Supply concentration clusters around two crop bases with divergent water intensity profiles, forcing buyers to balance cost stability against carbon disclosure mandates.
- Oat Milk:Aqueous extraction from milled Avena sativa kernels yields beta-glucan-rich emulsions with neutral flavor and foam-stable lipid structures. German and Swedish retail channels allocate expanding shelf space to oat-based formulations as EU Green Deal carbon-labeling schemes elevate lower-water crop credentials.
- Almond Milk:Blanched Prunus dulcis kernels processed through wet milling and filtration produce the mature volume base with established household penetration. California drought cycles expose European importers to input cost volatility, compressing margins for commodity-sourced supply.
- Soy Milk:Isoflavone-containing aqueous extract from Glycine max remains the protein-dense legacy base with fortification-established nutritional equivalence claims.
- Coconut Milk:High-fat emulsion from Cocos nucifera flesh extraction serves tropical-origin specialty applications and confectionery ingredient channels.
Today's leader: Almond Milk. Tomorrow's challenger: Oat Milk.
Packaging Type:
Cost tier stratification separates ambient distribution infrastructure from premium refrigerated positioning where visual differentiation commands slotting fee premiums.
- Carton:Multilayer laminates dominate ambient retail logistics with oxygen barrier properties enabling extended shelf stability without refrigeration. REACH-compliant mandates from ECHA are eliminating certain laminate structures, forcing substrate reformulation.
- Bottle:Transparent PET and rPET formats gain traction in German and French premium refrigerated sets where shelf visibility drives consumer selection.
- Tetra Pack:Aseptic brick formats serve bulk foodservice procurement with efficient pallet density and ambient storage compatibility.
- Pouch:Flexible film structures address single-serve convenience channels and direct-to-café subscription logistics with reduced shipping cube.
Carton holds volume dominance. Bottle captures margin expansion.
Distribution Channel:
Application-driven channel selection separates mass-market penetration from specialized nutrition positioning and ingredient supply contracts.
- Supermarkets:Conventional grocery channels in Germany have expanded refrigerated and ambient shelf space allocation significantly, concentrating volume through centralized procurement.
- Health Stores:Certified organic and allergen-free positioning commands premium pricing through specialized retail with educated consumer demographics.
- Online Retail:Direct-to-consumer subscription models bypass conventional slotting fee structures with cold-chain independent ultra-high temperature formats.
- Specialty Shops:Independent retailers serve niche variant demand with fragmented procurement across hemp, pea, and blended formulations.
Supermarkets anchor volume. Online Retail climbs fastest.
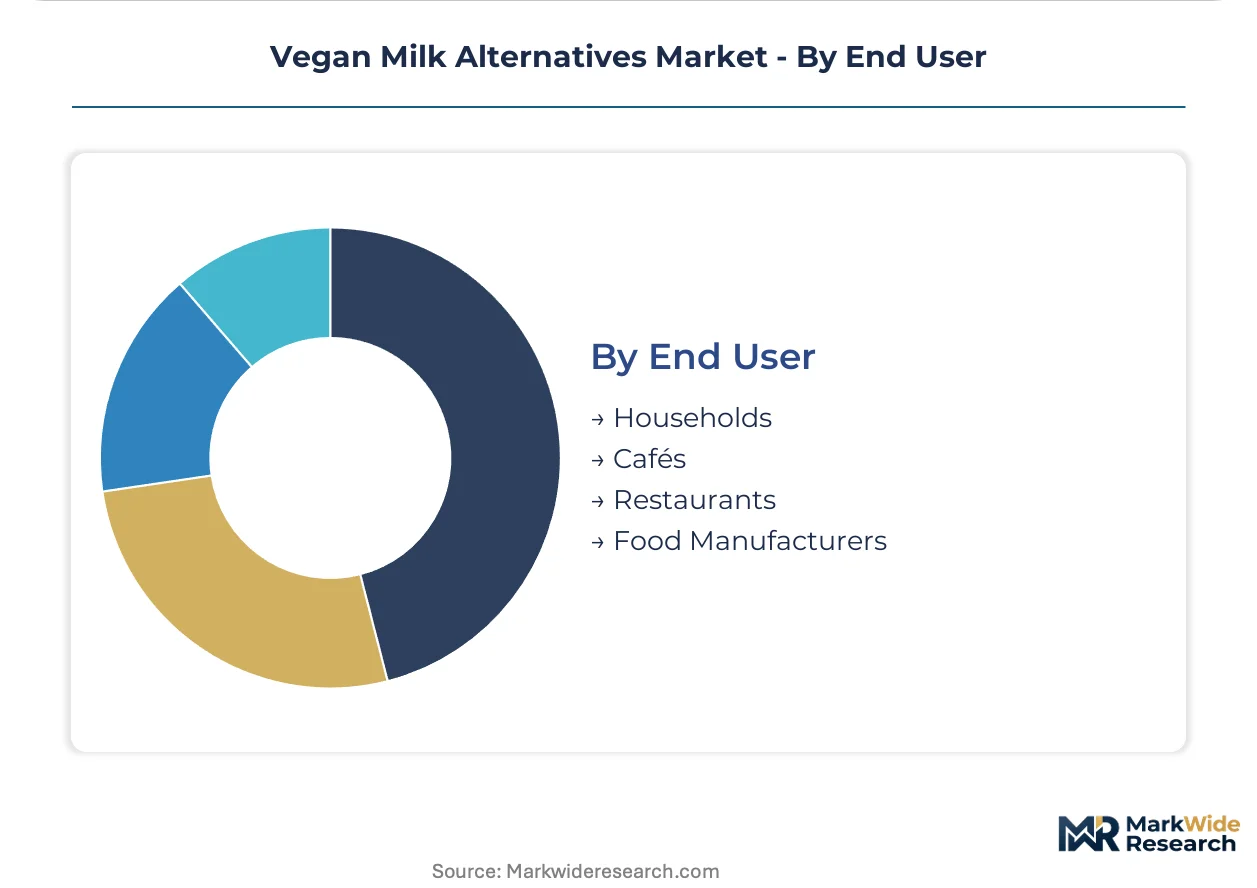
End User:
Customer type determines formulation specifications from direct-consumption fortification to industrial functional performance requirements.
- Households:Retail consumers drive nutritional mimicry demand with calcium carbonate and vitamin D2/B12 fortification for bovine milk equivalence.
- Cafés:Third-wave coffee chains in Berlin, Stockholm, and Melbourne specify barista-grade oat milk as default, pulling foam-stable emulsion technology development.
- Restaurants:Foodservice operators require consistent supply agreements with documented water stewardship credentials for municipal procurement compliance.
- Food Manufacturers:Industrial bakery and confectionery applications demand enzymatic hydrolysis advances for viscosity-controlled beta-glucan integration.
Cafés drive premium innovation. Food Manufacturers scale ingredient demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retail shelf expansion for plant-based beverages contrasts with India's nascent foodservice penetration, revealing divergent maturity stages across national markets while both face tightening carbon disclosure mandates.
Germany
Conventional grocery channels have expanded refrigerated and ambient shelf space allocation significantly, concentrating volume through centralized procurement. EU Green Deal carbon-labeling schemes mandate water and carbon footprint disclosure, accelerating retailer preference for oat and pea-based formulations. Berlin's third-wave café cluster now specifies barista-grade oat milk as default, pulling foam-stable emulsion technology development from Scandinavian suppliers.
United States
Specialty coffee chains consolidate procurement around oat and almond bases while independent cafés fragment demand across niche variants. FDA nutrition labeling requirements and USDA organic certification shape product positioning, elevating formulation transparency. California's almond-growing regions expose supply chains to drought-cycle input cost volatility, compressing margins for commodity-sourced supply to European importers.
Sweden
Third-wave café channel expansion in Stockholm creates pull-through demand for foam-stable emulsion technology from domestic oat millers. EFSA health claim regulations govern protein and calcium equivalence assertions, requiring clinical validation timelines that delay product launches. Roasting cooperatives consolidate volumes through direct contracting with Scandinavian oat millers, prioritizing origin-verified base crops with documented water stewardship credentials.
India
Tier-one metropolitan tea stall and QSR channels remain underpenetrated by organized plant-milk supply, creating whitespace for compliant formulation pathways. FSSAI fortification guidelines establish nutritional standards for calcium carbonate and vitamin D2/B12 enrichment. Mumbai and Delhi foodservice operators require consistent supply agreements as municipal procurement guidelines increasingly prioritize environmental disclosure in vendor selection.
Australia
Melbourne's specialty coffee chains specify barista-grade oat milk as default, mirroring Berlin and Stockholm procurement patterns. The country's national food standards regulator enforces allergen disclosure thresholds that restrict addressable population segments in pediatric channels. Sydney roasting cooperatives are adopting enzymatic lipid structuring technology at scale for consistency across multi-location operations.
Vegan Milk Alternatives Market Competitive Landscape
European producers anchor one tier; North American specialists hold established positions in legacy crop bases. The vendor base stratifies around scale-driven dairy-alternative infrastructure, grower cooperative supply integration, and barista-specific formulation capabilities. Three archetypes dominate: multinational beverage conglomerates leveraging refrigerated distribution networks, agricultural cooperatives controlling upstream nut and grain supply, and oat-focused challengers competing on away-from-home channel penetration. Competitive moves concentrate on direct-to-café subscription logistics and REACH-compliant packaging substrate migration.
Within the multinational tier, Danone S.A. and Blue Diamond Growers exemplify divergent strategic foundations—one leveraging European dairy-alternative infrastructure, the other anchoring North American almond supply through grower cooperative scale. Oatly Group AB occupies a position representing barista-specific formulation strength in away-from-home channels. Califia Farms LLC and Ripple Foods, PBC sit within the challenger archetype, with the former's geographic naming suggesting California-based operations and the latter's public benefit corporation structure indicating mission-aligned capitalization. These five entities collectively illustrate the competitive spectrum from legacy agricultural supply integration to channel-specific functional performance positioning.
| Leading Market Players |
|---|
| Danone S.A. |
| Blue Diamond Growers |
| Oatly Group AB |
| Califia Farms LLC |
| SunOpta, Inc. |
| The Hain Celestial Group, Inc. |
| Vitasoy International Holdings Ltd |
| Archer-Daniels-Midland Company |
| Ripple Foods, PBC |
| Others |
Pricing and Supply Chain Analysis
Enzymatic hydrolysis specialists in Sweden and Denmark command wage premiums that compress margin spreads between economy-tier commodity sourcing and premium barista-grade formulations. This labor-cost differential widens pricing tiers as EU Green Deal carbon-labeling mandates force investment in technical talent for beta-glucan extraction optimization.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for oat-based formulations as domestic millers expand enzymatic processing infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates origin-verified organic supply from conventional retail and foodservice bulk procurement. Price differentiation hinges on foam-stability certification and REACH-compliant packaging substrate compliance. Cost compression in economy-tier almond imports is intensifying because California drought exposure transmits volatility to European buyers, while cafés demonstrate lowest price sensitivity due to specification-locked procurement committees.
Supply Chain Analysis
Workforce availability in Swedish milling corridors and California Central Valley processing hubs constrains capacity expansion timelines for beta-glucan extraction and almond blanching operations. Supply concentrates in Germany, Sweden, and the United States for oat and almond base production, with secondary sourcing from Spain and Italy for Mediterranean specialty variants. Raw material dependencies center on Avena sativa grain contracts, Prunus dulcis kernel supply, and enzymatic processing agents. Single-source vulnerability runs through California almond irrigation rights exposed to drought-cycle curtailment. Distribution runs through refrigerated logistics networks for premium retail sets and ambient carton palletization for conventional grocery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
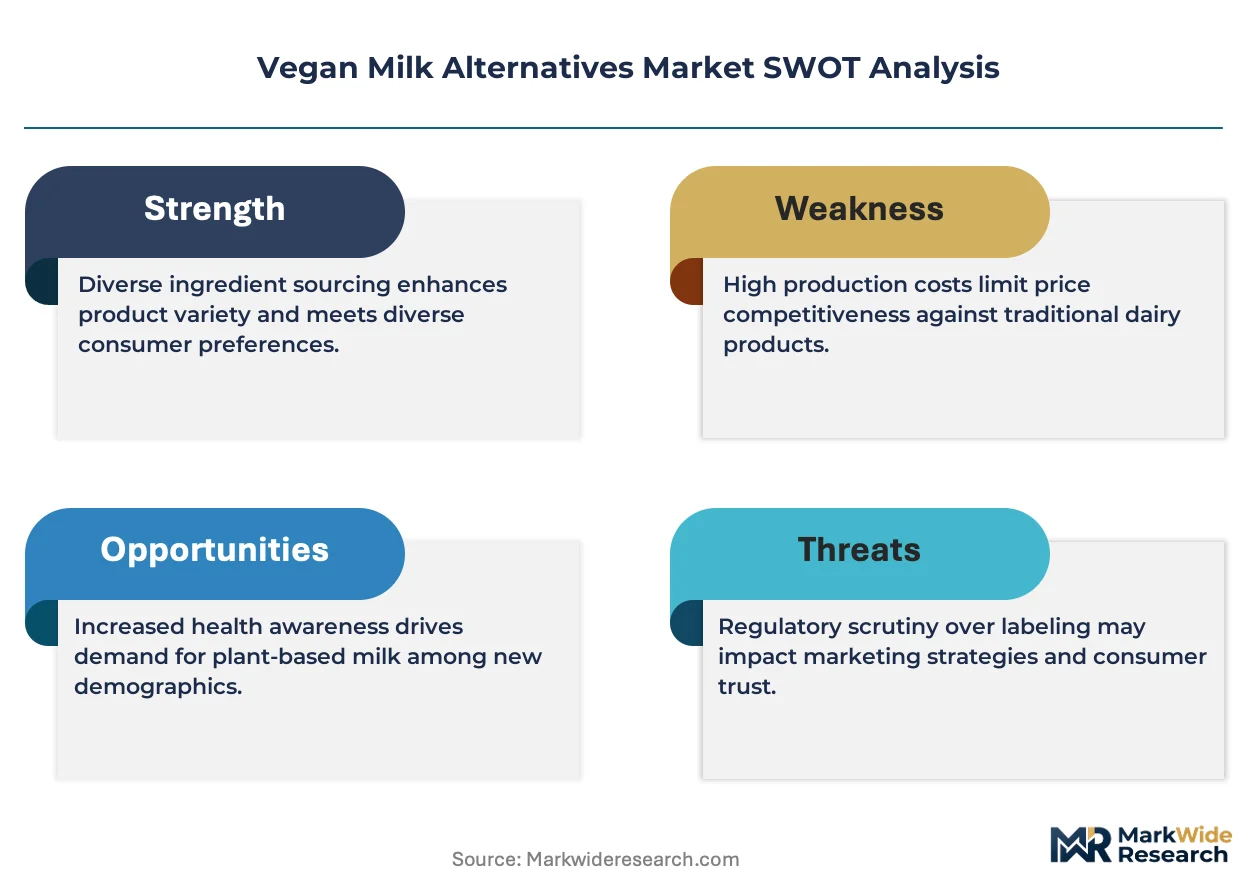
This market reads as a late-cycle quality story justified by café procurement committees shifting default specifications toward barista-grade foam stability. Premium-tier positioning now requires documented water stewardship credentials rather than nutritional equivalence claims alone.
For Market Incumbents: To counter precision fermentation hybrid entrants, anchor supply security through backward integration into Scandinavian oat milling and California almond cooperative equity. Prioritize EFSA health claim substantiation investment to defend shelf space against delayed-launch challengers. Lock barista certification partnerships with third-wave roasting cooperatives in Berlin and Melbourne to secure specification-default status. For New Entrants and Emerging Players: Direct-to-café subscription logistics offer the lowest barrier entry path around supermarket slotting fee structures. Target Indian tier-one metropolitan tea stall channels where FSSAI fortification compliance creates first-mover positioning. Penetrate Australian specialty coffee chains through enzymatic lipid structuring technology licensing rather than brand-building capex. For Investors and Strategic Acquirers: Beverage conglomerates with refrigerated distribution infrastructure are the most active acquirer in this space, seeking barista-formulation capabilities to fill portfolio gaps. Long-term viability over the projection horizon rests on defensible foam-technology IP and origin-verified supply agreements rather than commodity scale. Watch for EFSA protein-equivalence claim approvals as the inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Barista-Grade Formulation Development | Secures default specification status with third-wave café procurement committees in Berlin and Melbourne. |
| Origin-Verified Supply Contracting | Meets EU Green Deal carbon-labeling mandates and municipal procurement disclosure requirements. |
| REACH-Compliant Packaging Migration | Enables continued EU distribution as ECHA eliminates multilayer carton laminate structures. |
| Direct-to-Café Subscription Logistics | Bypasses conventional retail slotting fees with cold-chain independent ultra-high temperature formats. |
| Precision Fermentation Hybrid R&D | Opens allergen-free positioning while accessing clean-label credentials beyond plant-base limitations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from oat miller operations directors, café procurement committee leads, EFSA regulatory affairs specialists, and refrigerated distribution logistics managers. Secondary validation drew from EU Green Deal implementation documents, ECHA REACH compliance filings, FSSAI fortification guidelines, and Nielsen retail audit data for German plant-based beverage shelf space allocation. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-weighting applied differential growth assumptions across product type, packaging format, and channel dimensions. The analytical framework modeled oat, almond, soy, and coconut bases separately with distinct input cost trajectories for water intensity and enzymatic processing requirements. Carton, bottle, and pouch packaging carried separate oxygen-barrier degradation curves. CAGR derivation incorporated EU carbon-labeling adoption timelines and third-wave café expansion patterns without year-specific milestone assumptions.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation hybridization would alter the outlook for legacy plant-base incumbents. Forecasts reflect assumptions regarding EFSA claim approval timelines and California irrigation policy stability. Material deviation in EU Green Deal enforcement intensity or almond supply disruption severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
Pet Milk Market