
 Ice Cream Equipment Market | 2026-2036
Ice Cream Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Equipment Market Foresight
Premium stainless-steel specification tiers is collapsing the gap between artisan and industrial production lines, enabling smaller operators to access continuous freezing precision. GEA Group Aktiengesellschaft leverages its dairy processing heritage to dominate large-scale turnkey installations across European markets. Carpigiani Group anchors the artisan segment with specialized batch freezer architectures that sustain premium positioning in gelato-centric geographies. Tetra Pak Processing Equipment GmbH competes through aseptic filling integration that extends downstream control for dairy multinationals.
Ice cream equipment encompasses industrial machinery designed to pasteurize, homogenize, freeze, and package frozen dessert products, typically operating at temperatures between minus 35°C and minus 40°C with throughput rates from 100 to 10,000 liters per hour. These systems serve commercial producers seeking controlled overrun, texture consistency, and extended shelf stability in packaged or dispensed formats. Soft serve machines command the largest installed base among product types due to universal deployment in quick-service restaurants and convenience retail, though liquid nitrogen freezing technology captures the fastest growth trajectory by enabling on-demand artisan production with minimal floor space requirements. Blast freezers retain mature demand patterns in industrial settings where throughput scale outweighs flexibility premiums.
The FDA's Food Safety Modernization Act mandates hazard analysis and preventive controls for frozen dessert manufacturing, compelling equipment upgrades with validated clean-in-place protocols and automated allergen segregation. EFSA hygiene standards and EU MDR conformity requirements for food-contact materials restrict market access for non-certified Asian imports, reinforcing European vendor positions. Stakeholders must monitor evolving energy efficiency benchmarks under the EU Green Deal and assess whether captive retrofit services or third-party upgrade partnerships better protect installed-base profitability as regulatory compliance costs escalate.
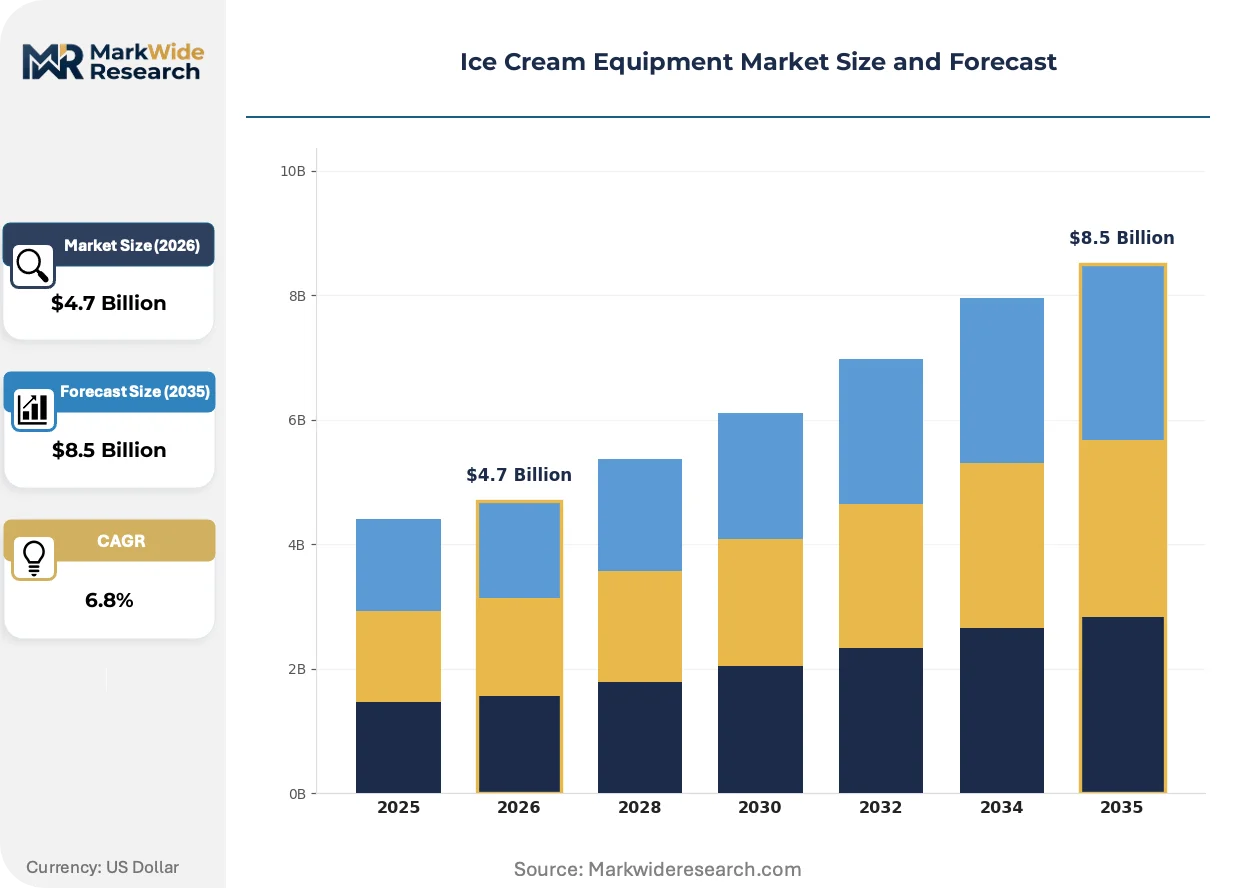
Market Dynamics
Automated clean-in-place systems are displacing manual sanitation protocols across frozen dessert manufacturing, as the FDA's Food Safety Modernization Act and evolving EFSA hygiene standards force capital redeployment toward validated allergen segregation architectures.
Growth Catalysts
- Liquid nitrogen freezing adoption:Artisan producers deploy compact on-demand freezing systems that eliminate floor space constraints and enable premium texture control without industrial-scale infrastructure.
- EU MDR conformity requirements:Certification barriers for food-contact materials block non-compliant Asian imports, reinforcing domestic European equipment vendor positions and protecting installed-base profitability.
- Quick-service restaurant expansion:Soft serve machine deployment accelerates in convenience retail and foodservice chains seeking consistent overrun control and extended operational uptime.
Market Restraints
- Stainless steel input volatility:Premium specification tiers depend on austenitic steel grades vulnerable to nickel price swings and energy-intensive European smelter capacity constraints.
- Italian supply concentration:Carpigiani and Technogel anchor a dense manufacturing cluster in Emilia-Romagna, creating geographic risk exposure for export-dependent procurement strategies.
- Blast freezer technical ceiling:Industrial throughput systems lack flexibility for SKU proliferation, limiting retrofit viability for producers pivoting toward artisan product lines.
Strategic Opportunities
- Western Europe artisan parlor densification:Premium gelato culture sustains batch freezer demand in Germany, France, and Spain where consumers prioritize texture authenticity over mass production economics.
- Aseptic filling integration:Dairy multinationals seek downstream control through combined freezing and sterile packaging architectures that extend shelf stability without cold chain dependency.
- EU Green Deal energy benchmarks:Efficiency retrofit incentives create captive service revenue streams for vendors offering heat recovery and variable-speed compressor upgrades.
Industry Challenges
- Clean-in-place validation expertise:Equipment operators face skill gaps in automated sanitation protocol programming and FDA-compliant hazard documentation.
- Legacy system integration friction:Continuous freezing lines from prior-generation architectures resist seamless connectivity with modern IoT-enabled monitoring and predictive maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Equipment Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Freezers, Soft Serve Machines, Blast Freezers, Mix Tanks Technology: Liquid Nitrogen Freezing, Direct Expansion, Air Injection, Indirect Cooling End User: Restaurants, Ice Cream Parlors, Retail Chains, Food Trucks Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Tetra Pak Processing Equipment GmbH, GEA Group Aktiengesellschaft, Carpigiani Group, ROKK Processing Ltd, Alfa Laval AB, Gram Equipment A/S, Technogel S.p.a, Ice Group Sp z o.o., SPX FLOW Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Equipment Market Shifts & Advancements
Equipment architectures are fragmenting between precision artisan systems and throughput-optimized industrial lines, with regulatory compliance costs and energy efficiency mandates forcing technology choices that reshape vendor competitive boundaries.
Continuous freezing technology is bifurcating the equipment landscape. Scraped-surface heat exchangers deliver overrun precision for mass-market producers, while compact batch freezers capture premium positioning among gelato specialists. Artisan operators adopt hybrid configurations that switch between production modes. This technological divergence is compressing mid-scale vendor margins as buyers polarize toward either extreme.
EFSA hygiene standards are tightening food-contact material specifications across European markets. Stainless-steel surface finish requirements now mandate Ra 0.8 micrometer thresholds for direct product zones, invalidating legacy equipment certifications. Italian and German producers accelerate retrofit programs to maintain market access, while non-compliant imports face customs detention at Rotterdam and Hamburg entry points.
Service unbundling is altering buyer-vendor relationships in North American markets. Quick-service chains separate equipment procurement from maintenance contracts, sourcing aftermarket parts through third-party distributors rather than captive vendor networks. This disintermediation pressures original equipment manufacturers to defend margin through proprietary control system architectures that resist independent servicing.
Ice Cream Equipment Market Segmentation
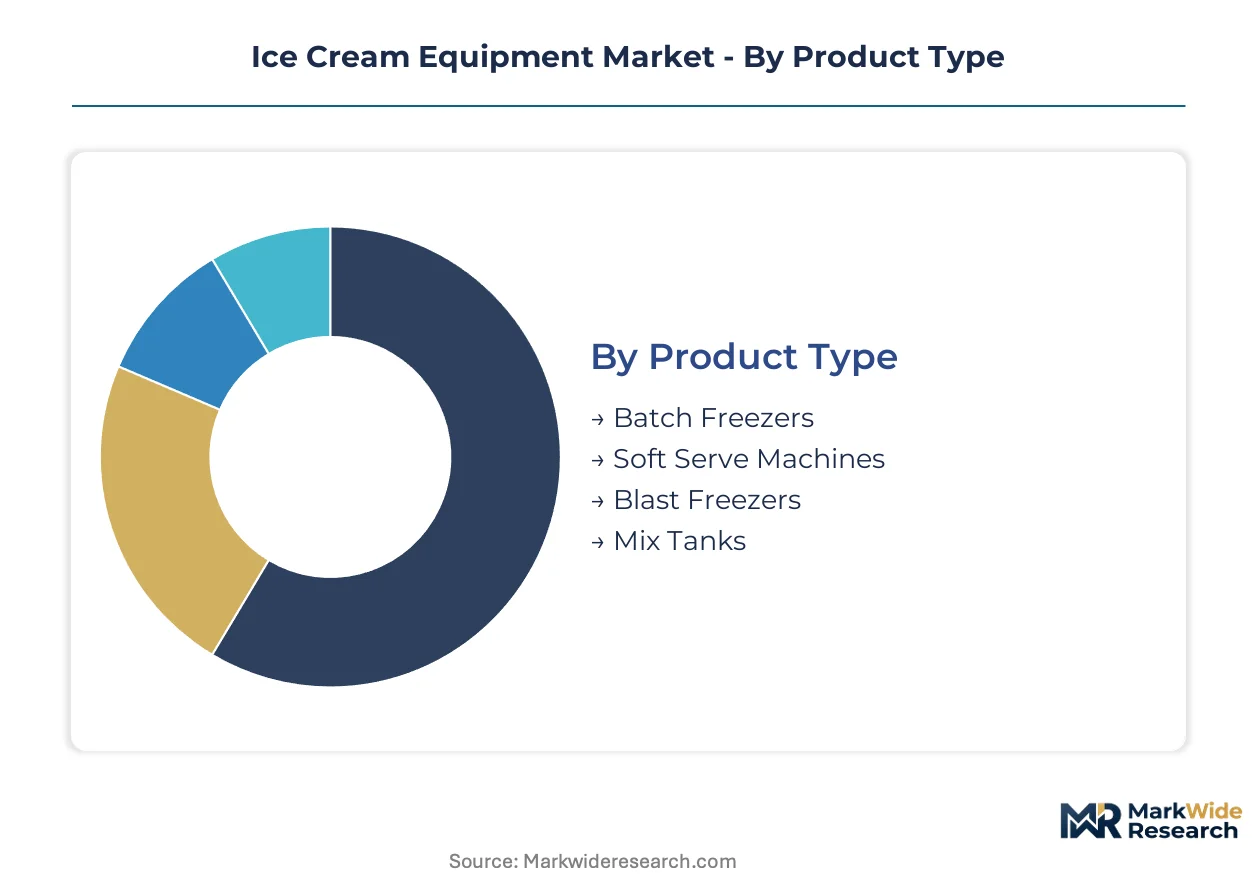
Equipment segmentation in frozen dessert manufacturing tracks divergent capital deployment patterns between artisan precision systems and throughput-optimized industrial lines. Margin concentration varies sharply across product architectures, freezing technologies, and channel configurations, forcing vendors to prioritize development roadmaps around specific buyer economics.
Product Type:
Margin pools concentrate in continuous freezing architectures where throughput scale amortizes premium stainless-steel specifications across high-volume production cycles.
- Batch Freezers:These discontinuous freezing systems employ scraped-surface heat exchangers with manual extraction cycles, delivering precise overrun control for gelato and premium ice cream formulations. Demand clusters in Italy's Emilia-Romagna manufacturing belt and Western European artisan parlors where texture authenticity commands price premiums over mass production economics.
- Soft Serve Machines:Gravity-fed or pump-driven dispensing systems maintain consistent product viscosity through refrigerated hoppers and freezing cylinders operating at minus 6°C to minus 8°C. Quick-service restaurants in the United States and convenience retail chains across Germany deploy these units universally, prioritizing operational uptime and standardized portion control over equipment flexibility.
- Blast Freezers:Forced-air convection systems achieve rapid temperature reduction from minus 35°C to minus 40°C for post-packaging hardening.
- Mix Tanks:Jacketed vessels with agitation systems prepare liquid ice cream base prior to freezing operations.
Soft serve machines hold installed capacity across quick-service deployment. Batch freezers are rotating up the share rankings among premium positioning strategies.
Technology:
Capital allocation patterns split between established mechanical refrigeration architectures and emerging cryogenic systems that eliminate compressor infrastructure.
- Liquid Nitrogen Freezing:Direct cryogenic injection systems achieve ultra-rapid nucleation at minus 196°C, producing smaller ice crystals and smoother texture profiles without floor space-intensive equipment. Artisan operators in urban United States markets and compact European retail locations adopt these systems to enable on-demand production with minimal real estate footprints.
- Direct Expansion:Ammonia or CO2 refrigerant circulates directly through evaporator plates, delivering energy efficiency for industrial-scale continuous freezing lines.
- Air Injection:Whipping systems introduce controlled air volumes to achieve target overrun percentages in soft serve and frozen dessert applications.
- Indirect Cooling:Glycol or brine secondary circuits provide temperature stability for sensitive gelato formulations requiring gradual thermal processing.
Direct expansion retains installed capacity across legacy industrial infrastructure. Liquid nitrogen freezing is climbing the fastest among technology adoption curves.
End User:
Procurement authority concentrates with operators seeking either brand differentiation through texture precision or operational standardization across distributed locations.
- Restaurants:Full-service dining establishments deploy compact batch freezers or soft serve attachments for dessert menu completion without dedicated frozen dessert infrastructure.
- Ice Cream Parlors:Specialized retail operators invest in premium specification batch freezers with pasteurization integration, anchoring equipment demand in Italian, French, and Spanish markets where gelato culture sustains independent artisan positioning against chain competition.
- Retail Chains:Corporate procurement functions standardize soft serve machine specifications across convenience store and supermarket networks, prioritizing remote monitoring compatibility and rapid service response.
- Food Trucks:Mobile operators favor compact liquid nitrogen systems or generator-compatible soft serve units with minimal power draw and vibration resistance.
Retail chains hold installed capacity through centralized procurement scale. Ice cream parlors are rotating up the share rankings amid artisan densification trends.
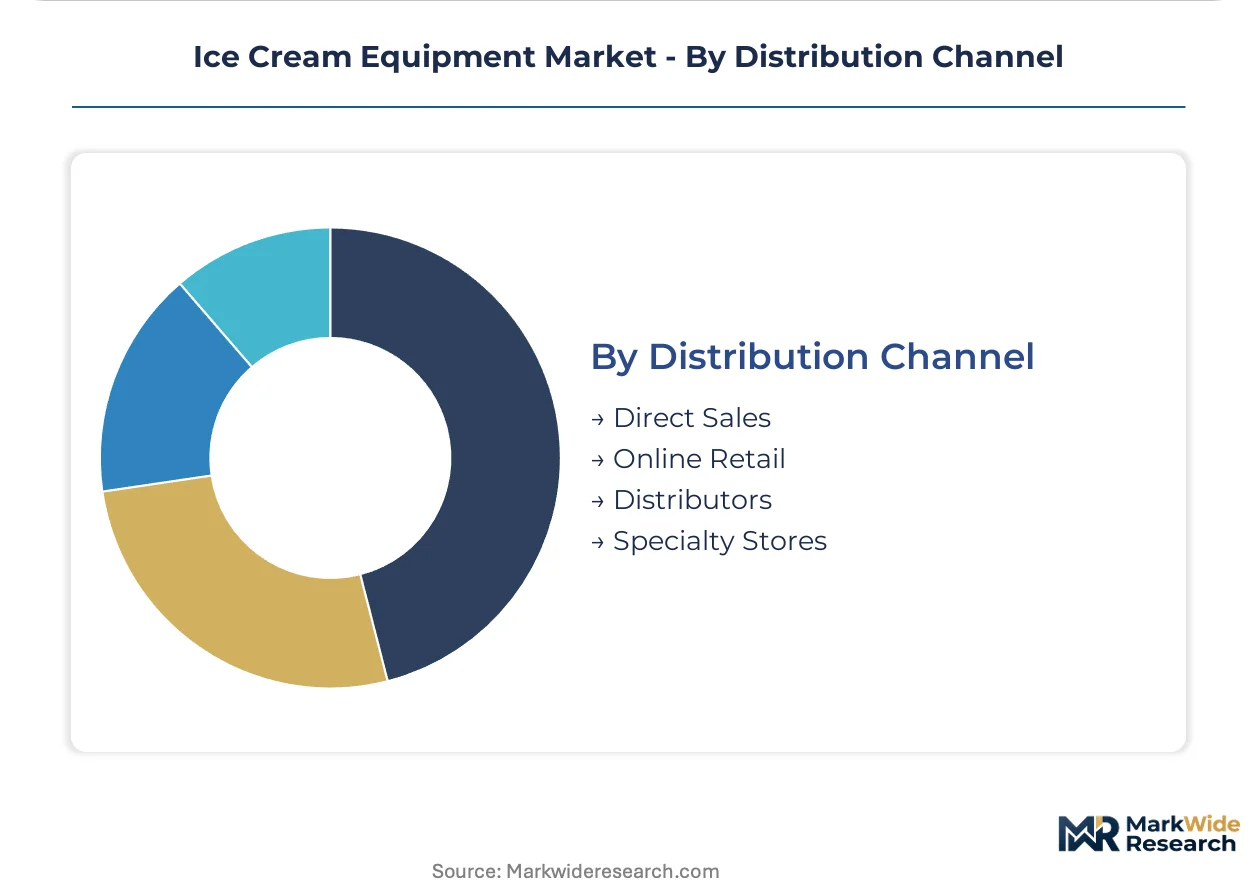
Distribution Channel:
Channel economics fragment between relationship-intensive direct sales for complex installations and transactional efficiency for standardized equipment replacement.
- Direct Sales:Manufacturer field engineers configure turnkey pasteurization-freezing-packaging lines for dairy multinationals, capturing premium project margins through installation supervision and commissioning validation.
- Online Retail:E-commerce platforms serve small-batch artisan operators sourcing compact batch freezers and replacement components with minimal technical consultation requirements.
- Distributors:Regional inventory stocking networks provide aftermarket parts availability and emergency service dispatch for quick-service restaurant maintenance contracts.
- Specialty Stores:Culinary equipment retailers in metropolitan United States and Western European markets offer hands-on demonstration and local technical support for emerging artisan entrants.
Direct sales hold installed capacity across project-based industrial procurement. Online retail is rotating up the share rankings among independent operator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing clusters over dispersed assembly operations. Italy's Emilia-Romagna equipment belt ships batch freezers to Western European parlors and North American artisan chains. German engineering houses anchor turnkey project exports across dairy processing corridors.
United States
Quick-service restaurant chains deploy soft serve machines at scale across convenience retail networks. FDA's Food Safety Modernization Act mandates hazard analysis protocols that accelerate clean-in-place system upgrades. Equipment demand concentrates in Chicago's foodservice manufacturing corridor and California's artisan dairy processing clusters.
Germany
Dairy multinationals source continuous freezing lines for high-throughput production of private-label frozen desserts. EU Green Deal energy efficiency benchmarks drive heat recovery retrofits and variable-speed compressor installations. Industrial equipment procurement centers on North Rhine-Westphalia's machinery manufacturing belt and Bavaria's dairy technology corridor.
Italy
Gelato culture sustains premium batch freezer demand across independent artisan parlors in Milan, Rome, and Florence. EFSA hygiene standards enforce Ra 0.8 micrometer surface finish thresholds that invalidate legacy certifications. Carpigiani and Technogel anchor dense manufacturing capacity in Bologna's Emilia-Romagna cluster serving export markets.
France
Premium dessert chains invest in pasteurization-integrated batch systems for authentic texture positioning against industrial competitors. EU MDR conformity requirements for food-contact materials block non-certified import competition. Equipment specification authority concentrates with Paris-based culinary equipment distributors and Lyon-region dairy technology specialists.
China
Domestic dairy processors expand automated freezing capacity for branded ice cream and frozen yogurt formats. The country's national food safety regulator tightens cold chain equipment certification standards that favor domestic vendor relationships. Manufacturing activity clusters in Shanghai's food machinery corridor and Shandong's dairy processing equipment zones.
Ice Cream Equipment Market Competitive Landscape
Concentration sits with diversified engineering conglomerates and specialized artisan equipment fabricators. The vendor base splits between turnkey project houses serving dairy multinationals and precision batch freezer specialists capturing premium gelato positioning. Two strategic archetypes dominate: scale-driven continuous freezing integrators and craftsmanship-oriented discontinuous system builders. Competitive moves center on aseptic filling integration partnerships and energy efficiency retrofit service unbundling.
Within the diversified engineering tier, GEA Group Aktiengesellschaft and Tetra Pak Processing Equipment GmbH exemplify turnkey project dominance through dairy processing heritage and downstream packaging control. Carpigiani Group anchors the specialized artisan segment with batch freezer architectures that sustain premium positioning in gelato-centric geographies. Among precision equipment specialists, Technogel S.p.a occupies a position within Italy's dense Emilia-Romagna manufacturing cluster.
| Leading Market Players |
|---|
| Tetra Pak Processing Equipment GmbH |
| GEA Group Aktiengesellschaft |
| Carpigiani Group |
| ROKK Processing Ltd |
| Alfa Laval AB |
| Gram Equipment A/S |
| Technogel S.p.a |
| Ice Group Sp z o.o. |
| SPX FLOW Inc. |
| Others |
Supply & Pricing Matrix
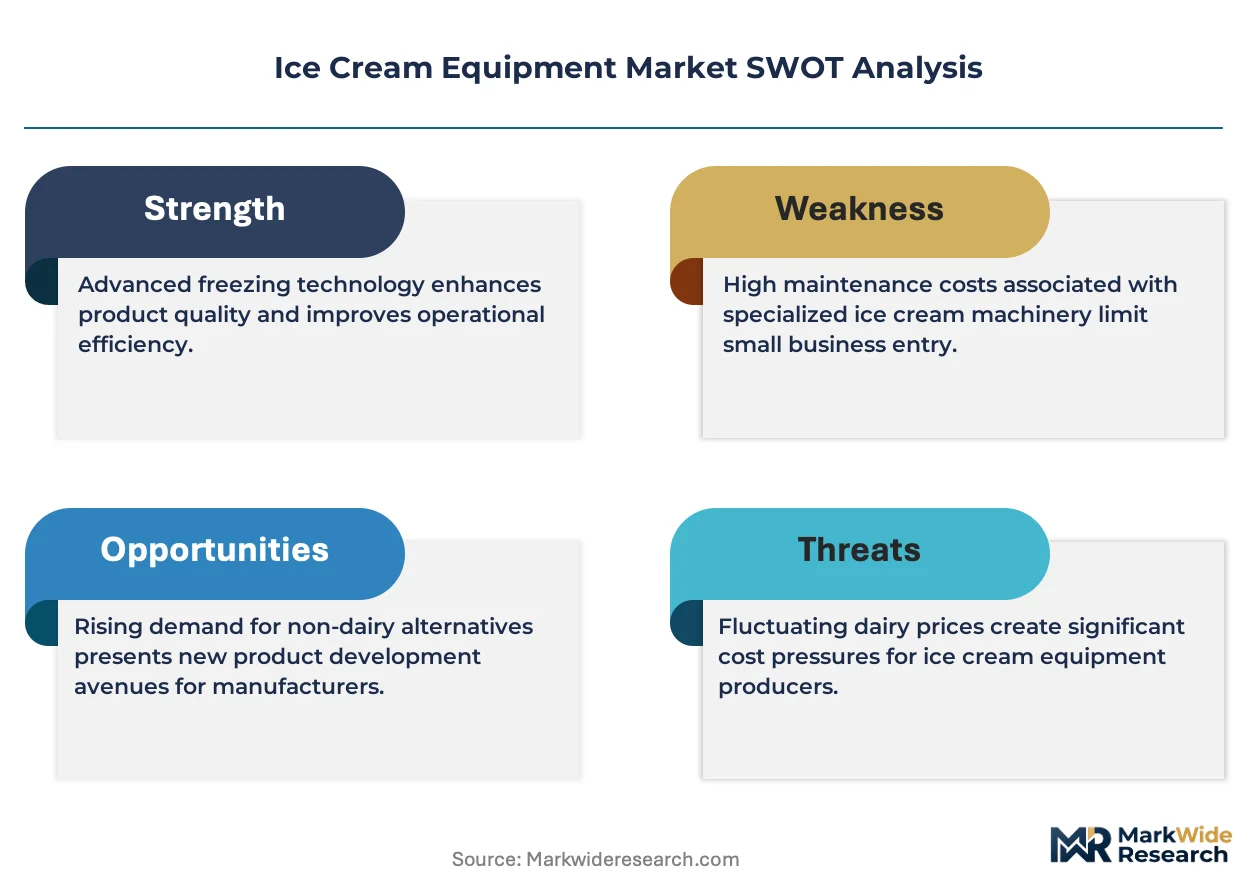
EFSA Ra 0.8 micrometer surface finish mandates gate both supplier qualification and price differentiation simultaneously, invalidating legacy certifications for non-compliant imports while enabling Italian and German vendors to command premium positioning through validated hygiene architectures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on stainless-steel grade certification and after-sales service bundling, with FDA-validated clean-in-place systems commanding substantial premiums over manual sanitation alternatives. Cost compression in economy tiers is intensifying because Asian imports face EU MDR conformity barriers at Rotterdam and Hamburg entry points. Quick-service restaurant chains exhibit highest price sensitivity due to standardized procurement scales, while artisan gelato parlors prioritize texture precision over unit economics.
Supply Chain Analysis
Nickel price volatility through London Metal Exchange contracts underwrites austenitic stainless-steel input cost instability for European smelters. Manufacturing gravity centers on Italy's Emilia-Romagna cluster, Germany's North Rhine-Westphalia machinery belt, and China's Shandong dairy equipment zones. Raw material dependencies draw from Indonesian nickel ore, Swedish specialty steel, and German precision compressor components. Single-source vulnerability concentrates in Italian batch freezer fabrication where Carpigiani and Technogel anchor export capacity. Distribution runs through manufacturer-direct project sales for dairy multinationals, regional distributor networks for quick-service maintenance contracts, and e-commerce platforms for compact artisan systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA Food Safety Modernization Act and EFSA hygiene protocols creates substantial switching costs for installed-base equipment, deepening defensive moats for validated vendors.
For Market Incumbents: Shield installed-base profitability by accelerating EU Green Deal heat recovery retrofit programs before third-party service providers capture aftermarket revenue. Deepen backward integration into precision compressor manufacturing to offset German component cost volatility. Counter liquid nitrogen freezing entrants by embedding IoT predictive maintenance architectures that resist independent servicing disintermediation. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Italy or Germany unlocks Western European artisan parlor procurement channels blocked to non-compliant Asian competitors. Target mobile food truck operators in urban United States markets with compact liquid nitrogen systems requiring minimal real estate footprints. Pursue demonstration-based go-to-market through culinary equipment specialty stores in metropolitan France and Spain. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across liquid nitrogen freezing sub-segments as cryogenic infrastructure commoditizes. Long-term viability favors vendors combining regulatory certification depth with service revenue capture rather than pure equipment manufacturing. Target batch freezer specialists with established EFSA validation and dense Emilia-Romagna supplier relationships. Monitor EU MDR enforcement intensity at Rotterdam customs as inflection indicator for import competition viability.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Integration | Tetra Pak and GEA extend downstream control through combined freezing-sterile packaging architectures. |
| Clean-in-Place Retrofit Programs | Italian vendors capture recurring service revenue from FDA-mandated sanitation protocol upgrades. |
| Liquid Nitrogen System Miniaturization | Artisan operators in Chicago and New York adopt compact cryogenic units for on-demand production. |
| EU Green Deal Heat Recovery Installation | German dairy processors deploy variable-speed compressor upgrades to meet energy efficiency benchmarks. |
| Online Retail Channel Expansion | E-commerce platforms disintermediate distributor relationships for small-batch artisan equipment procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC equipment manufacturer filings, EU customs import databases, and FDA Food Safety Modernization Act guidance documents. Primary interviews incorporated equipment procurement directors at dairy multinationals, maintenance supervisors at quick-service restaurant chains, artisan gelato parlor operators in Italy and France, and aftermarket service managers at regional distributors. Secondary validation drew from EFSA hygiene standard publications, EU MDR conformity assessment procedures, and trade flow data through Rotterdam and Hamburg ports. Bottom-up equipment shipment analysis triangulates against top-down frozen dessert production capacity estimates.
Segmentation dimensions modeled span product type, freezing technology, end-user category, and distribution channel across the projection horizon. The analytical framework incorporates batch freezer versus continuous freezing line deployment patterns, liquid nitrogen versus mechanical refrigeration adoption curves, and direct sales versus distributor channel mix shifts. CAGRs were derived from installed base replacement cycles, regulatory compliance upgrade timelines, and artisan parlor densification trajectories. Industry-specific forecast inputs include EU Green Deal energy retrofit incentive uptake and FDA clean-in-place validation protocol diffusion rates.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA enforcement intensity and stable nickel price corridors; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR food-contact material specifications evolve and cryogenic freezing technology cost curves shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Dispensing Systems and Equipment Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
De-Agglomerating Equipment Market