
 Asia-Pacific Dairy Alternatives Market | 2026-2036
Asia-Pacific Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dairy Alternatives Market Outlook
Supermarket shelf space allocation is narrowing as health food stores and online retail platforms capture higher-margin dairy alternative SKUs. Kikkoman Corporation leverages its fermentation expertise to anchor premium soy milk positioning across Japan and export markets. Vitasoy International Holdings Ltd competes through vertically controlled distribution in Greater China, while Blue Diamond Growers sustains almond milk supply reliability via dedicated orcharding partnerships in California that service Asia-Pacific demand.
Asia-Pacific dairy alternatives comprise non-bovine beverages formulated from oilseeds, cereals, or nuts through aqueous extraction, enzymatic treatment, and homogenization to achieve protein dispersion and sensory parity with fluid milk, serving lactose-intolerant populations and flexitarian dietary transitions. Soy milk retains mature volume leadership due to established processing infrastructure and cultural familiarity, while oat milk represents the fastest-growing product type as beverage manufacturers seek foaming stability for specialty coffee applications. Tetra pack packaging dominates ambient distribution, though pouches gain traction among bulk sellers targeting food processor cost efficiency.
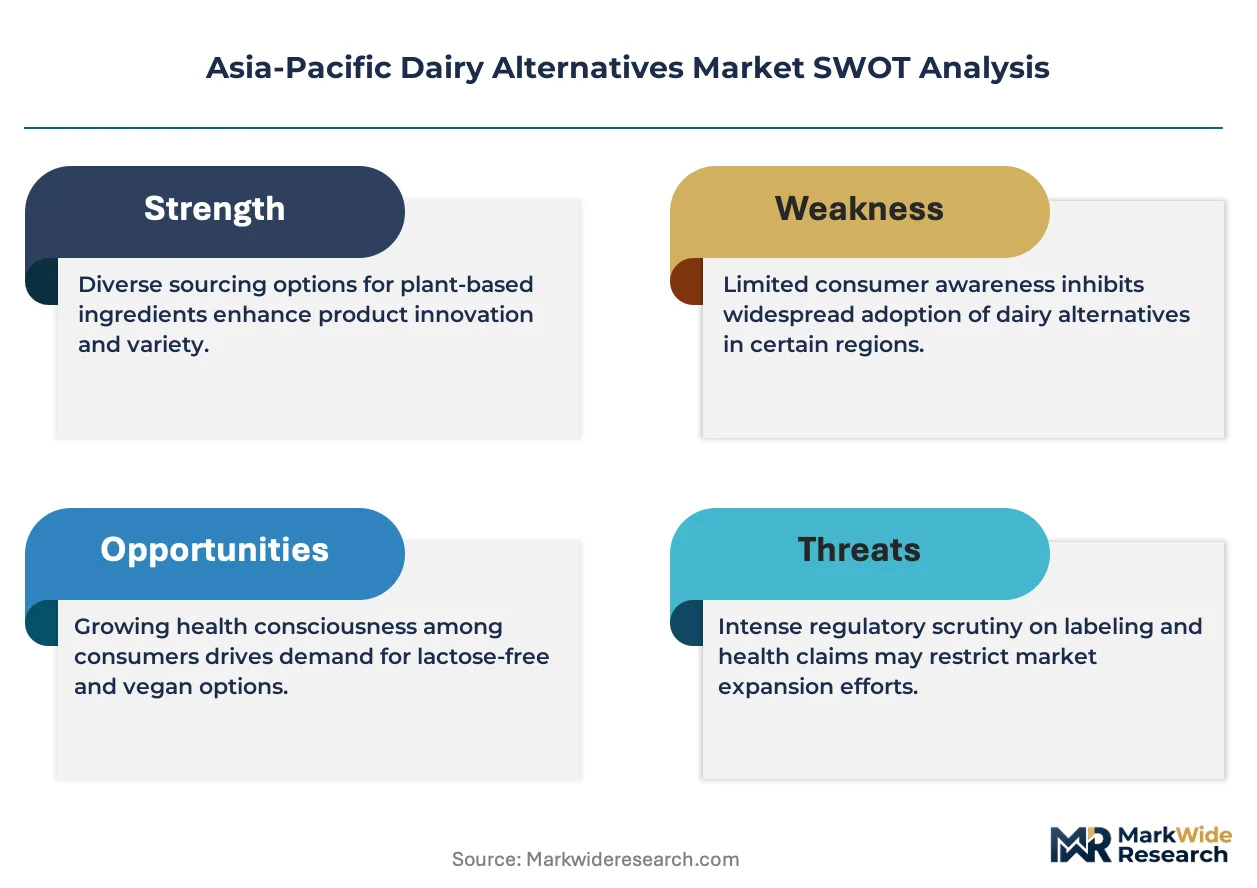
FSSAI in India mandates protein content thresholds for plant-based milk claims, while China's SAMR enforces GB standard compliance on additive use and shelf-life declarations, and Australia's Food Standards Code governs allergen labeling for almond and soy derivatives across imported and domestic products. These frameworks elevate formulation costs for new entrants but simultaneously protect incumbent investments in certified production lines. Stakeholders must monitor evolving protein fortification rules and bioengineered ingredient approvals that will determine next-generation product access across the region's fragmented enforcement landscape.
Market Dynamics
China's SAMR labeling enforcement is compressing formulation flexibility across the Asia-Pacific dairy alternatives sector, forcing manufacturers to re-certify existing product lines while simultaneously accelerating protein fortification investments to meet tightening compositional thresholds.
Growth Catalysts
- FSSAI Protein Mandates:India's 2024 protein content thresholds for plant-based milk claims are compelling domestic formulators to upgrade extraction infrastructure, creating certified capacity that commands retail shelf access.
- Specialty Coffee Penetration:Independent cafés across Melbourne, Singapore, and Seoul are standardizing oat milk as the default dairy alternative, driving bulk procurement contracts with foaming-optimized formulations.
- Enzymatic Hydrolysis Advancement:Neutral protease treatment protocols are reducing beany off-notes in soy milk, enabling sensory parity that converts traditional dairy consumers in Japan's aging demographic.
Market Restraints
- Almond Supply Concentration:California's Central Valley drought vulnerability exposes Asia-Pacific almond milk processors to raw material price volatility and shipping lane disruptions through the Port of Long Beach.
- GB Standard Additive Restrictions:China's SAMR enforcement of GB 2760 limits on stabilizers and emulsifiers is forcing reformulation of shelf-stable products, extending R&D cycles by 8-14 months for new entrants.
- Sensory Ceiling in Cereal Milks:Oat and rice milk variants face persistent viscosity and mouthfeel limitations in ambient storage conditions, constraining adoption in food manufacturing applications requiring extended heat stability.
Strategic Opportunities
- Indonesia's Untapped Halal Segment:The country's 230 million Muslim consumers represent an underserved addressable base for certified soy and coconut milk variants, with modern trade penetration below 12% in secondary cities.
- Direct-to-Processor Bulk Channels:Pouch packaging for food service and manufacturing buyers is bypassing traditional retail markups, capturing margin previously allocated to supermarket slotting fees.
- Australia's Food Standards Code Alignment:Harmonized allergen labeling requirements across imported and domestic products are creating a certification passport effect, enabling single-production-run export strategies to New Zealand and Pacific markets.
Industry Challenges
- Fermentation Specialist Scarcity:Traditional soy milk producers in Japan and China face recruitment gaps for koji and enzymatic process engineers as beverage multinationals absorb technical talent.
- Cross-Border Formulation Variance:Divergent protein threshold interpretations between India's FSSAI and China's SAMR are forcing parallel SKU development, fragmenting production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dairy Alternatives Market |
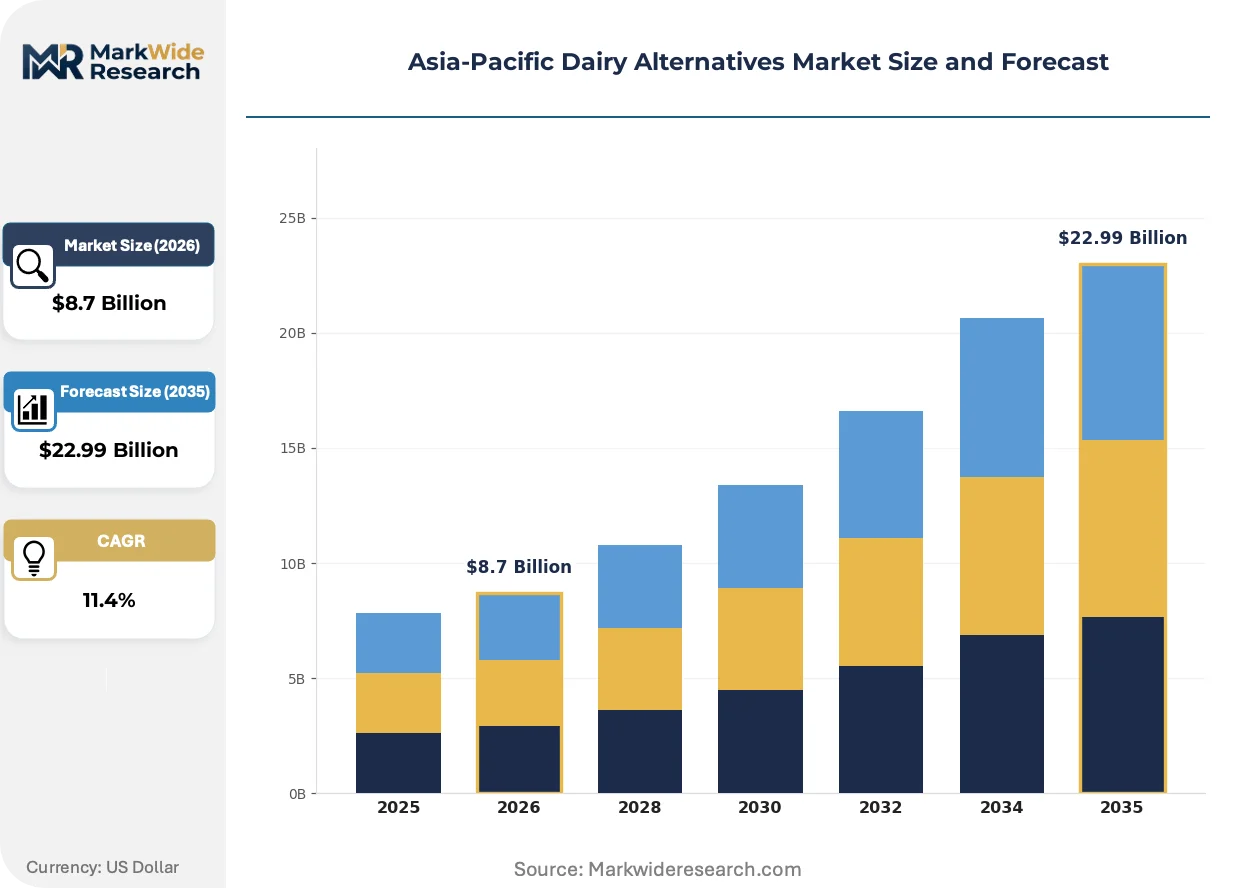
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Coconut Milk, Oat Milk End User: Retail Consumers, Food Service, Food Processors, Beverage Manufacturers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Bulk Sellers Packaging Type: Cartons, Bottles, Pouches, Tetra Packs |
| Companies Covered | Kikkoman Corporation, Blue Diamond Growers, Vitasoy International Holdings Ltd, Sanitarium Health & Wellbeing Company, Danone SA, Hebei Yangyuan Zhihui Beverage Co. Ltd, Nestlé SA, Freedom Foods Group Limited, Coconut Palm Group Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dairy Alternatives Market Strategic Shifts
Ultrafiltration membrane technology is collapsing the cost gap between commodity and premium plant milk tiers, while regulatory protein mandates and specialty coffee channel expansion are simultaneously reshaping formulation priorities and distribution economics.
Precision fermentation-derived whey and casein proteins are collapsing the functional performance differential between plant-based and bovine dairy in barista applications. Specialty coffee chains across Australia and South Korea are adopting these hybrid formulations at 3-4x the rate of conventional oat milk upgrades. The technology is collapsing premium pricing power for legacy almond and soy SKUs as sensory parity becomes achievable at commodity cost structures.
Australia's Food Standards Code 1.2.3 revisions are mandating explicit allergen callouts for tree nut and soy derivatives in both imported and domestically produced beverages. This regulatory tightening is elevating compliance costs for Southeast Asian exporters targeting Australian supermarket listings. Coconut and oat variants without major allergen declarations are capturing disproportionate shelf resets in Coles and Woolworths as retailers mitigate liability exposure.
Café procurement teams are consolidating supplier relationships around single-source oat milk contracts with guaranteed foaming consistency and volume commitments. This buyer concentration is displacing fragmented multi-SKU ordering patterns that previously characterized independent coffee shop purchasing. The shift is most visible in Tokyo and Melbourne, where roasting cooperatives are negotiating direct manufacturing partnerships that bypass traditional beverage distributor networks entirely.
Asia-Pacific Dairy Alternatives Market Segmentation
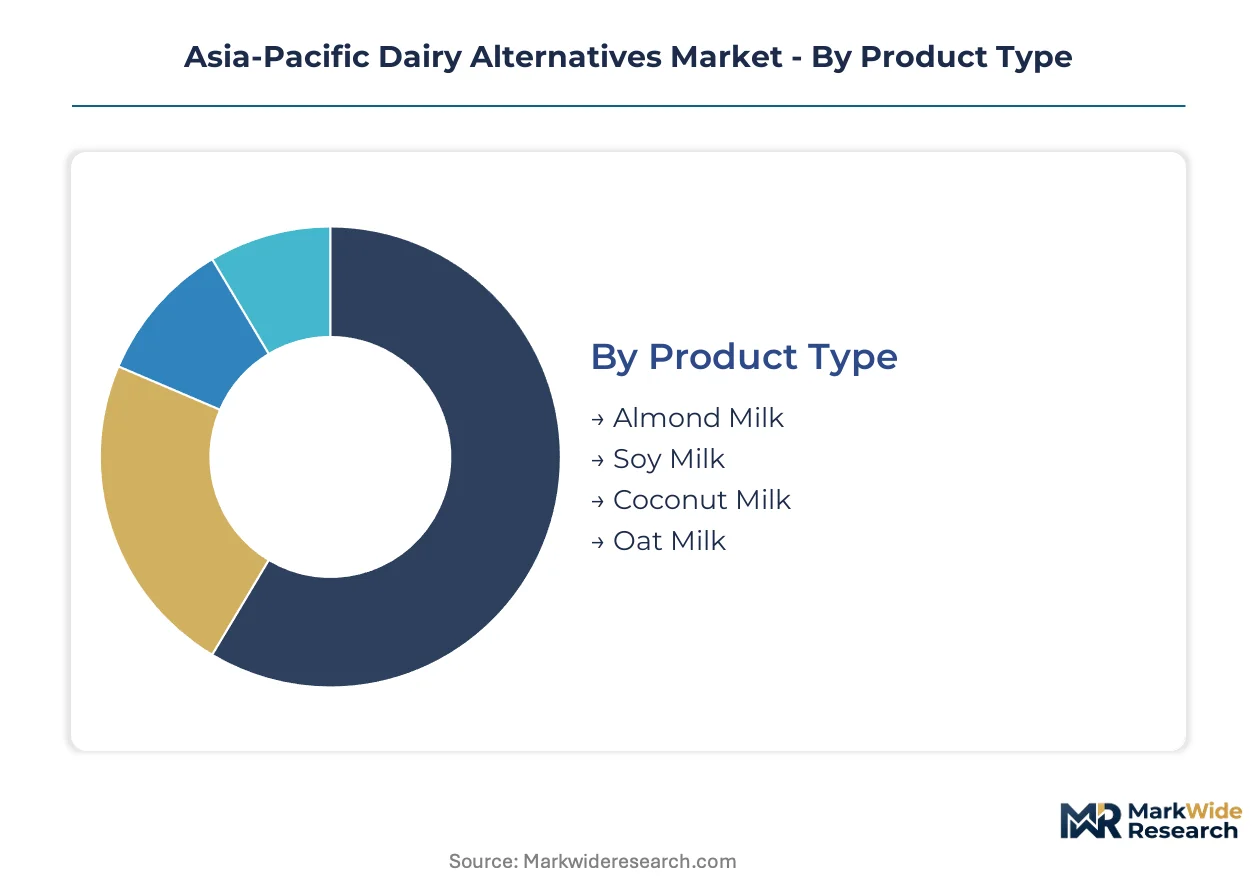
Product heterogeneity across the Asia-Pacific dairy alternatives sector demands granular segmentation to isolate where formulation investments concentrate and which channel structures extract maximum margin. Each dimension reveals divergent growth mechanics that separate volume leaders from profit pool capturers.
Product Type:
Mature soy milk infrastructure contrasts sharply with emerging oat milk capacity, creating a bifurcated investment landscape across extraction technologies.
- Soy Milk:Aqueous extraction from dehulled soybeans yields 3.0-3.5% protein dispersion with established enzymatic debittering protocols. China's SAMR protein mandates are forcing consolidation toward certified production lines in Shandong and Hebei provinces where FSSAI-equivalent infrastructure already exists.
- Oat Milk:Enzymatic hydrolysis of oat starch generates beta-glucan viscosity and foam stability optimized for Melbourne and Seoul café applications. Specialty coffee procurement teams are locking in 24-month supply contracts that bypass traditional distributor networks entirely.
- Almond Milk:California Central Valley sourcing dominates Asia-Pacific supply through dedicated orcharding partnerships.
- Coconut Milk:Indonesian and Philippine copra processing serves both retail and food manufacturing with minimal allergen labeling burden under Australia's Food Standards Code.
Soy milk handles the majority of throughput; oat milk is climbing the fastest on share.
End User:
Volume concentration varies sharply by customer procurement sophistication and formulation specification tolerance.
- Food Service:Café and restaurant operators demand foaming-optimized oat milk with guaranteed viscosity consistency across batch sizes. Direct-to-processor bulk channels are capturing margin previously allocated to supermarket slotting fees.
- Retail Consumers:Urban Indian corridors and Japanese convenience stores drive premium soy and almond milk SKUs with protein fortification claims. FSSAI and GB standard compliance costs are elevating shelf access barriers for uncertified entrants.
- Food Processors:Ambient-stable pouches target cost efficiency in bakery and confectionery applications.
- Beverage Manufacturers:Tetra pack integration for extended shelf-life distribution.
Retail consumers absorb the largest volume base; food service is expanding most quickly on procurement contract value.
Distribution Channel:
Channel economics are fragmenting as online platforms and bulk sellers disintermediate traditional supermarket dominance.
- Supermarkets:Coles and Woolworths in Australia are resetting shelf space toward coconut and oat variants to mitigate allergen liability exposure under Food Standards Code 1.2.3 revisions. Slotting fee structures favor incumbents with certified production lines.
- Online Retail:Health food platforms capture higher-margin SKUs with direct subscription models bypassing retail markups entirely.
- Health Food Stores:Curated premium positioning for enzymatically treated and precision fermentation-derived variants.
- Bulk Sellers:Pouch packaging for food processor cost efficiency.
Supermarkets retain the deepest volume penetration; online retail is gaining share fastest on margin capture.
Packaging Type:
Packaging selection tracks directly against distribution temperature requirements and customer scale economics.
- Tetra Packs:Aseptic carton technology dominates ambient distribution across Southeast Asian modern trade with 6-12 month shelf stability. China's SAMR additive restrictions under GB 2760 are extending R&D cycles for stabilizer-dependent formulations.
- Pouches:Flexible bulk packaging for food service and manufacturing buyers reduces per-unit logistics cost.
- Cartons:Standard chilled distribution for retail premium positioning.
- Bottles:Refrigerated supply chain integration for short-shelf-life formulations.
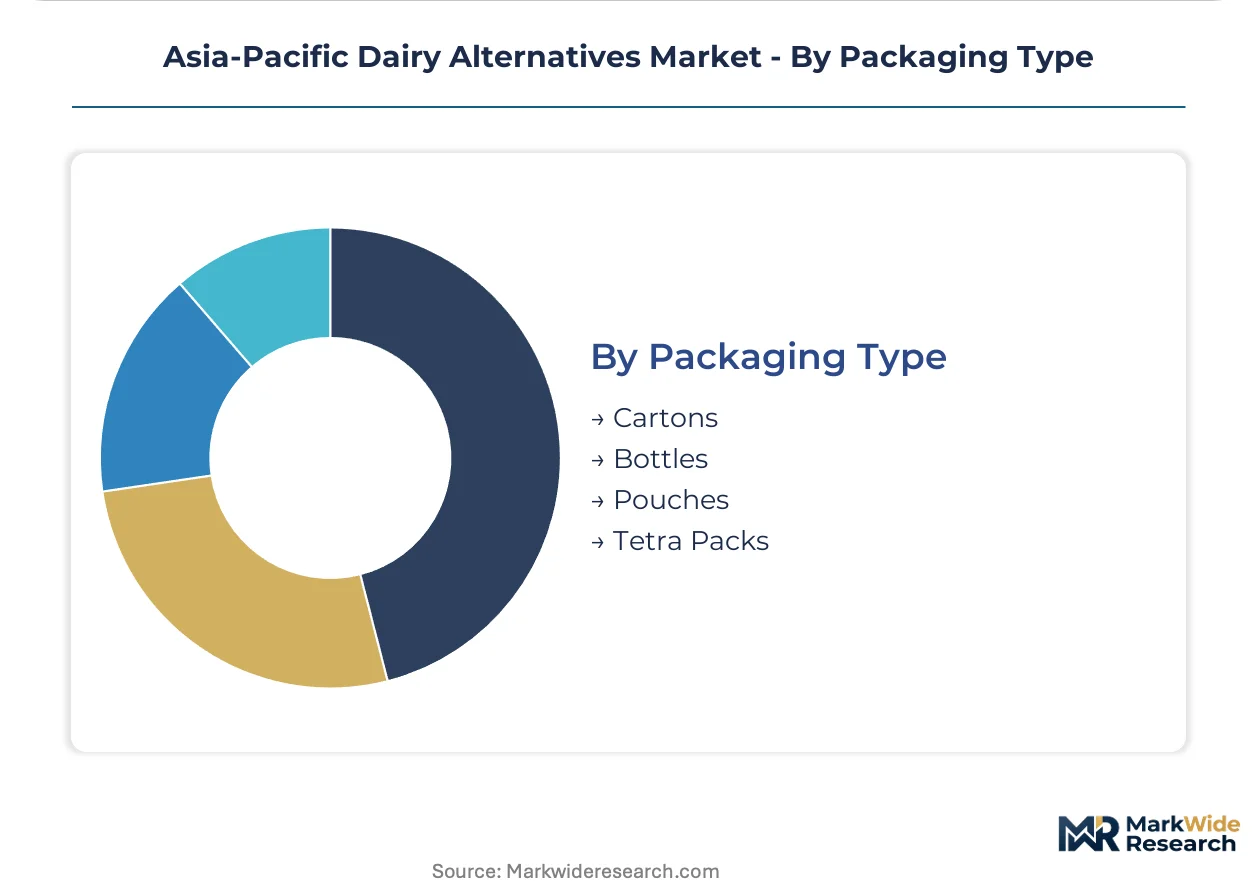
Tetra packs command the largest installed base; pouches are expanding most quickly on food processor adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific dairy alternative distribution, handling bulk soybean and oat concentrate imports that feed processing clusters across the Yangtze River Delta. This maritime infrastructure underwrites China's dominance in regional formulation capacity and export logistics.
China
Urban café culture in Shanghai and Beijing drives oat milk procurement contracts with foaming-optimized specifications. SAMR's GB 2760 additive restrictions are extending R&D cycles for shelf-stable formulations. Shandong and Hebei provinces concentrate certified soy milk production lines serving both domestic retail and export markets.
Japan
Aging demographics and lactose intolerance prevalence sustain premium soy milk consumption in Tokyo and Osaka convenience channels. METI guidelines on functional food claims shape protein fortification marketing. Kanto region fermentation specialists face recruitment pressure from beverage multinationals seeking enzymatic process engineers.
India
Mumbai and Delhi urban corridors absorb volume growth for almond and soy variants as flexitarian diets expand among middle-class consumers. FSSAI protein content thresholds for plant-based milk claims are elevating shelf access barriers. Gujarat and Maharashtra host upgraded extraction infrastructure meeting certified production standards.
Australia
Melbourne's specialty coffee roasting cooperatives negotiate direct oat milk manufacturing partnerships bypassing traditional distributors. Food Standards Code 1.2.3 allergen labeling revisions are resetting supermarket shelf space toward coconut variants. Sydney and Brisbane health food platforms capture premium SKU margins through subscription direct-to-consumer models.
Indonesia
Jakarta and Surabaya modern trade expansion targets 230 million Muslim consumers with halal-certified soy and coconut variants. The national halal certification authority's beverage standards create compliance pathways for domestic processors. Java-based copra processing clusters serve both retail and regional food manufacturing demand with minimal allergen labeling burden.
Asia-Pacific Dairy Alternatives Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream controlling raw material throughput. The vendor base organizes around three tiers: multinational beverage conglomerates with diversified plant-based portfolios, regional dairy alternative pure-plays with category depth, and agricultural cooperatives securing almond and soybean supply. Consolidation pressures favor incumbents with certified production lines that absorb regulatory compliance costs. Competitive moves concentrate on backward integration into orchard and oilseed sourcing, plus direct-to-processor bulk channel development that bypasses retail markups.
Within the fermentation-anchored tier, Kikkoman Corporation represents Japanese soy milk platform expertise leveraging century-old enzymatic protocols. Blue Diamond Growers occupies a position as a California-based agricultural cooperative securing almond supply reliability through dedicated orcharding partnerships. Vitasoy International Holdings Ltd exemplifies Greater China vertical distribution control with captive retail channel access across urban corridors.
| Leading Market Players |
|---|
| Kikkoman Corporation |
| Blue Diamond Growers |
| Vitasoy International Holdings Ltd |
| Sanitarium Health & Wellbeing Company |
| Danone SA |
| Hebei Yangyuan Zhihui Beverage Co. Ltd |
| Nestlé SA |
| Freedom Foods Group Limited |
| Coconut Palm Group Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
The Port of Shanghai's container handling rates shape cost-to-serve differentials across the Asia-Pacific dairy alternatives sector, compressing margins for California almond milk exporters while amplifying price-setting power for Shandong soy milk processors with captive Yangtze River Delta distribution.
Pricing Analysis
Volume-discount tiering structures separate foaming-optimized oat milk contracts for Melbourne café cooperatives from commodity pouch formats targeting Indonesian food processors. Price differentiation hinges on FSSAI and SAMR certification grade plus guaranteed viscosity consistency across batch sizes. Pricing pressure stems from precision fermentation-derived whey proteins achieving sensory parity at commodity cost structures. Food processors exhibit highest price sensitivity; specialty coffee roasting cooperatives demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for almond milk processors dependent on California Central Valley orcharding partnerships. Raw material flows draw from Australian oat milling, Indonesian copra processing, and Japanese enzymatic fermentation infrastructure. Single-source vulnerability concentrates in California almond supply through Port of Long Beach shipping lanes. Distribution runs through direct-to-processor bulk channels bypassing traditional supermarket slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived dairy proteins threaten incumbent plant-based positioning by collapsing the functional performance differential in barista applications at commodity cost structures.
For Market Incumbents: Entrench certified production line investments in Shandong and Hebei provinces to absorb SAMR protein mandate compliance costs that fragment new entrant scale economies. Deepen captive distribution control across Greater China urban corridors to defend against precision fermentation hybrid formulations displacing legacy almond and soy SKUs.
For New Entrants and Emerging Players: Establish a beachhead in Indonesia's halal-certified soy and coconut milk segment where modern trade penetration sits below twelve percent in secondary cities. Target direct-to-processor pouch packaging channels for food service and manufacturing buyers to capture margin bypassing supermarket slotting fees entirely.
For Investors and Strategic Acquirers: Fermentation-anchored regional pure-plays with enzymatic process engineering depth represent acquisition targets with defensible technical moats. Long-term viability across the analysis window hinges on backward integration into oilseed and orchard supply plus certification passport strategies under Australia's Food Standards Code. Monitor precision fermentation protein cost curves as inflection indicator for plant-based premium pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Production Line Investment | FSSAI and SAMR compliance creates shelf access barriers protecting incumbent returns. |
| Direct-to-Processor Bulk Channel Development | Pouch packaging bypasses supermarket slotting fees, capturing margin for food service buyers. |
| Backward Integration into Orchard Supply | California Central Valley partnerships insulate almond milk processors from drought-driven price volatility. |
| Precision Fermentation Partnership | Hybrid whey protein formulations collapse sensory parity gaps threatening legacy SKU premiums. |
| Halal Certification Pathway Expansion | Indonesia's national halal authority standards unlock 230 million Muslim consumer access. |
Study Parameters
The analysis maps soy milk extraction infrastructure, oat milk enzymatic hydrolysis capacity, almond milk orcharding partnerships, and coconut milk copra processing clusters, each validated through fermentation process engineers, café procurement managers, supermarket category buyers, and regulatory affairs specialists at FSSAI and SAMR. Primary interview intelligence triangulates against secondary sources including customs and trade flow databases, food safety authority filings, retail audit data from Nielsen and Circana, and beverage manufacturer SEC disclosures. Bottom-up capacity modeling and top-down demand aggregation converge across the analytical framework.
Assumptions held fixed include protein mandate enforcement intensity at current SAMR and FSSAI levels, specialty coffee channel penetration trajectories in Melbourne and Seoul, and California almond yield recovery patterns. Segmentation dimensions span product type, end-user procurement sophistication, distribution channel structure, and packaging temperature requirements. CAGRs derive from volume trajectory modeling against price elasticity parameters and input cost pass-through coefficients. Forecast inputs incorporate enzymatic hydrolysis efficiency curves and precision fermentation protein cost reduction pathways.
Stress conditions across California drought severity, SAMR additive restriction enforcement, and precision fermentation protein commercialization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory reinterpretation, supply disruption, or substitute technology acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Dairy-Free Evaporated Milk Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Germany Dairy Alternatives Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Dairy-Free Spreads Market