
 VCSEL Market | 2026-2036
VCSEL Market Size, Share, and Industry Trends Forecast 2026-2036
VCSEL Market Analysis
Aftermarket service revenue for legacy edge-emitting laser modules is narrowing as VCSEL-based transceivers displace field-replaceable components. Lumentum Operations LLC leverages vertical integration across epitaxial growth and wafer fabrication to sustain margin capture. Coherent Corp. anchors its position through in-house production of GaAs substrates and foundry-scale MOCVD capacity. TRUMPF competes in industrial sensing with high-power VCSEL arrays for thermal process monitoring.
A vertical-cavity surface-emitting laser emits coherent light perpendicular to the semiconductor wafer plane through a resonant cavity formed by distributed Bragg reflector mirrors, typically operating at wavelengths from 850 nm to 1,550 nm with threshold currents below one milliampere. Its primary commercial purpose centers on high-density optical interconnects, three-dimensional sensing arrays, and precision illumination for time-of-flight cameras. Multi-mode VCSELs dominate data communication transceivers for short-reach fiber links inside hyperscale data centers. Sensing applications in automotive LiDAR and facial recognition systems represent the fastest-expanding demand pool. Single-mode devices command premium positioning in telecommunications coherent detection and healthcare spectroscopy instruments.
The US FCC governs laser product emission limits under Code of Federal Regulations Title 21, while FDA's Center for Devices and Radiological Health classifies VCSEL-based medical devices by risk tier. Europe's RoHS directive and REACH framework restrict hazardous substances in gallium arsenide epitaxy and packaging materials. China's MIIT mandates GB standards for optical communication equipment and dual carbon compliance for semiconductor fabrication energy intensity. Stakeholders must monitor regulatory divergence between US laser safety classifications and EU MDR requirements for emerging healthcare VCSEL applications.
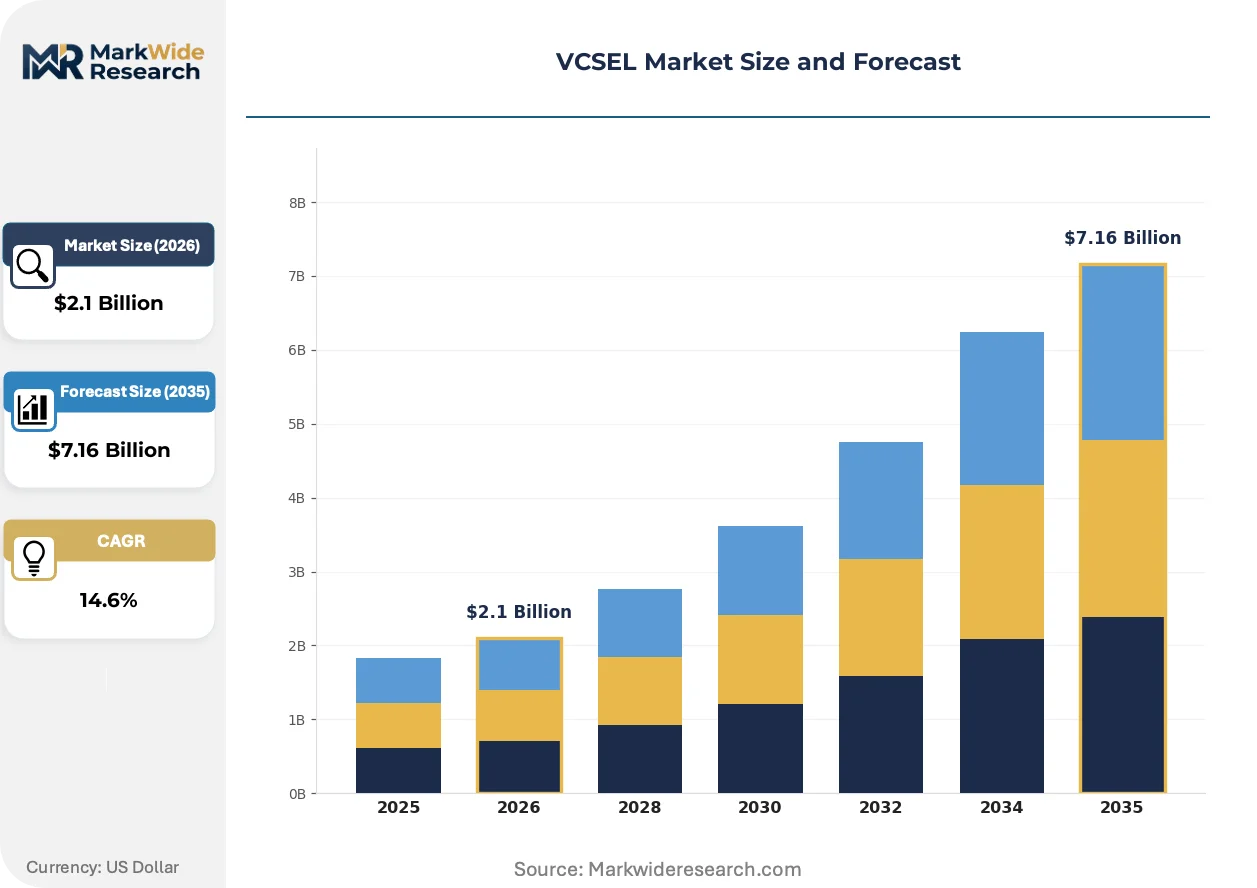
Market Dynamics
Data center buildouts and automotive LiDAR mandates are compressing VCSEL qualification cycles while China's MIIT dual carbon standards force foundry energy audits, reshaping where epitaxial capacity expands.
Growth Catalysts
- Hyperscale optical interconnects:Multi-mode VCSEL arrays power 800G transceivers inside cloud data centers, with fiber density requirements doubling every 18 months.
- Automotive LiDAR mandates:NHTSA proposed rules in the United States push OEMs toward solid-state sensing architectures that integrate VCSEL-based time-of-flight modules.
- China's dual carbon compliance:MIIT energy intensity standards for semiconductor fabrication accelerate migration to high-efficiency MOCVD reactors and renewable-powered foundries.
Market Restraints
- GaAs substrate concentration:Six-inch gallium arsenide wafer supply concentrates among Japanese and German substrate vendors, creating input bottlenecks during capacity expansions.
- RoHS material restrictions:ECHA's REACH framework limits certain dopants used in 940 nm epitaxy, forcing reformulation of long-wavelength device stacks.
- Edge-emitter substitution in telecom:Coherent detection links beyond 10 km increasingly favor distributed feedback lasers over single-mode VCSELs for linewidth stability.
Strategic Opportunities
- Underpenetrated healthcare spectroscopy:Near-infrared VCSELs for non-invasive glucose monitoring await FDA 510(k) clearance pathways, with pilot deployments in German university hospitals.
- Convergence with silicon photonics:Heterogeneous integration of VCSEL dies onto silicon interposers enables co-packaged optics for AI training clusters.
- India's PLI scheme for telecom:Production-linked incentives for optical fiber manufacturing create localized demand for 850 nm transceiver components.
Industry Challenges
- Compound semiconductor talent scarcity:MOCVD reactor operation and epitaxial characterization expertise pools thinly across the United States, Germany, and Japan.
- Automotive AEC-Q102 qualification timelines:VCSEL arrays for LiDAR face 18-24 month stress-test cycles, delaying revenue recognition against OEM platform deadlines.
- Legacy transceiver inventory absorption:Field-replaceable 100G modules face accelerated depreciation as 400G VCSEL-based shipments ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VCSEL Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, VCSEL Arrays, Coaxial VCSELs Application: Data Communication, Sensing, Industrial Automation, Consumer Electronics Technology: Broadband, High-Speed, Short-Wavelength, Long-Wavelength End User: Telecommunications, Automotive, Healthcare, Aerospace |
| Companies Covered | ams-OSRAM AG, TRUMPF, Lumentum Operations LLC, Vertilas GmbH, Santec Corporation, Coherent Corp., II-VI Incorporated, VIAVI Solutions Inc., Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VCSEL Market Emerging Trajectories
Wavelength extension and heterogeneous integration are redefining VCSEL performance boundaries while regulatory energy mandates reshape manufacturing footprints.
Long-wavelength VCSELs at 1,310 nm and 1,550 nm are hybridizing indium phosphide active regions with metamorphic buffer layers on GaAs substrates. Telecom equipment vendors in Germany and Japan are sampling these devices for coherent access networks. This hybridizing architecture collapses the cost gap between VCSELs and edge-emitters in metro links.
China's MIIT GB standards for optical communication equipment now mandate energy disclosure labels and carbon footprint documentation for exported transceiver modules. Foundries serving Chinese OEMs must submit third-party verified electricity consumption data per wafer start. European and American component suppliers are establishing parallel audit trails to maintain qualification status.
Hyperscale buyers are consolidating optical transceiver procurement around direct foundry relationships, bypassing traditional module integrators. Amazon Web Services, Microsoft Azure, and Google Cloud now specify VCSEL die performance bins directly with epitaxial houses. This channel compression concentrates volume with vertically integrated suppliers in the United States and Taiwan.
VCSEL Market Segmentation
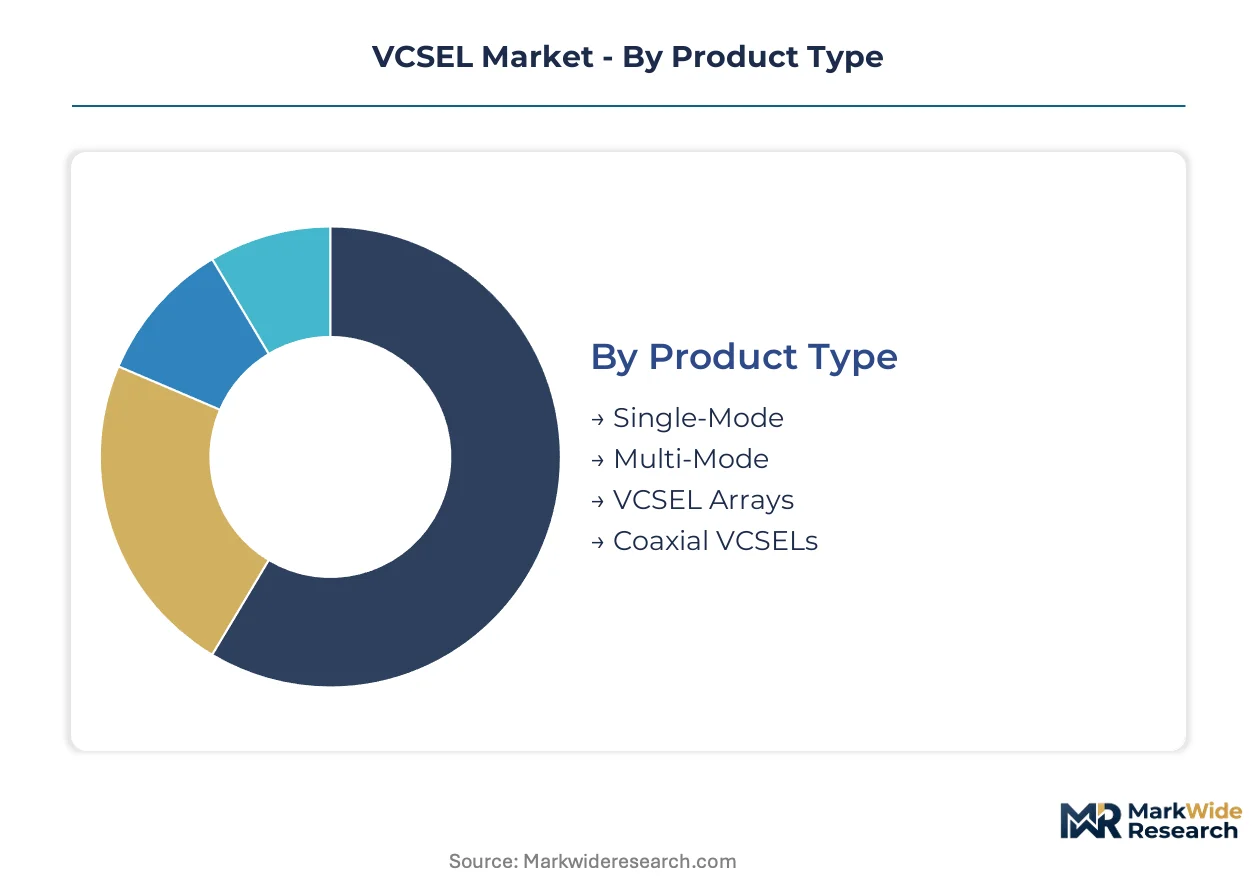
VCSEL market segmentation reveals how device architecture, wavelength engineering, and end-use requirements fragment demand across incompatible technical specifications. Each dimension carries distinct qualification protocols and margin structures that reshape supplier positioning.
Product Type:
Device architecture determines threshold current, beam quality, and array scalability for target applications.
- Single-Mode:Narrow spectral linewidth below 0.1 nm enables coherent detection in telecommunications links. German equipment vendors specify these devices for metro access networks where dispersion tolerance matters. Healthcare spectroscopy instruments in Swiss university hospitals source single-mode VCSELs for glucose monitoring precision.
- Multi-Mode:Larger aperture diameters emit multiple transverse modes with relaxed alignment tolerance. Hyperscale data centers in the United States deploy multi-mode arrays for 800G optical interconnects where fiber coupling efficiency dominates over spectral purity. China's MIIT energy disclosure standards now cover these transceiver modules.
- VCSEL Arrays:Monolithic integration of multiple emitters powers solid-state LiDAR illumination. NHTSA automotive qualification timelines stretch 18-24 months for these components.
- Coaxial VCSELs:Hermetic packaging with integrated monitoring photodiodes suits industrial sensing environments. Japanese factory automation OEMs specify these for thermal process monitoring.
Multi-Mode holds installed capacity. VCSEL Arrays is rotating up the share rankings.
Application:
End-use context dictates reliability grades, thermal management, and regulatory compliance pathways.
- Data Communication:Short-reach fiber links inside cloud facilities drive volume demand. EMA's RoHS restrictions on gallium arsenide packaging materials force substrate-level compliance redesigns for European-bound transceivers.
- Sensing:Time-of-flight modules for facial recognition and automotive LiDAR expand addressable device count per system. Solid-state architectures displace mechanical scanning in NHTSA-influenced vehicle platforms.
- Industrial Automation:High-power arrays monitor thermal processes in German precision manufacturing. METI standards in Japan govern eye safety classifications for these open-beam applications.
- Consumer Electronics:Proximity sensing and structured light projection integrate into smartphones and wearables. FDA laser product classifications apply to VCSEL-based medical accessories in the United States.
Data Communication anchors volume procurement. Sensing is gaining share fastest.
Technology:
Wavelength and speed specifications separate legacy infrastructure from next-generation performance tiers.
- Broadband:Wide spectral emission supports wavelength-division multiplexing without temperature stabilization. Chinese optical access networks deploy these for passive optical network terminals.
- High-Speed:Modulation bandwidths exceeding 50 GHz enable 400G and 800G transceiver lanes. Direct foundry relationships with hyperscale buyers concentrate procurement with vertically integrated suppliers.
- Short-Wavelength:850 nm and 940 nm devices leverage mature GaAs substrate infrastructure. ECHA's REACH framework restricts certain dopants in 940 nm epitaxy, forcing reformulation.
- Long-Wavelength:1,310 nm and 1,550 nm variants hybridize indium phosphide active regions for telecom coherent detection. German and Japanese equipment vendors sample these for metro link cost reduction.
Short-Wavelength holds mature capacity. Long-Wavelength is climbing the fastest.
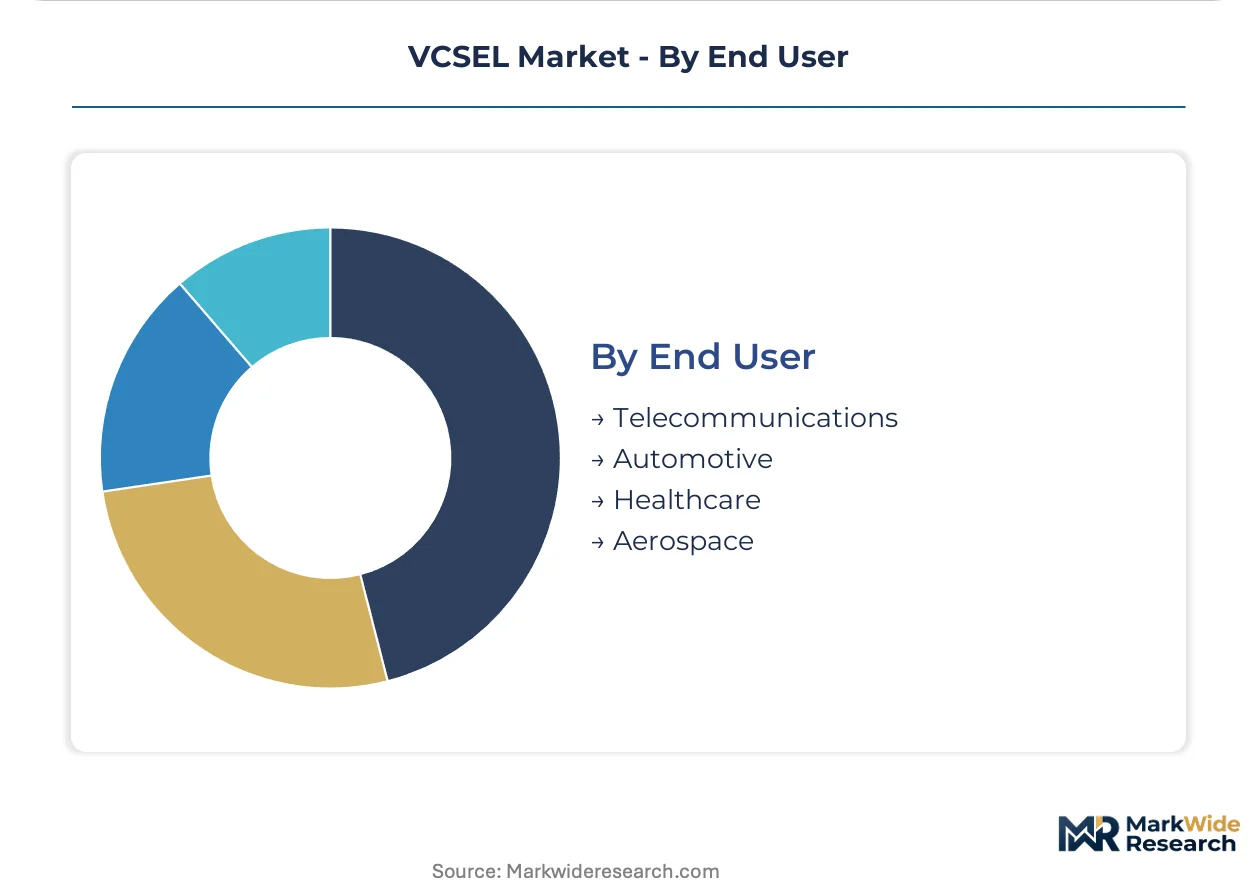
End User:
Customer industry determines qualification intensity, contract duration, and technical support requirements.
- Telecommunications:Coherent detection and access network equipment demand linewidth stability and temperature resilience. India's PLI scheme for optical fiber manufacturing creates localized component demand.
- Automotive:AEC-Q102 stress testing and ISO 26262 functional safety compliance extend design cycles. Solid-state LiDAR mandates from United States regulators accelerate VCSEL array qualification.
- Healthcare:Non-invasive spectroscopy and medical imaging require FDA 510(k) or NMPA registration. Near-infrared glucose monitoring pilots operate in German university hospitals pending clearance.
- Aerospace:Radiation-hardened packaging and extended temperature ranges suit satellite optical inter-satellite links. FAA equipment authorization governs airborne laser products in the United States.
Telecommunications commands legacy volume. Automotive is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators in the United States show the least price elasticity for 800G transceiver modules, while Chinese OEMs face acute cost pressure under MIIT dual carbon compliance audits that reshape foundry selection criteria.
United States
Amazon Web Services, Microsoft Azure, and Google Cloud drive procurement concentration for 800G optical interconnects. The FCC governs laser product emission limits under Code of Federal Regulations Title 21, while NHTSA proposed rules push automotive OEMs toward solid-state LiDAR architectures. Silicon Valley epitaxial houses and Boston-area photonics clusters anchor direct foundry relationships that bypass traditional module integrators.
China
Domestic hyperscale buildouts and automotive LiDAR mandates compress VCSEL qualification cycles for local OEMs. MIIT mandates GB standards for optical communication equipment and dual carbon compliance for semiconductor fabrication energy intensity, forcing third-party verified electricity consumption data per wafer start. Yangtze River Delta foundries migrate to renewable-powered MOCVD reactors to maintain export qualification status.
Germany
Telecommunications equipment vendors sample long-wavelength VCSELs for coherent access networks and metro link cost reduction. ECHA's REACH framework restricts certain dopants used in 940 nm epitaxy, forcing reformulation of device stacks for European-bound transceivers. Munich and Stuttgart industrial clusters deploy high-power VCSEL arrays for thermal process monitoring in precision manufacturing.
Japan
METI standards govern eye safety classifications for open-beam industrial sensing applications. Six-inch gallium arsenide wafer supply concentrates among domestic substrate vendors, creating input bottlenecks during capacity expansions. Tokyo and Osaka metropolitan areas host factory automation OEMs specifying coaxial VCSELs with hermetic packaging for harsh environment deployment.
India
Production-linked incentives for optical fiber manufacturing create localized demand for 850 nm transceiver components. TRAI regulations shape telecommunications infrastructure procurement patterns for access network deployment. Bengaluru and Hyderabad technology corridors attract component suppliers seeking to serve domestic telecom equipment vendors under PLI scheme localization requirements.
VCSEL Market Vendor Landscape
Capability concentration sits with vertically integrated epitaxial specialists; scale advantage sits with diversified photonics conglomerates. The vendor base separates into three tiers: captive suppliers serving single hyperscale buyer specifications, merchant houses selling across multiple end-use segments, and substrate specialists controlling gallium arsenide wafer inputs. Dominant competitive moves include backward integration into MOCVD reactor capacity and geographic expansion of epitaxial foundry footprints to satisfy regional content requirements.
Within the vertically integrated tier, Lumentum Operations LLC and Coherent Corp. occupy positions defined by in-house production of GaAs substrates and foundry-scale MOCVD capacity. TRUMPF exemplifies the industrial sensing specialist archetype. These three anchors demonstrate how control over epitaxial growth and wafer fabrication separates margin capture from module assembly commoditization.
| Leading Market Players |
|---|
| ams-OSRAM AG |
| TRUMPF |
| Lumentum Operations LLC |
| Vertilas GmbH |
| Santec Corporation |
| Coherent Corp. |
| II-VI Incorporated |
| VIAVI Solutions Inc. |
| Broadcom Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on six-inch gallium arsenide wafer supply from Japanese and German substrate vendors determines both the spread between premium single-mode and economy multi-mode VCSEL tiers and the geographic clustering of epitaxial foundry investments. This bottleneck concentrates pricing power upstream while compressing margins at module integrators who lack captive substrate access.
Pricing Analysis
Aftermarket service contracts for legacy edge-emitting laser modules drive lifetime value capture as field-replaceable components face accelerated depreciation. Three-tier pricing structure across AEC-Q102 automotive-certified, industrial-grade, and consumer-tier devices separates premium single-mode coherent detection units from standard multi-mode data center arrays. Cost compression in consumer electronics proximity sensing reflects hyperscale buyer consolidation around direct foundry relationships. Automotive OEMs show least price sensitivity due to 18-24 month qualification lock-in, while Chinese transceiver vendors face acute cost pressure under MIIT dual carbon compliance audits.
Supply Chain Analysis
Extended payment terms from Japanese and German substrate vendors to Taiwanese and American epitaxial houses shape working capital requirements across tier-two module integrators. Six-inch GaAs wafer supply concentrates in Japan and Germany, while MOCVD reactor fabrication anchors in the United States and China. Indium phosphide active regions, metamorphic buffer layers, and hermetic packaging ceramics constitute critical input dependencies. Single-source vulnerability in gallium arsenide substrate supply creates chokepoint exposure during capacity expansion cycles. Distribution runs through direct foundry relationships with hyperscale cloud operators, bypassing traditional module integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against distributed feedback lasers reclaiming telecom coherent detection links beyond 10 km through superior linewidth stability. Incumbents must navigate this edge-emitter threat while securing captive substrate access.
For Market Incumbents: Entrench position through backward integration into MOCVD reactor capacity and six-inch GaAs substrate production to escape module assembly commoditization. Secure AEC-Q102 qualification pipelines ahead of NHTSA solid-state LiDAR mandates to lock in automotive platform design wins. Prioritize renewable-powered foundry footprints to maintain Chinese OEM qualification under MIIT dual carbon standards.
For New Entrants and Emerging Players: Healthcare spectroscopy instruments for non-invasive glucose monitoring in German university hospitals represent the most penetrable entry point pending FDA 510(k) clearance pathways. India's PLI scheme for optical fiber manufacturing creates localized demand for 850 nm transceiver components with lower qualification barriers. Pursue heterogeneous integration partnerships with silicon photonics foundries serving AI training cluster co-packaged optics demand.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated epitaxial specialists with captive GaAs substrate production and foundry-scale MOCVD capacity. Compound semiconductor talent scarcity across the United States, Germany, and Japan extends the viability window for technical capability acquisition. Monitor NHTSA final rule publication on solid-state LiDAR mandates as inflection indicator for automotive VCSEL array demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive six-inch GaAs wafer supply escapes Japanese and German vendor bottlenecks during capacity expansions. |
| AEC-Q102 Qualification Pipeline Investment | Automotive platform design wins lock in 18-24 month revenue cycles ahead of NHTSA mandates. |
| Renewable-Powered Foundry Migration | MIIT dual carbon compliance maintains Chinese OEM export qualification status. |
| Heterogeneous Integration Partnership | Silicon photonics co-packaged optics serve AI training cluster demand from hyperscale buyers. |
| Healthcare Regulatory Pathway Navigation | FDA 510(k) clearance for glucose monitoring opens underpenetrated spectroscopy segment. |
Methodological Framework
Operator-level perspectives from epitaxial growth engineers, MOCVD reactor operators, hyperscale data center procurement directors, automotive Tier 1 supplier quality managers, and telecommunications equipment vendor optical engineers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC 10-K filings, MIIT GB standard documentation, NHTSA regulatory dockets, and ECHA REACH restriction updates. Bottom-up wafer start estimates and top-down transceiver shipment data triangulated volume and value outputs.
Scenario-bracketing around MIIT dual carbon compliance stringency, NHTSA LiDAR mandate timing, and edge-emitter substitution rates in telecom coherent detection bounded the projection range. Segmentation modeling spanned device architecture, wavelength specification, application end-use, and customer industry vertical. CAGRs derived from compound growth trajectory analysis across the analysis window. Forecast inputs included hyperscale capex disclosure patterns, automotive platform design win timelines, and foundry energy audit compliance trajectories.
Practitioners should monitor regulatory divergence between FDA laser safety classifications and EU MDR requirements, GaAs substrate vendor capacity expansion announcements, and hyperscale buyer direct foundry relationship consolidation for early signals. Forecasts assume sustained qualification cycle compression, continued RoHS material restriction enforcement, and stable compound semiconductor talent availability. Macroeconomic demand fluctuation in cloud infrastructure investment, regulatory delay in automotive sensing mandates, or breakthrough edge-emitter cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Asia-Pacific MLCC Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
Gan Transistor Market