
 Optical Wavelength Service Market | 2026-2036
Optical Wavelength Service Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Wavelength Service Market Intelligence
The EU Green Deal is broadening procurement criteria for network infrastructure across member states. AT&T leverages its nationwide fiber footprint to sustain wavelength service margins in enterprise segments. Lumen Technologies anchors wholesale connectivity through its long-haul route density. Nokia Corporation differentiates with photonic chipsets that reduce power consumption per wavelength.
Optical wavelength service delivers dedicated spectrum channels over fiber optic cables, typically operating at 10 Gbps to 400 Gbps per lambda using DWDM or CWDM multiplexing to transport bulk data between points without electronic regeneration. Its primary purpose is to provide transparent, protocol-independent bandwidth for carriers and enterprises requiring deterministic performance. Dedicated wavelength segments dominate revenue where financial and cloud buyers pay premiums for uncontended paths, while managed wavelength offerings capture fastest growth as enterprises outsource optical layer operations. Application demand concentrates in data center connectivity where latency-sensitive AI training clusters require dark-fiber-equivalent control.
FCC open-access rules in the United States, EU wholesale unbundling under the Electronic Communications Code, and Japan's MIC spectrum coordination for 5G backhaul collectively shape competitive access to fiber ducts and wavelength rights. These frameworks determine whether incumbent carriers must lease dark fiber or wavelength capacity to rival service providers. Stakeholders must monitor regulatory rulings on fiber sharing obligations and spectrum allocation that could alter the economics of building versus buying optical transport capacity.
Market Dynamics
Open optical networking standards are dismantling proprietary vendor lock-in across fiber transport infrastructure. The OIF's 400ZR specifications and TIP's Open Optical & Packet Transport group are forcing incumbent equipment suppliers to interoperate with white-box alternatives, compressing margins while expanding buyer choice.
Growth Catalysts
- AI Training Cluster Expansion:Hyperscale cloud operators in Northern Virginia, Frankfurt, and Tokyo are leasing dedicated wavelengths to interconnect GPU farms with sub-millisecond latency requirements.
- EU Green Deal Procurement Mandates:Member state tenders now weight energy efficiency per gigabit-kilometer, advantaging coherent optical systems over electronic regeneration architectures.
- Submarine Cable Landings:New transatlantic and transpacific cable systems terminating in Bude, Cornwall; Bilbao, Spain; and Shima, Japan are creating wavelength aggregation points for terrestrial backhaul.
Market Restraints
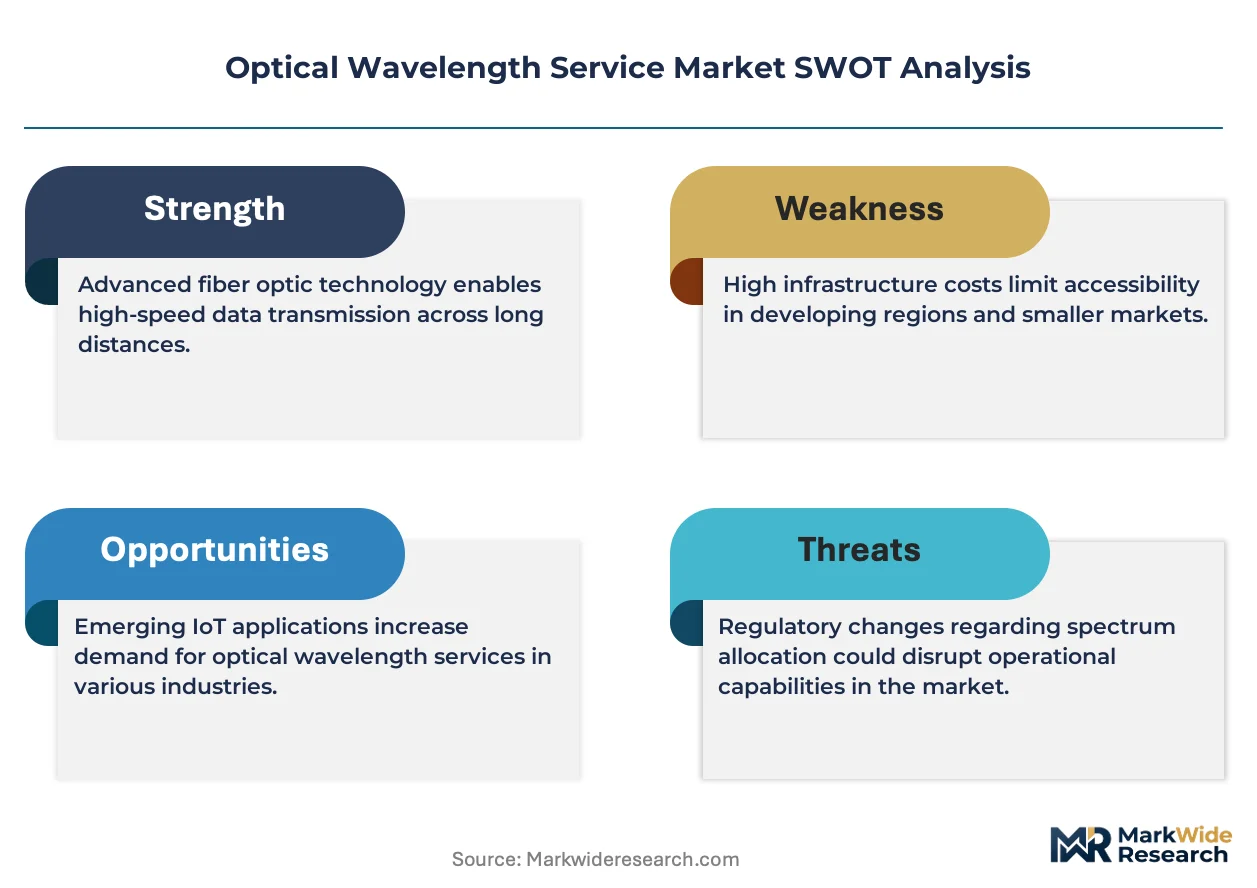
- Erbium-Doped Fiber Amplifier Supply Concentration:Three Japanese and American component houses control high-purity erbium sourcing, exposing wavelength providers to rare earth price volatility.
- FCC Open-Access Rule Uncertainty:Pending determinations on fiber unbundling obligations for incumbent local exchange carriers create capital deployment hesitation for competitive entrants.
- Electronic Regeneration Substitution:IP-over-DWDM routers with integrated coherent optics threaten standalone wavelength service margins in metro edge applications.
Strategic Opportunities
- India's BharatNet Phase III:The rural fiber expansion program requires wavelength-grade backhaul from district headquarters to gram panchayat aggregation points.
- Quantum Key Distribution Integration:Quantum-secured wavelength channels for financial services are converging with standard DWDM infrastructure in Switzerland and South Korea.
- Managed Wavelength Outsourcing:Mid-market enterprises in Germany's Mittelstand sector are abandoning self-operated optical networks for carrier-managed lambda services.
Industry Challenges
- Coherent DSP Engineering Talent Scarcity:The specialized skill set for 800G and 1.6T transceiver design concentrates among a handful of Silicon Valley and Shenzhen engineering teams.
- Legacy SONET/SDH Integration Complexity:Financial institutions in Japan and Germany maintain synchronous optical network interconnections that complicate transparent wavelength provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Wavelength Service Market |
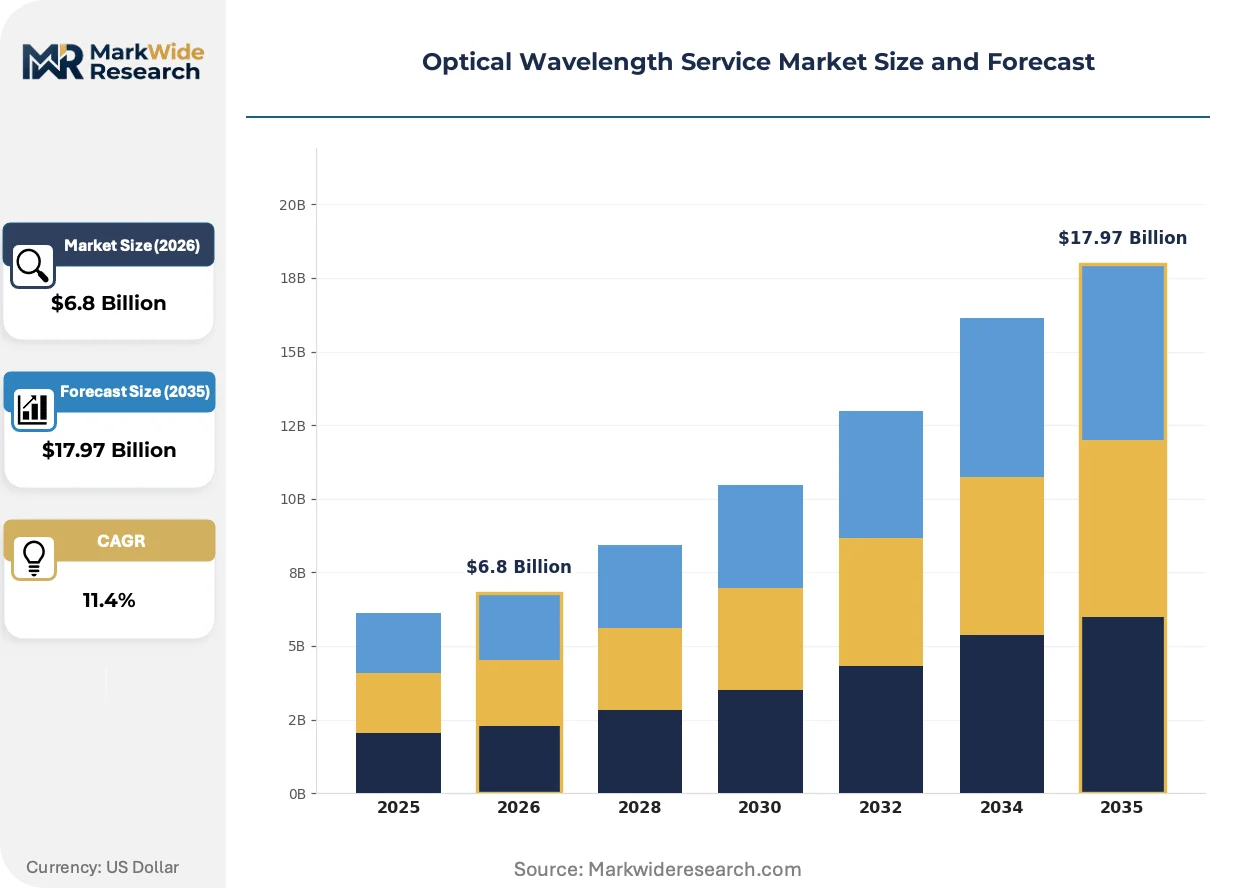
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Wavelength, Shared Wavelength, Managed Wavelength, Dark Fiber End User: Telecom Providers, Internet Service Providers, Enterprises, Government Agencies Application: Data Center Connectivity, Cloud Services, Disaster Recovery, Network Expansion Technology: DWDM, CWDM, SDH/SONET, Ethernet |
| Companies Covered | AT&T, Colt Technology Services Group Limited, Lumen Technologies, Nokia Corporation, Comcast Corporation, Zayo Group, Crown Castle, Windstream, Verizon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Wavelength Service Market Strategic Shifts & Innovations
Silicon photonics and programmable optical layer software are collapsing the traditional boundary between transport hardware and network intelligence. These developments are enabling disaggregated procurement models where wavelength buyers mix component vendors and management platforms.
Coherent pluggable optics operating at 400G and 800G per lambda is converging with open line system architectures from Ciena, Infinera, and Cisco. Cloud operators in Ashburn, Amsterdam, and Singapore are deploying these transceivers in router-facing configurations, eliminating standalone transponder shelves. This convergence is compressing equipment vendor addressable market while expanding the role of systems integrators and optical software orchestration layers.
The EU AI Act's risk-based classification system is mandating audit trails for data transmission paths used in high-risk artificial intelligence applications. Financial services and healthcare wavelength buyers in France, Germany, and the Netherlands must now document physical route diversity and latency consistency. Compliance teams are inserting contractual clauses requiring carriers to certify path engineering and failover procedures, adding operational overhead but creating premium service tiers.
Enterprise procurement of wavelength services is fragmenting from national carrier monopolies toward specialized metro fiber operators and cable landing station consortia. Large manufacturing firms in Japan's Aichi Prefecture and Germany's Baden-Württemberg are contracting directly with submarine cable landing parties for transpacific capacity, bypassing incumbent integrated carriers. This disintermediation is most pronounced in automotive and semiconductor verticals where supply chain latency requirements exceed standard carrier SLA frameworks.
Optical Wavelength Service Market Segmentation
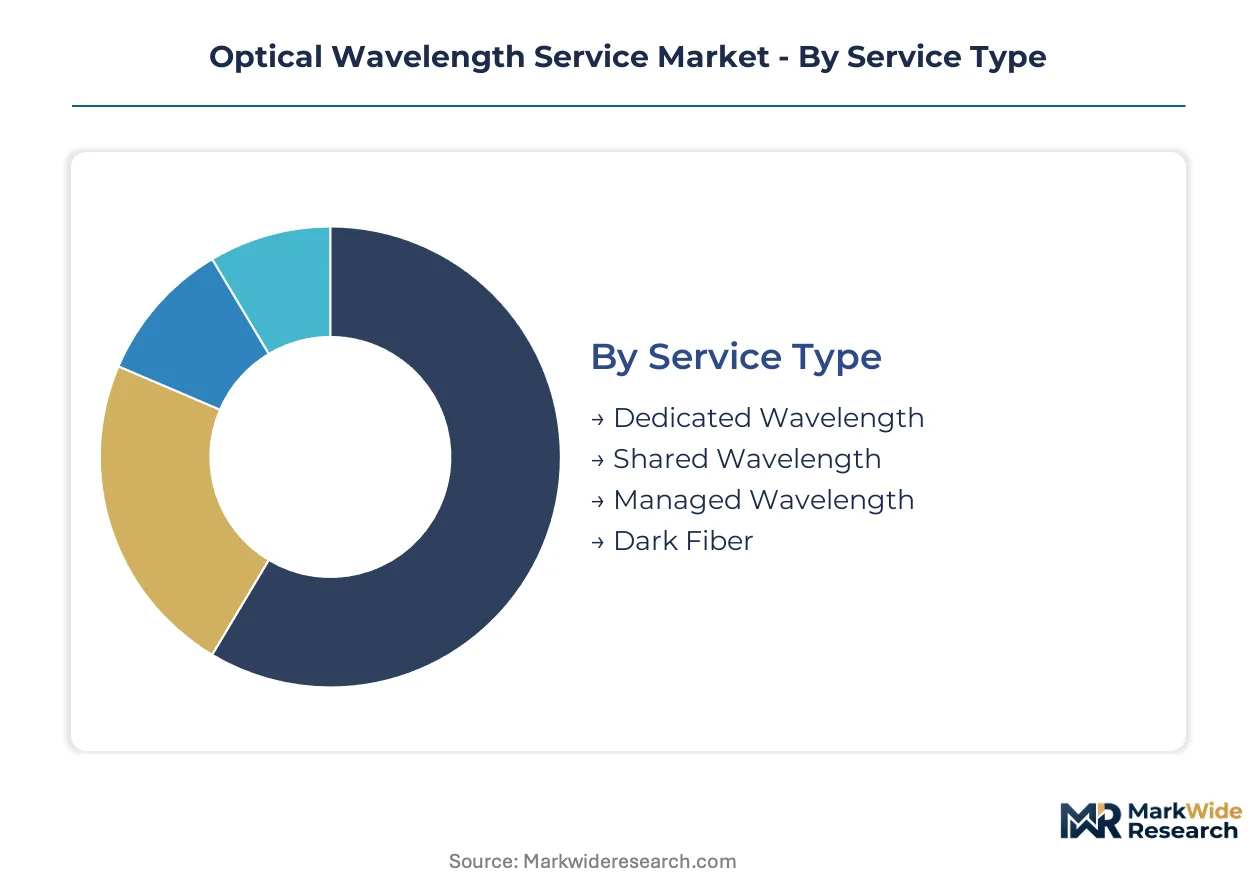
Optical wavelength service segmentation reveals how buyers balance control against operational burden. Procurement patterns diverge sharply between carriers seeking raw spectrum and enterprises demanding managed outcomes. Understanding these trade-offs explains margin distribution across the value chain.
Service Type:
Dedicated wavelengths operate as standalone infrastructure commitments, while managed and shared variants embed operational layers that alter buyer risk profiles.
- Dedicated Wavelength:Uncontended spectrum channels provisioned exclusively for a single tenant, typically at 10 Gbps to 400 Gbps per lambda using DWDM multiplexing. Financial exchanges in Frankfurt and cloud operators in Northern Virginia pay substantial premiums for deterministic latency and physical route control. Supply constraints around erbium-doped fiber amplifiers limit rapid scaling of this tier.
- Managed Wavelength:Carrier-operated optical layer services where the provider assumes monitoring, maintenance, and restoration responsibilities. Germany's Mittelstand manufacturers are migrating to this model to avoid coherent DSP engineering talent scarcity. Outsourcing demand concentrates where internal optical expertise has atrophied.
- Shared Wavelength:Statistical multiplexing of multiple tenants across common spectrum, reducing per-gigabit cost through contention. Regional ISPs in Japan leverage shared infrastructure for 5G backhaul aggregation where latency tolerances permit statistical sharing.
- Dark Fiber:Unlit physical fiber pairs sold on long-term IRU or lease arrangements, placing full operational burden on the lessee. Research networks and hyperscale cloud operators in Amsterdam and Singapore favor this option for maximum protocol flexibility.
Dedicated wavelength leads volumes today; managed wavelength is gaining share fastest.
End User:
Customer type determines whether procurement emphasizes wholesale arbitrage or internal consumption economics.
- Telecom Providers:Incumbent and competitive carriers acquiring spectrum for resale or network augmentation. These buyers dominate transatlantic and transpacific cable landing station capacity in Bude, Bilbao, and Shima.
- Internet Service Providers:Regional and national ISPs sourcing backhaul for broadband and mobile networks. India's BharatNet Phase III program is channeling substantial wavelength demand through this segment for rural fiber expansion.
- Enterprises:Large corporations with private network requirements spanning manufacturing, financial services, and healthcare. Automotive and semiconductor firms in Aichi Prefecture and Baden-Württemberg are contracting directly with cable landing parties, disintermediating traditional carriers.
- Government Agencies:Public sector entities procuring secure connectivity for administrative and defense applications. EU member state tenders under the Green Deal procurement framework now mandate energy efficiency per gigabit-kilometer.
Telecom providers anchor current demand; enterprise direct procurement shows the steepest expansion trajectory.
Application:
Use case segmentation tracks how latency sensitivity and resilience requirements map to service tier selection.
- Data Center Connectivity:Inter-facility links supporting AI training clusters and distributed compute fabrics. Hyperscale operators in Ashburn, Frankfurt, and Tokyo require sub-millisecond latency for GPU farm synchronization.
- Cloud Services:Connectivity enabling multi-cloud and hybrid cloud architectures for enterprise customers. Swiss and South Korean financial institutions are integrating quantum key distribution channels with standard DWDM for cloud access security.
- Disaster Recovery:Geographically diverse paths ensuring business continuity for critical systems. EU AI Act compliance now mandates documented physical route diversity for high-risk AI application data transmission.
- Network Expansion:Greenfield capacity additions for growing subscriber bases or geographic extension. Submarine cable landings in Cornwall, Spain, and Japan are creating terrestrial backhaul aggregation points for this application.
Data center connectivity commands the largest revenue pool; cloud services integration is expanding most quickly.
Technology:
Transport protocol selection reflects the tension between spectral efficiency and legacy interoperability.
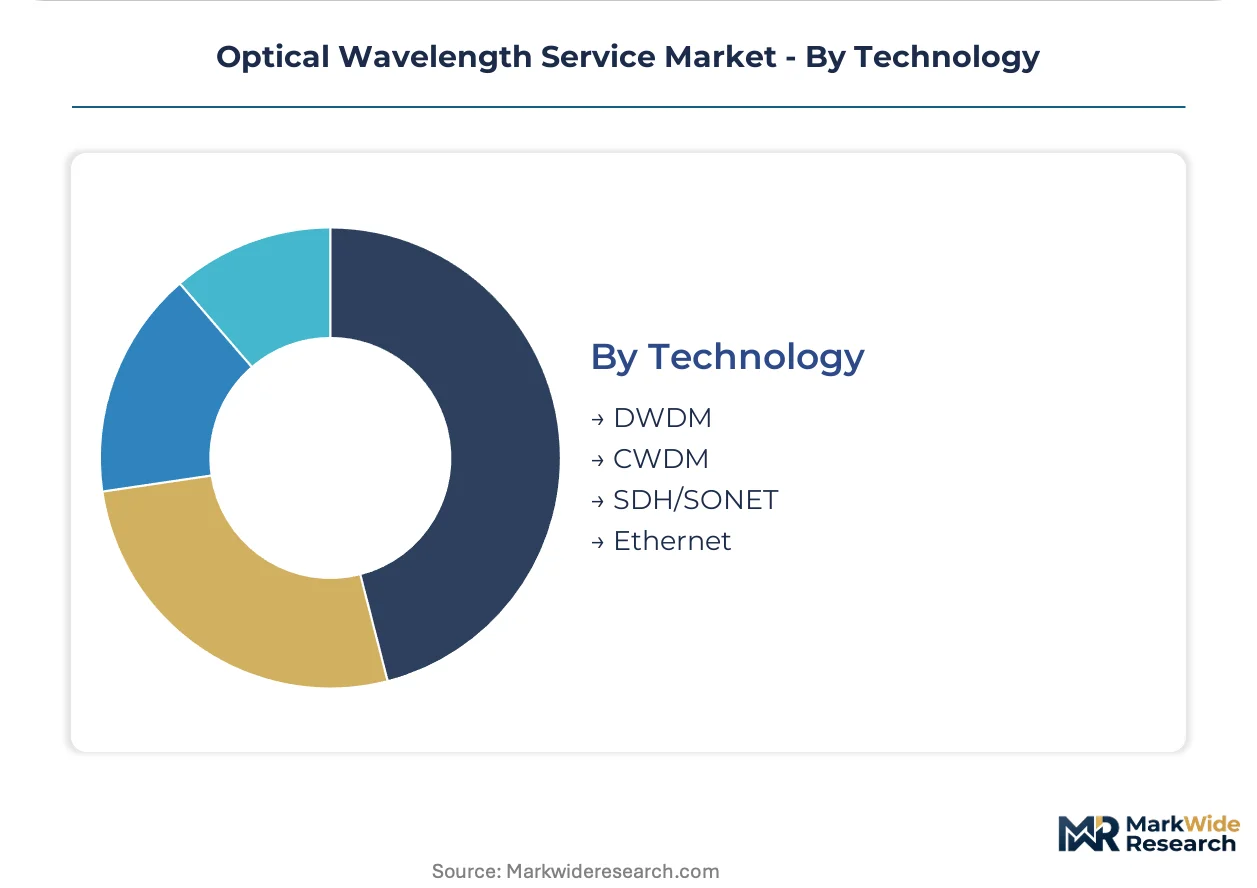
- DWDM:Dense wavelength division multiplexing supporting 40+ channels per fiber at 100 GHz or 50 GHz spacing. Coherent pluggable optics at 400G and 800G per lambda are converging with open line systems from major equipment vendors.
- CWDM:Coarse wavelength division multiplexing with wider 20 nm channel spacing for shorter-reach, cost-sensitive applications. Metro edge deployments favor this technology where fiber scarcity is less acute.
- SDH/SONET:Legacy synchronous optical networking protocols maintained for financial and government interconnections. Japanese and German institutions retain these interfaces, complicating transparent wavelength provisioning.
- Ethernet:Packet-native transport eliminating TDM conversion overhead for IP-centric traffic. IP-over-DWDM routers with integrated coherent optics threaten standalone wavelength margins in metro applications.
DWDM dominates deployed capacity; Ethernet-facing coherent pluggables are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The optical wavelength service industry traces its commercial origins to AT&T's deployment of dense wavelength division multiplexing across transcontinental fiber routes in the United States during the late 1990s, establishing the technical and pricing templates that European and Asian markets later adapted.
United States
Hyperscale cloud operators in Northern Virginia and the Pacific Northwest are leasing dedicated 400G wavelengths to interconnect AI training clusters with sub-millisecond latency requirements. FCC open-access rules under Section 224 continue to shape competitive access to incumbent fiber ducts and conduit infrastructure. The Ashburn-Loudoun County corridor hosts the densest concentration of wavelength aggregation points for transatlantic submarine cable landings.
Germany
Manufacturing enterprises in Baden-Württemberg's automotive and semiconductor sectors are contracting directly with cable landing parties for transpacific capacity, bypassing traditional carrier intermediaries. EU Green Deal procurement mandates now weight energy efficiency per gigabit-kilometer in member state network infrastructure tenders. Frankfurt's data center cluster drives continental demand for low-latency wavelength services connecting GPU farms across the Rhine-Main metropolitan region.
Japan
Financial institutions in Tokyo and Osaka maintain legacy SONET interconnections that complicate transparent wavelength provisioning for newer coherent optical systems. METI spectrum coordination policies govern 5G backhaul wavelength allocation alongside fixed fiber infrastructure planning. The Shima submarine cable landing station anchors transpacific capacity aggregation for terrestrial backhaul into the Chubu and Kansai industrial corridors.
United Kingdom
Research networks and hyperscale operators in the Slough-London corridor favor dark fiber arrangements for maximum protocol flexibility in high-performance computing interconnections. Ofcom's wholesale unbundling frameworks under the Electronic Communications Code shape competitive access to BT's fiber infrastructure. The Bude cable landing station in Cornwall serves as a critical wavelength aggregation point for transatlantic systems terminating on England's southwestern coast.
Singapore
Cloud operators are deploying 400G and 800G coherent pluggable optics in router-facing configurations, eliminating standalone transponder shelves and compressing equipment vendor addressable markets. The Infocomm Media Development Authority's submarine cable landing policies facilitate competitive access to terrestrial backhaul from cable landing stations. The Tuas and Changi cable landing zones concentrate wavelength demand for transpacific and intra-Asian capacity distribution.
Optical Wavelength Service Market Key Industry Players
Premium-margin players sit above commodity-margin players across spectrum exclusivity and operational control dimensions, with uncontended dedicated wavelengths commanding substantial pricing power over statistically multiplexed alternatives. The vendor base organizes into three tiers: integrated carriers with submarine cable ownership, specialized metro fiber operators, and systems integrators orchestrating multi-vendor optical layers. Consolidation pressures concentrate among equipment suppliers facing margin compression from open optical standards, while service providers pursue geographic expansion through cable landing station partnerships and strategic outsourcing arrangements with hyperscale cloud operators.
Within the integrated carrier tier, AT&T and Lumen Technologies occupy positions that exemplify divergent strategic emphases on enterprise retail versus wholesale infrastructure. Zayo Group represents the specialized metro fiber operator archetype with dense route networks in North American data center corridors. Nokia Corporation anchors the equipment supplier segment with photonic chipset differentiation addressing EU Green Deal energy efficiency mandates.
| Leading Market Players |
|---|
| AT&T |
| Colt Technology Services Group Limited |
| Lumen Technologies |
| Nokia Corporation |
| Comcast Corporation |
| Zayo Group |
| Crown Castle |
| Windstream |
| Verizon |
| Others |
Cost & Logistics Intelligence
Captive vertical integration into erbium-doped fiber amplifier manufacturing anchors both supply security and pricing power for wavelength providers serving hyperscale cloud operators in Northern Virginia and Frankfurt. This integration choice insulates incumbents from rare earth price volatility while compressing margins for competitors forced into spot-market component procurement.
Pricing Analysis
Three-tier pricing structure across dedicated, managed, and shared wavelength levels separates uncontended spectrum premiums from statistical multiplexing discounts. Price differentiation rests on latency guarantees and physical route certification, with financial exchanges in Frankfurt paying substantial premiums for deterministic performance. Cost compression in shared wavelength tiers is intensifying because IP-over-DWDM routers threaten standalone service margins. Regional ISPs in Japan exhibit highest price sensitivity, while AI training cluster operators in Ashburn show least sensitivity to per-lambda rates.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale buyers mandate multi-supplier qualification for coherent DSP chipsets and optical transceivers. Manufacturing concentrates in the United States, Japan, and Taiwan for photonic components and silicon photonics foundry capacity. Raw material dependencies include high-purity erbium, indium phosphide substrates, and specialized optical coatings. Single-source vulnerability around erbium-doped fiber amplifiers exposes providers to supply disruption. Distribution runs through submarine cable landing station consortia and metro fiber operators for terrestrial backhaul aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC open-access rule uncertainty in the United States versus EU wholesale unbundling certainty under the Electronic Communications Code creates a geographic-arbitrage window for capital deployment toward European wavelength infrastructure.
For Market Incumbents: Cement submarine cable landing station partnerships in Bude, Bilbao, and Shima to defend against disintermediation by enterprises contracting directly with cable consortia. Invest in coherent DSP engineering talent retention as open optical standards from OIF and TIP commoditize hardware margins. Prioritize backward integration into photonic chipset production to meet EU Green Deal energy efficiency mandates. For New Entrants and Emerging Players: BharatNet Phase III in India opens a window for wavelength-grade backhaul provision from district headquarters to rural aggregation points. Target Germany's Mittelstand manufacturing sector with managed wavelength outsourcing services where internal optical expertise has atrophied. Pursue quantum key distribution integration for financial services in Switzerland and South Korea as a differentiated security layer. For Investors and Strategic Acquirers: Roll-up economics work for specialized metro fiber operators because route density in data center corridors commands persistent scarcity premiums. Platform consolidation across North American and European metro networks offers long-term viability through captive demand from AI training cluster expansion. Watch FCC determinations on fiber unbundling obligations as the inflection signal for competitive entrant capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Open Line System Deployment | Enables interoperability between Ciena, Infinera, and Cisco equipment per OIF 400ZR specifications. |
| Coherent Pluggable Optics Integration | Eliminates standalone transponder shelves for cloud operators in Amsterdam and Singapore. |
| Submarine Cable Landing Partnership | Secures terrestrial backhaul aggregation rights at Bude, Bilbao, and Shima termination points. |
| Managed Wavelength Service Launch | Captures Mittelstand outsourcing demand where optical engineering talent scarcity persists. |
| Silicon Photonics Manufacturing Scale-Up | Addresses EU Green Deal procurement mandates weighting energy efficiency per gigabit-kilometer. |
Research Approach
Multiple input streams — structured interviews with network engineering executives, procurement officers at hyperscale cloud operators, submarine cable system planners, and optical equipment vendor product managers — were reconciled against secondary validation from FCC filings, EU Electronic Communications Code implementation reports, METI spectrum coordination documents, and hyperscaler capital expenditure disclosures. Bottom-up wavelength demand modeling across data center corridors triangulated with top-down market sizing from submarine cable capacity announcements.
Data-stream reconciliation across service type, end user category, application use case, and transport technology dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves incorporating AI training cluster expansion rates, EU Green Deal procurement adoption timelines, and open optical standards penetration assumptions. Industry-specific forecast inputs included erbium-doped fiber amplifier supply constraints and coherent pluggable optics deployment trajectories.
Revisions become necessary when FCC open-access rule determinations, EU AI Act transmission path audit requirements, or rare earth supply disruptions materialize. Deviation in submarine cable landing station access policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Smart Photochromic Lenses Market
Optics
Electro Optics Market
Optics
Advanced Optics Market
Optics
3D Optical Microscope Market
Optics
Tunable Laser Market
Optics
Global Optical Lens Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Fiber Optic Development Tools Market
Optics
Optical Measuring Systems Market
Optics
US Photonics Market
Optics
Photonics Market
Optics
Optical Liquid Level Sensor Market
Optics
India Laser Market
Optics
Optical Gratings Market
Optics
Excimer Laser Market
Optics
Europe Smart Glass Market