
 Micro and Nano PLC Market | 2026-2036
Micro and Nano PLC Market Size, Share, and Industry Trends Forecast 2026-2036
Micro and Nano PLC Market Intelligence
Increased semiconductor fabrication capacity in Asia is rebalancing the component supply chain for PLC manufacturers. This shift benefits firms like Mitsubishi Electric Corporation, which specializes in compact controllers for electronics manufacturing. Siemens AG leverages its extensive TIA Portal ecosystem for integrated engineering. Rockwell Automation sustains its market position through its established distribution channels and brand loyalty in North America.
A micro or nano PLC is a compact, solid-state control device designed for discrete automation tasks. These controllers typically manage a limited number of I/O points, often under 32, executing user-programmed logic to control machinery. In terms of applications, packaging automation shows significant momentum, demanding high-speed, compact control solutions. Micro PLCs constitute the largest product type segment, serving a wide array of OEM machinery builders who are the primary end users.
Compliance with international standards such as IEC 61131-3 for programming languages dictates product interoperability. In Europe, CE marking and RoHS directives govern market access by setting safety and material composition requirements. For U.S. industrial applications, UL 508 certification is a common prerequisite. The key strategic question for vendors involves allocating resources between supporting established fieldbus protocols and integrating next-generation wireless communication technologies.
Market Dynamics
The convergence of operational technology (OT) with information technology (IT) networks is the central force defining the market. This integration demands that compact controllers evolve from isolated logic devices into accessible, data-rich nodes within a larger factory automation architecture.
Growth Catalysts
- Factory Modernization:National manufacturing initiatives in countries like China and India incentivize the adoption of automated systems, boosting demand for compact controllers in new machinery and retrofits for small to medium enterprises.
- Packaging Automation:The consumer goods and pharmaceutical sectors require high-speed, precise, and small-footprint machinery for packaging, creating consistent demand for nano PLCs capable of executing rapid, repetitive tasks.
- Wireless Integration:The incorporation of Wi-Fi and 5G capabilities into micro PLCs enables real-time monitoring and remote diagnostics, opening up applications in logistics and distributed control systems where cabling is impractical.
Market Restraints
- Component Cost Volatility:The reliance on a concentrated supply chain for specialized microcontrollers and memory chips creates price sensitivity and potential production bottlenecks for PLC manufacturers, impacting final product cost.
- Technical I/O Limitations:The inherent design of micro and nano PLCs, typically with fewer than 32 I/O points, makes them unsuitable for complex, centralized control applications that require extensive input and output management.
- Substitution from IPCs:For applications demanding advanced data processing or graphical interfaces, powerful and increasingly compact Industrial PCs (IPCs) present a viable alternative, challenging the position of high-end micro PLCs.
Strategic Opportunities
- Edge Computing Integration:Embedding lightweight AI and machine learning algorithms directly into micro PLCs for edge-based predictive maintenance and process optimization creates a new value proposition beyond simple logic control.
- Building Automation Systems:Untapped demand exists in commercial buildings for localized control of HVAC, lighting, and access systems, where nano PLCs offer a cost-effective solution compared to traditional, more complex building management systems.
- Renewable Energy:Micro PLCs can be deployed for localized control and monitoring tasks within distributed energy resources like solar farms and battery storage systems, managing individual strings or units.
Industry Challenges
- Cybersecurity Vulnerabilities:As PLCs become more connected, securing them against cyber threats without compromising real-time performance is a significant technical and operational challenge, requiring new design paradigms.
- Legacy System Integration:Ensuring backward compatibility and seamless data exchange between modern, Ethernet-based micro PLCs and the vast installed base of older equipment running on serial fieldbus protocols is a major integration hurdle for end users.
- Programming Skill Gaps:The workforce transition from traditional IEC 61131-3 ladder logic to structured text and IT-oriented languages required for advanced IIoT functions creates a persistent talent shortage for system integrators and plant operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro and Nano PLC Market |
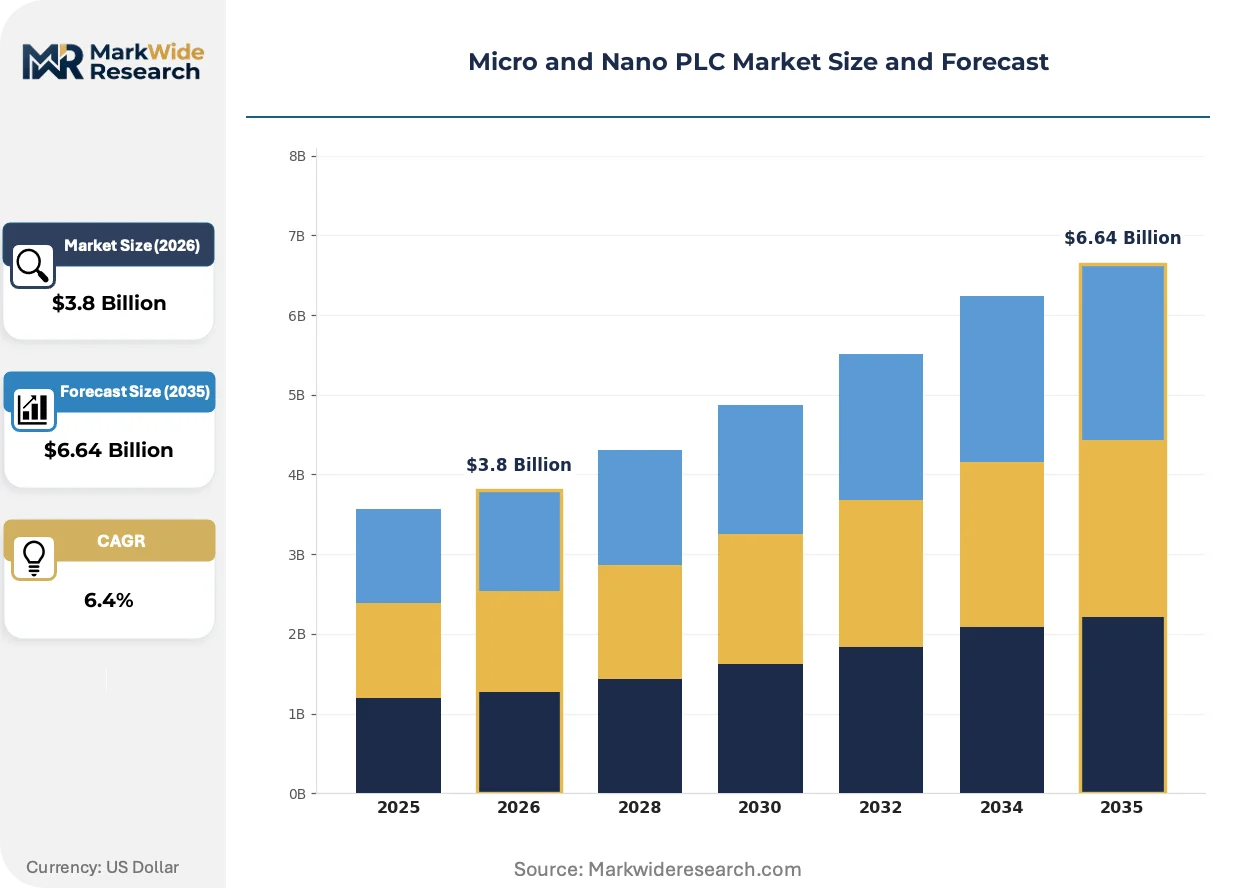
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro PLCs, Nano PLCs, Compact PLCs, Modular PLCs Technology: Digital I/O, Analog I/O, Mixed Signal, Wireless Communication Application: Process Automation, Building Automation, Packaging Automation, Automotive Manufacturing End User: OEMs, Machinery Suppliers, System Integrators, Facility Management Companies |
| Companies Covered | Siemens AG, Rockwell Automation, Mitsubishi Electric Corporation, Schneider Electric, ABB, Omron Corporation, IDEC Corporation, Bosch Rexroth AG, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro and Nano PLC Market Strategic Shifts & Innovations
The evolution of micro and nano PLCs is marked by their transformation from standalone logic solvers into intelligent, networked components. This shift is driven by a need for greater data visibility and interoperability within modern industrial environments, fundamentally changing their role on the factory floor.
A key technological development is the native integration of OPC UA (Open Platform Communications Unified Architecture) into controller firmware. Machine builders in the automotive and food and beverage sectors are rapidly adopting this standard for its vendor-neutral communication capabilities. The adoption of OPC UA is unifying disparate automation islands on the factory floor, allowing PLCs, robots, and enterprise systems to exchange data seamlessly using a common information model.
Regulatory frameworks are increasingly focused on the digital security of industrial components. The European Union’s Cyber Resilience Act (CRA) mandates specific cybersecurity features and vulnerability management processes for all products with digital elements sold in the region. This regulation is forcing PLC manufacturers to embed security-by-design principles into their product development cycles, particularly affecting network-enabled micro and nano controllers.
Customer purchasing behavior is moving away from discrete component selection toward adoption of integrated automation platforms. System integrators are choosing vendors based on the strength of their unified engineering software, which combines PLC programming, HMI design, and motion control into a single environment. This trend is most pronounced in Germany and the United States, where complex machine design benefits from a cohesive development ecosystem.
Micro and Nano PLC Market Segmentation
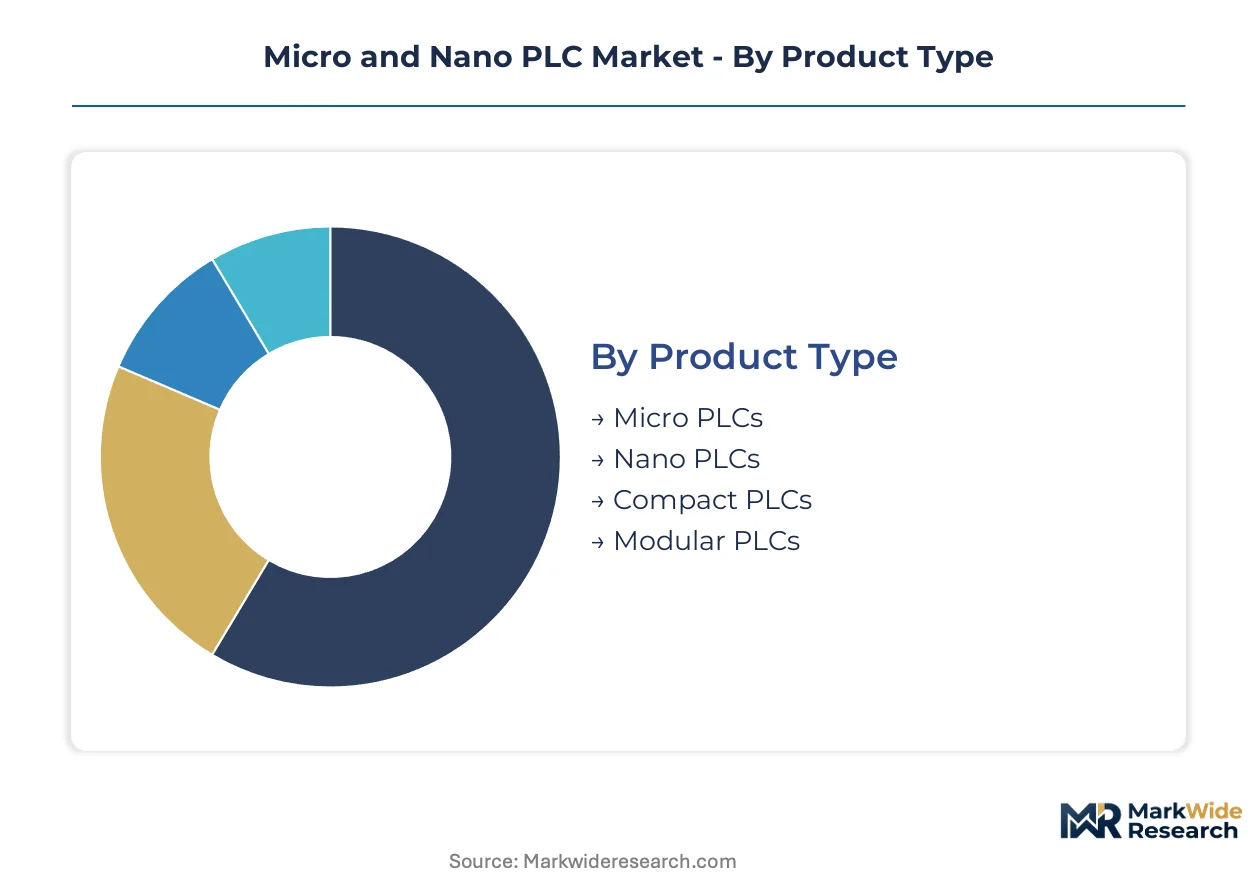
The Micro and Nano PLC market segmentation provides a granular view of product types, underlying technologies, diverse applications, and distinct end-user categories. Understanding these segments is crucial for vendors to tailor product development and market strategies, addressing specific demands within industrial automation.
Product Type:
Buyers in the Micro and Nano PLC market differentiate their product type choices based on the complexity and scale of the automation task, along with physical space constraints.
- Micro PLCs:These compact controllers manage a limited number of I/O points, typically under 32, and execute user-programmed logic for discrete automation tasks. Demand concentrates in OEM machinery for electronics manufacturing, driven by the need for reliable, cost-effective control solutions.
- Nano PLCs:Characterized by an even smaller footprint and fewer I/O points than micro PLCs, nano PLCs are designed for highly localized control of simple, repetitive functions. Packaging automation shows significant momentum for these devices, requiring high-speed, precise control within minimal space.
- Compact PLCs:These integrated units combine the CPU, power supply, and I/O into a single enclosure, offering a balance of capability and simplicity for small to medium-scale automation.
- Modular PLCs:Comprising a central processing unit and various plug-in I/O modules, modular PLCs offer flexibility and expandability for more complex systems requiring future upgrades.
Micro PLCs lead volumes today; Nano PLCs are gaining share fastest.
Technology:
The choice of technology in compact controllers primarily impacts the specific application requirements, from basic discrete control to advanced data exchange capabilities.
- Wireless Communication:This technology integrates Wi-Fi and 5G capabilities directly into micro PLCs, enabling real-time monitoring and remote diagnostics. Logistics and distributed control systems utilize this for applications where traditional cabling is impractical or costly.
- Digital I/O:These are discrete inputs and outputs that handle binary signals (on/off states), forming the foundational control mechanism for most automation tasks. Factory modernization initiatives across China and India rely on robust digital I/O for machine control.
- Analog I/O:Analog inputs and outputs process continuous signals, such as temperature, pressure, or flow, enabling PLCs to monitor and control process variables with fine granularity.
- Mixed Signal:This technology combines both digital and analog I/O capabilities within a single controller, offering versatility for applications requiring both discrete and continuous process control.
The market sees Digital I/O as foundational, while Wireless Communication drives future innovation.
Application:
Customer types dictate application emphasis, with distinct needs for speed, precision, and data integration across various industrial processes.
- Packaging Automation:This application demands high-speed, precise, and small-footprint machinery for consumer goods and pharmaceutical sectors. Nano PLCs are essential for executing rapid, repetitive tasks in these environments.
- Process Automation:Micro and nano PLCs are deployed for controlling continuous processes, such as fluid handling, temperature regulation, or chemical mixing, often in smaller-scale operations. The chemical industry and water treatment facilities utilize these for localized control.
- Building Automation:Untapped demand exists in commercial buildings for localized control of HVAC, lighting, and access systems. Nano PLCs offer a cost-effective solution compared to traditional, more complex building management systems.
- Automotive Manufacturing:These controllers manage specific tasks on production lines, such as robotic cell control, part assembly, or quality inspection, contributing to overall factory efficiency.
Packaging Automation represents significant installed capacity, with Building Automation showing strong expansion.
End User:
End-user decisions are often driven by the volume and scope of their automation projects, influencing the scale and integration level of PLC deployments.
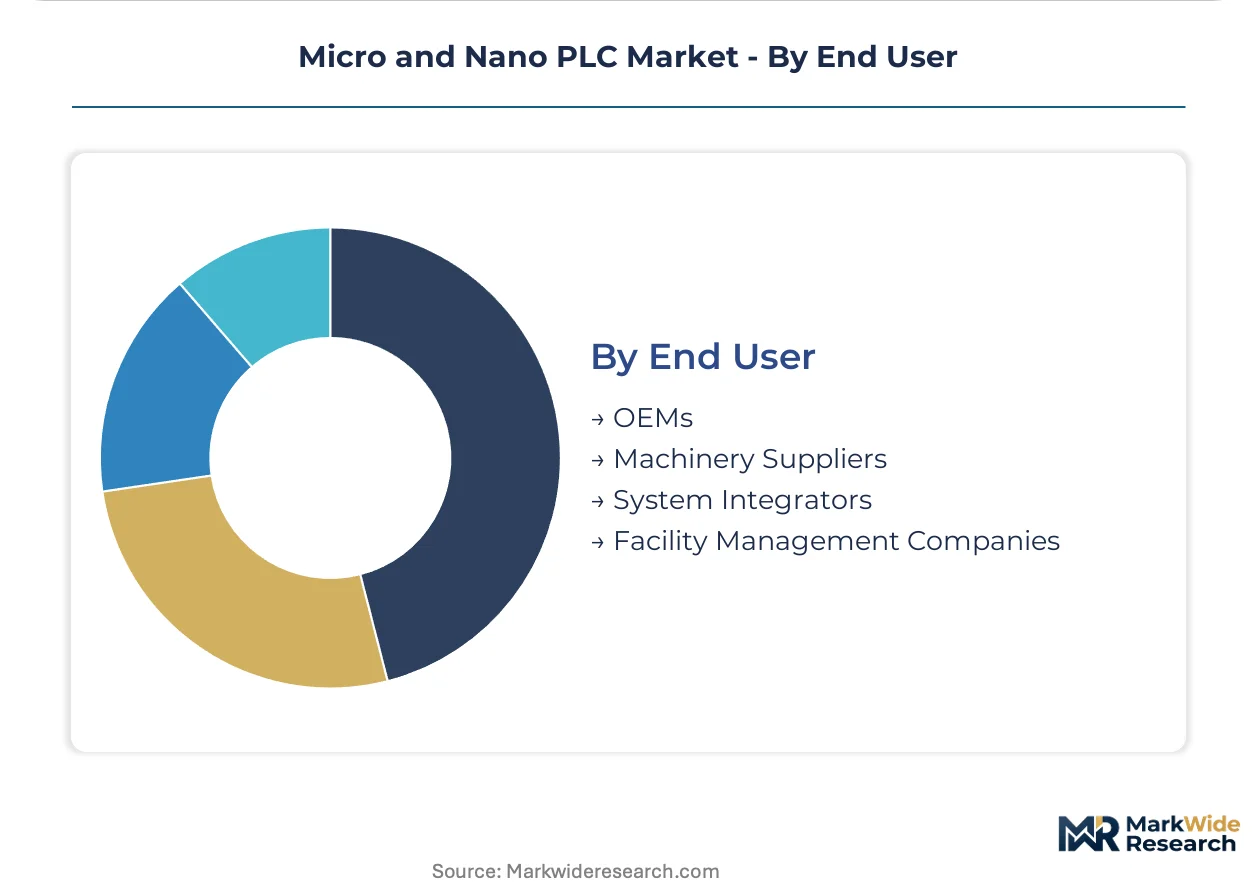
- OEMs:Original Equipment Manufacturers integrate micro and nano PLCs directly into the machinery they build, serving as the primary end users of these compact control devices. They seek reliable, compact, and easily programmable solutions for their equipment.
- System Integrators:These firms design, install, and commission complete automation systems for various industries, often selecting PLCs based on their interoperability and integration capabilities within a larger architecture. Rockwell Automation supports these integrators with its extensive ecosystem.
- Machinery Suppliers:Companies that provide individual machines or components to factories often bundle micro PLCs as part of their offerings, simplifying the control aspect for their customers.
- Facility Management Companies:These entities utilize micro PLCs for controlling building infrastructure, including HVAC, lighting, and security systems, optimizing operational efficiency and energy consumption.
Demand from OEMs is consistent, but System Integrators are expanding their market influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China's manufacturing sector drives significant demand for Micro and Nano PLCs, the United States also shows strong market activity, particularly in advanced automation and industrial IoT integration. These distinct regional dynamics reflect varied industrial priorities and regulatory landscapes influencing adoption rates.
China
Factory modernization initiatives and the expansion of advanced manufacturing hubs propel demand for compact controllers in China. The "Made in China 2025" policy incentivizes automation across various industries, boosting PLC deployment. Major industrial clusters in the Yangtze River Delta and Pearl River Delta actively integrate Micro and Nano PLCs into new machinery and retrofit existing production lines.
United States
Demand for Micro and Nano PLCs in the United States stems from packaging automation and the growing need for localized control in smart factories. UL 508 certification remains a common prerequisite for industrial applications, ensuring product safety and compliance. Technology clusters in California and the Midwest are adopting these controllers for their flexibility in discrete manufacturing and process optimization.
Germany
Germany's robust engineering sector and emphasis on Industry 4.0 drive the adoption of sophisticated Micro and Nano PLCs. CE marking and RoHS directives govern market access, ensuring products meet stringent safety and environmental standards. Industrial regions like Bavaria and Baden-Württemberg utilize compact PLCs extensively in specialized machinery and integrated automation systems.
Japan
The Japanese market for Micro and Nano PLCs is characterized by high precision manufacturing and a focus on energy efficiency in industrial applications. Compliance with JIS standards is essential for market entry and product acceptance across various sectors. Manufacturers in the Kanto region, particularly around Tokyo, implement these controllers for robotic cell control and compact equipment automation.
India
India's push for manufacturing growth, supported by the "Make in India" initiative, stimulates demand for cost-effective Micro and Nano PLCs in small to medium enterprises. Regulatory bodies like BIS set quality and safety standards for industrial components, influencing procurement decisions. Industrial corridors in Maharashtra and Gujarat are rapidly deploying compact automation solutions for various production processes.
Micro and Nano PLC Market Key Industry Players
German producers anchor one tier, emphasizing integrated engineering ecosystems, while Japanese specialists hold a strong position in compact and high-precision controllers. The market structure exhibits a tiered consolidation, with a few large global players alongside numerous regional and niche providers. Dominant competitive moves include strategic partnerships to expand ecosystem reach and continuous product portfolio diversification to address evolving application needs.
Among established industrial automation providers, Siemens AG and Rockwell Automation exemplify comprehensive ecosystem strategies, offering integrated software platforms and extensive distribution channels. Mitsubishi Electric Corporation, a Japan-based industrial electronics giant, occupies a strong position in the compact controller segment, particularly for electronics manufacturing applications. These companies represent archetypes of broad-portfolio automation leaders, leveraging their brand recognition and technological breadth to maintain market influence across diverse end-user industries.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation |
| Mitsubishi Electric Corporation |
| Schneider Electric |
| ABB |
| Omron Corporation |
| IDEC Corporation |
| Bosch Rexroth AG |
| General Electric |
| Others |
Cost & Logistics Intelligence
The **Semiconductor Manufacturing Cost Index** directly impacts the bill of materials for specialized microcontrollers and memory chips, which cascades into the tiered pricing structures for Micro and Nano PLCs. This cost volatility creates pressure points throughout the supply chain, influencing vendor margins and end-user procurement strategies.
Pricing Analysis
Distributor margins significantly influence the final pricing of Micro and Nano PLCs for smaller OEMs and end-users, affecting market accessibility. The dominant pricing structure is per-unit transactional, often with volume-based discounts for large OEM orders. Price differentiation stems from factors like UL 508 or CE certification levels and brand premium associated with established providers like Siemens AG. Pricing softness reflects intense competition from lower-cost regional manufacturers and the increasing capabilities of alternative solutions. OEMs are generally more price-sensitive, particularly for high-volume machinery, while system integrators prioritize integration capabilities and long-term support.
Supply Chain Analysis
Regional distribution centers in key industrial zones manage the flow of Micro and Nano PLCs to local markets, optimizing delivery times for OEMs. Geographic supply concentration for critical components like specialized microcontrollers and memory chips centers on Taiwan, South Korea, and China. The market relies on a concentrated supply chain for these complex semiconductor inputs. Component cost volatility represents a structural risk, creating potential production bottlenecks for PLC manufacturers. Distribution runs through a hybrid model, combining direct sales to large, strategic OEMs with extensive channel partnerships via distributors and system integrators for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Micro and Nano PLC market operates as a stable compounder, driven by continuous factory modernization initiatives across diverse manufacturing sectors.
For Market Incumbents:
Hedge against the threat of substitution from Industrial PCs by investing heavily in edge computing integration capabilities. Deepen vertical integration into software platforms, offering unified engineering environments to system integrators. Reinforce intellectual property around cybersecurity features within compact controllers, addressing the European Union’s Cyber Resilience Act. Expand strategic partnerships with cloud service providers to facilitate seamless data integration from the factory floor to enterprise systems.
For New Entrants and Emerging Players:
Online marketplaces specializing in industrial components offer a direct route for new entrants to reach a broad OEM customer base. Target underpenetrated segments like building automation systems, where nano PLCs provide cost-effective localized control. Focus on developing solutions with simplified programming interfaces and open standards like OPC UA to reduce integration barriers for small to medium enterprises. Offer flexible, wireless-enabled micro PLCs for distributed control applications in logistics and renewable energy, where cabling is impractical.
For Investors and Strategic Acquirers:
Consolidation pressure builds where vendor-neutral communication standards like OPC UA become universally adopted, favoring integrated platforms. The Micro and Nano PLC market offers long-term viability, given its foundational role in discrete automation and the ongoing IT/OT convergence. Acquisition targets should include niche providers specializing in secure wireless communication or lightweight edge AI capabilities. The signal to watch for inflection points is a significant increase in M&A activity for firms demonstrating robust cybersecurity IP or advanced software integration tools.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Expansion | Broadens market reach by offering specialized controllers for emerging applications like renewable energy. |
| Ecosystem Partnership | Enhances platform appeal by integrating with complementary software and hardware providers for comprehensive solutions. |
| Cybersecurity Enhancement | Addresses regulatory mandates and customer concerns regarding connected device vulnerabilities, particularly in Europe. |
| Regional Manufacturing Footprint | Mitigates supply chain risks and improves delivery times for key markets like China and the United States. |
| Software Platform Integration | Provides a unified engineering environment, simplifying development for system integrators and OEMs. |
Research Approach
Multiple input streams — primary interviews, technical literature, and regulatory filings — were reconciled to build a comprehensive view of the Micro and Nano PLC market. Interviews were conducted with OEM engineers, system integrators, plant operators, and PLC manufacturers' product managers across major industrial geographies. Secondary data sources included industry association reports, government manufacturing initiatives like "Made in China 2025," and technology standards bodies such as IEC and UL. This approach ensured a robust bottom-up and top-down triangulation of market data.
Historical market performance was cross-referenced against expert panel input to project future Micro and Nano PLC market trajectories over the projection horizon. The analytical framework modeled segmentation dimensions including product type (Micro PLCs, Nano PLCs), technology (wireless communication, digital I/O), application (packaging automation, building automation), end-user (OEMs, system integrators), and regional manufacturing output. Compound annual growth rates were derived from a multi-factor analysis considering industrial production indices and capital expenditure trends in target industries like consumer goods manufacturing and automotive production.
Geopolitical trade tensions, semiconductor supply chain disruptions, and evolving cybersecurity threats are the dominant revision risks for Micro and Nano PLC market forecasts. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability across the modeling period. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Photosensitive Semiconductor Device Market