
 Asia-Pacific MLCC Market | 2026-2036
Asia-Pacific MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific MLCC Market Insights
Japan is rewriting the competitive map of MLCC supply through sustained capital investment in high-layer-count manufacturing. Murata Manufacturing Co., Ltd. leverages proprietary thin-layer technology to dominate automotive-grade shipments across the region. Samsung Electro-Mechanics Co., Ltd. anchors South Korean supply security through captive vertical integration into ceramic powder and electrode materials. Taiyo Yuden Co., Ltd. specializes in ultra-compact designs for 5G smartphone RF modules, competing aggressively against Japanese and Korean rivals in the telecommunications segment.
Multi-layer ceramic capacitors are passive electronic components built from alternating layers of ceramic dielectric and metal electrodes, typically sintered at temperatures exceeding 1,200°C to achieve stable capacitance across temperature and voltage extremes. These components store and filter electrical energy in circuits where space constraints and reliability requirements preclude larger capacitor technologies. Automotive applications now lead value generation within the application segmentation, driven by electrified powertrains and advanced driver-assistance systems that demand AEC-Q200 qualified components. Thin and ultra-thin thickness categories capture the fastest expansion as device miniaturization in smartphones, wearables, and medical electronics forces component height reductions below 0.3 millimeters. Ceramic material formulations, particularly barium titanate-based Class 2 dielectrics, occupy the dominant volume share though margin pools concentrate in temperature-stable Class 1 formulations for precision timing and filtering circuits.
Japan's METI and South Korea's Ministry of Trade, Industry and Energy have each established semiconductor and passive component reshoring frameworks that condition subsidy access on domestic MLCC production expansion. China's SAMR enforces GB standards for electronic component reliability while MIIT directs industrial policy toward capacitor autonomy through its dual carbon and Made in China 2025 technology roadmaps. The region's fragmented regulatory landscape demands that procurement and compliance teams maintain parallel certification tracks across Japanese JIS, Korean KS, and Chinese GB testing protocols. Stakeholders must monitor how export control alignments between Tokyo, Seoul, and Taipei reshape cross-border material flows for nickel, palladium, and rare-earth dopants essential to high-performance dielectric formulations.
Market Dynamics
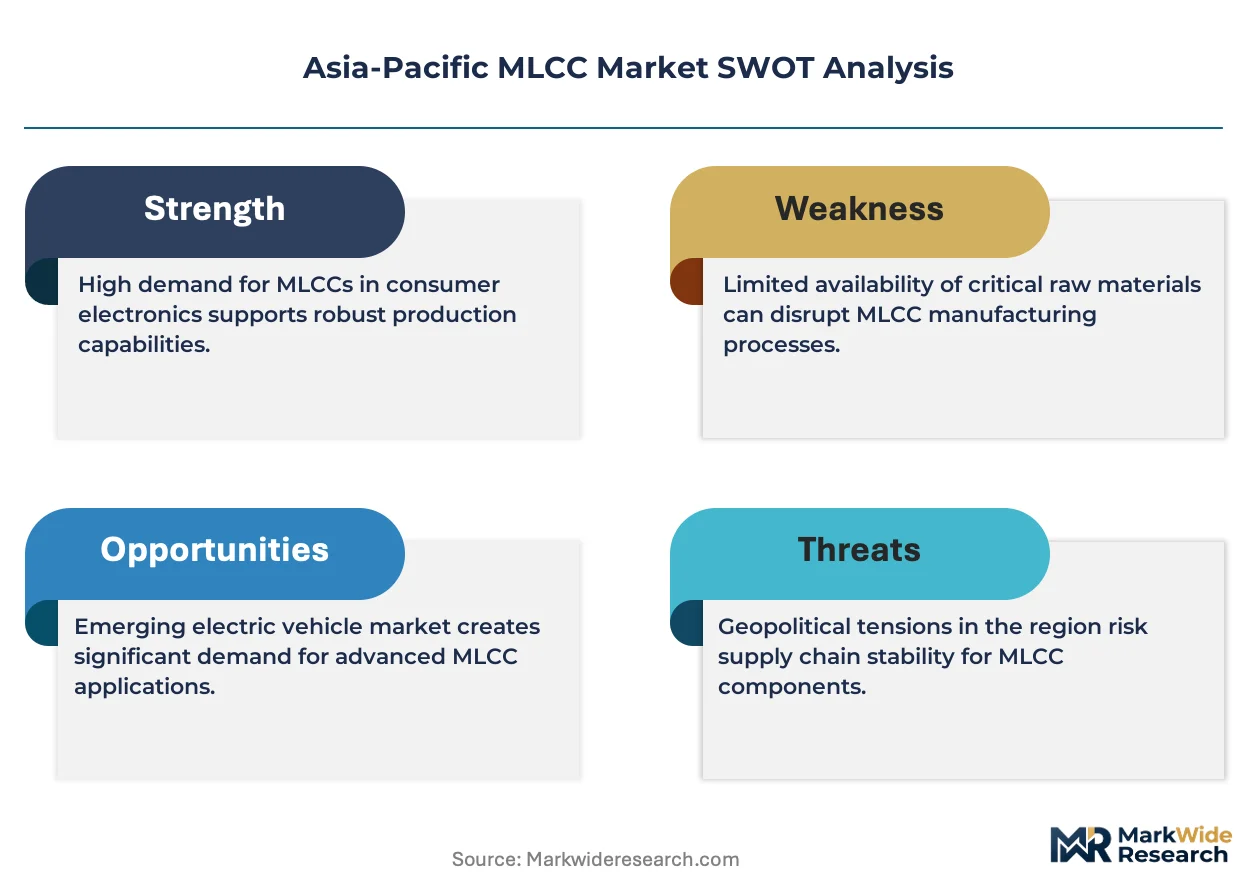
Automotive electrification across Japan, South Korea, and China is compressing MLCC specification cycles while simultaneously demanding AEC-Q200 qualification thresholds that only high-capacity manufacturers can meet. This demand surge from battery management systems and onboard chargers is restructuring supplier tier relationships across the region.
Growth Catalysts
- China's dual carbon goals:MIIT directives mandate capacitor autonomy through domestic capacity expansion, redirecting procurement toward local MLCC fabrication for EV powertrains and renewable energy inverters.
- 5G infrastructure densification:Base station deployments across South Korea and Japan consume high-frequency MLCC variants for RF filtering, with network operators specifying sub-millimeter thickness categories for compact antenna designs.
- Yangtze River Delta clustering:Tier-1 automotive suppliers co-locate with consumer electronics OEMs in this manufacturing corridor, creating consolidated procurement volumes that justify dedicated high-layer-count production lines.
Market Restraints
- Nickel and palladium volatility:Electrode material costs fluctuate with London Metal Exchange pricing, compressing margin pools for Class 2 dielectric formulations that depend on these base metals.
- Japanese supply concentration:Thin-layer technology leadership resides with a limited supplier base in Kyoto and Nagaokakyo industrial zones, creating single-source risk for automotive-grade shipments.
- Technical ceiling at sub-0.3mm:Ultra-thin thickness categories face mechanical yield constraints as layer counts exceed 500, limiting volume scalability for wearable and medical electronics applications.
Strategic Opportunities
- India's electronics manufacturing zones:PLI scheme incentives for semiconductor and passive component production create first-mover advantage for MLCC fabs serving domestic smartphone assembly and automotive wiring harness exports.
- Solid-state battery integration:Next-generation EV architectures require MLCCs with enhanced voltage ratings for 800V platforms, opening specification windows for temperature-stable Class 1 formulations in precision timing circuits.
- Cross-border material flow coordination:Taipei-Japan-Seoul alignment on rare-earth dopant export protocols could stabilize supply for high-performance barium titanate formulations.
Industry Challenges
- Multi-protocol certification burden:Suppliers must maintain parallel JIS, KS, and GB testing tracks for automotive and telecommunications segments, extending qualification timelines by 8-14 months.
- Sintering furnace capacity constraints:1,200°C+ production requires specialized thermal equipment with 24-36 month lead times, limiting rapid scale-up for emerging demand pockets.
- Thin-layer process IP fragmentation:Patent thickets around ceramic powder dispersion and electrode printing techniques complicate technology licensing for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific MLCC Market |
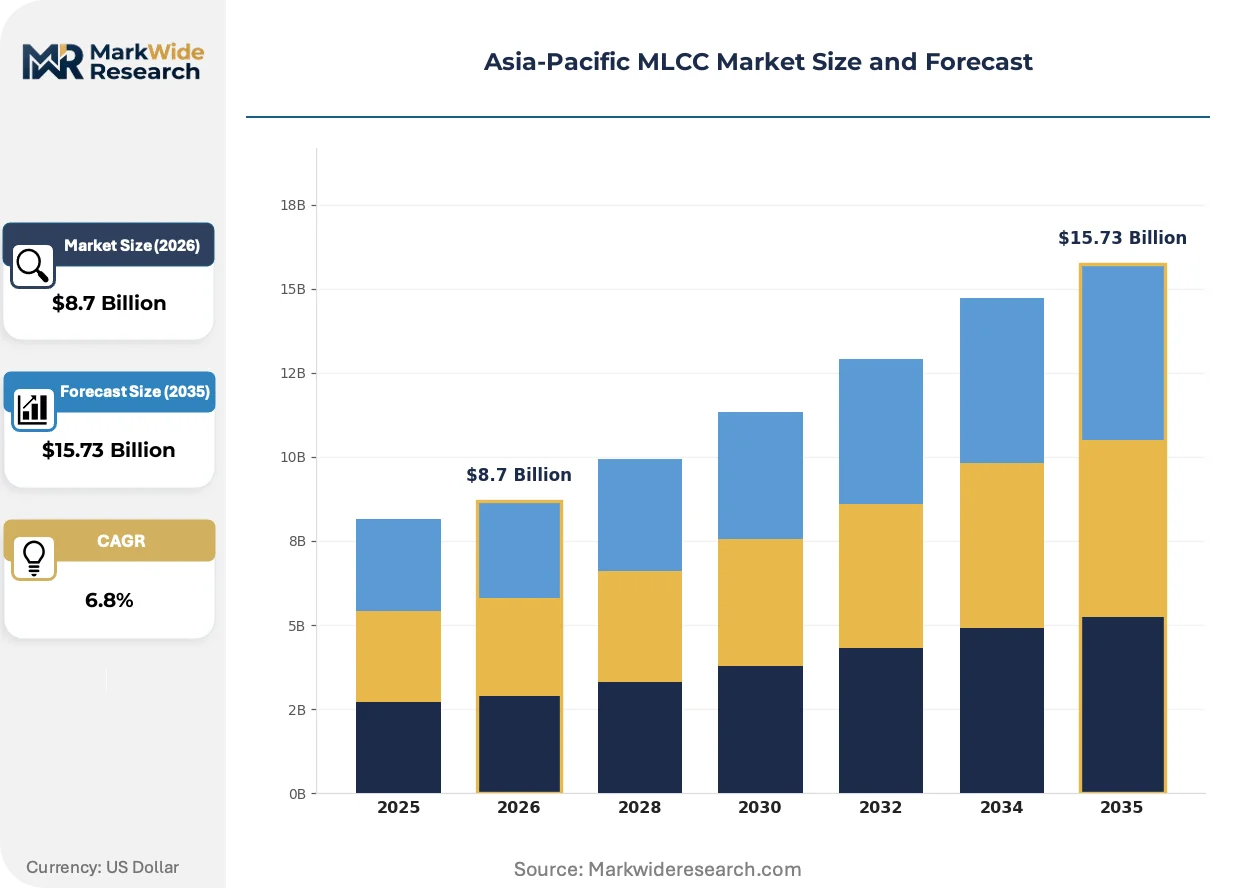
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Consumer Electronics, Automotive, Telecommunications, Industrial Thickness: Thin, Ultra-Thin, Standard, Thick End User: OEMs, Tier-1 Suppliers, Distributors, Aftermarket Providers Material: Ceramic, Polymer, Tantalum, Others |
| Companies Covered | Taiyo Yuden Co., Ltd., Kyocera AVX Components Corporation, Murata Manufacturing Co., Ltd., Yageo Corporation, Maruwa Co., Ltd., Samsung Electro-Mechanics Co., Ltd., Walsin Technology Corporation, Nippon Chemi-Con Corporation, TDK Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific MLCC Market Trends and Innovations
Manufacturing process intensification is collapsing traditional layer-count limitations while regulatory harmonization pressures reshape quality assurance protocols. These forces are compressing product development cycles and redrawing competitive boundaries across the Asia-Pacific capacitor landscape.
Ultra-high layer stacking beyond 1,000 layers is collapsing the physical volume required for equivalent capacitance in automotive DC-link applications. Tier-1 EV suppliers in South Korea now specify these densities for onboard charger modules, enabling footprint reductions that accommodate tighter engine bay packaging constraints without sacrificing ripple current handling.
METI's semiconductor and passive component reshoring framework conditions subsidy access on domestic MLCC production expansion, forcing suppliers to maintain dual Japan-ASEAN manufacturing footprints. Automotive OEMs with JIS-certified supply agreements face accelerated audit schedules, redirecting procurement teams toward suppliers with verified in-country sintering capacity.
Consolidated procurement consortia among Yangtze River Delta electronics manufacturers are displacing traditional distributor relationships for high-volume MLCC categories. These buying groups negotiate direct mill relationships for Class 2 dielectrics, capturing margin that previously accrued to authorized distributors while imposing stricter GB reliability documentation requirements on Japanese and Korean suppliers.
Asia-Pacific MLCC Market Segmentation
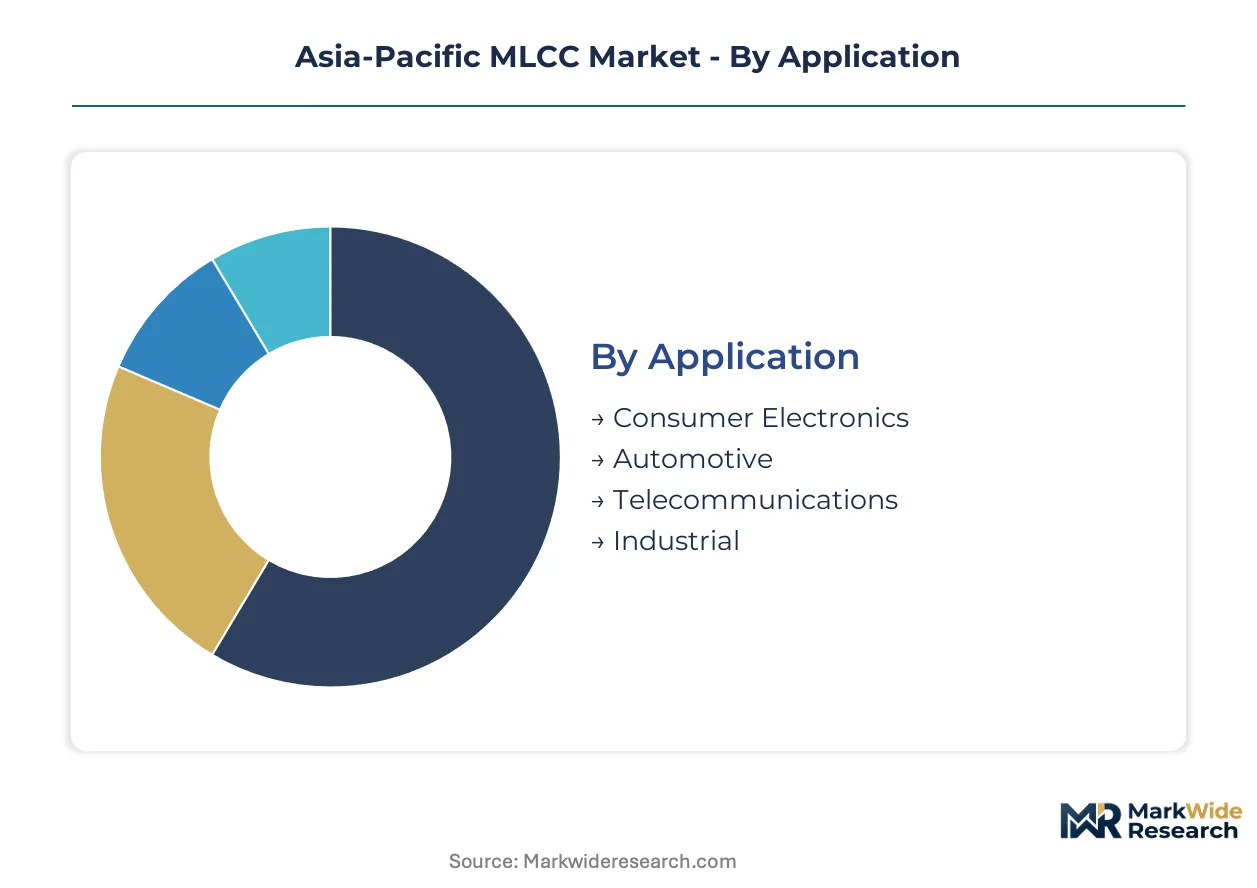
MLCC procurement patterns diverge sharply across application contexts, with automotive-grade components demanding intensive qualification support while consumer electronics volumes prioritize logistics efficiency. Understanding these segmentation fault lines reveals where margin pools concentrate and which technical specifications command pricing premiums.
Application:
After-sales service intensity varies dramatically by application, with automotive programs requiring decade-long traceability and field failure analysis that consumer electronics simply do not demand.
- Automotive:AEC-Q200 qualified components serve battery management systems and onboard chargers across Japan, South Korea, and China electrification programs. Tier-1 suppliers in the Yangtze River Delta now specify 1,000+ layer counts for DC-link filtering in 800V architectures.
- Consumer Electronics:Smartphones, wearables, and tablets drive sub-0.3mm thickness requirements. South Korean OEMs dominate RF module procurement, compressing supplier margins through consolidated procurement consortia.
- Telecommunications:5G base station deployments in South Korea and Japan consume high-frequency variants for compact antenna designs.
- Industrial:Factory automation and power inverter applications favor temperature-stable Class 1 formulations for precision timing circuits.
Automotive holds the largest share; momentum sits with telecommunications as network densification accelerates.
Thickness:
Cost tier stratification in thickness categories reflects manufacturing yield curves, with ultra-thin production commanding 40-60% price premiums over standard thickness due to sintering furnace constraints.
- Ultra-Thin:Sub-0.3mm heights enable wearable and medical electronics miniaturization. Mechanical yield constraints at 500+ layer counts limit volume scalability, creating supply bottlenecks for Japanese manufacturers in Kyoto industrial zones.
- Thin:0.3-0.8mm range captures smartphone RF module demand across South Korean and Chinese OEM assembly lines. Murata's proprietary thin-layer technology dominates automotive-grade shipments in this bracket.
- Standard:General-purpose industrial and consumer applications favor this thickness for cost efficiency.
- Thick:Legacy automotive and industrial equipment maintenance drives residual demand.
Standard thickness retains volume leadership; ultra-thin categories are expanding most quickly as device miniaturization intensifies.
End User:
Customer type determines contract structure, with OEMs demanding direct mill relationships while distributors absorb inventory risk for fragmented aftermarket demand.
- OEMs:Consumer electronics and automotive original equipment manufacturers negotiate direct procurement agreements. Yangtze River Delta electronics manufacturers increasingly bypass authorized distributors for Class 2 dielectrics.
- Tier-1 Suppliers:Battery management system and onboard charger module producers in South Korea specify high-layer-count MLCCs with verified in-country sintering capacity under METI reshoring frameworks.
- Distributors:Authorized channels retain relevance for mid-volume industrial and telecommunications customers requiring technical support.
- Aftermarket Providers:Repair and maintenance networks source legacy thickness categories for industrial equipment refurbishment.
OEMs command the largest procurement volumes; tier-1 suppliers are gaining share fastest as automotive electrification concentrates purchasing power.
Material:
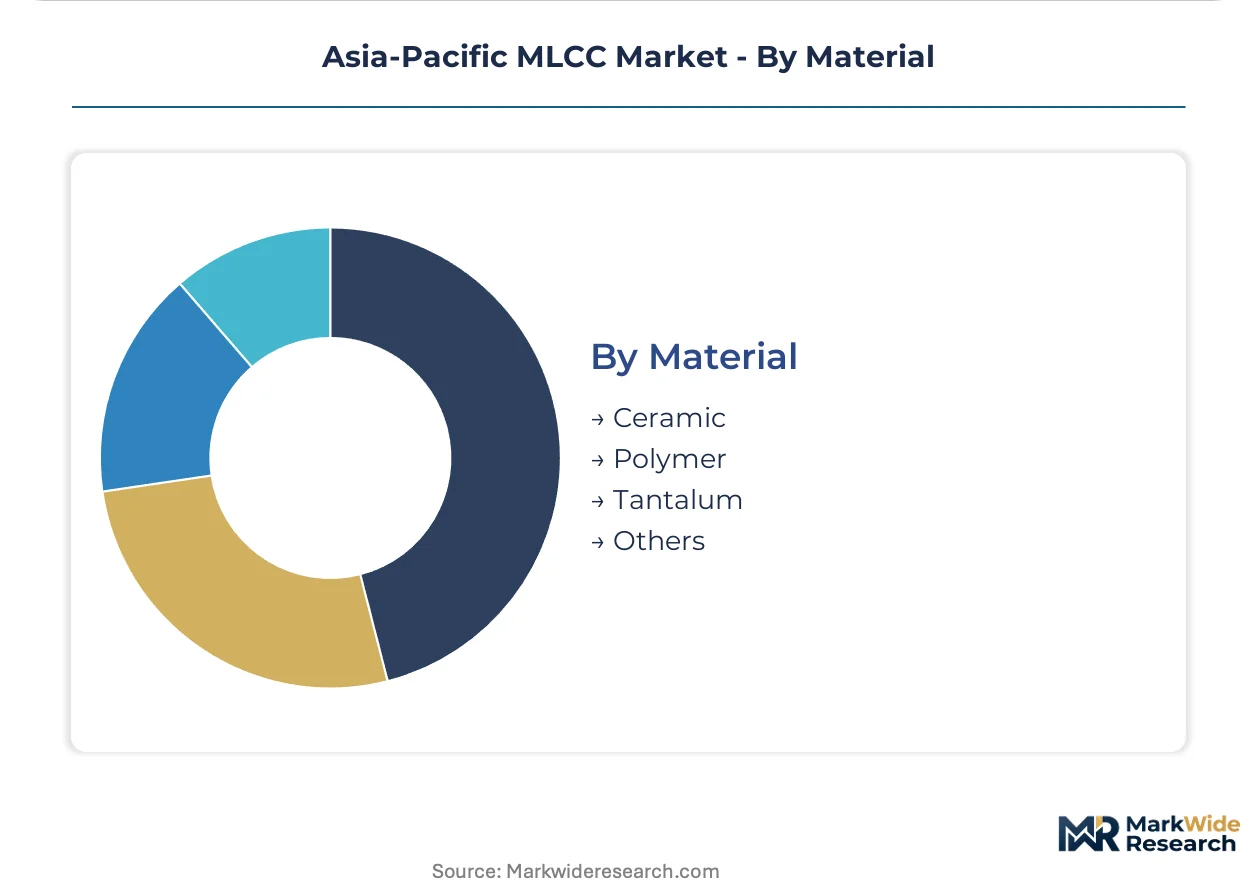
Supply concentration in ceramic formulations shapes competitive boundaries, with barium titanate-based dielectrics dominating while alternative materials carve niche applications.
- Ceramic:Barium titanate-based Class 2 dielectrics occupy dominant volume share. China's MIIT directives mandate domestic capacity expansion for ceramic powder and electrode materials to achieve capacitor autonomy.
- Polymer:Solid electrolyte alternatives serve select telecommunications filtering applications where equivalent series resistance requirements exceed ceramic capabilities.
- Tantalum:Niche industrial and military applications favor this material for stability in extreme temperature environments.
- Others:Niobium oxide and film capacitors address specialized medical and aerospace requirements.
Ceramic formulations hold the largest share; polymer alternatives are climbing the fastest as 5G infrastructure demands evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors regional policy direction through dual carbon mandates and capacitor autonomy roadmaps. Japan's METI reshoring framework and South Korea's industrial ministry subsidies reshape manufacturing footprints across the region.
China
MIIT directives mandate domestic MLCC capacity expansion for EV powertrains and renewable energy inverters. SAMR enforces GB standards for electronic component reliability while directing industrial policy toward capacitor autonomy. Yangtze River Delta and Pearl River Delta electronics manufacturing clusters concentrate procurement from tier-1 automotive suppliers and consumer electronics OEMs.
Japan
METI semiconductor and passive component reshoring frameworks condition subsidy access on domestic MLCC production expansion. JIS certification requirements accelerate audit schedules for automotive OEMs. Kyoto and Nagaokakyo industrial zones concentrate thin-layer technology leadership for automotive-grade shipments.
South Korea
The Ministry of Trade, Industry and Energy established passive component reshoring frameworks linking subsidies to domestic production expansion. 5G base station deployments consume high-frequency MLCC variants for RF filtering. Seoul Capital Area and Busan-Ulsan industrial corridors anchor battery management system and onboard charger module production.
India
PLI scheme incentives for semiconductor and passive component production create first-mover advantage for MLCC fabs. Maharashtra and Gujarat electronics manufacturing zones attract domestic smartphone assembly and automotive wiring harness exports. Karnataka and Tamil Nadu technology corridors concentrate procurement for telecommunications infrastructure.
Taiwan
Cross-border alignment with Tokyo and Seoul on rare-earth dopant export protocols stabilizes supply for high-performance dielectric formulations. Hsinchu Science Park and Tainan Technology Industrial Park concentrate advanced ceramic powder processing. Kaohsiung industrial zones anchor electrode material refining for regional MLCC supply chains.
Asia-Pacific MLCC Market Competitive Landscape
Thin-layer specialists and integrated material producers split the market along technology and supply chain axes. Japanese and South Korean fabricators dominate automotive-grade shipments through proprietary ceramic formulations and captive electrode material production. Three archetypes define competitive positioning: technology leaders commanding premium specifications, integrated producers controlling upstream powder and electrode inputs, and scale-driven manufacturers serving high-volume consumer electronics. Capacity expansion and strategic partnerships constitute the dominant competitive moves as electrification programs compress specification cycles.
Among Japanese technology leaders, Murata Manufacturing Co., Ltd. and Taiyo Yuden Co., Ltd. exemplify the thin-layer specialist archetype through proprietary manufacturing approaches. Samsung Electro-Mechanics Co., Ltd. represents the integrated producer model with upstream control over ceramic powder and electrode materials. These three anchors illustrate how regional competitors occupy distinct strategic positions based on technology depth and supply chain configuration rather than scale alone.
| Leading Market Players |
|---|
| Taiyo Yuden Co., Ltd. |
| Kyocera AVX Components Corporation |
| Murata Manufacturing Co., Ltd. |
| Yageo Corporation |
| Maruwa Co., Ltd. |
| Samsung Electro-Mechanics Co., Ltd. |
| Walsin Technology Corporation |
| Nippon Chemi-Con Corporation |
| TDK Corporation |
| Others |
Pricing and Supply Chain Analysis
Kyoto and Nagaokakyo industrial zones concentrate thin-layer technology leadership, anchoring premium pricing power for automotive-grade MLCCs while Chinese domestic capacity expansion compresses margins in standard-thickness consumer electronics categories. This geographic bifurcation creates divergent margin pools across the Asia-Pacific capacitor landscape.
Pricing Analysis
Japanese manufacturers command price premiums of 15-25% over Korean rivals in automotive-grade shipments, with AEC-Q200 certification tiers separating premium pricing from standard industrial grades. Cost compression in sub-0.3mm ultra-thin categories intensifies as mechanical yield constraints limit volume scalability, while consolidated procurement consortia in China's Yangtze River Delta squeeze supplier margins through direct mill relationships. Tier-1 automotive suppliers exhibit lowest price sensitivity due to decade-long traceability requirements, whereas smartphone OEMs drive hardest bargain through volume consolidation.
Supply Chain Analysis
Tokyo-Seoul-Taipei alignment on rare-earth dopant export protocols restricts cross-border flows of nickel, palladium, and barium titanate precursors essential to high-performance dielectric formulations. Ceramic powder processing concentrates in Japan's Kyoto industrial zone, South Korea's Seoul Capital Area, and Taiwan's Hsinchu Science Park, with electrode material refining anchored in Kaohsiung and Busan-Ulsan corridors. Single-source vulnerability persists for 1,000+ layer count sintering furnaces with extended equipment lead times. Distribution runs through authorized channels for mid-volume industrial customers, while OEMs increasingly bypass distributors for direct mill procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification programs across Japan, South Korea, and China are accelerating MLCC specification cycles, creating early-cycle expansion conditions for suppliers with verified AEC-Q200 capacity and in-country sintering footprints.
For Market Incumbents: Entrench automotive-grade positioning through captive ceramic powder production in Japan's Kyoto industrial zone and dual Japan-ASEAN manufacturing footprints compliant with METI reshoring frameworks. Accelerate JIS certification maintenance to defend against Korean rivals with KS-certified alternative supply, while expanding 1,000+ layer count capacity for 800V EV architectures before sintering furnace lead times extend further.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme electronics manufacturing zones, where domestic smartphone assembly and automotive wiring harness exports create first-mover advantage for MLCC fabs outside the Japan-Korea-Taiwan supply concentration. Target industrial and telecommunications segments with less stringent qualification timelines than automotive, leveraging GB standards compliance to access Yangtze River Delta procurement consortia through direct technical sales engagement.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with upstream ceramic powder and electrode material control, as backward integration separates viable long-term competitors from margin-compressed assemblers across the 5-10 year electrification window. Monitor Taipei-Japan-Seoul rare-earth dopant protocol negotiations as inflection signal for supply stability and input cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in High-Layer-Count Manufacturing | Enables 800V EV platform qualification for tier-1 battery management system suppliers. |
| Backward Integration into Ceramic Powder Production | Secures barium titanate supply autonomy under China's MIIT capacitor independence directives. |
| Dual Japan-ASEAN Manufacturing Footprint | Satisfies METI reshoring subsidy conditions while maintaining cost-competitive export capacity. |
| Long-term Supply Agreement with Rare-Earth Processors | Stabilizes dopant input costs for temperature-stable Class 1 dielectric formulations. |
| Joint Venture for Sintering Furnace Technology | Reduces 24-36 month equipment lead times constraining ultra-high layer count scale-up. |
Research Methodology
The analysis maps automotive electrification, 5G infrastructure, and consumer electronics miniaturization sub-sectors, each validated through procurement directors at tier-1 automotive suppliers, MLCC product managers at Japanese and Korean manufacturers, and regulatory affairs leads navigating JIS, KS, and GB certification tracks. Primary interview findings triangulate against secondary sources including MIIT industrial policy directives, METI semiconductor reshoring framework documentation, SAMR GB standards filings, customs trade data for nickel and palladium flows, and SEC disclosures from listed capacitor manufacturers. Bottom-up demand modeling from application-specific consumption rates converges with top-down market sizing across ceramic material formulations and thickness categories.
Assumptions hold fixed the current Tokyo-Seoul-Taipei rare-earth export control alignment and MIIT dual carbon mandate intensity, while varying EV penetration trajectories and 5G base station deployment cadences across the projection horizon. Segmentation dimensions include application context, thickness category, end-user type, and ceramic material formulation grade. CAGRs derive from fitted growth curves against historical production capacity expansion patterns and announced fab investments, with automotive content-per-vehicle and smartphone RF module density serving as key demand drivers.
Macroeconomic conditions sit as an overlay; deviation in yen-won-yuan exchange rates or London Metal Exchange nickel and palladium pricing would shift the trajectory. Material shifts in METI reshoring subsidy eligibility criteria or cross-border rare-earth dopant protocol breakdown would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
CZ Silicon Wafer Market