
 Global UV Spectroscopy Market | 2026-2036
Global UV Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global UV Spectroscopy Market Foresight
Software-defined spectral analysis is recalibrating what instrument vendors bundle with hardware, shifting revenue toward recurring licensing and cloud-enabled method libraries. Thermo Fisher Scientific leverages its informatics platform to anchor long-term contracts in pharmaceutical quality control. Agilent Technologies sustains R&D intensity across photodiode array architectures, while Shimadzu Corporation dominates ultraviolet-fluorescence configurations for environmental monitoring applications in East Asia.
UV spectroscopy measures molecular absorption in the ultraviolet wavelength range, typically spanning 190 to 400 nanometers, to quantify chemical concentration or identify structural properties. The technique relies on Beer-Lambert law calculations to determine analyte concentration from absorbance values at specific wavelengths. Double beam instruments command premium positioning in regulated pharmaceutical environments where baseline stability affects compliance documentation. Portable and fiber optic segments are expanding fastest in field-based environmental monitoring, though academic institutions still generate steady demand for single beam systems in teaching laboratories.
FDA 21 CFR Part 11 electronic records requirements and EMA GMP Annex 15 qualification standards shape instrument validation protocols across pharmaceutical end users. EPA methods such as 1664 and SM 5910B mandate specific UV detection parameters for wastewater and drinking water compliance testing. REACH chemical registration in Europe and dual carbon goals under China's MEE further extend demand for precise contaminant quantification. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters, as divergence in wavelength accuracy tolerances could fragment instrument specification requirements across export markets.
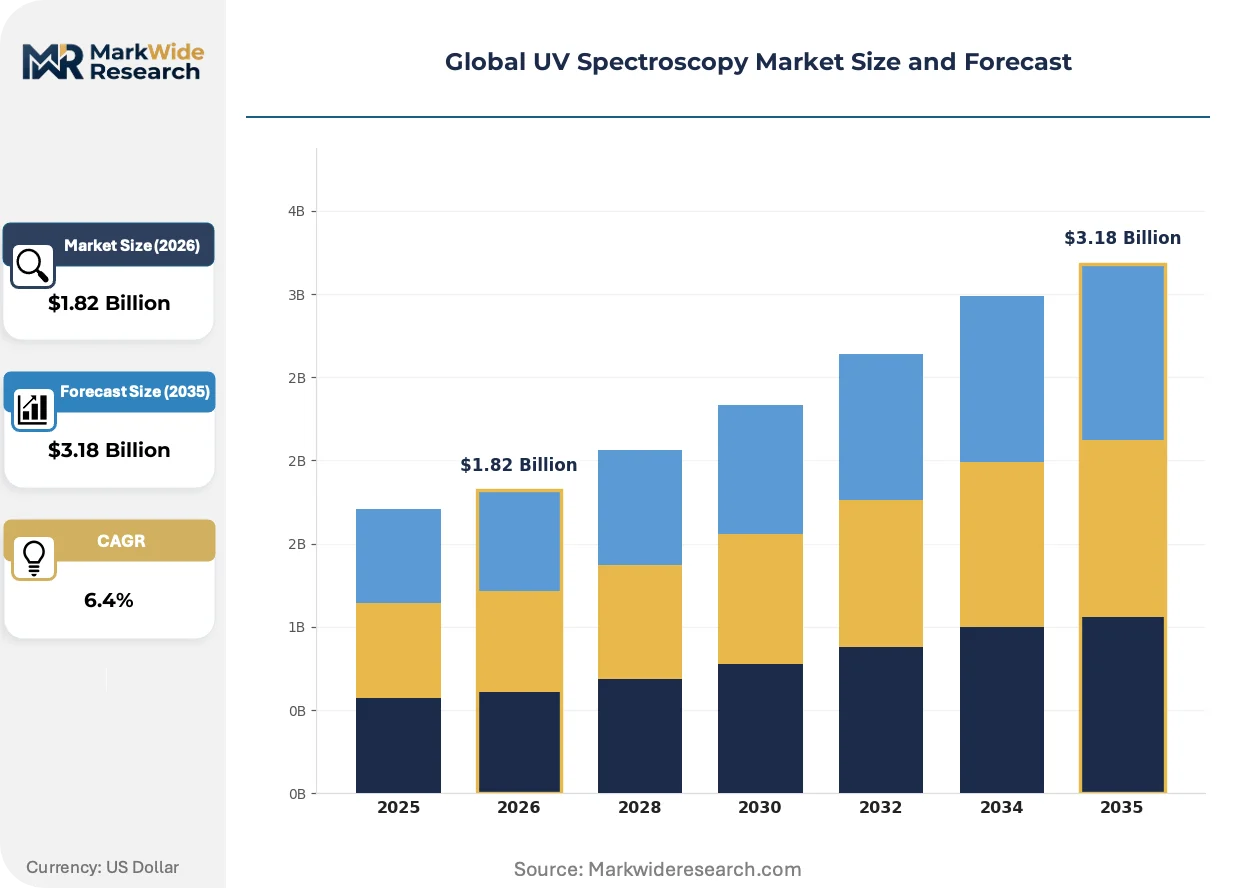
Market Dynamics
Software-defined spectral analysis is compressing hardware margins while locking pharmaceutical laboratories into recurring cloud licensing contracts. Thermo Fisher Scientific and Agilent Technologies now compete on informatics platform stickiness rather than photodiode array specifications alone.
Growth Catalysts
- FDA 21 CFR Part 11 mandates:Electronic records requirements in the United States force pharmaceutical quality control laboratories to upgrade UV systems with validated software audit trails. Double beam instruments with embedded compliance firmware capture replacement cycles.
- East Asian semiconductor clusters:Photoresist characterization in Taiwan and South Korea drives UV-fluorescence system deployment for sub-7nm node manufacturing. Foundries require real-time molecular absorption monitoring to maintain wafer yield.
- REACH chemical registration:European manufacturers must quantify contaminant thresholds for substance dossiers. UV spectroscopy provides the cost-effective quantification method for small-to-medium chemical producers in Germany and France.
Market Restraints
- Deuterium lamp supply concentration:Japanese and German specialty lamp manufacturers control critical ultraviolet source production. Any disruption in xenon or deuterium arc lamp supply chains halts instrument assembly lines.
- Grating fabrication technical ceiling:Holographic diffraction gratings with sub-nanometer precision remain limited to three specialized optical foundries worldwide. This constrains high-resolution instrument scaling.
- Photodiode array substitution:Fourier-transform infrared and Raman spectroscopy methods displace UV techniques in certain polymer identification applications. End-users in packaging industries increasingly specify multi-modal instruments.
Strategic Opportunities
- India pharmaceutical API testing:CDSCO tightening of active ingredient purity verification creates instrument demand in Mumbai and Hyderabad contract research organizations. Local distributors can capture service contract renewals.
- Cloud-enabled method libraries:Convergence of UV hardware with AI-driven spectral matching algorithms allows vendors to monetize proprietary compound databases. Subscription revenue streams decouple from capital equipment cycles.
- China MEE dual carbon monitoring:Wastewater treatment facilities in the Yangtze River basin must quantify organic pollutant loads. Portable UV-fluorescence systems enable field-based compliance verification without laboratory transport delays.
Industry Challenges
- Spectroscopic method development expertise:Pharmaceutical laboratories lack personnel trained in Beer-Lambert law optimization for complex matrix samples. Vendors must embed guided method setup workflows to reduce customer onboarding friction.
- Legacy LIMS integration complexity:UV instruments must interface with decade-old laboratory information management systems in regulated environments. API compatibility testing extends deployment timelines by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UV Spectroscopy Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Beam, Double Beam, Array Spectrophotometer, Fiber Optic, Portable Technology: UV-Visible, UV-Fluorescence, Photodiode Array, Charge-Coupled Device, Deuterium Lamp Application: Pharmaceutical Testing, Food Analysis, Environmental Monitoring, Chemical Research, Polymer Testing End User: Academic Institutions, Research Laboratories, Quality Control Units, Biotechnology Firms |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Shimadzu Corporation, PerkinElmer, Hitachi High-Tech Corporation, JASCO, Mettler Toledo, Bruker Corporation, Ocean Insight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UV Spectroscopy Market Shifts & Advancements
Three intersecting forces are reshaping competitive positioning: miniaturization of optical benches, regulatory digitization mandates, and the unbundling of hardware from analytical method IP.
Microspectrophotometry systems with fiber-optic probe interfaces are rewriting how semiconductor fabs perform inline photoresist thickness monitoring. Taiwan Semiconductor Manufacturing Company and Samsung Foundry now specify probe-integrated UV units for direct wafer-level measurement. This architecture is compressing the addressable market for traditional benchtop instruments in advanced node manufacturing.
EMA GMP Annex 15 qualification standards now require documented wavelength accuracy verification across the full 190-400 nanometer range. Pharmaceutical manufacturers in Ireland and Switzerland must implement automated performance qualification protocols that generate electronic signatures. This is forcing mid-tier instrument vendors to license compliance software from established informatics platforms rather than build proprietary modules.
Service contract unbundling is fragmenting how academic institutions acquire UV capability. Universities in the United Kingdom and Australia increasingly lease portable units through shared research infrastructure schemes rather than capitalizing departmental purchases. This behavioral shift concentrates demand with rental channel specialists and compresses direct manufacturer sales cycles in the education vertical.
Global UV Spectroscopy Market Segmentation
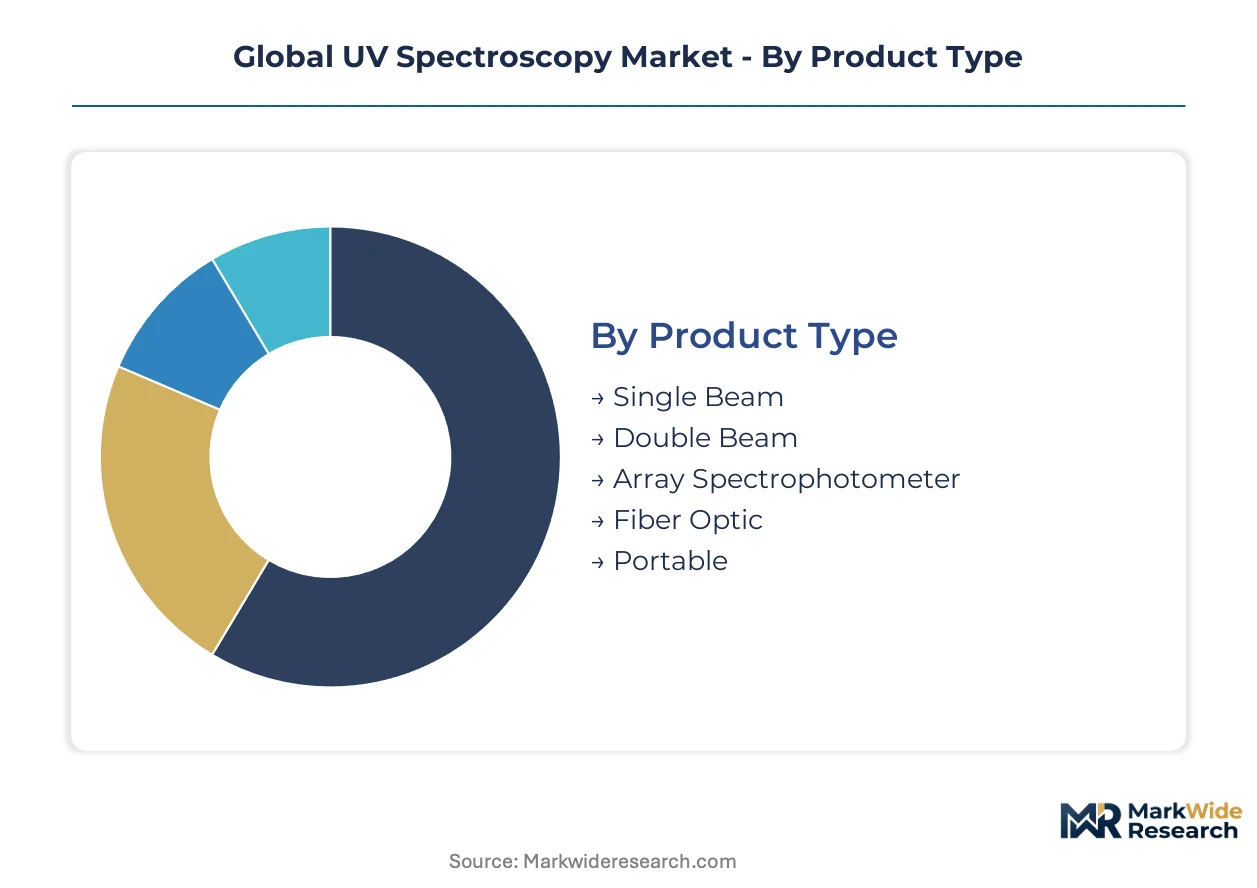
UV spectroscopy instruments fragment across four structural dimensions that determine procurement patterns, validation requirements, and vendor pricing power. Product architecture dictates whether systems operate as standalone laboratory assets or embed into process control loops. Technology selection locks buyers into specific lamp and detector supply chains with varying lead times.
Product Type:
Standalone benchtop configurations dominate regulated pharmaceutical environments where method transfer documentation is mandatory, while fiber optic and portable variants embed directly into manufacturing process streams.
- Double Beam:Simultaneous reference and sample beam measurement eliminates baseline drift in extended kinetic assays. FDA 21 CFR Part 11 compliance documentation in United States pharmaceutical quality control laboratories drives replacement demand for systems with embedded electronic signature firmware.
- Single Beam:Simpler optical path with sequential blank measurement suits teaching laboratories and routine concentration assays where capital constraints outweigh precision requirements. Academic institutions in Germany and Australia generate steady procurement for undergraduate training programs.
- Array Spectrophotometer:Photodiode array detectors capture full spectra in milliseconds without mechanical scanning. Semiconductor photoresist characterization in Taiwan foundries demands this speed for inline thickness monitoring.
- Fiber Optic:Remote probe interfaces extend UV measurement to hazardous or confined industrial environments. Chemical manufacturers in France deploy these for reactor monitoring without sample extraction.
- Portable:Battery-powered units with solid-state sources enable field-based environmental compliance testing. China's MEE dual carbon monitoring mandates are accelerating procurement for Yangtze River basin wastewater facilities.
Double beam systems lead volumes today; portable configurations are gaining share fastest.
Technology:
Light source and detector combinations create tiered performance bands that align with end-user regulatory exposure and analytical throughput requirements.
- UV-Visible:Broad spectral range covering 190-900 nanometers supports both organic chromophore quantification and visible colorimetric assays. Food safety laboratories in Italy rely on this versatility for multi-parameter contaminant screening.
- UV-Fluorescence:Photoluminescence detection achieves parts-per-trillion sensitivity for polycyclic aromatic hydrocarbon analysis. Environmental monitoring stations in South Korea deploy these for marine oil spill fingerprinting.
- Photodiode Array:Multi-channel parallel detection eliminates moving parts and reduces maintenance intervals. Pharmaceutical stability testing in Switzerland favors this architecture for forced degradation studies.
- Charge-Coupled Device:Two-dimensional array detectors enable imaging spectroscopy for microvolume samples. Biotechnology firms in Cambridge, United Kingdom specify these for high-throughput screening workflows.
- Deuterium Lamp:Continuous spectrum ultraviolet source spanning 160-400 nanometers remains the reference standard for wavelength accuracy verification. Japanese lamp manufacturers control critical supply concentration.
UV-Visible platforms anchor current installed base; UV-Fluorescence systems show steepest expansion trajectory.
Application:
Regulatory stringency varies sharply across use cases, with pharmaceutical and environmental segments demanding validated software while research applications prioritize hardware flexibility.
- Pharmaceutical Testing:Active ingredient assay and dissolution profile verification require wavelength accuracy within ±0.5 nanometers. EMA GMP Annex 15 qualification standards in Ireland and Switzerland mandate automated performance verification protocols.
- Environmental Monitoring:EPA Method 1664 oil and grease quantification and SM 5910B dissolved organic carbon testing specify detection parameters. Wastewater treatment utilities in Texas and California face compliance deadlines.
- Food Analysis:Mycotoxin and additive quantification for import certification. Brazilian agricultural exporters deploy UV systems to meet European Union maximum residue limits.
- Chemical Research:Reaction kinetics and equilibrium constant determination with minimal regulatory documentation burden. University chemistry departments in Netherlands prioritize open software architectures.
- Polymer Testing:Stabilizer content and degradation product identification. Packaging manufacturers in Japan substitute UV methods with FTIR for certain identification tasks.
Pharmaceutical testing commands premium pricing; environmental monitoring applications are expanding most quickly.
End User:
Capital availability and regulatory exposure create distinct procurement behaviors across institutional categories.
- Quality Control Units:Validated methods with documented uncertainty budgets support batch release decisions. FDA-inspected facilities in United States maintain instrument qualification records for seven-year retention periods.
- Research Laboratories:Method development flexibility and upgradeable software modules take priority over compliance features. Contract research organizations in India balance throughput demands against capital constraints.
- Academic Institutions:Shared research infrastructure schemes in United Kingdom and Australia are shifting procurement from departmental purchase to centralized rental models.
- Biotechnology Firms:High-throughput screening and process analytical technology integration requirements. Cell therapy developers in Singapore specify fiber optic probes for bioreactor monitoring.
Quality control units generate largest revenue concentration; biotechnology firms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains stricter EMA qualification protocols than the United States, while East Asian manufacturing clusters generate faster instrument replacement cycles for photoresist monitoring applications.
United States
FDA 21 CFR Part 11 mandates drive replacement demand in pharmaceutical quality control laboratories across New Jersey and Massachusetts. EPA Method 1664 compliance deadlines for wastewater utilities in Texas and California accelerate portable UV-fluorescence procurement. Boston and San Francisco biotechnology clusters specify fiber optic probe integration for bioreactor monitoring.
Germany
REACH chemical registration requirements force small-to-medium chemical producers in the Rhine-Ruhr region to quantify contaminant thresholds. EMA GMP Annex 15 qualification standards mandate automated performance verification with electronic signatures. Stuttgart and Munich pharmaceutical testing laboratories expand double beam instrument procurement for active ingredient purity verification.
China
MEE dual carbon goals require wastewater treatment facilities in the Yangtze River basin to quantify organic pollutant loads without laboratory transport delays. GB standards for drinking water compliance specify UV detection parameters. Shanghai and Suzhou semiconductor foundries deploy UV-fluorescence systems for sub-7nm node photoresist characterization.
South Korea
MFDS tightening of pharmaceutical purity standards drives instrument upgrades in Seoul contract research organizations. Samsung Foundry and SK Hynix specify photodiode array architectures for real-time molecular absorption monitoring. Busan-Ulsan chemical manufacturing complexes adopt fiber optic UV systems for reactor monitoring without sample extraction.
Switzerland
Swissmedic pharmaceutical manufacturing standards require wavelength accuracy within ±0.5 nanometers for batch release documentation. Basel and Zurich quality control units implement automated performance qualification protocols. Roche and Novartis manufacturing sites anchor premium double beam instrument demand for stability testing applications.
Global UV Spectroscopy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in regulated pharmaceutical environments and fragmented competition in portable field applications. Three strategic archetypes dominate: diversified life science conglomerates with informatics platforms, precision optics specialists with captive grating fabrication, and fiber optic component integrators serving semiconductor process control. M&A activity concentrates on software-defined spectral analysis capabilities, while geographic expansion targets Indian pharmaceutical contract research organizations.
Among diversified analytical instrument conglomerates, Thermo Fisher Scientific and Agilent Technologies occupy positions anchored by informatics platform stickiness rather than hardware specifications alone. Shimadzu Corporation exemplifies the precision optics archetype with dominant positioning in ultraviolet-fluorescence configurations for East Asian environmental monitoring applications.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| PerkinElmer |
| Hitachi High-Tech Corporation |
| JASCO |
| Mettler Toledo |
| Bruker Corporation |
| Ocean Insight |
| Others |
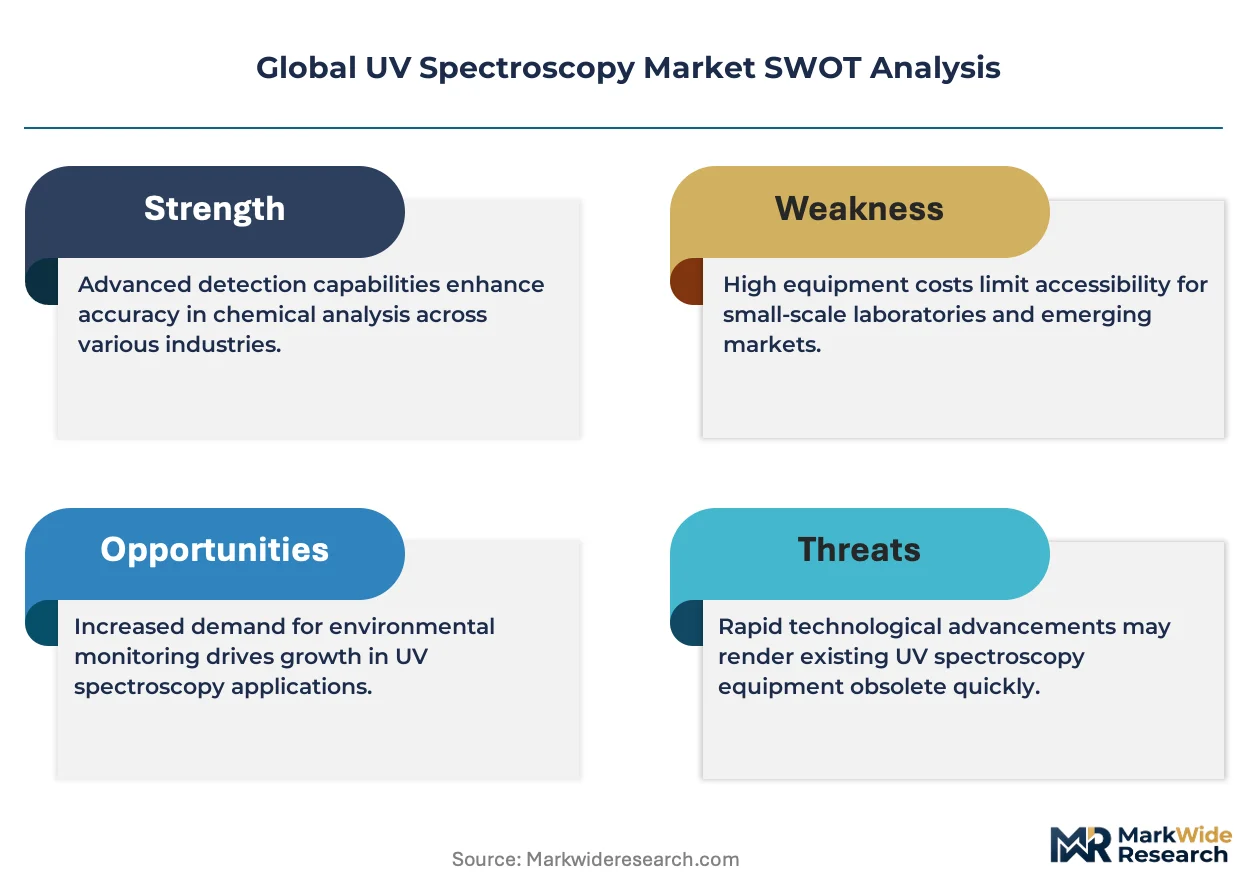
Supply & Pricing Matrix
Pharmaceutical quality control laboratories in Germany and the United States anchor demand for validated double beam systems, locking vendors into subscription-heavy pricing models that bundle compliance firmware with recurring cloud licensing. This buyer concentration grants incumbents pricing power while compressing margins for hardware-only competitors.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for portable UV-fluorescence systems deployed in environmental monitoring. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical units from teaching laboratory configurations and field-based compliance tools. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese MEE procurement mandates favor lowest-compliant-bid award criteria. Academic institutions exhibit highest price sensitivity; semiconductor foundries in Taiwan show lowest.
Supply Chain Analysis
Deuterium lamp supply rests on Japanese and German specialty manufacturers controlling ultraviolet source production. Holographic diffraction grating fabrication draws from three specialized optical foundries concentrated in Germany, Japan, and the United States. Raw material dependencies include xenon arc lamps, photodiode array sensors, and fused silica optics. Single-source vulnerability in deuterium lamp supply creates assembly line halt risk. Distribution runs through authorized dealer networks for regulated pharmaceutical segments and direct OEM relationships for semiconductor process control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into durable demand, with FDA 21 CFR Part 11 and EMA GMP Annex 15 digitization mandates forcing replacement cycles that decouple from pure hardware obsolescence.
For Market Incumbents: Cement informatics platform stickiness by embedding AI-driven spectral matching algorithms that lock pharmaceutical laboratories into proprietary method libraries. Deepen backward integration into deuterium lamp supply through captive production or long-term offtake agreements with Hamamatsu and Heraeus. Defend against Fourier-transform infrared substitution in polymer identification by bundling multi-modal detection capabilities. For New Entrants and Emerging Players: Enter via India's CDSCO-tightened API testing market, where Mumbai and Hyderabad contract research organizations lack established vendor relationships. Target portable UV-fluorescence configurations for China's Yangtze River basin wastewater facilities facing MEE dual carbon compliance deadlines. Lead with field-based method development services that reduce customer onboarding friction. For Investors and Strategic Acquirers: Diversified life science conglomerates with existing informatics platforms are the most active acquirer in this space, seeking software-defined spectral analysis capabilities. Long-term viability hinges on recurring revenue share exceeding capital equipment cycles. Acquisition target archetype: fiber optic probe specialists serving semiconductor process control with captive grating fabrication. Watch FDA-EMA pharmacopeial harmonization progress on wavelength accuracy tolerances as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Enabled Method Library Launch | AI-driven spectral matching locks pharmaceutical laboratories into recurring licensing revenue streams. |
| Backward Integration into Deuterium Lamp Supply | Captive ultraviolet source production mitigates single-source vulnerability in Japanese supply chains. |
| Fiber Optic Probe Integration Partnership | Semiconductor foundries in Taiwan specify probe-integrated units for direct wafer-level measurement. |
| CDSCO Compliance Certification Investment | Indian pharmaceutical API testing laboratories require validated systems for purity verification mandates. |
| Multi-Modal Detection Platform Development | FTIR substitution threat in polymer identification demands bundled UV-Raman capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with instrument vendor product managers, pharmaceutical quality control laboratory directors, semiconductor fab process engineers, and environmental compliance officers with secondary validation. Sources included FDA 510(k) filings, EMA GMP inspection reports, EPA method documentation, and customs trade records for spectrophotometer imports. Bottom-up instrument shipment tracking and top-down end-user spending estimates were triangulated.
Historical reference periods anchored the projection horizon across product architecture, technology selection, application vertical, and end-user category dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated regulatory deadline schedules for FDA 21 CFR Part 11 compliance, semiconductor node transition roadmaps, and MEE dual carbon implementation timelines.
Inputs from vendor shipment disclosures and regulatory filing databases were available through the study window; gaps in real-time foundry procurement data introduce uncertainty bands around semiconductor segment projections. Forecasts reflect documented assumptions on pharmacopeial harmonization progress and lamp supply chain stability. Supply disruption in Japanese deuterium lamp production, divergence in USP-EP-JP wavelength accuracy standards, and FTIR technology cost reduction warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Microanalysis Sample Preparation Systems Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Headspace Gas Analyzers Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Handheld XRF Analyzers Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Network Analyzers Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market