
 Multi-Mode Receiver Market | 2026-2036
Multi-Mode Receiver Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Mode Receiver Market Intelligence
Defense procurement concentration is shifting toward prime contractors managing integrated avionics suites rather than discrete component purchases. BAE Systems leverages its electronic warfare heritage to compete for multi-mode receiver slots on next-generation combat aircraft. Thales anchors European supply chains through national sovereignty requirements in France and allied export programs. Garmin Ltd. specializes in dual-use navigation receivers that bridge civil aviation certification with tactical resilience standards.
A multi-mode receiver integrates simultaneous signal processing across GPS, GLONASS, Galileo, and military-encrypted positioning waveforms within a single RF front-end and digital baseband architecture, typically achieving sub-meter accuracy through multi-constellation correlation and anti-jam null-steering. The device serves military and aerospace platforms requiring continuous position, navigation, and timing data under contested electromagnetic conditions. Software-defined radios within this category are capturing expanding design wins as programmable gate arrays and wideband ADCs enable post-deployment waveform updates without hardware obsolescence. Integrated units maintain stronger margin pools where airframe manufacturers bundle navigation, communication, and electronic warfare functions into line-replaceable modules.
FAA technical standard orders govern civil aviation receiver certification for precision approach operations, while the EU's Radio Equipment Directive mandates electromagnetic compatibility and spectrum efficiency for devices deployed in European airspace. Military procurement channels impose additional sovereign requirements through national security classifications and offset agreements. Stakeholders must monitor how software-defined architectures alter traditional hardware-centric certification pathways and supplier qualification timelines.
Market Dynamics
Software-defined radio architectures are compressing hardware refresh cycles across military avionics platforms, forcing suppliers to requalify digital baseband systems under accelerated FAA and EU Radio Equipment Directive timelines.
Growth Catalysts
- FAA Technical Standard Orders:Certification mandates for precision approach operations drive receiver upgrades in civil aviation fleets. Commercial operators replace legacy units to maintain operational authorization.
- Electronic warfare integration:NATO defense procurement channels demand multi-mode receivers with simultaneous GPS, GLONASS, and military-encrypted waveform processing for contested electromagnetic environments.
- FPGA and wideband ADC maturation:Programmable gate arrays enable post-deployment waveform reconfiguration without hardware swaps, extending platform service life across fighter aircraft and unmanned systems.
Market Restraints
- GaN and GaAs substrate costs:Wideband RF front-ends depend on gallium nitride and gallium arsenide semiconductors subject to supply concentration in East Asian foundries.
- Dual-use export control regimes:ITAR and EU dual-use regulations impose licensing friction on cross-border transfers of military-grade navigation receivers.
- Anti-jam null-steering complexity:Multi-element antenna arrays with adaptive beamforming require calibration infrastructure unavailable at smaller maintenance depots.
Strategic Opportunities
- Unmanned aerial system proliferation:Tactical drones require miniaturized multi-mode receivers with sub-meter accuracy for beyond-line-of-sight operations.
- EU Green Deal aviation incentives:Fuel efficiency mandates favor satellite-based navigation over ground-based aids, accelerating receiver retrofit programs.
- Software-defined convergence with electronic warfare:Programmable architectures allow navigation and jamming functions to share RF hardware, reducing unit count per airframe.
Industry Challenges
- DO-178C and DO-254 certification timelines:Civil aviation software and hardware assurance standards extend development cycles for dual-use navigation products.
- Legacy MIL-STD-1553 integration:New digital receivers must interface with analog bus architectures in fielded platforms without full avionics replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Mode Receiver Market |
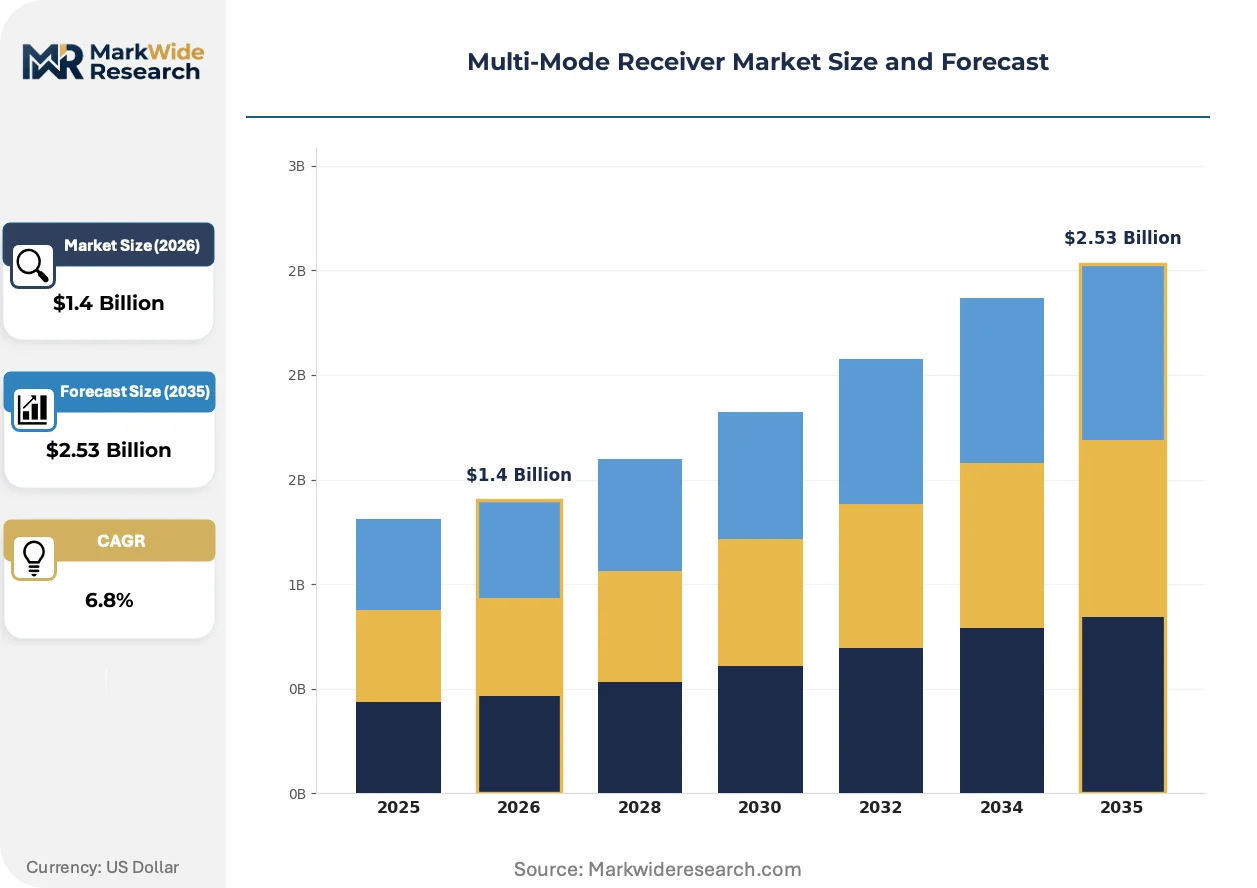
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Receivers, Integrated Units, Software-Defined Radios, Multi-Channel Systems End User: Military, Aerospace, Telecommunications, Transportation Technology: Analog, Digital, Hybrid, RF Deployment: Fixed, Mobile, Portable, Embedded |
| Companies Covered | BAE Systems, Honeywell International Inc., Collins Aerospace, Thales, Garmin Ltd., Leonardo S.p.A., Saab AB, Indra Sistemas, Intelcan Technosystems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Mode Receiver Market Strategic Shifts & Innovations
Digital signal processing integration is collapsing discrete hardware boundaries between navigation, communication, and electronic warfare functions. This convergence demands new supplier capabilities in programmable logic and RF subsystem integration.
Software-defined radio platforms are unifying GPS, Galileo, GLONASS, and military-encrypted waveform processing within single FPGA-based architectures. Prime contractors on sixth-generation combat aircraft programs specify these programmable systems to avoid hardware obsolescence during 30-year service lives. The technology is unifying previously separate receiver line items into integrated line-replaceable modules, compressing supplier count per platform.
EU Radio Equipment Directive electromagnetic compatibility mandates are tightening spurious emission limits for receivers operating in European airspace. Manufacturers must redesign RF shielding and filtering to meet revised spectrum efficiency requirements. Commercial aviation operators face retrofit deadlines that compress procurement cycles for certified units.
Defense procurement consolidation favors integrated avionics suites over discrete component purchases. Platform manufacturers now bundle navigation, communication, and electronic warfare functions into single vendor relationships. This pattern concentrates most visibly in US Department of Defense fighter modernization programs, where prime contractors manage subsystem integration risk.
Multi-Mode Receiver Market Segmentation
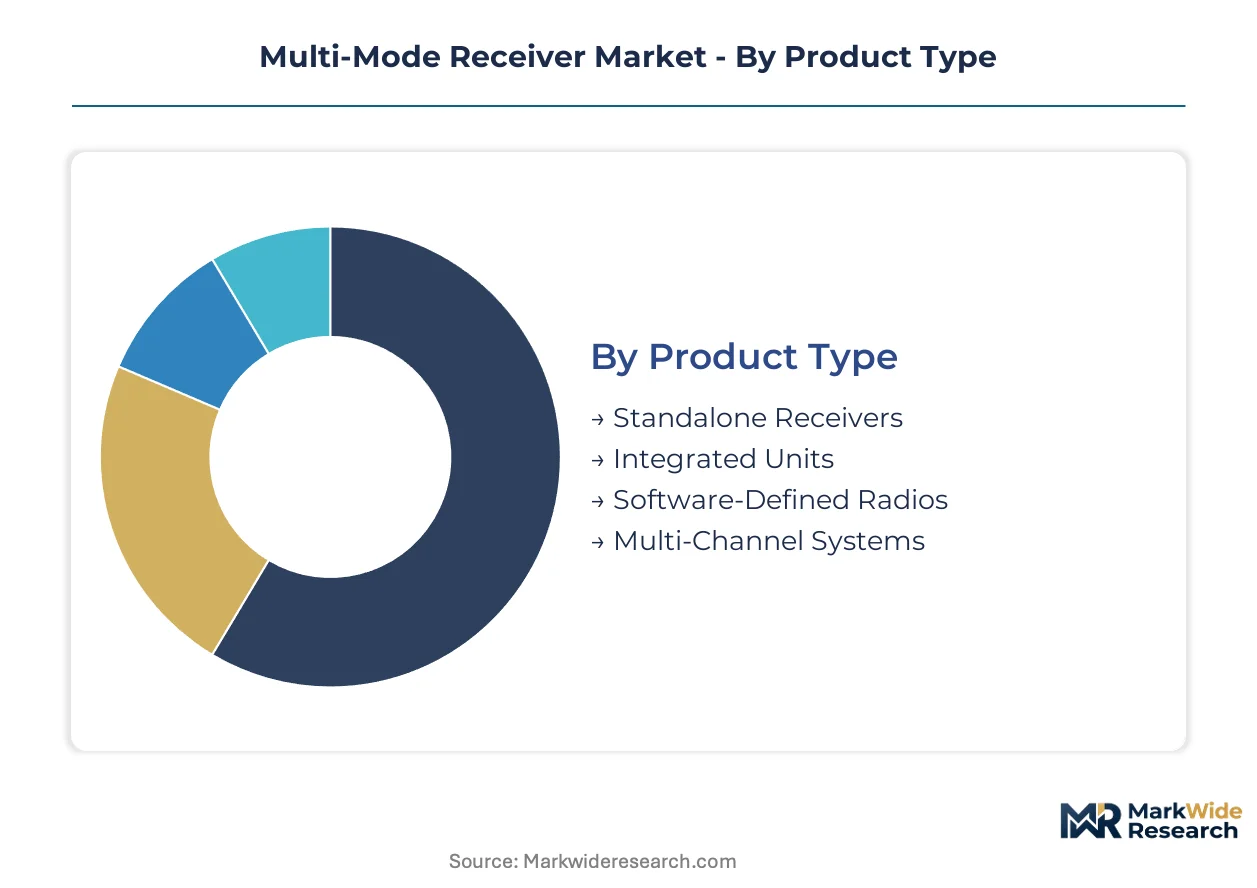
Multi-mode receiver procurement splits across hardware architectures, customer missions, signal processing generations, and physical integration formats. Each segmentation axis reveals distinct upgrade cycles, certification requirements, and supplier margin structures that shape competitive positioning.
Product Type:
Platform modernization programs are compressing replacement timelines as software-defined architectures displace legacy analog hardware across military and civil aviation fleets.
- Standalone Receivers:Discrete units process single-constellation signals through dedicated RF front-ends and baseband processors. Commercial aviation operators in the United States replace these units to maintain FAA precision approach certification, while smaller defense contractors specify them for retrofit programs on legacy airframes.
- Software-Defined Radios:FPGA-based architectures enable post-deployment waveform reconfiguration across GPS, GLONASS, Galileo, and military-encrypted signals without hardware swaps. The Department of Defense drives demand through sixth-generation combat aircraft specifications requiring 30-year service life extension.
- Integrated Units:Bundled navigation, communication, and electronic warfare functions reduce line-replaceable module count per platform.
- Multi-Channel Systems:Simultaneous multi-constellation correlation engines achieve sub-meter accuracy through parallel signal processing paths.
Standalone receivers sit at the top of the volume ranking, with software-defined radios climbing the fastest.
End User:
Customer mission profiles determine anti-jam requirements, export control exposure, and certification pathways that fragment supplier strategies.
- Military:Contested electromagnetic environments demand null-steering antenna arrays and encrypted waveform processing for fighter aircraft, unmanned systems, and electronic warfare platforms. NATO procurement channels concentrate spending on integrated avionics suites rather than discrete components.
- Aerospace:Dual-use navigation receivers bridge FAA civil certification with tactical resilience standards for government and commercial operators.
- Telecommunications:Network timing synchronization drives demand for multi-constellation receivers in 5G infrastructure and data center operations.
- Transportation:Maritime and rail applications require continuous position data under canopy and urban canyon conditions.
Military procurement commands the largest revenue share, with aerospace applications expanding most quickly.
Technology:
Signal processing architectures are migrating toward digital baseband implementations as analog components face obsolescence and supply concentration risks.
- Digital:Wideband ADCs and programmable gate arrays execute correlation, tracking, and anti-jam algorithms in software. The EU Radio Equipment Directive and FAA technical standard orders accelerate requalification timelines for these systems.
- Analog:Legacy discrete component designs persist in fielded platforms requiring MIL-STD-1553 bus compatibility.
- Hybrid:Mixed-signal architectures partition RF front-end analog processing from digital baseband computation.
- RF:Gallium nitride and gallium arsenide semiconductor substrates enable wideband frequency coverage with reduced noise figures.
Digital architectures dominate new platform awards, with hybrid systems retaining share in retrofit applications.
Deployment:
Physical form factors constrain power budgets, thermal management, and antenna configurations that differentiate supplier capabilities.
- Embedded:Chip-scale and module-level integration into airframe line-replaceable units minimizes size, weight, and power consumption. Prime contractors on fighter modernization programs specify these formats for unmanned aerial systems and missile platforms.
- Mobile:Vehicle-mounted units with external antenna arrays serve tactical ground vehicles and rotary-wing aircraft.
- Fixed:Rack-mounted installations in ground control stations and timing infrastructure prioritize precision over portability.
- Portable:Handheld or dismounted soldier systems require ruggedized enclosures and rapid field calibration.
Embedded formats lead platform integration awards, with portable systems gaining traction in special operations procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement intensity varies sharply between mature aerospace clusters and emerging manufacturing bases, with established markets prioritizing sixth-generation platform integration while newer entrants focus on unmanned system miniaturization.
United States
The Department of Defense drives platform modernization for fighter aircraft and unmanned systems through integrated avionics suites. FAA technical standard orders govern civil aviation receiver certification for precision approach operations. Defense contractors in the Greater Boston and Pacific Northwest clusters concentrate on software-defined radio architectures for electronic warfare applications.
France
National sovereignty requirements anchor multi-mode receiver procurement for Rafale fighter modernization and export programs. The EU Radio Equipment Directive mandates electromagnetic compatibility and spectrum efficiency for devices deployed in European airspace. Thales anchors supply chains through design and manufacturing concentration in the Île-de-France aerospace cluster.
Germany
NATO electronic warfare integration demands drive investment in null-steering antenna arrays and encrypted waveform processing. KBA and national security classifications impose sovereign requirements on military procurement channels. Bavaria's defense industrial base specializes in RF subsystem integration for Eurofighter and future combat air system platforms.
United Kingdom
Tempest sixth-generation combat aircraft specifications require programmable architectures avoiding hardware obsolescence across 30-year service lives. UK export control regimes parallel ITAR restrictions on military-grade navigation receiver transfers. BAE Systems leverages electronic warfare heritage from operations in Lancashire and Greater London facilities.
Israel
Contested electromagnetic environment expertise drives demand for anti-jam null-steering and multi-constellation correlation engines. National security classifications restrict cross-border technology transfer for military-encrypted positioning systems. Tel Aviv metropolitan area clusters concentrate on miniaturized embedded receivers for unmanned aerial system proliferation.
Multi-Mode Receiver Market Key Industry Players
United States producers anchor one tier; European specialists hold sovereign-protected positions through national security requirements. Market structure consolidates around prime contractors managing integrated avionics suites rather than discrete component vendors. Three archetypes dominate: defense primes with electronic warfare heritage, dual-use navigation specialists bridging civil and military certification, and RF subsystem integrators with GaN semiconductor capabilities. Competitive moves concentrate on strategic partnerships for software-defined architectures and geographic expansion through offset agreements in NATO procurement channels.
Among defense prime contractors, BAE Systems and Thales exemplify the integrated avionics archetype, occupying positions where platform manufacturers bundle navigation, communication, and electronic warfare functions. Garmin Ltd. represents the dual-use specialist tier, bridging FAA civil certification with tactical resilience standards. These three anchors illustrate how supplier qualification timelines and certification pathways fragment competitive positioning across military and civil procurement channels.
| Leading Market Players |
|---|
| BAE Systems |
| Honeywell International Inc. |
| Collins Aerospace |
| Thales |
| Garmin Ltd. |
| Leonardo S.p.A. |
| Saab AB |
| Indra Sistemas |
| Intelcan Technosystems Inc. |
| Others |
Cost & Logistics Intelligence
Department of Defense bundled procurement for integrated avionics suites is compressing supplier margins and forcing component vendors to absorb qualification costs or cede position to prime contractors with captive receiver capabilities.
Pricing Analysis
Capacity additions in South Korean and Taiwanese foundries are reshaping price floors for GaN and GaAs RF front-end substrates. Three-tier pricing structure across military-certified, dual-use FAA-compliant, and commercial-grade receivers reflects certification investment amortization and anti-jam feature depth. Cost compression in commercial aviation retrofit tiers is intensifying because FAA precision approach mandates compress procurement timelines. Commercial operators exhibit highest price sensitivity; sixth-generation combat aircraft programs demonstrate lowest sensitivity due to sovereign funding and 30-year service life requirements.
Supply Chain Analysis
France's national sovereignty requirements and offset agreements in NATO procurement channels are reshaping sourcing patterns toward domestic design and manufacturing concentration. GaN substrates, wideband ADCs, and programmable gate arrays draw from concentrated East Asian semiconductor fabrication. Single-source vulnerability persists for radiation-hardened FPGA supply. Distribution runs through prime contractor-managed integrated avionics suites rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by defense procurement cycles that extend across multi-decade platform service lives and resist cyclical downturns.
For Market Incumbents: Acquire FPGA design houses and RF subsystem specialists to consolidate software-defined radio capabilities before sixth-generation combat aircraft awards finalize. Offset agreements in NATO channels threaten margin capture for vendors without local manufacturing presence. Certification investment in DO-178C and DO-254 assurance standards preserves dual-use revenue streams against emerging entrants lacking civil aviation heritage. For New Entrants and Emerging Players: EU Green Deal aviation incentives in European member states open a window for satellite-based navigation retrofit specialists targeting commercial fleet fuel efficiency mandates. Unmanned aerial system miniaturization represents the most penetrable segment given prime contractor disinterest in sub-scale tactical drone volumes. Pursue strategic partnerships with Israeli or South Korean unmanned system integrators to bypass ITAR licensing friction. For Investors and Strategic Acquirers: Asymmetric upside sits with dual-use navigation specialists bridging FAA civil certification with tactical resilience standards. Five-to-ten-year viability hinges on software-defined architecture transition completion rather than analog legacy maintenance. Monitor sixth-generation combat aircraft downselection announcements as inflection indicator for prime contractor supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Design House Acquisition | Secures programmable waveform reconfiguration capability for 30-year service life platforms. |
| DO-178C Certification Investment | Unlocks FAA precision approach retrofit revenue from commercial aviation operators. |
| Offset Agreement Execution | Satisfies France and Germany national sovereignty requirements for Rafale and Eurofighter programs. |
| Unmanned System Miniaturization | Captures tactical drone navigation demand beyond prime contractor focus areas. |
| GaN Semiconductor Backward Integration | Reduces substrate cost exposure from East Asian foundry concentration. |
Research Approach
Direct dialogue with avionics procurement officers at prime contractors, FAA certification engineers, defense electronics program managers, and RF subsystem technical directors grounded qualitative assessments in operational constraints. Secondary validation drew from Department of Defense budget justification documents, FAA technical standard order filings, EU Radio Equipment Directive implementation guidance, and SEC 10-K disclosures from listed navigation equipment suppliers. Bottom-up segment sizing triangulated against top-down defense procurement budget allocation analysis.
Segment-level projections across hardware architecture, customer mission, signal processing generation, and physical integration format fed into platform-level aggregation. CAGRs were derived from procurement timeline phasing for sixth-generation combat aircraft, unmanned system fielding rates, and commercial aviation fleet retrofit cycles. Anti-jam null-steering adoption curves and software-defined radio displacement rates for legacy analog units informed technology transition assumptions.
Revisions become necessary when defense procurement budget reprioritization, export control regime expansion, or GaN substrate supply disruption materialize. Forecasts reflect documented assumptions about FAA certification timeline stability and NATO electronic warfare integration funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
5G Gain Block Amplifier Market
RF Components
RF Gan Market
RF Components
Radio Frequency Front End Market
RF Components
RF Switches Market
RF Components
Low Noise Amplifier Market
RF Components
Analog Phase Shifter Market
RF Components
Global RF Plasma Generator Market
RF Components
UHF RFID Inlays Market
RF Components
Coaxial Connectors (RF) Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
Smart Antenna Market
RF Components
RF Tester Market
RF Components
Multilayer Coupled Inductor Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
Frequency Synthesizer Market