
 Americas Semiconductor Diode Market | 2026-2036
Americas Semiconductor Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Semiconductor Diode Market Insights
OEM-direct procurement is tilting away from traditional electronics distribution as tier-one automotive and industrial buyers consolidate vendor relationships. ON Semiconductor Corporation anchors North American supply through its vertically integrated fabrication network. Vishay Intertechnology, Inc. dominates specialty diode portfolios for aerospace and defense end users. Infineon Technologies AG extends its SiC and GaN technology leadership into Americas power electronics applications.
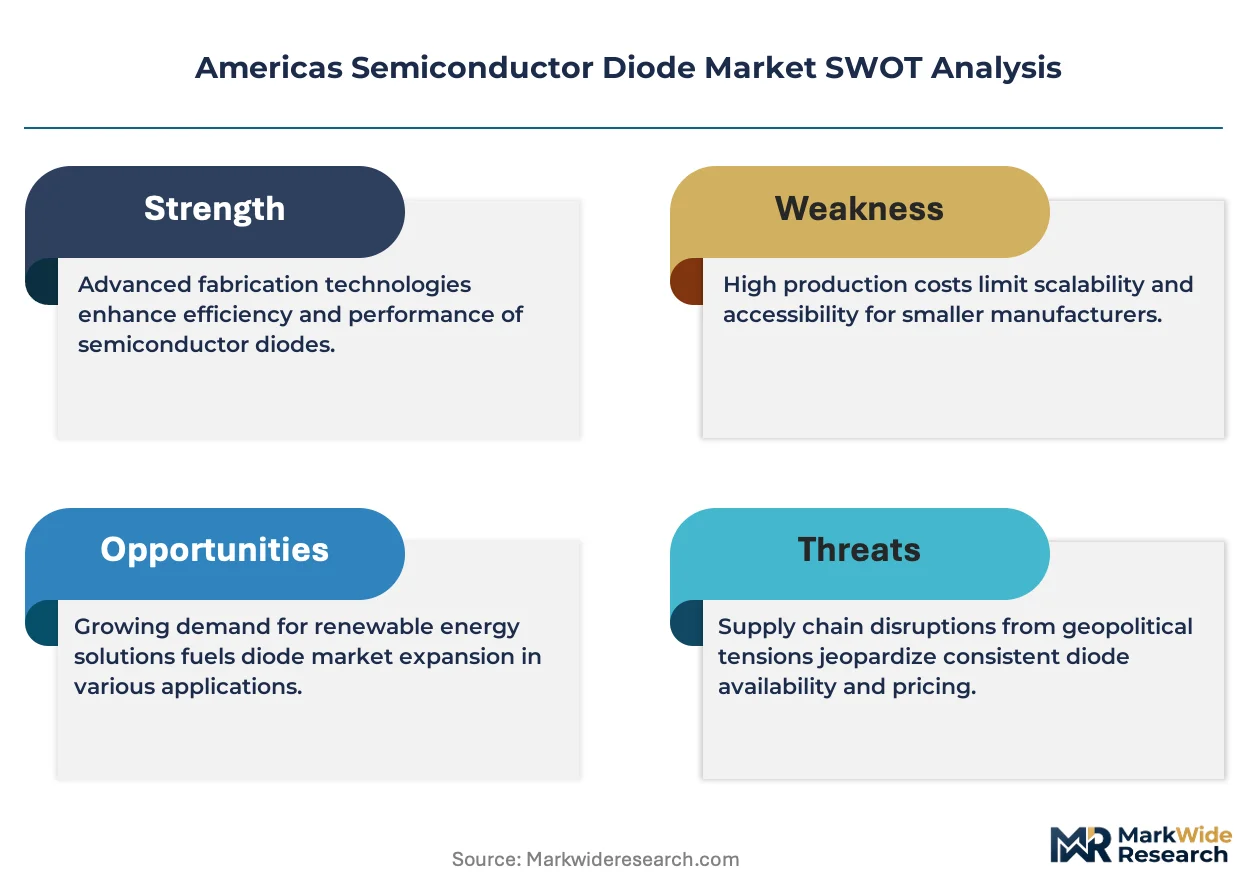
A semiconductor diode is a two-terminal electronic component formed at the junction of p-type and n-type semiconductor materials, operating with a typical forward voltage drop between 0.3V and 0.7V for silicon devices depending on doping concentration and junction geometry. Its primary commercial purpose is unidirectional current control, enabling rectification, voltage clamping, and signal demodulation across power electronics and communications hardware. Rectifier diodes sustain the largest revenue pool due to ubiquity in AC-DC power conversion infrastructure, while Schottky variants capture premium margins in high-frequency switching applications. Gallium nitride technology leads growth velocity as datacenter and EV charger OEMs prioritize reduced switching losses over silicon legacy performance.
US EPA energy efficiency mandates and FCC electromagnetic compatibility standards shape product certification requirements for diodes deployed in power supply and RF systems across the Americas. Mexico's national energy regulator and Brazil's telecommunications agency impose parallel conformity protocols that influence regional manufacturing location decisions. Stakeholders must monitor substrate supply constraints and foundry capacity allocation as compound semiconductor adoption accelerates beyond current silicon-dominant supply chains.
Market Dynamics
Silicon carbide and gallium nitride substrate transitions are collapsing legacy silicon efficiency benchmarks across power electronics applications, forcing foundry capacity reallocation and OEM procurement model restructuring throughout the Americas.
Growth Catalysts
- EPA Energy Efficiency Mandates:US power supply regulations tighten standby loss requirements, accelerating SiC diode deployment in datacenter and EV charging infrastructure.
- EV Powertrain Electrification:Automotive OEMs across the Americas consolidate high-voltage diode procurement for traction inverters and onboard chargers.
- Texas-Arizona Fabrication Clusters:Concentrated foundry investment in these states anchors domestic substrate processing and backend packaging capacity.
Market Restraints
- Compound Semiconductor Substrate Cost Volatility:SiC wafer pricing fluctuates with mining output from limited global sources, compressing margin buffers for device manufacturers.
- Single-Source Foundry Concentration:Advanced GaN epitaxy capacity concentrates with select North American and Asian suppliers, creating supply vulnerability.
- Silicon Device Substitution Resistance:Cost-sensitive industrial motor drive segments retain silicon IGBT-diode pairings despite efficiency penalties.
Strategic Opportunities
- Mexico Nearshoring Expansion:Automotive Tier-1 suppliers relocate power module assembly to capture USMCA tariff advantages and shorten logistics loops.
- Grid-Scale Energy Storage Integration:Utility-scale battery inverters create fresh demand for high-reliability rectifier diodes in bidirectional power conversion.
- IRA Clean Energy Tax Credits:Domestic content bonuses incentivize diode packaging and testing localization within US territory.
Industry Challenges
- Compound Semiconductor Process Engineering Talent Scarcity:SiC and GaN device physics expertise concentrates with veterans from legacy RF and LED industries, constraining foundry expansion timelines.
- AEC-Q101 Automotive Qualification Duration:Extended stress-test cycles for high-temperature operation delay new product introductions by 18-24 months.
- Legacy Silicon Supply Chain Disentanglement:Established distributor relationships and qualified vendor lists resist rapid reconfiguration toward compound semiconductor suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Semiconductor Diode Market |
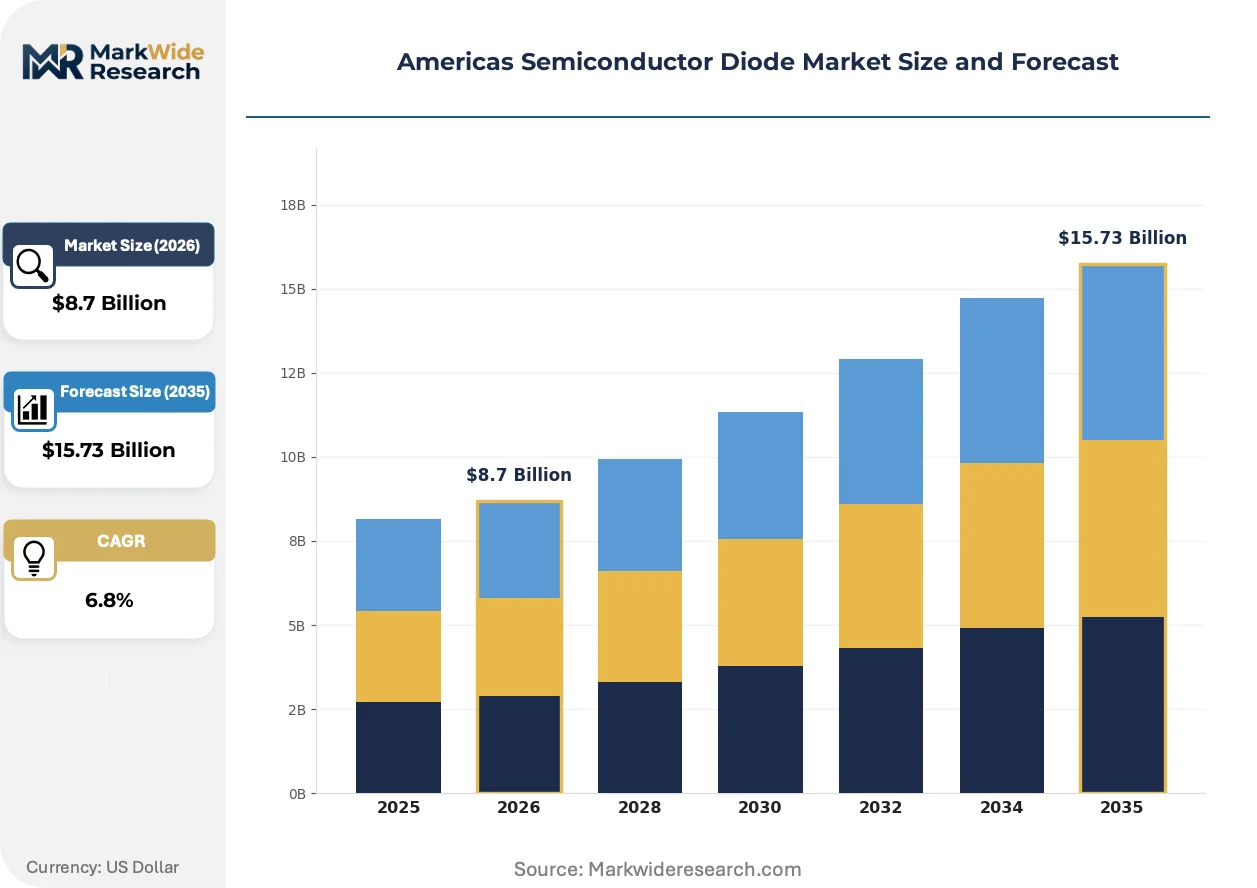
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectifier Diodes, Zener Diodes, Schottky Diodes, Laser Diodes End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Technology: Silicon, Gallium Nitride, SiC, Compound Semiconductors Application: Power Supply, Signal Processing, Voltage Regulation, RF Systems |
| Companies Covered | Central Semiconductor Corp., Diodes Incorporated, Infineon Technologies AG, Littelfuse Inc., ON Semiconductor Corporation, Vishay Intertechnology, Inc., Microchip Technology Inc., NXP Semiconductors N.V., Toshiba Electronic Devices & Storage Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Semiconductor Diode Market Trends and Innovations
Active material substitution and procurement centralization are restructuring competitive positioning across the Americas diode value chain, with efficiency mandates and buyer consolidation acting as twin accelerants.
Silicon carbide Schottky diodes are collapsing reverse recovery loss limitations in high-frequency power conversion. Datacenter hyperscalers and EV charger OEMs now specify SiC primary rectification as standard above 10kW power levels. This technology transition is collapsing the addressable market for ultrafast silicon recovery diodes in applications above 400V bus architectures.
US EPA ENERGY STAR specifications and FCC electromagnetic compatibility standards are tightening simultaneously, forcing dual-certification investments. Power supply manufacturers must validate conducted emissions and efficiency metrics through integrated testing protocols. Industrial and consumer electronics segments bear the heaviest compliance burden, with many suppliers consolidating product families to reduce certification matrix complexity.
Direct OEM procurement from foundry-qualified sources is displacing traditional electronics distribution for high-volume automotive and industrial accounts. Tier-one buyers now negotiate wafer-level supply agreements, bypassing authorized distributors for strategic diode categories. This channel compression is most visible in Michigan and California automotive engineering centers, where procurement teams maintain vendor engineering staff on-site.
Americas Semiconductor Diode Market Segmentation
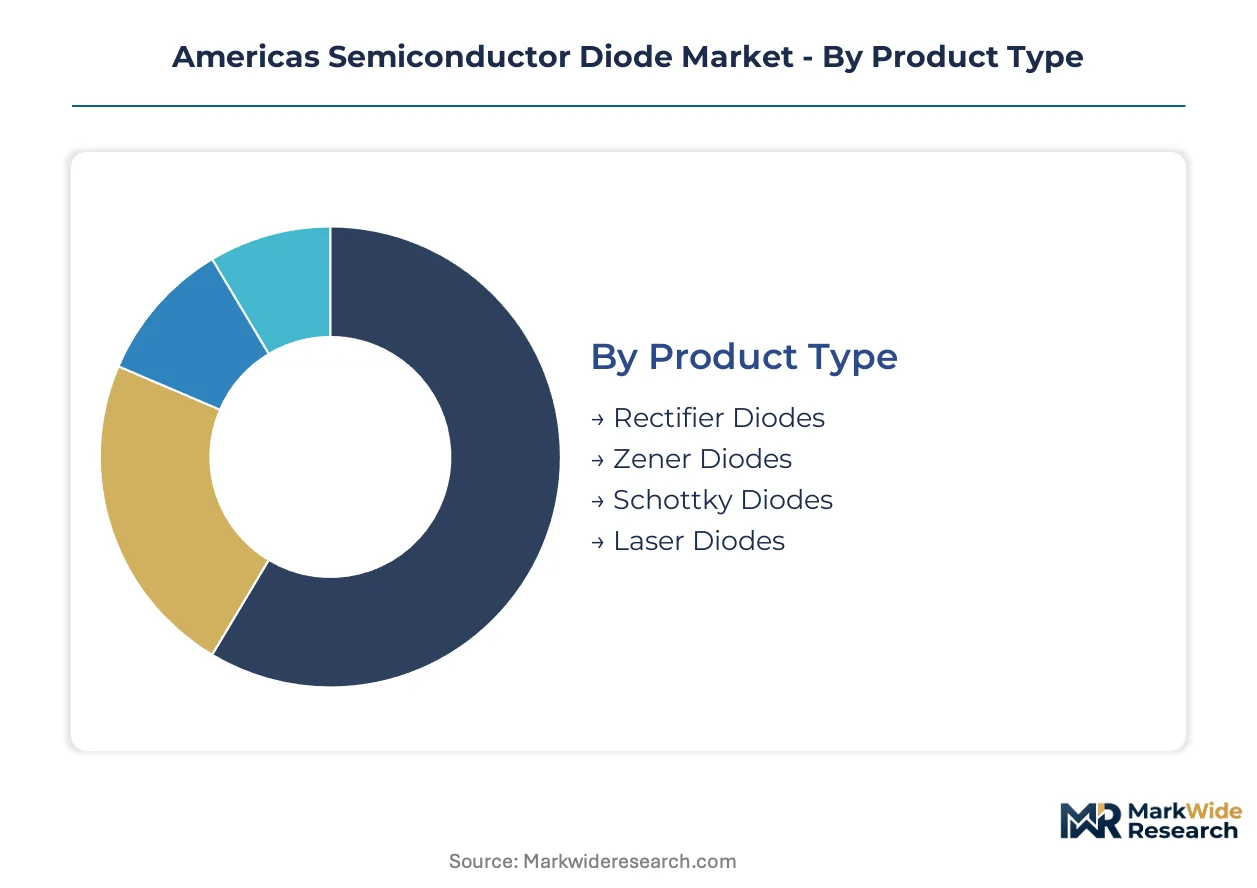
Semiconductor diode procurement patterns diverge sharply across application voltage, switching frequency, and thermal operating envelopes. Understanding these segment boundaries clarifies why SiC and GaN technologies command premium positioning while silicon retains cost-driven volume.
Product Type:
Rectifier and Schottky variants anchor opposite ends of the power-frequency spectrum, with Zener and laser diodes serving specialized protection and optoelectronic functions.
- Rectifier Diodes:Standard p-n junction devices handle high-current AC-DC conversion in industrial motor drives and grid-tied inverters. Demand concentrates in Texas and Arizona manufacturing clusters where EPA efficiency mandates accelerate SiC substitution above 400V bus architectures.
- Schottky Diodes:Metal-semiconductor junction construction delivers sub-50ns switching speeds with minimal reverse recovery losses. Datacenter hyperscalers in Virginia and California now specify SiC Schottky primary rectification as standard above 10kW power levels.
- Zener Diodes:Heavily doped p-n junctions exploit reverse breakdown for precise voltage clamping across automotive ECU protection circuits.
- Laser Diodes:Stimulated emission devices convert electrical input to coherent optical output for fiber-optic telecommunications infrastructure.
The dominant share belongs to Rectifier Diodes, while Schottky Diodes is closing the gap fastest.
End User:
Automotive and industrial buyers drive compound semiconductor adoption through direct foundry procurement, while consumer electronics and telecom retain distributor-mediated sourcing.
- Automotive:Traction inverters, onboard chargers, and DC-DC converters demand AEC-Q101 qualified diodes rated for 175°C junction temperatures. Michigan and California engineering centers consolidate vendor relationships through wafer-level supply agreements.
- Industrial Automation:Motor drives, welding equipment, and uninterruptible power supplies require robust rectification across 480V three-phase inputs. Mexico nearshoring expansion captures USMCA tariff advantages for power module assembly serving this segment.
- Consumer Electronics:Smartphone chargers and laptop adapters prioritize cost-optimized silicon superjunction devices over efficiency premiums.
- Telecommunications:Base station power amplifiers and optical transceivers specify GaN diodes for high-frequency RF switching applications.
Automotive captures the steepest expansion trajectory as EV powertrain electrification accelerates diode procurement consolidation.
Technology:
Substrate material selection determines efficiency benchmarks, thermal performance, and foundry capacity allocation across the Americas supply base.
- Silicon:Mature 8-inch wafer processing supports cost-sensitive applications below 200V operating voltages. Industrial motor drive segments retain silicon IGBT-diode pairings despite efficiency penalties from compound semiconductor alternatives.
- Silicon Carbide:Wide bandgap properties enable 10x faster switching with 70% lower switching losses than silicon equivalents. Texas-Arizona fabrication clusters anchor domestic SiC substrate processing and backend packaging capacity.
- Gallium Nitride:Heterostructure epitaxy delivers highest electron mobility for sub-100V high-frequency converters. Single-source foundry concentration with select North American suppliers creates supply vulnerability for GaN device procurement.
- Compound Semiconductors:Gallium arsenide and indium phosphide substrates serve specialized optoelectronic and millimeter-wave applications.
Silicon maintains volume dominance, though SiC is gaining share fastest as datacenter and EV charger OEMs prioritize reduced switching losses.
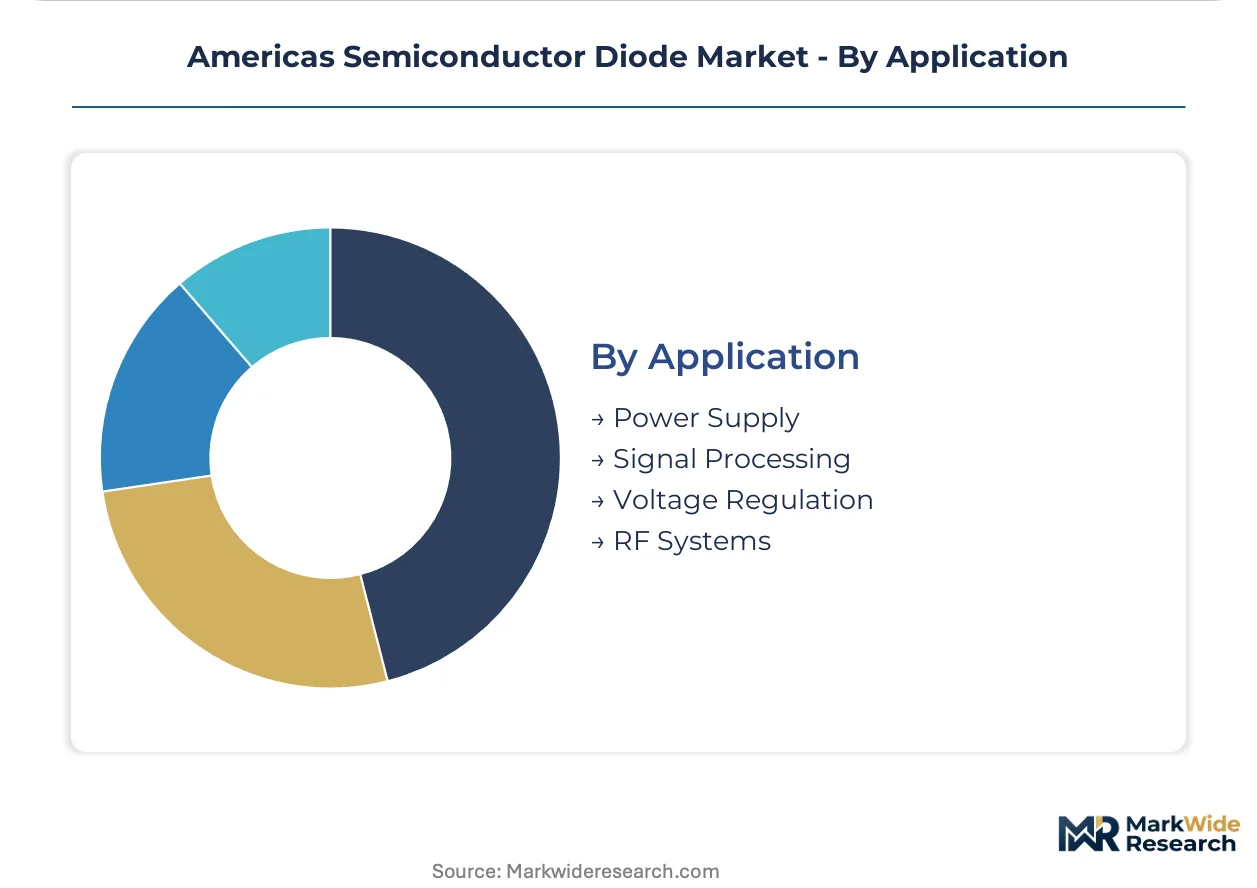
Application:
Voltage and frequency requirements stratify diode selection across power conversion, signal integrity, and electromagnetic compatibility functions.
- Power Supply:AC-DC and DC-DC conversion stages demand rectifier and Schottky devices across consumer, industrial, and automotive ratings. FCC electromagnetic compatibility standards and EPA ENERGY STAR specifications force dual-certification investments for power supply manufacturers.
- RF Systems:Radar, satellite communications, and 5G base stations require low-noise, high-linearity diode performance. Vishay Intertechnology dominates specialty portfolios for aerospace and defense end users in this application.
- Voltage Regulation:Linear regulators and switching controllers employ Zener and reference diodes for feedback loop stabilization.
- Signal Processing:Demodulation, mixing, and detection circuits utilize small-signal diodes for analog front-end functions.
Power Supply commands the largest revenue pool, while RF Systems is climbing the fastest as defense and telecommunications infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach-Los Angeles complex underwrites California's semiconductor logistics hub status, channeling Asian substrate imports into domestic packaging facilities. This maritime infrastructure anchors Americas diode supply chain resilience.
United States
EPA ENERGY STAR specifications and FCC electromagnetic compatibility standards tighten certification burdens for power supply manufacturers. Texas and Arizona fabrication clusters concentrate SiC substrate processing capacity. Michigan and California automotive engineering centers consolidate vendor relationships through direct wafer-level procurement agreements.
Mexico
Automotive Tier-1 suppliers relocate power module assembly to capture USMCA tariff advantages and shorten logistics loops. The national energy regulator imposes conformity protocols influencing manufacturing location decisions. Nuevo León and Bajío Region industrial corridors attract backend packaging investment from US-based device manufacturers.
Canada
Grid-scale energy storage integration creates demand for high-reliability rectifier diodes in bidirectional power conversion. Health Canada and PMRA coordinate electromagnetic emissions standards with US FCC benchmarks. Ontario's technology corridor hosts power electronics R&D facilities serving North American utility customers.
Brazil
Telecommunications infrastructure investment accelerates GaN diode procurement for 5G base station power amplifiers. ANVISA and the national telecommunications agency impose parallel conformity protocols affecting import certification timelines. São Paulo industrial districts concentrate consumer electronics assembly retaining cost-optimized silicon device demand.
Chile
Mining electrification programs drive rectifier diode consumption for haul truck and processing equipment power systems. The central bank's macroprudential frameworks influence capital equipment import financing. Santiago-Valparaíso logistics corridor channels device shipments to Andean mining operations.
Americas Semiconductor Diode Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated fabricators with captive substrate processing and foundry-qualified packaging capabilities. Tier-one automotive and industrial buyers compress distribution channels through direct procurement relationships. Two strategic archetypes dominate: compound semiconductor specialists commanding premium positioning in high-frequency applications, and diversified component houses leveraging scale across silicon legacy portfolios. Capacity expansion and strategic foundry partnerships represent the dominant competitive vectors as OEMs requalify supply bases.
Among North American-anchored suppliers, ON Semiconductor Corporation and Vishay Intertechnology, Inc. exemplify divergent positioning archetypes. ON Semiconductor occupies the vertically integrated fabrication tier with domestic substrate processing networks. Vishay Intertechnology represents the specialty component house model, concentrating portfolio breadth for aerospace and defense qualification requirements. Infineon Technologies AG anchors the European-originated technology leadership position, extending SiC and GaN process expertise into Americas power electronics applications through regional engineering presence.
| Leading Market Players |
|---|
| Central Semiconductor Corp. |
| Diodes Incorporated |
| Infineon Technologies AG |
| Littelfuse Inc. |
| ON Semiconductor Corporation |
| Vishay Intertechnology, Inc. |
| Microchip Technology Inc. |
| NXP Semiconductors N.V. |
| Toshiba Electronic Devices & Storage Corporation |
| Others |
Pricing and Supply Chain Analysis
Texas-Arizona fabrication clusters concentrate SiC substrate processing capacity, granting domestic device manufacturers pricing leverage over importers facing logistics premiums and tariff exposure. Foundry-qualified packaging capabilities in these states compress cost structures for automotive OEMs negotiating wafer-level supply agreements.
Pricing Analysis
Three-tier pricing structure across AEC-Q101 automotive grade, industrial qualification, and consumer-grade silicon separates premium SiC Schottky diodes from standard silicon rectifiers and economy Zener devices. Price differentiation hinges on junction temperature ratings and EPA ENERGY STAR certification status. Cost compression in consumer-grade tiers is intensifying as Chinese silicon superjunction devices penetrate smartphone charger markets. Industrial motor drive buyers exhibit highest price sensitivity, while datacenter hyperscalers absorb efficiency premiums without volume negotiation.
Supply Chain Analysis
Extended payment terms from automotive Tier-1 suppliers now stretch to 120 days, forcing foundries to utilize supply-chain finance facilities. Raw material sourcing draws from South African SiC crystal boule suppliers, Taiwanese GaN-on-silicon epitaxy houses, and Arizona-based silicon wafer reclaimers. Single-source vulnerability concentrates in North American GaN epitaxy capacity. Distribution runs through direct OEM procurement channels bypassing traditional electronics distributors for high-volume automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas semiconductor diode market sits in early-cycle expansion as EV powertrain electrification penetrates below 15% of regional vehicle production. SiC and GaN substrate transitions create displacement opportunities against legacy silicon incumbent positions.
For Market Incumbents: Pre-empt Chinese silicon superjunction encroachment by accelerating AEC-Q101 qualification timelines for SiC Schottky portfolios. Secure captive supply of South African SiC crystal boules through long-term offtake agreements. Channel control through on-site vendor engineering staff at Michigan automotive centers defends against distributor disintermediation. For New Entrants and Emerging Players: Mexico's Nuevo León industrial corridor offers underpenetrated backend packaging capacity for power module assembly serving USMCA tariff-advantaged supply chains. Target grid-scale energy storage inverter manufacturers with bidirectional rectifier diode solutions. Go-to-market leverage rests on IRA domestic content bonus qualification for US-based testing and packaging operations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compound semiconductor specialists with foundry-qualified packaging capabilities over diversified silicon legacy houses. Long-term viability over a multi-year horizon hinges on substrate process engineering talent retention. Watch SiC wafer pricing volatility as the inflection signal for margin compression or expansion across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Process Engineering Talent Acquisition | SiC and GaN device physics expertise concentrates with RF and LED industry veterans, constraining expansion timelines. |
| AEC-Q101 Automotive Qualification Investment | Extended 175°C junction temperature stress-test cycles delay new product introductions by 18-24 months. |
| Direct OEM Procurement Channel Development | Tier-one automotive buyers in Michigan and California consolidate vendor relationships through wafer-level supply agreements. |
| IRA Domestic Content Bonus Localization | US-based diode packaging and testing operations qualify for clean energy tax credit incentives. |
| Mexico Nearshoring Power Module Assembly | Nuevo León and Bajío Region corridors capture USMCA tariff advantages for automotive Tier-1 suppliers. |
Research Methodology
Operator-level perspectives from foundry process engineers, automotive Tier-1 procurement directors, and power electronics design engineers anchored the qualitative base. Secondary validation drew from SEC 10-K filings, EPA ENERGY STAR certification databases, and USMCA customs trade records. Bottom-up wafer demand modeling triangulated against top-down OEM procurement budget disclosures.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions spanned substrate material, application voltage tier, and end-use industry vertical. CAGRs derived from regression analysis of historical pricing elasticity and foundry capacity utilization rates. Forecast inputs incorporated SiC wafer supply constraints and AEC-Q101 qualification duration assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion moves by vertically integrated compound semiconductor specialists would shift outcomes. Macroeconomic deviation, regulatory modification to IRA domestic content rules, or breakthrough silicon carbide substrate cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market