
 Global Bipolar Power Transistor Market | 2026-2036
Global Bipolar Power Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bipolar Power Transistor Market Foresight
Software-defined thermal management and predictive maintenance subscriptions is recalibrating how bipolar power transistor vendors monetize hardware relationships. STMicroelectronics leverages its European fabrication network to sustain long-term supply agreements with industrial automation OEMs. Infineon Technologies anchors high-voltage IGBT portfolios through captive silicon carbide wafer capacity. ON Semiconductor differentiates by competing aggressively in automotive-qualified discrete packages for electrified powertrains.
A bipolar power transistor is a three-terminal semiconductor device employing alternating p-type and n-type doping layers to amplify or switch electrical signals, typically handling collector-emitter voltages from 40V to over 1,200V and continuous currents exceeding 100A in power modules. Its primary purpose centers on efficient power conversion and motor control across industrial, automotive, and energy systems where linear or switching operation demands precise current handling. Insulated Gate Bipolar Transistors capture the dominant value share due to their fusion of MOSFET gate control with bipolar conduction efficiency in medium-to-high voltage applications. Silicon carbide technology represents the fastest-expanding material platform as device makers push thermal performance beyond silicon theoretical limits. Consumer electronics applications remain mature with thinning margins, while renewable energy inverters and railway traction systems concentrate premium pricing power.
FDA medical device regulations, EU RoHS substance restrictions, and China's GB standards for electronic products collectively shape material selection, reliability testing protocols, and market access documentation across bipolar power transistor supply chains. Japan's METI energy efficiency frameworks and South Korea's MFDS-equivalent industrial safety requirements further segment qualification burdens by destination market. Stakeholders must monitor wafer substrate availability and evolving wide-bandgap material certifications to preserve design-win momentum across electrification end markets.
Market Dynamics
Silicon carbide substrate availability is compressing design cycles across electrification applications while China's dual carbon goals and EU efficiency mandates force simultaneous compliance recalibration.
Growth Catalysts
- EU RoHS substance restrictions:OEMs are accelerating qualification of lead-free packaging variants to maintain access across European industrial automation markets.
- Electric vehicle traction inverters:Silicon carbide technology adoption in 800V architectures is pulling demand for high-voltage discrete devices capable of switching above 100kHz.
- East Asian manufacturing clusters:Power semiconductor fabs in Japan and South Korea anchor captive supply chains that reduce procurement lead times for tier-one automotive suppliers.
Market Restraints
- Silicon carbide wafer supply concentration:Substrate fabrication capacity remains concentrated among a handful of specialized crystal growth facilities, creating input bottlenecks for device makers.
- Wide-bandgap material qualification timelines:Automotive AEC-Q101 certification for silicon carbide discretes extends 18-24 months, freezing design-win windows.
- Gallium nitride substitution threat:GaN HEMTs are capturing sub-650V applications where switching frequency outweighs voltage blocking requirements.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic assembly and test incentives are attracting packaging investments that could serve nearby industrial automation demand.
- Railway traction electrification:European and Asian rail operators are replacing legacy thyristor systems with IGBT-based converters, opening refurbishment contracts.
- Software-defined thermal management:Predictive maintenance subscriptions bundled with power modules are creating recurring revenue streams alongside hardware sales.
Industry Challenges
- Power electronics packaging engineering talent:The specialized skill set combining thermal simulation, wire bonding, and ceramic substrate design faces acute scarcity across all major manufacturing regions.
- Legacy system integration complexity:Industrial motor drive retrofits require mechanical and electrical interface adaptation that extends commissioning timelines and strains field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bipolar Power Transistor Market |
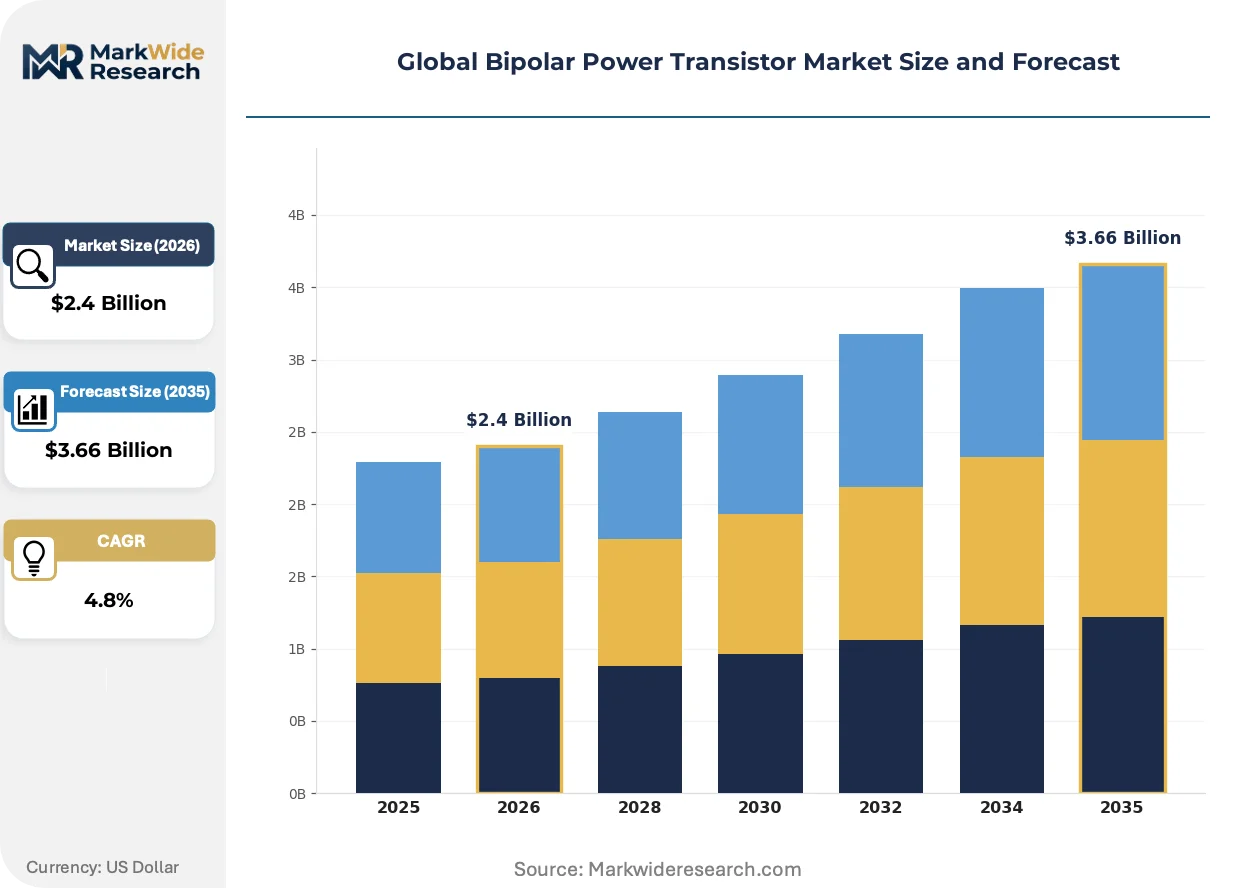
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
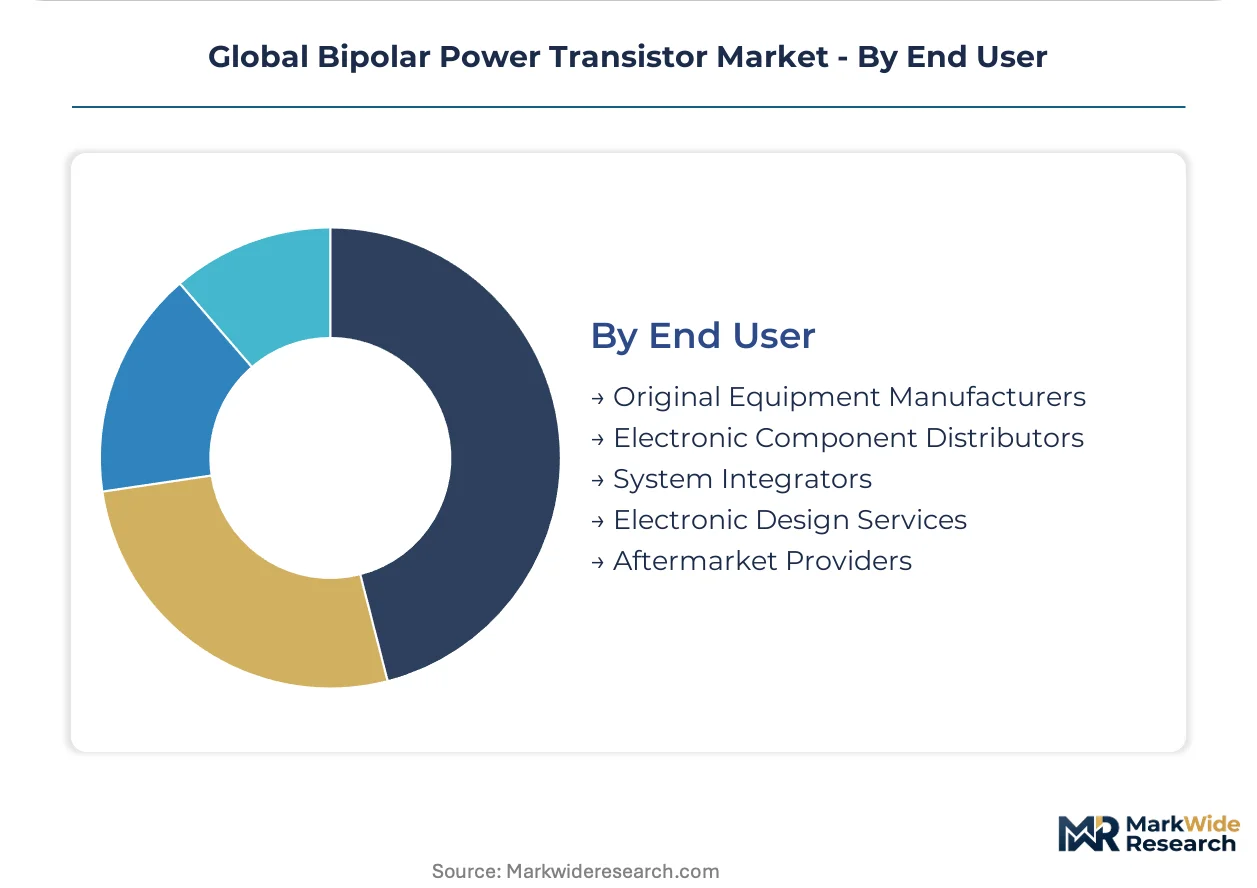
| Segmentation | Product Type: NPN Transistor, PNP Transistor, Darlington Transistor, Insulated Gate Bipolar Transistor, Others Technology: Silicon, Silicon Carbide, Gallium Nitride, Germanium, Gallium Arsenide Application: Consumer Electronics, Telecommunications, Industrial Automation, Aerospace & Defense, Renewable Energy, Railways End User: Original Equipment Manufacturers, Electronic Component Distributors, System Integrators, Electronic Design Services, Aftermarket Providers |
| Companies Covered | STMicroelectronics, ON Semiconductor (onsemi), Nexperia, Infineon Technologies, TT Electronics, Sanken Electric Co., Ltd., Renesas Electronics Corporation, Toshiba Electronic Devices, Diodes Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bipolar Power Transistor Market Shifts & Advancements
Material platform transitions and regulatory efficiency mandates are compressing traditional silicon device lifecycles while reshaping how vendors monetize hardware relationships through service layering.
Silicon carbide MOSFET technology is unifying gate drive compatibility with existing IGBT control architectures while delivering superior thermal performance. Automotive inverter engineers are adopting hybrid module designs that pair silicon carbide switches with silicon IGBT antiparallel diodes during this transition phase. The technology is unifying previously separate voltage classes into consolidated platform families that reduce SKU complexity for power module manufacturers.
China's GB standards for electronic products are tightening standby power consumption limits across industrial equipment categories. Domestic appliance and machine tool manufacturers must redesign drive electronics to comply with tiered efficiency grades that phase in through 2027. High-voltage motor control applications face the steepest redesign requirements as existing silicon bipolar devices approach theoretical loss limits.
Subscription-based thermal monitoring services are displacing traditional warranty coverage in premium power module segments. Industrial automation OEMs in Germany and Japan are piloting sensor-embedded packages that feed operational data to cloud analytics platforms. Railway traction system operators represent the most advanced adopters, with several European networks now requiring predictive maintenance capabilities as a procurement qualification criterion.
Global Bipolar Power Transistor Market Segmentation

Procurement patterns across the bipolar power transistor market diverge sharply by thermal performance requirements and voltage class. Buyers prioritize material platform compatibility with existing gate drive architectures while navigating qualification timelines that stretch across automotive and industrial certification regimes.
Product Type:
System architects select device topologies based on current gain requirements and switching frequency demands in target power conversion stages.
- Insulated Gate Bipolar Transistor:These devices merge MOSFET gate control with bipolar conduction efficiency, enabling switching above 20kHz in 600V to 1,700V classes. Demand concentrates in Japanese and South Korean automotive inverter supply chains where 800V electrification architectures require high-voltage discrete devices. EU efficiency mandates and China's dual carbon goals are compressing silicon IGBT lifecycles while expanding silicon carbide hybrid module adoption.
- Darlington Transistor:Cascaded NPN-PNP configurations deliver current gains exceeding 1,000, reducing base drive requirements in linear audio amplifiers and low-frequency motor controls. Industrial automation OEMs in Germany specify these devices for legacy servo drive retrofits where redesign costs outweigh efficiency gains. METI energy efficiency frameworks in Japan are phasing out Darlington configurations in new equipment designs above 3kW.
- NPN Transistor:Electron-majority carrier devices dominate switching applications below 200V with faster switching speeds than PNP equivalents.
- PNP Transistor:Hole-majority carrier construction suits high-side switching configurations in complementary push-pull amplifier stages.
- Others:Specialized configurations including Sziklai pairs and composite devices address niche thermal management requirements.
Volume sits with Insulated Gate Bipolar Transistor; growth tilts toward silicon carbide-enhanced variants.
Technology:
Material platform selection determines thermal performance ceilings and switching loss characteristics across voltage classes.
- Silicon Carbide:Wide-bandgap substrates enable junction temperatures above 175°C and switching frequencies beyond 100kHz, collapsing magnetic component sizes in traction inverters. China's dual carbon goals and EU Green Deal efficiency mandates are accelerating automotive qualification timelines for 1,200V discrete devices. Silicon carbide wafer supply concentration among specialized crystal growth facilities is extending lead times for device makers.
- Silicon:Mature epitaxial growth infrastructure and established AEC-Q101 qualification databases sustain cost advantages in sub-100kHz industrial motor drives. East Asian manufacturing clusters in Japan and South Korea anchor captive silicon wafer supply chains that reduce procurement lead times. GB standards in China are tightening standby power limits that erode silicon's efficiency competitiveness below 650V.
- Gallium Nitride:Two-dimensional electron gas channels enable switching above 1MHz in sub-650V applications where magnetic component miniaturization outweighs voltage blocking requirements.
- Germanium:Narrow bandgap construction persists in legacy audio amplifier and analog signal processing applications.
- Gallium Arsenide:Direct bandgap properties suit optoelectronic isolation and high-frequency RF power amplification.
Silicon retains volume dominance; silicon carbide claims the steepest expansion trajectory.
Application:
End-use thermal cycling requirements and voltage class specifications segment procurement priorities across equipment categories.
- Industrial Automation:Servo drives and variable frequency motor controls demand 600V to 1,200V IGBTs with short-circuit withstand capabilities above 10 microseconds. German and Japanese machine tool manufacturers specify automotive-qualified discrete devices to harmonize supply chains across factory automation and electrification divisions. EU RoHS substance restrictions are accelerating lead-free packaging qualification timelines.
- Renewable Energy:Photovoltaic inverters and wind turbine converters require 1,700V-class devices with reverse recovery softness to minimize EMI generation. Chinese inverter manufacturers are verticalizing into silicon carbide module assembly to secure substrate allocation. India's PLI scheme for semiconductors is attracting packaging investments targeting nearby solar installation growth.
- Consumer Electronics:Mature adapter and charger applications face margin compression from gallium nitride substitution below 100W.
- Telecommunications:Base station power supplies and RF amplifiers specify high-frequency bipolar devices for signal linearity.
- Aerospace & Defense:Radiation-hardened specifications and extended temperature ranges command qualification premiums.
- Railways:European and Asian rail operators are replacing legacy thyristor traction systems with IGBT-based converters.
Industrial Automation commands volume; Renewable Energy is climbing the fastest.
End User:
Purchasing authority and design influence determine channel strategy and technical support requirements.
- Original Equipment Manufacturers:Automotive and industrial equipment builders specify devices at the platform architecture stage, locking in multi-year supply agreements. STMicroelectronics and Infineon Technologies sustain long-term relationships through European fabrication networks and captive silicon carbide wafer capacity. OEMs in Japan and South Korea prioritize suppliers with local power semiconductor fabs to reduce logistics risk.
- Electronic Component Distributors:Arrow Electronics and Avnet maintain inventory buffers for small-to-medium industrial customers without direct foundry relationships. Distributor technical field support bridges capability gaps for machine tool retrofitters in Germany and Italy.
- System Integrators:Packaging power modules with thermal management and gate drive electronics adds value in custom motor control applications.
- Electronic Design Services:Consulting engineers specify devices for client reference designs that influence downstream procurement.
- Aftermarket Providers:Spare part distributors service legacy industrial equipment with end-of-life device sourcing.
Original Equipment Manufacturers concentrate volume; System Integrators are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication clusters supply the majority of bipolar power transistor output while European and North American markets absorb premium-grade devices for automotive and industrial automation. China's domestic inverter manufacturers are accelerating silicon carbide module assembly to reduce import dependency. India's emerging packaging investments target nearby industrial demand.
China
Domestic electric vehicle manufacturers are scaling 800V traction inverter production, pulling demand for high-voltage discrete devices. MIIT efficiency mandates and dual carbon goals are compressing silicon device qualification windows. Yangtze River Delta power semiconductor fabs are expanding silicon carbide wafer processing capacity to serve BYD and NIO supply chains.
Japan
Automotive inverter OEMs in Toyota and Honda supply chains specify hybrid silicon-silicon carbide modules for next-generation electrified platforms. METI energy efficiency frameworks are phasing out legacy Darlington configurations above 3kW. Kanto region power semiconductor fabs anchor captive supply relationships with tier-one automotive suppliers.
Germany
Industrial automation OEMs in Siemens and Bosch Rexroth networks demand automotive-qualified discrete devices to harmonize factory automation and electrification divisions. EU RoHS substance restrictions are accelerating lead-free packaging qualification timelines. Bavarian machine tool manufacturers specify short-circuit withstand capabilities above 10 microseconds for servo drive applications.
South Korea
Hyundai-Kia electrification programs are pulling 1,200V-class IGBT demand into domestic inverter supply chains. MFDS-equivalent industrial safety requirements segment qualification burdens for medical and automotive applications. Busan-Ulsan manufacturing clusters house power semiconductor fabs that reduce procurement lead times for domestic tier-one suppliers.
United States
Renewable energy inverter installers are specifying 1,700V-class devices with reverse recovery softness for utility-scale solar and wind conversions. IRA clean energy tax credits are accelerating domestic content requirements for power electronics. Texas and Arizona are attracting packaging investments to serve North American industrial automation demand.
Global Bipolar Power Transistor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across bipolar power transistor supply chains, with captive silicon carbide wafer capacity separating premium-tier participants from commodity assemblers. The vendor base clusters around three strategic archetypes: integrated device manufacturers with in-house epitaxial growth, fabless specialists outsourcing to foundry partners, and packaging houses adding thermal management value. Capacity expansion and strategic partnerships dominate competitive moves as substrate availability constrains output.
Among European integrated device manufacturers, STMicroelectronics and Infineon Technologies exemplify the captive-fabrication archetype through continental wafer networks. ON Semiconductor occupies a position bridging automotive-qualified discrete packaging with North American customer proximity. These three anchors represent divergent geographic and capability positioning within a market where silicon carbide substrate access determines design-win momentum.
| Leading Market Players |
|---|
| STMicroelectronics |
| ON Semiconductor (onsemi) |
| Nexperia |
| Infineon Technologies |
| TT Electronics |
| Sanken Electric Co., Ltd. |
| Renesas Electronics Corporation |
| Toshiba Electronic Devices |
| Diodes Incorporated |
| Others |
Supply & Pricing Matrix
Power electronics packaging engineering talent concentration in Japan and South Korea feeds labor-cost differentials that widen pricing-tier spreads between captive-fabrication premium modules and commodity-packaged discretes.
Pricing Analysis
Margin tightening in automotive-qualified IGBT modules reflects silicon carbide substrate scarcity and extended AEC-Q101 certification timelines. Contract-based long-term offtake agreements dominate, with price differentiation anchored in certification grade and volume scale. Cost-down pressure on standard silicon discretes accelerates because gallium nitride substitution erodes sub-650V positioning. Industrial automation OEMs exhibit highest price sensitivity; railway traction operators show lowest sensitivity given predictive maintenance bundling.
Supply Chain Analysis
Single-source vulnerability sits with specialized silicon carbide crystal growth facilities concentrated in the United States, Japan, and Germany. Device fabrication draws from silicon epitaxial wafers, ceramic substrates, and copper wire bonding materials. Tariff exposure on wide-bandgap substrate imports constrains European and Chinese module assemblers. Distribution runs through Arrow Electronics and Avnet inventory buffers for small-to-medium industrial customers without direct foundry relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as silicon carbide substrate scarcity forces weaker packaging houses without captive wafer access toward exit or acquisition.
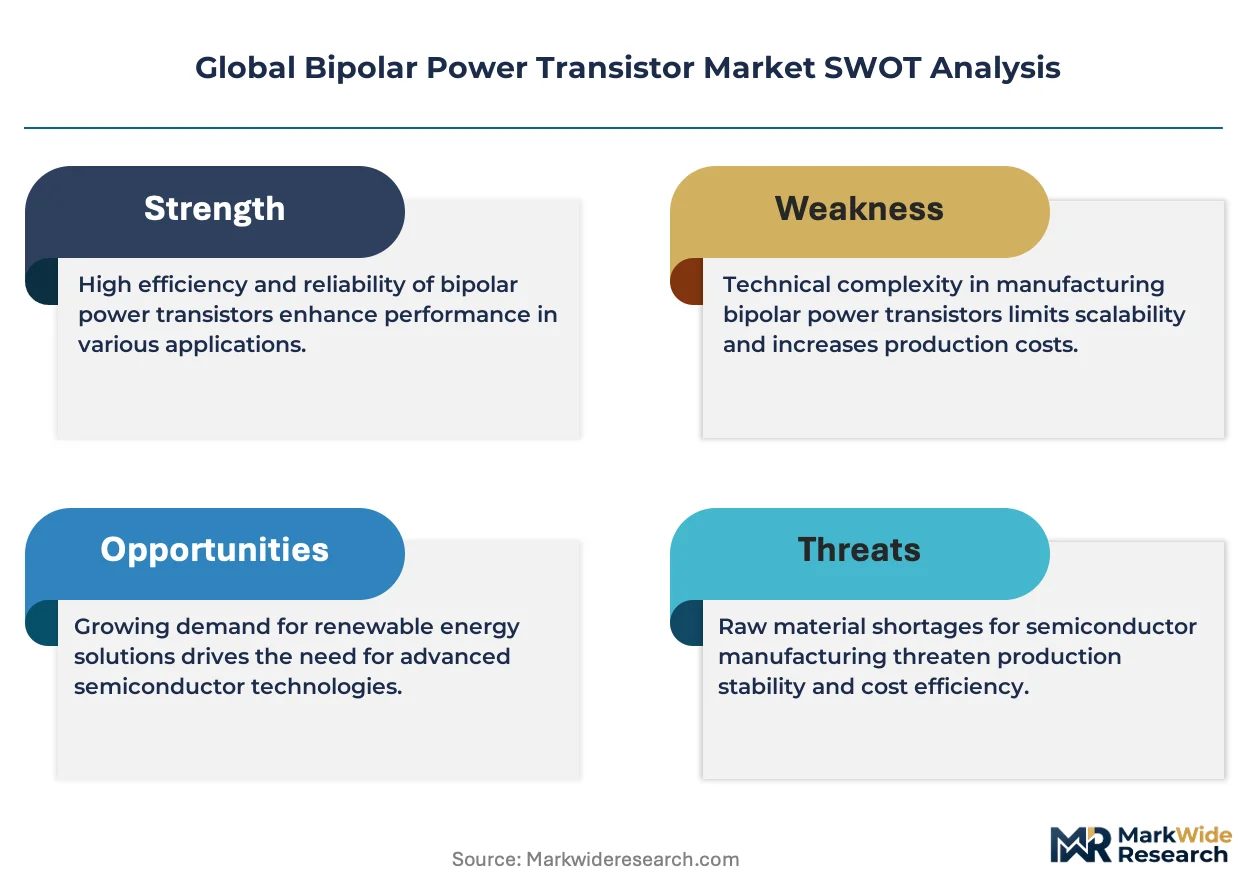
For Market Incumbents: Anchor long-term supply agreements with East Asian power semiconductor fabs to lock in silicon carbide allocation ahead of automotive platform freezes. Deepen backward integration into ceramic substrate design and thermal simulation capabilities to offset acute packaging engineering talent scarcity. Defend against gallium nitride substitution by accelerating hybrid module roadmaps that pair silicon IGBTs with silicon carbide antiparallel diodes.
For New Entrants and Emerging Players: Capture India's PLI scheme packaging investments targeting nearby industrial automation demand as the most penetrable geography. Exploit white-space in sensor-embedded power modules with predictive maintenance subscriptions for European railway operators. Pursue system integrator partnerships that bundle thermal management with gate drive electronics to bypass direct OEM qualification barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap packaging specialists possessing automotive AEC-Q101 certification databases given EU Green Deal efficiency mandate acceleration. Long-term viability favors participants with demonstrated design-win momentum across 800V electrification architectures. Monitor silicon carbide wafer supply allocation announcements from specialized crystal growth facilities as the critical inflection signal for module assembler output capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Wafer Capacity Expansion | Captive substrate supply secures design-win momentum across BYD and NIO 800V platforms. |
| Automotive AEC-Q101 Certification Investment | Extended 18-24 month timelines freeze competitor windows for qualified device portfolios. |
| Predictive Maintenance Subscription Launch | Recurring revenue streams displace traditional warranty coverage in German railway procurement. |
| India PLI Scheme Packaging Investment | Domestic assembly incentives attract capital serving nearby solar inverter demand growth. |
| Hybrid Silicon-Silicon Carbide Module Development | Gate drive compatibility preserves existing control architectures during material transition. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with power semiconductor fab operations directors, automotive inverter platform engineers, industrial automation procurement leads, and railway traction system maintenance heads. SEC 10-K disclosures, MIIT efficiency mandate documents, EU RoHS substance restriction updates, and Japan METI framework publications provided validation. Bottom-up demand modeling across voltage classes and applications triangulated against top-down fabrication capacity assessments.
Granularity-level modeling operated at the intersection of material platform, voltage class, and end-use thermal cycling requirements. Segmentation dimensions included product topology, substrate technology, application equipment category, and purchasing authority archetype. CAGRs derived from shipment volume trajectories and average selling price evolution across the projection horizon. Industry-specific forecast inputs encompassed silicon carbide wafer supply allocation schedules and automotive electrification platform ramp timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wide-bandgap material qualification timeline compression and gallium nitride substitution velocity in sub-650V classes. Forecasts reflect documented assumptions regarding substrate supply expansion and regulatory efficiency mandate phase-in schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market