
 Global Silicon Carbide Wafers Market | 2026-2036
Global Silicon Carbide Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicon Carbide Wafers Market Foresight
The EU Green Deal is realigning automotive supply chains toward silicon carbide power electronics. Wolfspeed, Inc. anchors North American substrate production through vertically integrated crystal growth operations. Coherent Corp. dominates materials science innovation for high-purity SiC boules. STMicroelectronics leverages European foundry partnerships to secure 6-inch wafer supply for EV inverters.
Silicon carbide wafers are monocrystalline substrates grown through physical vapor transport, typically achieving 4H polytype purity exceeding 99.9999 percent, engineered for high-temperature, high-voltage semiconductor applications in electric traction systems and grid infrastructure. The 6-inch diameter segment leads commercial volume as foundries transition from 4-inch legacy lines, while 8-inch pilot capacity concentrates margin pools among integrated device manufacturers. Physical vapor transport remains the dominant crystal growth method, though epitaxial growth commands premium pricing for RF device applications in defense and telecommunications.
FDA oversight of medical power supplies and EPA efficiency mandates for industrial motor drives shape North American qualification requirements, while REACH and RoHS compliance in Europe restrict heavy metal content in wafer processing chemicals. China's MIIT sets domestic content targets for SiC substrates under national semiconductor self-sufficiency directives. Stakeholders must monitor substrate diameter transitions, epitaxial layer thickness specifications, and regional subsidy regimes to align capacity investments with downstream qualification timelines.
Market Dynamics
Substrate diameter migration from 6-inch to 8-inch formats is compressing capital efficiency curves while concentrating margin capture among integrated device manufacturers with captive crystal growth operations.
Growth Catalysts
- EV powertrain electrification:Traction inverter demand from automotive OEMs in Germany, Japan, and the United States is pulling wafer consumption into dedicated supply agreements.
- EU Green Deal emissions mandates:Tightening CO2 standards for automotive fleets are forcing wide-bandgap semiconductor adoption in onboard charging systems.
- Physical vapor transport yield improvements:Defect density reduction in 4H polytype boules is expanding usable wafer area per crystal growth cycle.
Market Restraints
- High-purity graphite crucible supply:Chinese dominance in specialty carbon materials creates input cost volatility and single-source risk for crystal growth equipment.
- Epitaxial reactor capacity scarcity:Limited installed base of chemical vapor deposition tools constrains thick-drift-layer production for high-voltage devices.
- Silicon IGBT cost floor:Mature silicon power electronics retain price advantage in sub-800V applications, delaying SiC penetration in cost-sensitive segments.
Strategic Opportunities
- India automotive electrification:PLI scheme subsidies for domestic semiconductor manufacturing are attracting substrate qualification programs from tier-1 suppliers.
- Grid-scale energy storage:Utility inverter specifications above 1500V DC are mandating SiC device architectures for efficiency targets.
- RF defense applications:GaN-on-SiC epitaxial wafer demand from radar and electronic warfare programs is converging with telecommunications infrastructure buildouts.
Industry Challenges
- Crystal growth technician scarcity:Physical vapor transport process engineering expertise concentrates among a limited pool of specialists with decade-scale experience curves.
- Automotive AEC-Q101 qualification timelines:Extended stress-testing protocols for power discretes delay new substrate vendor entry by 18-36 months.
- 8-inch fab equipment retrofit costs:Legacy silicon lines require substantial capital outlay for SiC-compatible process tools and contamination control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicon Carbide Wafers Market |
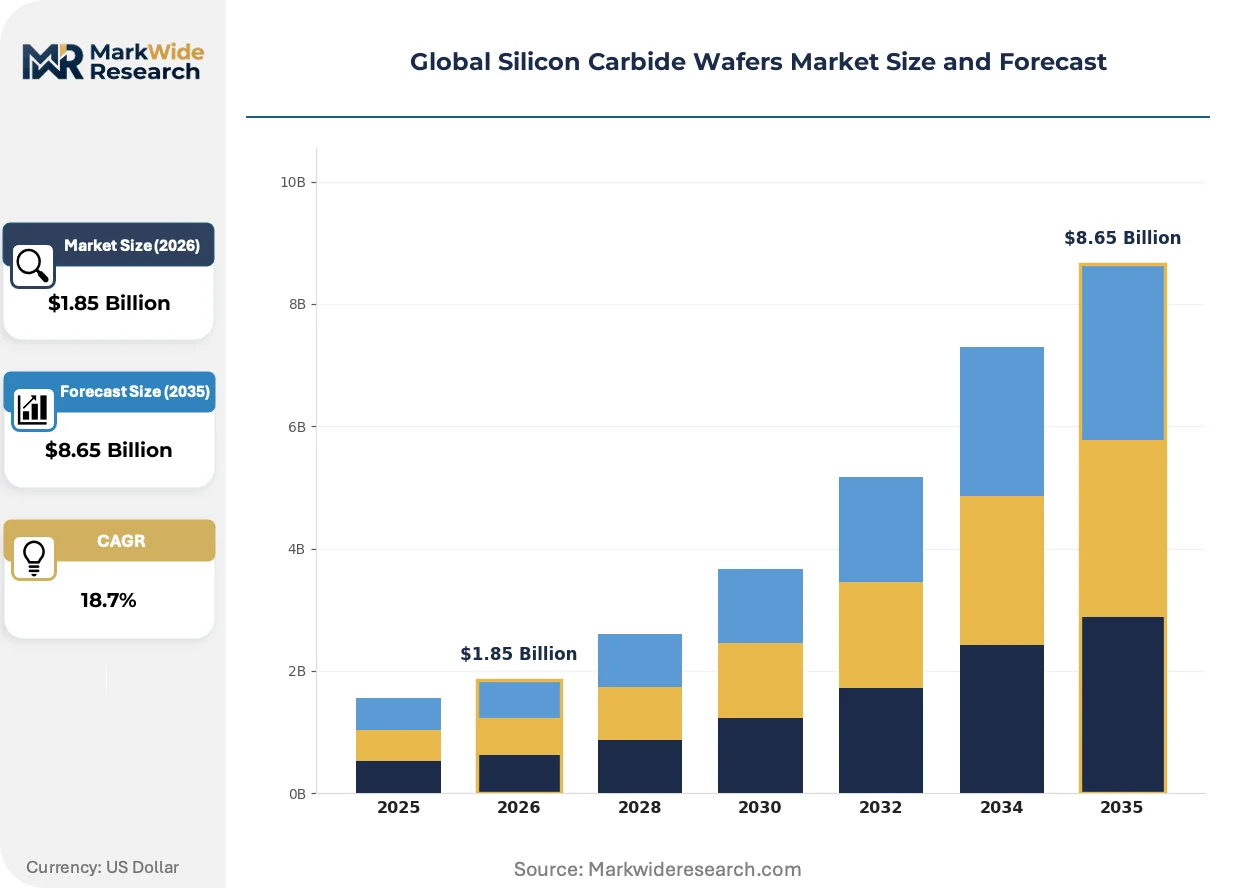
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4-inch, 6-inch, 8-inch, 12-inch Technology: Physical Vapor Transport, Chemical Vapor Deposition, Epitaxial Growth, Laser Lift-Off Application: Power Electronics, RF Devices, LED Lighting, Automotive Electronics, Aerospace Systems End User: Semiconductor Foundries, Power Module Manufacturers, LED Producers, Defense Contractors |
| Companies Covered | Wolfspeed, Inc., Coherent Corp., ROHM Co., Ltd., STMicroelectronics, Infineon Technologies AG, SK Siltron, Resonac Holdings Corporation, Xiamen Powerway Advanced Material Co., Ltd., SUMCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicon Carbide Wafers Market Shifts & Advancements
Wafer processing workflows are bifurcating between power electronics and RF applications, with divergent epitaxial specifications creating specialized equipment demand.
Advanced physical vapor transport systems with in-situ monitoring capabilities are converging with machine learning process control to reduce micropipe defect formation during boule growth. Automotive tier-1 suppliers in Germany and Japan are qualifying these enhanced substrates for 800V traction inverters ahead of 2025 model year ramps. The technology is converging with predictive maintenance algorithms that optimize thermal gradient profiles, compressing crystal growth cycle times.
China's MIIT domestic content directives are mandating substrate self-sufficiency ratios under national semiconductor independence frameworks. Local wafer manufacturers are securing preferential access to high-purity silicon carbide powder feedstock. The policy is concentrating capacity investments in 6-inch lines serving domestic EV and rail traction markets.
Long-term supply agreements are displacing spot market purchasing for automotive-qualified wafers. Tier-1 power module assemblers in the United States are locking multi-year substrate commitments with volume guarantees and price escalation clauses. The shift is most visible in inverter supply chains serving Detroit and Stuttgart manufacturing clusters.
Global Silicon Carbide Wafers Market Segmentation
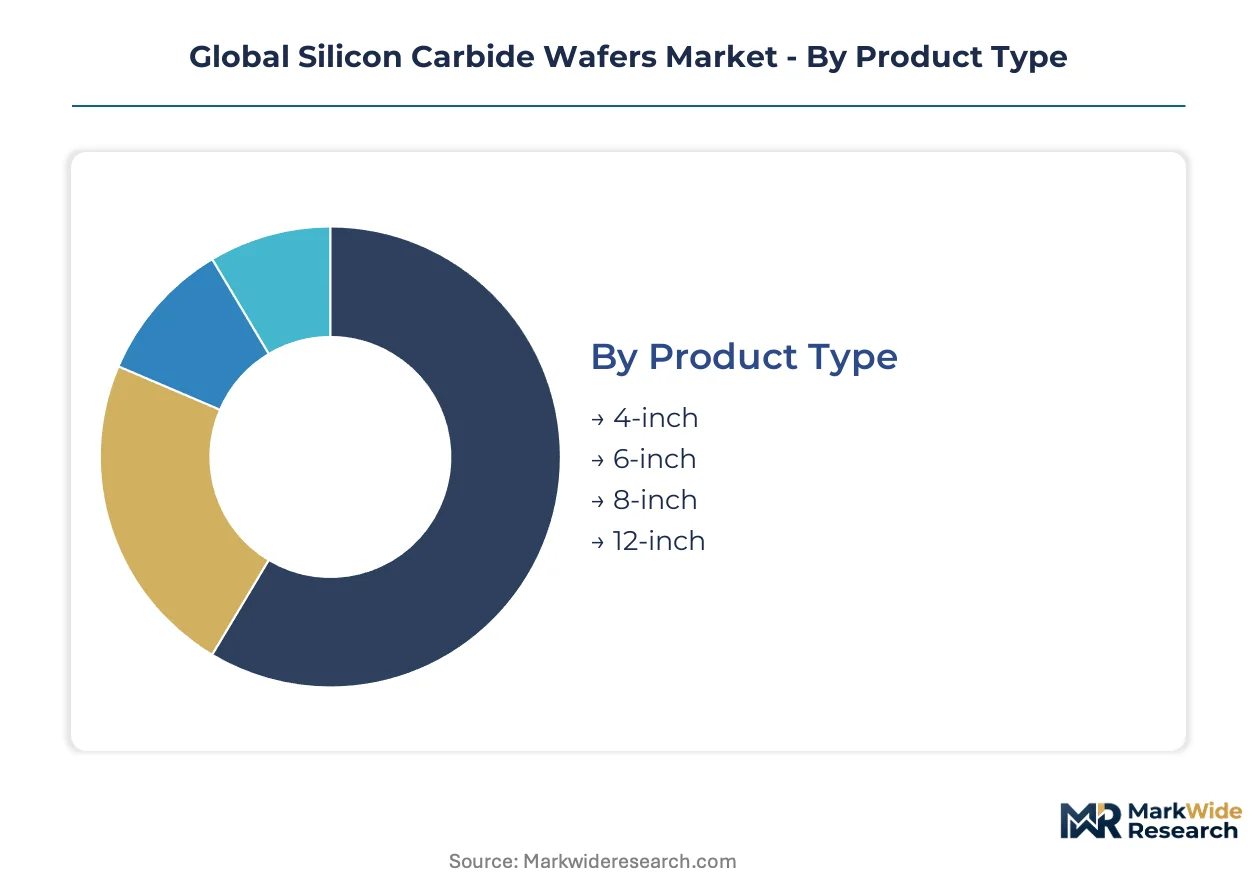
Silicon carbide wafer segmentation reveals distinct qualification pathways where automotive AEC-Q101 standards, defense MIL-PRF-38534 requirements, and telecommunications reliability protocols create divergent commercial entry barriers across diameter formats and growth technologies.
Product Type:
Wafer diameter segments carry differentiated certification burdens: automotive inverters demand AEC-Q101 qualified 6-inch substrates, while defense RF applications impose MIL-STD-883 screening on smaller formats.
- 4-inch:Legacy substrate format sustaining production lines for RF defense applications and specialty LED epitaxy. Demand concentrates in GaN-on-SiC radar modules from US and European defense contractors where MIL-PRF-38534 qualification timelines favor established supply relationships over diameter migration.
- 6-inch:Commercial volume leader dominating EV traction inverter supply chains. Foundries in Germany, Japan, and the United States are consolidating procurement around this format as AEC-Q101 qualification investments create switching costs for automotive tier-1 suppliers.
- 8-inch:Pilot production scale concentrating among integrated device manufacturers with captive crystal growth operations. The format is gaining traction in high-volume automotive programs where die-per-wafer economics offset retrofit capital requirements.
- 12-inch:Experimental scale limited to research consortiums and advanced development programs. The diameter remains pre-commercial with no qualified supply chains for power electronics or RF device manufacturing.
6-inch sits at the top of the volume ranking, with 8-inch climbing the fastest as IDMs commit capital to diameter transition roadmaps.
Technology:
Crystal growth methods stratify by capital intensity and end-use purity requirements, with physical vapor transport serving cost-sensitive power electronics and epitaxial growth commanding premium positioning in defense telecommunications.
- Physical Vapor Transport:Dominant boule growth technique achieving 4H polytype purity exceeding 99.9999 percent through controlled thermal gradient profiles. Capacity concentrates in vertically integrated operations serving automotive inverter markets where defect density reduction drives yield economics.
- Chemical Vapor Deposition:Thick-drift-layer production for high-voltage devices above 1200V blocking voltage. Reactor capacity scarcity in Germany and Japan is constraining supply expansion for grid-scale inverter applications.
- Epitaxial Growth:Premium-priced layer deposition for RF device applications in defense radar and 5G telecommunications infrastructure.
- Laser Lift-Off:Specialized substrate thinning technique enabling vertical device architectures with reduced thermal resistance.
Physical Vapor Transport dominates installed capacity, with Epitaxial Growth expanding most quickly in defense and telecommunications qualification programs.
Application:
Application segments diverge by voltage class and reliability tier, with automotive electronics imposing the most stringent traceability requirements through IATF 16949 supply chain standards.
- Power Electronics:Traction inverters, onboard chargers, and DC-DC converters for electric vehicle powertrains. Demand is concentrating in 800V architectures from German and US automotive OEMs where efficiency mandates under the EU Green Deal and EPA standards are accelerating wide-bandgap adoption.
- RF Devices:Radar systems, electronic warfare modules, and 5G base station power amplifiers. GaN-on-SiC epitaxial specifications from defense contractors in the United States and telecommunications equipment manufacturers in Japan are converging on common substrate requirements.
- LED Lighting:Solid-state lighting substrates for high-brightness applications.
- Automotive Electronics:Dedicated supply chains for AEC-Q101 qualified power discretes with extended stress-testing protocols.
- Aerospace Systems:Radiation-hardened device substrates for satellite power management and avionics.
Power Electronics holds the volume lead, with RF Devices gaining share fastest as defense and telecommunications procurement cycles align.
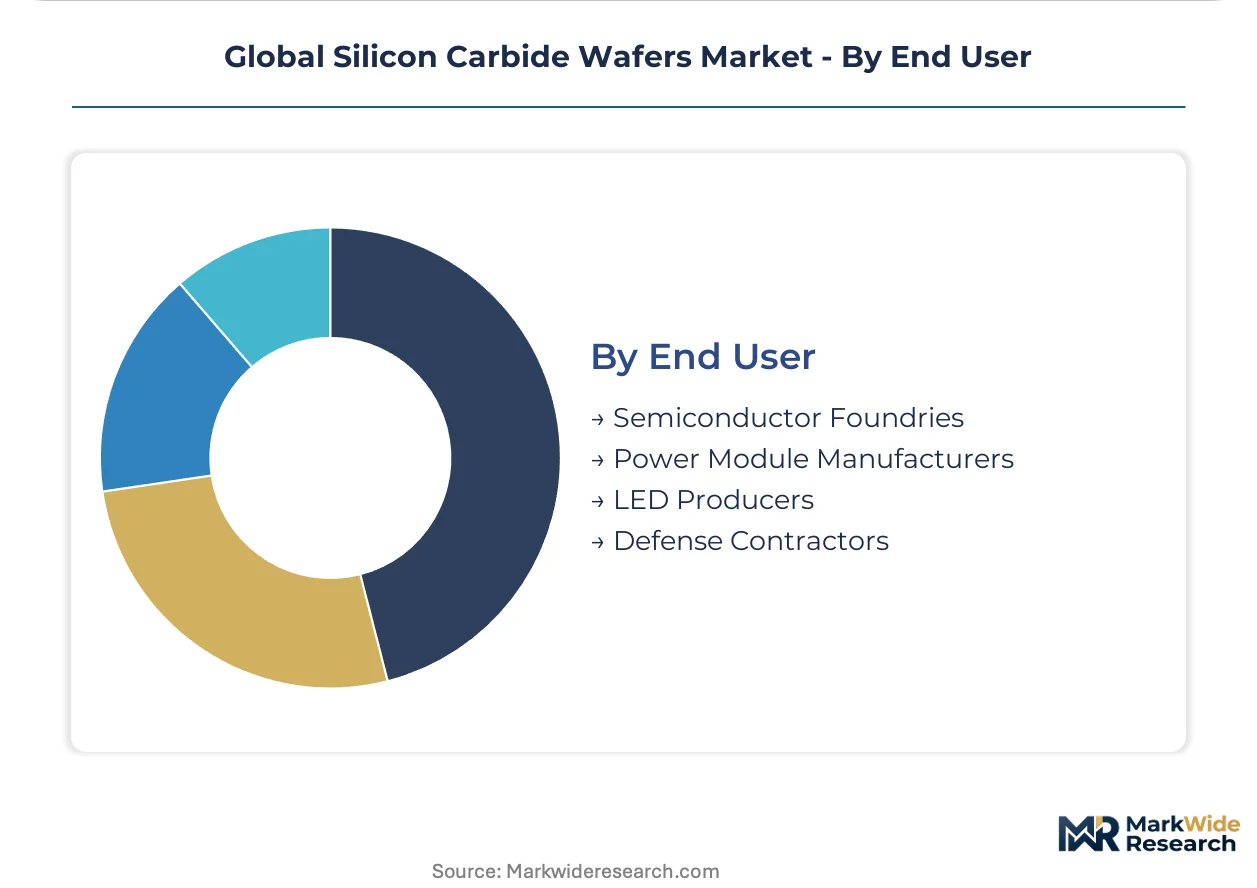
End User:
Customer type determines procurement structure, with foundries favoring spot purchasing flexibility and power module manufacturers locking long-term agreements to secure automotive qualification continuity.
- Semiconductor Foundries:Merchant wafer purchasers serving fabless design houses and integrated device manufacturers with excess capacity needs. Procurement patterns in Taiwan and South Korea favor quarterly price negotiations with volume flexibility clauses.
- Power Module Manufacturers:Tier-1 assemblers in Germany, Japan, and the United States securing dedicated supply agreements with substrate vendors. Multi-year contracts with price escalation mechanisms are displacing spot market purchasing for AEC-Q101 qualified material.
- LED Producers:Specialty substrate consumers for solid-state lighting applications.
- Defense Contractors:MIL-PRF-38534 qualified supply chains with traceability requirements through DFARS sourcing restrictions.
Power Module Manufacturers command the largest procurement volumes, with Semiconductor Foundries expanding most quickly as fabless power semiconductor design activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystal growth technicians with decade-scale experience curves concentrate in German, Japanese, and US industrial clusters, anchoring substrate production capacity across three continents.
United States
Detroit automotive OEMs and Austin semiconductor clusters are pulling wafer consumption through dedicated supply agreements for 800V traction inverters. EPA efficiency mandates for industrial motor drives shape qualification requirements for power electronics. Wolfspeed anchors North American substrate production through vertically integrated crystal growth operations in North Carolina.
Germany
Stuttgart manufacturing clusters and Munich-based automotive tier-1 suppliers are consolidating procurement around 6-inch AEC-Q101 qualified substrates. EU Green Deal emissions mandates tighten CO2 standards for automotive fleets, forcing wide-bandgap semiconductor adoption. Infineon Technologies AG exemplifies European foundry partnerships securing wafer supply for EV inverters.
Japan
Nagoya automotive electronics hubs and Tokyo-area semiconductor equipment manufacturers are driving epitaxial reactor demand for thick-drift-layer production. METI industrial policy supports domestic content targets for power semiconductor substrates. ROHM Co., Ltd. and Resonac Holdings Corporation occupy positions within the materials science tier serving RF defense applications.
China
Shanghai and Shenzhen EV manufacturing corridors are absorbing 6-inch wafer output from domestic substrate lines. MIIT domestic content directives mandate substrate self-sufficiency ratios under national semiconductor independence frameworks. Xiamen Powerway Advanced Material Co., Ltd. represents Chinese wafer manufacturers securing preferential access to high-purity silicon carbide powder feedstock.
South Korea
Seoul Capital Area semiconductor foundries and Busan-Ulsan automotive component clusters are qualifying SiC substrates for export-oriented power module assembly. Government semiconductor investment tax credits accelerate capacity buildout for wide-bandgap materials. SK Siltron anchors Korean substrate production serving merchant wafer markets.
Global Silicon Carbide Wafers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the silicon carbide wafer market. Vertically integrated crystal growth operations capture margin pools through captive substrate supply, while merchant vendors serve foundry flexibility requirements. Three archetypes dominate: integrated device manufacturers with in-house boule growth, specialty substrate pure-plays, and diversified materials science conglomerates. Capacity expansion and long-term supply agreement locking are the dominant competitive moves displacing spot market purchasing.
Among US-based integrated producers, Wolfspeed, Inc. exemplifies the vertically integrated archetype through crystal growth operations. Japanese specialists including ROHM Co., Ltd. and South Korea's SK Siltron occupy positions within the materials science tier serving divergent end-use qualification pathways.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| Coherent Corp. |
| ROHM Co., Ltd. |
| STMicroelectronics |
| Infineon Technologies AG |
| SK Siltron |
| Resonac Holdings Corporation |
| Xiamen Powerway Advanced Material Co., Ltd. |
| SUMCO Corporation |
| Others |
Supply & Pricing Matrix
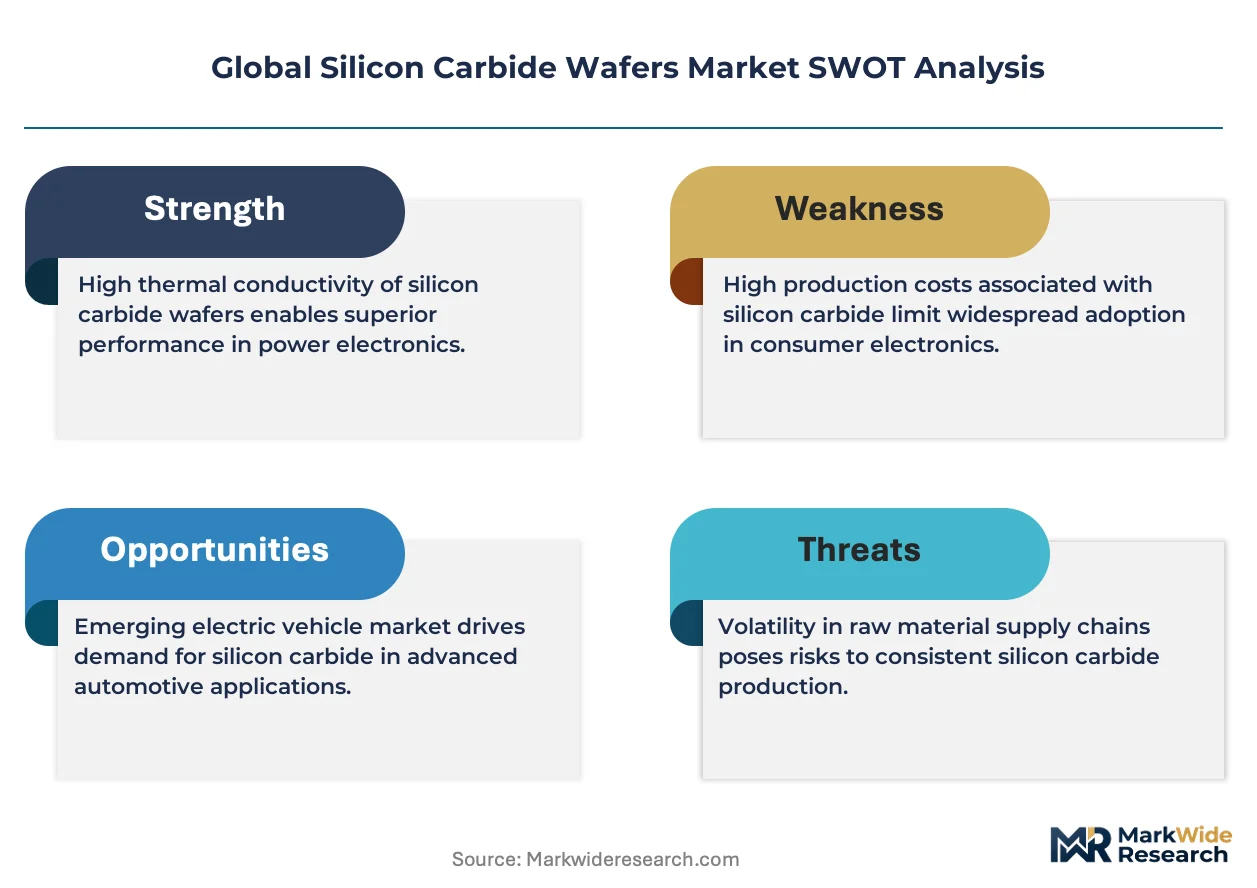
Automotive-grade AEC-Q101 certification separates premium 6-inch substrates from commodity RF-grade material, creating a bifurcation where qualified supply commands long-term offtake premiums while unqualified inventory trades in volatile spot markets. This tier divergence concentrates pricing power among vertically integrated producers with captive crystal growth operations in Germany, Japan, and the United States, while forcing merchant vendors to absorb feedstock cost volatility from Chinese graphite crucible suppliers.
Pricing Analysis
Bundled epitaxial layer deposition services trade at substantial premiums over bare substrate transactions, with thick-drift-layer CVD processing adding value for grid-scale inverter applications above 1200V. Three-tier pricing structure across automotive-qualified, industrial-grade, and RF-specialty levels reflects certification investment recovery timelines and defect density guarantees. Cost compression in 6-inch automotive tiers intensifies because foundries are consolidating procurement volumes under multi-year agreements with price escalation clauses tied to high-purity silicon carbide powder indices. Power module manufacturers in Detroit and Stuttgart exhibit lowest price sensitivity due to AEC-Q101 qualification switching costs, while merchant foundries in Taiwan and South Korea retain spot-market flexibility.
Supply Chain Analysis
Single-source vulnerability sits with Chinese producers of high-purity isostatic graphite crucibles essential for physical vapor transport crystal growth. Manufacturing capacity concentrates in Germany, Japan, and the United States for boule growth operations, while South Korea and Taiwan host epitaxial reactor clusters for thick-drift-layer processing. Raw material dependencies encompass high-purity silicon carbide powder feedstock, specialty carbon materials, and helium gas for crystal cooling systems. Tariff exposure on Chinese graphite imports threatens input cost stability for North American and European substrate producers. Distribution runs through direct long-term supply agreements from integrated device manufacturers to automotive tier-1 assemblers, displacing merchant spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicon carbide wafer market functions as a stable compounder anchored by irreversible EV powertrain electrification mandates across major automotive manufacturing clusters. Substrate demand exhibits low cyclicality because automotive platform decisions lock supply agreements across multi-year model generations.
For Market Incumbents:Cement AEC-Q101 qualification moats by accelerating 8-inch pilot line certification ahead of competitor entry timelines. Expand captive crystal growth capacity in North Carolina or Saxony to secure high-purity graphite crucible allocations before Chinese export restrictions tighten. Threat of silicon IGBT cost floors in sub-800V applications demands continuous defect density reduction to maintain die-per-wafer economics.
For New Entrants and Emerging Players:Direct-to-foundry digital procurement platforms offer a route to bypass entrenched supply agreements locking automotive tier-1 relationships. White-space concentrates in India PLI scheme qualification programs for domestic EV inverter substrate supply, and in grid-scale energy storage inverter specifications above 1500V DC requiring thick-drift-layer epitaxy. Target defense RF applications with GaN-on-SiC specifications where MIL-PRF-38534 traceability requirements favor new vendor entry over automotive qualification timelines.
For Investors and Strategic Acquirers:Consolidation pressure builds where automotive qualification investments exceed $50 million per substrate diameter transition, favoring acquisition of specialty substrate pure-plays over greenfield capacity builds. Long-term viability frames around 8-inch die economics and captive epitaxial reactor capacity serving 800V traction inverter ramps. Target acquisition archetype: vertically integrated 6-inch producers with established AEC-Q101 supply relationships and transferable technician expertise pools. Signal to monitor: automotive OEM announcements of 1200V platform architectures accelerating thick-drift-layer demand.
| Strategic Initiative | Industry Significance |
|---|---|
| 8-Inch Diameter Capacity Buildout | Die-per-wafer economics offset retrofit capital for IDMs serving Detroit and Stuttgart clusters. |
| Backward Integration into Graphite Crucible Supply | Reduces single-source exposure to Chinese specialty carbon material export volatility. |
| Long-Term Automotive Supply Agreement | Locks volume guarantees with Wolfspeed and Infineon tier-1 assemblers ahead of 800V ramps. |
| Epitaxial Reactor Capacity Expansion | Thick-drift-layer scarcity in Germany and Japan constrains high-voltage device output. |
| India PLI Scheme Qualification Program | Domestic substrate production subsidies attract tier-1 supplier partnerships for EV traction markets. |
Research Methodology
Coverage spans Germany, Japan, the United States, China, and South Korea, with primary inputs from each region's automotive electronics and semiconductor manufacturing clusters. The approach combines structured interviews with crystal growth technicians, power module procurement directors, and epitaxial reactor equipment specialists alongside secondary validation through SEC 10-K filings, ECHA REACH registration databases, and MIIT domestic content policy directives. Bottom-up wafer demand modeling triangulates against top-down EV production forecasts and inverter content-per-vehicle assumptions.
Granularity-level framing applies diameter format, crystal growth technology, and end-use qualification tier as core segmentation dimensions across the projection horizon. The analytical framework derives CAGRs from vehicle electrification adoption curves, substrate yield improvement trajectories, and foundry capacity expansion schedules. Industry-specific inputs include AEC-Q101 qualification timeline assumptions, physical vapor transport defect density reduction rates, and graphite crucible supply elasticity estimates.
The model assumes a particular technology adoption path; alternative pathways for silicon IGBT persistence in cost-sensitive 400V applications would alter the outlook. Forecasts reflect assumptions regarding EU Green Deal enforcement timelines, Chinese semiconductor self-sufficiency policy intensity, and automotive OEM platform voltage architecture decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific MLCC Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
AMD Motherboards Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
MBE Components Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
Modular Plating System Market