
 Solar Silicon Ingots Market | 2026-2036
Solar Silicon Ingots Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Silicon Ingots Market Insights
Polysilicon feedstock substitution toward metallurgical-grade refined silicon is restructuring cost curves for ingot producers. LONGi Solar Technology Co., Ltd. leverages captive polysilicon capacity to insulate margins from volatile feedstock pricing. Tongwei anchors its position through integrated production from polysilicon through wafering. JA Solar Technology Co., Ltd. competes on scale, operating some of the largest single-site ingot pulling facilities globally.
Solar silicon ingots are cylindrical or rectangular blocks of high-purity crystalline silicon, typically achieving resistivity of 1-3 ohm-cm and minority carrier lifetimes exceeding 2 milliseconds, produced via Czochralski or directional solidification methods for subsequent wafering into photovoltaic cells. The Czochralski Method segment dominates monocrystalline output where cell efficiency premiums justify slower pull rates and higher energy consumption. Polycrystalline ingots retain cost advantages in price-sensitive utility procurement through faster solidification cycles and lower kerf loss. Solar Panel Manufacturers represent the principal end-user channel, with procurement patterns shifting toward long-term supply agreements that lock in polysilicon conversion margins.
China's MIIT enforces GB standards for silicon material purity and energy consumption intensity per ingot kilogram, while the EU Green Deal's carbon border adjustments threaten non-compliant imports into European downstream markets. The EPA's domestic content incentives under the IRA are reshaping where ingot-stage investment locates relative to cell and module assembly. Stakeholders must track how embodied-carbon certification requirements evolve across multiple jurisdictions before committing to multi-gigawatt capacity expansions.
Market Dynamics
Metallurgical-grade refined silicon feedstock substitution is compressing polysilicon conversion margins and forcing ingot producers to recalibrate furnace pull rates and energy intensity benchmarks.
Growth Catalysts
- India's utility-scale solar procurement:Central and state-level tenders under the National Solar Mission are absorbing multi-gigawatt ingot volumes through domestic content requirements.
- EU Green Deal carbon border adjustments:Embodied-carbon certification mandates are redirecting supply chain investment toward low-carbon polysilicon conversion and renewable-powered pulling facilities.
- Continuous Czochralski pulling:This furnace automation technology reduces crucible change downtime and lifts effective throughput per installed growth station.
Market Restraints
- Polysilicon price volatility:Metallurgical-grade silicon refining economics remain tethered to ferrosilicon alloy demand swings and Chinese industrial power pricing.
- Xinjiang supply concentration:Over half of global polysilicon feedstock originates from this single province, exposing ingot producers to forced-labor scrutiny and trade restriction risk.
- Monocrystalline kerf loss floors:Diamond wire sawing of Czochralski ingots still sacrifices 30-35% of silicon mass as slurry, capping unit economics against wafer thickness reduction limits.
Strategic Opportunities
- Vietnam manufacturing corridor expansion:Cell and module assembly relocation is pulling ingot-stage investment into the Vinh Phuc and Thai Nguyen industrial zones.
- Topcon cell architecture penetration:N-type monocrystalline ingot demand is accelerating as manufacturers retool from boron-doped to phosphorus-doped crystal growth.
- US IRA domestic content bonus:The 10% investment tax credit adder for qualifying solar components is incentivizing polysilicon-to-ingot capacity siting in Arizona and Texas.
Industry Challenges
- Czochralski thermal engineer scarcity:Furnace hot zone design and defect engineering expertise concentrates among retiring veterans from German and Japanese equipment suppliers.
- Multi-jurisdiction embodied-carbon certification:Ingot producers must simultaneously satisfy China's GB energy intensity standards, EU CBAM documentation, and US IRA traceability rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Silicon Ingots Market |
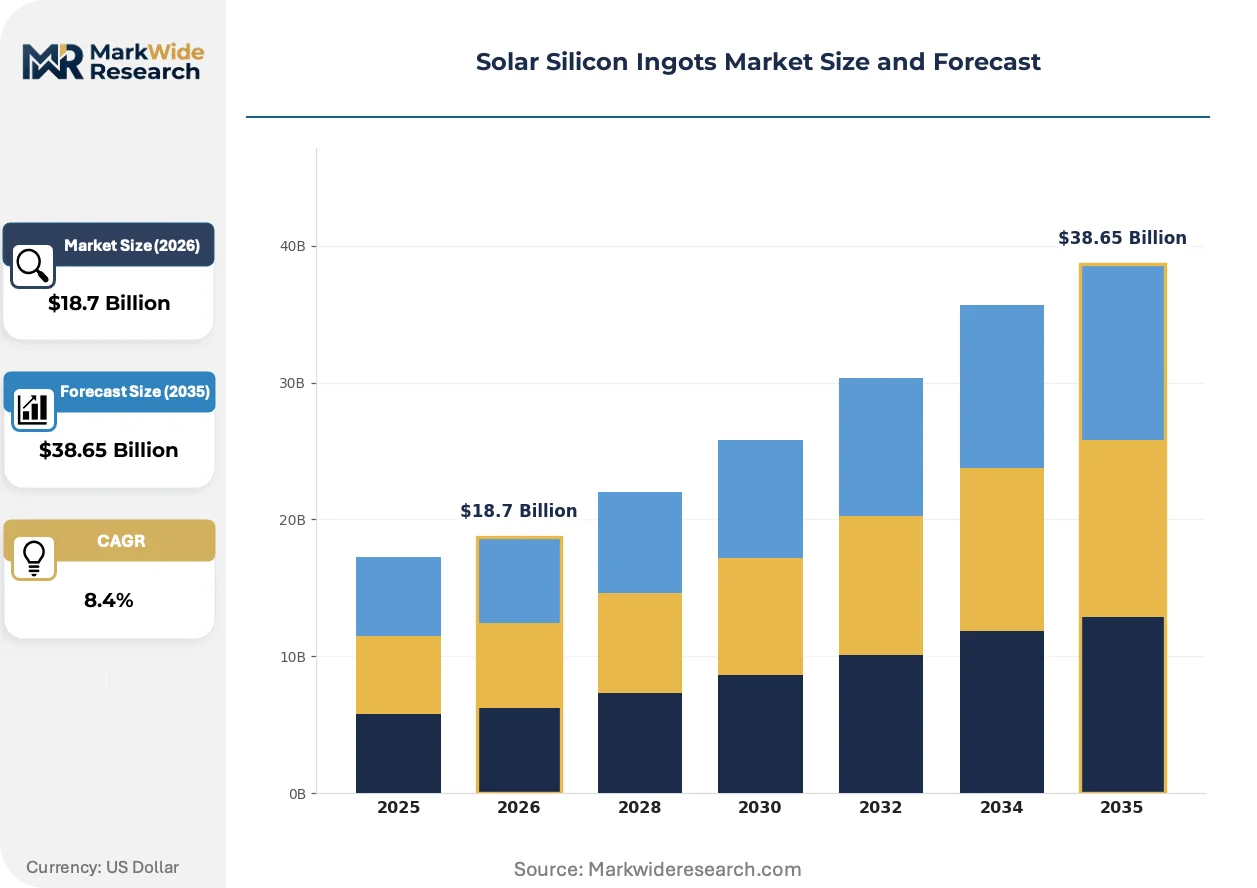
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Amphoteric Technology: Thin Film, Czochralski Method, Float Zone, Diamond Wire End User: Solar Panel Manufacturers, Power Plants, Research Institutions, OEMs Application: Residential, Commercial, Industrial, Off-Grid |
| Companies Covered | LONGi Solar Technology Co., Ltd., CETC Solar Energy Holdings Co., Ltd., GCL, NorSun AS, Corning, Tongwei, JA Solar Technology Co., Ltd., DCH Group, Kalyon Solar Technologies Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Silicon Ingots Market Trends and Innovations
Silicon ingot production is pivoting from commodity scale toward carbon-accounted differentiation, with furnace automation and feedstock chemistry emerging as the primary vectors of technical competition.
Continuous Czochralski pulling systems are rewriting throughput economics for monocrystalline ingot growth. Solar wafer manufacturers in Southeast Asia are retrofitting growth stations with automated crucible handling and real-time diameter control. This automation is compressing labor cost differentials between Chinese and Vietnamese production bases.
China's MIIT GB standards for silicon material purity and per-kilogram energy consumption are tightening enforcement timelines for ingot producers. Facilities failing to meet the 2025 intensity benchmarks face production quota restrictions and exclusion from state-backed procurement pools. European module buyers are now requiring third-party GB compliance attestations as preconditions for long-term supply agreements.
Long-term polysilicon conversion margin locks are displacing spot market purchasing for ingot-stage buyers. Utility-scale solar developers in India and the Middle East are signing five-year take-or-pay contracts directly with integrated polysilicon-to-wafer suppliers. This contracting shift is most visible in Saudi Arabia's PIF-backed renewable manufacturing cluster, where offtake security trumps unit price minimization in supplier selection criteria.
Solar Silicon Ingots Market Segmentation
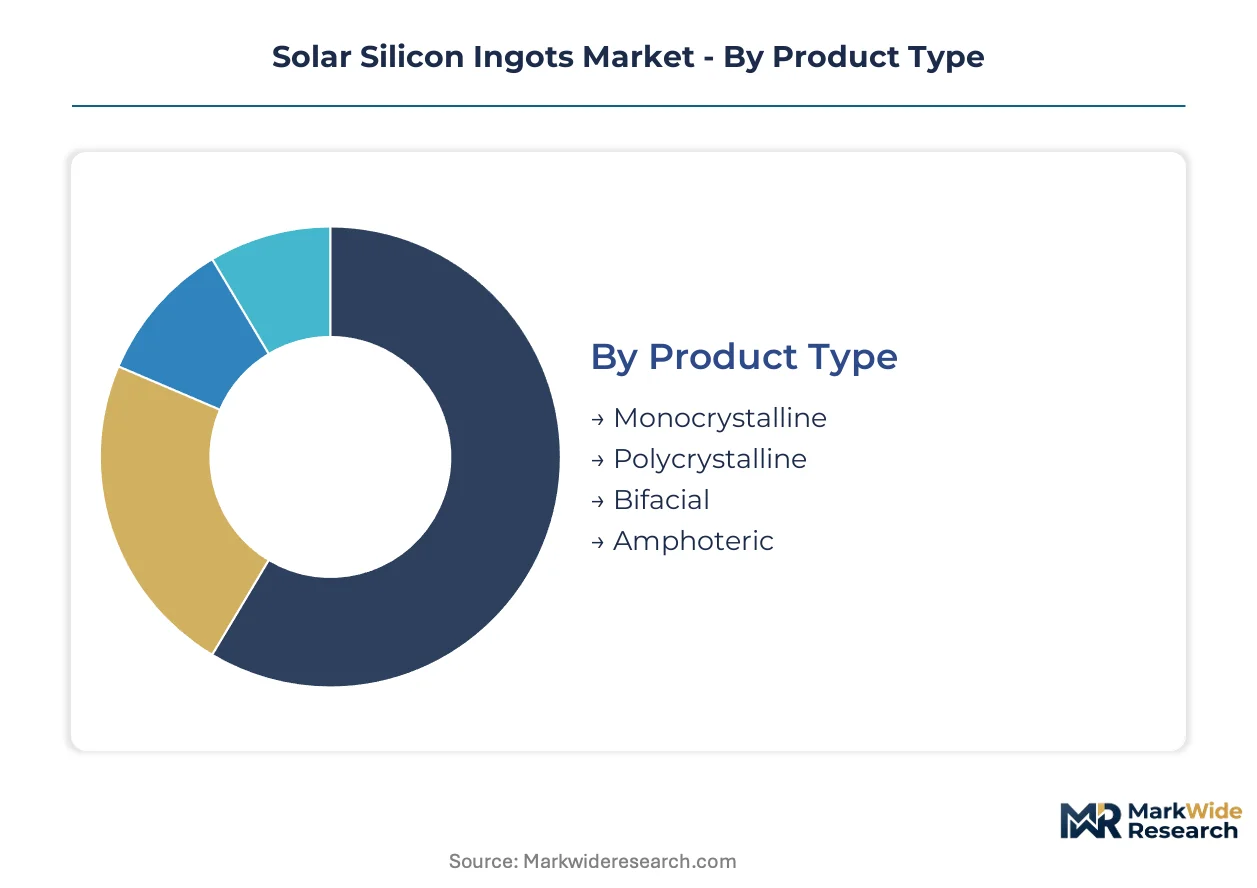
Solar silicon ingot segmentation reveals how crystalline structure, manufacturing method, and downstream integration requirements fragment procurement strategies across utility-scale and distributed generation markets.
Product Type:
Technical specifications around crystal orientation and doping chemistry determine efficiency premiums and furnace throughput economics.
- Monocrystalline:Single-crystal ingots achieve 1-3 ohm-cm resistivity with minority carrier lifetimes exceeding 2 milliseconds, commanding price premiums from PERC and TOPCon cell manufacturers in Vietnam's manufacturing corridor where efficiency maximization outweighs capex sensitivity.
- Polycrystalline:Directional solidification produces multicrystalline blocks with faster growth cycles and lower energy intensity, retaining cost advantages in India's National Solar Mission tenders where procurement weighting favors lowest levelized cost over conversion efficiency.
- Bifacial:Symmetrically doped ingots enable dual-sided light absorption with reduced rear-side recombination.
- Amphoteric:Dopant-flexible crystal growth accommodates both boron and phosphorus doping in single furnace configurations.
Monocrystalline leads on scale; amphoteric leads on momentum.
Technology:
Pulling and sawing methods differentiate throughput, material utilization, and automation potential.
- Czochralski Method:Seed crystal rotation and precise thermal gradient control produce uniform monocrystalline boules, dominating premium wafer supply to cell makers retooling for n-type TOPCon architectures in Thailand and Malaysia.
- Diamond Wire:Fixed-abrasive slicing reduces kerf loss to 140-180 microns versus 180-250 microns for slurry-based alternatives, penetrating fastest among Southeast Asian wafering operations seeking to offset polysilicon feedstock cost volatility.
- Thin Film:Non-silicon or amorphous silicon deposition bypasses ingot stage entirely.
- Float Zone:Containerless crystal growth achieves ultra-high purity for semiconductor-grade applications.
Czochralski Method leads on scale; Diamond Wire leads on momentum.
End User:
Procurement scale and integration depth shape contract structures and technical specifications.
- Solar Panel Manufacturers:Integrated cell and module makers purchase ingots directly for captive wafering, with Indian domestic content requirements forcing long-term supply agreements that lock in polysilicon conversion margins.
- Power Plants:Utility-scale developers in Saudi Arabia's PIF-backed renewable cluster source through integrated polysilicon-to-module suppliers, prioritizing offtake security over spot price minimization.
- Research Institutions:National laboratories and university programs require small-batch custom doping for next-generation cell architecture validation.
- OEMs:Equipment manufacturers procure reference-grade material for furnace calibration and process development.
Solar Panel Manufacturers lead on scale; Power Plants lead on momentum.
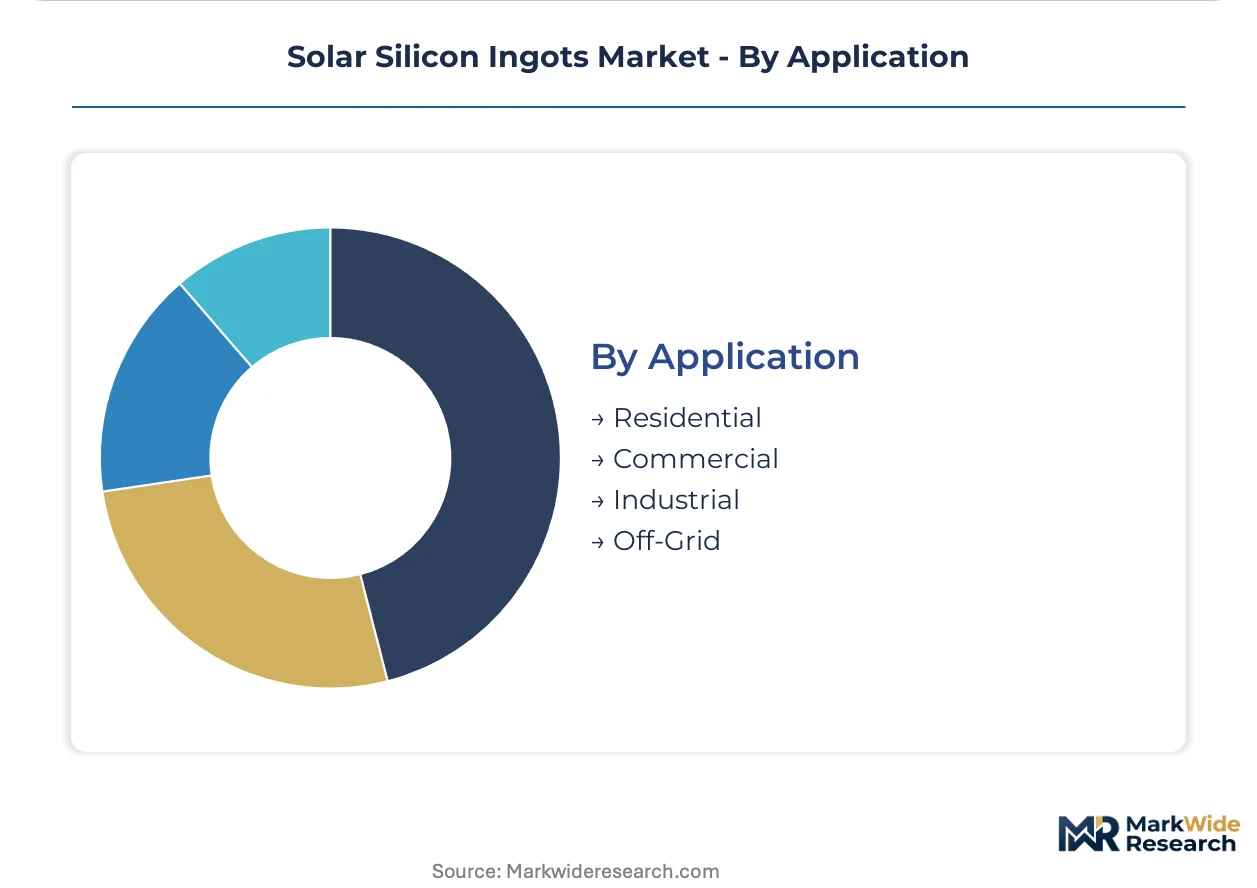
Application:
Installation scale and grid connection status determine efficiency requirements and price sensitivity thresholds.
- Industrial:Rooftop and ground-mounted systems above 1 MW capacity balance footprint constraints with energy yield optimization, driving demand for high-efficiency monocrystalline ingots in Germany's commercial sector under EU Green Deal carbon border compliance pressure.
- Utility-Scale:Grid-connected installations above 10 MW dominate volume absorption, with procurement concentrating in India's state-level tenders and Vietnam's manufacturing corridor feedstock requirements.
- Residential:Distributed rooftop installations prioritize module aesthetics and warranty terms over peak efficiency.
- Off-Grid:Remote and rural electrification projects tolerate lower efficiency for cost minimization and supply chain simplicity.
Industrial leads on scale; Utility-Scale leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's polysilicon concentration anchors upstream feedstock supply for ingot producers worldwide. Manufacturing corridors in Vietnam and India are absorbing relocated capacity as trade restrictions reshape investment geography. Regulatory fragmentation across China's MIIT standards, the EU Green Deal, and the US IRA is forcing multi-jurisdiction compliance strategies.
China
MIIT's GB energy intensity benchmarks for silicon material purity are tightening enforcement timelines through 2025. Facilities in Xinjiang and Inner Mongolia face production quota restrictions if they miss per-kilogram consumption targets. The Ningxia and Gansu industrial zones are attracting renewable-powered pulling investments to meet dual carbon goals.
Vietnam
Cell and module assembly relocation from China is pulling ingot-stage investment into Vinh Phuc and Thai Nguyen provinces. Domestic content requirements under Vietnam's renewable energy development strategy are strengthening backward integration incentives. The northern manufacturing corridor now hosts automated Czochralski growth stations serving Southeast Asian wafer demand.
India
Central and state-level tenders under the National Solar Mission are absorbing multi-gigawatt ingot volumes through PLI-linked domestic content mandates. CEA procurement guidelines favor integrated polysilicon-to-module suppliers for utility-scale projects. Gujarat and Rajasthan industrial zones are emerging as preferred locations for captive ingot capacity serving western solar parks.
United States
The IRA's 10% investment tax credit adder for qualifying solar components is incentivizing polysilicon-to-ingot capacity siting in Arizona and Texas. EPA domestic content incentives are reshaping where ingot-stage investment locates relative to cell and module assembly. The Southwest manufacturing belt is attracting equipment suppliers for furnace hot zone retrofit programs.
Germany
EU Green Deal carbon border adjustments are threatening non-compliant ingot imports into European downstream markets. ECHA documentation requirements for embodied-carbon certification are redirecting supply chain investment toward low-carbon conversion facilities. Saxony and Bavaria retain specialized furnace engineering expertise for defect control in monocrystalline growth.
Solar Silicon Ingots Market Competitive Landscape
Capacity expansion dominates the current landscape as producers race to secure polysilicon conversion margins before feedstock substitution accelerates. The vendor base clusters around three strategic archetypes: integrated polysilicon-to-wafer operators, captive ingot specialists serving module assembly, and equipment-technology licensors. Consolidation pressure is intensifying as metallurgical-grade silicon refining economics compress legacy conversion margins. Geographic expansion and strategic partnerships are emerging as dominant competitive moves for accessing India and Middle East procurement pools.
Among Chinese integrated operators, LONGi Solar Technology Co., Ltd. and Tongwei exemplify the backward-integrated archetype controlling feedstock through wafering stages. JA Solar Technology Co., Ltd. occupies a position representing scale-driven monocrystalline output, while CETC Solar Energy Holdings Co., Ltd. and GCL sit within the state-affiliated technology licensing tier. NorSun AS anchors European-based specialty production, and Corning represents the materials-science cross-over segment supplying crucible and hot zone components.
| Leading Market Players |
|---|
| LONGi Solar Technology Co., Ltd. |
| CETC Solar Energy Holdings Co., Ltd. |
| GCL |
| NorSun AS |
| Corning |
| Tongwei |
| JA Solar Technology Co., Ltd. |
| DCH Group |
| Kalyon Solar Technologies Factory |
| Others |
Pricing and Supply Chain Analysis
Backward integration from polysilicon through ingot pulling anchors both supply security and margin capture for producers competing under China's MIIT energy intensity benchmarks and the EU Green Deal's carbon border adjustments. This integration choice determines whether furnace operators absorb volatile metallurgical-grade silicon feedstock costs or pass them through to wafer buyers under long-term offtake contracts.
Pricing Analysis
Metallurgical-grade silicon feedstock cost pass-through dominates contract negotiations between ingot producers and integrated cell manufacturers in Vietnam's manufacturing corridor. Pricing stratifies across premium n-type monocrystalline, standard p-type monocrystalline, and economy polycrystalline tiers based on minority carrier lifetime specifications and GB standard compliance certification. Cost compression in the polycrystalline tier is intensifying because directional solidification furnaces achieve faster throughput with lower energy intensity. Utility-scale developers in India's National Solar Mission tenders exhibit highest price sensitivity, while TOPCon cell retoolers in Thailand demonstrate lowest sensitivity due to efficiency yield premiums.
Supply Chain Analysis
Czochralski thermal engineer scarcity in Vietnam's Vinh Phuc and Thai Nguyen provinces constrains furnace commissioning timelines for relocated capacity from Chinese operators. Supply concentrates in China, Vietnam, and India as cell and module assembly relocation redraws investment geography. Polysilicon feedstock, quartz crucibles, and diamond wire sawing equipment constitute critical input dependencies. Single-source vulnerability runs through Xinjiang polysilicon concentration exposing ingot producers to forced-labor scrutiny and trade restriction risk. Distribution runs through integrated polysilicon-to-wafer suppliers serving utility-scale procurement pools in Saudi Arabia's PIF-backed renewable cluster and India's state-level solar parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in solar silicon ingots rests on continuous Czochralski automation compressing labor cost differentials and n-type monocrystalline premiums widening as TOPCon penetration accelerates.
For Market Incumbents: Cement furnace pull rate advantages through automated crucible handling retrofits in Vietnamese growth stations before labor cost parity erodes Chinese competitive positioning. Lock polysilicon conversion margins through five-year take-or-pay contracts with Saudi PIF-backed and Indian National Solar Mission procurement pools. Defend against metallurgical-grade silicon feedstock substitution by securing captive polysilicon capacity or backward integration into refined silicon refining. For New Entrants and Emerging Players: Equipment-technology licensors represent the most accessible channel partner type for furnace hot zone design expertise concentrated among retiring German and Japanese engineering veterans. Target the US Southwest manufacturing belt where IRA domestic content bonuses incentivize greenfield polysilicon-to-ingot capacity in Arizona and Texas. Penetrate through TOPCon cell architecture retrofit demand for phosphorus-doped monocrystalline ingots as Thai and Malaysian cell makers retool from boron-doped p-type lines. For Investors and Strategic Acquirers: Roll-up economics work for automated Czochralski equipment specialists because furnace automation technology concentrates among fragmented German and Japanese suppliers facing generational knowledge transfer gaps. Long-term viability favors platforms controlling continuous pulling IP and real-time diameter control software rather than commodity scale operators. Watch for inflection in EU CBAM enforcement stringency as the signal triggering premium pricing power for low-carbon certified ingot supply into European downstream markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive feedstock supply insulates margins from metallurgical-grade silicon price volatility under Chinese industrial power pricing swings. |
| Continuous Czochralski Automation Deployment | Automated crucible handling reduces downtime and lifts throughput per growth station in Vietnam's manufacturing corridor. |
| Low-Carbon Certification Investment | GB standard compliance and renewable-powered pulling unlock EU Green Deal carbon border adjustment avoidance and premium contract access. |
| Long-Term Offtake Agreement Structuring | Five-year take-or-pay contracts with Saudi PIF-backed and Indian PLI-linked developers secure volume visibility against spot market volatility. |
| N-Type Monocrystalline Capacity Conversion | Phosphorus-doped crystal growth furnace retooling captures TOPCon cell architecture demand from Thai and Malaysian cell manufacturers. |
Research Methodology
Coverage spans China, Vietnam, India, the United States, and Germany, with primary inputs from each market informing supply concentration and regulatory fragmentation dynamics. The research combines structured interviews with furnace operations directors, polysilicon procurement leads at integrated wafer manufacturers, CEA procurement guideline officials, and EU ECHA carbon border documentation specialists with secondary validation. Secondary sources include MIIT GB standard enforcement notices, EU Green Deal CBAM regulatory filings, EPA IRA domestic content guidance, Indian PLI scheme implementation circulars, and SEC disclosures from listed solar supply chain operators. Bottom-up capacity and utilization estimates triangulate against top-down demand absorption from utility-scale tender awards.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models crystalline structure segmentation, manufacturing method technology tiers, end-user integration depth, and application scale dimensions. CAGRs derive from installed capacity expansion schedules, furnace pull rate improvement curves, and feedstock substitution elasticity assumptions. Industry-specific forecast inputs incorporate TOPCon cell architecture penetration trajectories and carbon intensity certification adoption rates across jurisdictional procurement pools.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Xinjiang polysilicon trade restriction enforcement, EU CBAM documentation stringency escalation, and metallurgical-grade silicon refining cost curve shifts. Forecasts reflect documented assumptions regarding furnace automation adoption timelines, renewable power purchase agreement penetration for pulling facilities, and domestic content requirement implementation consistency. Material deviation in Xinjiang supply access, EU carbon border adjustment rates, or IRA domestic content bonus qualification rules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Tungsten Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
Electronic Thermal Management Materials Market