
 Europe Power Transistor Market | 2026-2036
Europe Power Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Power Transistor Market Insights
The EU Green Deal is realigning procurement criteria for industrial power electronics across European manufacturing bases. Infineon Technologies AG leverages its Dresden fab complex to anchor silicon carbide wafer supply for automotive traction inverters. STMicroelectronics competes through integrated SiC substrate production at its Catania facility serving Continental and Renault. NXP Semiconductors differentiates via gallium nitride roadmaps targeting 800V EV architectures for premium German OEMs.
Europe power transistors are semiconductor switching devices engineered to handle voltage ratings from several hundred to several thousand volts and current levels exceeding hundreds of amperes, fabricated on silicon, silicon carbide, or gallium nitride substrates using epitaxial growth and ion implantation processes to manage thermal dissipation in high-frequency power conversion. These components serve as the fundamental control elements in motor drives, renewable energy inverters, and switched-mode power supplies where efficiency and switching speed determine system performance. Insulated Gate Bipolar Transistors dominate industrial motor control applications where voltage blocking requirements exceed 600V and switching losses must balance conduction efficiency. Silicon Carbide technology captures expanding share in automotive and renewable energy segments where higher junction temperatures and reduced cooling burdens offset premium wafer costs.
EMA efficiency frameworks, EU F-Gas Regulation phase-down schedules, and CE marking under the Low Voltage Directive collectively mandate minimum performance thresholds for power conversion equipment sold across member states. REACH compliance restricts certain substrate dopants and packaging materials, forcing reformulation of epitaxial processes and module encapsulants. Stakeholders must monitor how the EU AI Act's emerging energy efficiency disclosure requirements for intelligent power systems reshape competitive qualification timelines for new transistor platforms.
Market Dynamics
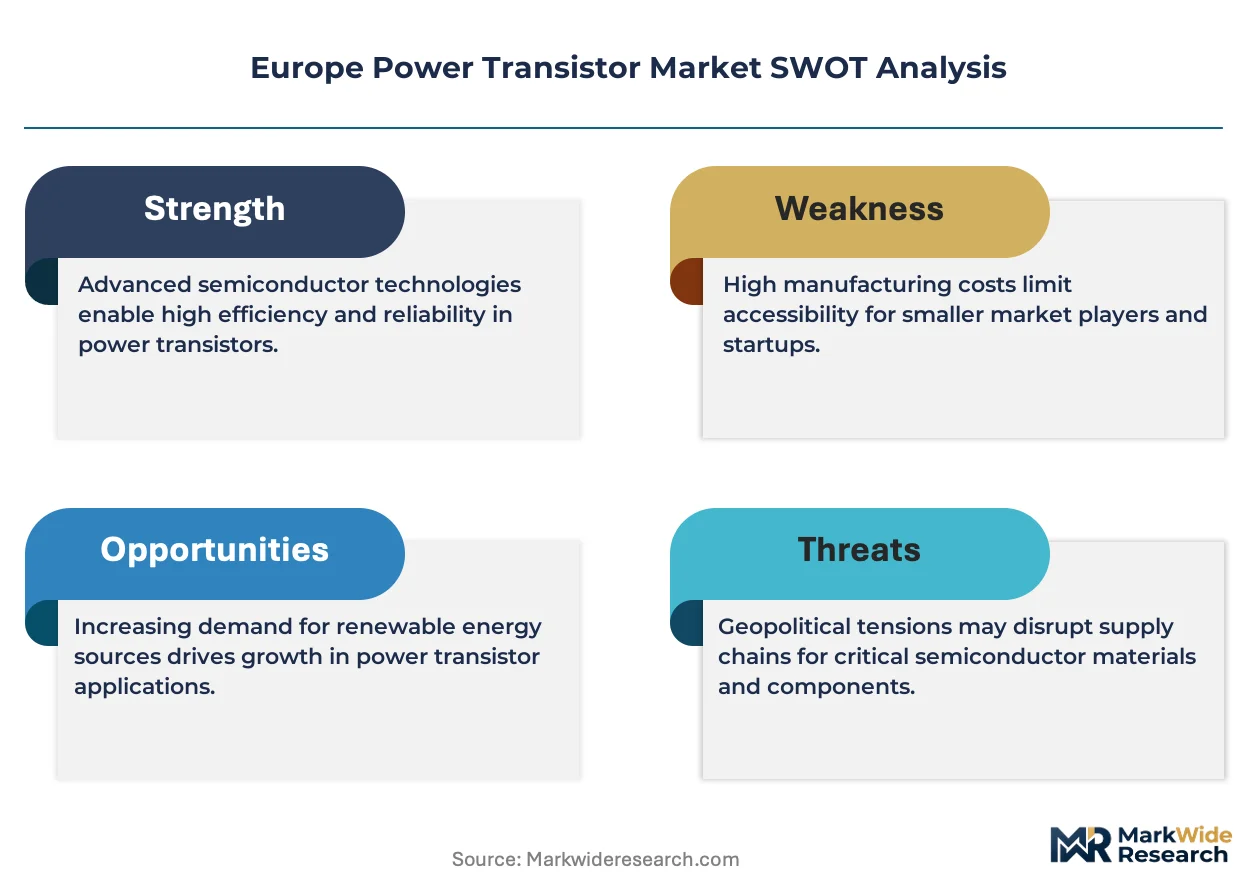
Silicon carbide substrate shortages are compressing qualification timelines for automotive power modules across European OEM supply chains, forcing tier-one suppliers to lock multi-year wafer offtake agreements before fab capacity expansion materializes.
Growth Catalysts
- EU Green Deal efficiency mandates:Industrial motor drive manufacturers must retrofit existing installations to meet tightened energy performance standards, triggering replacement cycles for legacy IGBT systems.
- 800V EV architectures:Premium German and French automakers are specifying wide-bandgap semiconductors for traction inverters to reduce charging times and extend vehicle range.
- Renewable energy buildout:Solar and wind inverter producers in Spain and Poland are scaling orders for high-voltage switching devices to support grid-scale storage integration.
Market Restraints
- Silicon carbide wafer cost premiums:Six-inch SiC substrates command 10-15x price multiples over equivalent silicon epitaxial wafers, constraining adoption in cost-sensitive industrial drives.
- Dresden-Munich supply corridor concentration:Frontend fabrication for automotive-grade power modules clusters in southeastern Germany, creating geographic vulnerability to localized disruption.
- Gallium nitride voltage ceiling:GaN HEMT devices face fundamental breakdown voltage limitations below 650V in standard commercial offerings, blocking penetration in heavy-truck electrification.
Strategic Opportunities
- Eastern European manufacturing expansion:Czech and Romanian industrial zones offer underutilized packaging capacity for power module assembly serving mid-market motor drive producers.
- EU AI Act energy disclosure requirements:Intelligent power systems with embedded efficiency monitoring will qualify for accelerated CE marking under emerging disclosure frameworks.
- Silicon carbide-gallium nitride hybrid modules:Combining SiC MOSFETs with GaN gate drivers enables optimized switching performance for next-generation renewable inverters.
Industry Challenges
- Wide-bandgap device characterization expertise:Power electronics engineers trained in silicon IGBT design require substantial retraining to model SiC switching behavior under inductive load conditions.
- REACH-compliant encapsulant reformulation:Module suppliers must validate new epoxy and silicone gel formulations for thermal cycling reliability while eliminating restricted substance content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Power Transistor Market |
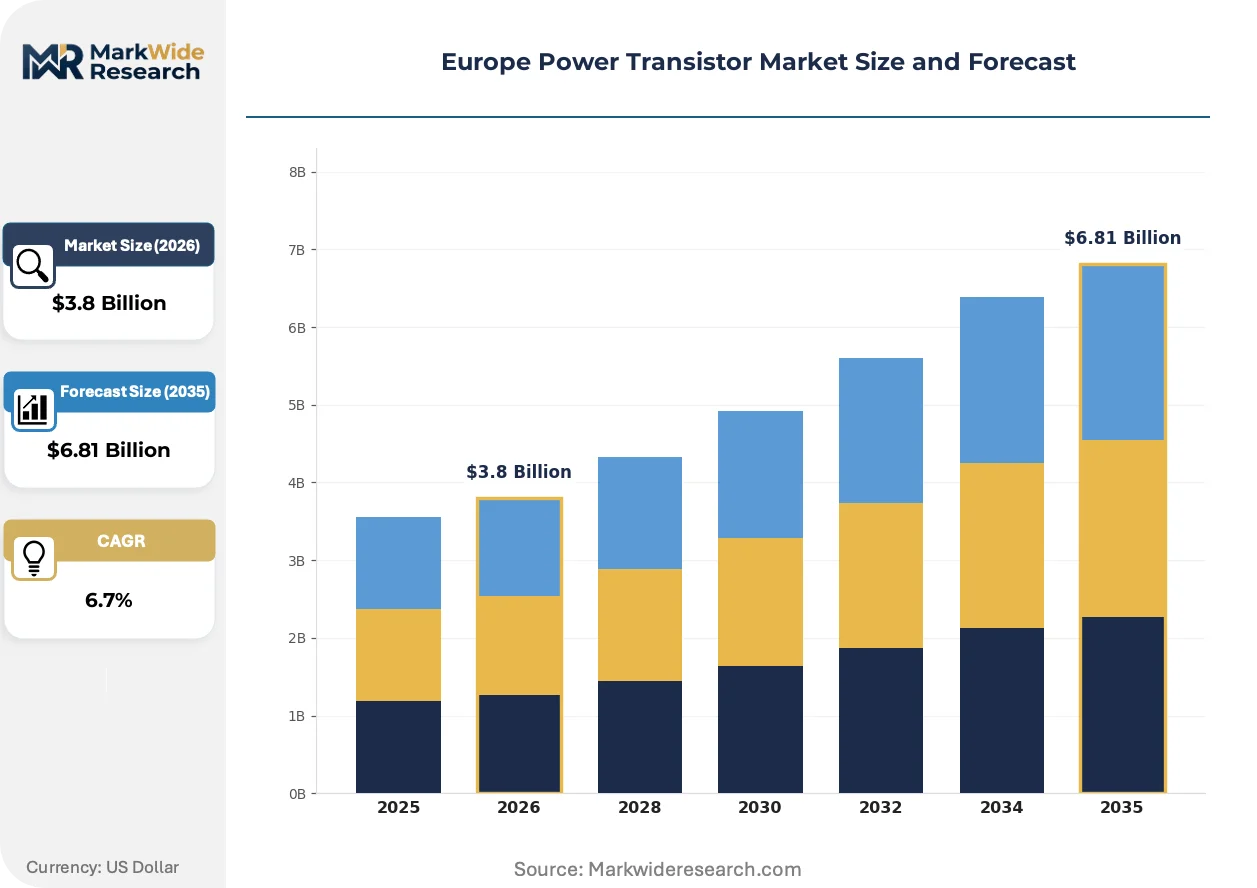
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, Insulated Gate Bipolar Transistor, Lateral Double-Diffused Metal-Oxide-Semiconductor Application: Power Supply, Motor Control, Renewable Energy, Consumer Electronics End User: Telecommunications, Automotive, Industrial, Aerospace Technology: Silicon, Silicon Carbide, Gallium Nitride, Others |
| Companies Covered | Infineon Technologies AG, STMicroelectronics, NXP Semiconductors, ON Semiconductor, Renesas Electronics Corporation, Texas Instruments, Mitsubishi Electric Corporation, Vishay Intertechnology, Toshiba Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Power Transistor Market Trends and Innovations
Wafer-level packaging architectures and integrated cooling substrates are compressing thermal management footprints while enabling higher power density in confined automotive and industrial enclosures.
Silicon carbide trench MOSFET designs are expanding into 800V EV traction inverters by reducing specific on-resistance and enabling faster switching frequencies that shrink passive component volume. German premium automakers have accelerated platform adoption from 2028 to 2026 model years. This expansion is compressing silicon IGBT market share in segments above 400kW peak power.
The EU F-Gas Regulation phase-down schedule is forcing industrial refrigeration and heat pump manufacturers to specify higher-efficiency compressors driven by variable-frequency power electronics. Motor drive suppliers must certify new inverter platforms under updated Ecodesign requirements before market entry. Cold chain equipment producers in Italy and the Netherlands face the most compressed compliance timelines.
Automotive tier-one suppliers are consolidating power module procurement through direct fab relationships rather than distribution channels, compressing traditional semiconductor distributor margins. Bosch and Continental have established dedicated sourcing offices at Infineon's Dresden complex. This concentration is most visible in Bavaria's automotive semiconductor corridor.
Europe Power Transistor Market Segmentation
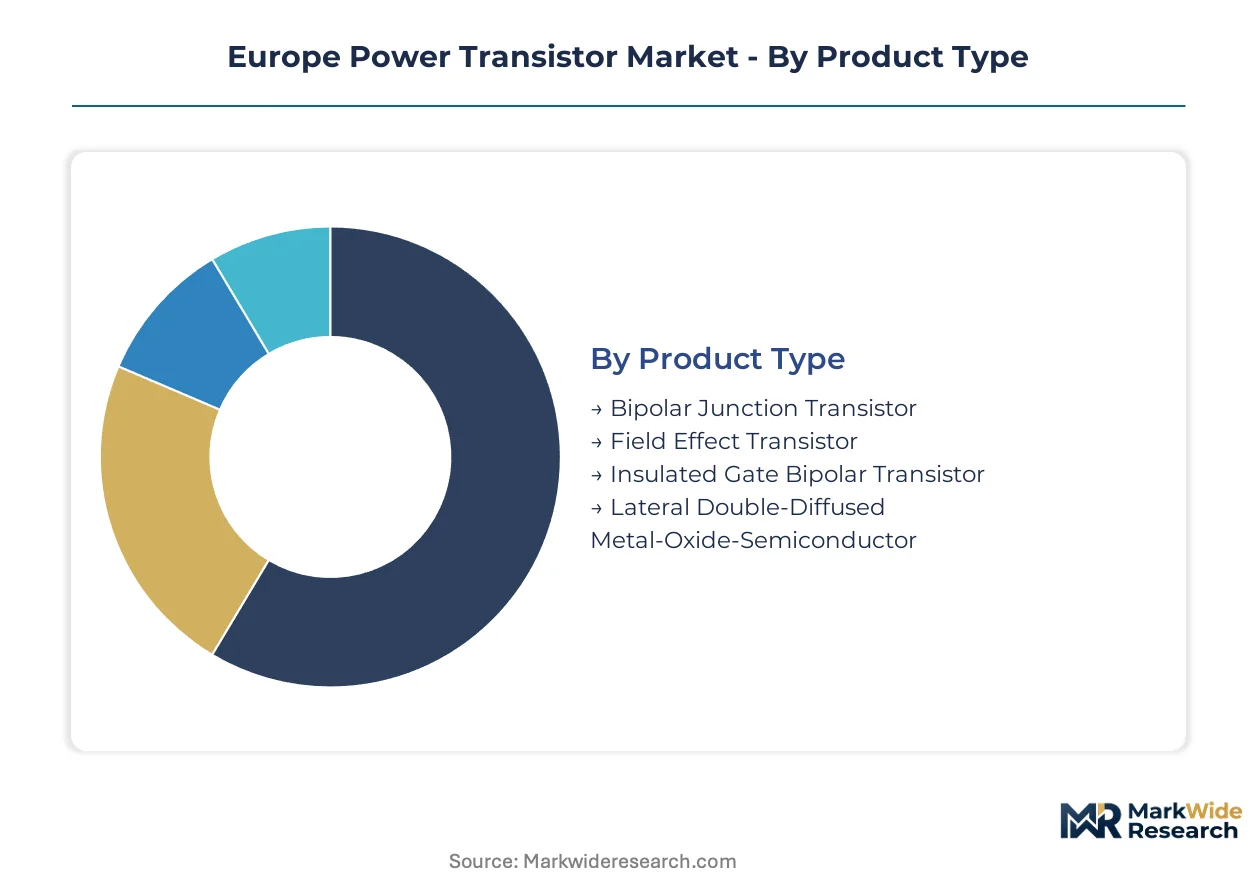
Power transistor segmentation in Europe reflects divergent upgrade cycles across automotive electrification, industrial retrofit mandates, and renewable energy buildout. Each dimension captures distinct procurement patterns, technology substitution rates, and regulatory compliance pressures that reshape competitive positioning.
Product Type:
Replacement cycles for legacy silicon devices are accelerating as EU efficiency regulations force industrial motor drive upgrades and automotive platforms migrate to wide-bandgap architectures.
- Insulated Gate Bipolar Transistor:Silicon-based IGBTs dominate voltage ratings from 600V to 6.5kV with optimized conduction loss profiles for heavy-duty motor drives. German industrial equipment manufacturers in the Ruhr region are phasing out older generation-4 modules ahead of Ecodesign deadlines.
- Field Effect Transistor:MOSFET structures enable faster switching frequencies above 100kHz for compact power supplies and DC-DC converters. French telecom infrastructure suppliers are specifying super-junction devices for 5G base station rectifiers under tightened energy performance contracting.
- Bipolar Junction Transistor:Cost-optimized bipolar devices persist in linear amplification and low-frequency switching below 10kHz where silicon efficiency suffices.
- Lateral Double-Diffused Metal-Oxide-Semiconductor:LDMOS technology serves RF power amplification in broadcast transmitters and radar systems with specialized voltage-handling requirements.
Volume placements concentrate in Insulated Gate Bipolar Transistor; the faster expansion belongs to Field Effect Transistor.
Application:
Cost tier differentiation separates premium wide-bandgap deployments from price-sensitive silicon retention in mature equipment categories.
- Motor Control:Variable-frequency drives for pumps, compressors, and conveyors represent the largest installed base requiring retrofit under EU Green Deal efficiency mandates. Italian HVAC manufacturers face compressed compliance timelines for F-Gas Regulation alignment.
- Renewable Energy:Solar inverters and wind turbine converters demand high-voltage switching with minimal cooling overhead. Polish and Spanish project developers are scaling orders for 1500V DC-rated devices as grid-scale storage integration accelerates.
- Power Supply:Server and telecom rectifier applications prioritize power density metrics over absolute efficiency in rack-mounted configurations.
- Consumer Electronics:Adapter and charger applications remain cost-constrained with limited wide-bandgap penetration outside premium mobile device segments.
Revenue concentration sits with Motor Control; Renewable Energy is climbing the fastest.
End User:
Customer type segmentation reveals divergent procurement sophistication, with automotive tier-ones consolidating direct fab relationships while industrial buyers fragment across distribution channels.
- Automotive:Traction inverters, onboard chargers, and DC-DC converters for battery electric vehicles specify silicon carbide above 400V bus architectures. German premium OEMs have compressed platform adoption timelines from 2028 to 2026 model years.
- Industrial:Factory automation, process control, and material handling equipment drive replacement demand as REACH-compliant encapsulants and Ecodesign certification reshape supplier qualification. Czech packaging zones are capturing assembly overflow from saturated German corridors.
- Telecommunications:Base station power supplies and data center rectifiers emphasize efficiency at partial load conditions under emerging EU AI Act energy disclosure frameworks.
- Aerospace:Satellites and avionics systems require radiation-hardened devices with extended temperature ranges and qualification cycles measured in years.
Procurement volume tilts toward Industrial; Automotive delivers the steepest expansion trajectory.
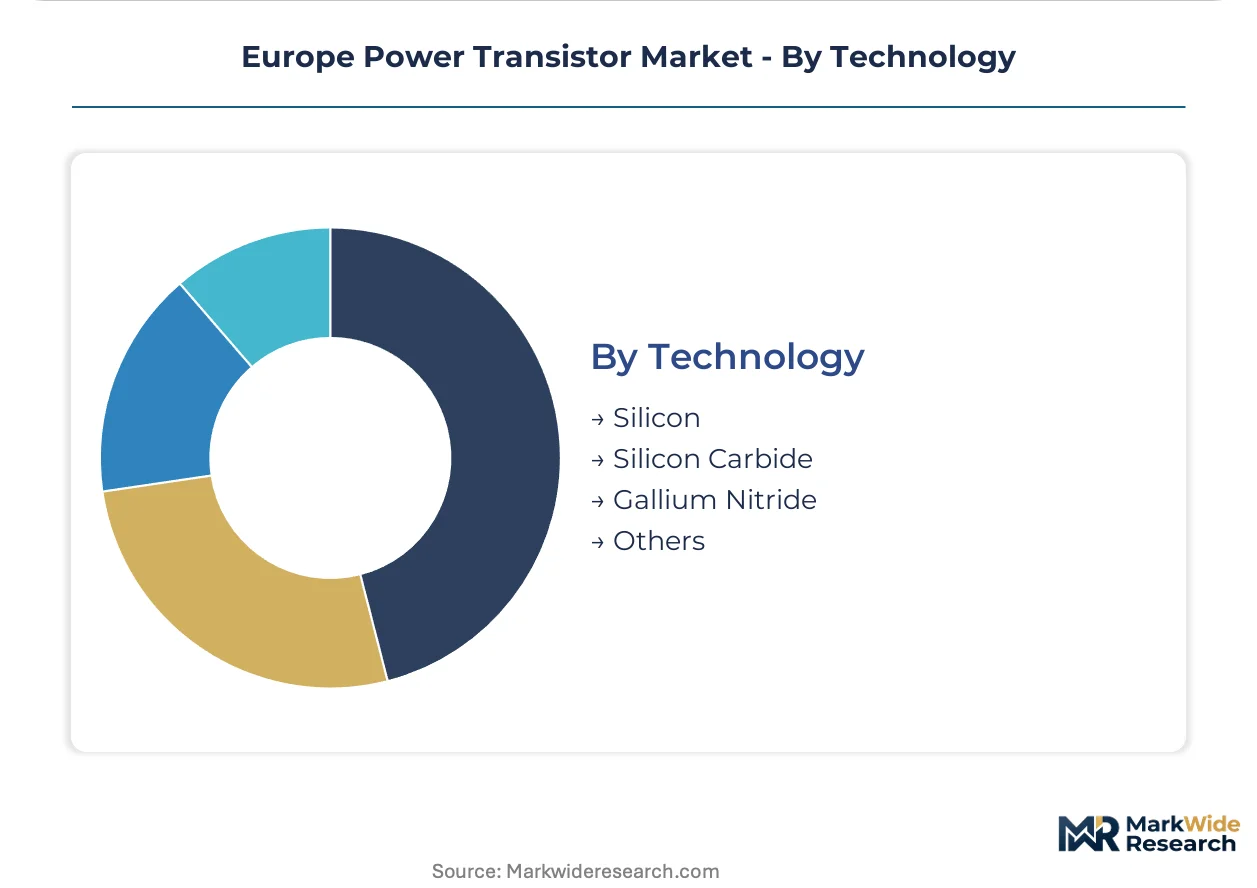
Technology:
Supply concentration for wide-bandgap substrates is compressing qualification timelines and locking tier-one suppliers into multi-year wafer offtake agreements.
- Silicon Carbide:4H-SiC substrates enable junction temperatures above 175°C with reduced switching losses for 800V EV traction inverters. Dresden fab complexes are anchoring European wafer supply as substrate shortages persist.
- Silicon:Mature epitaxial processes and established packaging infrastructure sustain cost advantages for voltage ratings below 600V and switching frequencies under 50kHz.
- Gallium Nitride:GaN HEMT devices penetrate 400V-650V applications where power density metrics outweigh voltage ceiling limitations. Premium German OEMs are specifying GaN for onboard charger designs.
- Others:Emerging wide-bandgap materials including gallium oxide and aluminum nitride remain in research phases with limited commercial availability.
Silicon retains volume dominance; Silicon Carbide is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dresden-Munich automotive semiconductor corridor anchors European power transistor demand, with Infineon's fab complex and tier-one supplier offices clustering across Bavaria and Saxony. This concentration shapes procurement patterns and supply security calculations for the entire region.
Germany
Premium automakers in Stuttgart and Munich have accelerated 800V EV platform timelines from 2028 to 2026 model years. The KBA enforces type-approval standards that mandate electromagnetic compatibility testing for power electronics. Bosch and Continental maintain dedicated sourcing offices at Infineon's Dresden fab, locking multi-year wafer offtake agreements for traction inverter modules.
France
Renault and Stellantis are scaling silicon carbide orders for next-generation electric drivetrains manufactured at Douai and Rennes facilities. ANSM oversight of industrial equipment safety intersects with Ecodesign implementation timelines for motor drive retrofits. The Auvergne-Rhône-Alpes region hosts STMicroelectronics' substrate development activities serving Continental's French operations.
Italy
HVAC and refrigeration equipment producers in Lombardy and Emilia-Romagna face compressed F-Gas Regulation compliance deadlines requiring higher-efficiency compressor drives. The Ministry of Economic Development coordinates REACH-aligned reformulation of module encapsulants for thermal cycling reliability. Industrial motor drive assembly clusters around Milan and Bologna are qualifying new inverter platforms under updated Ecodesign requirements.
Spain
Solar inverter manufacturers in Catalonia and Andalusia are scaling 1500V DC-rated device orders for grid-scale storage integration projects. The national energy regulator enforces grid connection standards that favor wide-bandgap switching performance in utility-scale installations. Barcelona-area power electronics firms are expanding procurement teams to secure SiC supply from German wafer fabs.
Poland
Wind turbine converter producers in Lower Silesia and Pomerania are increasing high-voltage switching device procurement for Baltic Sea offshore installations. The Energy Regulatory Office implements renewable energy auction mechanisms that reward converter efficiency metrics. Wrocław industrial zones are attracting packaging capacity overflow from saturated German corridors.
Europe Power Transistor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across substrate technology and automotive qualification tiers. The vendor base stratifies between captive silicon carbide substrate producers, fabless wide-bandgap designers, and integrated silicon IGBT manufacturers serving industrial retrofit cycles. Three archetypes dominate: European IDMs with in-house SiC growth, Asian conglomerates with diversified power semiconductor portfolios, and specialized RF power device suppliers. Competitive moves concentrate on multi-year wafer offtake agreements and Dresden-Munich corridor co-location strategies.
Within the integrated device manufacturer tier, Infineon Technologies AG, STMicroelectronics, and NXP Semiconductors exemplify divergent technology anchoring strategies. Infineon occupies a position tied to Dresden fab capacity for automotive traction applications. STMicroelectronics represents integrated SiC substrate production serving Continental and Renault supply chains. NXP sits within the gallium nitride development trajectory targeting 800V architectures for premium German OEMs. These three European-headquartered players illustrate how geographic proximity to automotive engineering centers shapes competitive positioning.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics |
| NXP Semiconductors |
| ON Semiconductor |
| Renesas Electronics Corporation |
| Texas Instruments |
| Mitsubishi Electric Corporation |
| Vishay Intertechnology |
| Toshiba Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned German fab operators anchor wafer supply discipline through multi-year offtake relationships with automotive tier-ones, translating captive substrate capacity into pricing power that resists spot-market volatility. This ownership structure concentrates bargaining leverage along the Dresden-Munich corridor while insulating contract rates from silicon carbide spot price swings.
Pricing Analysis
Price differentiation by certification tier dominates the European power transistor market. Automotive-grade AEC-Q101 qualification commands substantial premiums over industrial-tier devices, while CE marking under the Low Voltage Directive separates compliant from non-compliant supplier pools. Cost compression in standard-grade silicon IGBTs is intensifying because Eastern European packaging zones are absorbing overflow capacity from saturated German corridors. Industrial motor drive manufacturers exhibit the highest price sensitivity due to thin margins on retrofit installations, whereas premium German OEMs prioritize performance metrics over unit economics for 800V traction inverters.
Supply Chain Analysis
Domestic-content requirements under the EU Chips Act are reshaping sourcing patterns for substrate and epitaxial growth equipment. Supply concentrates in Germany, France, and Italy for frontend fabrication, while raw material dependencies draw from China for high-purity silicon feedstock and the United States for ion implantation systems. Single-source vulnerability persists for six-inch silicon carbide substrates, where Infineon's Dresden complex controls European wafer supply. Distribution runs through direct fab relationships rather than traditional semiconductor distributors, with Bosch and Continental maintaining dedicated sourcing offices at major production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe power transistor market functions as a vertical-integration race where captive silicon carbide substrate production determines competitive survival. Players are pursuing upstream control over epitaxial growth capacity to lock supply security and defend margin structures.
For Market Incumbents: Cement multi-year wafer offtake agreements before substrate capacity expansion materializes, locking supply security against silicon carbide shortage risks. Expand Dresden-Munich corridor co-location strategies to compress logistics costs and accelerate qualification timelines for automotive tier-ones. Prioritize REACH-compliant encapsulant reformulation to maintain Ecodesign certification eligibility as regulatory deadlines tighten. For New Entrants and Emerging Players: Capture packaging assembly overflow in Czech and Romanian industrial zones where German corridor saturation has created capacity gaps. Target mid-market industrial motor drive producers underserved by direct fab relationships, offering distribution-channel accessibility that incumbents have abandoned. Lead with GaN-based solutions for 400V-650V applications where voltage ceilings do not constrain penetration. For Investors and Strategic Acquirers: Multi-year wafer offtake announcement velocity is the leading indicator that substrate supply security is becoming the primary valuation differentiator. Focus acquisition screening on fabless wide-bandgap designers with established automotive qualification pathways but lacking captive substrate supply. Watch for EU AI Act energy disclosure implementation as the signal triggering accelerated procurement of intelligent power systems with embedded efficiency monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Capacity Expansion | Dresden fab complexes anchor European wafer supply as automotive demand accelerates. |
| Multi-Year Wafer Offtake Agreements | Bosch and Continental lock supply security through direct relationships with substrate producers. |
| REACH-Compliant Encapsulant Reformulation | Italian HVAC manufacturers validate new epoxy formulations for F-Gas Regulation alignment. |
| Eastern European Packaging Expansion | Czech and Romanian zones capture assembly overflow from saturated German corridors. |
| GaN Roadmap Development for 800V Architectures | Premium German OEMs specify gallium nitride for onboard charger and DC-DC converter designs. |
Research Methodology
SEC filings, ECHA REACH registration databases, and EU Ecodesign directive implementation reports formed the secondary backbone for market sizing and regulatory timeline calibration. Primary interviews with power electronics procurement managers at German automotive tier-ones, fab operations directors at Dresden-area facilities, and industrial motor drive engineering heads at Italian HVAC manufacturers provided demand-side validation. Bottom-up unit economics triangulated against top-down sector spending patterns derived the market estimates.
Historical trendline analysis across silicon and wide-bandgap technology substitution cycles informed the projection framework. Segmentation modeling covered product type, application, end user, and technology dimensions, with additional granularity on voltage rating tiers and automotive qualification status. CAGRs were derived from fitted growth curves incorporating EU Green Deal efficiency mandate implementation schedules and EV platform adoption timelines. Forecast inputs included substrate capacity expansion announcements, REACH-compliant material reformulation timelines, and F-Gas Regulation phase-down schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon carbide substrate supply disruptions, geopolitical trade restrictions on semiconductor manufacturing equipment, and EU AI Act energy disclosure requirement finalization. Forecasts reflect documented assumptions regarding automotive electrification penetration rates and industrial retrofit cycle timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Varactor Diode Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Silicon on Insulator Market