
 Global Substrate-Like PCB Market | 2026-2036
Global Substrate-Like PCB Market Size, Share, and Industry Trends Forecast 2026-2036
Global Substrate-Like PCB Market Outlook
Trained lithography engineer availability is collapsing across East Asian fabrication hubs, tightening capacity expansion timelines for advanced substrate production. Kinsus Interconnect Technology leverages captive via-filling capabilities to sustain wafer-level packaging output. Ibiden Co., Ltd. anchors Japan's supply position through proprietary ABF laminate development. Samsung Electro-Mechanics dominates South Korea's smartphone substrate segment with in-house flip-chip BGA scale.
Substrate-like PCB denotes high-density interconnect boards manufactured with semiconductor packaging-grade processes, typically featuring line/space geometries below 15 micrometers and dielectric layers under 30 micrometers for chip-scale integration. Multi-layer configurations lead unit economics due to stacked microvia complexity in 5G modem packages. HDI substrates capture premium pricing from automotive radar module qualification cycles. Epoxy-based materials retain volume dominance while polyimide gains traction in medical device flex-rigid applications where biocompatibility testing under IEC 60601 governs selection.
EU REACH restrictions on brominated flame retardants reshape material formulations for export-bound European automotive electronics. FDA electromagnetic compatibility standards for implantable medical devices constrain substrate signal integrity specifications in US-bound shipments. China's GB standards on hazardous substance limits, administered by SAMR, mandate testing protocols for domestically sold IoT hardware. Stakeholders must monitor how divergent chemical compliance regimes fragment substrate qualification pools across end-use verticals.
Market Dynamics
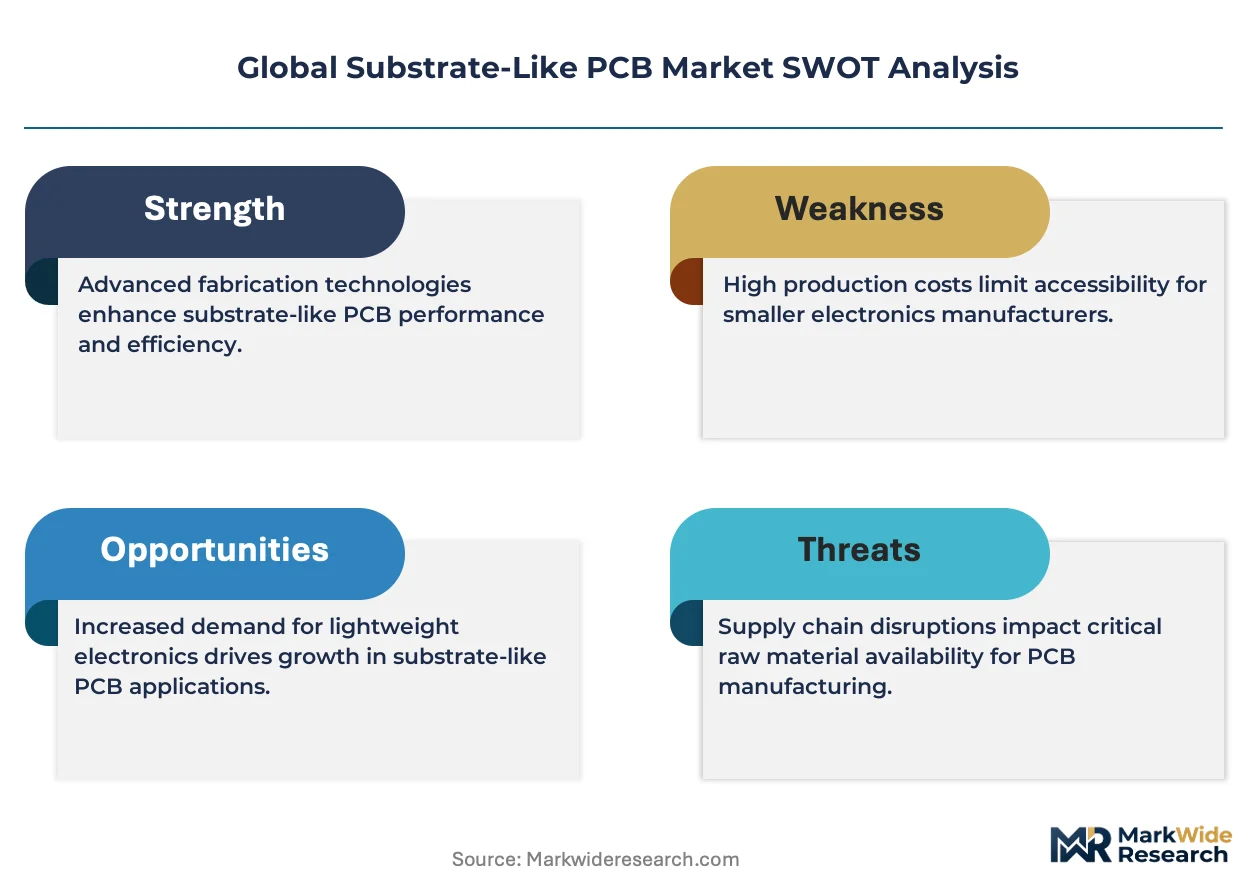
Semiconductor packaging-grade lithography capacity constraints are compressing expansion timelines for advanced substrate production, forcing buyers into allocation negotiations with East Asian fabrication hubs.
Growth Catalysts
- 5G Modem Package Complexity:Smartphone OEMs in South Korea and Taiwan require stacked microvia configurations for RF front-end integration, pulling substrate-like PCB specifications below 15-micrometer line/space geometries.
- EU REACH Halogen-Free Mandates:Brominated flame retardant restrictions under ECHA oversight are accelerating material qualification cycles for export-bound European automotive electronics.
- Flip-Chip BGA Scale:Captive production lines at South Korean component houses are absorbing wafer-level packaging substrate volume previously served by merchant suppliers.
Market Restraints
- ABF Laminate Supply Concentration:Proprietary resin formulations from Japanese chemical houses create single-source dependencies for high-layer-count builds.
- Trained Lithography Engineer Scarcity:East Asian fabrication hubs face collapsing pipeline of process engineers capable of sub-20-micrometer patterning.
- Polyimide Cost Volatility:Medical device flex-rigid applications confront raw material pricing swings driven by aerospace composite demand competition.
Strategic Opportunities
- Automotive Radar Module Qualification:HDI substrate suppliers capturing tier-one automotive electronics certification cycles for 77GHz sensor packages.
- India PLI Scheme for Electronics:Domestic assembly incentives are creating substrate packaging demand from smartphone contract manufacturers relocating capacity from China.
- Biocompatibility-Driven Medical Convergence:IEC 60601 testing protocols for implantable devices are opening flex-rigid substrate specifications to polyimide alternatives.
Industry Challenges
- Multi-Physics Simulation Skill Gaps:Signal integrity engineers capable of electromagnetic-thermal co-design for chip-scale packages command premium compensation in South Korea and Taiwan.
- Cross-Regulatory Qualification Pools:Divergent chemical compliance regimes across EU REACH, China GB standards, and FDA electromagnetic compatibility requirements fragment substrate testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Substrate-Like PCB Market |
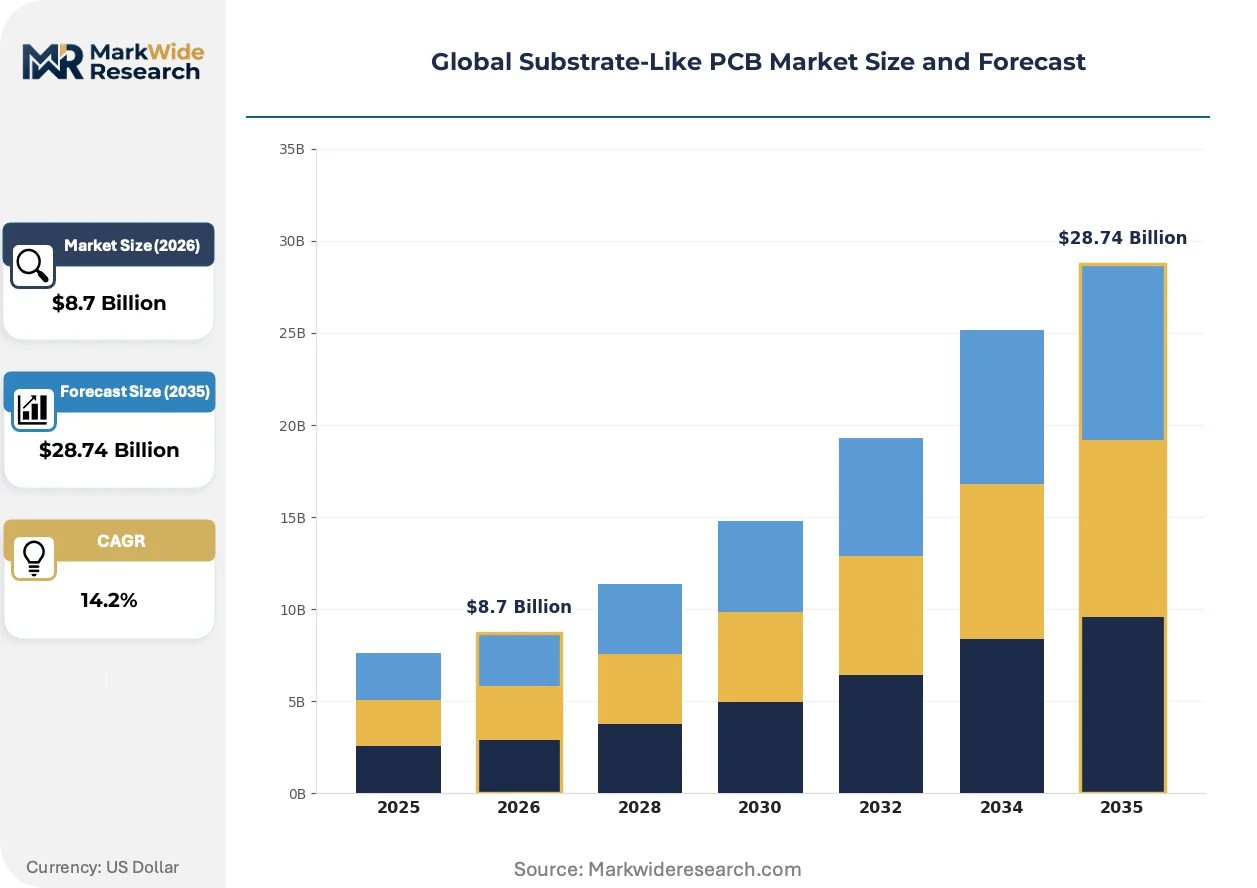
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multi-Layer, HDI End User: Consumer Electronics, Automotive, Telecommunications, Medical Devices Material: Epoxy, Polyimide, Ceramic, FR-4 Application: Smartphones, Laptops, IoT Devices, Gaming Consoles |
| Companies Covered | Kinsus Interconnect Technology, Ibiden Co., Ltd., Compeq Manufacturing Co., Ltd., Unimicron Technology Corporation, Zhen Ding Technology, AT&S, TTM Technologies, Samsung Electro-Mechanics, Daeduck Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Substrate-Like PCB Market Strategic Shifts
Process-material convergence is compressing traditional boundaries between semiconductor fabrication and PCB manufacturing, with equipment suppliers repositioning lithography and plating systems for intermediate-scale production.
Modified semi-additive process (mSAP) technology is fragmenting competitive positioning between subtractive-etch PCB houses and semiconductor packaging foundries. Automotive radar module suppliers in Germany are adopting mSAP for 50-micrometer line/space requirements. The technology is fragmenting vendor segmentation by enabling mid-scale substrate producers to capture qualification cycles previously reserved to captive semiconductor packaging operations.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing plasma etching equipment retrofits at European substrate pilot lines. Industrial consequence includes extended qualification timelines for halogen-free dielectric materials. Medical device substrate suppliers serving European OEMs are absorbing compliance costs through dedicated material grade segregation.
Consolidated procurement models among South Korean smartphone OEMs are compressing merchant substrate supplier margins. Tier-one electronics manufacturing services firms are establishing captive substrate packaging partnerships in Vietnam and India. This concentration is most visible in 5G modem package sourcing, where three OEMs control volume allocation decisions across East Asian fabrication capacity.
Global Substrate-Like PCB Market Segmentation
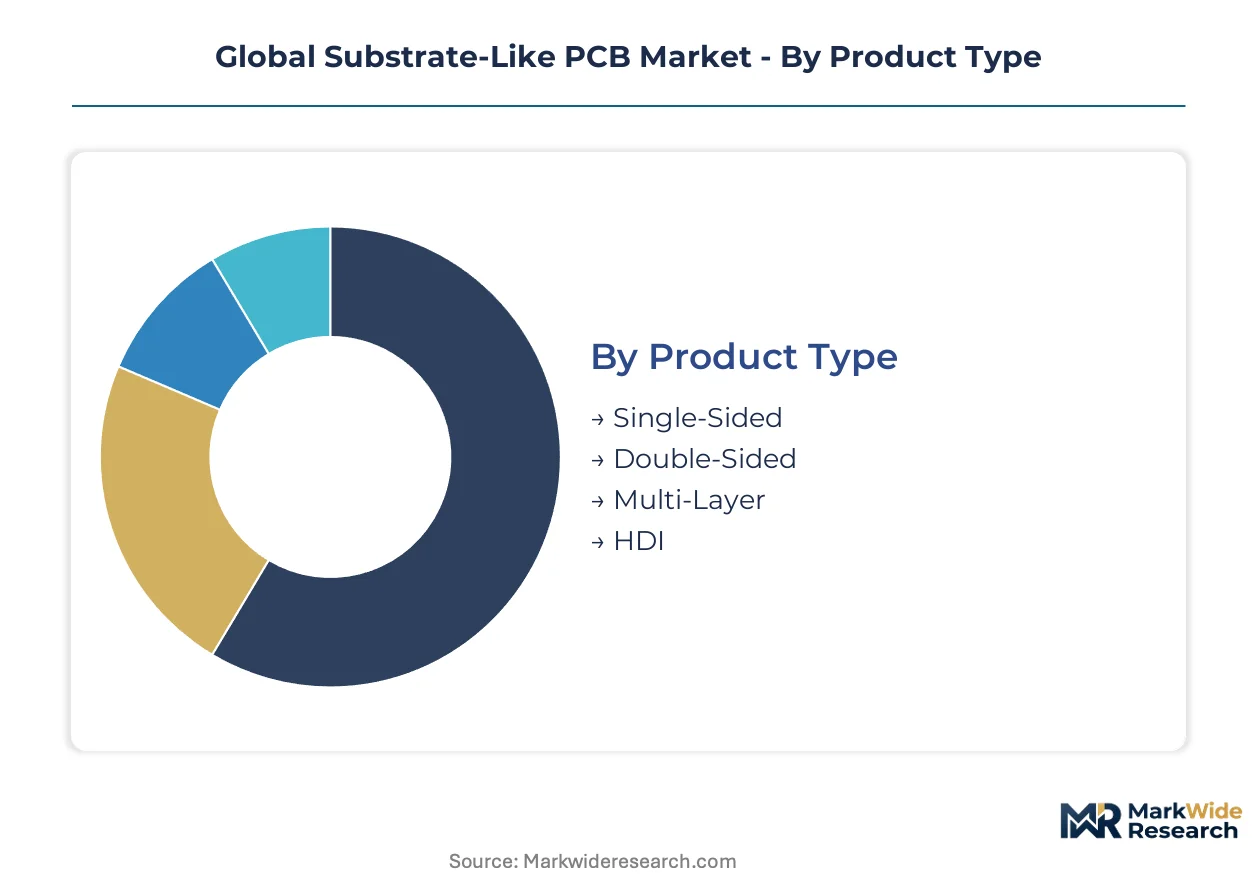
Substrate-like PCB segmentation reveals how semiconductor packaging-grade specifications fragment across end-use requirements. Material choices and layer counts diverge sharply between consumer electronics volume plays and medical device qualification cycles.
Product Type:
Substitution pressure from wafer-level packaging technologies intensifies for simpler configurations while multi-layer builds defend their position through stacked microvia complexity.
- Multi-Layer:Configurations stack dielectric layers under 30 micrometers with line/space geometries below 15 micrometers for chip-scale integration. South Korean smartphone OEMs absorb the majority of high-layer-count output for 5G modem packages, where RF front-end density requirements block simpler substitutes.
- HDI:High-density interconnect substrates command premium pricing from automotive radar module qualification cycles at 77GHz sensor specifications. German tier-one electronics suppliers are adopting modified semi-additive process technology to capture these certification timelines.
- Single-Sided:Basic configurations serve cost-constrained IoT peripheral applications where line density requirements remain above 50 micrometers.
- Double-Sided:Two-layer builds occupy the mid-market for industrial control hardware requiring moderate signal integrity without microvia stacking.
Multi-layer retains volume leadership; HDI holds the steepest expansion curve.
End User:
Customer concentration patterns split between consolidated procurement models in consumer electronics and fragmented qualification pools in regulated medical applications.
- Consumer Electronics:Smartphone and laptop OEMs in South Korea and Taiwan drive stacked microvia demand through consolidated volume allocation decisions. Three OEMs control substrate sourcing across East Asian fabrication capacity.
- Automotive:Radar module suppliers in Germany face EU REACH brominated flame retardant restrictions under ECHA oversight, accelerating material qualification cycles for halogen-free dielectric formulations.
- Telecommunications:5G infrastructure hardware requires intermediate layer counts for baseband processing modules.
- Medical Devices:Implantable device specifications under FDA electromagnetic compatibility standards constrain signal integrity requirements for US-bound shipments, while IEC 60601 biocompatibility testing opens flex-rigid configurations to polyimide alternatives.
Consumer electronics commands the largest revenue pool; medical devices delivers the highest margin tier.
Material:
Cost tier stratification separates commodity epoxy formulations from specialty polymers serving thermal and biocompatibility requirements.
- Epoxy:Volume-dominant resin systems anchor standard consumer electronics production despite EU REACH pressure on legacy flame retardant packages. Japanese chemical houses control proprietary ABF laminate formulations for high-layer-count builds.
- Polyimide:Flex-rigid substrates for medical devices confront raw material pricing volatility driven by aerospace composite demand competition. The material gains traction where biocompatibility testing under IEC 60601 governs selection.
- Ceramic:High-frequency applications in telecommunications infrastructure leverage thermal stability for millimeter-wave substrate requirements.
- FR-4:Standard glass-reinforced epoxy retains position in cost-sensitive IoT hardware where performance specifications permit conventional dielectric constants.
Epoxy maintains the broadest installed base; polyimide climbs the fastest on medical convergence.
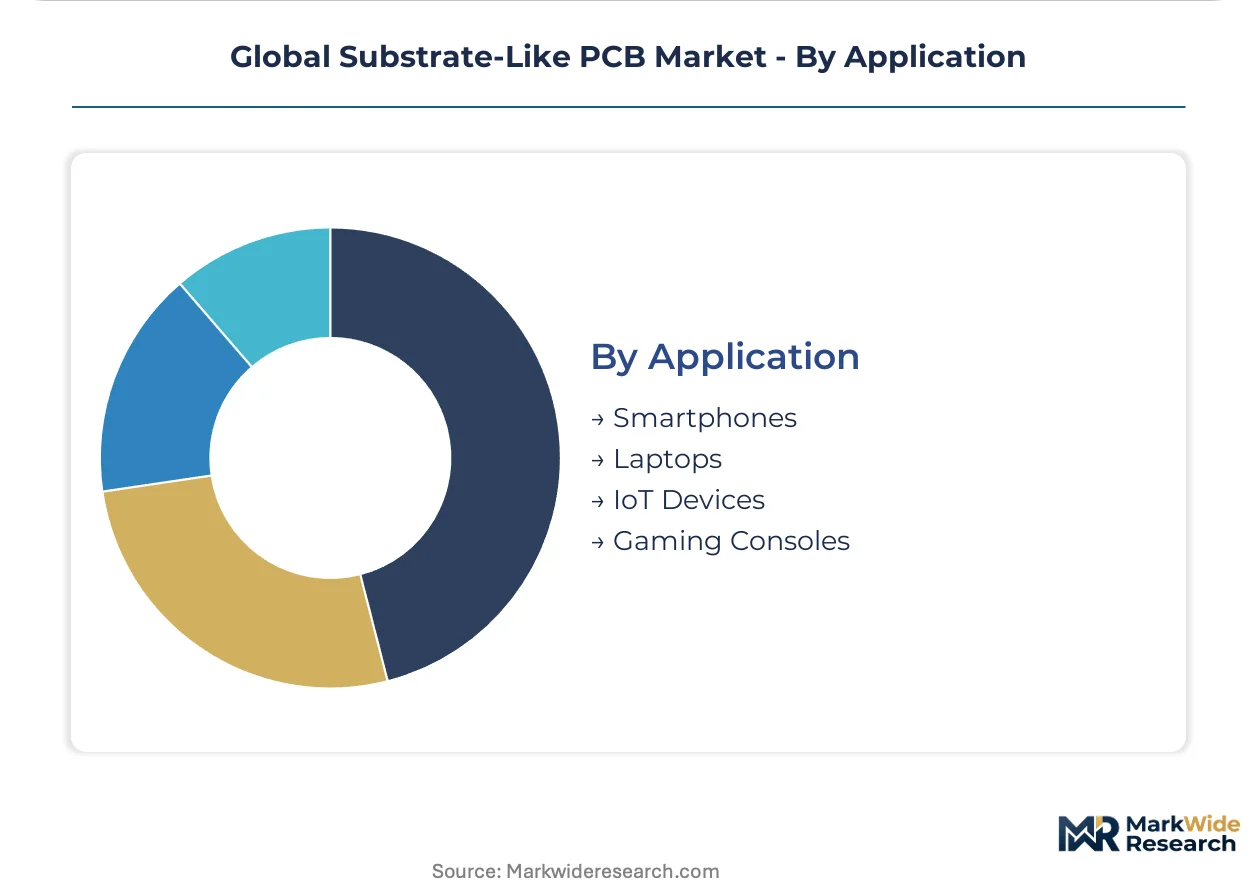
Application:
Device form factors dictate layer count and material flexibility requirements across portable electronics categories.
- Smartphones:5G modem packages pull specifications below 15-micrometer line/space geometries through RF front-end integration density. South Korean component houses absorb wafer-level packaging substrate volume through captive flip-chip BGA production lines.
- Laptops:Compute module substrates require intermediate HDI specifications for processor and memory interconnect without the extreme density of smartphone modems.
- IoT Devices:Sensor node hardware in China faces GB standards on hazardous substance limits administered by SAMR, mandating testing protocols for domestically sold units.
- Gaming Consoles:Graphics processing unit substrates demand high layer counts for memory bus routing in stationary form factors without portable flexibility constraints.
Smartphones dominate unit volume; IoT devices posts the steepest share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's MFDS semiconductor packaging regulations anchor the dominant geography, where substrate fabrication clusters absorb the majority of advanced smartphone substrate volume. Divergent chemical compliance regimes across export destinations fragment qualification protocols for multinational suppliers.
South Korea
Samsung Electro-Mechanics and Daeduck Electronics drive stacked microvia demand through captive flip-chip BGA production lines for 5G modem packages. MFDS hazardous substance oversight aligns with REACH-equivalent domestic standards for halogen-free dielectric formulations. The Seoul Capital Area concentration hosts wafer-level packaging substrate fabrication serving domestic smartphone OEM procurement.
Japan
Ibiden Co., Ltd. anchors proprietary ABF laminate development for high-layer-count builds in automotive radar modules. METI industrial standards govern material qualification cycles for export-bound European electronics under bilateral equivalency agreements. The Nagoya industrial corridor concentrates chemical substrate resin formulation expertise for semiconductor packaging-grade dielectrics.
Taiwan
Kinsus Interconnect Technology and Unimicron Technology Corporation leverage captive via-filling capabilities for wafer-level packaging output. The island's EPA-administered electronics manufacturing standards mandate testing protocols for halogen-free substrate exports to EU markets. Hsinchu Science Park hosts lithography equipment clusters facing trained engineer scarcity for sub-20-micrometer patterning.
China
Zhen Ding Technology and Compeq Manufacturing serve domestic smartphone assembly demand amid GB standards hazardous substance limits administered by SAMR. MIIT industrial policy directs substrate packaging investment toward IoT hardware certification for domestically sold units. The Yangtze River Delta concentration absorbs merchant substrate volume for laptop compute module specifications.
Germany
AT&S and automotive tier-one suppliers adopt modified semi-additive process technology for 77GHz radar sensor qualification cycles. ECHA REACH brominated flame retardant restrictions accelerate material reformulation timelines for export-bound substrate shipments. The Bavarian electronics corridor hosts pilot lines confronting EU F-Gas Regulation plasma etching equipment retrofit requirements.
Global Substrate-Like PCB Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with proprietary resin formulators and scale-driven fabricators occupying distinct competitive tiers. The market structure concentrates around captive semiconductor packaging operations and merchant substrate specialists serving overlapping but non-identical customer pools. Three strategic archetypes dominate: proprietary material developers controlling ABF laminate formulations, captive production lines at component houses absorbing wafer-level volume, and merchant fabricators competing on lithography capacity access. Dominant competitive moves include backward integration into chemical substrate resin production and geographic expansion into Vietnam and India assembly corridors.
Among East Asian fabricators, Kinsus Interconnect Technology, Ibiden Co., Ltd., and Samsung Electro-Mechanics exemplify the divergence between merchant and captive positioning. Kinsus occupies a position within the via-filling specialist tier serving external smartphone OEM procurement. Ibiden represents the proprietary material archetype through ABF laminate development. Samsung Electro-Mechanics anchors the captive integration model where in-house substrate production feeds directly to component assembly.
| Leading Market Players |
|---|
| Kinsus Interconnect Technology |
| Ibiden Co., Ltd. |
| Compeq Manufacturing Co., Ltd. |
| Unimicron Technology Corporation |
| Zhen Ding Technology |
| AT&S |
| TTM Technologies |
| Samsung Electro-Mechanics |
| Daeduck Electronics |
| Others |
Value Chain & Pricing Dynamics
Wafer-level packaging scale economies at South Korean component houses compress merchant supplier margins while anchoring price floors for advanced substrate tiers. Samsung Electro-Mechanics and Daeduck Electronics absorb captive volume through in-house flip-chip BGA lines, forcing external fabricators into allocation-driven pricing negotiations with consolidated smartphone OEM procurement pools.
Pricing Analysis
East Asian fabrication hubs command 40-60% premiums over European pilot-line output for equivalent layer-count specifications. Three-tier pricing structure across premium, standard, and economy levels separates automotive radar-qualified HDI substrates from consumer electronics multi-layer builds and cost-constrained IoT single-sided configurations. Cost compression in standard-tier smartphone substrates intensifies as consolidated South Korean OEM procurement pools squeeze merchant fabricator margins. Consumer electronics buyers exhibit extreme price sensitivity through volume allocation leverage, while medical device OEMs tolerate premium positioning for IEC 60601 biocompatibility certification.
Supply Chain Analysis
Japan and Taiwan anchor ABF laminate resin formulation and wafer-level packaging substrate fabrication respectively. Proprietary resin systems from Japanese chemical houses draw from brominated flame retardant precursor supply chains facing EU REACH substitution mandates. Single-source vulnerability concentrates in high-layer-count ABF laminate dependencies for semiconductor packaging-grade builds. Distribution runs through captive production lines at South Korean component houses and merchant fabricator direct contracts with smartphone OEM procurement divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through three South Korean smartphone OEMs controlling volume allocation decisions across East Asian fabrication capacity, fragmenting supplier negotiation leverage.
For Market Incumbents: Compound lithography capacity access advantages in Taiwan and South Korea before trained engineer scarcity hardens into structural constraint. Defend position by accelerating proprietary ABF laminate partnerships with Japanese chemical houses against merchant competitor encroachment. Prioritize captive via-filling capability investment to match Kinsus Interconnect Technology's wafer-level packaging output scale. For New Entrants and Emerging Players: Differentiate on automotive radar module qualification cycles where German tier-one electronics suppliers seek mSAP-capable substrate partners for 77GHz sensor specifications. Target India's PLI scheme electronics assembly corridors where smartphone contract manufacturers relocating from China create packaging substrate demand without incumbent supplier relationships. Lead with modified semi-additive process technology positioning to bypass lithography engineer scarcity constraints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors proprietary material developers controlling halogen-free dielectric formulations ahead of EU REACH enforcement expansion. Long-term viability hinges on substrate suppliers capturing medical device flex-rigid specifications where polyimide biocompatibility testing under IEC 60601 opens premium margin tiers. Watch for inflection when automotive radar module qualification cycles accelerate beyond German tier-one supplier mSAP adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Resin Production | Captive ABF laminate supply secures high-layer-count build capacity against Japanese chemical house concentration. |
| Geographic Expansion into Vietnam Assembly Corridors | Proximity to smartphone contract manufacturing relocation from China reduces logistics exposure to tariff volatility. |
| Modified Semi-Additive Process Technology Adoption | mSAP capability captures automotive radar qualification cycles previously reserved to semiconductor packaging foundries. |
| Halogen-Free Dielectric Certification Investment | EU REACH compliance accelerates material qualification timelines for export-bound European automotive electronics. |
| Captive Via-Filling Capability Scale-Up | Wafer-level packaging output matches South Korean component house integration models for smartphone OEM procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with substrate fabrication plant managers, smartphone OEM procurement directors, automotive tier-one electronics sourcing leads, and semiconductor packaging process engineers. Secondary validation drew from ECHA REACH substance restriction databases, MFDS hazardous substance oversight filings, SAMR GB standards documentation, and SEC 10-K disclosures from listed substrate manufacturers. Bottom-up capacity utilization estimates triangulated against top-down smartphone substrate bill-of-materials calculations.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product type (multi-layer, HDI, single-sided, double-sided), end user (consumer electronics, automotive, telecommunications, medical devices), material (epoxy, polyimide, ceramic, FR-4), and application (smartphones, laptops, IoT devices, gaming consoles). CAGRs derived from capacity expansion timelines, lithography equipment installation pipelines, and OEM procurement cycle visibility. Industry-specific inputs included trained lithography engineer pipeline data from East Asian technical universities and EU F-Gas Regulation equipment retrofit compliance schedules.
The analysis sits within stated boundaries; outcomes outside sustained smartphone 5G modem package complexity expansion or accelerated EU REACH halogen-free mandate enforcement would require recalibration. Forecasts reflect assumptions on semiconductor packaging-grade lithography capacity availability and ABF laminate resin supply continuity. Recalibration cycles align with material shifts in automotive radar module qualification timelines and India PLI scheme electronics assembly investment trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market
Semiconductor Devices
Global Semiconductor Device Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Global Automotive Mosfets Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Data Processing Unit Market