
 VCSEL for Data Communication Market | 2026-2036
VCSEL for Data Communication Market Size, Share, and Industry Trends Forecast 2026-2036
VCSEL for Data Communication Market Analysis
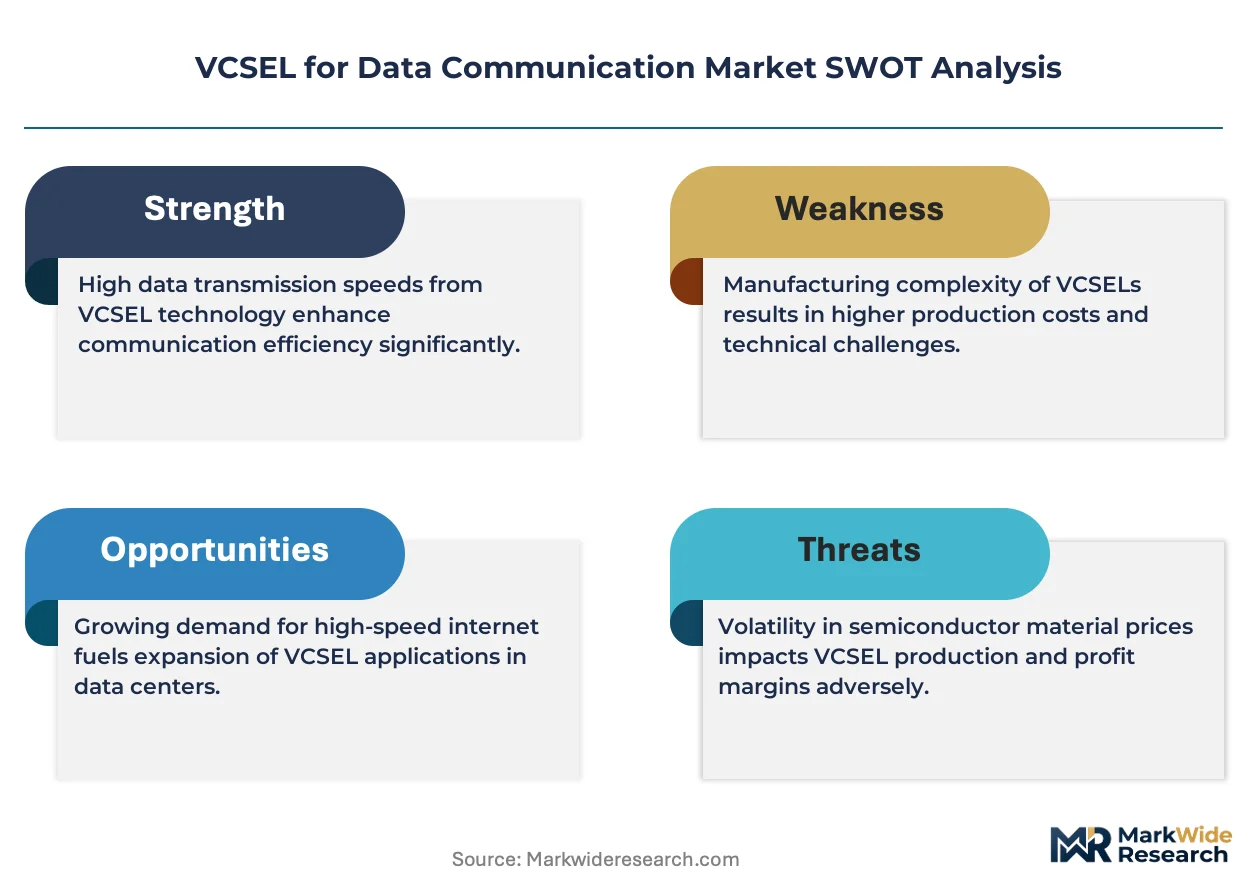
Modular transceiver packaging is decoupling VCSEL arrays from integrated driver electronics, giving buyers flexibility to mix semiconductor sources across generations. Lumentum Operations LLC leverages vertical integration to control epitaxial wafer supply for high-volume data center contracts. Coherent Corp. anchors its position through sustained R&D intensity in long-wavelength VCSEL architectures. Broadcom differentiates by dominating the merchant market for 850 nm multimode solutions in enterprise switching.
VCSEL for Data Communication refers to vertical-cavity surface-emitting lasers engineered with distributed Bragg reflector mirrors and active regions typically 1-3 quantum wells thick, emitting perpendicular to the wafer surface at wavelengths of 850 nm, 980 nm, or longer for fiber-optic transmission. These devices serve as the primary light source in short-reach optical interconnects, converting electrical signals into modulated optical output for multi-gigabit data links. Multi-mode VCSEL technology occupies the mature volume tier for data center networking applications up to 100 meters, while single-mode variants are capturing the fastest expansion in telecommunications backhaul where reach extends beyond 500 meters. Long-wavelength technology above 980 nm concentrates margin pools as silicon photonics integration demands higher-performance sources for co-packaged optics architectures.
FCC equipment authorization rules shape transmitter certification timelines for VCSEL modules entering US data center infrastructure, while OSHA laser safety standards govern deployment thresholds in densely staffed telecom facilities. The EU RoHS directive and REACH chemical restrictions constrain gallium arsenide substrate sourcing and indium phosphide integration pathways for European-bound products. Stakeholders must monitor how IEEE 802.3 standards evolution toward 800G and 1.6T Ethernet redefines VCSEL bandwidth and thermal density requirements before committing next-generation fab capacity.
Market Dynamics
Co-packaged optics architectures are compressing link distances inside data center switches, forcing VCSEL suppliers to requalify thermal and electrical performance at sub-millimeter proximity to silicon photonics dies.
Growth Catalysts
- China's MIIT dual carbon goals:GB standards for energy-efficient data center infrastructure mandate lower power-per-bit transmission, accelerating adoption of 850 nm and 980 nm VCSEL arrays in domestic cloud facilities.
- Hyperscale cloud campus expansion:Virginia and Oregon data center clusters are driving concentrated demand for multi-mode optical interconnects below 100 meters, pulling VCSEL volume through transceiver module contracts.
- IEEE 802.3 evolution:Standards progression toward 800G and 1.6T Ethernet redefines bandwidth density requirements, creating specification pull for next-generation VCSEL designs before fab capacity commitments lock in.
Market Restraints
- Gallium arsenide substrate concentration:Epitaxial wafer supply chains cluster in East Asian foundries, exposing buyers to single-source risk for distributed Bragg reflector mirror stacks.
- EU RoHS and REACH chemical restrictions:Indium phosphide integration pathways face constrained sourcing for European-bound products, limiting long-wavelength VCSEL manufacturing flexibility.
- Silicon photonics substitution:External laser sources for co-packaged optics threaten to displace direct VCSEL integration in reach segments above 500 meters.
Strategic Opportunities
- Telecommunications backhaul expansion:Single-mode VCSEL variants above 980 nm capture fastest expansion in 500-meter-plus links where reach requirements exceed multi-mode capability.
- Modular transceiver packaging:Decoupling VCSEL arrays from integrated driver electronics gives buyers flexibility to mix semiconductor sources across generations, opening merchant component markets.
- OSHA laser safety compliance services:Dense telecom facility deployments create demand for certified installation protocols and power-threshold monitoring systems.
Industry Challenges
- Quantum well epitaxy talent scarcity:Active region fabrication requiring 1-3 quantum well precision faces limited specialist availability in optoelectronics foundries.
- FCC equipment authorization timelines:Transmitter certification delays for US data center infrastructure compress product launch windows against IEEE standard ratification schedules.
- Thermal density qualification:Sub-millimeter proximity to silicon photonics dies demands new reliability testing protocols that extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VCSEL for Data Communication Market |
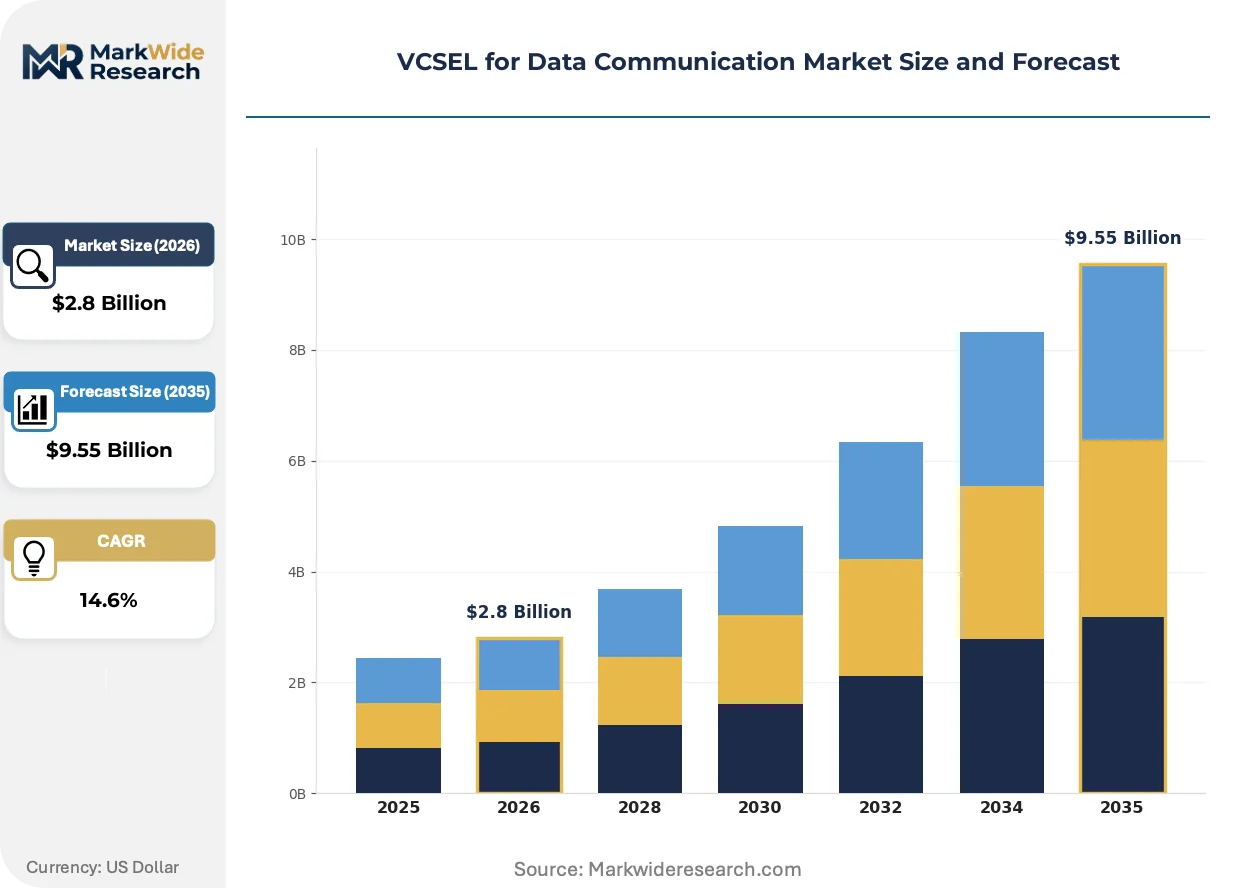
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode VCSEL, Multi-Mode VCSEL, High-Power VCSEL, Ultrafast VCSEL Application: Telecommunications, Data Center Networking, Optical Interconnects, Consumer Electronics End User: Telecom Operators, Enterprises, Data Centers, OEMs Technology: Short-Wavelength, Long-Wavelength, 850 nm, 980 nm |
| Companies Covered | Hamamatsu Photonics K.K, Coherent Corp., Lumentum Operations LLC, II-VI Incorporated, ams-OSRAM AG, TRUMPF, Broadcom, Bandwidth10, Vertilas GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VCSEL for Data Communication Market Emerging Trajectories
Long-wavelength VCSEL architectures are converging with silicon photonics integration requirements, reshaping how suppliers partition optical and electrical functions inside data center switches.
Single-mode VCSEL technology operating above 980 nm is converging with co-packaged optics requirements for 500-meter-plus telecommunications backhaul. Cloud networking operators in hyperscale campuses are qualifying these sources for disaggregated switch architectures. The structural consequence is compressing merchant markets for external laser sources while elevating captive VCSEL design capabilities.
China's MIIT GB standards for data center energy efficiency are tightening power-per-bit thresholds for optical interconnects. Domestic cloud operators must demonstrate compliance with dual carbon goals through documented transmission efficiency metrics. Long-wavelength VCSEL suppliers targeting Chinese infrastructure face accelerated thermal performance requalification cycles.
Transceiver procurement is fragmenting between integrated module vendors and component-agnostic system builders. Hyperscale operators in Virginia and Oregon are unbundling VCSEL array sourcing from driver electronics to preserve generational mixing flexibility. This pattern concentrates in North American cloud campuses where multi-source qualification programs are standard practice.
VCSEL for Data Communication Market Segmentation
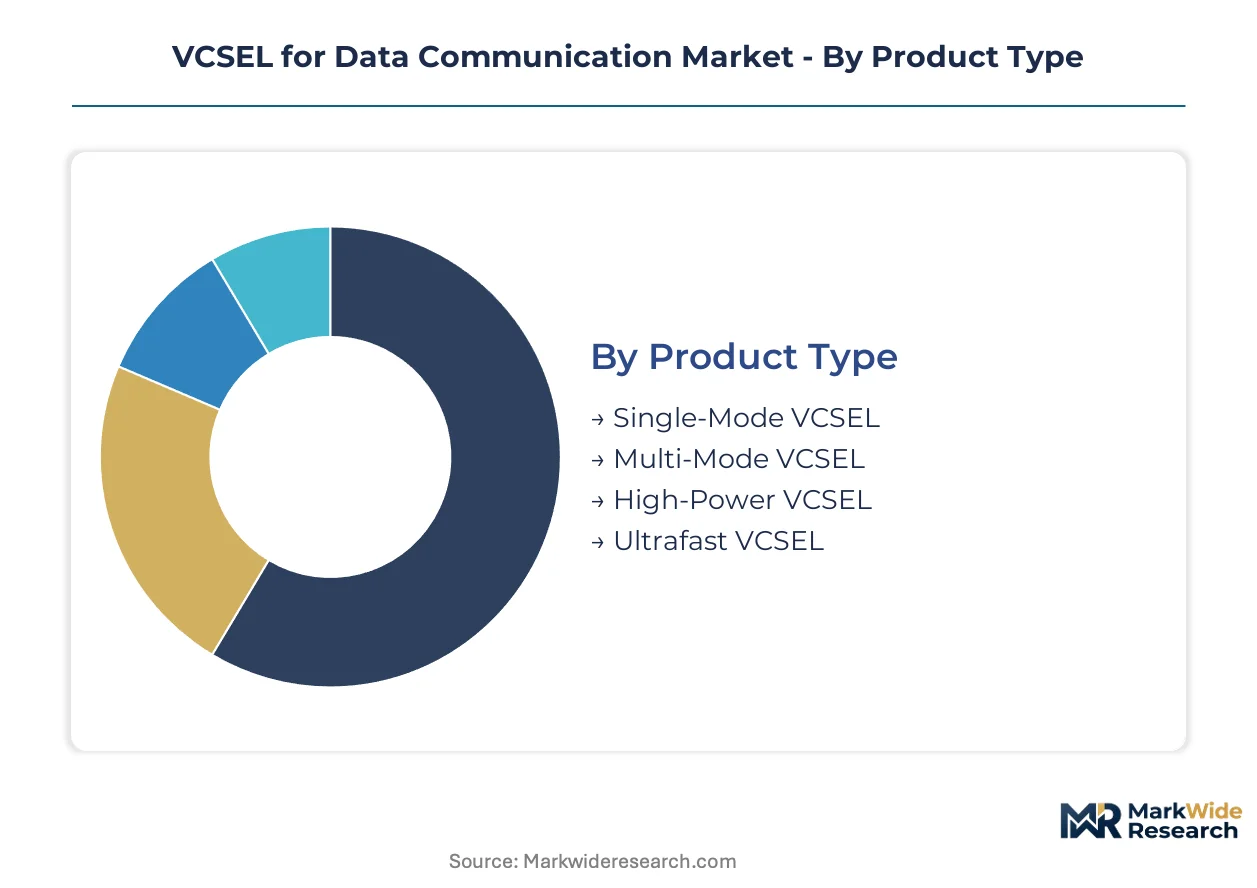
VCSEL segmentation reveals how capital allocation, wavelength engineering, and customer procurement patterns partition value across the data communication supply chain. Distinct technical requirements and qualification timelines separate segments with radically different margin profiles.
Product Type:
Capital intensity peaks with epitaxial wafer fabrication and quantum well precision, creating divergent barriers to entry across device architectures.
- Single-Mode VCSEL:Distributed Bragg reflector mirrors and narrow aperture design enable 500-meter-plus reach for telecommunications backhaul. Demand concentrates in hyperscale cloud campuses in Virginia and Oregon where disaggregated switch architectures require extended link distances.
- Multi-Mode VCSEL:Larger aperture geometry and 850 nm emission dominate short-reach optical interconnects below 100 meters. Data center networking operators in United States facilities pull volume through transceiver module contracts requiring proven thermal reliability.
- High-Power VCSEL:Arrays stack multiple emitters for parallel optical channels demanding elevated output density.
- Ultrafast VCSEL:Modulation bandwidth above 50 GHz targets next-generation 800G and 1.6T Ethernet interfaces.
Multi-Mode VCSEL absorbs the bulk of installed capacity; Single-Mode VCSEL is expanding most quickly.
Application:
End-use differentiation tracks link distance requirements and thermal density constraints inside switching equipment.
- Data Center Networking:Short-reach interconnects below 100 meters constitute the volume anchor for 850 nm multi-mode deployment. United States hyperscale operators in Virginia and Oregon drive concentrated procurement through multi-source qualification programs.
- Telecommunications:Single-mode architectures above 980 nm capture backhaul expansion where reach exceeds 500 meters. China's MIIT dual carbon goals accelerate energy-efficient laser adoption in domestic cloud facilities.
- Optical Interconnects:Board-level and chip-to-chip links inside servers demand sub-millimeter proximity tolerance.
- Consumer Electronics:3D sensing and LiDAR applications pull 940 nm VCSEL volume outside traditional data communication.
Data Center Networking commands the dominant share of wafer starts; Telecommunications claims the steepest expansion trajectory.
End User:
Procurement authority concentrates with operators controlling transceiver module specifications and multi-source qualification timelines.
- Data Centers:Hyperscale cloud campuses in Virginia and Oregon unbundle VCSEL array sourcing from driver electronics to preserve generational mixing flexibility. United States facilities dominate merchant demand for multi-mode solutions.
- Telecom Operators:Backhaul network expansion drives single-mode qualification above 980 nm for 500-meter-plus links. China's domestic cloud operators face accelerated thermal performance requalification under MIIT GB standards.
- Enterprises:Campus and metro networks rely on merchant transceiver modules with standardized 850 nm interfaces.
- OEMs:Switch and server manufacturers integrate VCSEL arrays into co-packaged optics architectures.
Data Centers absorb the bulk of installed capacity; Telecom Operators are climbing the fastest.
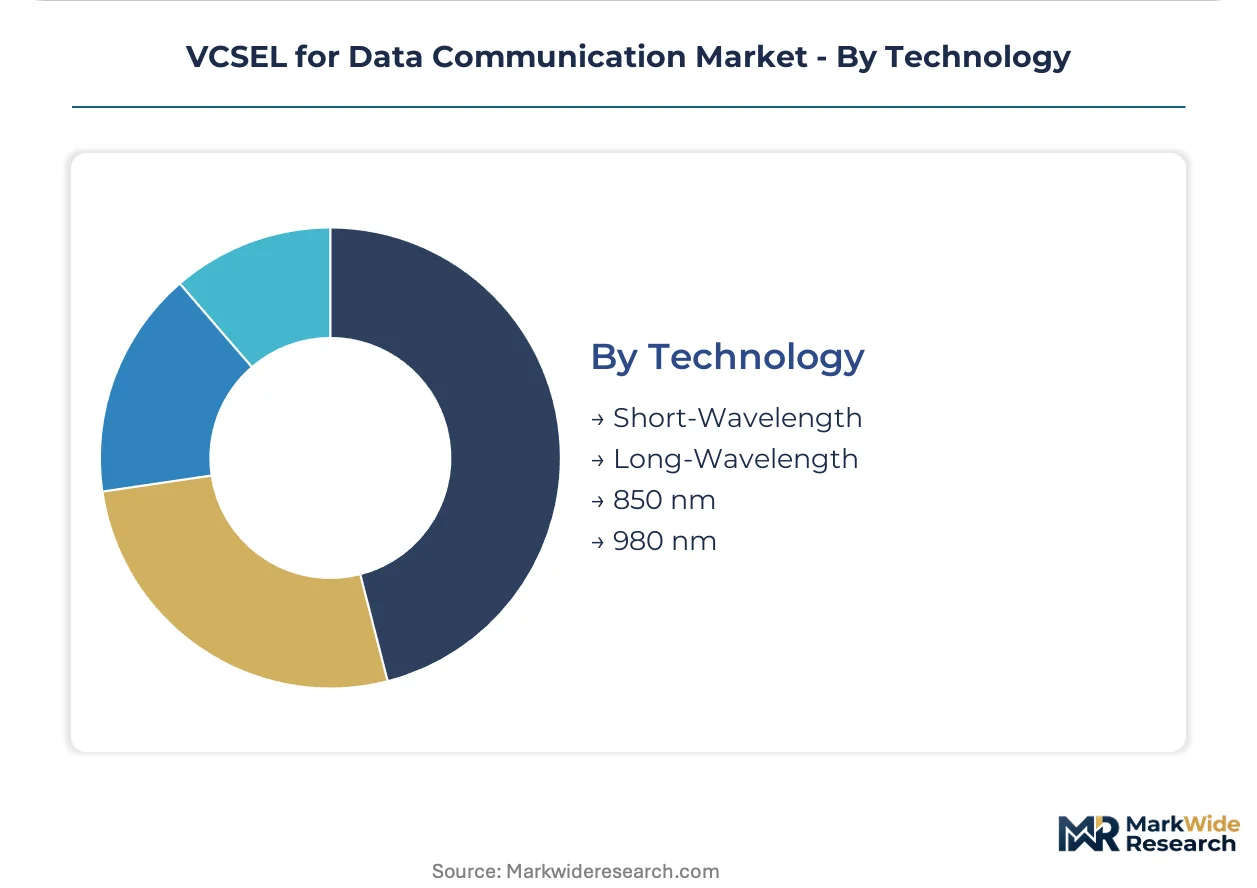
Technology:
Wavelength selection determines substrate material, epitaxial complexity, and compatibility with silicon photonics integration.
- 850 nm:Gallium arsenide substrate and mature multi-mode architecture anchor enterprise switching and short-reach data center applications. Broadcom dominates this merchant market segment through high-volume supply agreements.
- Long-Wavelength:Indium phosphide integration enables 980 nm-plus emission for telecommunications backhaul and co-packaged optics. Coherent Corp. anchors position through sustained R&D intensity in these architectures.
- Short-Wavelength:Below 850 nm variants target specialized sensing and emerging interconnect applications.
- 980 nm:Intermediate wavelength bridges multi-mode volume and single-mode reach requirements.
850 nm absorbs the bulk of installed capacity; Long-Wavelength is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
VCSEL fabrication concentrates in East Asian foundries while consumption clusters in North American hyperscale campuses and Chinese cloud facilities. This production-consumption divide shapes supply chain risk profiles and qualification timelines across regions.
United States
Hyperscale operators in Virginia and Oregon data center campuses drive concentrated demand for multi-mode optical interconnects below 100 meters. FCC equipment authorization rules govern transmitter certification timelines for modules entering domestic infrastructure. Cloud networking procurement in these clusters unbundles VCSEL sourcing from driver electronics to preserve generational mixing flexibility.
China
Domestic cloud operators face accelerated thermal performance requalification under MIIT GB standards for energy-efficient data center infrastructure. The country's dual carbon goals mandate documented power-per-bit transmission efficiency metrics for optical interconnect deployments. Yangtze River Delta fabrication clusters supply epitaxial wafers for distributed Bragg reflector mirror stacks serving both domestic and export markets.
Germany
EU RoHS directive and REACH chemical restrictions constrain gallium arsenide substrate sourcing and indium phosphide integration pathways for European-bound VCSEL products. ECHA regulatory oversight shapes material compliance timelines for long-wavelength architectures targeting telecommunications backhaul. Industrial laser specialists in Baden-Württemberg anchor precision optics manufacturing for test and measurement equipment serving the sector.
Japan
METI industrial policy supports optoelectronics R&D intensity in long-wavelength VCSEL architectures above 980 nm. JIS standards govern reliability testing protocols for devices deployed in densely staffed telecom facilities. Kanto region precision manufacturing clusters produce quantum well epitaxy equipment and characterization systems for active region fabrication.
South Korea
Seoul Capital Area semiconductor foundries supply backend packaging and testing services for VCSEL arrays bound for data center transceiver modules. MFDS regulatory frameworks apply to laser safety certification for medical-adjacent applications expanding from data communication technology. Memory and logic chip manufacturers in Busan-Ulsan drive co-packaged optics integration demand for sub-millimeter proximity applications.
VCSEL for Data Communication Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists controlling epitaxial wafer supply. Three tiers separate captive designers serving hyperscale operators, merchant component suppliers, and precision equipment fabricators. Strategic differentiation runs through backward integration into substrate sourcing, sustained R&D intensity in long-wavelength architectures, and modular packaging flexibility. M&A activity concentrates on quantum well epitaxy capabilities while capacity expansion targets 800G and 1.6T Ethernet qualification timelines.
Among North American-based suppliers, Lumentum Operations LLC exemplifies the vertically integrated archetype through captive control of high-volume data center contracts. Coherent Corp. occupies a position representing sustained R&D intensity in long-wavelength architectures above 980 nm. Broadcom anchors the merchant market tier for 850 nm multimode solutions in enterprise switching applications. These three patterns—integration depth, research intensity, and merchant scale—structure competitive positioning across procurement segments.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K |
| Coherent Corp. |
| Lumentum Operations LLC |
| II-VI Incorporated |
| ams-OSRAM AG |
| TRUMPF |
| Broadcom |
| Bandwidth10 |
| Vertilas GmbH |
| Others |
Supply Flow & Price Mechanics
Vertically integrated specialists controlling epitaxial wafer supply exercise asymmetric pricing power over merchant module vendors, while private-equity-rolled-up packaging houses in South Korea compress assembly margins through scale-based procurement leverage.
Pricing Analysis
Cost-down pressure on 850 nm multi-mode arrays accelerates because hyperscale operators in Virginia and Oregon unbundle VCSEL sourcing from driver electronics to force component-level competition. Three-tier pricing structure across premium long-wavelength, standard 980 nm, and economy 850 nm tiers separates qualification-intensive single-mode designs from commodity multi-mode volume. Price differentiation hinges on IEEE 802.3 certification tier and thermal density specification, with telecom backhaul buyers least price-sensitive and enterprise switching procurement most sensitive to per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with gallium arsenide substrate fabrication clustering in Taiwan and Japan, while distributed Bragg reflector mirror stacks draw from Yangtze River Delta foundries in China. Raw material dependencies center on high-purity gallium arsenide wafers, indium phosphide substrates for long-wavelength architectures, and specialty gases for metal-organic chemical vapor deposition. Tariff exposure on epitaxial equipment imports threatens cost structures, with distribution running through transceiver module vendors qualified by hyperscale cloud operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-wavelength VCSEL architectures above 980 nm are displacing legacy 850 nm multi-mode dominance in telecommunications backhaul, compressing the window for backward integration investments before silicon photonics substitution accelerates.
For Market Incumbents: Deepen captive control of epitaxial wafer supply through qualification timelines that lock hyperscale operators into multi-year contracts before IEEE 802.3 standards ratification. Expand thermal testing protocols for sub-millimeter proximity to silicon photonics dies to defend against external laser source substitution in co-packaged optics architectures. For New Entrants and Emerging Players: Modular transceiver packaging specialists seeking generational mixing flexibility represent an underserved buyer archetype unbundling VCSEL arrays from integrated driver electronics. Target China's domestic cloud operators facing MIIT GB standard requalification with thermal performance documentation services, using OSHA laser safety compliance certification as the go-to-market wedge against established module vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor quantum well epitaxy specialists in Japan and South Korea where talent scarcity has compressed valuation multiples for precision active region fabrication capabilities. Long-term viability over the projection horizon rests on positioning for 800G and 1.6T Ethernet qualification timelines, with the signal to monitor being IEEE 802.3 standards ratification schedules locking in fab capacity commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Lumentum's captive control of distributed Bragg reflector mirror stacks locks hyperscale data center contracts against merchant competition. |
| Long-Wavelength R&D Intensity | Coherent Corp.'s sustained investment in 980 nm-plus architectures anchors position for telecommunications backhaul expansion. |
| Modular Transceiver Packaging | Decoupling VCSEL arrays from driver electronics gives Virginia and Oregon cloud campuses generational mixing flexibility. |
| Thermal Performance Requalification | China's MIIT GB standards force documented power-per-bit efficiency metrics for domestic cloud operator compliance. |
| OSHA Laser Safety Certification | Dense telecom facility deployments in United States create demand for certified installation protocols and power-threshold monitoring systems. |
Methodological Framework
SEC filings from Lumentum Operations LLC, Coherent Corp., and Broadcom, alongside IEEE 802.3 standards documentation and FCC equipment authorization databases, formed the secondary backbone. Primary interviews with epitaxial wafer procurement managers at hyperscale cloud operators, thermal test engineers at transceiver module vendors, quantum well epitaxy specialists at optoelectronics foundries, and regulatory compliance officers at telecom equipment manufacturers combined with bottom-up and top-down triangulation across these sources.
Historical trendline analysis of VCSEL array shipments tracked wavelength migration patterns and thermal density qualification timelines across the modeling period. Segmentation dimensions modeled include device architecture, application by link distance tier, end-user procurement authority, and technology by substrate material compatibility. CAGRs derived from curve-fitting against hyperscaler capex disclosure trajectories, with forecast inputs incorporating MIIT dual carbon goal compliance deadlines and IEEE 802.3 evolution schedules.
Revisions become necessary when silicon photonics substitution accelerates beyond 500-meter reach segments, gallium arsenide substrate supply concentrates further in East Asian foundries, or EU RoHS restrictions tighten indium phosphide integration pathways. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Transceiver Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Global Optical Diode Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Laser Photomask Market
Optical Components
Erbium Oxide Market
Optical Components
Optical Transmitter Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Liquid Lenses Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Nonlinear Optical Crystals Market