
 Indicator Lights Market | 2026-2036
Indicator Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Indicator Lights Market Analytics
REACH is recalibrating the cost-of-entry calculus for indicator light suppliers serving European industrial and automotive customers. Signify Holding leverages its vertical integration across LED chip fabrication and luminaire assembly to sustain margin resilience under tightening substance restrictions. ams OSRAM anchors its competitive position through deep specialization in high-reliability automotive indicator modules with extended temperature ratings.
Indicator lights are electroluminescent signaling devices, typically employing semiconductor junctions, noble gas discharge, or resistive filament excitation to emit visible radiation within specified chromaticity coordinates and candela outputs. These devices perform critical status-communication functions across human-machine interfaces, where immediate visual recognition of equipment state prevents operational error or safety incidents. LED product types command the dominant value share given their superior luminous efficacy and operational lifespan, while smart lighting technology segments attract the fastest investment inflows as IoT-enabled status indicators gain traction in predictive maintenance architectures. Neon and halogen categories occupy diminishing but defensible niches in legacy aviation and explosion-proof industrial settings where certification inertia preserves incumbent supply relationships.
The US EPA and OSHA frameworks govern workplace visibility and hazardous location illumination standards that directly shape product specification requirements for industrial machinery applications. China's GB standards and MIIT technical regulations mandate energy efficiency thresholds and electromagnetic compatibility testing that condition market access for imported indicator assemblies. ECHA's SVHC candidate list and RoHS substance restrictions compel continuous reformulation of phosphor coatings and solder alloys across the supply base. Stakeholders must monitor the divergence between regional material compliance regimes and the accelerating consolidation of wireless-enabled smart indicator platforms to calibrate portfolio and certification investments.
Market Dynamics
Automotive electrification is compressing design cycles for dashboard indicator modules while forcing simultaneous compliance with tightening substance restrictions across multiple jurisdictions.
Growth Catalysts
- EU Green Deal ecodesign mandates:The European Commission's accelerating incandescent-to-LED substitution requirements are pulling forward replacement demand across German automotive supplier networks and industrial machinery OEMs.
- Industrial automation expansion:China's MIIT technical regulations for smart factory equipment are embedding multi-status LED indicators into programmable logic controller interfaces across Shenzhen and Suzhou manufacturing zones.
- Predictive maintenance architectures:IoT-enabled indicator systems with wireless feedback loops are penetrating process industries where downtime costs justify premium sensor-luminaire integration.
Market Restraints
- Phosphor coating reformulation costs:ECHA's SVHC candidate list expansions are forcing continuous reformulation of rare-earth dopant chemistries, compressing margins for mid-tier LED packaging houses.
- Substrate supply concentration:Sapphire wafer and silicon carbide substrate production clusters in East Asian foundries create vulnerability to logistics disruptions and export control friction.
- Aviation certification inertia:FAA and EASA type certification timelines for legacy neon indicator replacements in cockpit annunciator panels extend 18-36 months, freezing incumbent supplier relationships.
Strategic Opportunities
- Explosion-proof industrial retrofits:ATEX and IECEx certification gaps in Eastern European petrochemical facilities create whitespace for LED indicator suppliers with hazardous location expertise.
- Smart city traffic infrastructure:NHTSA's vehicle-to-infrastructure communication standards are opening specification windows for networked pedestrian crossing and traffic signal indicators with embedded sensors.
- Dual carbon alignment in China:The country's 2060 carbon neutrality targets are accelerating municipal procurement of solar-powered LED indicator systems for off-grid applications in western provinces.
Industry Challenges
- Optoelectronics talent scarcity:Compound semiconductor packaging engineers with thermal management expertise for automotive grade indicators command 40% wage premiums, constraining expansion timelines.
- Cross-regulatory testing burden:Suppliers serving multiple automotive OEMs must simultaneously maintain GB, ECE, and SAE compliance test matrices, extending product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indicator Lights Market |
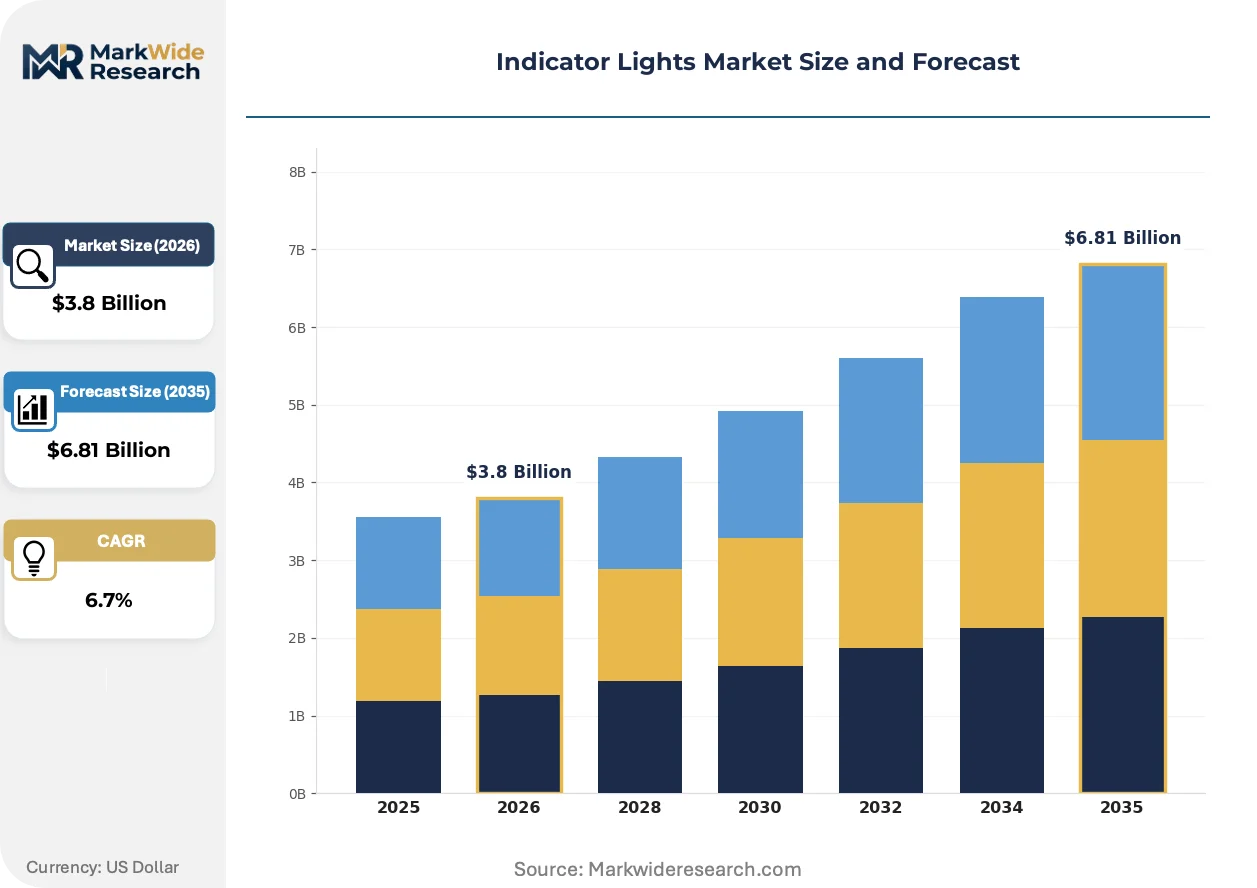
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Incandescent, Neon, Halogen Application: Automotive, Industrial Machinery, Home Appliances, Aviation Technology: Smart Lighting, Traditional Lighting, Fiber Optic, Wireless End User: Manufacturers, Retailers, Installers, Consumers |
| Companies Covered | Signify Holding, Acuity Brands, ams OSRAM, Panasonic Holdings Corporation, Legrand, Lutron Electronics, Schneider Electric, LEDVANCE, Zumtobel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indicator Lights Market Evolving Landscape
Multi-spectral indicator modules with integrated diagnostics are displacing single-function devices across safety-critical applications, compressing supplier differentiation to firmware and thermal design capabilities.
Chip-on-board LED architectures with direct thermal path substrates are consolidating the mid-power indicator segment. Automotive Tier 1 suppliers in Germany and Japan are adopting these packages for instrument cluster backlighting. The technology is consolidating vendor tiers by collapsing discrete LED, lens, and heat sink sourcing into single-source module procurement.
REACH substance restriction expansions are recalibrating phosphor and solder alloy formulations across European manufacturing bases. Industrial machinery OEMs in Northern Italy and the Netherlands are accelerating supplier audits for cadmium and lead content compliance. High-reliability automotive indicator modules with extended temperature ratings face the steepest reformulation cost curves.
Specification authority is migrating from maintenance departments to corporate sustainability offices in Fortune 500 industrial accounts. Energy service companies are bundling LED indicator retrofits into facility-wide lighting-as-a-service contracts, displacing traditional electrical distributor channels. This pattern is most pronounced in US Midwest manufacturing belts and German Ruhr industrial corridors.
Indicator Lights Market Segmentation
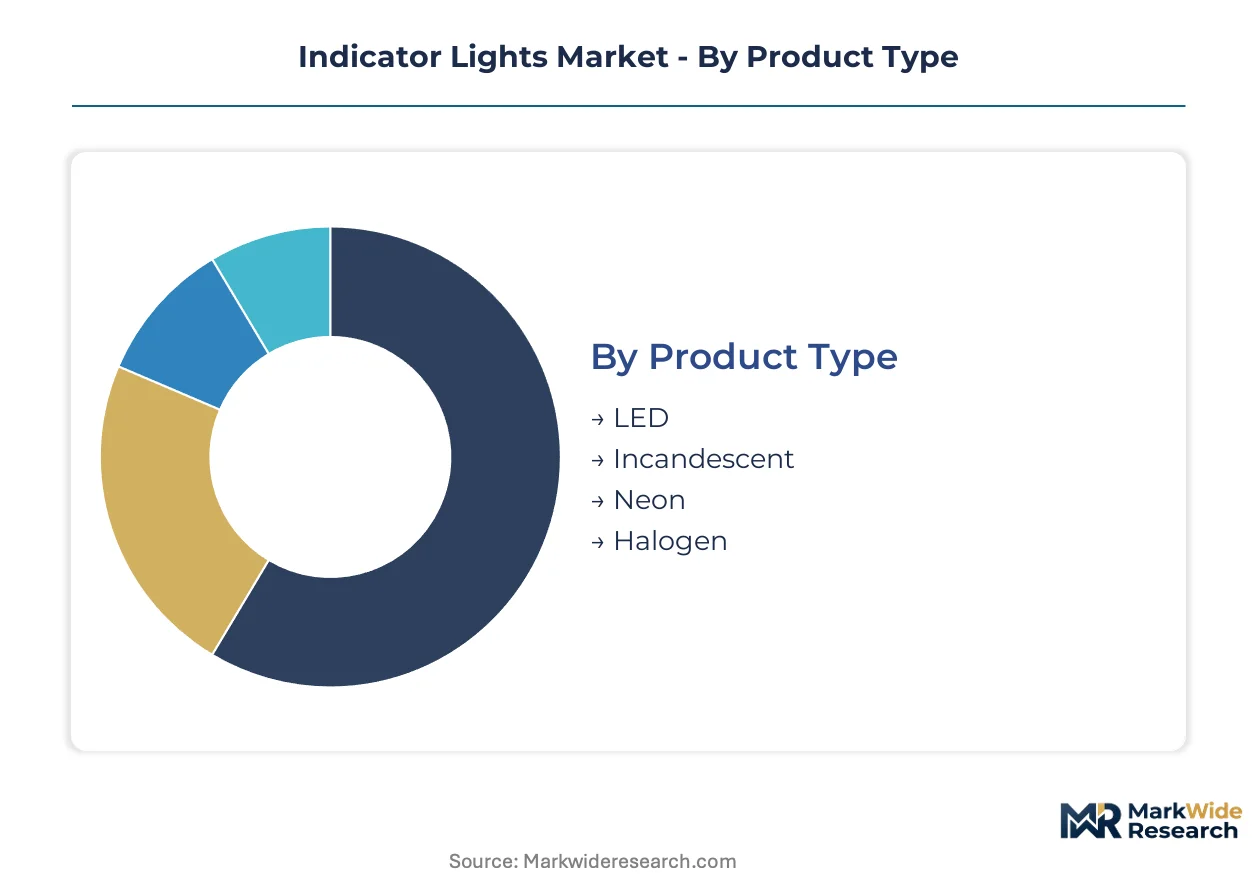
Segmentation in the indicator lights market reveals how specification requirements diverge across safety-critical and cost-sensitive applications. Technology choices, regulatory compliance tiers, and procurement channel structures each create distinct competitive battlegrounds with different margin profiles and certification barriers.
Product Type:
Semiconductor junction technologies dominate specification sheets where luminous efficacy and operational lifespan determine total cost of ownership calculations.
- LED:Solid-state electroluminescence through compound semiconductor junctions delivers 50,000-100,000 hour operational lifespans with minimal thermal degradation. Automotive electrification in Germany and China's industrial automation corridors are embedding multi-color SMD LED indicators into dashboard modules and PLC interfaces as standard configuration.
- Incandescent:Resistive filament excitation through tungsten wire in inert gas envelopes produces warm color temperatures but suffers rapid lumen depreciation. EU Green Deal ecodesign mandates are accelerating phase-out timelines across European manufacturing bases, compressing residual demand to legacy aviation and budget appliance segments.
- Neon:Noble gas discharge through glass tubes generates distinctive orange-red chromaticity with exceptional visibility in fog and vibration environments. FAA and EASA certification inertia preserves incumbent supply relationships in cockpit annunciator panels despite LED substitution pressure.
- Halogen:Tungsten-halogen regenerative cycles extend filament life versus conventional incandescent designs while maintaining compact form factors. Explosion-proof industrial settings with ATEX certification requirements retain halogen indicators where LED thermal management remains unproven.
Mature deployment sits with Incandescent. Newer deployment is concentrated in LED.
Application:
End-use environments impose divergent reliability standards, from consumer appliance cost floors to aviation failure-mode probabilities.
- Automotive:Instrument cluster backlighting and dashboard status indicators face simultaneous pressure for multi-color customization and REACH substance compliance. Tier 1 suppliers in Germany and Japan are consolidating discrete component sourcing into chip-on-board module procurement.
- Industrial Machinery:Programmable logic controller interfaces and safety interlock systems demand IP-rated housings with extended temperature specifications. China's MIIT technical regulations for smart factory equipment are mandating embedded multi-status indicators with electromagnetic compatibility certification.
- Home Appliances:White goods control panels prioritize cost-optimized through-hole LED packages with basic on/off signaling functions. Major appliance OEMs in Turkey and Mexico are standardizing on single-source indicator module procurement to simplify supply chains.
- Aviation:Cockpit annunciator panels require FAA TSO-C30c certification with demonstrated mean time between failures exceeding 50,000 hours. Neon indicator incumbency persists due to 18-36 month type certification timelines for LED alternatives.
Procurement consolidation is most advanced in Automotive. Specification fragmentation persists in Industrial Machinery.
Technology:
Connectivity integration is recalibrating value capture from hardware luminaires to firmware-enabled diagnostic platforms.
- Smart Lighting:IoT-enabled indicators with wireless feedback loops and predictive maintenance algorithms command premium positioning. Process industries with downtime costs exceeding $100,000 per hour are justifying sensor-luminaire integration in German chemical corridors.
- Traditional Lighting:Passive electromechanical indicators without data connectivity remain standard for cost-constrained applications. Budget appliance manufacturers in Southeast Asia continue specifying basic LED packages without communication protocols.
- Fiber Optic:Light guide transmission from remote sources enables indicator placement in explosive or high-EMI environments without electrical components at the point of indication. Oil and gas facilities in the North Sea and Gulf of Mexico deploy fiber optic indicators in Zone 0 hazardous locations.
- Wireless:Bluetooth Low Energy and Zigbee protocols enable battery-powered indicator deployment without conduit installation. Solar-powered LED indicator systems for off-grid traffic infrastructure in western China are adopting wireless mesh networking for centralized monitoring.
Volume concentration favors Traditional Lighting. Margin expansion is concentrating in Smart Lighting.
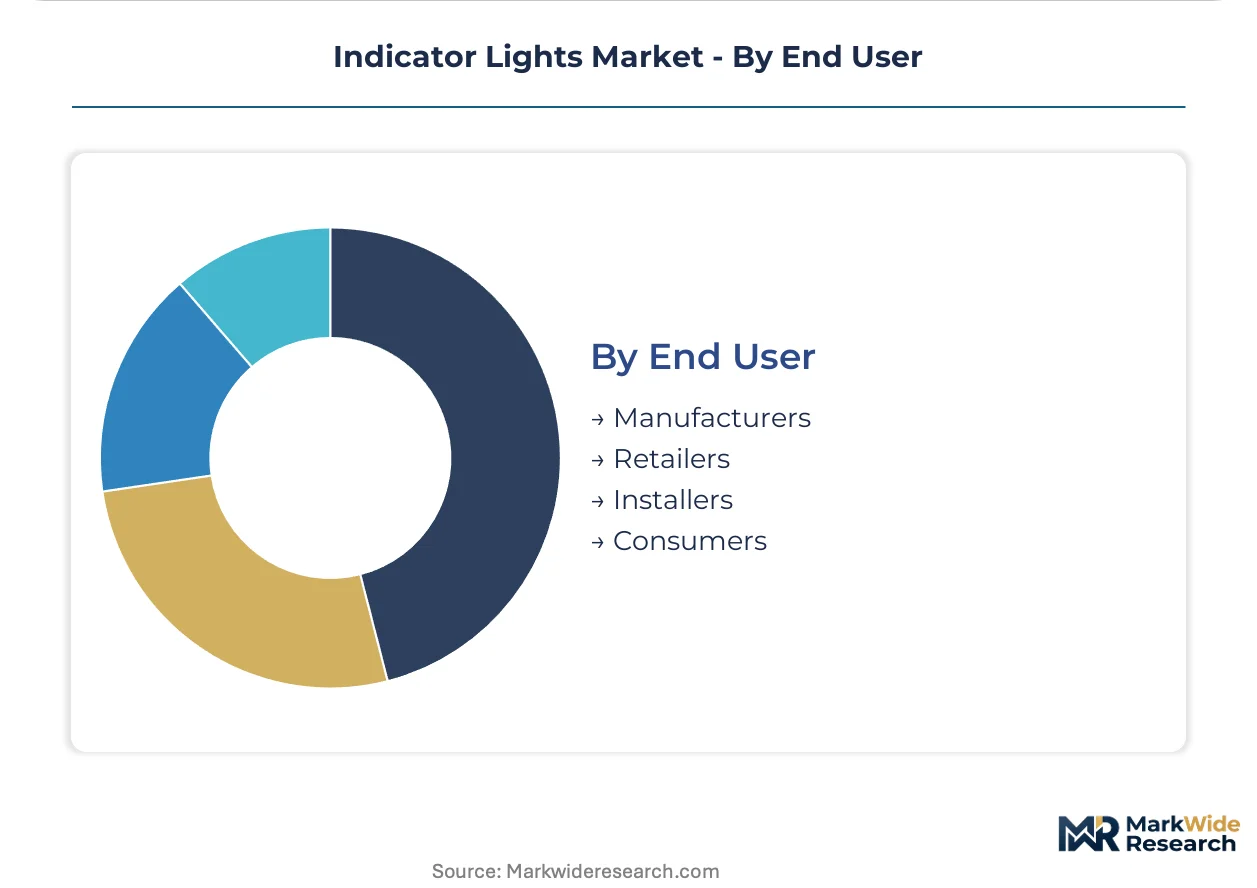
End User:
Channel structures determine specification authority, from corporate sustainability offices to maintenance departments with legacy part preferences.
- Manufacturers:OEM engineering teams specify indicator modules during product development with 5-10 year supply agreements. Automotive Tier 1 suppliers in Stuttgart and Nagoya are qualifying single-source chip-on-board packages for instrument cluster programs.
- Retailers:Electrical distributors stock standard indicator SKUs for maintenance-repair-operations procurement with limited technical support. US Midwest manufacturing belts are seeing energy service companies displace traditional distributor channels through lighting-as-a-service bundling.
- Installers:Systems integrators select indicators based on compatibility with existing control architectures and field termination convenience. Industrial automation installers in Shenzhen manufacturing zones prioritize indicators with standardized PLC communication protocols.
- Consumers:Aftermarket replacement demand for appliance indicators follows price-visibility search patterns with minimal brand loyalty. E-commerce platforms are capturing consumer indicator procurement through cross-sell algorithms with thermal fuses and control boards.
Specification authority is migrating toward Manufacturers. Price transparency is most acute for Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for indicator lights concentrates in automotive supplier corridors and industrial automation zones across three continents, with regulatory divergence shaping procurement patterns in each geography.
Germany
Automotive dashboard electrification drives multi-color LED adoption across Stuttgart and Munich supplier networks. EU Green Deal ecodesign mandates accelerate incandescent phase-out timelines for industrial machinery OEMs. The Baden-Württemberg automotive cluster sees Tier 1 suppliers consolidating chip-on-board module procurement for instrument cluster programs.
China
Industrial automation expansion embeds multi-status indicators into PLC interfaces across Shenzhen and Suzhou manufacturing zones. MIIT technical regulations mandate energy efficiency thresholds and electromagnetic compatibility testing for smart factory equipment. Western provinces accelerate municipal procurement of solar-powered LED systems under 2060 carbon neutrality targets.
United States
Process industries with high downtime costs justify premium sensor-luminaire integration in Gulf Coast petrochemical corridors. EPA and OSHA frameworks govern workplace visibility standards for industrial machinery applications. Midwest manufacturing belts see energy service companies displace traditional electrical distributor channels through lighting-as-a-service bundling.
Japan
Automotive Tier 1 suppliers in Nagoya adopt chip-on-board architectures for instrument cluster backlighting programs. METI industrial standards shape domestic procurement specifications for factory automation equipment. The Chubu region maintains concentration in high-reliability indicator module qualification for export markets.
Italy
Industrial machinery OEMs in Northern Italy accelerate supplier audits for cadmium and lead content compliance under REACH expansions. ECHA SVHC candidate list updates force continuous reformulation of phosphor coatings across European manufacturing bases. The Lombardy automation cluster embeds LED indicators into legacy equipment retrofit programs.
Indicator Lights Market Competitive Landscape
European producers anchor the premium tier through regulatory compliance specialization; East Asian fabricators hold volume positions in cost-optimized segments. The vendor base splits between consolidated lighting conglomerates with captive LED chip supply and fragmented mid-tier packaging houses serving regional industrial accounts. Three archetypes dominate: vertically integrated luminaire specialists, compound semiconductor packaging experts, and automation-focused indicator module suppliers. Competitive moves concentrate on backward integration into LED chip fabrication and hazardous location certification expansion.
Within the integrated lighting tier, Signify Holding and ams OSRAM exemplify divergent strategic positions. Signify occupies a position anchored in vertical control across LED chip fabrication and luminaire assembly, sustaining margin resilience under tightening substance restrictions. The Dutch entity represents the conglomerate archetype with captive supply chain configuration. ams OSRAM sits within the semiconductor specialization vector, anchoring competitive position through deep focus in high-reliability automotive indicator modules. The Austrian-German entity exemplifies the compound semiconductor packaging expert archetype with extended temperature rating capabilities. Panasonic Holdings Corporation represents the diversified electronics conglomerate model, with indicator products flowing through broader industrial component portfolios.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| ams OSRAM |
| Panasonic Holdings Corporation |
| Legrand |
| Lutron Electronics |
| Schneider Electric |
| LEDVANCE |
| Zumtobel Group |
| Others |
Value Network & Pricing Analysis
Automotive Tier 1 suppliers in Stuttgart and Nagoya anchor demand concentration for chip-on-board LED modules, locking in contract-based long-term offtake pricing with volume-scaled discounts and premium tiers for expedited qualification cycles. This procurement structure rewards suppliers with captive LED chip fabrication while squeezing mid-tier packaging houses dependent on spot substrate markets.
Pricing Analysis
Short lead-time premiums of 15-25% apply to automotive indicator modules requiring accelerated ECE compliance testing, while spot inventory of standard industrial LED packages trades at discounts to contract rates. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aviation indicators from IP65-rated industrial units and basic appliance through-hole packages. Price differentiation hinges on REACH substance compliance certification and thermal management performance grade. Cost compression in mid-tier LED packaging is intensifying because ECHA's SVHC list expansions force continuous phosphor reformulation. Budget appliance manufacturers in Southeast Asia exhibit highest price sensitivity, while process industries with downtime costs exceeding $100,000 per hour show least sensitivity.
Supply Chain Analysis
ATEX and IECEx qualification gating restricts hazardous location indicator supply to certified fabricators, concentrating production in Germany, Japan, and China for automotive and industrial segments. Sapphire wafer and silicon carbide substrate supply draws from East Asian foundries in Taiwan and South Korea, with rare-earth phosphor dopants sourced from Chinese separation facilities. Single-source vulnerability in compound semiconductor packaging creates exposure to export control friction. Distribution runs through energy service companies bundling retrofits in US Midwest manufacturing belts and traditional electrical distributors serving maintenance-repair-operations procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions and ECHA's expanding SVHC candidate list have erected a cost-of-compliance moat that favors incumbents with in-house regulatory affairs capabilities and captive reformulation R&D. New entrants face 18-24 month qualification timelines before European automotive OEMs approve supplier status.
For Market Incumbents: Acquire phosphor coating and solder alloy formulation capabilities to internalize REACH compliance costs and block mid-tier competitors from margin recovery. Defensive consolidation should prioritize ATEX certification expansion into Eastern European petrochemical facilities where incumbent relationships remain frozen. LED substitution pressure in aviation cockpit annunciators threatens neon indicator incumbency; preemptive investment in FAA TSO-C30c qualification for solid-state alternatives secures position before certification windows reopen. For New Entrants and Emerging Players: Municipal procurement offices in western Chinese provinces represent an underserved buyer archetype with accelerating solar-powered LED indicator demand under 2060 carbon neutrality targets. Explosion-proof industrial retrofits in Eastern European petrochemical corridors offer penetrable whitespace given ATEX certification gaps. Go-to-market execution should leverage wireless mesh networking integration as a technical wedge against legacy wired indicator suppliers. For Investors and Strategic Acquirers: The window for entry favors compound semiconductor packaging specialists with thermal management expertise for automotive grade indicators. Long-term viability rests on 5-10 year supply agreements with German and Japanese Tier 1 suppliers consolidating vendor tiers. Acquisition targets should display backward integration into LED chip fabrication or hazardous location certification depth. Watch for MIIT technical regulation expansions mandating smart factory indicator integration as the inflection signal for IoT-enabled platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Fabrication | Captive supply of compound semiconductor junctions insulates margin from sapphire wafer price volatility and ECHA phosphor restrictions. |
| Hazardous Location Certification Expansion | ATEX and IECEx qualification opens specification windows in Eastern European petrochemical and North Sea oil and gas facilities. |
| Smart Lighting Platform Development | IoT-enabled diagnostic firmware captures value from predictive maintenance architectures in German chemical corridors. |
| Chip-on-Board Module Consolidation | Single-source procurement contracts with Stuttgart and Nagoya Tier 1 suppliers displace discrete component vendor tiers. |
| REACH Compliance Infrastructure Investment | In-house reformulation capabilities for cadmium-free phosphors and lead-free solder alloys defend European automotive supply position. |
Research Methodology
Multi-period observation of automotive dashboard electrification programs and EU Green Deal implementation timelines anchored the trend analysis, supplemented by interviews with LED packaging engineers, automotive Tier 1 procurement managers, industrial machinery OEM specification leads, and energy service company account executives. Secondary validation drew from ECHA SVHC candidate list updates, MIIT technical regulation filings, EPA workplace visibility standards documentation, and SEC 10-K disclosures from listed lighting conglomerates. Bottom-up indicator unit demand modeling triangulated against top-down automotive production and industrial automation capital expenditure forecasts.
Segment-weighting across product type, application, technology, and end-user dimensions structured the analytical framework, with technology adoption curves calibrated to regulatory compliance deadlines over the projection horizon. LED substitution rates in automotive and industrial segments, aviation certification pipeline status for solid-state alternatives, and smart lighting penetration in process industries served as industry-specific forecast inputs. CAGRs derived from installed base turnover analysis and replacement demand elasticity across compliance-driven and discretionary procurement cycles.
Revisions become necessary when ECHA expands SVHC restrictions beyond current phosphor coating formulations, when FAA accelerates LED cockpit annunciator certification timelines, or when MIIT mandates additional electromagnetic compatibility testing for smart factory equipment. Forecasts reflect assumptions about regulatory implementation schedules and automotive electrification program commitments. A model refresh is warranted upon material change in EU Green Deal ecodesign enforcement intensity or Chinese dual carbon policy acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
South America Outdoor LED Lighting Market
Lighting
Programmable Stage Lighting Market
Lighting
UV Lamps Market
Lighting
Directional Luminaire Market
Lighting
Ring Lights Market
Lighting
Battery Operated Lights Market
Lighting
High-End Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
Art and Museum Lighting Market
Lighting
Photography Light Box Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
Digital Light Processing Technology Market
Lighting
Global Commercial Lighting Market
Lighting
Bulb Market
Lighting
Europe Lighting Control Systems Market
Lighting
Industrial OLED Lighting Market