
 Global Gan on Diamond Semiconductor Substrates Market | 2026-2036
Global Gan on Diamond Semiconductor Substrates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gan on Diamond Semiconductor Substrates Market Intelligence
Custom substrate development revenue is narrowing the profitability gap with high-volume, standardized wafer production. This shift favors specialists in material science and epitaxial growth. Element Six leverages its leadership in synthetic diamond production to offer tailored thermal management solutions. Qorvo Inc. competes by integrating these advanced substrates into its high-performance RF device portfolio for aerospace and defense clients.
Gallium Nitride (GaN) on diamond semiconductor substrates are composite structures where a GaN device layer is grown on a diamond base. This material system exploits diamond's exceptional thermal conductivity, often exceeding 2000 W/mK, to manage heat in high-power density electronics. Demand for power amplifiers in 5G base stations and military radar systems drives the market. While single crystal diamond offers ultimate performance, polycrystalline diamond substrates represent the fastest-growing product type due to a better cost-performance balance.
Material and performance standards established by organizations like the US Department of Defense for military-grade electronics set a high bar for reliability. In Europe, compliance with the RoHS directive on hazardous substances and REACH regulations for chemical safety influences material selection and supply chain transparency. These frameworks shape market access for suppliers. Navigating the intellectual property landscape around diamond growth and GaN-on-diamond bonding techniques remains a critical strategic consideration for all market participants.
Market Dynamics
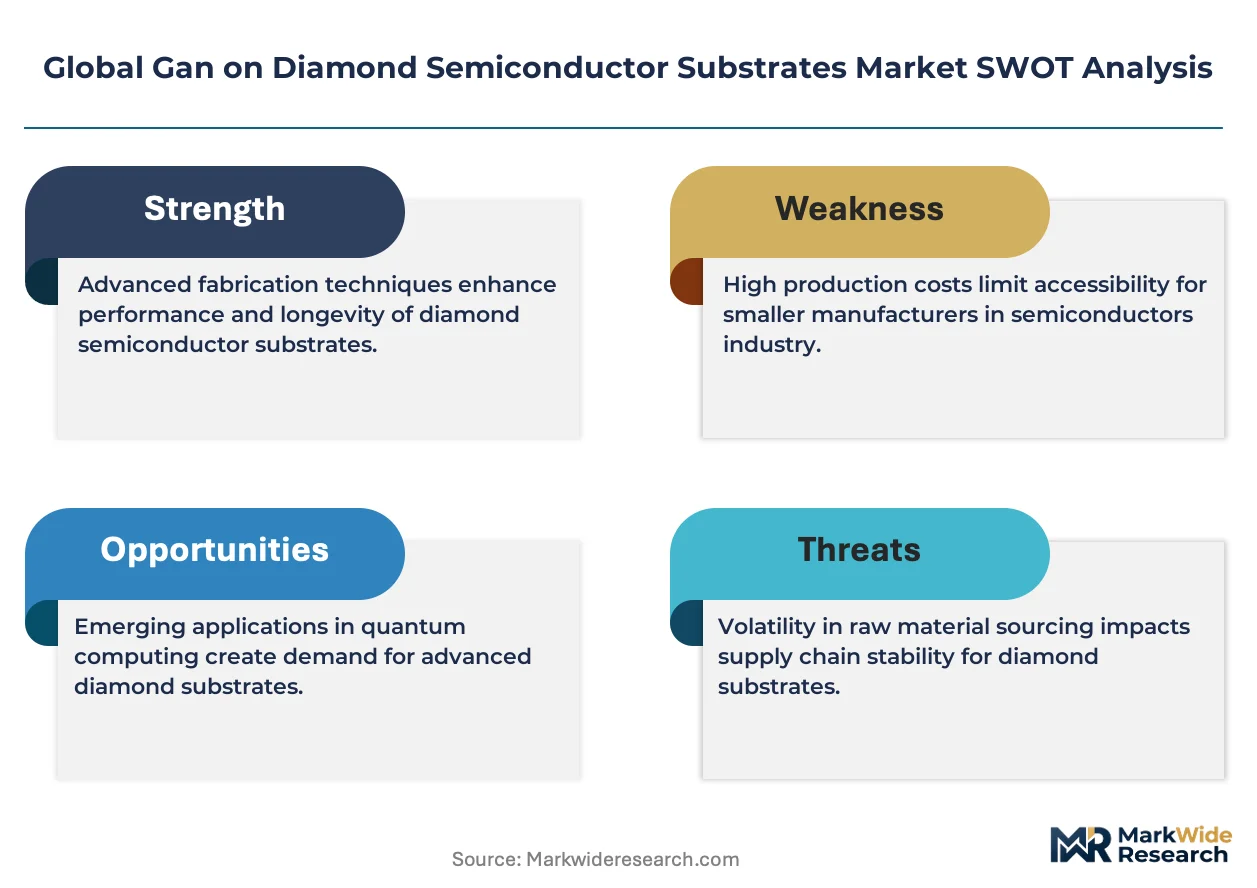
The primary structural force shaping this market is the technical and economic tension between diamond's unparalleled thermal conductivity and the high manufacturing cost associated with producing defect-free, large-area substrates suitable for semiconductor fabrication.
Growth Catalysts
- Next-Generation Wireless Infrastructure:The global deployment of 5G and early-stage 6G networks requires power amplifiers with superior heat dissipation, a need directly met by GaN-on-diamond's thermal properties for base station and backhaul equipment.
- Defense Modernization Programs:Advanced military radar and electronic warfare systems, particularly in the United States and Israel, mandate higher power density and reliability, driving demand for substrates that meet stringent US Department of Defense performance standards.
- Polycrystalline Diamond Advancement:Innovations in chemical vapor deposition (CVD) are improving the quality and reducing the cost of polycrystalline diamond, making it a viable, high-performance alternative to less conductive materials like silicon carbide.
Market Restraints
- Substrate Cost Structure:The high price of single-crystal diamond, stemming from complex, energy-intensive high-pressure/high-temperature (HPHT) or CVD synthesis processes, remains a significant barrier to broader commercial adoption outside of high-value applications.
- Epitaxial Growth Complexity:Achieving a high-quality, low-defect interface between the GaN and diamond layers is technically challenging due to lattice and thermal expansion mismatches, which can limit device yield and reliability.
- Supply Chain Concentration:The global supply of high-purity, electronics-grade synthetic diamond is concentrated among a few specialized producers, creating potential bottlenecks and price volatility for substrate manufacturers.
Strategic Opportunities
- Electric Vehicle Power Electronics:GaN-on-diamond substrates offer a potential solution for thermal management in next-generation EV inverters and onboard chargers, enabling higher power density and efficiency as the automotive industry transitions to higher voltage architectures.
- Satellite Communications:The expanding market for low Earth orbit (LEO) satellite constellations presents an opportunity for high-frequency, high-power RF components that require efficient thermal management for both ground stations and space-based payloads.
- Wafer Diameter Expansion:Developing processes to manufacture larger diameter GaN-on-diamond wafers (e.g., 150mm) would unlock significant economies of scale, reducing per-device costs and making the technology more competitive for high-volume markets.
Industry Challenges
- Intellectual Property Navigation:The patent landscape for both diamond synthesis and GaN-on-diamond bonding techniques is dense and highly contested, creating legal risks and licensing complexities for new entrants and established firms alike.
- Workforce Skill Gaps:A scarcity of engineers and material scientists with dual expertise in wide-bandgap semiconductor epitaxy and ultra-hard material science hinders research and development efforts and slows production scaling.
- Standardization Deficits:The absence of universally accepted standards for testing and qualifying the thermal performance and long-term reliability of GaN-on-diamond devices creates friction between suppliers and end-users, particularly in non-military sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gan on Diamond Semiconductor Substrates Market |
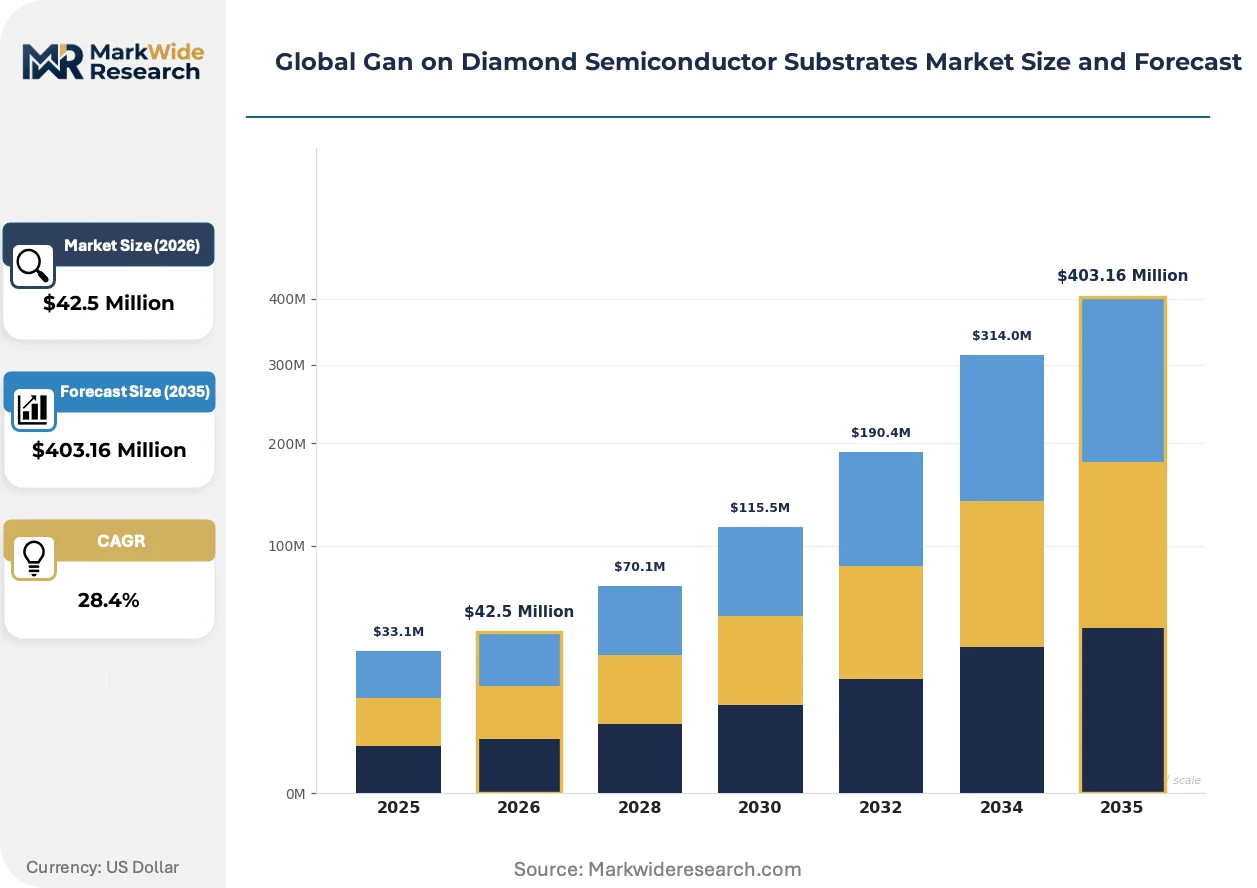
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $403.16 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Diamond, Polycrystalline Diamond, Single Crystal Diamond, Gradient Layered Substrates Technology: Metal-Organic Chemical Vapor Deposition, Molecular Beam Epitaxy, Hydride Vapor Phase Epitaxy, Pulsed Laser Deposition Application: Power Amplifiers, RF Devices, Microwave Components, High-Frequency Switches End User: Telecommunication Equipment Manufacturers, Semiconductor Foundries, Consumer Electronics Producers, Aerospace Component Suppliers |
| Companies Covered | Blue Wave Semiconductors, Element Six, Carat Systems, Shenzhen Coming Technology Co., Ltd., Crystallume, Diamond Microwave, IIa Technologies, NeoCoat SA, Qorvo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gan on Diamond Semiconductor Substrates Market Strategic Shifts & Innovations
Innovation focuses intensely on bridging the cost-performance gap to unlock mainstream applications. This effort manifests in material science breakthroughs, evolving regulatory compliance demands, and new models of customer-supplier collaboration for application-specific development.
Polycrystalline diamond substrates provide a cost-effective thermal management solution compared to their single-crystal counterparts. Radio frequency device manufacturers for telecommunications infrastructure are adopting this technology to handle the power demands of 5G active antenna units. The increasing availability of these high-performance, lower-cost substrates is collapsing the economic barrier that previously confined GaN-on-diamond technology to niche defense systems.
European Union directives like RoHS and REACH are influencing material choices and supply chain management for electronics manufacturers. These regulations require detailed documentation and transparency regarding the chemical composition of components, including semiconductor substrates. This pressure particularly affects suppliers targeting the European telecom equipment market, compelling them to validate and declare all materials used in their GaN-on-diamond products.
A notable behavioral shift is the move from purchasing standardized wafers to engaging in co-development partnerships for custom substrate engineering. This model favors material science specialists over commodity suppliers, as it requires deep collaboration to tailor thermal properties to specific device requirements. The trend is most pronounced in the aerospace and defense sectors in North America and Europe, where unique system-level performance goals justify bespoke substrate designs.
Global Gan on Diamond Semiconductor Substrates Market Segmentation
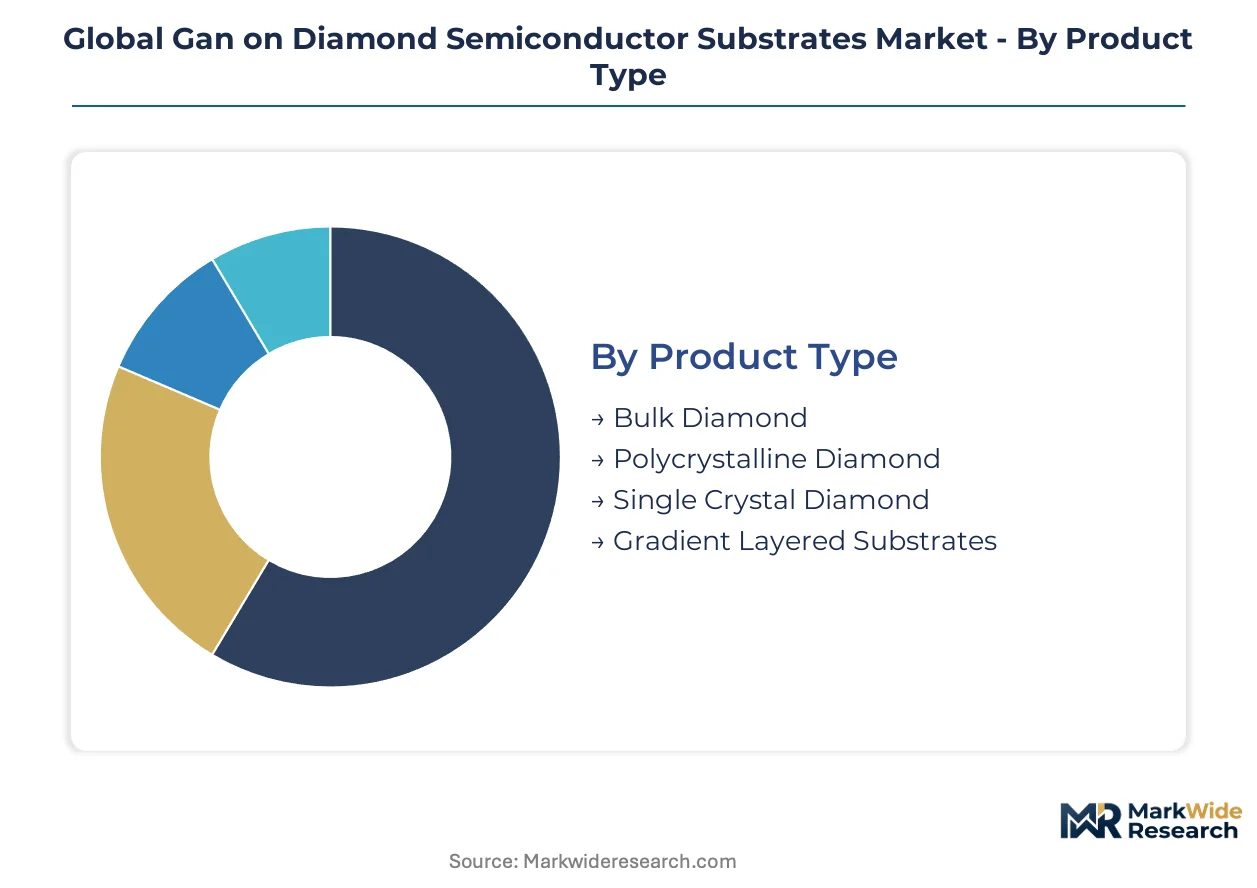
The GaN on diamond semiconductor substrates market is stratified across several key dimensions, reflecting the diverse technical requirements and commercial priorities of its end-users. Understanding these segments clarifies the varying levels of performance, cost, and technological maturity influencing adoption rates. Each category illuminates specific market dynamics and growth vectors.
Product Type:
The product type segmentation reveals a maturity spectrum, from established materials to advanced composite structures addressing specific thermal challenges.
- Polycrystalline Diamond:This material offers cost-effective thermal management with high thermal conductivity via CVD processes. Demand concentrates in telecommunications infrastructure for 5G active antenna units, enabling superior heat dissipation.
- Single Crystal Diamond:Single crystal diamond offers ultimate thermal conductivity and structural perfection, produced through HPHT or advanced CVD methods. Its primary application lies in high-value defense modernization programs for military radar systems in the United States.
- Bulk Diamond:These substrates generally refer to larger, less refined diamond forms used as heat spreaders, often with lower purity.
- Gradient Layered Substrates:These composite structures feature engineered interfaces to mitigate thermal expansion mismatches, improving bonding between GaN and diamond layers.
Single Crystal Diamond handles the majority of throughput; Polycrystalline Diamond is the fastest mover on share.
Technology:
Technology choices reflect the trade-offs between deposition precision, material quality, and manufacturing scalability required for GaN-on-diamond integration.
- Metal-Organic Chemical Vapor Deposition:MOCVD is a widely adopted technique for growing high-quality GaN layers, known for its scalability and precise control. This technology is critical for producing power amplifiers used in 5G base stations.
- Molecular Beam Epitaxy:MBE offers atomic-layer precision for GaN growth, resulting in superior material quality and abrupt interfaces, albeit at lower throughput. This technique is favored for high-frequency RF devices requiring exceptional electron mobility for aerospace and defense applications.
- Hydride Vapor Phase Epitaxy:HVPE provides high growth rates for GaN, suitable for producing thick buffer layers or freestanding GaN substrates, often used as templates.
- Pulsed Laser Deposition:PLD enables the deposition of complex oxide and nitride films with precise stoichiometric control, though less common for large-scale GaN-on-diamond fabrication.
MOCVD is the most prevalent method for volume production; MBE is gaining traction for high-performance niche applications.
Application:
The application landscape demonstrates how GaN-on-diamond substrates address critical thermal management needs across high-power and high-frequency electronic systems.
- Power Amplifiers:These devices are central to wireless communication, requiring efficient heat dissipation to maintain performance and reliability under high power densities. Demand is significant in 5G base stations and active antenna units.
- RF Devices:GaN-on-diamond enhances performance of various radio frequency components by enabling higher operating temperatures and power output. This is particularly relevant for advanced military radar systems in the United States.
- Microwave Components:This segment includes components operating at microwave frequencies, benefiting from diamond's thermal properties for improved efficiency and extended lifespan.
- High-Frequency Switches:GaN-on-diamond enables switches to handle higher power at higher frequencies with reduced thermal breakdown, crucial for next-generation telecommunications and defense.
Power Amplifiers drive the largest demand volume; RF Devices are expanding fastest due to defense modernization.
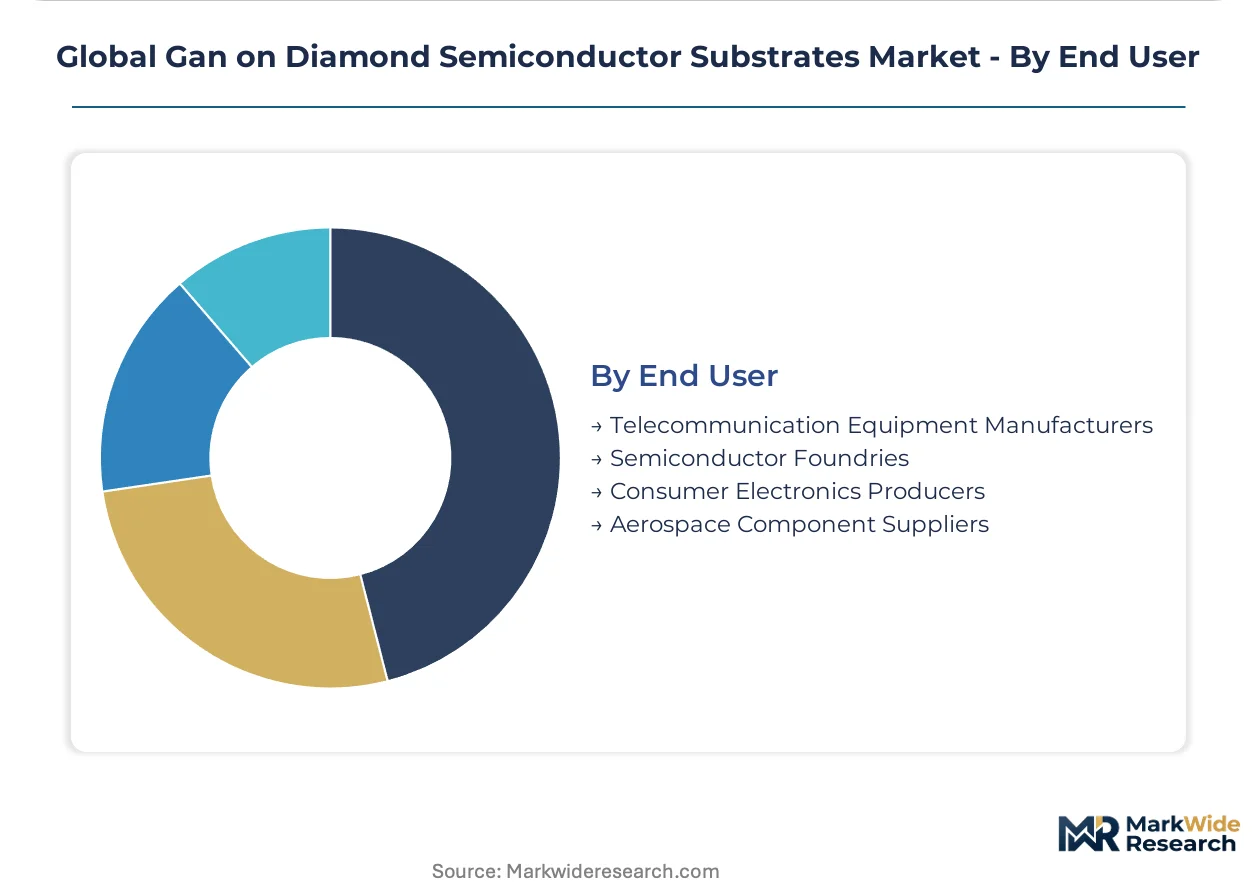
End User:
End-user segments highlight the primary industries leveraging GaN-on-diamond substrates for their specific product development and performance requirements.
- Telecommunication Equipment Manufacturers:These companies integrate GaN-on-diamond substrates into power amplifiers and RF modules for 5G and future 6G network infrastructure. They prioritize thermal efficiency and reliability for dense base station deployment.
- Aerospace Component Suppliers:Suppliers to aerospace and defense utilize these substrates for high-power radar, electronic warfare, and satellite communication systems. US Department of Defense standards drive demand for robust, thermally stable components.
- Semiconductor Foundries:Foundries offer fabrication services for GaN-on-diamond devices, catering to diverse clients by providing advanced processing capabilities and epitaxy services.
- Consumer Electronics Producers:While nascent, some producers explore GaN-on-diamond for high-power fast chargers or compact, high-performance wireless modules in premium devices.
Telecommunication Equipment Manufacturers represent the largest consumer base; Aerospace Component Suppliers are demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global consumption of GaN on diamond semiconductor substrates shows distinct regional patterns. The United States and South Korea currently dominate demand, driven by advanced semiconductor fabrication and defense modernization. European markets are increasingly focused on telecommunication infrastructure deployment.
United States
Demand for GaN-on-diamond substrates in the United States is primarily driven by defense modernization programs and advanced radar systems. The US Department of Defense sets stringent performance standards for military-grade electronics. Silicon Valley and defense contractors across the country develop high-power RF devices requiring superior thermal management.
South Korea
South Korea exhibits strong demand for GaN-on-diamond in next-generation wireless infrastructure and 5G base stations. The Ministry of Science and ICT actively supports R&D in advanced semiconductor materials. Suwon and Gyeonggi Province house major telecommunication equipment manufacturers and semiconductor design houses.
Germany
German industries are adopting GaN-on-diamond for high-power electronics in automotive applications and industrial radar systems. Compliance with REACH regulations for chemical safety influences material selection in the European market. Dresden's Silicon Saxony cluster sees significant investment in wide-bandgap semiconductor research and fabrication.
Japan
Japan's market for GaN-on-diamond substrates is driven by advanced telecommunications and high-frequency microwave components. METI initiatives promote innovation in next-generation semiconductor materials and manufacturing processes. Research institutes and foundries in Tohoku and Kyushu regions contribute to epitaxial growth advancements.
Israel
Israel's defense sector fuels demand for GaN-on-diamond in electronic warfare systems and high-power radar applications. The Ministry of Defense prioritizes robust, high-performance components for national security. Tel Aviv and Haifa host numerous defense technology companies and R&D centers focused on advanced RF solutions.
Global Gan on Diamond Semiconductor Substrates Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the GaN on diamond semiconductor substrates market. The market structure is tiered, featuring specialized material science firms and larger integrated device manufacturers. Two primary archetypes include high-performance material innovators and application-specific solution providers. Strategic partnerships between material producers and device manufacturers are common, alongside continued investment in R&D to overcome technical challenges.
Specialized material science firms like Element Six exemplify the high-performance material innovator archetype, leveraging their extensive expertise in synthetic diamond production for tailored thermal management solutions. Qorvo Inc. represents an integrated device manufacturer, strategically incorporating these advanced substrates into its high-performance RF device portfolio for demanding aerospace and defense clients. Shenzhen Coming Technology Co., Ltd., a China-based entity, occupies a position among emerging producers focused on expanding substrate availability and improving cost-performance balance, particularly for telecommunication applications.
| Leading Market Players |
|---|
| Blue Wave Semiconductors |
| Element Six |
| Carat Systems |
| Shenzhen Coming Technology Co., Ltd. |
| Crystallume |
| Diamond Microwave |
| IIa Technologies |
| NeoCoat SA |
| Qorvo Inc. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes' cost dynamics influence the overall pricing for GaN-on-diamond substrates, linking concentrated Asian manufacturing capabilities to differentiated pricing for specialized high-performance materials versus more commoditized offerings.
Pricing Analysis
Project-based contracts dominate custom substrate engineering, while long-term offtake agreements secure high-volume standardized wafer production. Price differentiation stems from the material's quality grade, specifically single crystal versus polycrystalline diamond, and the level of customization required for specific device integration. Cost compression on polycrystalline diamond intensifies due to advancements in chemical vapor deposition techniques, making it more accessible. Telecommunication equipment manufacturers exhibit higher price sensitivity for volume applications, whereas aerospace and defense clients prioritize performance over cost for mission-critical systems.
Supply Chain Analysis
High-purity carbon precursors and specialized GaN source materials form the upstream bedrock of this market's supply chain. Geographic supply concentration exists in the United Kingdom, China, and Japan for advanced diamond synthesis and epitaxy services. Single-source vulnerability for electronics-grade synthetic diamond poses a significant supply chain risk, potentially leading to price volatility. Downstream distribution primarily runs through direct sales channels and strategic partnerships with integrated device manufacturers and semiconductor foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, driven by the increasing penetration of GaN-on-diamond substrates into next-generation 5G and 6G wireless infrastructure.
For Market Incumbents:
Entrench leadership by investing heavily in research and development for larger diameter GaN-on-diamond wafers, such as 150mm, to unlock economies of scale. Secure long-term supply agreements for critical high-purity precursors to mitigate single-source vulnerabilities. Expand intellectual property portfolios around advanced bonding techniques and defect reduction to counter emerging lower-cost alternatives. This proactive approach defends against commoditization and maintains a performance edge.
For New Entrants and Emerging Players:
European automotive power electronics market represents a significant underpenetration opportunity for GaN-on-diamond substrates. Target electric vehicle inverter and onboard charger applications, leveraging polycrystalline diamond for its cost-performance balance. Focus on co-development partnerships with established automotive Tier 1 suppliers to tailor thermal management solutions. Low Earth Orbit satellite constellations also offer a white-space target for high-frequency, high-power RF components, providing an entry point for specialized offerings.
For Investors and Strategic Acquirers:
Carve-out targets emerge from large integrated device manufacturers or diversified materials companies seeking to divest non-core advanced materials divisions. The long-term viability for GaN-on-diamond remains strong over the next decade, driven by persistent thermal management challenges in high-power electronics. Identify specialized material science firms with proprietary CVD diamond growth technologies or unique GaN-on-diamond bonding IP as prime acquisition candidates. The successful commercialization of 150mm GaN-on-diamond wafers serves as a critical signal to watch for broader market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in 150mm Wafer R&D | Expands manufacturing scale, reducing per-device costs for high-volume applications. |
| Secure Long-Term Precursor Supply | Mitigates raw material price volatility and ensures production continuity for substrate manufacturers. |
| Form Co-Development Partnerships | Accelerates application-specific substrate design and market penetration in new sectors. |
| Expand Intellectual Property Portfolio | Strengthens market position against competitors and protects proprietary material science breakthroughs. |
| Target EV Power Electronics Segment | Captures new demand in the rapidly growing automotive electrification market. |
Research Approach
Findings reconcile primary fieldwork against secondary review of US Department of Defense procurement reports, METI (Japan) innovation reports, EU RoHS/REACH compliance documentation, and company annual reports. Primary interviews engaged R&D directors at semiconductor foundries, material scientists at diamond producers, procurement leads at telecommunication equipment manufacturers, and aerospace component engineers. This comprehensive approach ensures bottom-up and top-down triangulation of market data.
Forecast inputs considered current technology adoption rates, regulatory compliance trends, and evolving application requirements across the analysis window. The analytical framework models market dynamics across product type, technology, application, end-user, and thermal conductivity performance tier. Compound annual growth rates derive from historical trends and projected technological adoption curves. 5G/6G deployment roadmaps and military spending on advanced radar systems serve as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new diamond synthesis startups or integrated device manufacturers would shift outcomes. Forecasts reflect assumptions regarding technological maturation rates and stable geopolitical conditions. Cross-checking against industry association roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Coated Silicon Wafer Market