
 LTCC and HTCC Market | 2026-2036
LTCC and HTCC Market Size, Share, and Industry Trends Forecast 2026-2036
LTCC and HTCC Market Intelligence
Capacity expansion in China is fragmenting the supply base for ceramic substrates, introducing new regional competitors. Kyocera leverages its deep material science expertise to offer highly customized HTCC solutions for demanding aerospace applications. Murata Manufacturing specializes in the LTCC segment for high-frequency modules used in smartphones and telecommunication infrastructure, controlling a significant portion of that sub-market. TDK Corporation competes through its broad portfolio of electronic components, integrating ceramic substrates into its power and RF solutions.
LTCC and HTCC are multi-layered ceramic substrates manufactured by firing ceramic tape and conductive materials together to create integrated electronic circuits. The key difference is the firing temperature; LTCC is processed below 1000°C, allowing co-firing with highly conductive metals like silver, while HTCC requires over 1500°C. LTCC products command a significant share due to their widespread use in high-volume consumer electronics and telecommunications applications. The automotive end-user segment shows rapid expansion, driven by demand for robust sensors and power modules in electric vehicles.
Material composition and manufacturing processes are governed by environmental regulations such as the EU's RoHS and REACH directives, which restrict hazardous substances. In the United States, standards from the FCC influence the design of RF modules, indirectly shaping substrate requirements for telecommunications equipment. Future investment decisions will hinge on balancing the performance benefits of specific ceramic formulations against evolving environmental compliance costs and material sourcing challenges.
Market Dynamics
The central force shaping the market is the relentless demand from the telecommunications sector for higher frequency and more integrated RF modules. This requirement, driven by 5G and future network deployments, dictates material science innovation and manufacturing process advancements.
Growth Catalysts
- Automotive Electrification:The transition to electric vehicles creates substantial demand for HTCC and LTCC in power modules, battery management systems, and high-temperature sensors, where ceramic's robustness is critical.
- Component Miniaturization:Ongoing size reduction in consumer electronics, particularly smartphones and wearables, propels the adoption of LTCC for creating compact, high-density System-in-Package (SiP) modules.
- 5G Infrastructure Build-out:Government-supported rollouts of 5G networks in countries like South Korea and the United States necessitate a new generation of high-frequency ceramic substrates for base stations and user equipment.
Market Restraints
- High Processing Costs:HTCC manufacturing requires firing temperatures above 1500°C and co-firing with expensive refractory metals like tungsten, leading to high energy consumption and production costs.
- Material Sourcing Volatility:The supply of high-purity alumina powders and specialized conductive pastes, such as silver, is subject to price fluctuations and geopolitical sourcing risks, impacting cost stability.
- Technical Performance Trade-offs:LTCC offers lower firing temperatures but has inferior mechanical strength and thermal conductivity compared to HTCC, limiting its application in mechanically or thermally demanding environments.
Strategic Opportunities
- Medical Device Integration:There is an opportunity to develop biocompatible ceramic substrates for implantable medical devices, such as pacemakers and neural stimulators, which require high reliability and hermetic sealing.
- Next-Generation Satellites:The proliferation of LEO satellite constellations for global internet coverage presents a new frontier for radiation-hardened HTCC and high-frequency LTCC components in space-based communication payloads.
- Advanced Packaging in India:Supporting India's PLI scheme for electronics manufacturing offers a chance to establish local substrate production to serve its burgeoning semiconductor and consumer electronics industries.
Industry Challenges
- Specialized Talent Scarcity:A shortage of material scientists and process engineers with deep expertise in co-fired ceramic technology and circuit design hinders new product development and process optimization.
- Capital-Intensive Expansion:Building or expanding a ceramic substrate fabrication facility requires significant capital investment in cleanrooms, high-temperature furnaces, and precision screen-printing equipment.
- Design and Simulation Complexity:Modeling the electromagnetic and thermal performance of complex, multi-layered 3D ceramic circuits requires sophisticated software tools and expertise, creating a barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LTCC and HTCC Market |
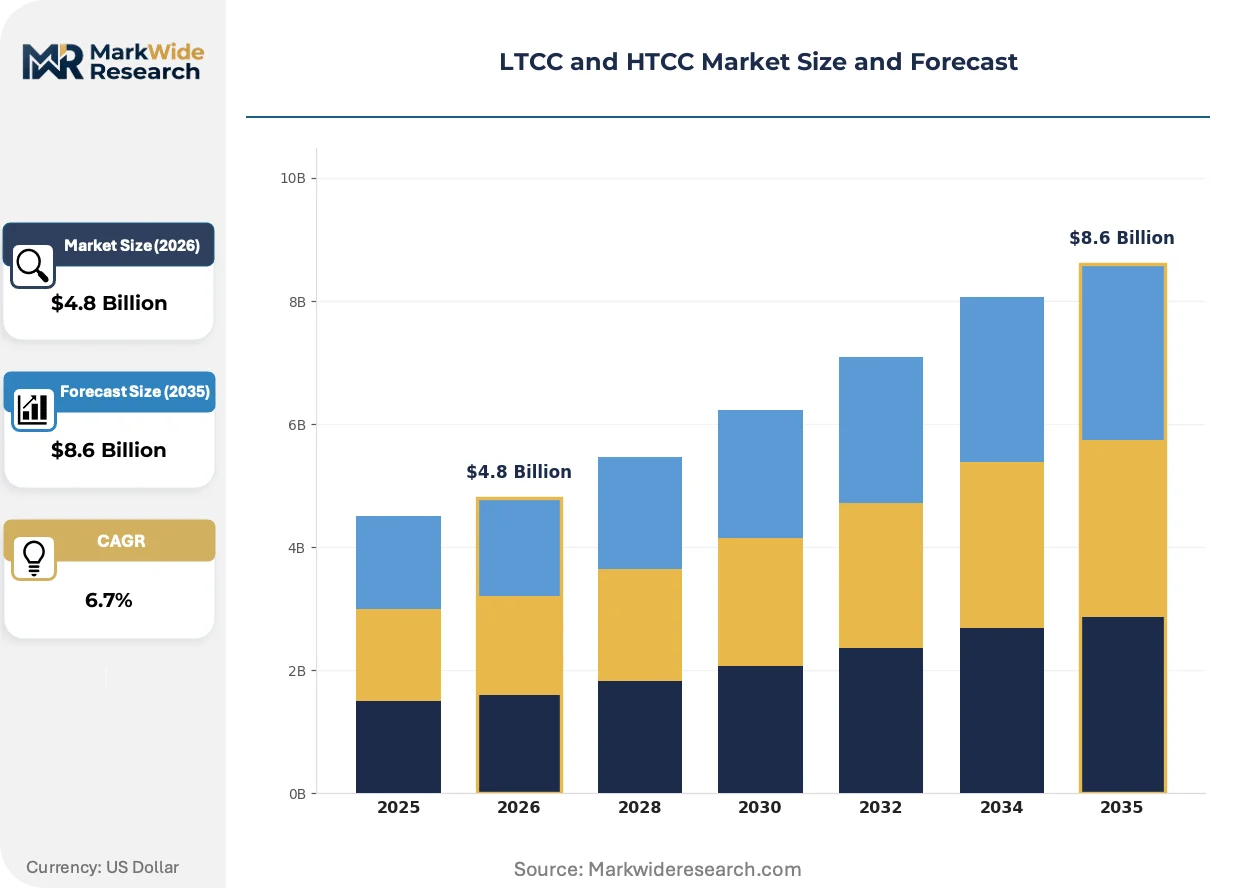
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LTCC, HTCC, Thick Film, Thin Film Technology: Multi-layered, Circuit Integration, Thermal Management, Electrical Insulation End User: Aerospace, Consumer Electronics, Telecommunications, Automotive Application: RF Modules, Sensors, Power Amplifiers, Microwave Devices |
| Companies Covered | Hitachi Metals, Taiyo Yuden, Murata Manufacturing, KOA Corporation, Samsung Electro-Mechanics, Kyocera, NGK Spark Plug, Maruwa, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTCC and HTCC Market Strategic Shifts & Innovations
Material science advancements are converging with electronic design automation to address the dual pressures of performance enhancement and cost management. This evolution is most apparent in the development of substrates that integrate more functionality directly into the ceramic body.
Embedded passive component technology integrates elements like resistors and capacitors directly into the ceramic substrate layers during manufacturing. RF module designers for smartphones and 5G base stations are adopting this to achieve higher circuit density and improved signal integrity. This technology is digitizing the design of radio front-ends by enabling more complex, software-defined functionalities within a smaller physical footprint.
The European Union’s RoHS and REACH directives impose stringent restrictions on hazardous substances, including lead and certain plasticizers, used in electronic components. This regulatory pressure compels substrate manufacturers to invest in R&D for compliant ceramic and conductive paste formulations. The aerospace and defense sectors, which often rely on legacy materials with specific performance characteristics, are most affected as commercial supply chains pivot to newer, compliant alternatives.
A notable behavioral change is the move from purchasing standard substrates to forming co-design partnerships between ceramic suppliers and OEMs. This collaborative model is displacing the traditional component catalog approach, especially in demanding fields like high-performance computing and automotive electronics. This trend is most pronounced in the advanced packaging ecosystems of Taiwan and South Korea, where close integration is vital for developing complex System-in-Package solutions.
LTCC and HTCC Market Segmentation
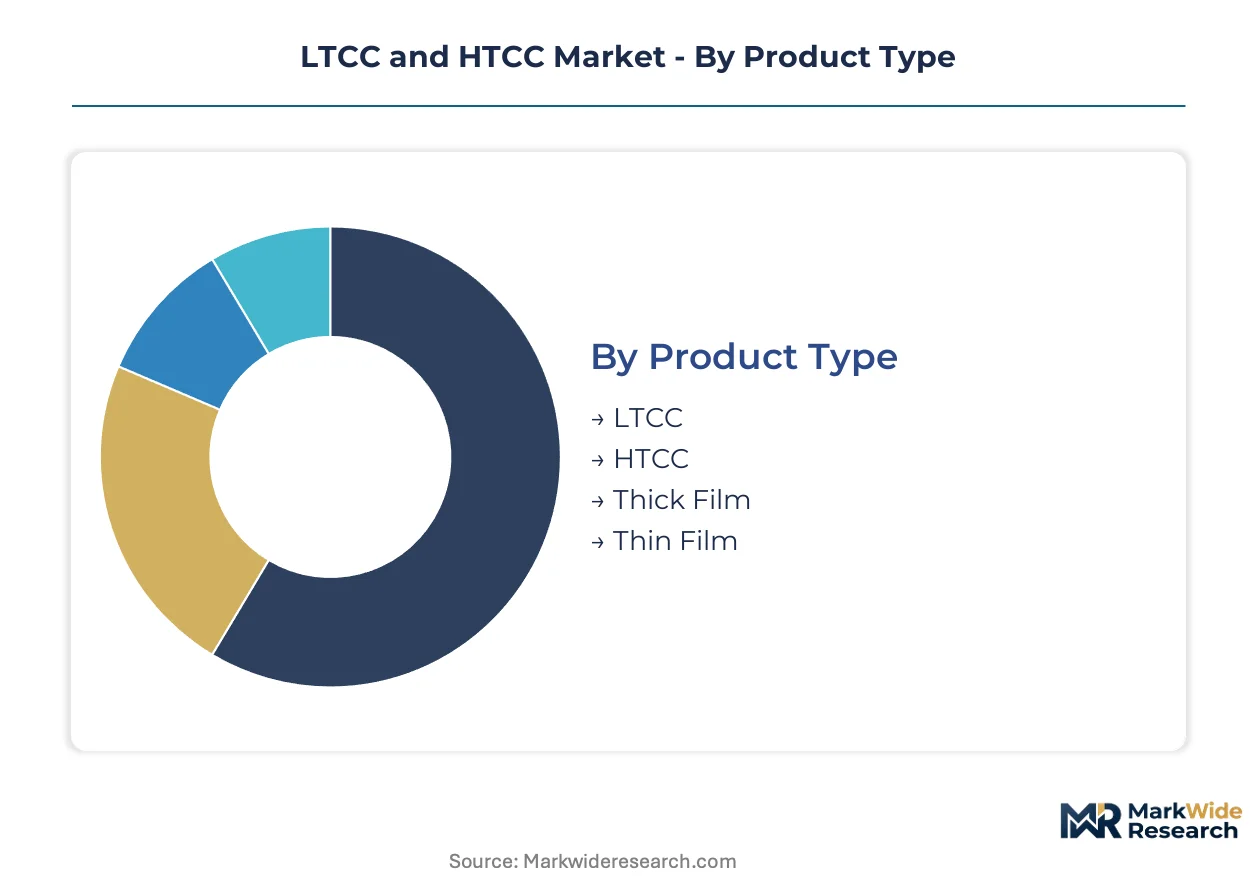
Market segmentation provides a clear framework for understanding the diverse applications and technological requirements driving demand for LTCC and HTCC substrates. Each segment exhibits unique material specifications and manufacturing challenges. Analyzing these distinct categories helps identify strategic investment areas and competitive advantages within the market.
Product Type:
The intensity of after-sales service often correlates with the complexity and customization required for each product type, influencing supplier relationships and market positioning.
- LTCC:Low-Temperature Co-fired Ceramic substrates are fired below 1000°C, enabling co-firing with highly conductive metals such as silver. This technology finds widespread use in high-volume consumer electronics and telecommunications applications due to its cost-effectiveness and excellent high-frequency performance.
- HTCC:High-Temperature Co-fired Ceramic substrates require firing temperatures exceeding 1500°C, co-fired with refractory metals like tungsten for internal circuitry. HTCC products offer superior mechanical strength and thermal conductivity, making them suitable for demanding aerospace and power module applications.
- Thick Film:This technology involves screen-printing conductive and resistive pastes onto a ceramic base, then firing at moderate temperatures. Thick film offers design flexibility for less demanding applications like automotive sensors and industrial controls.
- Thin Film:Thin film processes deposit materials in extremely thin layers, typically through sputtering or evaporation, creating highly precise circuits. This method supports high-density interconnects and fine line resolution for advanced RF and optical modules.
By volume, LTCC leads. By growth pace, HTCC is ahead.
Technology:
The cost tier for various ceramic substrate technologies reflects the complexity of their manufacturing processes and the specialized materials involved.
- Multi-layered:This core technology integrates multiple ceramic layers with embedded conductive patterns and passive components, creating compact, high-density circuits. Multi-layered designs are fundamental to achieving miniaturization in modern electronics, particularly in System-in-Package (SiP) solutions.
- Circuit Integration:This technology focuses on embedding active and passive components directly within the ceramic substrate, reducing overall size and improving electrical performance. Circuit integration is critical for advanced RF modules in 5G infrastructure and high-frequency communication devices.
- Thermal Management:Ceramic substrates with enhanced thermal conductivity dissipate heat effectively from integrated circuits, prolonging device lifespan and improving reliability. This capability is vital for high-power applications in electric vehicles and data center equipment.
- Electrical Insulation:Providing high dielectric strength, these ceramic technologies prevent electrical leakage and ensure signal integrity in high-voltage or high-frequency environments. Electrical insulation is a foundational requirement for all ceramic substrate applications.
Supply concentration for multi-layered technology remains high in established electronics manufacturing regions.
End User:
The application diversity within the end-user segments drives distinct material requirements and performance specifications for ceramic substrates.
- Aerospace:This segment demands radiation-hardened HTCC and high-reliability LTCC components for avionics, satellite communication payloads, and control systems. Aerospace applications prioritize extreme temperature tolerance and long-term stability.
- Consumer Electronics:High-volume production of smartphones, wearables, and other portable devices drives significant demand for compact, cost-effective LTCC solutions. Miniaturization and high-frequency performance are paramount for these products.
- Telecommunications:The 5G infrastructure build-out and next-generation network deployments necessitate advanced RF modules, filters, and antennas built on high-frequency LTCC and HTCC substrates. This sector requires excellent signal integrity at higher frequencies.
- Automotive:The transition to electric vehicles and advanced driver-assistance systems (ADAS) fuels demand for robust HTCC and LTCC in power modules, battery management systems, and high-temperature sensors. Ceramic's resistance to harsh environments is critical here.
The telecommunications sector currently represents the largest volume consumption, while automotive electrification shows the steepest expansion trajectory.
Application:
Customer type influences the procurement patterns and technical collaboration required for ceramic substrate applications.
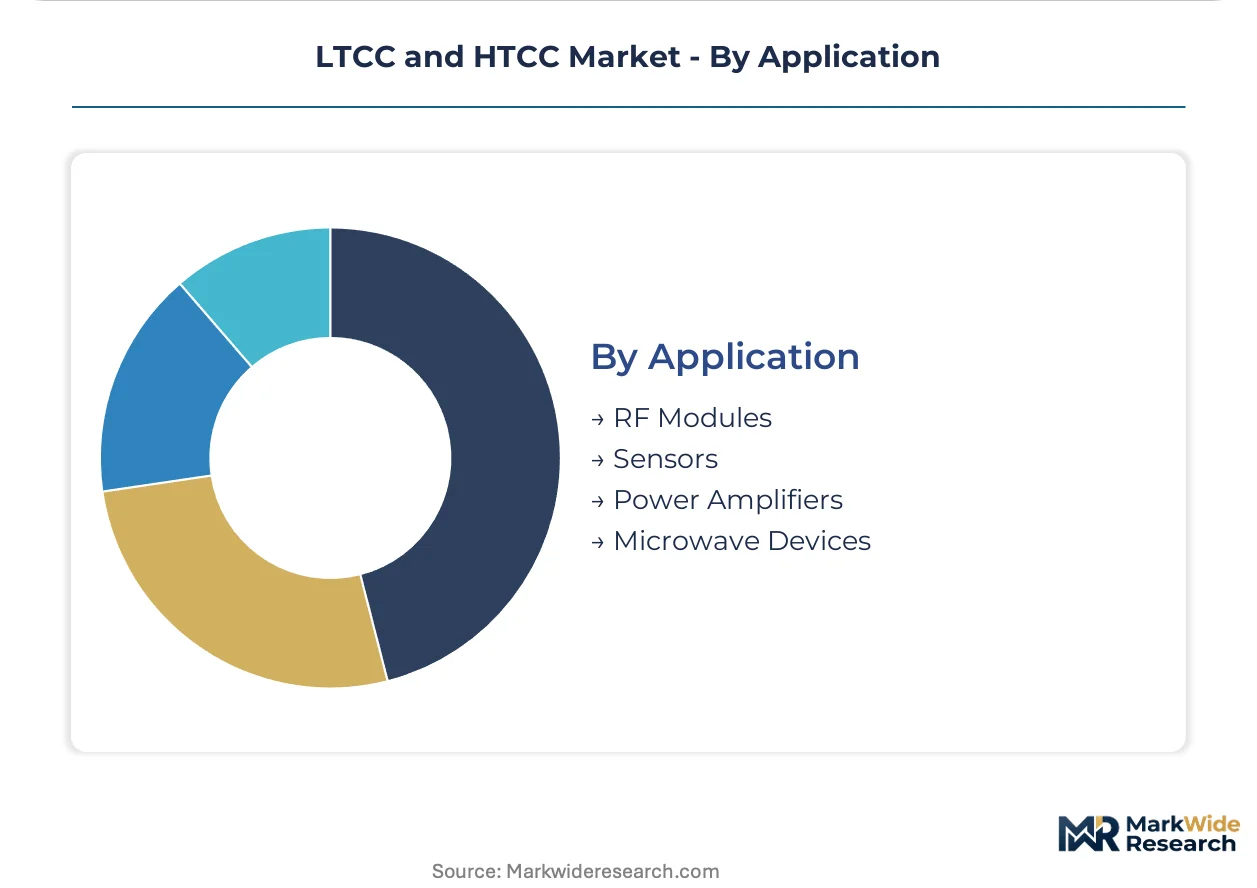
- RF Modules:These modules integrate multiple components onto a single substrate for wireless communication, radar, and satellite systems. RF modules for 5G base stations and user equipment are a primary application for LTCC and HTCC.
- Sensors:Ceramic substrates provide stable platforms for various sensors, including pressure, temperature, and gas sensors, particularly in harsh environments. Automotive and industrial sectors rely heavily on ceramic-based sensors for their robustness.
- Power Amplifiers:High-power applications, such as base stations and industrial equipment, utilize ceramic substrates for their excellent thermal management capabilities. HTCC is often preferred for its ability to handle high temperatures and power densities.
- Microwave Devices:These components operate at very high frequencies, requiring substrates with low dielectric loss and precise dimensional stability. LTCC and HTCC are essential for filters, oscillators, and antennas in microwave communication.
The market for RF modules commands the largest share, while sensors are gaining share fastest due to automotive electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's robust telecommunications infrastructure underwrites its central role in the LTCC and HTCC market. This infrastructure supports extensive 5G network deployments and advanced electronics manufacturing. The country's strategic investments foster innovation in high-frequency ceramic substrates.
United States
The United States drives demand through its extensive 5G infrastructure build-out and demanding aerospace applications. FCC standards influence RF module design, shaping substrate requirements for telecommunications equipment. Silicon Valley in California concentrates advanced packaging capabilities for high-frequency components.
Germany
German automotive electrification initiatives propel demand for robust HTCC and LTCC in power modules. The EU's RoHS and REACH directives mandate compliant ceramic and conductive paste formulations for electronic components. Bavaria's industrial clusters focus on high-temperature sensors and power electronics manufacturing.
China
China's rapid telecommunications expansion and vast consumer electronics manufacturing base fuel significant substrate demand. MIIT policies support domestic production capacity for advanced ceramic materials. The Yangtze River Delta region is expanding its ceramic substrate fabrication facilities.
Taiwan
Taiwan's advanced packaging capabilities and leading semiconductor industry create strong demand for high-density LTCC solutions. Local government incentives encourage co-design partnerships between ceramic suppliers and OEMs. The Hsinchu Science Park specializes in developing complex System-in-Package solutions.
Japan
Japanese manufacturers require high-frequency modules and specialized industrial sensors, driving demand for innovative ceramic substrates. METI initiatives support material science advancements and precision manufacturing processes. The Kansai region hosts significant research and development for co-fired ceramic technology.
LTCC and HTCC Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical ceramic substrates. The market exhibits a tiered structure, with a few large integrated manufacturers alongside numerous specialized component providers. Strategic archetypes include diversified electronics conglomerates, material science experts, and niche high-performance substrate producers focusing on specific end-user needs. Companies often pursue portfolio diversification and strategic partnerships to capture new opportunities in areas like automotive electrification and 5G infrastructure.
Among the diversified electronics conglomerates, Murata Manufacturing exemplifies a specialist in high-frequency LTCC modules for consumer electronics and telecommunications applications. Kyocera Corporation represents a material science expert, providing highly customized HTCC solutions for demanding aerospace requirements. TDK Corporation sits within the broad electronic components provider archetype, integrating ceramic substrates into its power and RF solutions across diverse end-user segments. These companies anchor significant portions of the market through their distinct technological focuses and strategic market positioning.
| Leading Market Players |
|---|
| Hitachi Metals |
| Taiyo Yuden |
| Murata Manufacturing |
| KOA Corporation |
| Samsung Electro-Mechanics |
| Kyocera |
| NGK Spark Plug |
| Maruwa |
| TDK Corporation |
| Others |
Cost & Logistics Intelligence
The Pacific Rim shipping lanes' cost dynamics, influenced by global energy prices, directly impact the supply concentration of ceramic substrates and their downstream price differentiation in consumer electronics.
Pricing Analysis
Volume-based pricing models dominate the LTCC and HTCC market, reflecting a contract-based long-term offtake approach for major OEMs. Price differentiation stems from customization levels for aerospace applications and certification grades for automotive power modules. Pricing pressure intensifies due to material sourcing volatility, particularly for high-purity alumina powders. Consumer electronics manufacturers exhibit the highest price sensitivity, contrasting with the lower sensitivity in aerospace.
Supply Chain Analysis
Leading contract manufacturers like Samsung Electro-Mechanics and Murata Manufacturing anchor significant co-fired ceramic substrate production capacity in Asia. Geographic supply concentration centers on Taiwan, South Korea, and Japan for advanced packaging. Raw material dependencies include high-purity alumina powders, specialized conductive pastes, and refractory metals like tungsten. Geopolitical sourcing risks for these critical inputs present a structural supply chain risk. Distribution runs through direct OEM engagements and specialized electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LTCC and HTCC market is experiencing a shift in buyer power, driven by the increasing consolidation of telecommunications equipment manufacturers and automotive Tier 1 suppliers.
For Market Incumbents:
Pre-empt emerging material science threats by investing heavily in R&D for compliant ceramic and conductive paste formulations. Diversify manufacturing footprints beyond traditional hubs like Japan and South Korea to mitigate geopolitical sourcing risks for key inputs. Leverage deep material science expertise to offer highly customized HTCC solutions, strengthening existing relationships with demanding aerospace clients. Expand capacity in high-growth regions like India, supported by local government incentives, to counter regional competitors.
For New Entrants and Emerging Players:
Establish a beachhead in niche high-reliability applications, such as implantable medical devices, where performance outweighs initial cost. Target the burgeoning electric vehicle power module segment in Europe, leveraging robust HTCC solutions. Penetrate markets with less established domestic supply, like India, by offering cost-effective LTCC solutions for consumer electronics. Go-to-market via strategic partnerships with local electronics manufacturing service providers.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified electronics conglomerates seeking to divest non-core ceramic substrate divisions. Long-term viability rests on securing intellectual property in advanced packaging and next-generation material formulations. Acquisition targets include specialized producers of biocompatible ceramics or radiation-hardened HTCC for space applications. The signal to watch is the acceleration of 6G research and development, indicating future high-frequency substrate requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Establishes local production to serve burgeoning semiconductor and consumer electronics industries. |
| Biocompatible Ceramic R&D | Unlocks new opportunities in the high-reliability implantable medical device market. |
| Partnerships with Automotive OEMs | Secures long-term contracts for robust HTCC solutions in electric vehicle power modules. |
| Investment in 3D Ceramic Printing | Enables rapid prototyping and customization for complex, multi-layered circuit designs. |
| Acquisition of Specialty Paste Manufacturers | Strengthens upstream control over critical conductive material inputs and intellectual property. |
Research Approach
Desk research of academic journals, patent databases, and regulatory filings preceded structured interviews with material scientists, procurement leads, and product development engineers. This approach combined primary insights with secondary validation across industry reports, company annual statements, and trade association publications. Bottom-up and top-down triangulation ensured data consistency and comprehensiveness.
Assumptions regarding technological adoption rates and regulatory stability were held fixed across the analysis window, while variations in raw material costs were modeled. The analytical framework segmented the market by product type, technology, end-user, application, and regional manufacturing capabilities. Compound annual growth rates were derived from historical data extrapolation and projected demand curves. Key forecast inputs included 5G infrastructure build-out plans and electric vehicle production forecasts.
Stress conditions across geopolitical trade policies and critical mineral supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented through expert consensus and quantitative modeling. Quarterly review of telecommunications infrastructure investment and automotive electrification rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Reachers Market