
 Gan Transistor Market | 2026-2036
Gan Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Gan Transistor Market Foresight
Silicon carbide substrate integration is reconfiguring how GaN transistor manufacturers design epitaxial stacks and thermal management architectures. Infineon Technologies leverages its vertically integrated SiC and GaN portfolios to control wafer supply from substrate to packaged device. Qorvo anchors its defense and 5G infrastructure positions through specialized foundry relationships and proprietary process nodes. Texas Instruments competes by extending its analog power management expertise into integrated GaN gate drivers and module solutions.
Gallium nitride transistors are wide-bandgap semiconductor devices fabricated on silicon, silicon carbide, or sapphire substrates, typically operating at switching frequencies above 1 MHz with breakdown voltages ranging from 15 V to 650 V; they deliver higher power density and lower switching losses than silicon MOSFETs for power conversion and RF amplification applications. High electron mobility transistors dominate RF and millimeter-wave applications where electron mobility exceeding 2,000 cm²/V·s enables superior gain at frequencies above 3 GHz. Enhancement-mode technology leads consumer electronics and adapter markets because normally-off operation simplifies circuit design and meets safety requirements without complex gate drive circuits. Power amplifiers represent the fastest-growing application segment as 5G massive MIMO deployments and radar modernization programs consume higher volumes of discrete and integrated GaN devices.
The U.S. Department of Commerce export controls on advanced semiconductor manufacturing equipment shape which foundries can access epitaxial growth and lithography tools for GaN production. The EU Green Deal and REACH regulations constrain material sourcing and mandate energy efficiency benchmarks that favor GaN adoption in data center power supplies and renewable energy inverters. China's MIIT dual carbon goals and GB standards for telecommunications equipment accelerate domestic GaN qualification programs. Stakeholders must monitor how evolving trade restrictions and carbon accounting rules reshape substrate sourcing strategies and foundry location decisions.
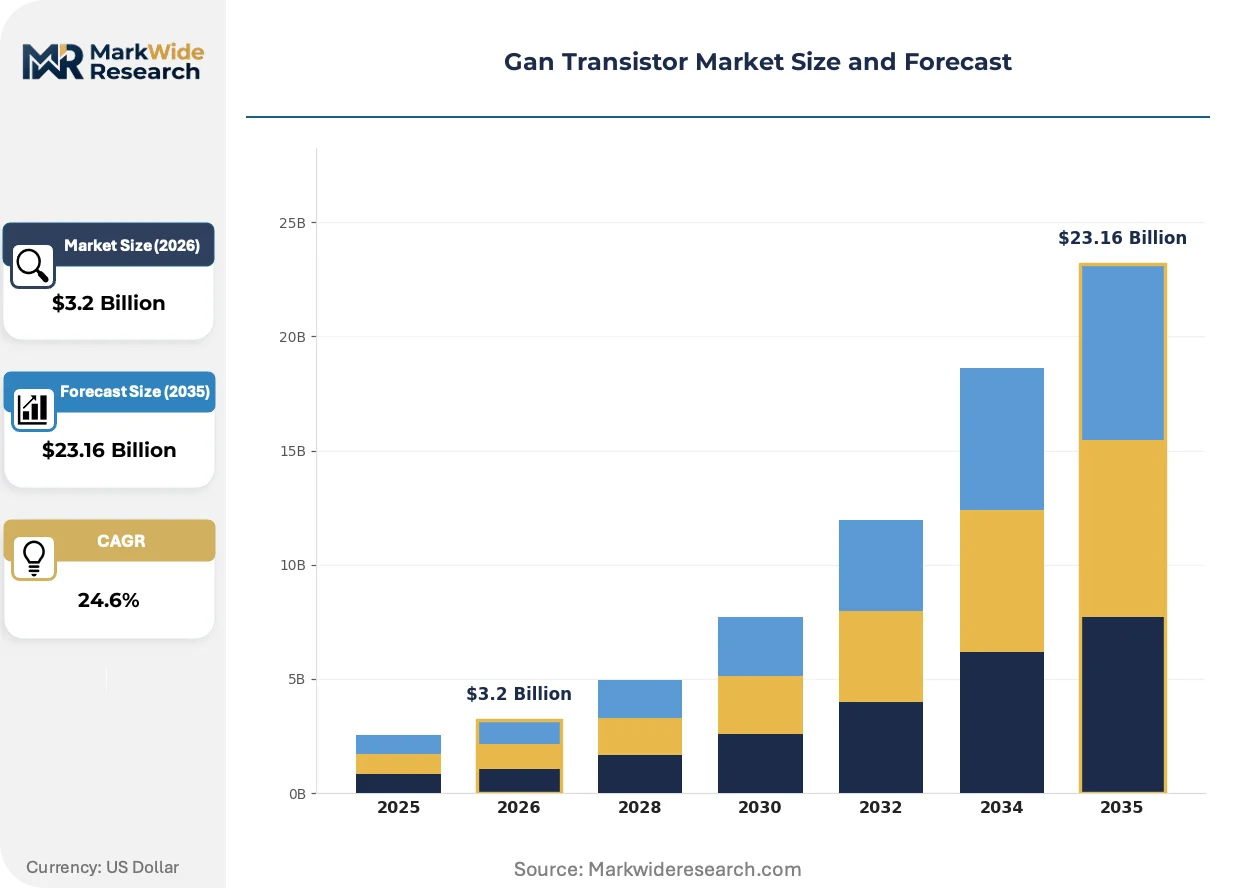
Market Dynamics
Silicon carbide substrate integration is reconfiguring how GaN transistor manufacturers design epitaxial stacks and thermal management architectures, compressing development cycles while raising capital barriers for new entrants.
Growth Catalysts
- EU Green Deal energy efficiency mandates:Tightening requirements for power conversion components in data centers and renewable energy inverters are pulling GaN adoption forward across European telecommunications infrastructure.
- 5G massive MIMO deployment:Power amplifier demand in base stations is accelerating volume consumption of discrete and integrated GaN devices for millimeter-wave transmission.
- China domestic foundry expansion:MIIT dual carbon goals and GB standards for telecommunications equipment are accelerating domestic GaN qualification programs and captive supply buildout.
Market Restraints
- Epitaxial wafer supply concentration:Limited qualified suppliers for GaN-on-SiC epiwares creates bottleneck risk, with substrate sourcing concentrated among Japanese and U.S. vendors.
- U.S. Department of Commerce export controls:Restrictions on advanced semiconductor manufacturing equipment constrain which foundries can access MOCVD reactors and lithography tools for GaN production.
- Silicon superjunction MOSFET cost advantage:Mature silicon technology maintains price-performance competitiveness below 200 V applications, limiting GaN penetration in cost-sensitive consumer adapters.
Strategic Opportunities
- Automotive onboard charging integration:Electric vehicle platforms above 400 V architecture present white space for GaN power modules, with OEMs qualifying devices for 11 kW and 22 kW OBC designs.
- India PLI scheme for semiconductor manufacturing:Production-linked incentives for compound semiconductors are attracting GaN fab investments targeting domestic 5G and defense electronics demand.
- GaN-SiC hybrid module convergence:Combining GaN HEMT switching with SiC diode freewheeling enables new power density benchmarks in multi-kilowatt server power supplies.
Industry Challenges
- Gate driver integration complexity:Designing robust gate drive circuits for enhancement-mode GaN devices requires specialized expertise in millivolt-precision timing and dv/dt management that remains scarce among power electronics engineers.
- JEDEC qualification timeline compression:Accelerating automotive AEC-Q101 and industrial JEDEC standards compliance for new GaN process nodes demands extended burn-in testing that strains R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan Transistor Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $23.16 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Electron Mobility Transistor, Metal Semiconductor Field Effect Transistor, Junction Field Effect Transistor, Gate Injection Transistor Technology: Enhancement Mode, Depletion Mode, Cascode, Lateral, Vertical Application: 5G Infrastructure, Radar Systems, Satellite Communications, Power Amplifiers, Consumer Electronics End User: Telecommunication Equipment Manufacturers, Defense Contractors, Satellite Operators, Semiconductor Foundries |
| Companies Covered | Infineon Technologies, GaN Systems, Efficient Power Conversion, Transphorm, Navitas Semiconductor, Qorvo, Texas Instruments, Toshiba Electronic Devices & Storage Corporation, Nexperia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan Transistor Market Shifts & Advancements
GaN transistor architecture is undergoing rapid compression as substrate engineering, packaging integration, and system-level design converge to unlock frequency and density benchmarks unreachable with silicon legacy.
Enhancement-mode GaN-on-silicon technology is collapsing the cost-performance barrier for sub-500 V power conversion. Consumer electronics OEMs in adapter and mobile fast-charging segments are adopting integrated GaN power ICs at volumes that compress silicon superjunction MOSFET share in 65 W to 140 W applications. This substrate choice is collapsing the traditional three-chip solution—controller, driver, power switch—into single-package monolithic devices that halve board area and passive component count.
REACH and RoHS substance restrictions are tightening material sourcing constraints for GaN device metallization and die-attach processes. The EU Green Deal's carbon border adjustment mechanism is forcing foundries to document embodied emissions across epitaxial growth and wafer fabrication stages. European power supply manufacturers are responding by qualifying GaN devices from suppliers with verified low-carbon substrate sourcing, prioritizing vendors with vertically controlled SiC wafer supply.
Telecommunications equipment procurement is consolidating around qualified second-source requirements that favor GaN suppliers with dual-fab redundancy. Base station OEMs are disintermediating traditional distributor channels for direct foundry relationships that secure allocation priority during supply constraints. This pattern is most visible in China, where domestic 5G infrastructure buildout has concentrated procurement decisions among three state-owned operators with centralized device qualification lists.
Gan Transistor Market Segmentation
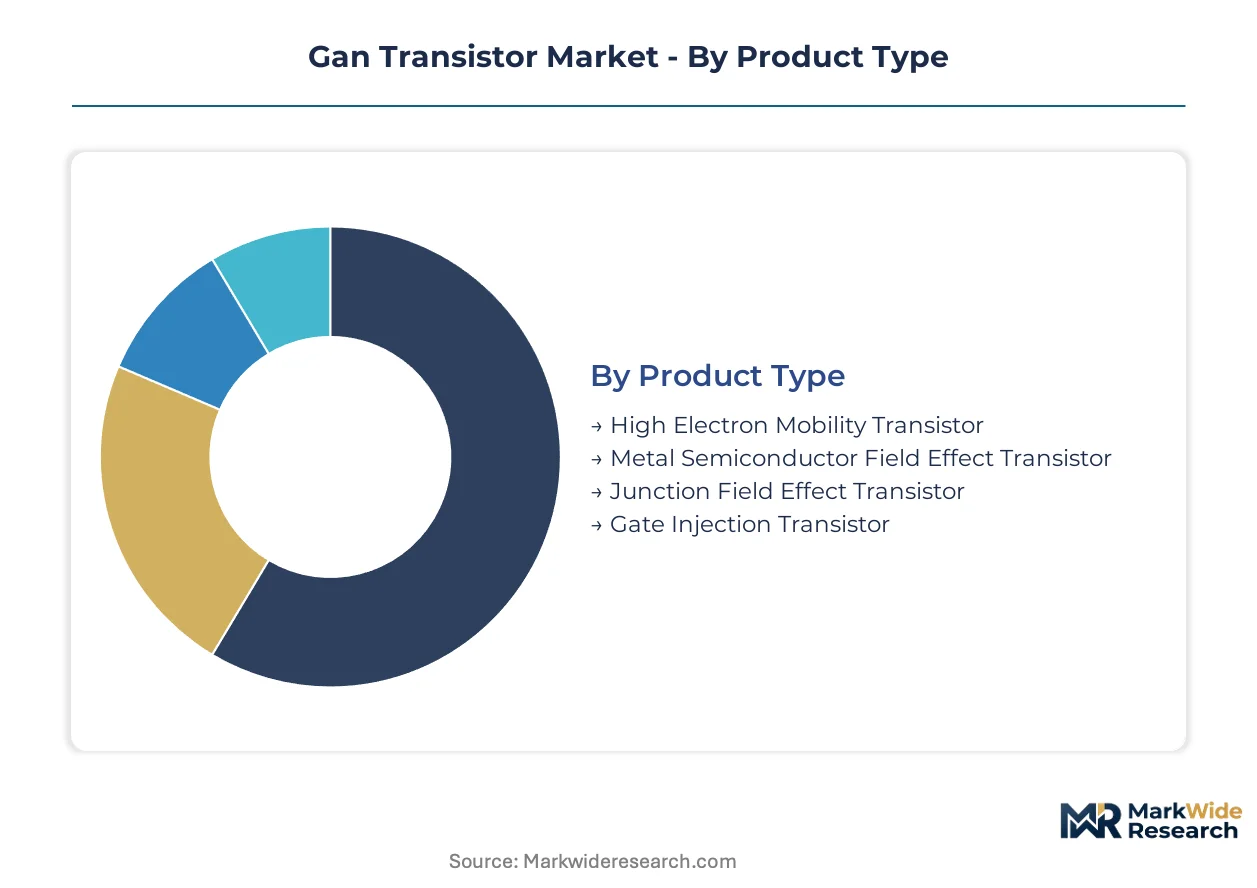
GaN transistor segmentation reveals how substrate engineering, circuit topology, and end-use requirements fragment supply chains. Manufacturers configure process nodes and packaging architectures differently for RF amplification versus power conversion, creating distinct competitive arenas with unique qualification barriers.
Product Type:
Mature epitaxial designs coexist with emerging architectures as frequency demands and thermal constraints push device physics boundaries.
- High Electron Mobility Transistor:HEMT structures exploit two-dimensional electron gas channels with electron mobility exceeding 2,000 cm²/V·s, enabling millimeter-wave gain above 3 GHz. 5G massive MIMO base stations in China concentrate procurement for these devices as state-owned operators consolidate qualified supplier lists.
- Metal Semiconductor Field Effect Transistor:MESFET technology relies on Schottky gate contacts on semi-insulating GaN substrates, delivering robust performance in harsh radiation environments. Satellite operators in geostationary and low-earth orbit constellations specify MESFETs for space-qualified transponder systems.
- Junction Field Effect Transistor:JFET architectures offer normally-on operation with simple gate drive requirements for high-reliability defense applications.
- Gate Injection Transistor:GIT devices integrate p-GaN gate structures for native enhancement-mode operation without cascode complexity.
HEMT handles the majority of throughput; Gate Injection Transistor is the fastest mover on share.
Technology:
Cost tier differentiation separates premium substrate-integration approaches from volume silicon-based alternatives.
- Enhancement Mode:Normally-off operation eliminates complex gate drive circuits and satisfies safety agency requirements for consumer electronics. Adapter manufacturers in Shenzhen and Dongguan qualify enhancement-mode GaN-on-silicon devices for 65 W to 140 W fast-charging applications.
- Depletion Mode:Native normally-on devices require negative gate bias but achieve lower on-resistance and higher breakdown voltage for RF power amplifiers.
- Cascode:Series connection of low-voltage silicon MOSFET with depletion-mode GaN HEMT delivers enhancement-mode functionality using mature packaging.
- Lateral:Current flows parallel to substrate surface, enabling high-frequency operation with simplified epitaxial growth on silicon wafers.
- Vertical:Current traverses the substrate thickness, supporting higher voltage blocking and superior thermal extraction for automotive traction inverters.
Enhancement Mode commands the dominant revenue position; Vertical architectures are expanding most quickly as electric vehicle platforms above 400 V qualify devices for onboard charging.
Application:
Volume concentration varies sharply between infrastructure deployment cycles and consumer replacement markets.
- 5G Infrastructure:Massive MIMO arrays and millimeter-wave small cells consume discrete and integrated GaN power amplifiers. China's MIIT dual carbon goals accelerate domestic base station buildout with centralized procurement through three state-owned operators.
- Power Amplifiers:RF amplification spans cellular base stations, radar transmitters, and broadcast transmitters with efficiency requirements above 60%. Defense contractors in the US and Europe specify GaN for phased array radar modernization programs.
- Radar Systems:Active electronically scanned arrays leverage GaN's power density for airborne and naval surveillance platforms.
- Satellite Communications:Ka-band and Q-band transponders require high linearity and radiation tolerance for geostationary and constellation deployments.
- Consumer Electronics:Smartphone chargers and laptop adapters adopt integrated GaN power ICs to minimize board area and passive component count.
Power Amplifiers absorb the largest device volumes; 5G Infrastructure is gaining share fastest as deployment waves concentrate procurement.
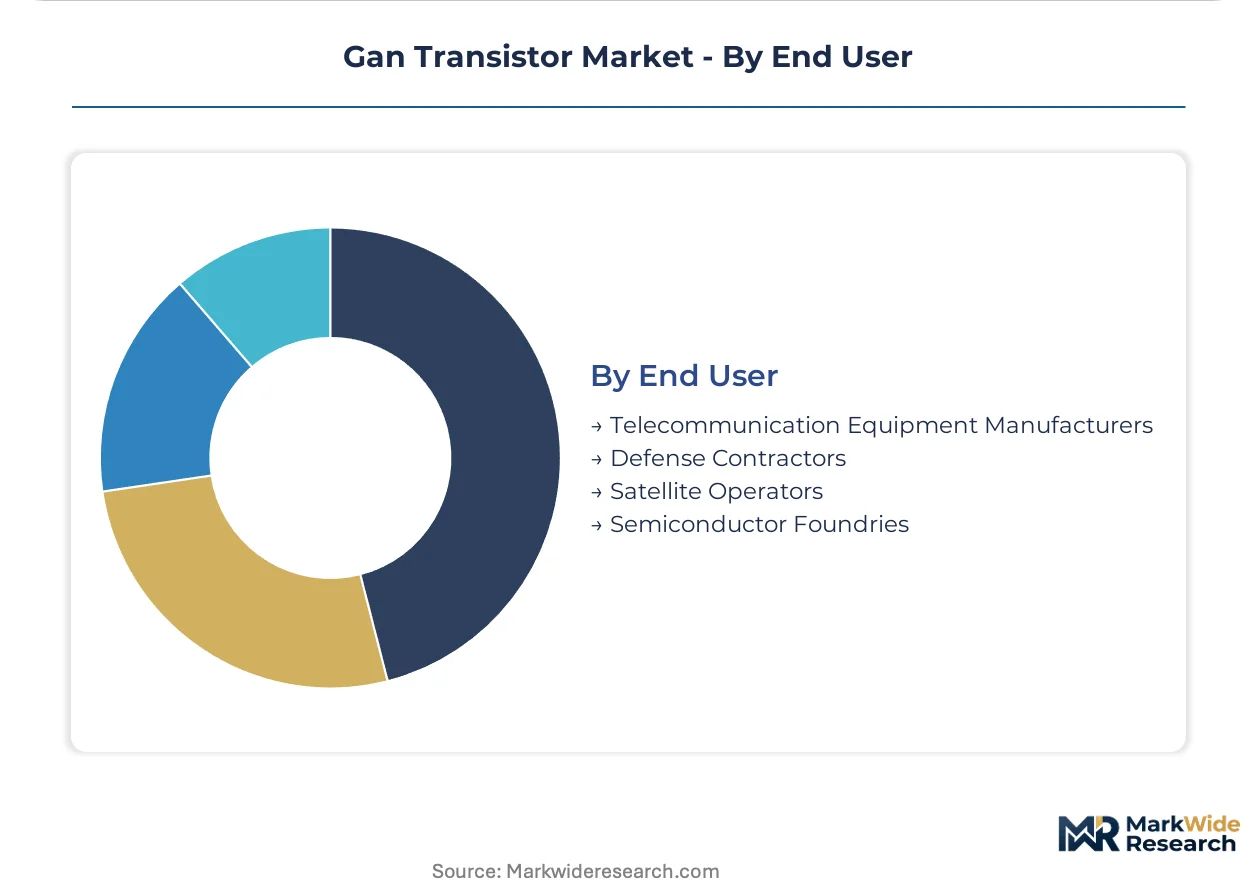
End User:
Customer type determines qualification protocols, with defense and satellite applications imposing multi-year validation timelines.
- Telecommunication Equipment Manufacturers:Base station OEMs including Ericsson, Nokia, and Huawei specify GaN devices for macro cell and small cell radio units. These manufacturers disintermediate distributors for direct foundry relationships that secure allocation priority during supply constraints.
- Defense Contractors:Prime contractors for radar, electronic warfare, and communications systems require JEDEC-qualified devices with traceable supply chains.
- Satellite Operators:Constellation deployers and geostationary service providers specify radiation-hardened GaN for transponder and traveling-wave tube replacement.
- Semiconductor Foundries:Merchant fab operators including X-FAB and Tower Semiconductor offer GaN process platforms for fabless design houses.
Telecommunication Equipment Manufacturers drive the dominant procurement volume; Defense Contractors are climbing the fastest as radar modernization programs accelerate qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in GaN transistors reflect divergent export control regimes and domestic capacity buildouts. Nations with captive epitaxial growth capabilities run structural surpluses, while import dependence concentrates in regions prioritizing downstream system integration.
United States
Defense procurement and 5G infrastructure deployment drive domestic absorption of high-frequency GaN HEMTs. The U.S. Department of Commerce export controls on MOCVD equipment constrain foundry expansion, pushing design houses toward fabless models. Defense contractors in Massachusetts and California anchor qualification programs for radar and electronic warfare systems.
China
State-owned operators consolidate procurement for 5G massive MIMO buildout under MIIT dual carbon targets. GB standards for telecommunications equipment accelerate domestic GaN qualification timelines. Foundry investments in Shenzhen and Dongguan expand GaN-on-silicon capacity for consumer adapter and base station power amplifier markets.
Germany
Automotive OEMs qualify GaN devices for 400 V onboard charging architectures in electric vehicle platforms. EU Green Deal energy efficiency mandates tighten requirements for data center power supplies, pulling GaN adoption forward. Industrial electronics clusters in Bavaria and Baden-Württemberg integrate GaN power modules into renewable energy inverter designs.
Japan
Epitaxial wafer suppliers concentrate substrate sourcing for GaN-on-SiC devices serving satellite and radar applications. METI industrial policy supports compound semiconductor foundry investments targeting 6G pre-standardization research. Equipment manufacturers in Tokyo and Osaka supply MOCVD reactors to qualified fabs globally.
South Korea
Memory and display conglomerates diversify into GaN power ICs for smartphone fast-charging adapters. MFDS-equivalent semiconductor regulations align with international JEDEC standards for consumer electronics qualification. Seoul Capital Area packaging houses develop system-in-package solutions integrating GaN switches with gate drivers.
Gan Transistor Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated substrate-to-device manufacturers and fabless design houses dependent on merchant foundry capacity. Tier-one players control epitaxial wafer supply chains through captive production or exclusive sourcing agreements. Three archetypes dominate: integrated semiconductor conglomerates with SiC and GaN portfolios, RF specialists leveraging defense and telecommunications relationships, and power management incumbents extending analog expertise into integrated GaN solutions. Competitive moves concentrate on foundry partnership exclusivity and JEDEC qualification acceleration for automotive-grade process nodes.
Within the integrated conglomerate tier, Infineon Technologies and Toshiba Electronic Devices & Storage Corporation exemplify substrate-to-module control strategies. Among RF-focused specialists, Qorvo occupies a position anchored by defense and 5G infrastructure relationships. Texas Instruments represents the power management extension archetype, translating analog gate driver expertise into integrated GaN module designs. These three company profiles illustrate how divergent heritage competencies—materials science, high-frequency design, and power conversion systems—converge on overlapping GaN market opportunities through distinct technical and commercial pathways.
| Leading Market Players |
|---|
| Infineon Technologies |
| GaN Systems |
| Efficient Power Conversion |
| Transphorm |
| Navitas Semiconductor |
| Qorvo |
| Texas Instruments |
| Toshiba Electronic Devices & Storage Corporation |
| Nexperia |
| Others |
Supply & Pricing Matrix
Japanese and U.S. epitaxial wafer suppliers concentrate control over GaN-on-SiC substrate sourcing, anchoring margin capture in the upstream substrate tier while downstream power module assemblers face persistent cost pass-through pressure.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium automotive-grade, standard industrial-grade, and economy consumer-grade tiers. Price differentiation rests on AEC-Q101 certification status and volume commitment scale, with automotive-grade devices commanding substantial premiums over adapter-market alternatives. Cost compression in the consumer tier intensifies because Shenzhen-based fast-charging OEMs negotiate aggressive foundry allocations. Defense contractors exhibit the least price sensitivity due to multi-year qualification lock-in, while white-label adapter manufacturers operate on thinnest margins.
Supply Chain Analysis
Extended payment terms from Japanese MOCVD equipment vendors strain working capital for emerging foundries attempting capacity expansion. Geographic supply concentration centers on Japan for epitaxial reactors, China for GaN-on-silicon foundry services, and Germany for automotive qualification testing. Raw material dependencies encompass high-purity gallium metal, silicon carbide substrates, and specialty precursor gases. Single-source vulnerability around qualified GaN-on-SiC epiware suppliers creates allocation risk during demand surges. Distribution runs through direct foundry relationships for base station OEMs and authorized distributors for smaller industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN transistor demand is accelerating through a technology inflection as 5G massive MIMO deployment and 400 V electric vehicle architectures simultaneously displace silicon legacy solutions.
For Market Incumbents: Insulate core margin pools by securing exclusive multi-year epitaxial wafer supply agreements with Japanese substrate vendors before export control tightening restricts equipment access. Prioritize AEC-Q101 certification investment for automotive onboard charging designs, as OEM qualification timelines create sticky switching costs that emerging competitors cannot easily replicate. For New Entrants and Emerging Players: Indian production-linked incentive schemes for compound semiconductors represent the most penetrable entry point for fabless GaN design houses seeking foundry partnerships outside Chinese and U.S. regulatory crossfire. Target 11 kW electric vehicle onboard charging module designs where incumbent qualification gaps persist, deploying direct application engineering support to accelerate OEM design-in cycles. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated substrate-to-device specialists with captive SiC wafer supply and existing JEDEC qualification infrastructure. Long-term viability over the coming decade hinges on automotive-grade process node maturity rather than consumer adapter volume exposure. Watch for MIIT procurement list inclusion as the signal that Chinese domestic qualification programs have achieved technical parity with foreign incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive AEC-Q101 Qualification | Unlocks 400 V onboard charging module supply agreements with German and U.S. electric vehicle OEMs. |
| GaN-on-SiC Epitaxial Capacity Expansion | Addresses bottleneck risk as 5G base station power amplifier procurement concentrates among three state-owned Chinese operators. |
| Integrated Gate Driver Module Development | Compresses board area and passive component count for Shenzhen consumer adapter manufacturers. |
| Dual-Fab Redundancy Certification | Satisfies Ericsson and Nokia second-source requirements for European telecommunications infrastructure procurement. |
| REACH-Compliant Low-Carbon Sourcing | Aligns with EU Green Deal carbon border adjustment mechanism for data center power supply qualification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with GaN process engineers, base station procurement directors, automotive platform power electronics leads, and semiconductor foundry operations managers; and secondary validation through SEC semiconductor filings, MIIT equipment procurement disclosures, EU Green Deal regulatory texts, and JEDEC qualification databases. Bottom-up and top-down triangulation cross-checked wafer capacity announcements against end-use equipment shipment data.
Forecast inputs encompassed technology segmentation by substrate material, voltage class, and application vertical across the projection horizon. Analytical framework modeled enhancement-mode versus depletion-mode adoption curves, RF power amplifier versus power conversion demand splits, and regional foundry capacity buildout trajectories. CAGRs were derived from equipment deployment cycles, automotive platform electrification roadmaps, and telecommunications infrastructure replacement waves.
Stress conditions across export control escalation, epitaxial reactor delivery delays, and electric vehicle platform voltage architecture shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about qualification timeline compression and foundry yield maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market