
 Precision Link Carrier Market | 2026-2036
Precision Link Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Link Carrier Market Analytics
Buyer concentration among automotive OEMs is recalibrating procurement patterns across the precision link carrier supply base. DESTACO leverages its Dover Corporation parent network to dominate fixture and carrier integration for high-volume assembly cells. Sankyo Automation anchors its position through specialized cam-driven indexing technology serving Japanese and North American electronics manufacturers. CDS competes on customized carrier configurations for European packaging automation integrators.
A precision link carrier is a mechanically indexed conveyor system that transfers workpieces through discrete stations using cam-driven or servo-controlled link chains, typically achieving positioning repeatability within ±0.05 mm for synchronized assembly operations. Steel-constructed high-load carriers sustain the dominant share of automotive powertrain and body-in-white applications where payload requirements exceed 500 kg per station. Customized carrier configurations represent the fastest-expanding segment as electronics manufacturers demand substrate-specific pallet designs for semiconductor test-and-burn-in lines. Aluminum standard carriers occupy the mature volume tier in consumer goods packaging where lighter payloads and faster cycle times prioritize material cost efficiency over structural rigidity.
The EU Machinery Directive and ISO 13849 safety standards mandate redundant positioning verification for automated carrier systems in European manufacturing facilities, elevating demand for servo-encoded link designs. The US OSHA lockout/tagout regulations and FDA cGMP requirements for medical device assembly constrain material selection and cleanability specifications in regulated end-uses. Stakeholders must monitor how NHTSA traceability mandates for automotive component origin affect carrier serialization and data-logging requirements in battery module assembly lines.
Market Dynamics
Automotive OEM consolidation around electric vehicle platforms is compressing carrier specification cycles and forcing modular redesigns that accommodate multiple battery form factors within single assembly lines.
Growth Catalysts
- ISO 13849-1 compliance mandates:European automotive plants must install safety-rated positioning systems, accelerating servo-encoded link carrier deployments in Germany and Czechia.
- Semiconductor test-and-burn-in expansion:Electronics manufacturers in Taiwan and South Korea demand substrate-specific pallet carriers for high-throughput chip validation lines.
- Steel alloy innovations:Advanced high-strength steel formulations enable lighter high-load carriers without sacrificing rigidity for powertrain assembly applications.
Market Restraints
- Specialized cam manufacturing concentration:Precision grinding capacity for indexing cams concentrates in Japan and southern Germany, creating supply vulnerability.
- Aluminum price volatility:Standard carrier margins compress when LME aluminum benchmarks spike, squeezing packaging automation integrators.
- Linear motor substitution:Direct-drive conveyor systems threaten link carriers in cleanroom electronics applications where magnetic levitation eliminates mechanical wear.
Strategic Opportunities
- India PLI scheme for automotive:Domestic EV manufacturing incentives attract precision carrier vendors to establish local assembly for Maruti Suzuki and Tata Motors lines.
- Servo-pneumatic hybrid architectures:Convergence of electric positioning with pneumatic clamping opens pharmaceutical packaging applications requiring explosive atmosphere certification.
- Battery module assembly retrofit:Legacy internal combustion engine plants in Michigan and Stuttgart require carrier system overhauls for cylindrical and prismatic cell handling.
Industry Challenges
- Mechatronics technician scarcity:Cam-driven system commissioning requires rare expertise combining mechanical timing and servo tuning, extending installation timelines.
- Legacy PLC integration:Brownfield automotive plants running Siemens S7-300 or Allen-Bradley ControlLogix platforms demand custom gateway development for modern encoder feedback.
- CE-MDR dual certification:Medical device carriers must simultaneously satisfy machinery safety and medical device regulations, doubling documentation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Link Carrier Market |
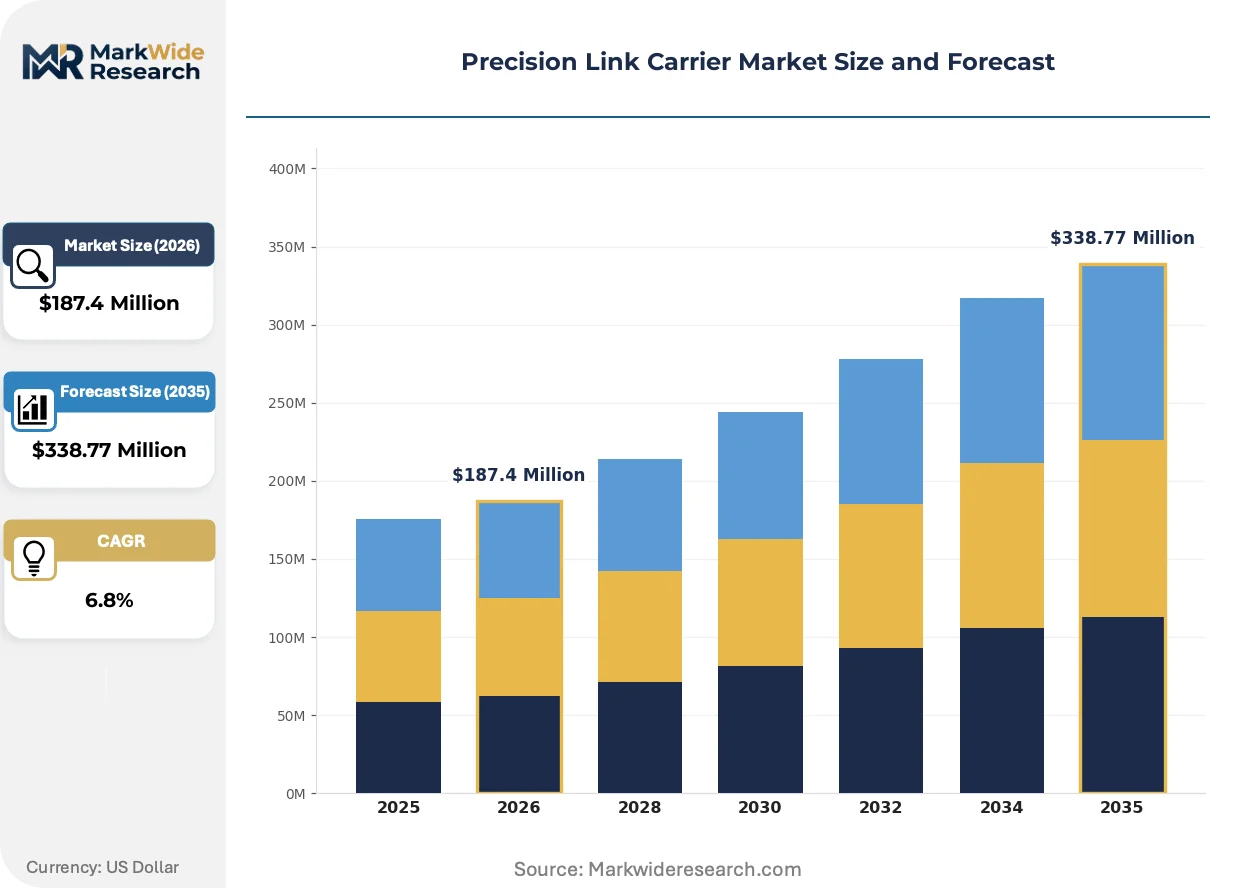
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Carrier, Customized Carrier, High-Load Carrier, Low-Load Carrier Material: Aluminum, Steel, Plastic, Composite Application: Automotive Assembly, Electronics Manufacturing, Packaging Solutions, Aerospace Engineering End User: Manufacturers, Distributors, Retailers, Service Providers |
| Companies Covered | DESTACO (Dover Corporation), CDS (Bettinelli), ITALPLANT srl, Cyclo Index (Leggett & Platt), Sankyo Automation, Motion Index Drives, Inc., Stelron Components, Packam Controls, Alphabetech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Link Carrier Market Evolving Landscape
Distributed control architectures are fragmenting traditional centralized carrier system designs, enabling cell-level autonomy that reduces wiring complexity and improves fault isolation.
Servo-driven link chains with integrated safety encoders are decentralizing motion control from plant-level PLCs to edge-mounted drive modules. Automotive OEMs in Germany and the US Midwest are deploying these architectures for body-in-white lines requiring sub-100-millisecond reconfiguration between vehicle variants. The shift compresses commissioning timelines and reduces cabinet footprint by eliminating centralized servo amplifiers.
EU Machinery Directive 2006/42/EC amendments tighten functional safety requirements for collaborative carrier zones where human operators interact with automated pallets. Manufacturers must now implement redundant position verification through dual-channel encoders or mechanical interlocks, elevating system cost but reducing liability exposure. German Tier-1 suppliers are responding by pre-certifying carrier modules to accelerate end-user compliance.
Automotive procurement teams are unbundling carrier hardware from integration services, awarding mechanical supply to specialized vendors while retaining system engineering in-house. This bifurcation disrupts traditional turnkey automation channels and pressures distributor margins. The pattern is most pronounced in Volkswagen Group and Hyundai Motor facilities, where direct carrier sourcing from DESTACO and CDS precedes third-party integration.
Precision Link Carrier Market Segmentation
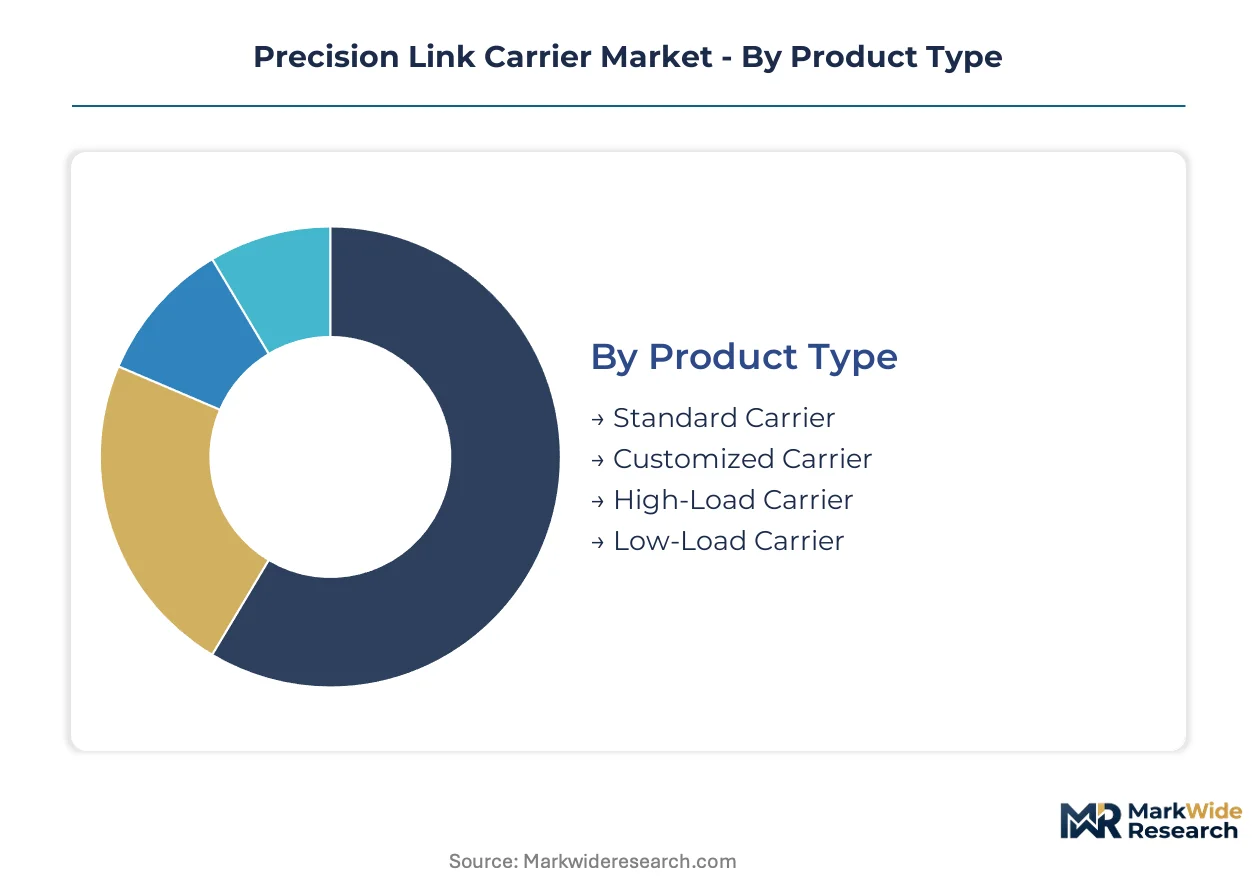
Precision link carrier segmentation reveals how payload requirements, material specifications, and end-use complexity fragment procurement patterns across discrete manufacturing environments. Distinct carrier configurations serve standalone indexing stations versus deeply embedded transfer systems within larger automation architectures.
Product Type:
Integration depth varies sharply across product types, with standalone modular carriers dominating retrofit installations while embedded high-load systems anchor greenfield automotive lines.
- High-Load Carrier:Steel-reinforced link chains engineered for payloads exceeding 500 kg per station, featuring hardened cam followers and precision-ground indexing cams. Automotive powertrain and body-in-white lines in Germany and Michigan specify these for engine block and battery module transfer operations where structural deflection tolerance falls below 0.02 mm. The EU Machinery Directive's redundant safety encoder mandates elevate system cost but lock in specification for European OEMs.
- Customized Carrier:Substrate-specific pallet designs with dedicated clamping geometries, vacuum channels, or thermal management features tailored to workpiece contours. Electronics manufacturers in Taiwan and South Korea commission these for semiconductor test-and-burn-in lines where die-level handling demands electrostatic discharge protection and sub-micron positioning repeatability. Wafer thinning trends toward 50-micron thicknesses intensify demand for compliant support surfaces.
- Standard Carrier:Catalog-configured aluminum link chains with standardized pitch dimensions and interchangeable tooling plates. Packaging automation integrators in consumer goods manufacturing deploy these for carton handling and bottle indexing where payload requirements stay below 50 kg and cycle time compression outweighs customization needs.
- Low-Load Carrier:Lightweight polymer or aluminum constructions optimized for rapid acceleration profiles and sub-100-millisecond station-to-station transfer times. Cleanroom electronics assembly in Singapore and Penang utilizes these for printed circuit board population and micro-component placement where inertial loading limits drive specification.
High-load carriers lead volumes today; customized configurations are gaining share fastest.
Material:
Material selection traces cost-performance tradeoffs, with premium alloys commanding structural applications and commodity metals saturating high-volume packaging segments.
- Steel:Advanced high-strength steel formulations combining manganese-boron microalloying with controlled cooling protocols achieve tensile strengths above 1,200 MPa while maintaining machinability for precision cam grinding. Automotive OEMs in Stuttgart and Wolfsburg specify these for battery module assembly lines where carrier rigidity directly impacts weld seam consistency. NHTSA traceability mandates for component origin are accelerating serialization integration into steel carrier forgings.
- Aluminum:Extruded 6061-T6 or 7075-T6 profiles with hard-anodized wear surfaces deliver weight reductions of 60-70% versus steel equivalents. Standard carrier producers serving European packaging integrators face margin compression when LME aluminum benchmarks spike, driving selective substitution toward steel-polymer hybrid constructions.
- Plastic:Glass-filled polyamide or PEEK link segments with integral wear pads, specified for corrosive washdown environments and pharmaceutical cleanrooms where metallic contamination risks exclude ferrous materials.
- Composite:Carbon fiber reinforced polymer link chains emerging for aerospace tool handling applications where specific stiffness requirements exceed metallic capabilities and magnetic transparency enables automated guided vehicle co-navigation.
Steel dominates revenue concentration; aluminum maintains the widest installation base across end-uses.
Application:
Application segmentation maps carrier specification intensity, with automotive and electronics demanding precision indexing while packaging prioritizes throughput velocity.
- Automotive Assembly:Multi-station transfer systems synchronizing body-in-white framing, powertrain marriage, and battery module integration with cycle times below 60 seconds per vehicle. Volkswagen Group and Hyundai Motor facilities are unbundling carrier hardware procurement from integration services, awarding mechanical supply to specialized vendors while retaining system engineering in-house.
- Electronics Manufacturing:High-density substrate handling for semiconductor test, burn-in, and final assembly operations where electrostatic discharge control and particulate contamination limits constrain material selection and surface finish specifications.
- Packaging Solutions:Continuous-motion and intermittent-motion carriers for carton erecting, filling, and sealing lines where pneumatic clamping integration and rapid changeover between SKU formats drive specification.
- Aerospace Engineering:Specialized large-format carriers for airframe component transfer and tooling positioning, incorporating laser tracking compatibility and thermal compensation for hangar environment variability.
Automotive assembly generates the largest contract values; electronics manufacturing shows the steepest specification escalation.
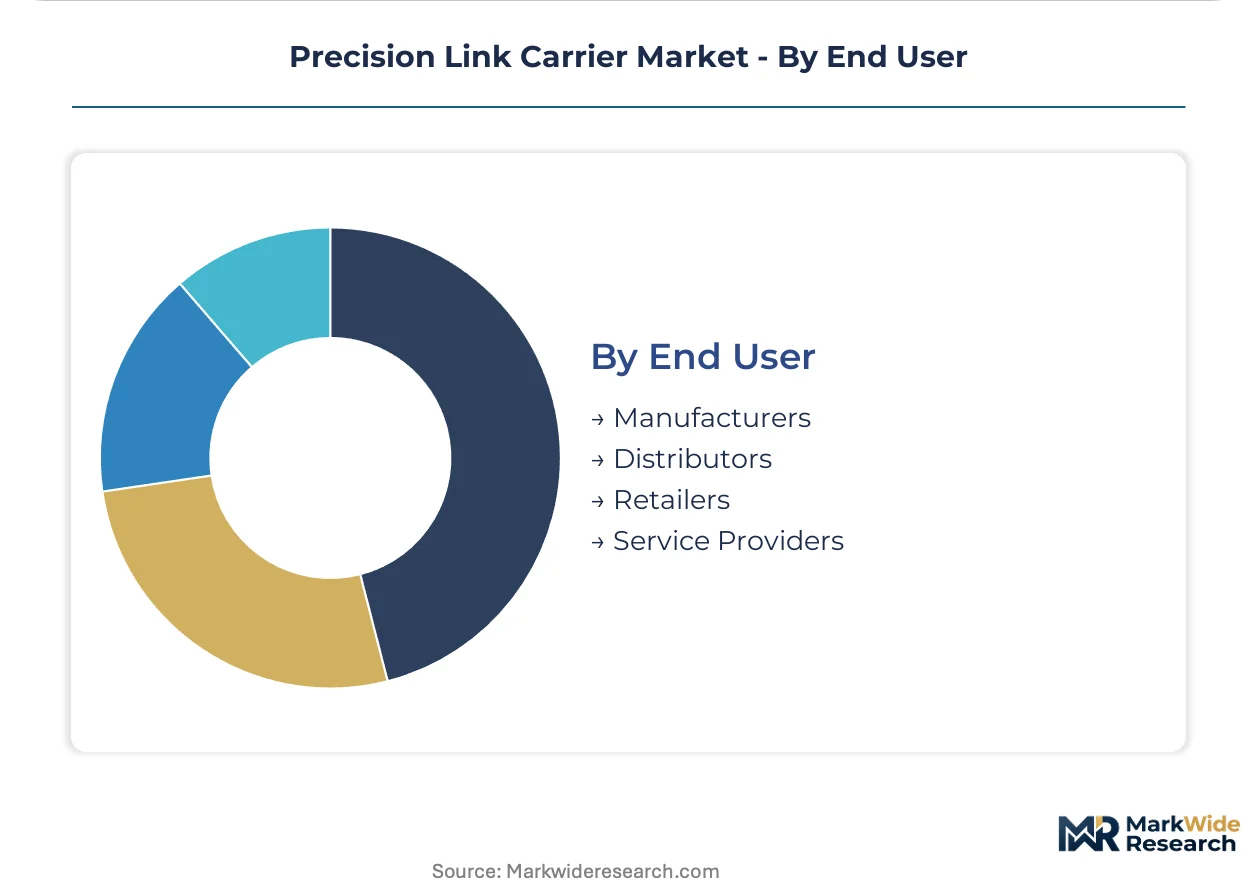
End User:
End user type determines procurement channel structure, with direct OEM relationships displacing traditional distributor networks in high-specification applications.
- Manufacturers:Tier-1 automotive suppliers and electronics contract manufacturers operating captive automation engineering teams that specify carriers directly and manage integration in-house. DESTACO and CDS are capturing expanded share through direct supply relationships with Volkswagen Group and Hyundai Motor.
- Distributors:Industrial automation distributors serving mid-market packaging and general manufacturing customers with catalog-configured standard carriers and application engineering support.
- Retailers:E-commerce fulfillment center operators deploying light-load carriers for sortation and order consolidation systems, typically procuring through systems integrators rather than direct carrier sourcing.
- Service Providers:Third-party maintenance and retrofit contractors specifying replacement carriers for legacy line upgrades, particularly active in Michigan and Stuttgart where internal combustion engine plants require battery module handling retrofits.
Manufacturers command the specification authority; service providers are expanding fastest as retrofit activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mechatronics engineers and Japanese precision machinists anchor the industry's technical workforce concentration, with specialized cam grinding expertise concentrating in Nagoya and Stuttgart industrial corridors.
Germany
Automotive OEMs in Wolfsburg and Stuttgart modernize conveyor systems for electric vehicle battery module assembly. EU Machinery Directive 2006/42/EC mandates redundant safety encoders for automated carrier zones, accelerating servo-encoded link deployments. The Baden-Württemberg precision engineering cluster hosts Tier-1 suppliers pre-certifying carrier modules to compress end-user compliance timelines.
United States
Michigan-based powertrain suppliers retrofit legacy internal combustion engine plants for cylindrical and prismatic cell handling. NHTSA traceability mandates for automotive component origin drive carrier serialization integration into steel forgings. The Detroit-Warren-Dearborn metropolitan area concentrates battery module assembly line overhauls for domestic EV manufacturing platforms.
Japan
Electronics contract manufacturers in Nagoya and Osaka demand substrate-specific pallet designs for semiconductor test-and-burn-in operations. METI industrial automation incentives support precision grinding capacity expansion for indexing cam production. The Chubu region maintains concentrated expertise in cam-driven timing mechanisms for high-repeatability assembly systems.
South Korea
Memory chip manufacturers in Suwon and Pyeongtaek commission customized carriers for wafer thinning trends toward 50-micron thicknesses. MFDS pharmaceutical regulations constrain material selection for cleanroom-compatible carrier segments. The Seoul Capital Area anchors high-throughput chip validation line expansion with electrostatic discharge protection requirements.
India
Domestic EV manufacturing incentives under the PLI scheme attract precision carrier vendors to establish local assembly operations. Maruti Suzuki and Tata Motors production lines in Haryana and Gujarat specify modular carrier systems accommodating multiple battery form factors. The Delhi-Mumbai Industrial Corridor concentrates automotive conveyor modernization investments.
Precision Link Carrier Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the precision link carrier supply base, creating a tiered structure where parent-company networks dominate high-volume automotive contracts. The vendor landscape fragments between steel-forging heavy-load specialists, aluminum extrusion standard carriers, and customized substrate-handling designers. Two strategic archetypes predominate: integrated automation conglomerates leveraging cross-divisional sales channels, and independent precision mechanics competing on application engineering depth. Competitive moves center on unbundling hardware supply from integration services, and pre-certifying modular components to accelerate EU Machinery Directive compliance.
Within the conglomerate tier, DESTACO anchors its position through Dover Corporation parent-network access to high-volume assembly cell procurement. CDS occupies a position among European fabricators serving packaging automation integrators with customized carrier configurations. Sankyo Automation exemplifies the precision mechanics archetype, representing Japanese cam-driven indexing expertise concentrated in electronics manufacturing applications.
| Leading Market Players |
|---|
| DESTACO (Dover Corporation) |
| CDS (Bettinelli) |
| ITALPLANT srl |
| Cyclo Index (Leggett & Platt) |
| Sankyo Automation |
| Motion Index Drives, Inc. |
| Stelron Components |
| Packam Controls |
| Alphabetech |
| Others |
Value Network & Pricing Analysis
LME aluminum benchmarks and manganese-boron steel pricing cascade through precision link carrier manufacturing, compressing margins for standard aluminum constructions while elevating cost premiums for safety-certified servo-encoded systems serving European automotive OEMs.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for high-load steel carriers, while aluminum standard carriers face persistent margin compression. Three-tier pricing structure across premium servo-encoded, standard cam-driven, and economy pneumatic systems differentiates on ISO 13849-1 certification grade and redundant encoder integration. Cost compression in aluminum standard tiers intensifies because LME volatility transfers directly to extrusion costs. Packaging automation integrators exhibit highest price sensitivity; automotive OEMs absorb premium pricing for safety-rated positioning verification.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Detroit anchor hub-and-spoke patterns for precision-ground cam components and hardened steel link assemblies. Manufacturing concentrates in Germany, Japan, and the United States for cam grinding expertise and advanced high-strength steel forging. Raw material flows draw from Swedish specialty steel mills, Chinese rare-earth magnet suppliers for servo motors, and German precision bearing manufacturers. Single-source vulnerability concentrates in Japanese cam grinding capacity for indexing mechanisms. Distribution runs through Tier-1 automotive supplier networks and packaging automation integrators rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precision link carrier market compounds steadily as electric vehicle platform standardization forces recurring retrofit cycles across legacy internal combustion engine plants.
For Market Incumbents: Anchor market position through captive precision grinding capacity in Stuttgart or Nagoya industrial corridors, insulating against cam manufacturing concentration risk. Pre-certify modular carrier modules to EU Machinery Directive amendments, accelerating compliance timelines for Volkswagen Group and Hyundai Motor procurement teams. Backward integration into hardened steel forging secures margin control against specialty alloy price volatility. For New Entrants and Emerging Players: Servo-pneumatic hybrid architectures offer a technology-first wedge into pharmaceutical packaging applications requiring explosive atmosphere certification. White-space targets concentrate in India's PLI scheme automotive corridors and legacy powertrain retrofit contracts in Michigan. Penetration runs fastest through battery module handling retrofits for cylindrical and prismatic cell formats. Go-to-market positioning emphasizes mechatronics technician training partnerships to overcome commissioning expertise scarcity. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cam-driven indexing mechanics possessing embedded relationships with Taiwanese semiconductor test-and-burn-in manufacturers. Long-term viability frames around sustained EV platform churn and recurring safety standard upgrades. Acquisition targets center on German Tier-1 suppliers pre-certifying carrier modules to EU Machinery Directive requirements. Watch NHTSA traceability mandate implementation timelines as inflection indicator for carrier serialization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Forging | Captures margin from Swedish manganese-boron suppliers serving Stuttgart automotive OEMs. |
| Servo-Pneumatic Hybrid Architecture Development | Opens MFDS-regulated pharmaceutical packaging corridors in Seoul Capital Area. |
| Pre-Certification to EU Machinery Directive Amendments | Compresses compliance timelines for Baden-Württemberg Tier-1 supplier procurement. |
| Mechatronics Technician Training Partnerships | Addresses commissioning bottleneck delaying automotive line reconfiguration projects. |
| Carrier Serialization Integration | Satisfies NHTSA traceability mandates for battery module origin tracking in Michigan plants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with automotive OEM procurement directors, Tier-1 supplier automation engineers, packaging integrator technical leads, and precision mechanics R&D heads with secondary validation. Sources included SEC filings from Dover Corporation and Leggett & Platt, EU Machinery Directive amendment texts, METI industrial automation incentive disclosures, and IHS Markit vehicle production databases. Bottom-up carrier shipment estimates triangulated against top-down automotive capital expenditure allocations.
Segment-weighting applied product type, material specification, application intensity, and end-user procurement channel dimensions across the modeling period. CAGRs derived from regression against automotive EV platform rollout schedules and semiconductor capital expenditure cycles. Industry-specific inputs incorporated EU Machinery Directive compliance cost trajectories and NHTSA traceability mandate implementation phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to linear motor substitution rates in cleanroom electronics and aluminum price volatility transmission. Outputs reflect documented assumptions around regulatory implementation timelines and technology substitution curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
AMD Motherboards Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Ram BOP Market