
 Global Bipolar Small Signal Transistor Market | 2026-2036
Global Bipolar Small Signal Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bipolar Small Signal Transistor Market Foresight
REACH compliance is realigning the cost-of-entry calculus for European-sourced substrates and packaging materials. STMicroelectronics leverages its vertically integrated French-Italian manufacturing footprint to sustain qualification advantages under ECHA substance restrictions. ON Semiconductor anchors its competitive position through captive silicon foundries in the Czech Republic and Malaysia. NXP Semiconductors N.V. differentiates via AEC-Q100 automotive-grade certifications that command premium positioning in vehicle electronics.
Bipolar small signal transistors are three-terminal semiconductor devices constructed from doped silicon or silicon-germanium epitaxial layers, operating with current gains (hFE) typically ranging from 100 to 800 for linear amplification and fast switching below 1 MHz. These devices serve as fundamental building blocks in analog signal conditioning, voltage regulation, and low-frequency RF circuits across industrial and consumer systems. NPN transistors occupy the dominant volume position due to superior electron mobility and broader foundry process compatibility, while Darlington configurations capture specialized margin pools in high-gain instrumentation and medical sensor front-ends. SOT-23 surface-mount packages are displacing legacy TO-92 through-hole formats in telecommunication and portable electronics, driven by miniaturization mandates and automated assembly economics.
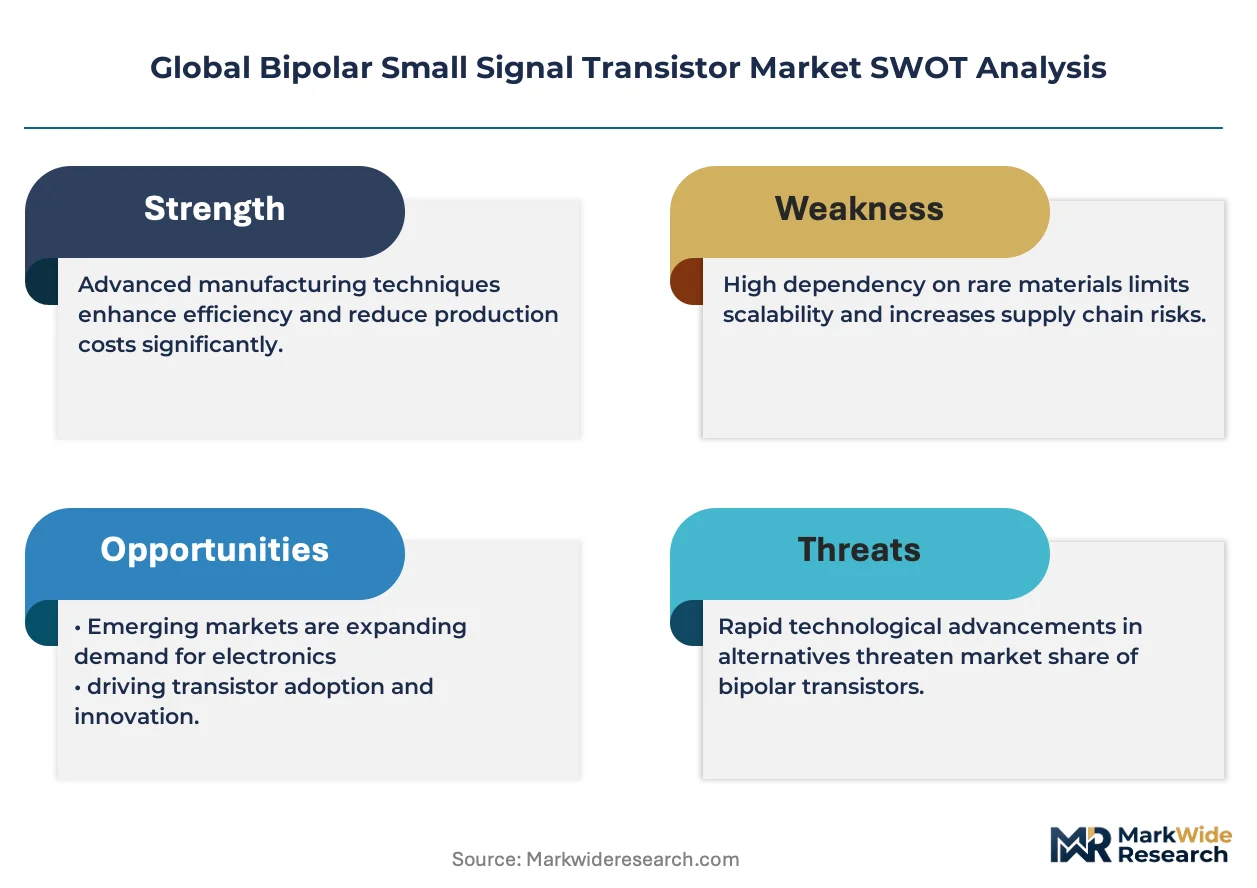
FDA device regulations for patient-connected electronics, EU RoHS substance restrictions on lead-bearing solders, and China's GB standards for domestic semiconductor procurement collectively shape product qualification requirements and market access conditions across major demand centers. Japan's METI energy-efficiency directives for industrial equipment are tightening standby-power limits, forcing redesigns of control circuitry where small-signal transistors serve as gate drivers and feedback elements. Stakeholders must monitor divergence between regional substance regulations and packaging form-factor standards when allocating R&D resources across qualification programs.
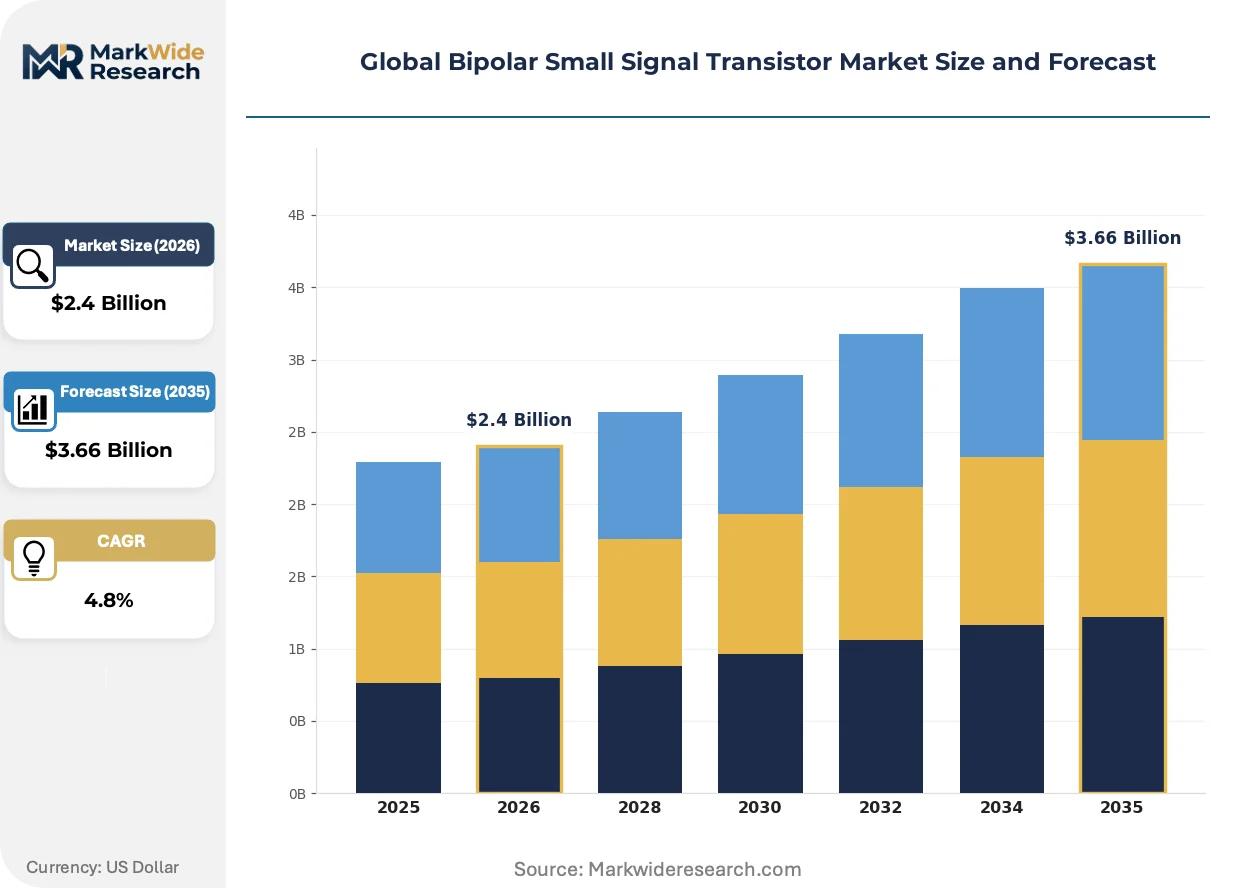
Market Dynamics
Automotive electrification is forcing a wholesale recalibration of small-signal transistor specifications, as 48V mild-hybrid architectures and battery management systems demand higher-temperature operation and tighter parametric matching than legacy consumer-grade devices ever required.
Growth Catalysts
- AEC-Q100 Automotive Certification:Vehicle electronics suppliers are mandating grade-zero and grade-one qualified devices for powertrain and ADAS modules, creating dedicated demand pools that standard industrial transistors cannot serve.
- EU F-Gas Regulation:Semiconductor fabrication equipment upgrades to reduce fluorinated gas emissions are accelerating process modernization at European foundries, expanding capacity for precision bipolar devices.
- Industrial Sensor Networks:Factory automation deployments across Germany, Japan, and South Korea are consuming millions of units annually for 4-20mA loop interfaces and temperature transmitter front-ends.
Market Restraints
- Epitaxial Wafer Supply Concentration:Six-inch silicon epitaxy for bipolar processes concentrates in Japanese and German merchant suppliers, creating input bottlenecks during demand spikes.
- Gallium Nitride Substitution:GaN FETs are capturing switching applications above 100 kHz where small-signal bipolar transistors previously served, compressing addressable frequency range.
- REACH Substance Restrictions:ECHA candidate list expansions for lead and cadmium compounds are complicating plating chemistry choices for TO-92 and SOT-23 package terminations.
Strategic Opportunities
- Medical Wearables:Ultra-low-noise bipolar front-ends for ECG and glucose monitoring patches represent an underpenetrated application segment with premium pricing power.
- India PLI Scheme:Domestic electronics manufacturing incentives are attracting component suppliers to establish local SMD packaging operations for consumer and telecom demand.
- SiGe HBT Convergence:Silicon-germanium heterojunction technology is merging with standard bipolar processes to deliver GHz-range performance for 5G small-cell RF chains.
Industry Challenges
- Parametric Test Engineering Talent:Automated wafer probing for hFE matching and noise figure characterization requires specialized skills that fabs struggle to recruit outside Taiwan and the US.
- Dual Sourcing Qualification Timelines:Automotive Tier-1s demand 18-month second-source validation cycles that strain development bandwidth and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bipolar Small Signal Transistor Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NPN Transistor, PNP Transistor, Darlington Transistor, Phototransistor, Others Application: Amplifiers, Oscillators, Switching Circuits, Modulators, Signal Processing, Communication Devices End User: Consumer Electronics Manufacturers, Telecommunication Firms, Aerospace Equipment Makers, Industrial Automation Suppliers, Defense Contractors Packaging Type: TO-92, SOT-23, SOIC, DIP, SOT-223 |
| Companies Covered | Microchip Technology Inc, Toshiba Electronic Devices & Storage Corporation, STMicroelectronics, ON Semiconductor Corporation, NXP Semiconductors N.V., Renesas Electronics Corporation, Nexperia B.V, Vishay Intertechnology, Inc., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bipolar Small Signal Transistor Market Shifts & Advancements
Process-node migration and packaging miniaturization are converging to redefine performance benchmarks, while regulatory pressure on manufacturing emissions is filtering down to component-level specifications.
Silicon-germanium epitaxial deposition is expanding into standard bipolar foundry flows, delivering transit frequencies above 30 GHz for millimeter-wave radar and 5G infrastructure. RF module manufacturers in South Korea and Finland are adopting these devices for beamforming front-ends. The technology is expanding into cost-sensitive automotive radar segments previously served by gallium arsenide.
REACH authorization requirements for lead stabilizers in PVC cable compounds are indirectly constraining equipment wire harness specifications, forcing transistor manufacturers to document full material declarations for automotive customers. ECHA's sunset date enforcement is compressing supplier qualification windows. German OEMs are responding by mandating IECQ QC 080000 hazardous substance process management certifications across their component base.
Contract manufacturers in Vietnam and Mexico are consolidating component purchasing through authorized distributor alliances rather than direct Asian trading houses, tightening traceability and reducing gray-market exposure. EMS providers serving US medical device OEMs are driving this shift to satisfy FDA unique device identifier requirements. The behavioral change is most visible in diabetes monitoring equipment supply chains where lot-level genealogy is mandatory.
Global Bipolar Small Signal Transistor Market Segmentation
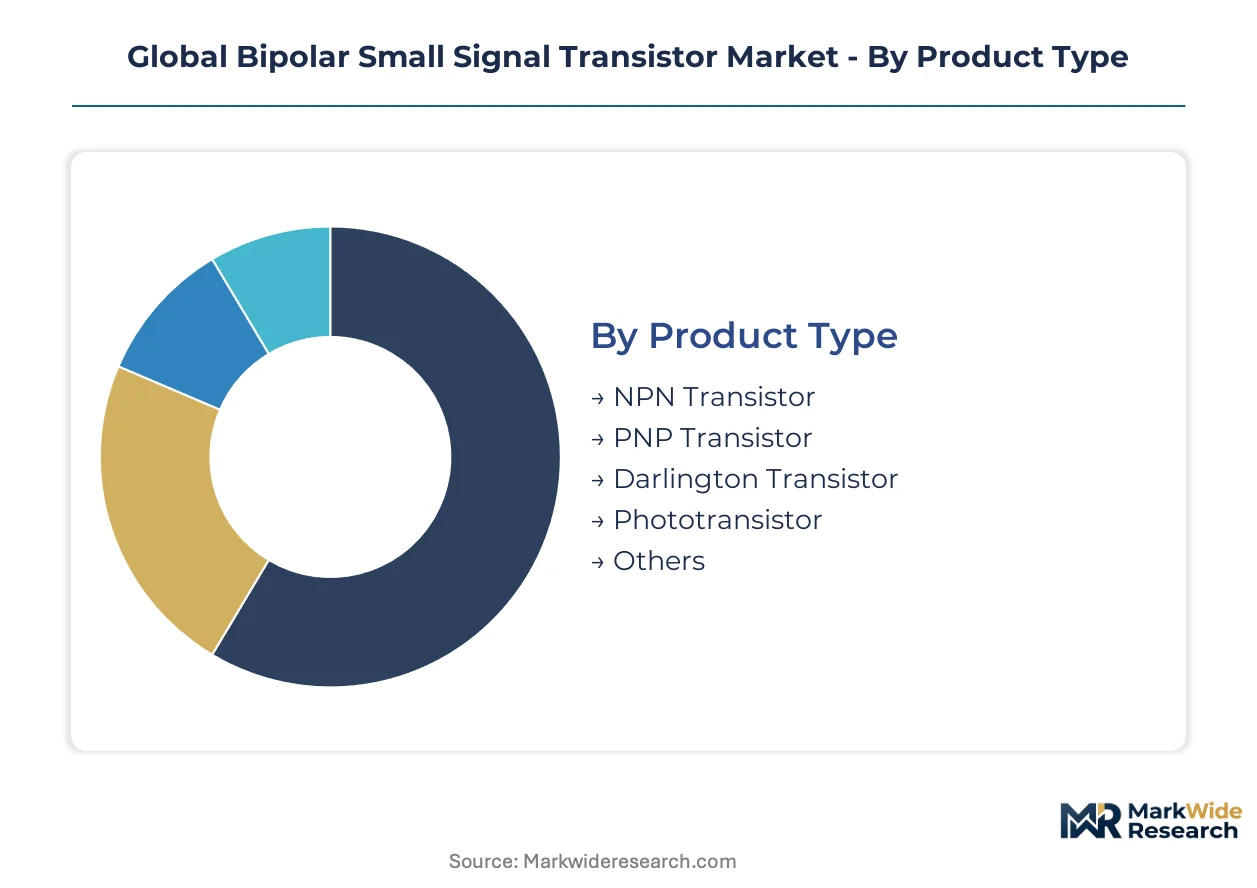
Segmentation in the bipolar small signal transistor market reveals how device physics, assembly economics, and customer qualification requirements stratify procurement patterns. Suppliers configure product portfolios around these dimensions to defend margin pools and manage capacity allocation.
Product Type:
Process tooling and epitaxial wafer sourcing concentrate disproportionately around NPN architectures, creating supply-side lock-in that shapes competitive dynamics across this category.
- NPN Transistor:Electron mobility superiority enables higher switching speeds and superior current gain linearity across temperature ranges. Demand concentrates in automotive sensor interfaces and industrial motor drives, where AEC-Q100 qualification requirements filter out marginal suppliers.
- Darlington Transistor:Cascaded dual-transistor construction delivers composite current gains exceeding 1000 from compact footprints. Medical instrumentation and precision weighing systems in Germany and Japan absorb volume, driven by noise-sensitive front-end requirements.
- PNP Transistor:Hole mobility constraints limit frequency response but enable complementary symmetry in audio amplifiers and push-pull output stages.
- Phototransistor:Light-sensitive base regions convert optical signals to current without discrete photodiode-amplifier pairs.
- Others:Specialized configurations including Sziklai pairs and avalanche-rated devices serve niche protection and high-voltage triggering applications.
NPN devices absorb the bulk of installed capacity; Darlington configurations are expanding most quickly.
Application:
Customer qualification intensity varies dramatically across applications, with automotive and medical segments demanding documentation burdens that consumer-grade suppliers cannot shoulder.
- Amplifiers:Small-signal voltage gain stages in audio preamplifiers and sensor conditioning circuits require tight hFE matching and low 1/f noise characteristics. Industrial process control deployments across South Korea and Finland drive procurement, constrained by METI energy-efficiency standby power limits.
- Switching Circuits:Saturated operation for logic level translation and load control prioritizes storage time minimization over linearity. Battery management systems in 48V mild-hybrid vehicles are recalibrating temperature and parametric specifications beyond legacy consumer-grade tolerances.
- Oscillators:Feedback loop stability depends on predictable gain-bandwidth product and temperature coefficients.
- Modulators:Amplitude and frequency modulation stages in RF equipment leverage transistor nonlinearity under controlled bias conditions.
- Signal Processing:Active filter implementations and analog computation elements require matched transistor pairs.
- Communication Devices:Low-frequency RF front-ends and baseband processing in legacy infrastructure equipment.
Amplifier applications command the deepest qualification backlogs; switching circuits are climbing the fastest as electrification multiplies gate driver and protection circuit counts.
End User:
Procurement authority and volume concentration diverge sharply between fragmented consumer electronics and concentrated defense contracting channels.
- Industrial Automation Suppliers:Factory equipment builders in Germany, Japan, and South Korea consume millions of units annually for 4-20mA loop interfaces and temperature transmitter signal conditioning. REACH substance restrictions on lead-bearing solders complicate TO-92 termination plating choices.
- Consumer Electronics Manufacturers:Portable device assemblers in China drive SOT-23 volume through miniaturization mandates and automated placement economics.
- Telecommunication Firms:Base station and network equipment builders source qualified devices for power supply regulation and protection circuits.
- Aerospace Equipment Makers:Satellite and avionics systems demand radiation-tolerant variants with extended temperature ranges.
- Defense Contractors:Domestic sourcing requirements and ITAR export controls constrain supplier eligibility.
Industrial automation absorbs the bulk of installed capacity; medical wearable integration is gaining share fastest.
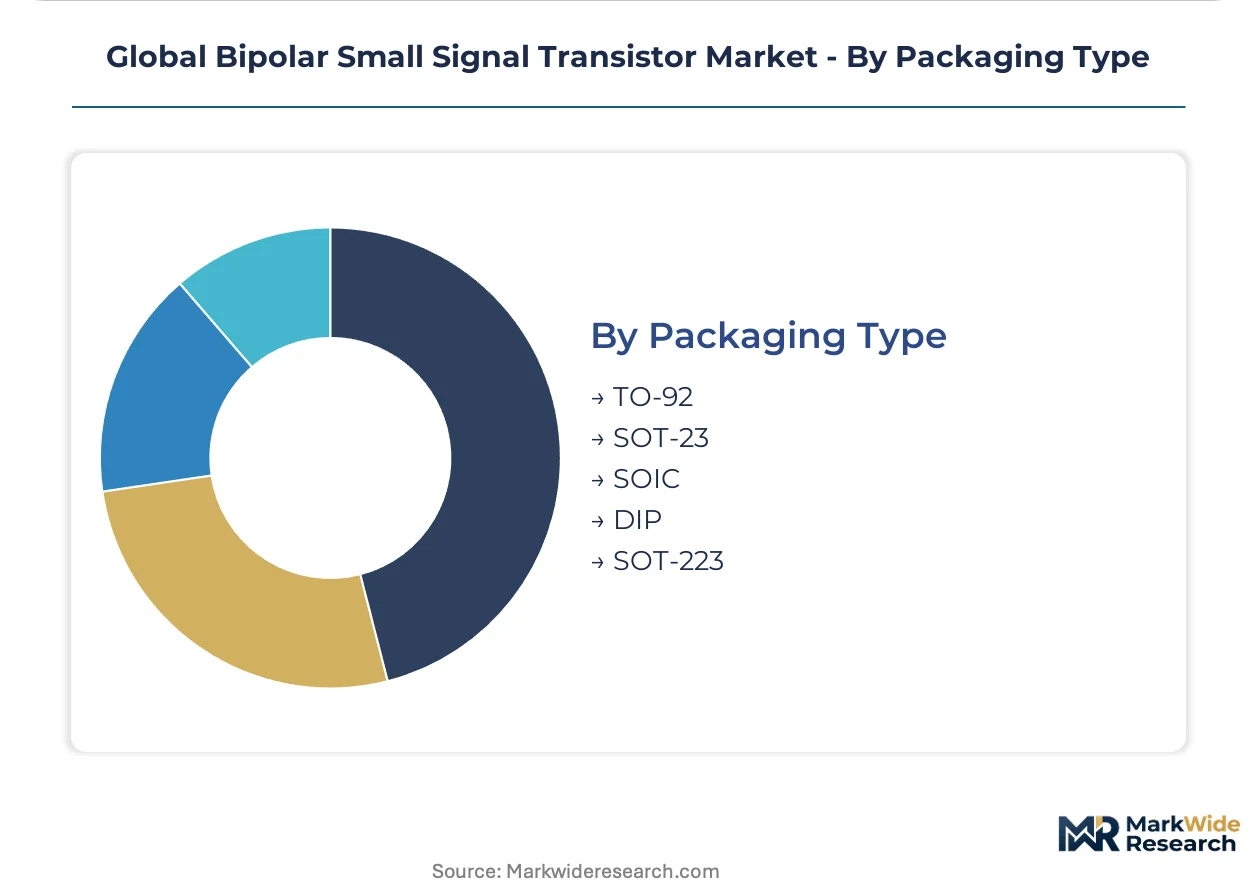
Packaging Type:
Assembly equipment depreciation schedules and board density requirements are displacing legacy through-hole formats despite continued demand in repair and industrial retrofit channels.
- SOT-23:Three-lead surface-mount plastic package dominates portable electronics and telecommunications equipment. Vietnam and Mexico contract manufacturers are consolidating purchasing through authorized distributor alliances to satisfy FDA unique device identifier requirements.
- TO-92:Through-hole epoxy package persists in industrial equipment and educational markets where hand soldering remains economical.
- SOIC:Small-outline integrated circuit housing accommodates matched transistor pairs and array configurations.
- DIP:Dual in-line package serves prototyping, legacy equipment replacement, and high-reliability socketed applications.
- SOT-223:Medium-power surface-mount variant with improved thermal dissipation for linear regulators and small power stages.
SOT-23 absorbs the bulk of installed capacity; SOT-223 is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate bipolar transistor fabrication capacity through tax incentives for semiconductor equipment imports. Domestic foundries in Shanghai and Wuxi scale production lines for industrial-grade NPN devices. The MIIT dual carbon goals pressure fabs to upgrade epitaxial reactor efficiency.
China
Domestic foundries in Shanghai and Wuxi absorb the bulk of regional NPN transistor capacity for industrial motor drives and sensor interfaces. The MIIT dual carbon goals mandate fab energy-efficiency upgrades by 2025. Suzhou packaging houses convert legacy TO-92 lines to SOT-23 surface-mount formats for telecom export orders.
Germany
Automotive Tier-1s in Stuttgart and Munich mandate AEC-Q100 grade-zero devices for 48V mild-hybrid powertrain modules. The KBA enforces extended producer responsibility for semiconductor-containing vehicle electronics. Dresden's silicon foundry cluster expands six-inch epitaxial wafer supply for precision bipolar processes.
United States
Defense contractors in Arizona and Texas consume radiation-tolerant variants for satellite avionics under ITAR sourcing constraints. The FDA unique device identifier rules push medical OEMs toward authorized distributor channels. Silicon Valley RF module designers adopt SiGe HBT transistors for 5G small-cell beamforming chains.
Japan
Factory automation builders in Nagoya and Osaka procure millions of units annually for 4-20mA loop interfaces and temperature transmitters. METI energy-efficiency directives tighten standby-power limits for industrial control circuitry. Tokyo-based merchant suppliers concentrate six-inch silicon epitaxy capacity for bipolar process inputs.
South Korea
RF equipment manufacturers in Seoul and Suwon integrate SiGe HBT devices for millimeter-wave radar and 5G infrastructure front-ends. The MFDS medical device regulations align with FDA traceability standards for patient-connected electronics. Busan packaging subcontractors qualify SOT-223 formats for automotive thermal dissipation requirements.
Global Bipolar Small Signal Transistor Market Competitive Landscape
European producers anchor one tier through vertically integrated French-Italian and Czech manufacturing footprints; Japanese and South Korean specialists hold process technology advantages in epitaxial deposition and RF performance. The vendor base stratifies between automotive-qualified volume suppliers and industrial-grade commodity producers. Three archetypes dominate: AEC-Q100 certified automotive specialists, SiGe HBT RF performance leaders, and cost-optimized consumer-grade fabricators. Competitive moves concentrate on captive silicon foundry expansion and second-source qualification partnerships with Tier-1 automotive electronics suppliers.
Within the automotive-certified tier, STMicroelectronics and ON Semiconductor exemplify vertically integrated European positioning through captive French-Italian and Czech-Malaysian fabrication assets. NXP Semiconductors N.V. occupies the premium-tier vector through AEC-Q100 qualification depth that commands positioning in vehicle electronics procurement. These three anchors represent the structural split between integrated device manufacturers with in-house epitaxial capacity and fabless specialists dependent on merchant wafer supply.
| Leading Market Players |
|---|
| Microchip Technology Inc |
| Toshiba Electronic Devices & Storage Corporation |
| STMicroelectronics |
| ON Semiconductor Corporation |
| NXP Semiconductors N.V. |
| Renesas Electronics Corporation |
| Nexperia B.V |
| Vishay Intertechnology, Inc. |
| Infineon Technologies AG |
| Others |
Supply & Pricing Matrix
Silicon epitaxial wafer spot indices cascade through bipolar transistor supply chains into three distinct procurement tiers, with AEC-Q100 automotive-grade devices commanding substantial premiums over industrial commodity units as Japanese and German merchant suppliers tighten six-inch wafer allocation.
Pricing Analysis
Lead-time compression premiums dominate transactional pricing, with automotive Tier-1s paying substantial markups for grade-zero devices delivered under eighteen-week cycles while spot inventory in SOT-23 packages trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 qualified automotive units from industrial-grade NPN transistors and unscreened consumer commodity devices. Pricing pressure stems from gallium nitride substitution above 100 kHz, compressing addressable frequency ranges for legacy bipolar switches. Consumer electronics manufacturers exhibit highest price sensitivity, while medical instrumentation buyers prioritize noise figure specifications over unit cost.
Supply Chain Analysis
Certification gating through AEC-Q100 and IECQ QC 080000 hazardous substance management restricts qualified supplier pools to vertically integrated European and Japanese producers with captive epitaxial capacity. Manufacturing concentrates in China, Germany, and Japan, with six-inch silicon epitaxy drawing from Tokyo-based merchant suppliers and Dresden foundry clusters. Raw material dependencies span high-purity silicon feedstock, boron and phosphorus dopants, and lead-free plating chemistry for RoHS-compliant terminations. Single-source vulnerability concentrates in Japanese epitaxial wafer supply during demand spikes. Distribution runs through authorized distributor alliances rather than direct Asian trading houses, tightening traceability for FDA unique device identifier compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH substance restrictions and AEC-Q100 qualification burdens force marginal commodity suppliers toward exit or acquisition.
For Market Incumbents: To counter gallium nitride substitution in switching applications above 100 kHz, incumbents should deepen SiGe HBT integration for millimeter-wave radar and 5G infrastructure while expanding captive six-inch epitaxial capacity in French-Italian manufacturing corridors. Second-source qualification partnerships with automotive Tier-1s lock in eighteen-month validation cycles that strain competitor development bandwidth.
For New Entrants and Emerging Players: SiGe heterojunction bipolar technology offers a technology-first wedge into cost-sensitive automotive radar segments previously served by gallium arsenide, bypassing entrenched NPN commodity competition. Medical wearables for ECG and glucose monitoring patches present the most penetrable white-space target, with premium pricing power and less stringent AEC-Q100 barriers. Go-to-market execution should prioritize IECQ QC 080000 certification to satisfy German OEM material declaration mandates.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated European specialists with captive Czech or Malaysian fabrication assets and existing AEC-Q100 qualification depth. Long-term viability over the next decade hinges on automotive electrification sustaining 48V mild-hybrid transistor counts despite silicon carbide and gallium nitride encroachment. The signal to monitor is Japanese epitaxial wafer allocation discipline during industrial automation demand spikes, which would indicate pricing power inflection for qualified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade-Zero Qualification | Unlocks procurement access to Stuttgart and Munich automotive Tier-1 powertrain modules. |
| SiGe HBT Process Migration | Delivers 30 GHz transit frequencies for South Korean 5G small-cell beamforming front-ends. |
| Captive Epitaxial Capacity Expansion | Reduces dependency on Tokyo-based merchant wafer suppliers during demand spikes. |
| Authorized Distributor Alliance | Satisfies FDA unique device identifier requirements for diabetes monitoring equipment supply chains. |
| REACH-Compliant Plating Conversion | Anticipates ECHA sunset date enforcement for lead stabilizers in TO-92 and SOT-23 terminations. |
Research Methodology
Document review covered semiconductor equipment import records, ECHA substance restriction filings, and AEC-Q100 qualification databases, complemented by interviews with bipolar process engineers at European IDMs, procurement directors at German automotive Tier-1s, and distribution channel managers serving US medical device OEMs. Secondary validation drew from customs trade data, SEC semiconductor segment disclosures, and METI industrial equipment energy-efficiency filings. Bottom-up unit demand estimates for 4-20mA loop interfaces and temperature transmitters were cross-referenced against top-down fab capacity utilization figures from Shanghai and Wuxi foundry zones.
Historical shipment trajectories for NPN, PNP, and Darlington configurations were cross-referenced against panel input from epitaxial wafer suppliers and SOT-23 packaging subcontractors in Vietnam and Mexico. The analytical framework models volume and value across product type, application, end user, and packaging format dimensions throughout the forecast period. CAGRs were derived from regression analysis of qualification backlog durations and automotive electrification content-per-vehicle trends. Industry-specific inputs include METI standby-power limit compliance costs and India PLI scheme packaging subsidy eligibility.
Several conditions sit outside the modeled scope, including unforeseen gallium nitride cost-parity breakthroughs, abrupt ECHA candidate list expansions, and geopolitical disruptions to six-inch silicon epitaxy trade flows. Forecasts reflect documented assumptions regarding AEC-Q100 adoption curves and industrial automation deployment rates. A model refresh is warranted upon material change in Japanese merchant wafer pricing or EU F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market