
 5G Modems Market | 2026-2036
5G Modems Market Size, Share, and Industry Trends Forecast 2026-2036
5G Modems Market Analysis
RF engineering talent scarcity is redrawing competitive boundaries across the 5G modems landscape. Qualcomm leverages its decades-long baseband architecture leadership to dominate premium smartphone sockets. MediaTek sustains aggressive sub-6 GHz portfolio expansion across mid-tier consumer electronics. Samsung anchors captive modem supply for its Galaxy device ecosystem while competing for external automotive design wins.
A 5G modem is a baseband processor with integrated RF transceiver circuitry that converts digital data into radio signals compliant with 3GPP Release 15 and subsequent standards, operating across sub-6 GHz and millimeter wave spectrum bands to enable cellular connectivity. The device manages modulation, encoding, and beamforming protocols to deliver throughput exceeding 1 Gbps in commercial deployments. Integrated modems command the deepest margin pools as smartphone OEMs prioritize board-space efficiency and thermal consolidation. Sub-6 GHz technology leads volume shipment today, though millimeter wave modules are capturing design wins where dense urban capacity demands justify higher bill-of-materials costs. Automotive end-user applications represent the fastest structural expansion as telematics control units and V2X communication stacks become standard equipment.
The Federal Communications Commission governs spectrum allocation and device certification in the United States, directly shaping modem frequency support requirements and market access timelines. The European Telecommunications Standards Institute coordinates 5G NR conformance benchmarks that modems must satisfy for CE marking and operator acceptance across EU member states. China's Ministry of Industry and Information Technology enforces domestic encryption and network access standards that foreign modem vendors must navigate for commercial deployment. Stakeholders must monitor spectrum reallocation proceedings and open-RAN interoperability mandates as these will determine which modem architectures retain strategic relevance.
Market Dynamics
Automotive OEMs are forcing embedded modem integration timelines forward as connected vehicle mandates in the European Union and China harden into enforceable compliance deadlines. This demand surge is compressing supplier qualification windows and redrawing procurement power structures.
Growth Catalysts
- EU Cybersecurity Regulation:UN R155 mandates for software-defined vehicles require certified cellular connectivity modules, embedding modems into vehicle type-approval pathways.
- Industrial automation:Smart factory retrofits across China's Guangdong and Jiangsu provinces require OEM-integrated sub-6 GHz modules for machine-to-machine coordination.
- India's PLI scheme:Production-linked incentives for telecom equipment manufacturing are concentrating local sourcing decisions for sub-6 GHz deployments.
Market Restraints
- RF front-end concentration:Advanced filter and amplifier supply concentrates among a handful of compound semiconductor foundries, creating single-source vulnerability.
- Millimeter wave cost structure:Beamforming antenna arrays and thermal management subsystems inflate bill-of-materials costs beyond mass-market smartphone tolerance.
- MIIT encryption standards:China's domestic network access certification requires foreign modem vendors to navigate protracted compliance timelines.
Strategic Opportunities
- Fixed wireless access:Broadband substitution in suburban and rural India is creating a new equipment category for CPE-embedded modems.
- Open RAN interoperability:O-RAN Alliance specifications are opening socket opportunities for non-integrated baseband-RF suppliers in disaggregated network builds.
- Edge AI convergence:On-device inference workloads are driving demand for modems with integrated neural processing units in industrial gateways.
Industry Challenges
- RF systems engineering scarcity:Baseband-PHY co-design expertise pools concentrate within a narrow demographic of experienced architects.
- 3GPP release fragmentation:Concurrent support for Release 15, 16, and 17 feature sets complicates firmware validation matrices.
- Automotive qualification cycles:AEC-Q100 stress testing and ASPICE process audits extend time-to-revenue for new modem variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Modems Market |
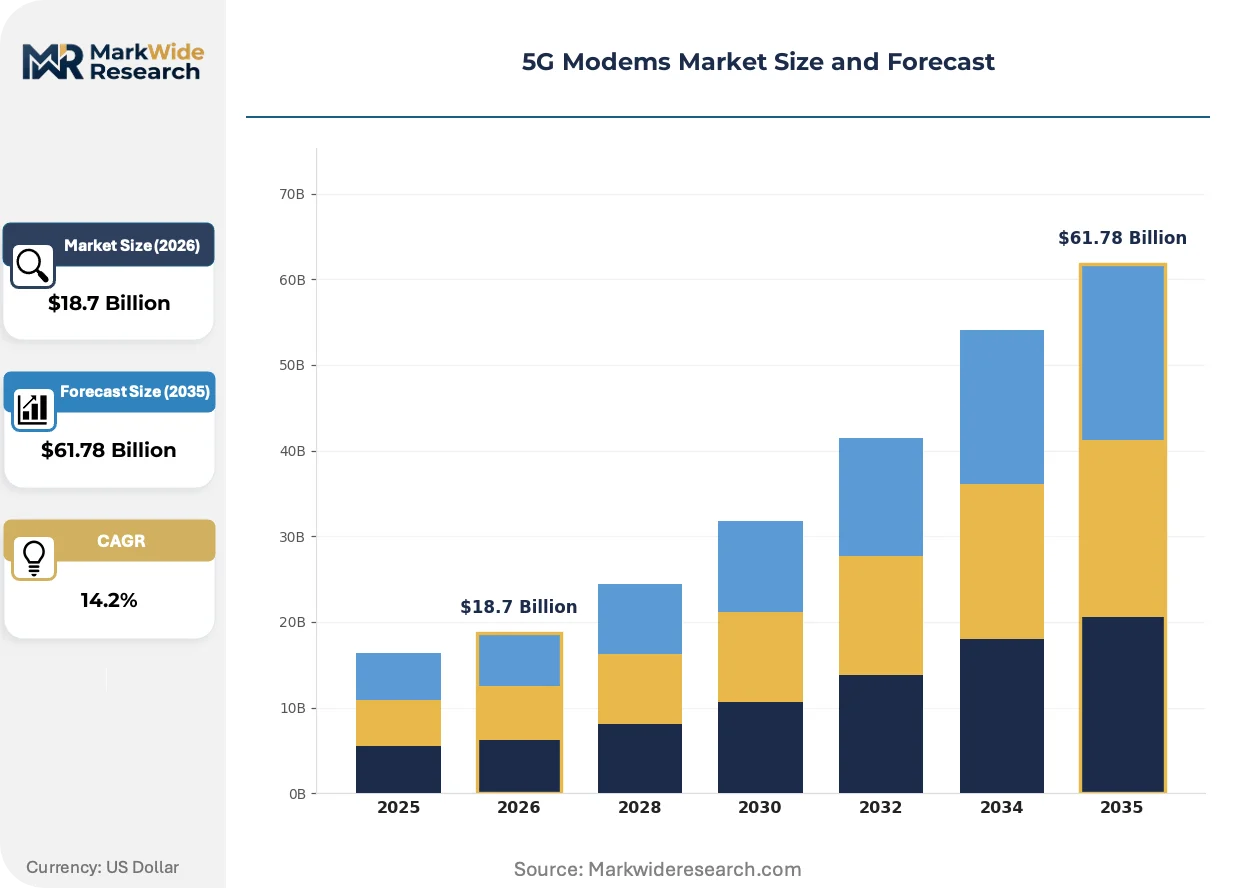
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Modems, Outdoor Modems, USB Modems, Integrated Modems Technology: Millimeter Wave, Sub-6 GHz, New Radio, Beamforming End User: Telecommunications, Automotive, Consumer Electronics, Industrial Automation Form Factor: Portable, Fixed, OEM Modules, Router Devices |
| Companies Covered | Intel, NXP Semiconductors, Qualcomm, Qorvo, Marvell, MediaTek, UNISOC, Huawei, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Modems Market Emerging Trajectories
Modem architecture is bifurcating between extreme integration for handheld devices and modular disaggregation for infrastructure and automotive platforms. This divergence is forcing vendors to maintain parallel development tracks with incompatible resource requirements.
System-in-package technology is miniaturizing millimeter wave RF front ends by stacking antenna-in-module components atop baseband die. Smartphone OEMs are absorbing these compact solutions to preserve board space for larger battery cells. The resulting footprint compression is enabling slimmer flagship designs without sacrificing cellular band coverage.
ETSI's 5G NR conformance benchmarks are tightening emission mask requirements for CE marking across EU member states. Modem vendors must recalibrate power amplifier linearization algorithms to satisfy revised spurious emission limits. Automotive TCU suppliers face the steepest recertification burden as vehicle-mounted antennas amplify regulatory scrutiny.
Automotive procurement is consolidating around long-term supply agreements with penalty clauses for qualification delays. Tier-1 telematics suppliers are displacing spot-market component purchases with multi-year modem supply contracts. German and Japanese OEMs are pioneering this contractual rigor to secure silicon allocation against consumer electronics demand surges.
5G Modems Market Segmentation
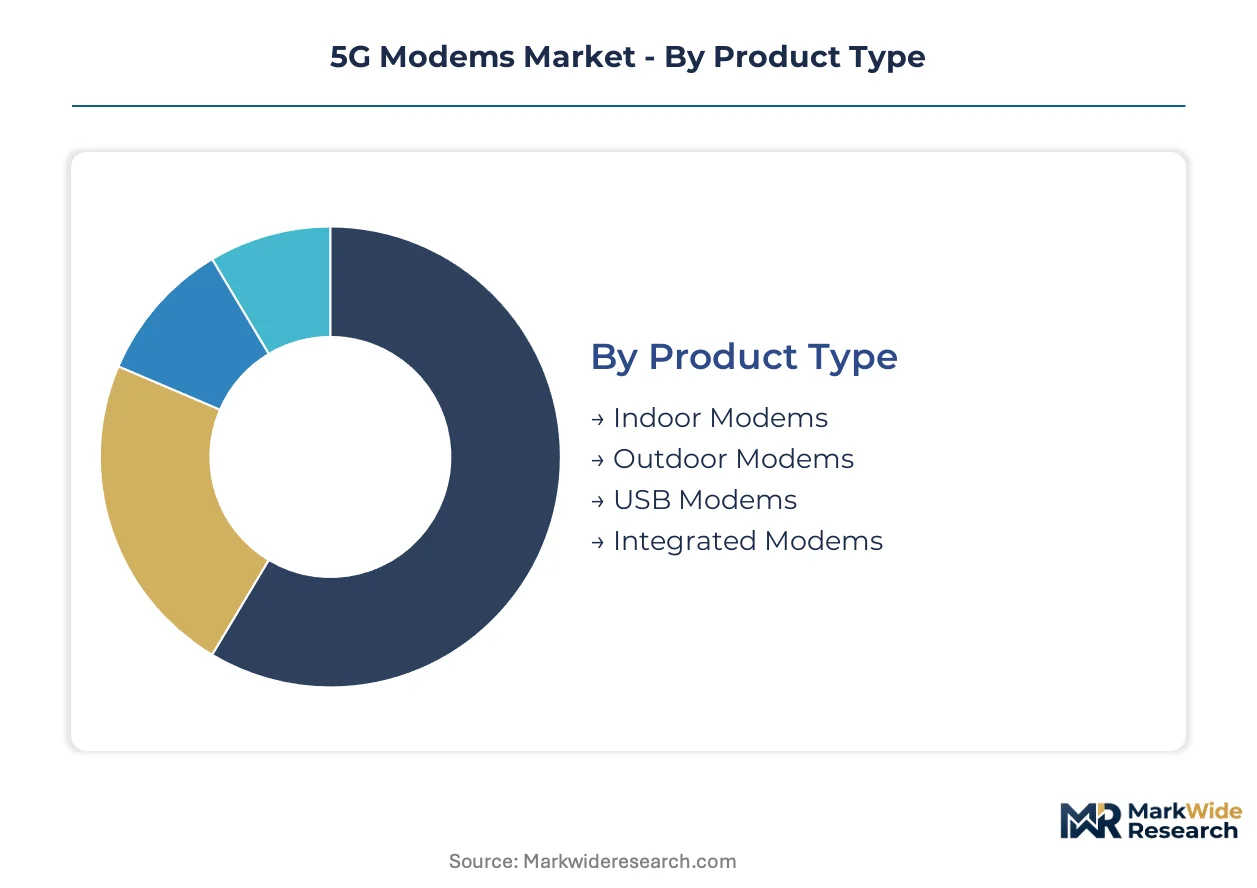
Segmentation in 5G modems reveals how architectural choices cascade through pricing, qualification timelines, and customer procurement power. Each dimension—product type, technology, end user, and form factor—carries distinct margin structures and competitive barriers that reshape vendor positioning.
Product Type:
Integrated modems command the deepest margin pools as smartphone OEMs prioritize board-space efficiency and thermal consolidation over discrete component savings.
- Integrated Modems:Baseband-RF system-on-chip designs stack transceiver, power management, and memory controllers onto single die. Demand concentrates in flagship smartphone sockets where Apple and Samsung negotiate multi-year allocation agreements.
- Outdoor Modems:Weather-sealed enclosures with active thermal management for pole-mounted and rooftop fixed wireless access deployments. Procurement in India's suburban broadband expansion is accelerating as Jio and Airtel densify coverage.
- Indoor Modems:Self-install CPE units for residential fixed wireless access.
- USB Modems:Plug-and-play connectivity dongles for laptop and industrial gateway retrofit.
The dominant share belongs to Integrated Modems, while Outdoor Modems is closing the gap fastest.
Technology:
Sub-6 GHz deployments absorb the highest absolute silicon volume, though millimeter wave modules capture premium pricing where dense urban capacity justifies elevated bill-of-materials costs.
- Sub-6 GHz:Operates below 6 GHz across licensed mid-band spectrum with superior propagation characteristics for wide-area coverage. China's industrial automation corridor in Guangdong and Jiangsu provinces is driving OEM module integration for machine-to-machine coordination.
- Millimeter Wave:Exploits 24-100 GHz spectrum with massive bandwidth availability but limited range requiring beamforming antenna arrays. Urban densification in Seoul, Tokyo, and New York City is sustaining design wins despite thermal and cost constraints.
- New Radio:3GPP Release 15 and subsequent standards-compliant air interface.
- Beamforming:Phased-array antenna techniques for directional signal enhancement.
Sub-6 GHz holds the volume lead, while Millimeter Wave is expanding most quickly in infrastructure applications.
End User:
Automotive procurement carries the steepest margin premiums as AEC-Q100 qualification and ASPICE process audits filter out commodity suppliers.
- Automotive:Embedded modems for telematics control units, V2X communication stacks, and over-the-air software update pipelines. EU UN R155 cybersecurity mandates and China's connected vehicle regulations are compressing supplier qualification windows.
- Industrial Automation:Ruggedized modules for smart factory retrofits requiring deterministic latency for machine coordination. German automotive OEMs and Japanese electronics manufacturers are pioneering long-term supply agreements with penalty clauses.
- Telecommunications:Infrastructure equipment and carrier-grade customer premises equipment.
- Consumer Electronics:Smartphones, tablets, wearables, and home devices.
Telecommunications retains the largest revenue base, though Automotive is climbing the fastest as mandates harden into enforceable compliance deadlines.
Form Factor:
OEM Modules concentrate procurement power with Tier-1 suppliers who displace spot-market purchases with multi-year contracts and silicon allocation guarantees.
- OEM Modules:Surface-mount modem subsystems qualified for direct integration into host device mainboards. German and Japanese automotive OEMs are consolidating procurement around penalty-clad long-term agreements to secure allocation against consumer electronics demand surges.
- Router Devices:CPE-embedded modems for fixed wireless access broadband substitution. India's PLI scheme for telecom equipment manufacturing is concentrating local sourcing decisions for sub-6 GHz deployments.
- Portable:Battery-powered mobile hotspot and USB dongle formats.
- Fixed:Desktop and wall-mounted units for stationary installation.
OEM Modules dominate supplier revenue, while Router Devices is gaining share fastest on India's broadband substitution wave.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs spectrum allocation and device certification in the United States, directly shaping modem frequency support requirements and market access timelines across the 5G modems landscape.
United States
Fixed wireless access deployments in suburban and rural markets drive CPE-embedded modem procurement. The FCC's spectrum reallocation proceedings determine which frequency bands require hardware support. Austin and Dallas metro areas concentrate infrastructure vendor engineering centers.
China
Industrial automation retrofits in Guangdong and Jiangsu provinces absorb sub-6 GHz OEM modules for machine coordination. MIIT enforces domestic encryption and network access standards that foreign vendors must navigate. Shenzhen anchors the hardware ecosystem for module integration.
Germany
Automotive OEMs compress supplier qualification windows as UN R155 cybersecurity mandates harden into enforceable compliance deadlines. The KBA oversees vehicle type-approval pathways embedding certified cellular connectivity. Stuttgart and Munich concentrate telematics control unit development.
India
Jio and Airtel densify fixed wireless access coverage across suburban broadband markets. TRAI's PLI scheme for telecom equipment manufacturing concentrates local sourcing decisions. Bengaluru and Hyderabad host module qualification and integration facilities.
Japan
Smart factory retrofits in the Chubu region require deterministic latency modules for machine-to-machine coordination. METI coordinates 5G private network deployment standards affecting modem specifications. Nagoya anchors automotive electronics manufacturing clusters.
5G Modems Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the 5G modems landscape. Qualcomm and MediaTek dominate premium and mid-tier smartphone sockets through baseband-RF system-on-chip designs. Samsung anchors captive supply for its Galaxy ecosystem while competing for external automotive sockets. UNISOC and Huawei represent vertically integrated challengers with domestic market anchoring. Competitive moves concentrate on long-term supply agreements with penalty clauses and silicon allocation guarantees against consumer electronics demand surges.
Within the integrated leader tier, Qualcomm and MediaTek occupy positions spanning premium through mid-tier device categories. Samsung exemplifies the captive-integrated archetype, balancing internal consumption against external revenue opportunities. Among China-based challengers, UNISOC and Huawei sit within a regionally anchored tier navigating MIIT certification requirements. Intel and Marvell represent the infrastructure-specialist archetype, targeting disaggregated baseband-RF opportunities in Open RAN deployments. NXP Semiconductors and Qorvo anchor the automotive and RF front-end specialist segments respectively.
| Leading Market Players |
|---|
| Intel |
| NXP Semiconductors |
| Qualcomm |
| Qorvo |
| Marvell |
| MediaTek |
| UNISOC |
| Huawei |
| Samsung |
| Others |
Supply Flow & Price Mechanics
Twenty-six-week qualification cycles for AEC-Q100 automotive certification concentrate procurement leverage with German and Japanese OEMs who negotiate multi-year allocation agreements. This extended validation timeline compresses supplier margins on sub-6 GHz modules while amplifying pricing power for compound semiconductor foundries supplying RF front-end components.
Pricing Analysis
Millimeter wave modules command 3-4x premiums over sub-6 GHz equivalents in Seoul and Tokyo deployments where dense urban capacity justifies elevated bill-of-materials costs. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade certified sockets from consumer electronics spot purchases. Cost compression in mid-tier smartphone sockets is intensifying because MediaTek and UNISOC expand sub-6 GHz portfolio overlap. Consumer electronics OEMs exhibit highest price sensitivity, while automotive Tier-1 suppliers accept premium positioning to secure silicon allocation against handset demand surges.
Supply Chain Analysis
Strait of Malacca transit congestion threatens RF front-end component delivery schedules for Southeast Asian module assembly plants. Taiwan, South Korea, and the United States anchor baseband die fabrication capacity, while China's Jiangsu province concentrates module integration and test operations. Supply chains draw from gallium arsenide substrate suppliers, advanced filter foundries, and beamforming antenna array specialists. Single-source vulnerability concentrates in compound semiconductor epitaxy capacity. Distribution runs through Tier-1 telematics suppliers who displace spot-market purchases with penalty-clad long-term contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM procurement consolidation around multi-year supply agreements with penalty clauses has shifted supplier-negotiating leverage toward volume-guaranteed buyers. German and Japanese vehicle manufacturers now dictate qualification timelines and silicon allocation priorities.
For Market Incumbents: Shield premium smartphone socket margins by accelerating integrated baseband-RF roadmap cadence against MediaTek sub-6 GHz expansion. Deepen captive supply relationships with Samsung Galaxy ecosystem commitments while securing external automotive design wins ahead of UN R155 enforcement deadlines. Prioritize RF systems engineering retention as talent scarcity concentrates within narrow demographic pools. For New Entrants and Emerging Players: Differentiate on Open RAN interoperability certification to capture disaggregated baseband-RF opportunities in India's PLI-scheme infrastructure builds. Target fixed wireless access CPE-embedded sockets in suburban broadband substitution markets where Jio and Airtel densify coverage. Pursue industrial automation corridor penetration in China's Guangdong province through deterministic latency module specialization. For Investors and Strategic Acquirers: Long-term, this sits as a automotive-electrification play because connected vehicle mandates harden into enforceable compliance deadlines across EU and Chinese regulatory frameworks. Acquisition targets should display AEC-Q100 qualification completion and ASPICE process audit certification. Monitor MIIT encryption standard navigation timelines as inflection indicator for foreign vendor market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| RF Front-End Vertical Integration | Captures margin pools from filter and amplifier supply concentration in compound semiconductor foundries. |
| Automotive Certification Fast-Track | Compresses AEC-Q100 validation timelines ahead of UN R155 cybersecurity mandate enforcement. |
| Open RAN Interoperability Investment | Opens socket opportunities in India's PLI-scheme infrastructure builds per O-RAN Alliance specifications. |
| Fixed Wireless Access CPE Development | Targets broadband substitution demand as Jio and Airtel densify suburban coverage across India. |
| Edge AI Modem Convergence | Integrates neural processing units for on-device inference in industrial gateway applications. |
Methodological Framework
A spread of perspectives from RF systems architects, Tier-1 telematics procurement directors, automotive platform engineers, and carrier network planning officers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from FCC spectrum allocation proceedings, MIIT network access certification databases, ETSI conformance benchmark publications, and 3GPP release documentation established foundational inputs. Bottom-up shipment estimates by product type and technology tier triangulated against top-down semiconductor foundry capacity disclosures.
Segmentation dimensions modeled span integrated versus discrete modem architectures, sub-6 GHz versus millimeter wave frequency bands, automotive versus consumer electronics end-use applications, and OEM module versus CPE router form factors. CAGRs were derived through logistic adoption curve fitting against infrastructure deployment timelines and regulatory mandate enforcement schedules. Industry-specific forecast inputs include connected vehicle type-approval pathways, smart factory retrofit cadence in China's industrial automation corridor, and India's PLI scheme localization requirements.
The analysis sits within stated boundaries; outcomes outside sustained sub-6 GHz volume leadership or accelerated millimeter wave urban densification would require recalibration. Forecasts reflect documented assumptions regarding 3GPP release adoption rates, automotive qualification cycle durations, and compound semiconductor foundry capacity expansion. Practitioners should keep alternative scenarios live as spectrum reallocation proceedings, open-RAN interoperability mandates, and MIIT encryption standard revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
SLD Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Europe Power Transistor Market