
 IGBT Market | 2026-2036
IGBT Market Size, Share, and Industry Trends Forecast 2026-2036
IGBT Market Intelligence
Consolidation among high-volume end-users, particularly in automotive and industrial sectors, is pivoting procurement toward suppliers with proven scale and reliability. Infineon Technologies leverages its extensive R&D in automotive-grade components to secure large contracts. Mitsubishi Electric sustains a strong position in high-power industrial and railway traction applications. StarPower Semiconductor specializes in the Chinese domestic market, capitalizing on local industrial policy and EV demand.
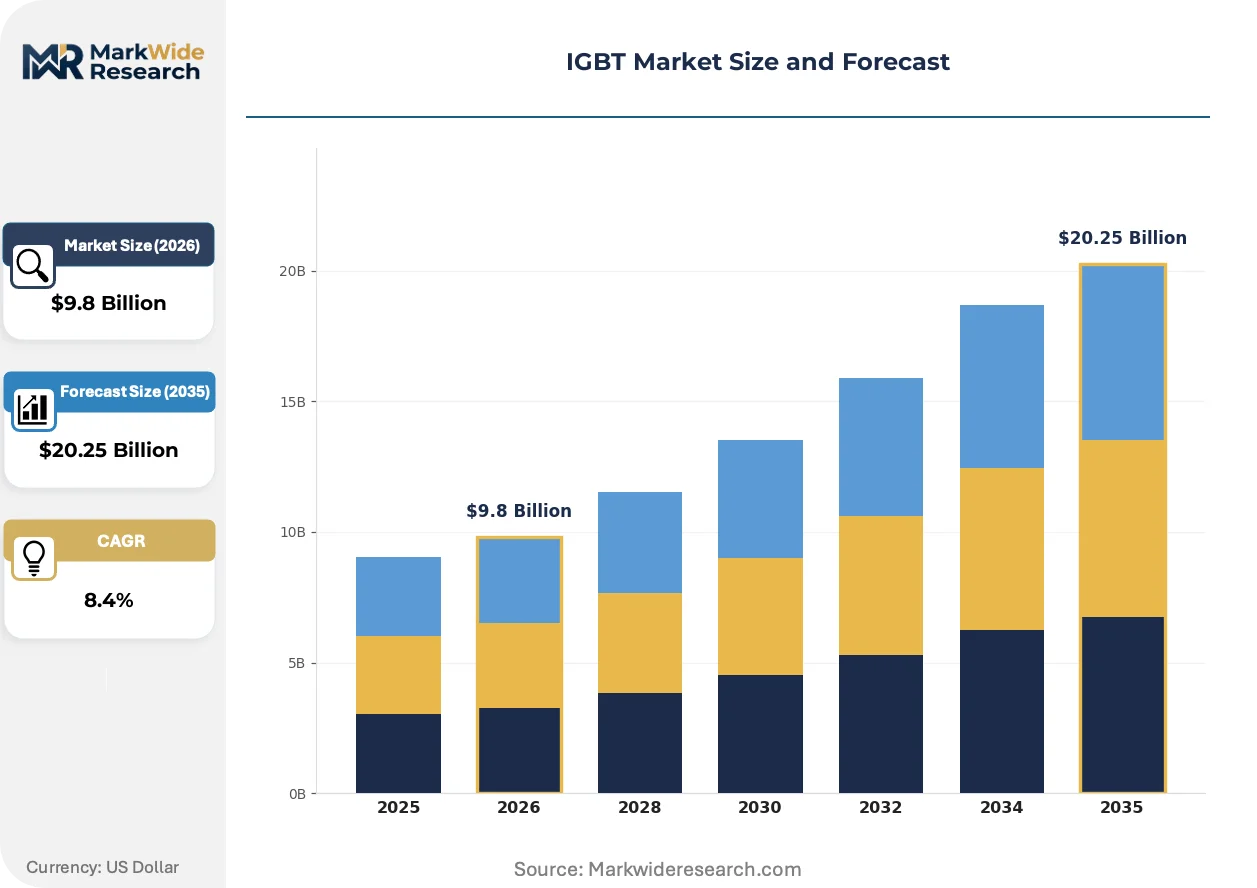
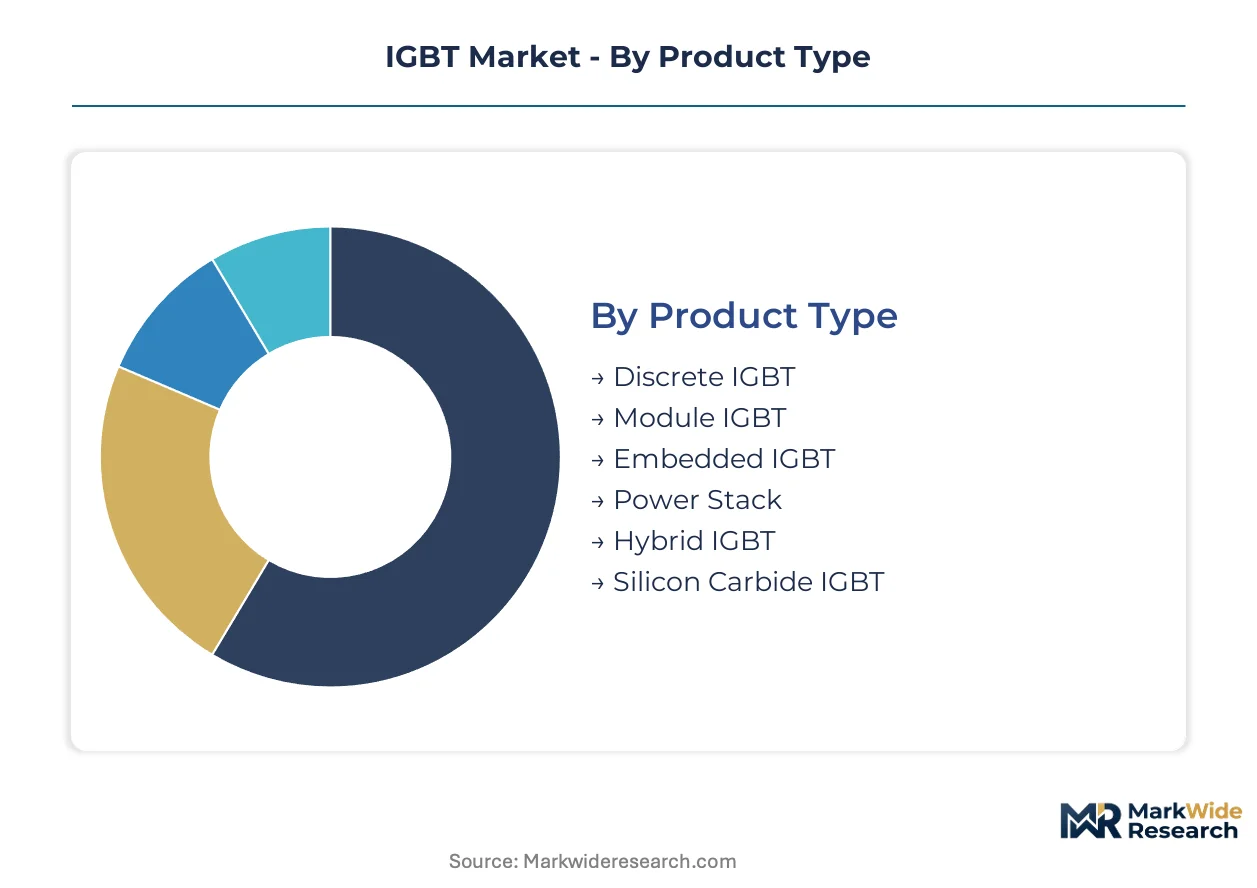
An Insulated-Gate Bipolar Transistor (IGBT) is a power semiconductor device engineered for rapid and efficient electronic switching. It merges the simple gate-drive characteristics of a MOSFET with the high-current and low-saturation-voltage capability of a bipolar transistor. Module IGBTs represent the largest product segment, valued for their integrated design in high-power systems. Demand from traction systems and renewable energy applications is expanding rapidly, driven by global decarbonization initiatives.
Regulatory frameworks such as the EU's F-Gas Regulation and China's dual carbon goals directly influence IGBT design and application demand. In the United States, EPA emissions standards for vehicles accelerate the shift to electric powertrains, subsequently boosting requirements for high-efficiency power modules. Component selection for new platforms now hinges on a critical trade-off between the performance of Silicon Carbide IGBTs and the cost-effectiveness of traditional silicon-based devices.
Market Dynamics
The primary force shaping the IGBT market is the global decarbonization mandate, which accelerates demand from electric vehicle powertrains and grid-scale renewable energy systems like wind and solar inverters.
Growth Catalysts
- EV Adoption:The automotive shift to electric vehicles requires high-voltage IGBT modules for powertrain inverters, especially in China and Europe.
- Renewable Energy Mandates:Policies like the EU Green Deal drive demand for IGBTs in solar inverters and wind turbines to meet clean energy targets.
- Advanced Materials:Silicon Carbide substrates enable IGBTs with higher efficiency and power density, expanding their use in demanding high-power applications.
Market Restraints
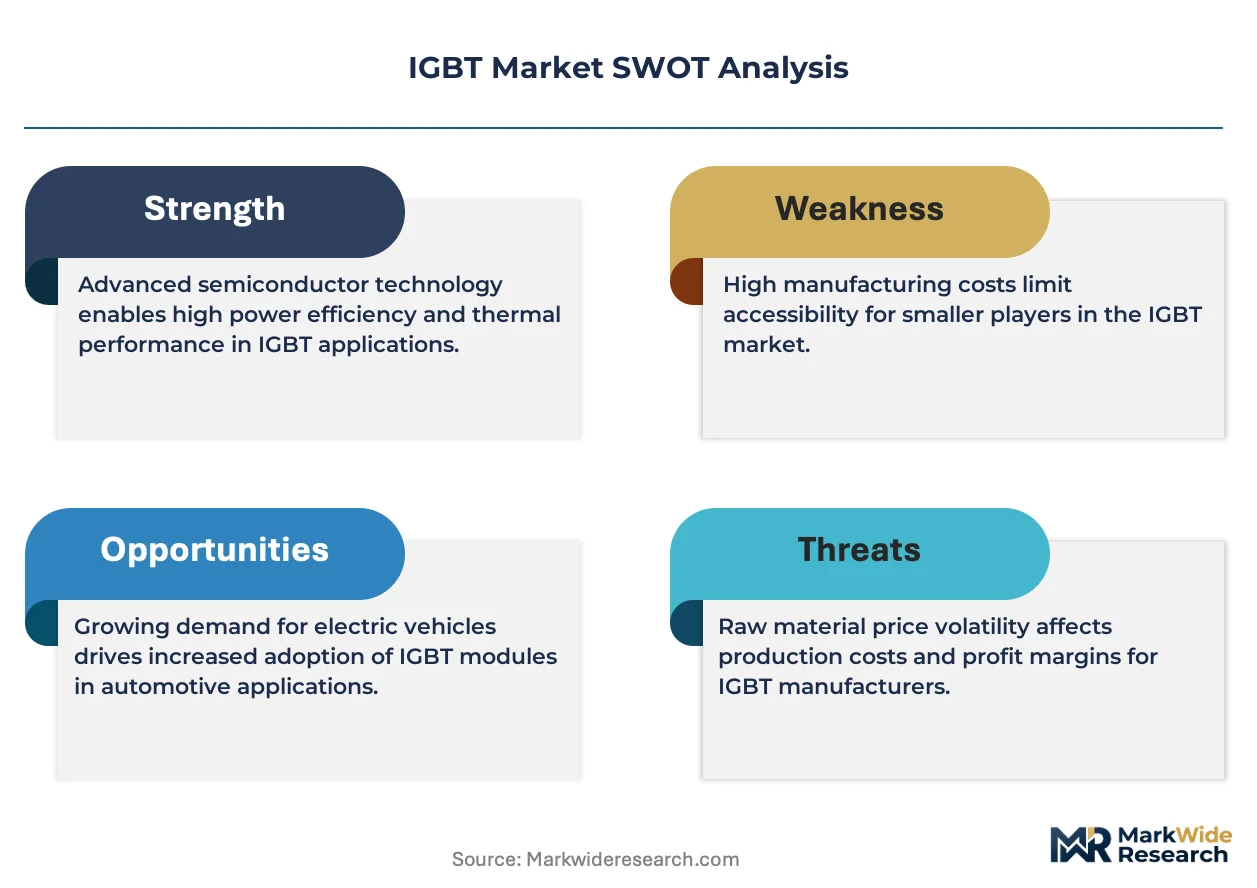
- Substrate Cost:High costs and constrained supply of Silicon Carbide wafers, concentrated among few suppliers, limit cost-effective, high-volume production.
- Thermal Management:Increasing power density in IGBT modules creates significant thermal challenges, requiring complex and expensive cooling solutions.
- Substitution Threat:Gallium Nitride (GaN) devices offer superior frequency in lower-power ranges, capping IGBT growth in those segments.
Strategic Opportunities
- Energy Storage Systems:The growth of grid-scale battery storage systems creates a major new application category for high-power IGBT modules.
- US Manufacturing Incentives:The Inflation Reduction Act (IRA) encourages onshore IGBT production for EVs and renewables through significant tax credits.
- Module Integration:Integrating IGBTs with drivers and sensors into Intelligent Power Modules (IPMs) offers a significant value-add opportunity.
Industry Challenges
- Fabrication Capex:Building and equipping fabs for 300mm IGBT wafer production requires massive capital investment and long lead times.
- Packaging Standardization:A lack of standard module footprints complicates second-sourcing for OEMs and slows system design and qualification cycles.
- Talent Gap:A shortage of power electronics engineers with high-voltage design skills hinders product development and application support industry-wide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IGBT Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete IGBT, Module IGBT, Embedded IGBT, Power Stack, Hybrid IGBT, Silicon Carbide IGBT Technology: Bipolar Junction Transistor, Field-Effect Transistor, MOS-Controlled Thyristor, Punch-Through IGBT, Non-Punch-Through IGBT, Trench Gate IGBT Application: Renewable Energy, Traction Systems, Industrial Drives, Consumer Electronics, Smart Grid, Power Supplies End User: Wind Turbine Manufacturers, Railway Operators, Heavy Equipment Manufacturers, Electronics OEMs, Solar Inverter Producers, Data Center Operators |
| Companies Covered | Semikron Danfoss, BYD Semiconductor, Infineon Technologies, onsemi, StarPower Semiconductor, Mitsubishi Electric, Zhuzhou CRRC Times Electric, Toshiba Electronic Devices & Storage, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IGBT Market Strategic Shifts & Innovations
Component design is evolving to meet system-level demands for greater power density and operational reliability. The focus is shifting from discrete component performance to integrated solutions that simplify end-system design and improve total cost of ownership.
Intelligent Power Modules (IPMs) integrate the IGBT switch with dedicated gate drivers and protection circuits. Industrial motor and appliance manufacturers are rapidly adopting these modules to accelerate their development cycles. This integration is automating critical functions like fault detection and thermal management, simplifying the design process for system engineers.
The EU’s F-Gas Regulation phases down potent greenhouse gases like SF6, which is used in high-voltage electrical switchgear. This policy directly stimulates demand for solid-state circuit breakers built with power semiconductors. As a result, the utility grid infrastructure segment is accelerating investment in IGBT-based switching solutions.
Automotive OEMs are altering their procurement models, seeking complete inverter systems rather than discrete semiconductor components. This trend favors suppliers capable of delivering integrated hardware and software solutions, bypassing traditional component distributors. This shift is most visible within the fast-paced EV markets of China and Germany.
IGBT Market Segmentation
Understanding the segmentation of the IGBT market is crucial for identifying distinct demand patterns and technological preferences across various power electronics applications. This granular view helps stakeholders tailor product development and market strategies to specific industry needs and performance requirements.
Product Type:
The product type segmentation delineates IGBT offerings based on their packaging, integration, and material composition, influencing their performance across various power applications.
- Module IGBT:These integrated units combine multiple IGBTs and diodes into a single package, offering simplified design and thermal management for high-power systems. Demand concentrates in traction systems and renewable energy applications, driven by global decarbonization initiatives and grid modernization.
- Silicon Carbide IGBT:Leveraging advanced wide-bandgap materials, these devices achieve significantly higher efficiency, power density, and operating temperatures compared to traditional silicon. Their use is expanding in demanding high-power applications like electric vehicle powertrains and grid-scale energy storage systems.
- Discrete IGBT:Individual IGBT chips packaged for lower to medium power applications, offering flexibility for custom circuit designs.
- Embedded IGBT:These are integrated directly onto system boards, providing compact solutions for specific power control functions.
- Power Stack:A complete power conversion subsystem integrating IGBTs with other components like capacitors and cooling, simplifying system assembly.
- Hybrid IGBT:Combines silicon IGBTs with silicon carbide diodes, balancing performance gains with cost considerations for specific applications.
Module IGBT leads on scale; Silicon Carbide IGBT leads on momentum.
Technology:
Different IGBT technologies are engineered to optimize specific performance characteristics, from switching speed to voltage handling, tailoring devices for diverse power management needs.
- Trench Gate IGBT:This design features a vertical trench structure in the silicon, enhancing current density and reducing conduction losses, making it ideal for high-efficiency power converters. It finds extensive use in industrial drives and electric vehicle inverters, particularly in China and Europe.
- Non-Punch-Through IGBT:Characterized by its robust short-circuit withstand capability and soft switching characteristics, this technology is designed for applications demanding high reliability and lower switching frequencies. It is extensively used in motor control and welding equipment where durability is paramount.
- Bipolar Junction Transistor:An older power switching technology, now largely superseded by IGBTs in high-power applications due to lower efficiency.
- Field-Effect Transistor:MOSFETs offer high switching speeds but typically lower voltage and current ratings than IGBTs, used in different power ranges.
- MOS-Controlled Thyristor:A power semiconductor device combining aspects of MOSFETs and thyristors, used in specific high-power switching applications.
- Punch-Through IGBT:Features a thin N-drift region and N-buffer layer, optimizing for lower conduction losses at the expense of some short-circuit ruggedness.
The Trench Gate design dominates modern high-power applications, while Non-Punch-Through variants offer specific advantages in high-reliability scenarios.
Application:
IGBT applications span critical sectors where efficient power conversion is essential, directly supporting global electrification and energy transition efforts.
- Renewable Energy:IGBTs are fundamental components in solar inverters and wind turbine converters, facilitating the efficient conversion of generated power for grid integration. Policy mandates like the EU Green Deal and China's dual carbon goals drive significant demand in this segment.
- Traction Systems:High-voltage IGBT modules manage power flow in electric trains, trams, and subways, enabling efficient motor control and regenerative braking. Demand accelerates due to public transport electrification and infrastructure upgrades in countries like Germany and Japan.
- Industrial Drives:IGBTs control the speed and torque of electric motors in factories and heavy machinery, improving energy efficiency and process control.
- Consumer Electronics:Used in high-power appliances like induction cooktops and air conditioners for precise power regulation.
- Smart Grid:IGBTs are integral to grid infrastructure for power quality management, flexible AC transmission systems (FACTS), and high-voltage direct current (HVDC) transmission.
- Power Supplies:Employed in uninterruptible power supplies (UPS) and switch-mode power supplies (SMPS) for efficient power conversion and regulation.
Renewable Energy and Traction Systems represent the fastest-growing trajectories for IGBT deployment, propelled by decarbonization.
End User:
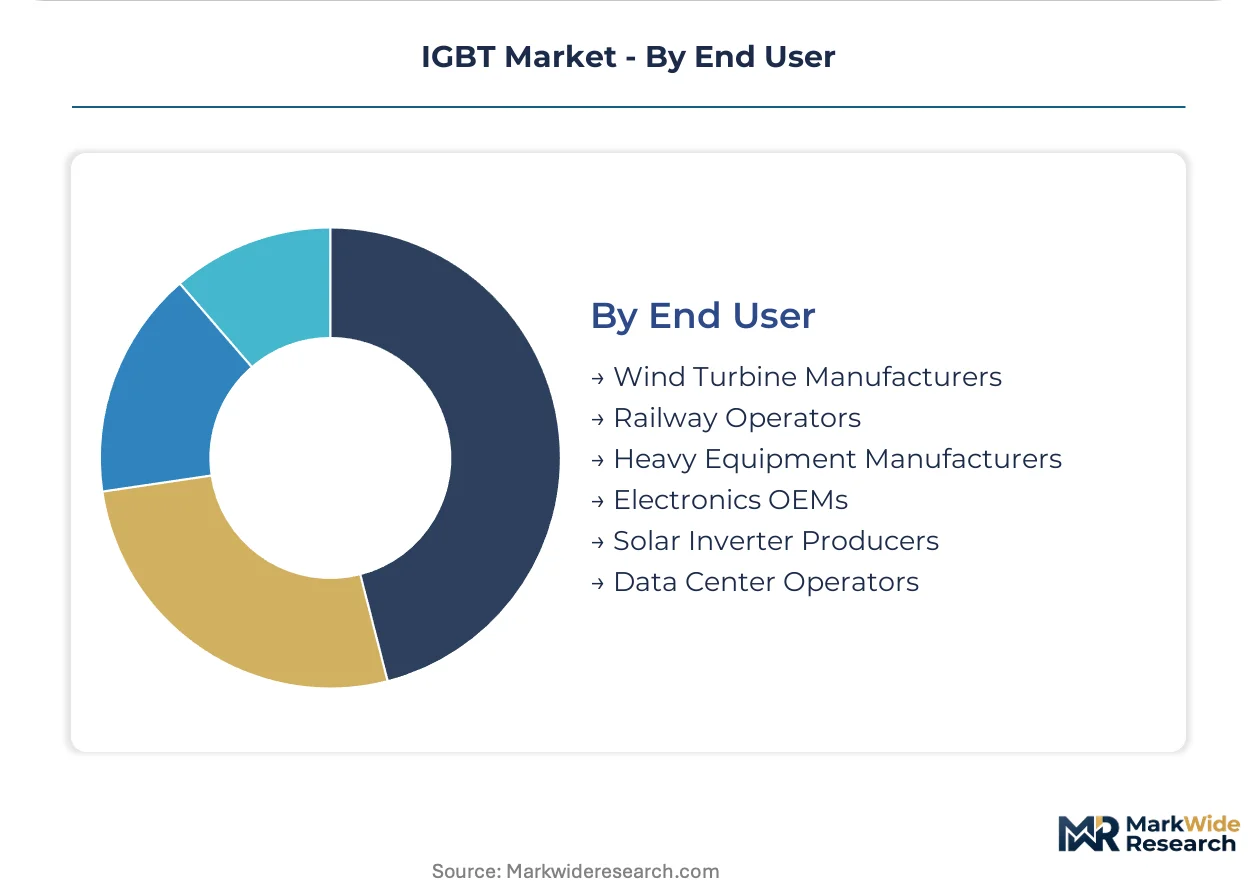
End-user segments reflect the diverse industries integrating IGBT technology into their power electronics, each with distinct procurement patterns and performance requirements.
- Wind Turbine Manufacturers:These manufacturers integrate high-power IGBT modules into their turbine converters and pitch control systems to maximize energy capture and grid stability. Significant investments in offshore wind farms across Europe and onshore projects in China drive this segment.
- Railway Operators:Operators rely on robust IGBTs for traction inverters, auxiliary power units, and braking systems in their electric locomotives and rolling stock. Procurement is significantly influenced by modernization programs and expansion of high-speed rail networks in countries like France and India.
- Heavy Equipment Manufacturers:Utilize IGBTs in power electronics for electric and hybrid construction machinery, forklifts, and mining equipment, enhancing efficiency and reducing emissions.
- Electronics OEMs:Original equipment manufacturers incorporate IGBTs into a wide array of products, from industrial equipment to high-power consumer devices.
- Solar Inverter Producers:These companies are key consumers of IGBTs, integrating them into central and string inverters for solar photovoltaic installations.
- Data Center Operators:Employ IGBTs in their UPS systems and power distribution units to ensure reliable and efficient power delivery to servers.
Wind Turbine Manufacturers and Railway Operators are significant consumers of high-power IGBT modules, driving innovation in module robustness and efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China's expansive manufacturing base fuels significant IGBT demand for electric vehicles and renewable energy, Germany's focus on high-power industrial applications and railway traction also drives considerable procurement. Both nations prioritize decarbonization, necessitating advanced power semiconductor solutions. This global push shapes regional market dynamics.
China
China's robust electric vehicle manufacturing and extensive renewable energy projects drive substantial IGBT consumption. The nation's dual carbon goals directly accelerate investment in high-efficiency power modules for these sectors. The Yangtze River Delta region, a hub for EV production, sees concentrated demand for advanced IGBT solutions.
Germany
Germany's advanced industrial sector and extensive railway networks create sustained demand for high-power IGBT modules. The EU Green Deal mandates drive the adoption of efficient power electronics in wind turbines and electric mobility infrastructure. Bavaria, a center for automotive and industrial technology, actively integrates IGBTs into next-generation systems.
United States
The United States experiences surging demand for IGBTs due to accelerating electric vehicle production and grid modernization efforts. The Inflation Reduction Act provides tax credits encouraging onshore manufacturing of these critical components for EVs and renewables. California's burgeoning EV ecosystem and renewable energy projects require high-efficiency power modules.
Japan
Japan's focus on high-speed rail systems and advanced industrial automation sustains a strong market for robust IGBTs. The Ministry of Economy, Trade and Industry (METI) promotes energy efficiency standards, boosting demand for high-performance power semiconductors. The Kansai region, home to major electronics manufacturers, innovates in IGBT applications for infrastructure.
India
India's ambitious renewable energy targets and ongoing railway modernization projects fuel significant IGBT requirements. The Production-Linked Incentive (PLI) scheme supports domestic electronics manufacturing, including power semiconductors. Karnataka, with its growing electronics industry, is witnessing increased integration of IGBTs in local infrastructure development.
IGBT Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the IGBT market, creating a tiered competitive structure. Large established players leverage extensive R&D and global distribution networks, while niche manufacturers target specific regional or application segments. Key strategic archetypes include integrated device manufacturers with broad portfolios and specialized module assemblers. Competitive moves frequently involve capacity expansion to meet rising demand and strategic partnerships for technology co-development.
Within the high-power and automotive segments, Infineon Technologies and Mitsubishi Electric exemplify established global leaders. Infineon, a German-based semiconductor manufacturer, anchors significant demand through its extensive R&D in automotive-grade components. Mitsubishi Electric, a Japanese conglomerate, maintains a strong position in high-power industrial and railway traction applications. StarPower Semiconductor, a Chinese entity, represents a regional specialist, capitalizing on local industrial policy and the surging electric vehicle demand within its home market. These entities collectively shape market dynamics through their distinct strategic emphases and geographic footprints.
| Leading Market Players |
|---|
| Semikron Danfoss |
| BYD Semiconductor |
| Infineon Technologies |
| onsemi |
| StarPower Semiconductor |
| Mitsubishi Electric |
| Zhuzhou CRRC Times Electric |
| Toshiba Electronic Devices & Storage |
| Fuji Electric |
| Others |
Cost & Logistics Intelligence
Silicon Carbide wafer prices cascade through the IGBT supply chain, directly influencing module manufacturing costs and subsequently affecting pricing tiers for end-users like automotive OEMs. This critical raw material shortage creates a direct link between upstream supply and downstream product cost.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard silicon-based IGBT modules, particularly for industrial applications. The dominant pricing model is contract-based long-term offtake, especially for high-volume automotive and renewable energy procurements. Price differentiation stems from certification level, such as automotive-grade AEC-Q101, and the integration of advanced materials like Silicon Carbide. Pricing pressure stems from the high cost and constrained supply of Silicon Carbide wafers, impacting premium segments. Industrial drives and consumer electronics manufacturers exhibit higher price sensitivity compared to electric vehicle and railway operators.
Supply Chain Analysis
Logistics costs for specialized components and finished modules impact regional pricing, particularly for cross-continental shipments. Geographic supply concentration for IGBT manufacturing centers in China, Germany, and Japan. The supply chain depends on critical raw materials like high-purity silicon and Silicon Carbide wafers, which have limited suppliers. Single-source vulnerability for advanced Silicon Carbide substrates presents a significant structural risk. Distribution runs primarily through direct sales channels to large OEMs, supplemented by specialized power electronics distributors for smaller industrial customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, driven by the persistent global decarbonization mandate that sustains demand across diverse applications.
For Market Incumbents: Lock in long-term supply agreements for Silicon Carbide wafers to mitigate raw material cost volatility and ensure production continuity. Invest heavily in R&D for advanced packaging techniques and Intelligent Power Modules (IPMs) to counter the substitution threat from Gallium Nitride devices in lower-power ranges. Expand 300mm wafer fabrication capacity in strategic geographies like the United States to leverage local incentives and secure market share, particularly in the automotive segment. Strengthen partnerships with automotive OEMs for integrated inverter solutions.
For New Entrants and Emerging Players: Underserved industrial motor manufacturers in rapidly industrializing regions like India represent a penetrable segment for cost-effective IGBT solutions. Target niche applications such as grid-scale battery storage systems, focusing on robust, high-power module designs. A compelling go-to-market angle involves offering hybrid IGBTs that balance Silicon Carbide performance with silicon cost-effectiveness, bundled with strong application engineering support. Focus on regions with less established local supply chains for faster market entry.
For Investors and Strategic Acquirers: Consolidation pressure builds where fabrication capital expenditure remains extremely high and specialized talent is scarce. The long-term viability of the IGBT market is strong, anchored by sustained demand from electric vehicles and renewable energy infrastructure over the next decade. Target specialized module assemblers or power electronics design firms with strong intellectual property in advanced materials or integrated solutions. The signal to watch is the expansion of Silicon Carbide wafer production capacity beyond current concentrated suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for 300mm Wafers | Increases supply resilience and reduces substrate costs for high-volume IGBT production, especially in China. |
| Development of Intelligent Power Modules (IPMs) | Simplifies system design for industrial and appliance OEMs, accelerating adoption and reducing total cost of ownership. |
| Strategic Partnerships for Silicon Carbide Supply | Secures access to critical wide-bandgap materials, enabling higher efficiency and power density in advanced IGBTs. |
| Geographic Expansion into Emerging EV Markets | Captures new demand from electric vehicle manufacturing hubs beyond established regions like Germany and Japan. |
| Investment in Thermal Management Solutions | Addresses power density challenges in IGBT modules, improving operational reliability and extending component lifespan. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and internal market models — were reconciled to construct a robust market view. This involved combining insights from power electronics engineers, automotive OEM procurement leads, renewable energy system integrators, and semiconductor R&D directors. Secondary data sources included company annual reports, industry association data, government energy reports, and academic research. Bottom-up data collection from individual product segments was triangulated with top-down market sizing approaches for validation.
The analytical framework systematically integrated various data streams across the analysis window, ensuring consistency in volume and value projections. Segmentation dimensions modeled included product type, technology, application, end user, and regional market dynamics. Compound annual growth rates were derived from historical trends, projected market drivers, and expert consensus on future technology adoption. Industry-specific forecast inputs included electric vehicle production forecasts and renewable energy deployment targets, alongside regulatory policy impacts.
Underlying measurement precision varies by segment; Module IGBTs and Trench Gate technology carry tighter precision than others due to established market data. Forecasts reflect assumptions regarding technological advancements and regulatory stability. A model refresh is warranted upon material change in Silicon Carbide supply chain stability or major shifts in global decarbonization policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market