
 N-Topcon Solar Cells Market | 2026-2036
N-Topcon Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
N-Topcon Solar Cells Market Insights
Performance-guarantee subscription layers tied to module output is expanding how N-TOPCon vendors monetize long-term relationships beyond hardware sales. LONGi Green Energy Technology Co., Ltd. leverages its integrated wafer-cell-module footprint to control cost curves across the value chain. JinkoSolar Holding Co., Ltd. anchors its competitiveness through relentless R&D spending on tunnel-oxide passivated contact architectures. Trina Solar Limited differentiates by bundling tracking-software compatibility with its high-efficiency cell offerings.
N-type tunnel oxide passivated contact solar cells employ an ultrathin silicon oxide layer and doped polysilicon to suppress carrier recombination, delivering conversion efficiencies above 25% in commercial formats. The technology serves ground-mounted and rooftop installations where levelized cost of electricity drives procurement. Bifacial product types command attention because dual-sided light capture raises energy density without expanding land use. TOPCon technology segments outpace PERC alternatives as manufacturers retool existing lines for the lower-temperature process architecture. Utility end users concentrate procurement volume, while residential segments show faster growth rates as distributed generation policies spread.
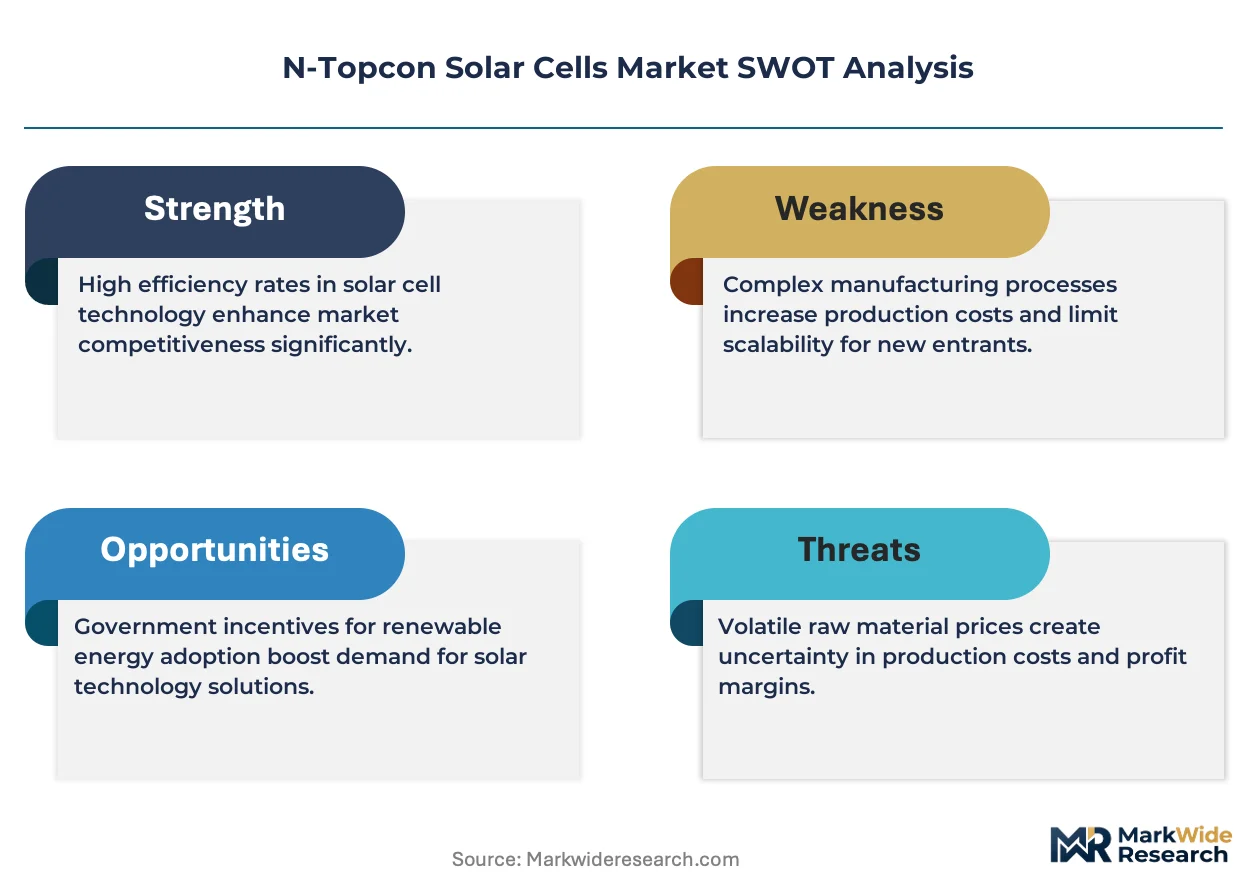
FDA oversight applies where solar installations power medical facility microgrids, though EPA rules on hazardous materials in semiconductor manufacturing shape cell production standards more directly. China's MIIT sets efficiency thresholds and production-capacity quotas that filter which N-TOPCon fabs receive state support. The EU Green Deal's carbon border adjustment mechanism will force exporters to document embodied emissions or face tariff penalties. Stakeholders must track which regulatory regimes merge carbon accounting with trade policy, since compliance costs will determine competitive access to the largest procurement markets.
Market Dynamics
Manufacturers are retooling PERC lines for TOPCon architectures to meet efficiency thresholds set by China's MIIT and the EU Green Deal's carbon border adjustments, compressing investment cycles and reshaping competitive access to procurement markets.
Growth Catalysts
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology sets minimum conversion efficiency thresholds that disqualify legacy PERC capacity from state support, forcing technology migration.
- Bifacial Ground-Mount Deployment:Utility-scale solar farms in India and Germany deploy dual-sided modules to maximize energy yield per hectare without land expansion.
- EU Carbon Border Adjustment Mechanism:The EU Green Deal's CBAM forces exporters to document embodied emissions or face tariff penalties, advantaging low-carbon cell producers.
Market Restraints
- Polysilicon Supply Concentration:Over 80% of metallurgical-grade silicon processing clusters in Xinjiang creates geopolitical and ESG audit risks for module buyers.
- Silver Paste Cost Volatility:N-TOPCon cells require 20-30% more silver per watt than PERC alternatives, exposing margins to precious metal price swings.
- Wafer Thickness Limitations:Tunnel-oxide passivation performance degrades below 130-micron wafer thickness, capping silicon cost reduction potential.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for domestic cell and module manufacturing create localized supply alternatives to Chinese imports.
- Agrivoltaics Convergence:Elevated bifacial installations combine crop cultivation with energy generation, opening farmland-adjacent deployment without land-use conflict.
- Performance-Guarantee Subscriptions:Long-term output warranties bundled with monitoring software transform hardware vendors into energy-yield service providers.
Industry Challenges
- Tunnel-Oxide Process Control:Sub-nanometer oxide thickness uniformity demands atomic-layer deposition expertise scarce outside leading fabs.
- Legacy PERC Stranded Assets:Retooling existing lines requires 12-18 month downtime and specialized equipment, creating cash-flow interruption for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Topcon Solar Cells Market |
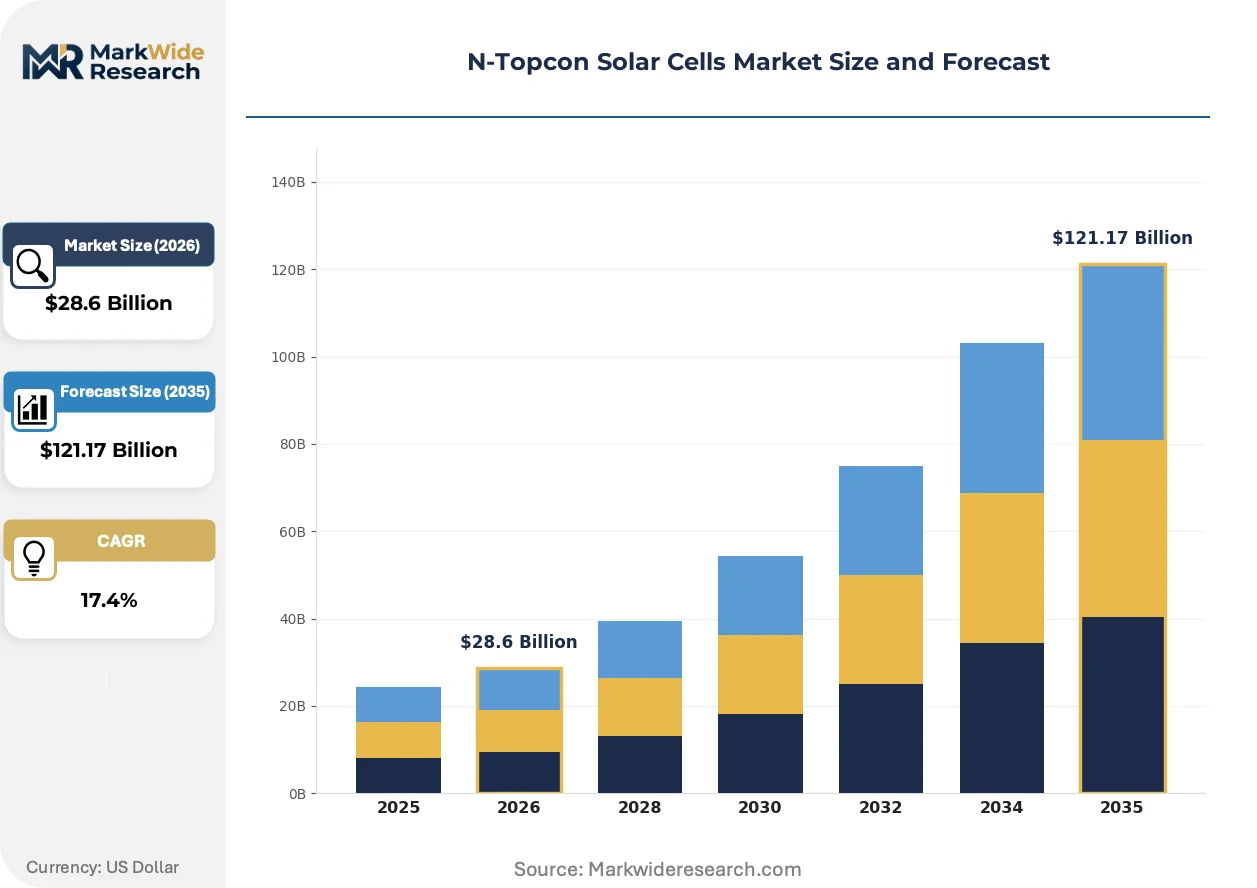
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film Technology: PERC, HJT, TOPCon, CdTe Installation: Rooftop, Ground-Mounted, Floating, Building-Integrated End User: Residential, Commercial, Utility, Industrial |
| Companies Covered | JinkoSolar Holding Co., Ltd., LONGi Green Energy Technology Co., Ltd., Trina Solar Limited, JA Solar Technology Co., Ltd., Canadian Solar Inc., Tongwei Co. Ltd., Hanwha Q CELLS, Risen Energy, Jolywood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Topcon Solar Cells Market Trends and Innovations
Process integration and digital twin deployment are compressing development cycles while regulatory carbon accounting fuses with trade policy, altering how cell manufacturers qualify for procurement tenders.
Silicon heterojunction-TOPCon tandem architectures are unifying the passivation benefits of tunnel-oxide contacts with heterojunction's superior temperature coefficients. European utility developers pilot these stacks in Mediterranean climates where thermal degradation erodes standard TOPCon returns. The convergence is unifying two previously separate R&D trajectories into a single commercialization pathway, forcing equipment suppliers to support hybrid process flows.
The EU Green Deal's carbon border adjustment mechanism is reshaping supply chain documentation requirements. Cell exporters must now obtain verified lifecycle emissions certificates from accredited third-party auditors to avoid tariff penalties. German and Dutch utility procurement teams have begun rejecting tenders lacking ISO 14064-compliant carbon footprints, shifting competitive advantage toward manufacturers with captive polysilicon and renewable-powered fabs.
Buyers are consolidating module procurement through multi-year framework agreements rather than spot-market purchases. European IPPs and Indian discoms now negotiate 3-5 year supply contracts with fixed pricing and guaranteed capacity allocation, displacing the auction-driven spot procurement that dominated 2019-2023. This shift concentrates volume with vertically integrated cell-to-module manufacturers capable of underwriting long-term delivery commitments.
N-Topcon Solar Cells Market Segmentation
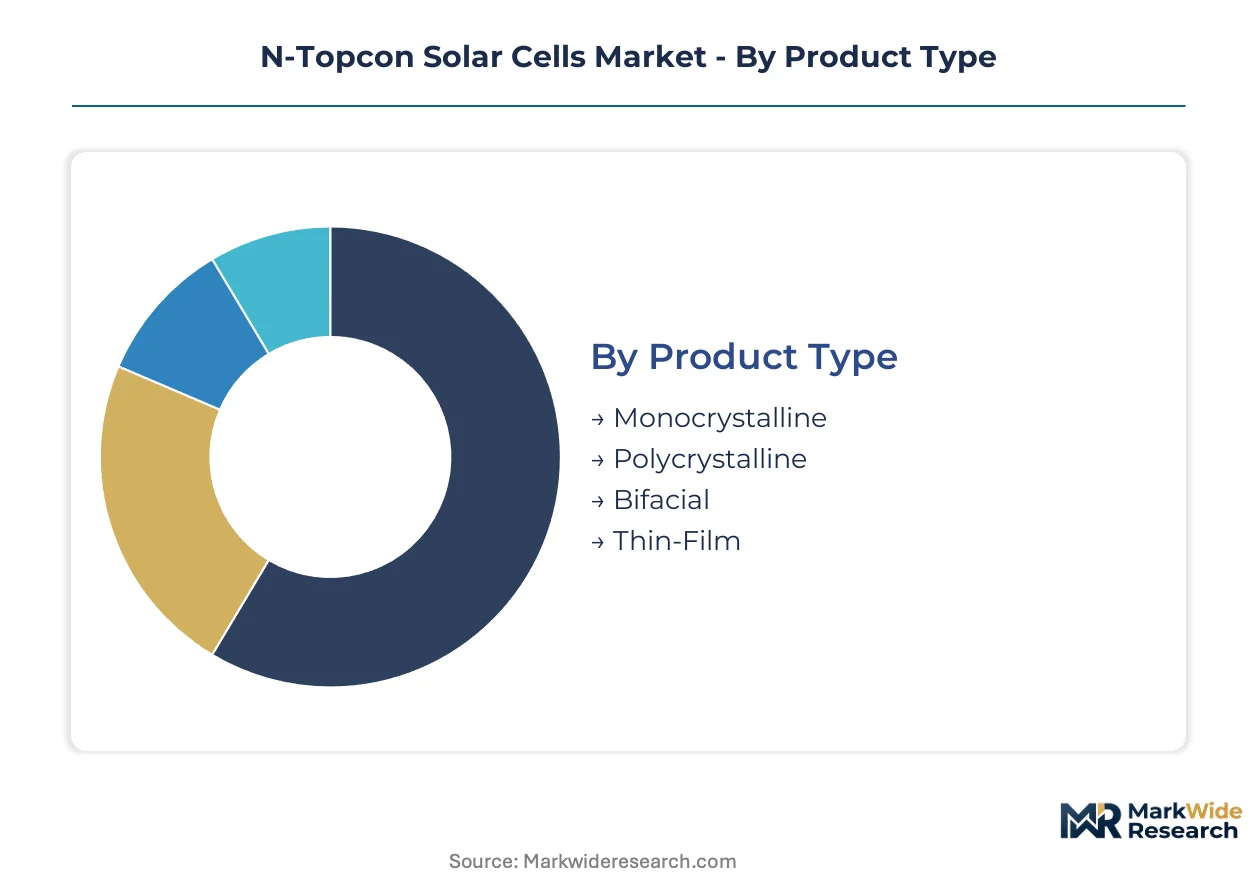
N-TOPCon solar cells serve distinct deployment contexts where cell architecture, mounting configuration, and procurement scale determine technology selection. Manufacturers align product portfolios across these dimensions to capture replacement cycles from legacy PERC capacity and emerging utility tenders.
Product Type:
Upgrade cycles from PERC to TOPCon architectures favor cell formats with higher conversion efficiency and bifacial energy yield, reshaping procurement specifications across utility and distributed segments.
- Monocrystalline:Single-crystal silicon ingots deliver the highest electron mobility and conversion efficiency in commercial N-TOPCon formats. Chinese and German utility developers specify monocrystalline cells for ground-mounted farms where energy density per hectare drives project returns. Wafer thinning limitations below 130 microns constrain cost reduction pathways despite efficiency advantages.
- Bifacial:Dual-sided light capture raises effective energy yield through rear-side albedo reflection without expanding land footprint. Indian solar parks and agrivoltaic installations in Germany deploy bifacial N-TOPCon modules to maximize output from fixed installation areas. Silver paste requirements run 20-30% above monofacial alternatives, exposing margins to precious metal volatility.
- Polycrystalline:Multi-crystal silicon offers lower manufacturing cost but reduced efficiency versus monocrystalline alternatives.
- Thin-Film:Cadmium telluride and CIGS architectures occupy niche applications where weight constraints or flexible form factors override efficiency priorities.
Volume placements concentrate in Bifacial; the faster expansion belongs to Monocrystalline.
Technology:
Process temperature requirements and equipment compatibility determine which cell architectures manufacturers adopt when retooling existing PERC lines.
- TOPCon:Tunnel oxide passivated contact structures employ ultrathin silicon oxide and doped polysilicon layers to suppress carrier recombination, delivering commercial efficiencies above 25%. China's MIIT efficiency mandates and EU Green Deal carbon border adjustments accelerate migration from PERC to TOPCon process flows. Atomic-layer deposition expertise for sub-nanometer oxide uniformity remains concentrated among leading fabs.
- PERC:Passivated emitter and rear contact technology dominates installed manufacturing capacity but faces disqualification from state support under rising efficiency thresholds. Legacy line stranded assets create cash-flow interruption risks for mid-tier manufacturers during 12-18 month retooling cycles.
- HJT:Silicon heterojunction stacks pair amorphous silicon passivation with superior temperature coefficients for Mediterranean and desert climates.
- CdTe:Cadmium telluride thin-film technology occupies utility-scale applications where manufacturing cost offsets lower efficiency benchmarks.
Procurement volume currently flows through PERC; steepest expansion trajectory attaches to TOPCon.
Installation:
Mounting configuration dictates cell form factor, framing requirements, and balance-of-system integration complexity.
- Ground-Mounted:Fixed-tilt and tracking installations on dedicated solar land absorb the largest N-TOPCon volumes as developers chase levelized cost targets. Indian and German utility-scale parks specify high-efficiency bifacial ground-mounted modules to maximize energy yield per hectare.
- Rooftop:Distributed generation on commercial and residential buildings favors lightweight module formats with simplified mounting hardware. India's net metering policies and Germany's residential feed-in tariffs accelerate rooftop N-TOPCon adoption despite higher per-watt installation costs.
- Floating:FPV arrays on reservoirs and quarry lakes reduce land-use conflict while water cooling enhances cell performance.
- Building-Integrated:Architectural integration replaces conventional building materials with photovoltaic surfaces, requiring custom cell dimensions and aesthetic finishes.
Ground-Mounted commands current procurement volume; Rooftop is climbing the fastest.
End User:
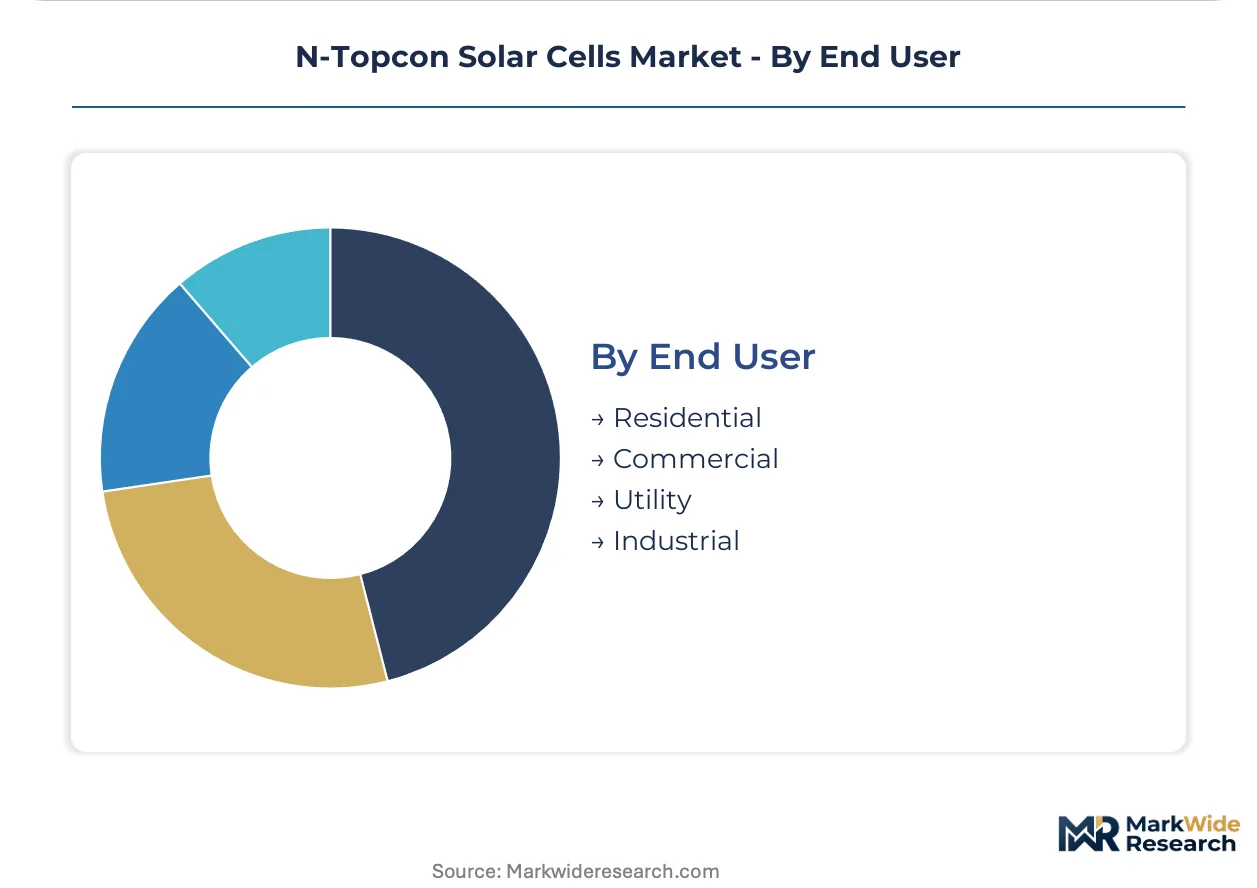
Procurement scale and contract duration differentiate customer segments from residential distributed generation to multi-gigawatt utility tenders.
- Utility:Independent power producers and state discoms negotiate multi-year framework agreements with fixed pricing and guaranteed capacity allocation. European and Indian utilities now reject spot-market procurement in favor of 3-5 year supply contracts with vertically integrated cell-to-module manufacturers capable of underwriting long-term delivery commitments.
- Residential:Homeowner-sited systems benefit from distributed generation incentives and net metering policies spreading across India and Germany. Smaller transaction sizes and fragmented installer networks create customer acquisition cost challenges despite faster growth rates.
- Commercial:Corporate offtake agreements and on-site generation targets drive C&I procurement with shorter payback period requirements than utility-scale projects.
- Industrial:Manufacturing facility microgrids and renewable energy certificates support decarbonization commitments with captive generation assets.
Utility captures dominant procurement volume; Residential is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the overwhelming majority of N-TOPCon cells and wafers, while India and Germany absorb the largest installation volumes outside Chinese domestic demand. This production-consumption divide shapes trade flows, carbon accounting disputes, and equipment procurement patterns across the value chain.
China
Domestic utility-scale deployment absorbs over half of Chinese N-TOPCon module output as provincial governments auction gigawatt-scale solar parks. MIIT efficiency mandates disqualify legacy PERC capacity from state support, accelerating fab retooling in Jiangsu and Anhui provinces. The Yangtze River Delta cluster hosts the densest concentration of tunnel-oxide deposition equipment suppliers serving both domestic and export orders.
India
Central and state discoms tender multi-gigawatt capacity under national renewable purchase obligations driving N-TOPCon adoption. The PLI scheme for domestic cell and module manufacturing offers capital subsidies to fabs locating in Gujarat and Tamil Nadu. Manufacturing incentives have attracted Chinese equipment vendors to establish technical service centers in Delhi-NCR and Mumbai.
Germany
Utility developers specify high-efficiency bifacial modules for agrivoltaic and ground-mounted projects to maximize yield per hectare. The EU Green Deal's carbon border adjustment mechanism requires documented lifecycle emissions for imported cells, filtering procurement toward low-carbon suppliers. Industrial clusters in Saxony-Anhalt and Brandenburg host pilot lines for silicon heterojunction-TOPCon tandem architectures.
United States
Independent power producers negotiate long-term supply agreements with vertically integrated manufacturers to secure IRA production tax credit eligibility. FERC interconnection queue reforms aim to accelerate utility-scale solar deployment timelines congested by grid access delays. Arizona and Texas utility commissions have approved accelerated depreciation schedules for bifacial ground-mounted installations.
South Korea
Corporate renewable energy certificate demand drives procurement from domestic module assemblers sourcing N-TOPCon cells from Chinese foundries. METI-aligned efficiency standards for building-integrated photovoltaics create niche demand for lightweight high-efficiency formats. The Busan-Ulsan industrial corridor hosts testing facilities certifying module performance for Mediterranean and desert climate exports.
N-Topcon Solar Cells Market Competitive Landscape
Top-tier vendors anchor the premium efficiency segment, while mid-scale fabricators compete on regional logistics and domestic content compliance. The vendor base stratifies across three tiers: integrated wafer-cell-module operators, cell-specialist foundries, and module assemblers sourcing cells on contract. Strategic archetypes include backward-integrated polysilicon producers, equipment-technology licensors, and project-development affiliates. Dominant competitive moves encompass multi-year framework agreements with utility offtakers and captive polysilicon investments to secure low-carbon supply credentials.
Among Chinese-integrated operators, LONGi Green Energy Technology Co., Ltd., JinkoSolar Holding Co., Ltd., and Trina Solar Limited occupy positions exemplifying the scale-driven archetype. These entities represent the vertically consolidated tier where in-house wafering, cell fabrication, and module assembly enable long-term delivery commitments. Their positioning reflects the competitive imperative to underwrite multi-gigawatt supply contracts while documenting carbon footprints for EU and US market access.
| Leading Market Players |
|---|
| JinkoSolar Holding Co., Ltd. |
| LONGi Green Energy Technology Co., Ltd. |
| Trina Solar Limited |
| JA Solar Technology Co., Ltd. |
| Canadian Solar Inc. |
| Tongwei Co. Ltd. |
| Hanwha Q CELLS |
| Risen Energy |
| Jolywood |
| Others |
Pricing and Supply Chain Analysis
Utility-scale IPPs and state discoms in India and Germany concentrate procurement through multi-year framework agreements, locking in contract-based long-term offtake pricing that rewards vertically integrated cell-to-module manufacturers with delivery certainty.
Pricing Analysis
Margin tightening in standard-tier modules reflects silver paste cost volatility and wafer thickness limitations capping silicon savings. Pricing stratifies across premium, standard, and economy tiers based on conversion efficiency certification and bifacial energy yield guarantees. Cost-down pressure accelerates as Chinese MIIT efficiency mandates disqualify legacy PERC capacity from state support, forcing retooling investments. Residential segments exhibit highest price sensitivity due to fragmented installer networks and customer acquisition costs, while utility buyers prioritize levelized cost of electricity over per-watt pricing.
Supply Chain Analysis
India's PLI scheme and the EU Green Deal's carbon border adjustment mechanism are reshaping sourcing patterns by rewarding domestic-content compliance and documented lifecycle emissions. Manufacturing concentrates in China, India, and Germany, with metallurgical-grade silicon processing anchored in Xinjiang creating geopolitical audit exposure. N-TOPCon production draws from silver paste, high-purity polysilicon, and atomic-layer deposition equipment inputs. Single-source vulnerability concentrates in tunnel-oxide deposition tool suppliers outside leading fabs. Distribution runs through vertically integrated wafer-cell-module operators underwriting multi-gigawatt utility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The N-TOPCon solar cells market is consolidating around integrated manufacturers capable of underwriting long-term delivery commitments, with MIIT efficiency mandates and EU carbon border adjustments forcing weaker players into stranded asset positions.
For Market Incumbents: Anticipate silver paste cost volatility by securing backward integration into polysilicon supply or captive renewable-powered fab operations. Retool PERC lines ahead of efficiency threshold escalations to avoid cash-flow interruption during 12-18 month downtime cycles. Prioritize ISO 14064-compliant carbon footprint documentation to maintain EU market access under CBAM enforcement. For New Entrants and Emerging Players: Launch via India's PLI scheme production-linked incentives to capture localized supply alternatives to Chinese imports with state-backed capital subsidies. Target agrivoltaic installations in Germany where elevated bifacial deployment combines crop cultivation with energy generation, opening farmland-adjacent white space without land-use conflict. Pursue performance-guarantee subscription models bundling long-term output warranties with monitoring software to differentiate from hardware-only vendors. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with atomic-layer deposition expertise and established utility offtake relationships. Focus acquisition screening on fabs with captive polysilicon and renewable energy credentials qualifying for EU and US procurement tenders. Watch for tunnel-oxide process control capability scarcity as the inflection signal separating sustainable operators from stranded legacy capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expands wafer-cell-module throughput to underwrite multi-gigawatt utility framework agreements with guaranteed allocation. |
| Backward Integration | Captive polysilicon supply secures low-carbon credentials required for EU Green Deal CBAM compliance and German procurement. |
| Technology Licensing | Equipment-technology partnerships transfer atomic-layer deposition expertise to mid-tier fabs retooling from PERC architectures. |
| Power Purchase Agreement | Long-term renewable energy offtake powers fabs with documented clean generation supporting carbon footprint certification. |
| Green Certification Program | ISO 14064-compliant lifecycle emissions documentation qualifies modules for Dutch and German utility tender requirements. |
Research Methodology
Document review covered EIA project databases, IEA renewable energy reports, and FERC interconnection filings, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across China, India, Germany, and the United States. Secondary validation drew from MIIT efficiency mandate texts, EU Green Deal regulatory documentation, and SEC filings from vertically integrated cell-to-module manufacturers. Bottom-up capacity and demand modeling triangulated against top-down policy target aggregation.
Cross-referencing historical deployment trajectories with expert panel input on retooling timelines and silver paste cost assumptions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cell technology type, installation configuration, end-user scale tier, and regional regulatory cluster. CAGRs derived from capacity expansion schedules, efficiency improvement curves, and procurement volume forecasts tied to national renewable purchase obligations and dual carbon goal trajectories.
The model assumes a particular technology adoption path; alternative pathways for silicon heterojunction-TOPCon tandem architectures or perovskite integration would alter the outlook for tunnel-oxide passivated contact market share. Forecasts reflect assumptions regarding MIIT threshold escalation timing, EU CBAM enforcement stringency, and polysilicon supply chain ESG audit resolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Asia-Pacific MLCC Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Gan on Silicon Technology Market